
 Automotive Subframe Market | 2026-2036
Automotive Subframe Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Subframe Market Analysis
Steel mill capacity in Germany and Japan is hardening supply security for high-strength automotive-grade substrates. Benteler International AG leverages its tubular expertise and European rolling mill network to anchor premium chassis component supply. Martinrea International sustains North American OEM relationships through dedicated stamping and assembly footprints near Detroit and Ontario vehicle plants. Magna International competes on modular system integration, combining subframe fabrication with adjacent suspension module assembly to capture bundled program awards.
An automotive subframe is a structural chassis component, typically fabricated from stamped steel, cast aluminum, or hybrid metal-composite assemblies, that carries powertrain, suspension, and steering loads while isolating vibration from the vehicle body. The component functions as a detachable cradle enabling modular assembly, service access, and crash-energy management in passenger cars and light trucks. Front subframe demand dominates volume owing to powertrain mounting requirements across internal-combustion and battery-electric architectures, while aluminum material adoption is expanding fastest as OEMs pursue mass reduction to offset battery pack weight. Steel retains cost-sensitive segments and heavy-duty applications where yield strength thresholds exceed current aluminum casting capabilities.
NHTSA crashworthiness standards and EPA Corporate Average Fuel Economy regulations in the United States compel subframe redesigns toward lighter, more deformable structures, while ECHA REACH compliance and EU End-of-Life Vehicle directives in Europe restrict certain coatings and mandate recyclability disclosures that filter material selection. China's MIIT New Energy Vehicle mandate and GB standards for structural integrity shape domestic supplier qualification and import substitution priorities. Stakeholders must monitor evolving battery-electric platform architectures where integrated subframe-battery-tray structures are displacing traditional cradle designs.
Market Dynamics
Electric vehicle platform architectures are compressing subframe design cycles as OEMs abandon traditional cradle structures for integrated battery-tray assemblies that merge structural functions.
Growth Catalysts
- EPA Corporate Average Fuel Economy mandates:OEMs redesign subframes toward aluminum-intensive architectures to achieve fleet-wide efficiency targets, accelerating material substitution in North American production lines.
- China's MIIT New Energy Vehicle mandate:Domestic EV manufacturers scale dedicated skateboard platforms requiring modular front and rear subframe systems, concentrating procurement volume with qualified local suppliers.
- High-pressure die-casting:Giga-press manufacturing enables single-piece aluminum subframe castings that eliminate welded joints, reducing assembly complexity and improving structural consistency.
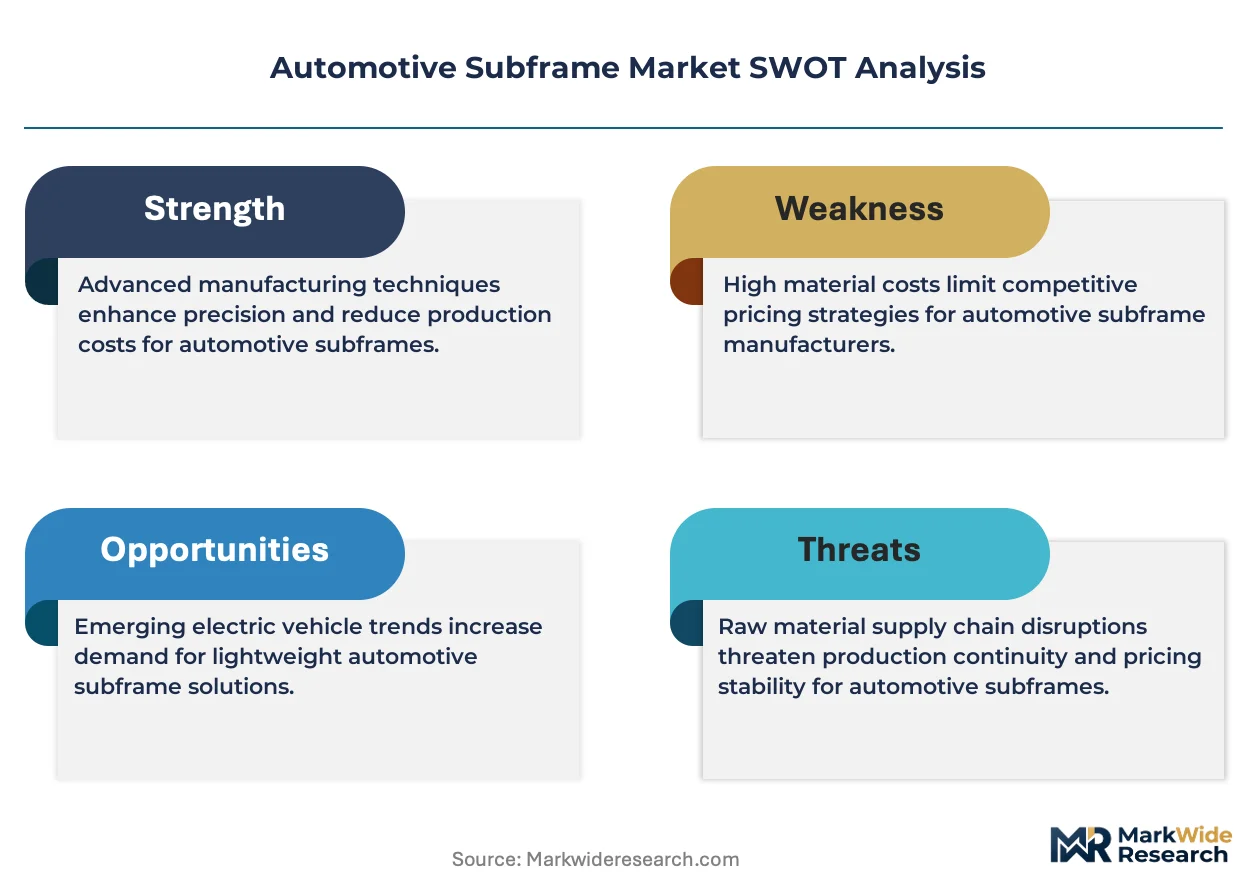
Market Restraints
- Primary aluminum price volatility:London Metal Exchange pricing swings compress margins for aluminum-intensive subframe producers, forcing steel retention in cost-sensitive vehicle segments.
- European rolling mill concentration:Benteler International AG and a limited supplier base control high-strength automotive-grade steel substrate supply, creating qualification bottlenecks for new entrants.
- Cast aluminum yield strength thresholds:Heavy-duty pickup and commercial vehicle applications exceed current aluminum casting capabilities, locking steel dominance in load-bearing architectures.
Strategic Opportunities
- India's PLI scheme for automotive components:Tier-1 suppliers establish dedicated stamping and assembly footprints to capture import substitution demand from domestic OEMs expanding EV portfolios.
- Integrated subframe-battery-tray structures:Convergence of structural battery enclosures with traditional cradle functions creates new engineering service contracts for chassis system integrators.
- EU End-of-Life Vehicle directive recyclability mandates:Design-for-disclosure requirements favor mono-material aluminum subframes over hybrid metal-composite assemblies, reshaping material specification patterns.
Industry Challenges
- Multi-material joining expertise scarcity:Welding technicians qualified for steel-aluminum hybrid subframe fabrication remain concentrated in Germany and Japan, constraining production scale-up in emerging manufacturing regions.
- GB standards structural integrity certification timelines:China's mandatory crash-testing protocols for new subframe designs extend program approval cycles, delaying platform launch schedules.
- Legacy ICE platform service parts commitment:OEMs maintain dual supply chains for traditional steel subframes alongside EV-optimized architectures, fragmenting procurement volume and supplier attention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Subframe Market |
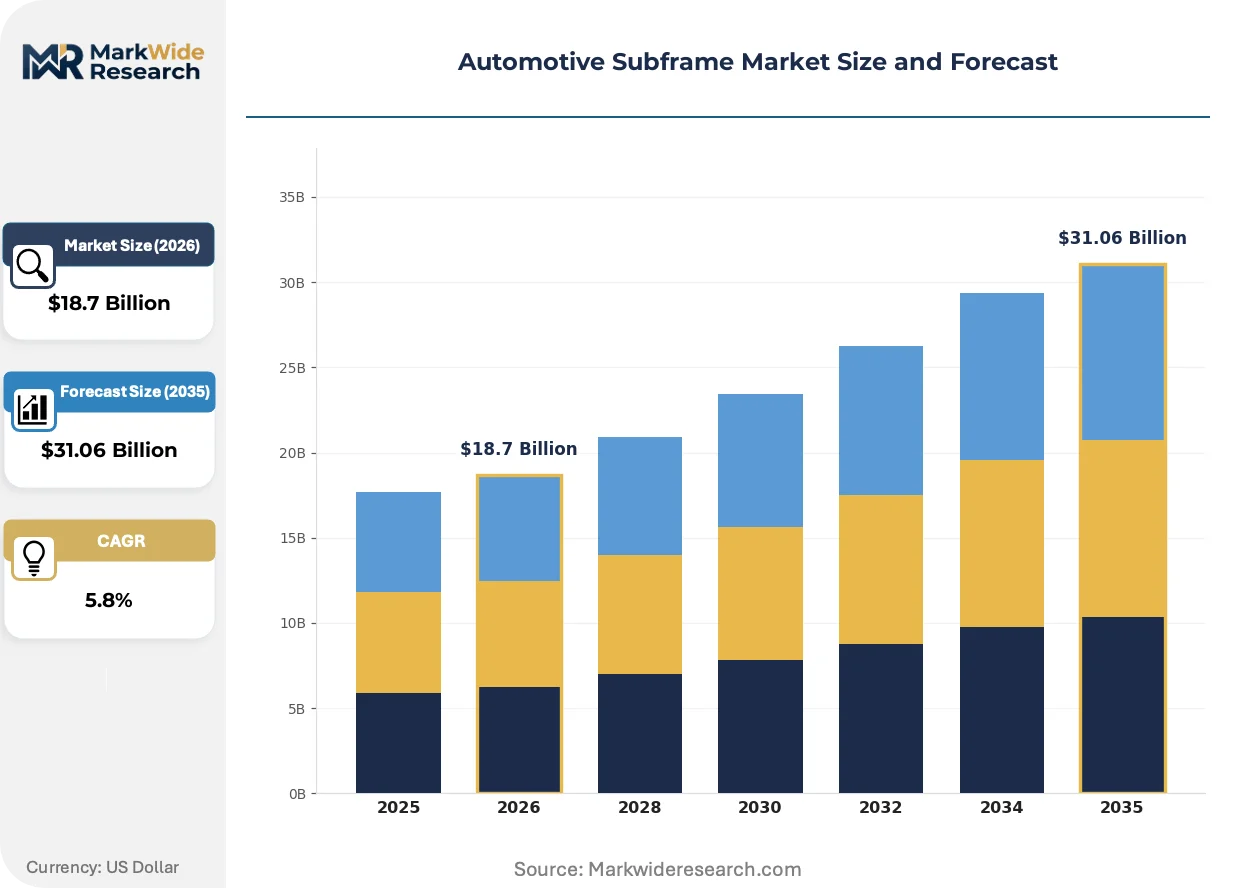
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Subframe, Rear Subframe, Complete Frame, Independent Subframe Material: Steel, Aluminum, Composite, Magnesium End User: OEMs, Aftermarket Suppliers, Tier-1 Suppliers, Vehicle Assemblers Manufacturing Stage: Fabrication, Machining, Assembly, Surface Treatment |
| Companies Covered | Benteler International AG, Martinrea International, Magna International, Kirchhoff Automotive, Aisin Corporation, Gestamp Automoción, F-TECH Inc., CIE Automotive, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Subframe Market Emerging Trajectories
Subframe engineering is converging with battery-electric platform development, compressing the boundary between chassis structure and energy storage enclosure.
Aluminum-intensive subframe architectures are consolidating multiple stamped and cast components into single high-pressure die-castings. Volkswagen Group and Hyundai-Kia are adopting giga-press manufacturing for rear subframe modules, eliminating welded joints and reducing piece count. This consolidation is compressing tier-2 supplier roles while elevating system integrators who control casting and machining capabilities.
EU REACH compliance and ECHA substance restrictions are filtering coating chemistries and surface treatment processes for subframe corrosion protection. Chromate conversion coatings face phase-out timelines, forcing suppliers to qualify trivalent chromium and zirconium-based alternatives. European OEMs are responding fastest, embedding new material declarations into supplier qualification scorecards ahead of End-of-Life Vehicle directive enforcement.
Buyer concentration among dedicated EV platform operators is compressing subframe sourcing cycles and fragmenting legacy supply relationships. Tesla, BYD, and Rivian negotiate direct system-level contracts bypassing traditional tier-1 intermediaries, while established OEMs unbundle suspension module assembly from subframe fabrication. This pattern is most visible in China, where domestic EV pure-plays consolidate procurement with captive chassis engineering teams.
Automotive Subframe Market Segmentation
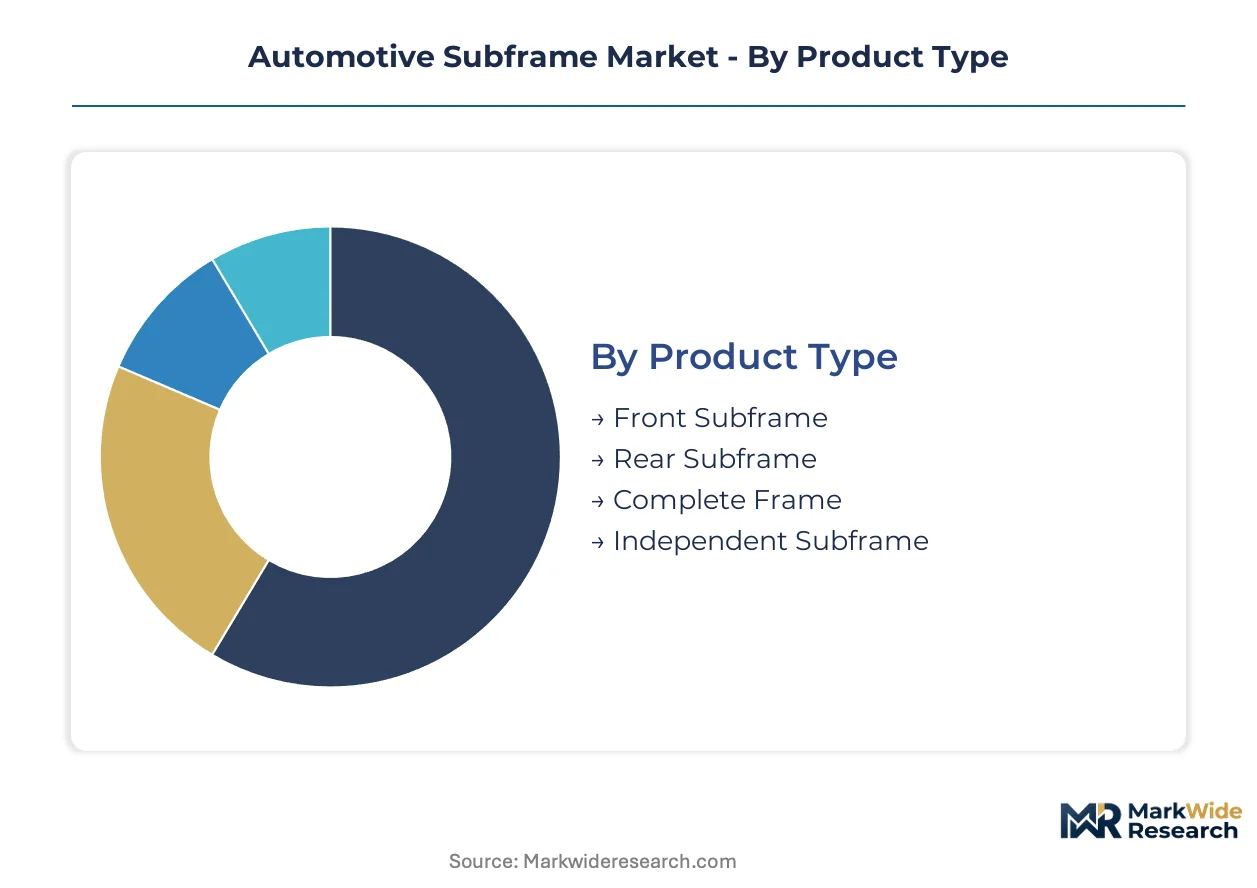
Automotive subframe segmentation reveals how engineering requirements fragment across vehicle architectures. Material choices and mounting positions determine load paths, while manufacturing stage specialization shapes supplier competitive positioning.
Product Type:
Integration depth varies sharply across mounting positions, with front modules carrying powertrain loads as standalone cradles while rear designs increasingly merge with battery enclosures.
- Front Subframe:Stamped steel or cast aluminum cradle structures mount engines, transmissions, and steering racks in ICE and hybrid vehicles. Demand concentrates in North American pickup trucks and European premium sedans where modular service access remains critical. EPA fuel-economy mandates are accelerating aluminum substitution despite cost premiums.
- Rear Subframe:Suspension mounting structures that increasingly integrate with battery trays in skateboard EV platforms. China's MIIT NEV mandate is driving fastest expansion here as BYD and NIO scale dedicated rear-cradle-battery assemblies that eliminate discrete subframe boundaries.
- Complete Frame:Full-perimeter chassis structures spanning front and rear mounting points in body-on-frame trucks.
- Independent Subframe:Detachable corner modules enabling corner-specific crash repair and platform flexibility.
Front Subframe leads volumes today; Rear Subframe is gaining share fastest.
Material:
Cost tiers separate commodity steel from performance aluminum, with composite and magnesium occupying narrow premium niches where mass reduction justifies process complexity.
- Steel:High-strength low-alloy and advanced high-strength grades dominate heavy-duty and cost-sensitive applications. German and Japanese rolling mill networks anchor supply security for automotive-grade substrates.
- Aluminum:High-pressure die-cast and extruded profiles enable mass reduction for EV range extension. Volkswagen Group and Hyundai-Kia giga-press adoption is consolidating multi-piece welded assemblies into single castings.
- Composite:Carbon-fiber reinforced polymers in motorsport and ultra-luxury segments where unit economics tolerate material cost.
- Magnesium:Cast AZ91D and AM60B alloys in steering support brackets and small structural nodes seeking maximum specific stiffness.
Steel retains the largest installed base; aluminum is climbing the fastest.
End User:
Customer type determines contract structure, with OEM direct procurement compressing tier-1 margins while aftermarket channels sustain legacy platform service economics.
- OEMs:Vehicle manufacturers specifying subframe designs and awarding system-level contracts. Tesla and Rivian bypass traditional tier-1 intermediaries for direct chassis engineering partnerships.
- Tier-1 Suppliers:Magna International and Benteler International AG compete on bundled suspension-subframe module assembly to capture integrated program awards.
- Aftermarket Suppliers:Independent distributors serving collision repair and legacy ICE platform maintenance.
- Vehicle Assemblers:Contract manufacturers and joint-venture production facilities procuring subframes as CKD kit components.
OEM direct sourcing dominates new platform awards; Tier-1 Suppliers retain the steepest expansion trajectory in emerging manufacturing regions.
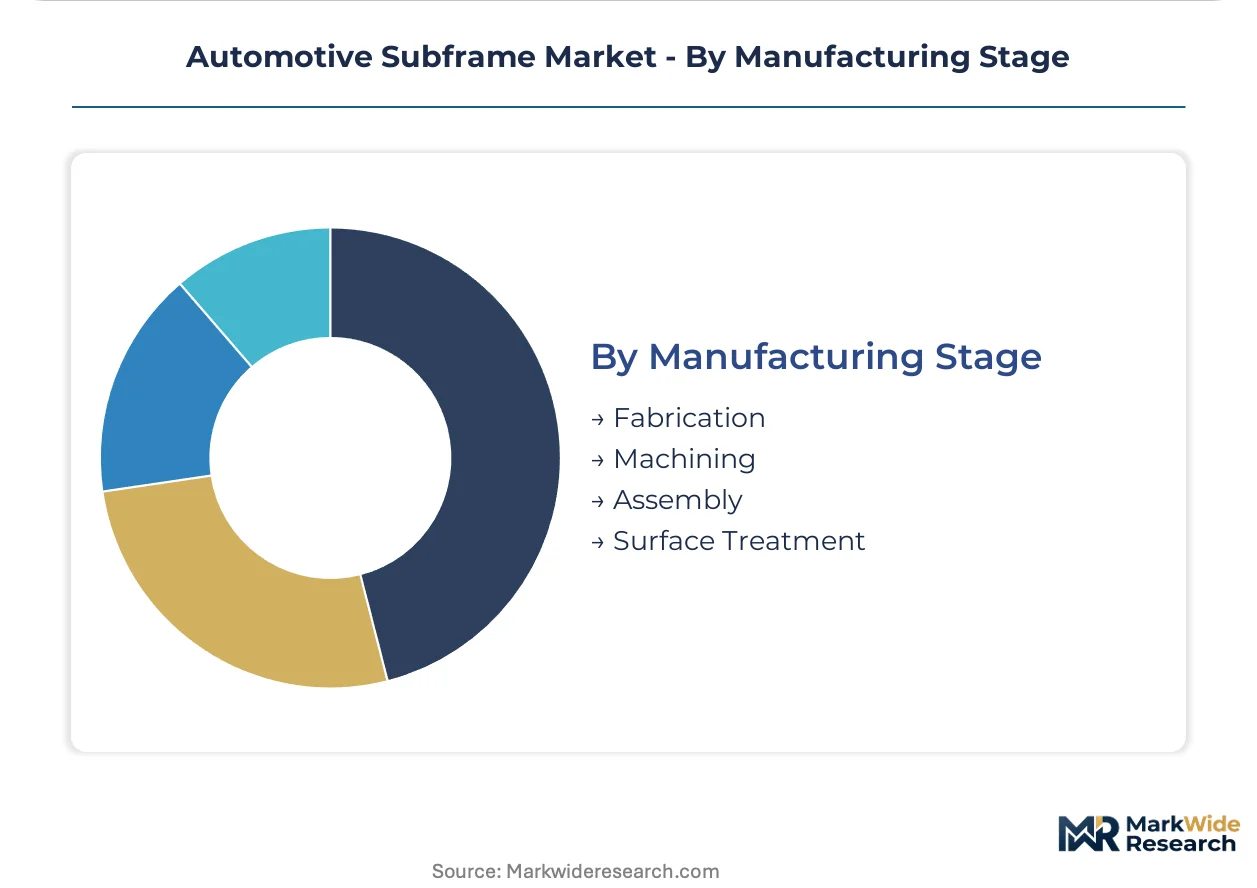
Manufacturing Stage:
Process maturity separates high-volume stamping operations from precision-dependent machining and corrosion-critical finishing stages.
- Fabrication:Stamping, casting, and extrusion of raw subframe blanks. Giga-press manufacturing is displacing multi-stage stamping for aluminum-intensive EV architectures.
- Machining:CNC finishing of cast nodes and drilled mounting interfaces requiring tight geometric tolerances.
- Assembly:Welding, riveting, and adhesive bonding of multi-component subframe modules.
- Surface Treatment:E-coat, powder coat, and zirconium-based conversion coatings replacing chromate pretreatments under ECHA REACH phase-out timelines.
Fabrication commands the largest capacity footprint; Surface Treatment is expanding most quickly as regulatory compliance reshapes process investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting subframe production toward jurisdictions with favorable cost-of-compliance profiles, particularly where EV mandates accelerate faster than environmental enforcement tightens. This divergence creates procurement migration patterns that reshape supplier footprints.
China
MIIT's NEV mandate drives BYD and NIO to scale dedicated skateboard platforms requiring integrated rear subframe-battery assemblies. GB standards for structural integrity extend certification timelines but concentrate procurement with qualified domestic suppliers. The Yangtze River Delta hosts the densest cluster of high-pressure die-casting capacity serving these programs.
Germany
EPA-equivalent EU CO2 fleet mandates compel Volkswagen Group and BMW toward aluminum-intensive architectures, while ECHA REACH restrictions on chromate coatings force surface treatment reinvestment. Benteler International AG leverages its European rolling mill network from North Rhine-Westphalia to anchor premium chassis supply security.
United States
NHTSA crashworthiness standards and EPA CAFE regulations compel subframe redesigns toward lighter, more deformable structures. Detroit and Ontario vehicle plants sustain Martinrea International's dedicated stamping footprints. The Midwest corridor retains steel dominance for heavy-duty pickup applications where aluminum yield thresholds fall short.
Japan
METI industrial policy supports Toyota and Honda's hybrid platform diversification, preserving multi-material joining expertise concentrated in Aichi and Kanagawa prefectures. JIS standards for high-strength automotive-grade substrates harden qualification barriers for foreign entrants. Domestic rolling mill networks anchor supply security for traditional cradle designs.
India
PLI scheme incentives for automotive components attract Tier-1 suppliers to establish dedicated stamping and assembly footprints. Tamil Nadu and Maharashtra host expanding OEM EV portfolios requiring localized subframe procurement. BIS certification timelines create qualification bottlenecks that favor early entrants with established testing relationships.
Automotive Subframe Market Vendor Landscape
German producers anchor one tier; Japanese specialists hold process expertise in multi-material fabrication; North American fabricators compete on proximity to Detroit and Ontario vehicle plants. The vendor base organizes around three strategic archetypes: rolling mill-integrated steel substrate suppliers, giga-press-equipped aluminum casters, and modular system integrators bundling suspension assembly. Dominant competitive moves include captive capacity expansion near OEM EV platform launches and technology licensing for high-pressure die-casting processes.
Within the rolling mill-integrated tier, Benteler International AG exemplifies European substrate security; among North American modular specialists, Martinrea International occupies a position shaped by Detroit-proximate footprints; at the system-integration end, Magna International represents the bundled program award archetype combining subframe fabrication with adjacent suspension modules.
| Leading Market Players |
|---|
| Benteler International AG |
| Martinrea International |
| Magna International |
| Kirchhoff Automotive |
| Aisin Corporation |
| Gestamp Automoción |
| F-TECH Inc. |
| CIE Automotive |
| ZF Friedrichshafen AG |
| Others |
Supply Flow & Price Mechanics
Multi-material welding technicians concentrated in Aichi and Kanagawa prefectures drive labor-cost differentials that widen pricing spreads between steel-intensive and aluminum-intensive subframe tiers.
Pricing Analysis
Distributor margins for aftermarket subframe replacement modules compress pricing transparency, while direct-to-OEM contracts command volume discounts tied to platform exclusivity. Three-tier pricing structure across premium aluminum castings, standard stamped steel assemblies, and economy-grade refurbished units separates OEM-grade certifications from import-substitute alternatives. Pricing pressure stems from London Metal Exchange aluminum volatility forcing steel retention in cost-sensitive vehicle segments. Fleet operators and commercial vehicle buyers exhibit highest price sensitivity, while premium EV platform engineers prioritize mass reduction over unit cost.
Supply Chain Analysis
China's MIIT domestic-content mandates for NEV platforms are reshaping sourcing patterns toward Yangtze River Delta die-casting clusters. Raw material flows draw from German and Japanese rolling mills for high-strength automotive-grade steel substrates, while primary aluminum feeds from Chinese smelters and Australian bauxite. Single-source vulnerability concentrates in European rolling mill networks controlled by Benteler International AG and limited qualified suppliers. Distribution runs through tier-1 system integrators bundling suspension module assembly with subframe fabrication for just-in-time delivery to OEM platform launches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive subframe market represents a late-cycle quality story as OEM procurement shifts toward integrated aluminum-intensive architectures demanding precision casting and surface treatment certifications.
For Market Incumbents: Deploy captive giga-press capacity expansion near BYD and NIO platform launches in the Yangtze River Delta to anchor EV-dedicated supply relationships. Deepen backward integration into high-pressure die-casting process licensing to defend against emerging Chinese pure-play competitors. Secure chromate-alternative surface treatment qualifications ahead of ECHA REACH enforcement timelines. For New Entrants and Emerging Players: Enter via India's PLI scheme automotive component incentives to capture localized stamping and assembly demand from Tamil Nadu and Maharashtra OEM EV expansions. Target rear subframe-battery-tray convergence segments where traditional tier-1 relationships remain unconsolidated. Pursue direct engineering service contracts with domestic EV pure-plays bypassing established intermediary structures. For Investors and Strategic Acquirers: Tier-1 system integrators with bundled suspension-subframe capabilities are the most active acquirer in this space, consolidating casting and machining assets to capture modular program awards. Long-term viability hinges on aluminum casting yield strength advancement and giga-press process scale economics over the coming decade. Monitor high-pressure die-casting equipment order backlogs as inflection indicator for capacity-constrained expansion windows.| Strategic Initiative | Industry Significance |
|---|---|
| Giga-Press Capacity Expansion | Single-piece aluminum subframe castings eliminate welded joints for Volkswagen Group and Hyundai-Kia platforms. |
| Chromate-Alternative Surface Treatment Qualification | ECHA REACH compliance forces trivalent chromium and zirconium-based coating investments ahead of phase-out deadlines. |
| Integrated Subframe-Battery-Tray Engineering | Structural battery enclosure convergence creates new chassis system integrator contracts for skateboard EV architectures. |
| PLI Scheme Manufacturing Footprint Establishment | India's component incentives attract dedicated stamping and assembly capacity for domestic OEM EV portfolios. |
| Multi-Material Joining Expertise Development | Welding technician scarcity in Germany and Japan constrains steel-aluminum hybrid fabrication scale-up elsewhere. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, tier-1 supplier procurement directors, high-pressure die-casting equipment specialists, and aftermarket distribution channel managers with secondary validation. Vehicle production databases, IHS Markit registration data, SEC filings from exposed suppliers, and ECHA substance restriction timelines anchored the evidence base. Bottom-up segment sizing and top-down macro constraint checks triangulated volume and value estimates.
Historical reference periods spanning pre-pandemic baseline, supply disruption interval, and recovery trajectory anchored the forecast window across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, material grade tier, mounting position, and regional production cluster. CAGRs derived from segment-level growth rate synthesis applied to base-year estimates, with aluminum price elasticity and EV platform adoption curves as industry-specific forecast inputs.
Inputs from OEM platform engineering disclosures and tier-1 supplier qualification records were available through the study window; gaps in proprietary casting yield data and battery-tray structural integration roadmaps introduce uncertainty bands. Forecasts reflect documented assumptions regarding MIIT NEV mandate enforcement trajectories and ECHA REACH phase-out adherence. A small set of triggers—including giga-press equipment delivery delays and primary aluminum price spike duration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Asia-Pacific Automotive Parts and Components Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Auto Fender Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
Mexico Automotive Pneumatic Actuators Market
Automotive Components
US Automotive Composites Market
Automotive Components
Automotive Carbon Ceramic Brakes Market
Automotive Components
Egypt Commercial Vehicles Lubricants Market
Automotive Components
Automotive Exhaust Manifolds Market
Automotive Components
Germany Automotive Carbon Fiber Composites Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Automotive Stabilizer Bar Link Market
Automotive Components
Remote Automotive Exhaust Sensing Market