
 LAMEA Composite Process Material Kits Market | 2026-2036
LAMEA Composite Process Material Kits Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Composite Process Material Kits Market Insights
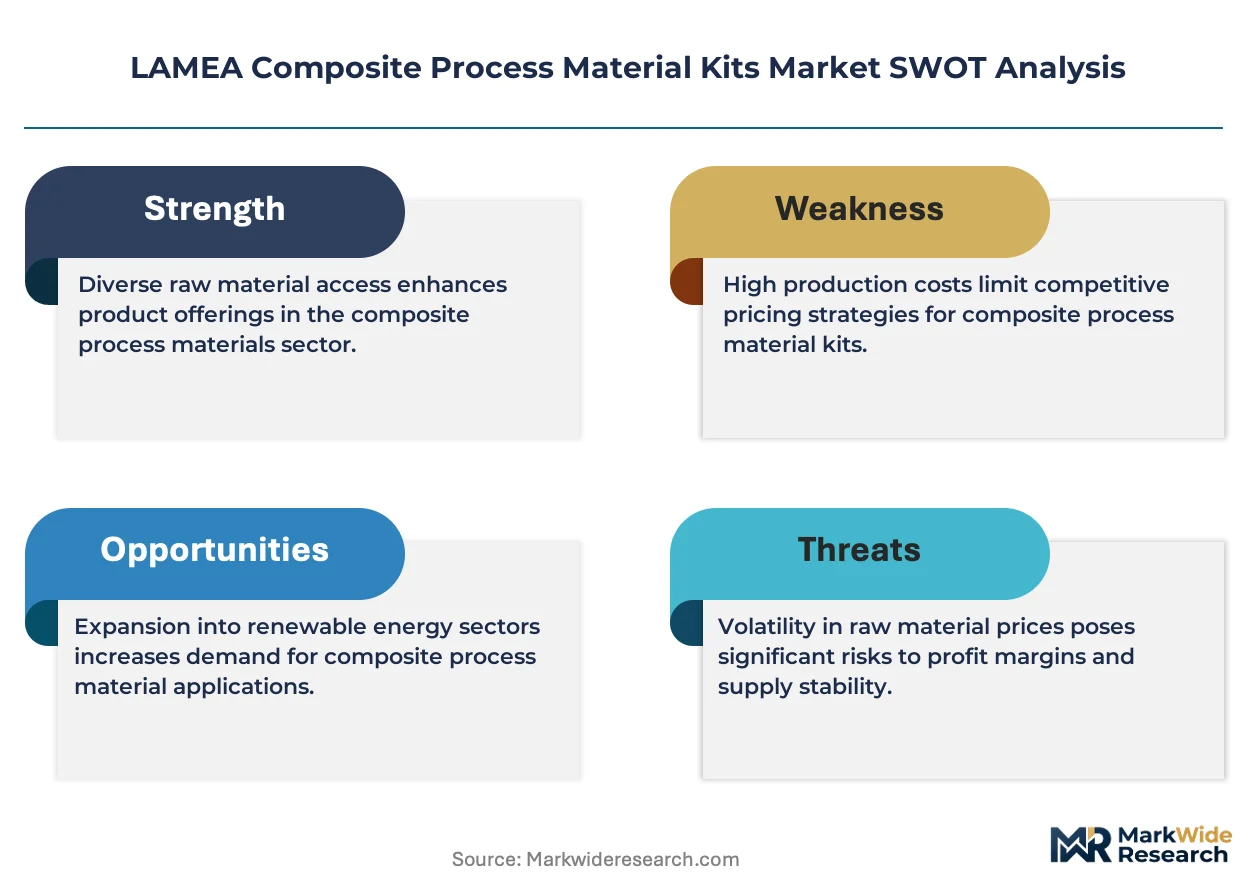
Aerospace procurement is hardening as the dominant demand pillar across the LAMEA region. Airtech Advanced Materials Group leverages its vacuum bagging film specialization to anchor long-term contracts with Gulf-based MRO facilities. Aerovac Composites One competes through distributor density across Brazilian and South African fabrication shops. Shanghai Leadgo-Tech Co., Ltd. extends its prepreg formatting capabilities into Middle Eastern tooling houses serving wind energy nacelle producers.
Composite process material kits encompass consumable systems—vacuum bagging films, release fabrics, peel plies, sealant tapes, and resin flow media—engineered to withstand cure cycles up to 400°F while enabling controlled resin distribution during closed-mold fabrication. These kits eliminate surface contamination and optimize fiber-volume fraction in finished laminates for structural integrity. Prepreg formulations dominate value capture due to refrigerated supply chain complexity and autoclave compatibility premiums, while vacuum infusion consumables represent the fastest-growing technology channel as shipyards and wind blade factories adopt out-of-autoclave methods. Structural components applications concentrate the highest margin pools because aerospace tier-one suppliers specify full kit traceability and batch certification.
Brazil's ANAC, South Africa's SABS, and the UAE's GCAA collectively enforce material lot traceability and flammability compliance that elevates kit documentation costs for entrants. REACH-aligned substance restrictions from European OEM supply agreements propagate into LAMEA procurement specifications, favoring suppliers with certified clean-chemistries. Stakeholders must monitor how Saudi Vision 2030 localization mandates reshape supplier qualification pathways for giga-project composite structures.
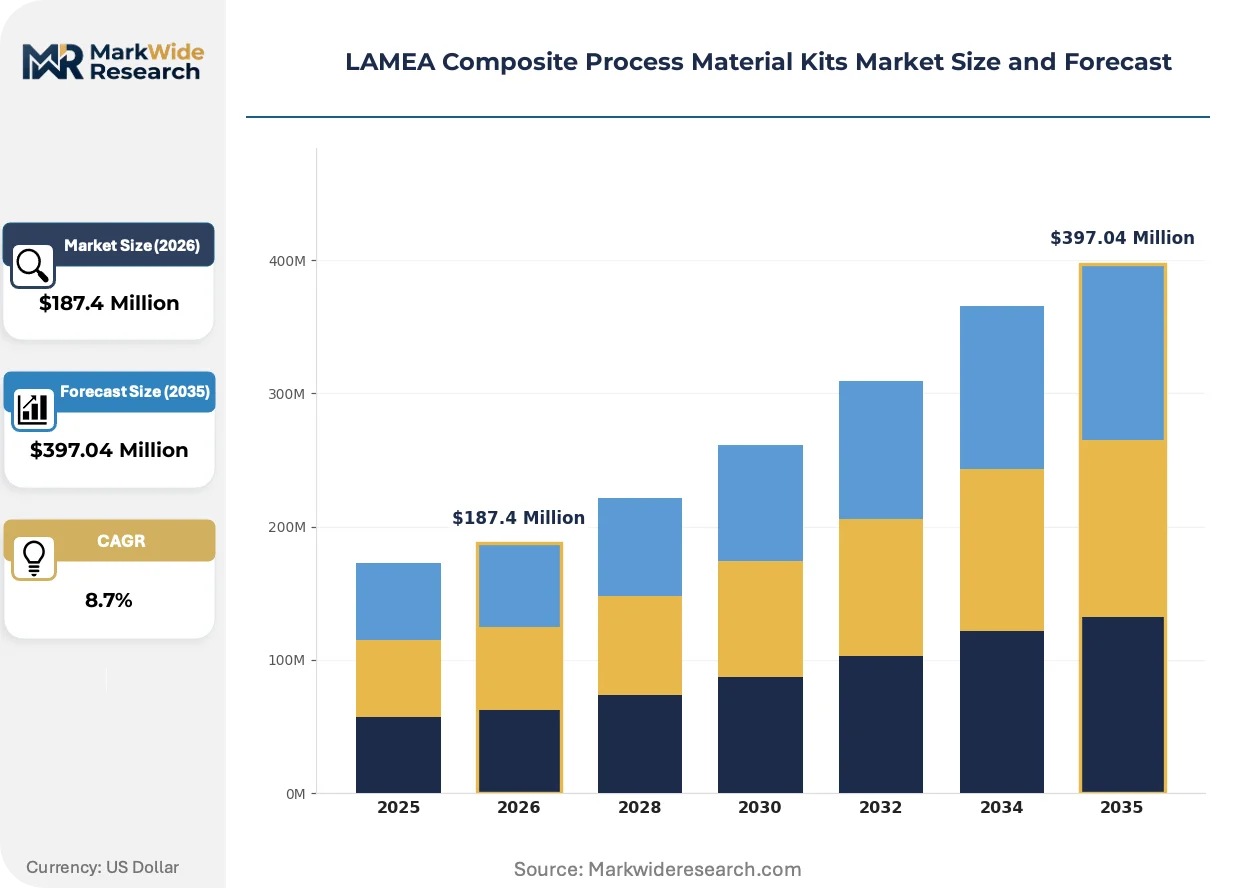
Market Dynamics
Vacuum infusion consumables are hardening demand structures across LAMEA aerospace and wind energy fabrication, as out-of-autoclave methods compress cure cycle costs while ANAC and GCAA traceability mandates elevate documentation burdens for kit suppliers.
Growth Catalysts
- ANAC airworthiness directives:Brazil's tightening material lot traceability for commercial aircraft retrofits is pulling vacuum bagging systems into MRO facility upgrade cycles.
- Wind blade nacelle tooling:Saudi Arabia's giga-project pipeline is channeling prepreg kit demand into localized composite structure fabrication for renewable energy infrastructure.
- Vacuum infusion adoption:Shipyards across South Africa are displacing open-mold layup with closed-mold resin flow media to achieve controlled fiber-volume fractions in hull laminates.
Market Restraints
- Refrigerated supply chain concentration:Prepreg cold-chain logistics remain concentrated among Gulf-based distributors, creating temperature excursion risks for inland African fabrication shops.
- SABS certification timelines:South Africa's composite material approval pathways extend supplier qualification periods, compressing working capital efficiency for kit entrants.
- Release film input volatility:Fluoropolymer feedstock price swings are pressuring vacuum bagging film margins across Brazilian tier-two suppliers.
Strategic Opportunities
- Saudi Vision 2030 localization:Domestic content mandates for Neom and Red Sea Project composite structures are opening qualification pathways for regional kit assemblers.
- Peel ply automation:Robotic placement systems for release fabric positioning are converging with automated fiber placement to reduce touch labor in UAE aerospace MRO clusters.
- Secondary distribution channels:Direct-to-fabricator digital procurement platforms are emerging in South Africa's Eastern Cape wind blade manufacturing zone.
Industry Challenges
- Autoclave technician scarcity:Gulf-based MRO facilities face recruitment friction for operators certified to 400°F cure cycle management.
- REACH-aligned chemistry documentation:European OEM supply agreements are propagating substance restriction paperwork into LAMEA kit certification workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Composite Process Material Kits Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepregs, Resins, Adhesives, Reinforcements End User: Aerospace, Automotive, Marine, Construction Technology: Vacuum Infusion, RTM, Compression Molding, Filament Winding Application: Structural Components, Lightweight Parts, Tooling, Prototyping |
| Companies Covered | Airtech Advanced Materials Group, Aerovac Composites One, Shanghai Leadgo-Tech Co., Ltd., Diatex SAS, InCom Group, Metyx Composites, GEFiM, Pro-Vac Vacuum Consumables, Velocity Composites plc, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Composite Process Material Kits Market Trends and Innovations
Process material kit specifications are pivoting toward cure-cycle flexibility and digital traceability as aerospace tier-one suppliers extend their documentation requirements downstream into regional fabrication networks.
Out-of-autoclave prepregs with dual-cure formulations are electrifying fabrication economics across wind energy and marine applications. These systems enable room-temperature staging followed by elevated-temperature final cure, allowing Saudi nacelle producers to stage large tools without continuous autoclave occupancy. Brazilian shipyards are adopting the technology at pace to compress hull production timelines, compressing capital intensity for mid-scale fabrication operations.
REACH substance restrictions propagated through European OEM supply agreements are hardening chemical compliance requirements across LAMEA procurement specifications. The industrial consequence is elevated testing costs for sealant tape and release fabric formulations entering aerospace-certified workflows. UAE-based MRO clusters are responding by consolidating supplier panels around vendors with pre-certified clean-chemistry portfolios, compressing qualification timelines for compliant entrants.
Consolidated kit procurement—single-source contracts covering vacuum bagging films, peel plies, flow media, and sealant tapes—is displacing component-level purchasing in Gulf aerospace maintenance operations. Tier-one suppliers are bundling full traceability documentation to capture multi-year MRO service agreements. This pattern is most visible in Dubai's Al Maktoum International Airport maintenance cluster, where full-kit contracts now dominate composite repair workflow sourcing.
LAMEA Composite Process Material Kits Market Segmentation
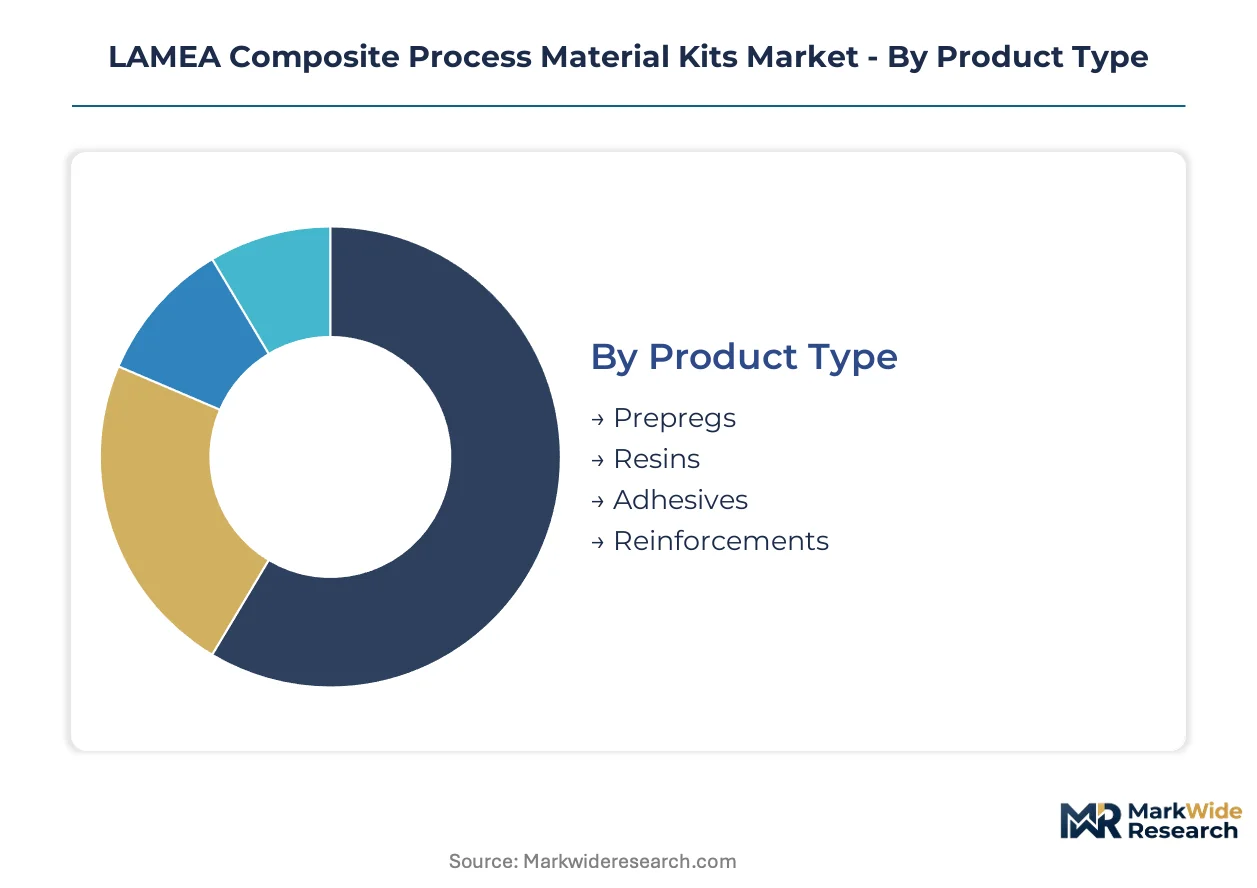
Composite process material kits fragment across four distinct axes in LAMEA markets. Technology selection dictates consumable specifications, while end-use certification requirements determine margin structures and supplier qualification pathways.
Product Type:
Prepreg formulations anchor value capture through refrigerated supply chain complexity and autoclave compatibility premiums, while commodity resins and reinforcements compete on distributor density.
- Prepregs:Refrigerated resin-impregnated fiber systems requiring continuous cold-chain logistics from Gulf distributors to fabrication shops. ANAC and GCAA traceability mandates elevate batch certification costs for aerospace retrofits across Brazil and the UAE.
- Resins:Epoxy and thermoset formulations enabling room-temperature staging with elevated-temperature final cure. Saudi nacelle producers adopt dual-cure systems to compress tooling timelines without continuous autoclave occupancy.
- Adhesives:Structural bonding agents with flammability compliance documentation for aircraft interior applications.
- Reinforcements:Carbon and glass fiber fabrics supplying fiber-volume fraction control in vacuum infusion workflows.
Prepregs lead on scale; resins lead on momentum.
End User:
Customer concentration patterns split between certified aerospace procurement and cost-driven marine fabrication, with construction emerging from Saudi giga-project localization mandates.
- Aerospace:Tier-one suppliers specify full kit traceability and batch certification for MRO facility contracts. Dubai's Al Maktoum International Airport maintenance cluster now sources consolidated vacuum bagging films, peel plies, and flow media through single-source agreements.
- Marine:South African shipyards displace open-mold layup with closed-mold resin flow media to achieve controlled fiber-volume fractions in hull laminates.
- Automotive:Limited penetration concentrated in motorsport and specialty vehicle fabrication with SABS certification requirements.
- Construction:Neom and Red Sea Project composite structures channel prepreg demand into localized fabrication under Saudi Vision 2030 domestic content mandates.
Aerospace dominates margin capture; construction expands most quickly.
Technology:
Fabrication method selection determines consumable kit composition and cure cycle temperature requirements, with out-of-autoclave methods compressing capital intensity for mid-scale operations.
- Vacuum Infusion:Closed-mold resin flow media systems enabling controlled resin distribution without autoclave occupancy. Brazilian shipyards and South African hull producers adopt at pace to displace open-mold labor intensity.
- RTM:Resin transfer molding for medium-volume structural components with repeatable dimensional tolerance.
- Compression Molding:High-pressure thermoset forming for automotive and industrial applications with shorter cycle times.
- Filament Winding:Automated fiber placement for cylindrical pressure vessels and piping systems.
Vacuum infusion leads on adoption velocity; RTM maintains steady replacement demand.
Application:
Functional use cases stratify by structural load requirements and certification burden, with aerospace structural components commanding full documentation premiums.
- Structural Components:Load-bearing laminates requiring fiber-volume fraction optimization and surface contamination elimination. Full kit traceability documentation bundles capture multi-year MRO service agreements in UAE aerospace clusters.
- Lightweight Parts:Secondary structures and interior panels with reduced certification documentation.
- Tooling:Composite molds and fixtures for wind blade nacelle production staging large tools without continuous autoclave occupancy.
- Prototyping:Low-volume validation parts with expedited qualification pathways and reduced batch certification.
Structural components lead on margin; tooling gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions where ANAC traceability costs undercut GCAA documentation burdens, creating arbitrage corridors between Brazilian fabrication shops and Gulf aerospace clusters. This regulatory-cost gradient channels kit assembly capacity into São Paulo state and the UAE's Al Ain industrial zone.
Brazil
ANAC airworthiness directives for commercial aircraft retrofits pull vacuum bagging systems into MRO facility upgrade cycles across São Paulo and Rio de Janeiro. The national civil aviation regulator tightens material lot traceability requirements quarterly. Campinas aerospace suppliers now bundle full-kit documentation to capture multi-year service contracts from Embraer-tier maintenance networks.
United Arab Emirates
Dubai's Al Maktoum International Airport maintenance cluster sources consolidated vacuum bagging films and peel plies through single-source agreements. GCAA composite certification standards enforce batch-level documentation that elevates qualification costs for kit entrants. Sharjah's emerging fabrication zone attracts secondary distributors seeking proximity to MRO procurement hubs without Dubai's facility premiums.
Saudi Arabia
Neom and Red Sea Project composite structures channel prepreg demand into localized fabrication under Vision 2030 domestic content mandates. SFDA-aligned substance documentation propagates from European OEM supply agreements into procurement specifications. Jubail Industrial City's tooling houses now stage large wind nacelle molds using dual-cure systems to bypass continuous autoclave occupancy.
South Africa
SABS certification timelines extend supplier qualification periods, compressing working capital efficiency for kit entrants targeting Eastern Cape wind blade manufacturing. The national standards body's composite material approval pathways average fourteen months for new product categories. Gqeberha's marine fabrication corridor adopts vacuum infusion consumables to displace open-mold hull production methods.
Mexico
Querétaro's aerospace supplier park pulls vacuum bagging film demand from Gulf-based distributors seeking NAFTA-adjacent assembly capacity. COFEPRIS chemical substance documentation requirements remain less stringent than REACH-aligned specifications, creating documentation-cost arbitrage for kit assemblers. Tijuana's contract manufacturers now serve California aerospace tier-one suppliers with staged prepreg formats.
LAMEA Composite Process Material Kits Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with Gulf-based MRO procurement favoring consolidated kit suppliers while Brazilian fabrication shops disaggregate purchases across distributor networks. The vendor base organizes into three archetypes: vacuum bagging film specialists, prepreg cold-chain distributors, and full-kit assemblers bundling traceability documentation. Consolidation pressure concentrates among tier-two Brazilian suppliers facing fluoropolymer feedstock volatility. Geographic expansion and strategic partnerships represent the dominant competitive vectors as Saudi localization mandates reshape qualification pathways.
Within the vacuum bagging specialization tier, Airtech Advanced Materials Group and Aerovac Composites One exemplify divergent geographic anchoring strategies. Airtech occupies a position tied to Gulf-based MRO facility networks, while Aerovac represents distributor-density approaches across Brazilian and South African fabrication shops. Shanghai Leadgo-Tech Co., Ltd. sits within the prepreg formatting archetype, extending capabilities into Middle Eastern tooling houses serving adjacent wind energy demand.
| Leading Market Players |
|---|
| Airtech Advanced Materials Group |
| Aerovac Composites One |
| Shanghai Leadgo-Tech Co., Ltd. |
| Diatex SAS |
| InCom Group |
| Metyx Composites |
| GEFiM |
| Pro-Vac Vacuum Consumables |
| Velocity Composites plc |
| Others |
Pricing and Supply Chain Analysis
Consolidated kit procurement mandates from Dubai's Al Maktoum International Airport maintenance cluster are compressing distributor margins and forcing Gulf-based suppliers to bundle full traceability documentation, elevating qualification costs for tier-two Brazilian entrants facing fluoropolymer feedstock volatility.
Pricing Analysis
Distributor margin layers stratify across three tiers: premium autoclave-compatible prepreg systems command cold-chain logistics premiums, standard vacuum infusion consumables compete on batch certification speed, and economy-grade release films face price erosion from Brazilian tier-two suppliers. Price differentiation hinges on ANAC traceability grade and refrigerated supply chain reach. Cost compression in standard-tier vacuum bagging films intensifies as Aerovac Composites One extends distributor density across São Paulo fabrication shops. Aerospace MRO procurement shows lowest price sensitivity; marine hull producers in Gqeberha exhibit highest.
Supply Chain Analysis
Saudi Vision 2030 domestic content mandates for Neom and Red Sea Project composite structures are reshaping sourcing patterns, pulling kit assembly capacity toward Jubail Industrial City. Raw material flows draw from fluoropolymer producers in China, epoxy resin formulators in South Korea, and carbon fiber precursors from Japan. Single-source vulnerability concentrates in Gulf-based refrigerated prepreg distribution, where temperature excursion risks threaten inland African fabrication shops. Distribution runs through consolidated full-kit suppliers in UAE aerospace clusters and fragmented component distributors across Brazilian and South African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANAC's quarterly tightening of material lot traceability requirements compounds demand for certified kit documentation, creating sustained procurement upgrade cycles across Brazilian MRO networks.
For Market Incumbents: Anticipate margin compression from dual-cure prepreg substitution in Saudi wind nacelle tooling by securing backward integration into sealant tape formulation. Consolidate supplier panels around pre-certified REACH-aligned chemistry portfolios to compress qualification timelines for compliant entrants. Channel control through long-term service agreements with Dubai's Al Maktoum maintenance cluster anchors pricing power. For New Entrants and Emerging Players: SABS certification timelines in South Africa open a window for digital procurement platforms targeting Eastern Cape wind blade manufacturers with expedited documentation workflows. White-space concentrates in secondary distribution channels serving mid-scale Brazilian shipyards adopting vacuum infusion methods. A direct-to-fabricator go-to-market angle bypasses incumbent distributor lock-in. For Investors and Strategic Acquirers: Asymmetric upside sits with regional kit assemblers possessing pre-certified clean-chemistry portfolios and Saudi localization qualifications. Long-term viability favors entities with captive supply chain control across prepreg formatting and vacuum bagging film production. Watch for SFDA-aligned substance documentation propagation as the inflection signal for procurement specification hardening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sealant Tape Formulation | Captures margin pools from REACH-aligned chemistry documentation requirements propagating through European OEM supply agreements. |
| Digital Procurement Platform Launch | Disintermediates incumbent distributors in South Africa's Eastern Cape wind blade manufacturing zone. |
| Saudi Localization Partnership | Qualifies kit assemblers for Neom and Red Sea Project composite structures under Vision 2030 mandates. |
| Dual-Cure Prepreg Capacity Expansion | Serves Jubail Industrial City tooling houses staging large wind nacelle molds without continuous autoclave occupancy. |
| Robotic Peel Ply Automation Deployment | Converges with automated fiber placement to reduce touch labor in UAE aerospace MRO clusters. |
Research Methodology
Multiple input streams — primary interviews with composite fabrication engineers, procurement leads at Gulf-based MRO facilities, and technical directors at prepreg cold-chain distributors — were reconciled against secondary validation from ANAC airworthiness directives, SABS composite certification standards, and customs trade data for fluoropolymer feedstock flows. Bottom-up fabrication shop surveys across São Paulo, Dubai, and Gqeberha were triangulated with top-down aerospace tier-one supplier procurement disclosures.
Historical volume trajectories were cross-referenced against panel input from wind energy project developers and marine hull producers to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type tier, end-use certification burden, fabrication technology, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves for vacuum infusion methods and localization-mandated procurement shifts. Industry-specific inputs incorporated ANAC traceability cost escalation and SFDA-aligned substance documentation propagation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH substance restriction expansion or Gulf cold-chain logistics disruption. Forecasts reflect documented assumptions regarding cure-cycle technology substitution rates and domestic content mandate enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Wall Cladding Materials Market
Composite Materials
Asia Pacific Bio Composites Market
Composite Materials
Long-Fiber Thermoset Composites Market
Composite Materials
Global Closed Molding Composites Market
Composite Materials
Isostatic Graphite Market
Composite Materials
Structural Core Materials Market
Composite Materials
Lightweight Materials Market
Composite Materials
Hybrid Composites Market
Composite Materials
Non-Honeycomb Sandwich Panel Core Materials Market
Composite Materials
High Frequency High Speed Copper Clad Laminate CCL Market
Composite Materials
Composite Metal Finishing Market
Composite Materials
Core Material for Composites Market
Composite Materials
Thermoplastic Honeycomb Market
Composite Materials
CFRTP Market
Composite Materials
Short Fiber Thermoplastic Composites Market
Composite Materials
Molded Underfill Material Market