
 Global Dental Adhesive Market | 2026-2036
Global Dental Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Adhesive Market Foresight
Cosmetic dentistry is recalibrating demand patterns across adhesive categories as patients prioritize aesthetic outcomes over traditional amalgam restorations. 3M leverages its materials science heritage to dominate universal adhesive formulations with simplified clinical protocols. GC Corporation anchors the glass ionomer cement segment through sustained R&D investment in bioactive ion-release chemistry. Ivoclar Vivadent specializes in premium indirect restoration bonding systems that command premium positioning in specialty practices.
Dental adhesive denotes a resin-based or ionomeric material formulated with methacrylate monomers, acidic primers, and filler particles that establishes micromechanical and chemical retention between tooth substrate and restorative materials. The composition typically incorporates 10-methacryloyloxydecyl dihydrogen phosphate for enamel and dentin bonding with film thickness specifications below 25 micrometers. Universal adhesives now lead product type dynamics by collapsing the etch-and-rinse and self-etch categories into single-bottle protocols that reduce technique sensitivity. Self-etching adhesives represent the fastest-growing product category as clinicians adopt gentler demineralization approaches for pediatric and geriatric cohorts. Direct restorations capture the dominant application share while orthodontic bonding generates the highest margin pools through recurring consumable requirements.
The FDA regulates dental adhesives as Class II medical devices under 21 CFR 872, enforcing biocompatibility testing per ISO 10993 and cytotoxicity thresholds that constrain monomer selection. The EU Medical Device Regulation mandates clinical evaluation and post-market surveillance through notified bodies, elevating compliance costs for non-European manufacturers seeking CE marking. Japan's PMDA applies JIS T 6503 standards for dental cements that require local clinical data for market authorization. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions in polymer chemistry as regulators scrutinize fluorinated compounds across medical device supply chains.
Market Dynamics
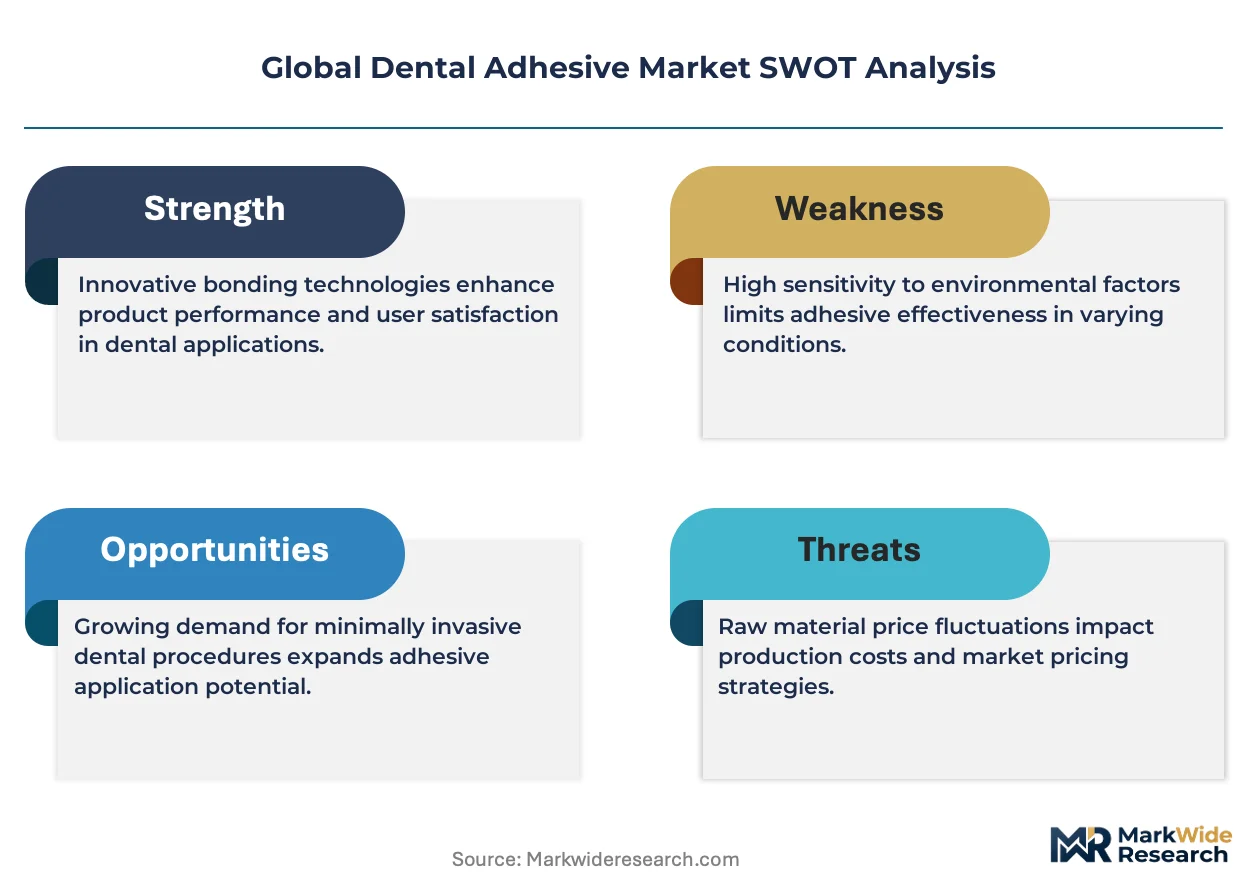
Universal adhesive protocols are collapsing the traditional etch-and-rinse versus self-etch dichotomy, compressing SKU complexity while forcing manufacturers to reformulate for simplified clinical workflows. This consolidation redistributes margin pools toward bioactive and ion-releasing chemistries that command premium positioning in minimally invasive protocols.
Growth Catalysts
- EU MDR biocompatibility thresholds:Stricter cytotoxicity standards for resin monomers are accelerating R&D investment in alternative chemistries, pulling next-generation adhesives through clinical validation pipelines faster than historical norms.
- Orthodontic clear aligner bonding:Recurring consumable requirements for attachment bonding generate high-margin recurring revenue streams as aligner therapy expands beyond adolescent into adult demographic segments.
- 10-methacryloyloxydecyl dihydrogen phosphate chemistry:Advances in phosphate-ester monomer stability are extending shelf life and reducing technique sensitivity in universal formulations, expanding addressable clinician base.
Market Restraints
- Bisphenol A glycol methacrylate input volatility:Petrochemical feedstock price swings compress formulation margins, particularly for economy-tier universal adhesives where price elasticity limits pass-through capability.
- Notified body concentration in Germany and Netherlands:EU MDR certification bottlenecks create 12-18 month approval delays for non-European manufacturers seeking CE marking, entrenching incumbent market positions.
- Glass ionomer cement substitution in pediatric applications:Fluoride-releasing alternatives with lower technique sensitivity capture share in primary dentition restorations where moisture control challenges adhesive performance.
Strategic Opportunities
- Brazil's ANVISA regulatory pathway:Streamlined equivalence frameworks for Class II dental devices enable faster market entry for adhesives with existing FDA or CE clearance, opening Latin America's largest dental consumables market.
- Bioactive ion-release convergence with digital dentistry:Integration of remineralizing chemistries with CAD/CAM chairside workflows creates premium positioning for adhesives that bond both tooth substrate and ceramic restorations in single-visit protocols.
- Direct-to-specialist e-commerce channels:Platform-based procurement bypasses traditional dental distributor markups, enabling manufacturers to capture margin while offering subscription-based consumable replenishment for high-volume orthodontic practices.
Industry Challenges
- ISO 10993-5 cytotoxicity testing capacity:Laboratory bottlenecks for in vitro biocompatibility validation extend product development timelines, particularly for novel monomer platforms seeking regulatory clearance across multiple jurisdictions.
- Legacy etch-and-rinse protocol entrenchment:Established clinician training and institutional purchasing habits create inertia against universal adhesive adoption, requiring substantial clinical education investment to shift behavior.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Adhesive Market |
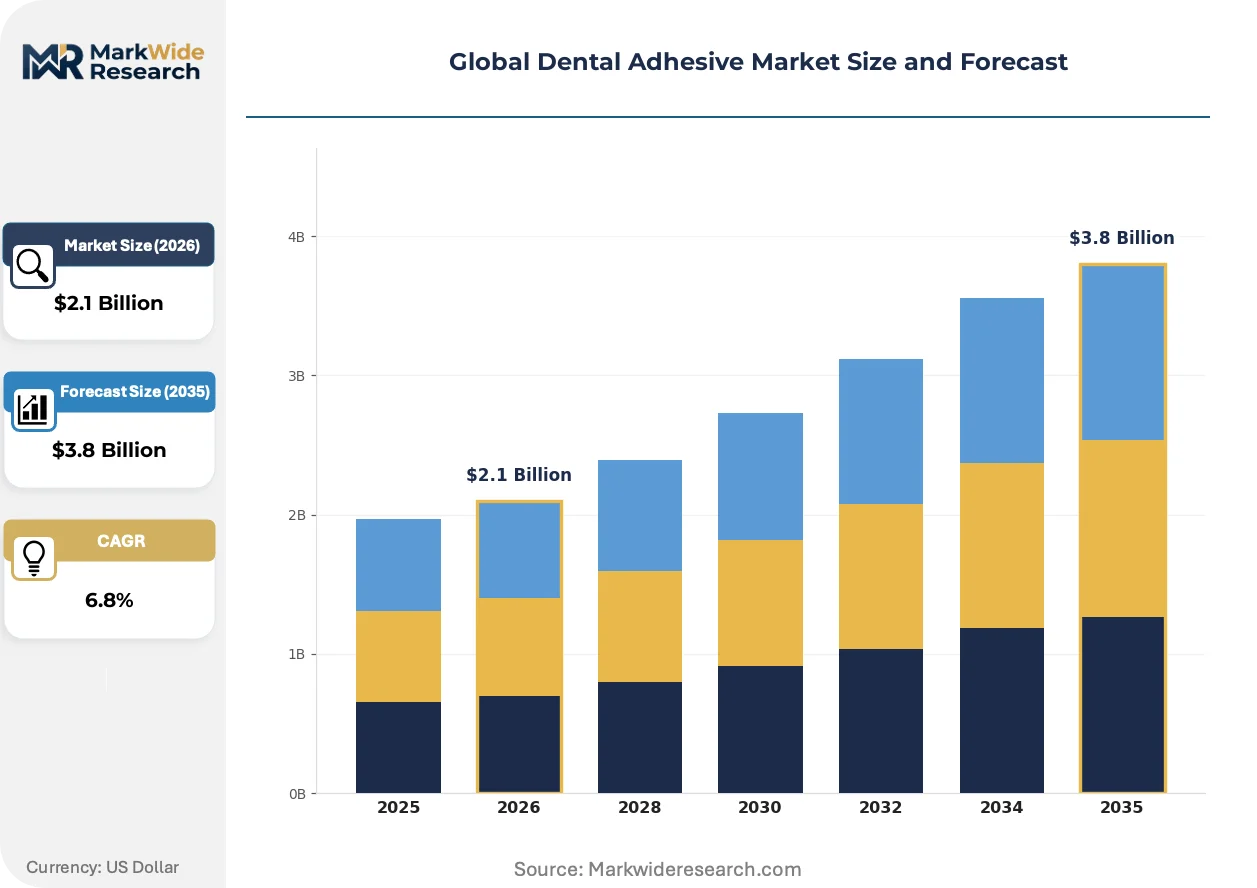
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Etch-and-Rinse Adhesives, Self-Etching Adhesives, Universal Adhesives, Glass Ionomer Cements Application: Direct Restorations, Indirect Restorations, Orthodontics, Periodontics, Prosthodontics End User: Dental Clinics, Specialty Practices, Dental Laboratories, Academic Institutions Packaging Type: Single-Dose Units, Multi-Dose Bottles, Automix Syringes, Capsules |
| Companies Covered | Tokuyama Dental, Kerr Dental, 3M, Ultradent Products, GC Corporation, Dentsply Sirona, Ivoclar Vivadent, Henkel, Kuraray Noritake Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Adhesive Market Shifts & Advancements
Digital dentistry workflows are compressing the restoration timeline from multiple visits to single-appointment protocols, forcing adhesive formulations to perform under accelerated curing schedules and suboptimal moisture conditions. This pressure is reshaping product development priorities across the value chain.
Universal adhesive technology is consolidating the historically separate etch-and-rinse, self-etch, and selective-etch categories into single-bottle systems with pH-tolerant chemistry. General practitioners and dental service organizations are adopting these simplified protocols at accelerating rates to reduce chair time and training burden. The technology is consolidating supplier bases as multi-SKU portfolios compress toward streamlined universal offerings that reduce inventory complexity for group practices.
Japan's PMDA has tightened JIS T 6503 standards for dental cements to require local clinical data submission for market authorization, elevating barriers for foreign manufacturers. This regulatory friction is redirecting investment toward in-country clinical trial infrastructure and partnership strategies with domestic distributors. Premium indirect restoration bonding systems face the steepest compliance burden, as these categories fall under stricter pre-market scrutiny than direct restoration materials.
Group purchasing organizations and dental service organizations are consolidating procurement authority across multi-site practices, displacing individual clinician purchasing autonomy. Traditional full-service dental distributors face margin compression as these consolidated buyers negotiate direct manufacturer relationships or platform-based purchasing. This concentration is most visible in the United States and Germany, where reimbursement structures favor high-volume adhesive consumption in minimally invasive protocols.
Global Dental Adhesive Market Segmentation
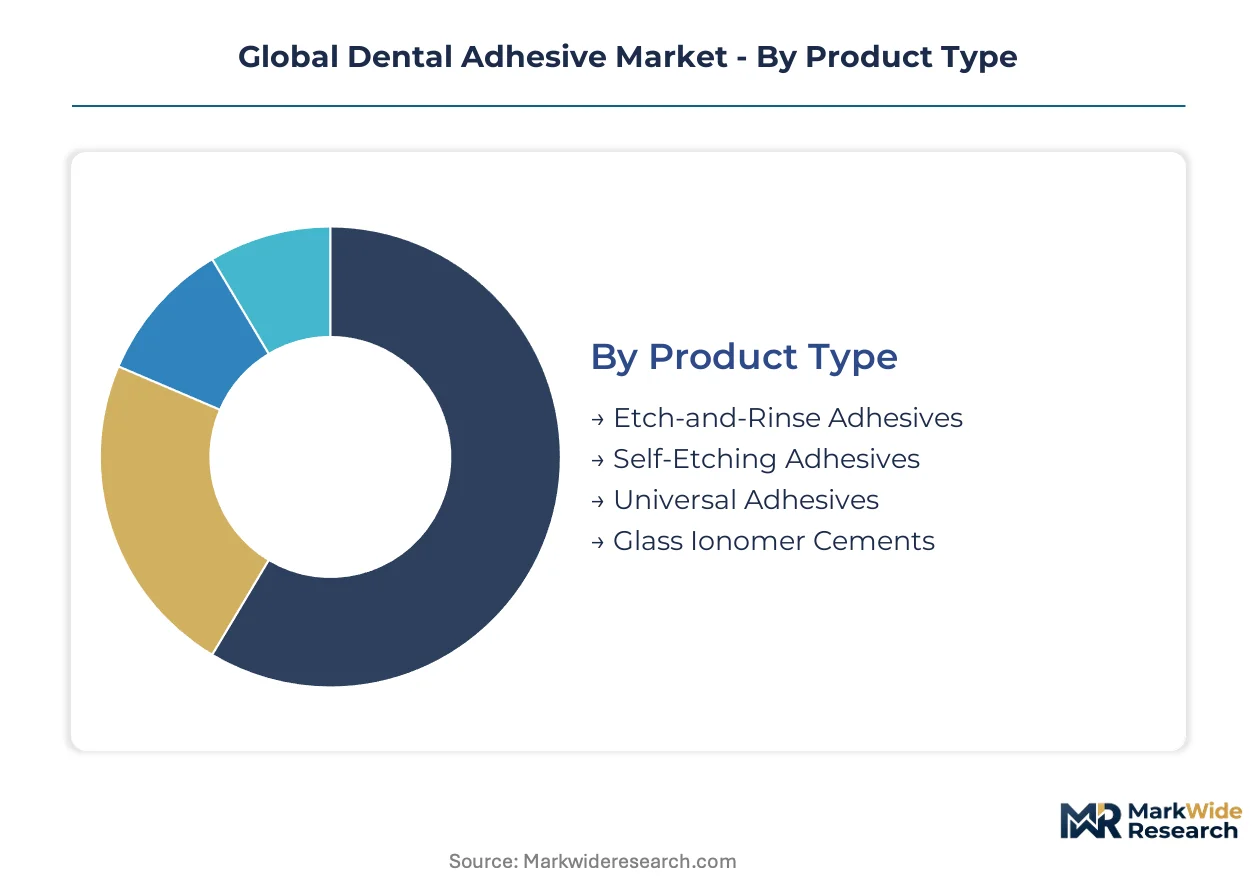
Dental adhesive purchasing decisions pivot on clinical workflow efficiency, regulatory compliance burden, and total cost-per-procedure across diverse practice settings. Manufacturers must align formulation portfolios with distinct technical requirements of direct versus indirect bonding protocols while navigating divergent procurement authority between independent clinicians and consolidated dental service organizations.
Product Type:
Clinicians select adhesive chemistry based on substrate condition, moisture control capability, and desired bond durability rather than price alone.
- Universal Adhesives:These pH-tolerant formulations combine etch-and-rinse and self-etch functionality in single-bottle protocols, reducing inventory complexity and technique sensitivity. Demand concentrates in United States dental service organizations where standardized workflows across multi-site practices prioritize protocol simplification over marginal performance gains.
- Self-Etching Adhesives:Gentler demineralization chemistry preserves collagen matrix integrity in pediatric and geriatric cohorts with compromised dentin. Germany's statutory reimbursement structures favor minimally invasive techniques that reduce post-operative sensitivity claims, accelerating adoption in family practices serving aging populations.
- Etch-and-Rinse Adhesives:Phosphoric acid pre-treatment delivers highest enamel bond strengths for high-stress posterior restorations.
- Glass Ionomer Cements:Fluoride-releasing ionomeric systems dominate pediatric applications where moisture tolerance outweighs aesthetic demands.
Volume sits with Universal Adhesives; growth tilts toward Self-Etching Adhesives.
Application:
Procedure reimbursement rates and restoration longevity requirements create divergent margin structures across clinical specialties.
- Direct Restorations:Immediate chairside bonding of composite resins generates highest absolute consumption volumes through recurrent caries treatment and replacement cycles. Japan's PMDA-enforced JIS T 6503 standards elevate compliance costs for foreign manufacturers, entrenching domestic suppliers in this high-frequency category.
- Orthodontics:Clear aligner attachment bonding creates recurring consumable demand through treatment refinement and replacement protocols. Adult demographic expansion beyond traditional adolescent segments in United States and Germany drives premium positioning for light-cure systems with rapid polymerization kinetics.
- Indirect Restorations:Cementation of CAD/CAM-fabricated crowns and bridges demands dual-cure capability for opaque ceramic substrates.
- Periodontics:Surgical site bonding applications require biocompatible formulations with minimal cytotoxicity profiles.
- Prosthodontics:Removable prosthesis adhesive applications serve edentulous populations with specific retention challenges.
Revenue concentrates in Direct Restorations; margin expansion centers on Orthodontics.
End User:
Procurement authority distribution determines channel strategy and pricing architecture across customer types.
- Dental Clinics:General practice settings generate foundational demand volume through restorative and preventive procedures. Group purchasing organization consolidation in United States compresses distributor margins while favoring manufacturers with direct contracting capabilities and subscription replenishment platforms.
- Specialty Practices:Orthodontic and prosthodontic specialists command premium formulations with validated clinical performance data. Germany's private reimbursement environment supports higher per-procedure adhesive expenditure compared to statutory-insurance-dominated general practice segments.
- Dental Laboratories:Outsourced restoration fabrication creates demand for dual-cure resin cements with extended working times.
- Academic Institutions:Training programs drive early-career protocol standardization and brand preference formation.
Transaction volume flows through Dental Clinics; premium capture targets Specialty Practices.
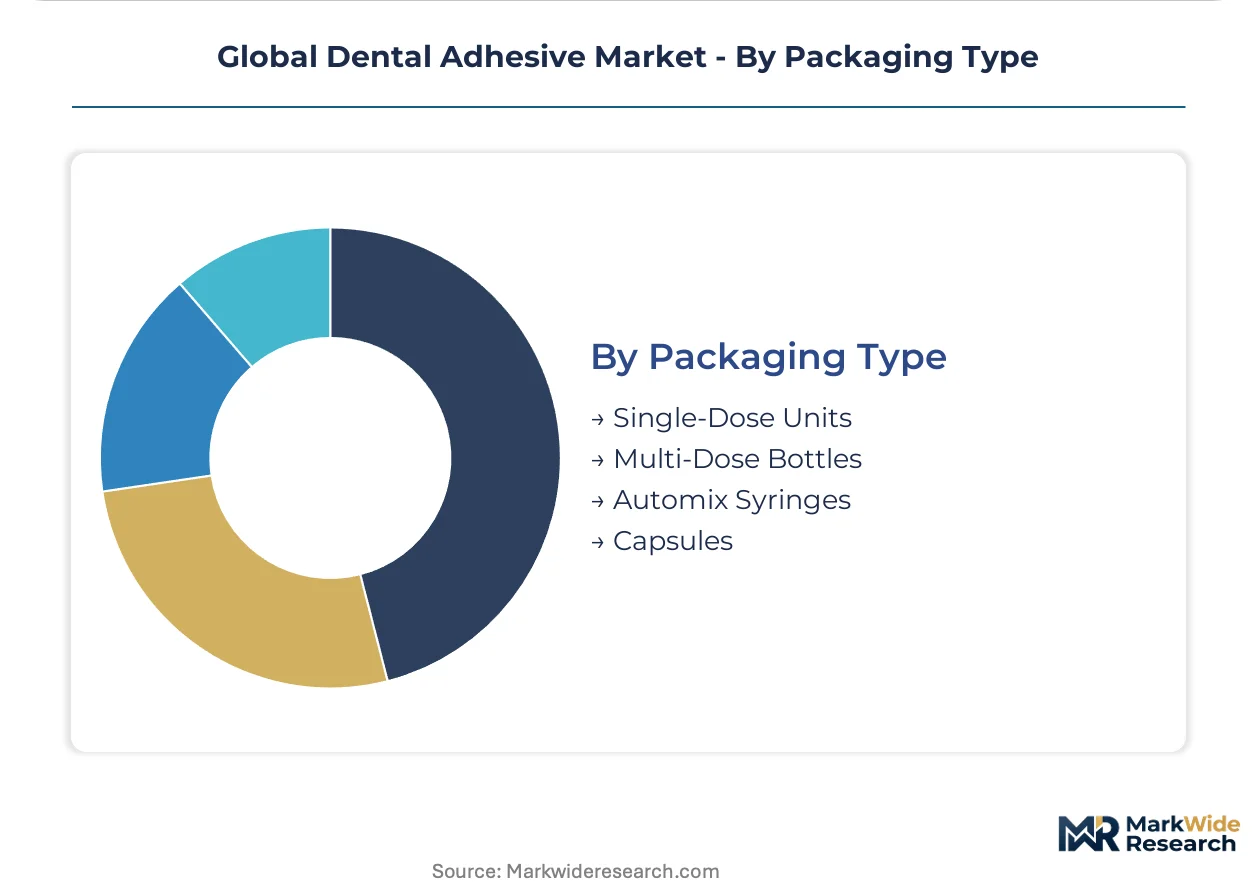
Packaging Type:
Infection control protocols and chairside workflow efficiency dictate format selection across practice modalities.
- Single-Dose Units:Pre-dispensed, unit-dose packaging eliminates cross-contamination risk and ensures optimal monomer stability through sealed barrier protection. Japan's stringent infection control guidelines and aging practitioner population favor disposable formats that reduce preparation burden.
- Multi-Dose Bottles:Bulk packaging serves high-volume practices with predictable consumption patterns and robust inventory management systems. United States dental service organizations leverage scale procurement to offset per-unit cost advantages against spoilage risk from repeated bottle opening.
- Automix Syringes:Dual-barrel delivery systems ensure precise base-catalyst ratios for self-cure resin cements.
- Capsules:Mechanical mixing systems provide consistent filler dispersion for glass ionomer applications.
Cost efficiency favors Multi-Dose Bottles; infection control compliance accelerates Single-Dose Units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Hamburg concentrate dental adhesive manufacturing and distribution infrastructure, with tax incentives pulling formulation facilities toward coastal logistics hubs. These zones anchor supply chain efficiency for multinational suppliers serving adjacent consumer markets.
United States
Dental service organizations consolidate procurement across multi-site practices, favoring standardized universal adhesive protocols. The FDA enforces Class II medical device standards under 21 CFR 872 with ISO 10993 biocompatibility testing. Minneapolis-St. Paul hosts 3M's materials science operations, driving simplified clinical workflow development.
Germany
Statutory reimbursement structures incentivize minimally invasive adhesive techniques in family practices serving aging populations. EU MDR notified body concentration in Berlin and Munich creates certification bottlenecks for foreign manufacturers. The Rhine-Ruhr corridor anchors glass ionomer R&D through sustained industrial chemistry investment.
Japan
PMDA-enforced JIS T 6503 standards require local clinical data submission, elevating compliance costs for imported formulations. Tokyo's dental distributor networks favor single-dose packaging formats aligned with stringent infection control protocols. Domestic suppliers capture share in high-frequency direct restoration categories.
Brazil
ANVISA's streamlined equivalence frameworks for Class II dental devices accelerate market entry for adhesives with existing FDA or CE clearance. São Paulo's dental consumables distribution hub serves Latin America's largest addressable market. Private dental insurance expansion drives premium product penetration beyond public sector procurement.
China
Domestic clear aligner therapy adoption generates recurring attachment bonding demand across tier-one cities. NMPA medical device registration requirements intensify for resin-based dental materials with novel monomer platforms. The Yangtze River Delta concentrates contract manufacturing for multinational adhesive brands serving Asia-Pacific markets.
Global Dental Adhesive Market Competitive Landscape
Top-tier vendors anchor premium indirect restoration and universal adhesive segments, while mid-tier specialists occupy bioactive ion-release and pediatric formulation niches. The vendor base distributes across diversified materials conglomerates, dedicated dental consumables manufacturers, and regional formulation specialists. Three archetypes dominate: universal protocol simplifiers, bioactive chemistry innovators, and orthodontic consumable pure-plays. Competitive dynamics center on M&A-driven portfolio consolidation and direct-to-specialist e-commerce channel development.
Within the universal adhesive tier, 3M and GC Corporation occupy positions reflecting materials science heritage and sustained R&D investment in simplified clinical protocols. Kerr Dental and Ultradent Products exemplify the mid-tier specialist archetype with concentrated focus on practitioner-centric workflow solutions. Tokuyama Dental and Kuraray Noritake Dental represent Japanese-origin manufacturers navigating PMDA regulatory requirements while serving domestic and export markets.
| Leading Market Players |
|---|
| Tokuyama Dental |
| Kerr Dental |
| 3M |
| Ultradent Products |
| GC Corporation |
| Dentsply Sirona |
| Ivoclar Vivadent |
| Henkel |
| Kuraray Noritake Dental |
| Others |
Supply & Pricing Matrix
Group purchasing organization consolidation across United States dental service organizations is compressing distributor markups and forcing manufacturers toward direct contracting models that reshape margin allocation across formulation tiers.
Pricing Analysis
Short lead-time premiums attach to single-dose unit formats demanded by Japan's infection control protocols, while spot inventory discounts flow to multi-dose bottle purchasers in high-volume German practices. Three-tier pricing structure across premium, standard, and economy levels separates bioactive ion-release formulations from universal adhesives and commodity glass ionomer cements. Pricing pressure stems from bisphenol A glycol methacrylate feedstock volatility that constrains pass-through capability in economy tiers. Dental clinics exhibit highest price sensitivity through GPO-negotiated contracts, while specialty orthodontic practices absorb premium positioning for rapid-cure systems.
Supply Chain Analysis
Regional distribution centers in Minneapolis-St. Paul, Tokyo, and the Rhine-Ruhr corridor anchor hub-and-spoke patterns serving adjacent consumer markets with tax-advantaged logistics. Manufacturing concentration rests on Germany, Japan, and the United States for proprietary monomer synthesis and formulation finishing. Raw material dependencies center on petrochemical-derived methacrylate monomers, phosphate-ester coupling agents, and nano-filler particles sourced from specialty chemical suppliers. Single-source vulnerability concentrates in 10-methacryloyloxydecyl dihydrogen phosphate precursor supply. Distribution runs through full-service dental distributors facing compression from direct-to-specialist e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 10993-5 cytotoxicity testing laboratory bottlenecks constrain new monomer platform validation throughput, propping pricing for cleared formulations across multiple jurisdictions.
For Market Incumbents: Acquire regional distribution networks in Brazil and China to preempt ANVISA and NMPA pathway congestion for emerging competitors. Consolidate bioactive ion-release R&D capabilities to defend against glass ionomer substitution in pediatric segments. Backward integration into phosphate-ester monomer production mitigates single-source feedstock risk. For New Entrants and Emerging Players: Direct-to-specialist e-commerce platforms offer lowest channel friction for orthodontic consumable penetration in United States and Germany. Brazil's ANVISA equivalence frameworks present the most penetrable regulatory entry point for FDA-cleared universal adhesives. Target clear aligner attachment bonding workflows with subscription replenishment models. For Investors and Strategic Acquirers: Re-rating potential sits with bioactive chemistry innovators given EU MDR biocompatibility threshold escalation and fluoride-release convergence with digital dentistry. Five-to-ten year viability favors specialists with validated clinical data packages across FDA, CE, and PMDA jurisdictions. Signal to watch: notified body capacity expansion in Germany and Netherlands as approval bottleneck resolution indicator.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body concentration in Berlin and Munich creates 12-18 month certification delays for non-European manufacturers. |
| Backward Integration | In-house production of 10-methacryloyloxydecyl dihydrogen phosphate precursors reduces petrochemical feedstock price swing exposure. |
| Direct-to-Specialist E-Commerce | Platform-based procurement bypasses traditional dental distributor markups while enabling subscription-based consumable replenishment. |
| Hospital System Partnership | Dental service organization consolidation favors manufacturers with direct contracting capabilities across multi-site practices. |
| Reimbursement Strategy | Germany's statutory insurance structures favor minimally invasive adhesive techniques that reduce post-operative sensitivity claims. |
Research Methodology
Multi-period observation of adhesive protocol adoption rates, regulatory submission timelines, and procurement pattern shifts anchored the trend analysis, supplemented by interviews with formulation chemists, dental service organization procurement directors, GPO contracts managers, and orthodontic practice administrators. Secondary validation drew from FDA 510(k) filings, EMA notified body designation records, PMDA clinical data submission requirements, and customs trade data for methacrylate monomer imports. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation converged on segment-level estimates.
Input-output matrices mapped formulation chemistry types to end-use applications across direct restorations, orthodontics, indirect restorations, periodontics, and prosthodontics. Segmentation dimensions spanned product type, application, end user, and packaging format with regional regulatory cluster overlays. CAGRs were derived from procedure frequency projections, replacement cycle assumptions, and premium product mix shifts throughout the forecast period. Forecast inputs incorporated clear aligner therapy expansion rates and EU MDR compliance cost pass-through coefficients.
Caveats apply where ISO 10993-5 testing capacity constraints, notified body approval delays, or per- and polyfluoroalkyl substance regulatory restrictions could materially shift the outlook for novel monomer platforms. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Calcium Hydroxylapatite Fillers Market
Dental Materials
Zirconia Based Dental Ceramics Market
Dental Materials
Charcoal Teeth Whitening Powder Market
Dental Materials
Dental Fiberglass Posts Market
Dental Materials
Fluoride Mouthwash Market
Dental Materials
Dental Plaster Market
Dental Materials
Dental Materials for 3D Printing Market
Dental Materials
Global Dental Zirconia Block Market
Dental Materials
Crack Tooth Syndrome Market
Dental Materials
Tooth Filling Materials Market
Dental Materials
Global Dental Bone Void Filler Market
Dental Materials
Dental Cavity Filling Material Market
Dental Materials
Oral Bone Implant Material Market
Dental Materials
Nanotechnology Toothpaste Formulations Market
Dental Materials
Global Dental Membrane and Bone Graft Substitutes Market
Dental Materials
Dental Fluoride Varnish Market