
 Dental Materials for 3D Printing Market | 2026-2036
Dental Materials for 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Materials for 3D Printing Market Insights
Trained dental technicians with digital design competencies is reorganizing production economics across dental laboratories worldwide. Stratasys leverages its polymer expertise to dominate hardware-software integration for chairside workflows. Formlabs sustains market presence through accessible desktop systems that lower capital barriers for mid-sized labs. EOS GmbH anchors industrial-grade metal and polymer production for high-throughput dental manufacturing networks.
Dental materials for 3D printing comprise photopolymerizable resins, ceramic-filled composites, and wax-based formulations engineered for biocompatibility, dimensional accuracy, and mechanical properties matching natural dentition, typically processed through vat photopolymerization or powder bed fusion to produce patient-specific restorative and prosthetic devices. Resins currently lead material type segments due to mature formulation libraries and broad printer compatibility, while ceramic composites represent the fastest-growing category as laboratories pursue metal-free alternatives with superior aesthetics. Among applications, crowns and bridges command the largest volume share given their ubiquity in restorative dentistry, whereas orthodontic devices are expanding rapidly as clear aligner production scales.
FDA regulates these materials as Class II medical devices requiring 510(k) premarket notification, while ISO 10993 biocompatibility testing and ISO 13485 quality management standards govern international market access and manufacturing consistency. The EU Medical Device Regulation imposes additional clinical evaluation and post-market surveillance obligations on manufacturers distributing in Europe. Stakeholders must monitor evolving regulatory harmonization between FDA and notified body requirements as digital workflows compress traditional validation timelines.
Market Dynamics
Photopolymer resin formulation advances are compressing production timelines for same-day dental restorations, forcing laboratories to restructure technician workflows and capital deployment around chairside manufacturing capabilities.
Growth Catalysts
- ISO 13485 harmonization:Quality management standardization across EU notified bodies and FDA 510(k) pathways is accelerating material qualification cycles for dental resin manufacturers seeking dual-market clearance.
- Stuttgart-Munich laboratory cluster:Precision manufacturing ecosystems in southern Germany concentrate digital dentistry expertise, creating knowledge spillovers that lower adoption barriers for mid-sized European laboratories.
- Vat photopolymerization maturation:Printer hardware reliability improvements and open-material platforms are expanding resin formulation competition beyond proprietary ecosystems.
Market Restraints
- Raw material concentration:Specialty acrylate monomer supply concentrates among German and Japanese chemical suppliers, exposing resin formulators to input cost volatility and allocation risk during supply shocks.
- Biocompatibility testing burden:ISO 10993 cytotoxicity and sensitization protocols require 12-18 month validation timelines that delay product commercialization and tie up R&D capital.
- Milled zirconia substitution:Subtractive CAD/CAM systems retain cost advantages for full-contour crowns in high-volume laboratories, limiting addressable market expansion for printed ceramic composites.
Strategic Opportunities
- India dental laboratory modernization:CDSCO medical device rules alignment with ISO standards creates regulatory runway for imported resin systems as domestic digital dentistry infrastructure scales.
- Clear aligner direct manufacturing:Orthodontic device production bypassing traditional thermoforming represents white-space expansion for high-temperature resistant resin formulations.
- EU MDR post-market surveillance:Clinical evaluation requirements for permanent restorative materials favor established manufacturers with vigilance infrastructure, creating consolidation incentives.
Industry Challenges
- Digital design competency gaps:Trained technicians capable of operating CAD software and printer calibration remain scarce relative to laboratory demand, inflating wage costs and constraining throughput scaling.
- Legacy equipment integration:Chairside workflows require interoperability with existing intraoral scanners and milling units, forcing middleware investments that complicate ROI calculations for smaller laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Materials for 3D Printing Market |
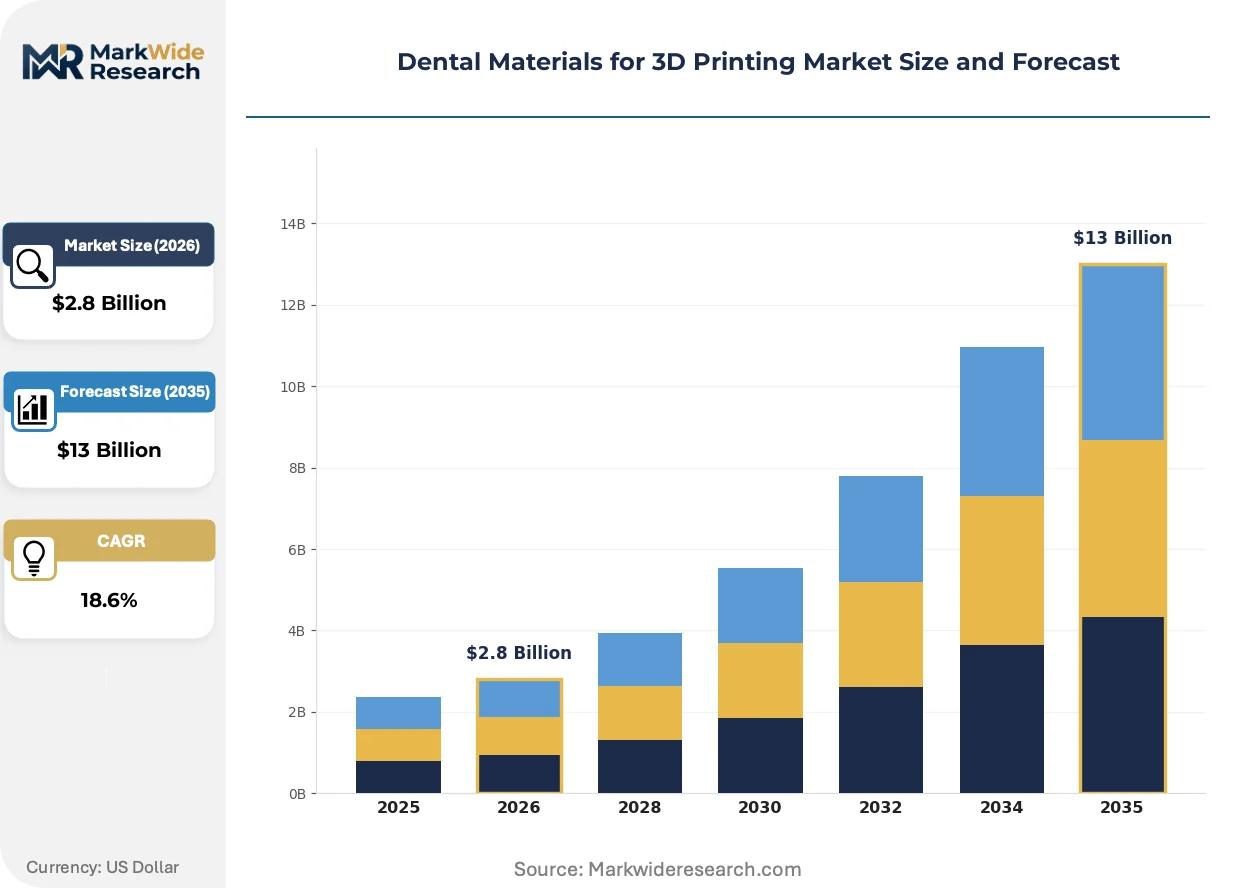
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Resins, Polymer Composites, Wax, Ceramics Application: Crowns, Bridges, Dentures, Orthodontic Devices Technology: SLA, SLS, FDM, DLP End User: Dental Clinics, Dental Laboratories, Research Institutions, Educational Institutions |
| Companies Covered | Stratasys, 3D Systems, Formlabs, Desktop Metal, Carbon, Renishaw, EOS GmbH, EnvisionTEC GmbH, Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Materials for 3D Printing Market Trends and Innovations
Material science advances are fragmenting traditional supply relationships as resin formulators bypass hardware OEMs to serve laboratories directly through validated open-platform partnerships.
Ceramic-filled hybrid resins are decomposing the historical separation between temporary and definitive restorations by delivering flexural strength and wear resistance comparable to milled glass ceramics. High-throughput dental laboratories in Germany and Switzerland are adopting these formulations for definitive crown production, collapsing the traditional two-appointment workflow into single-visit dentistry. This compression is decomposing the economic rationale for centralized milling center networks that dominated restorative logistics over the past decade.
EU MDR clinical evaluation requirements for Class IIa permanent implants are extending material validation timelines, forcing resin manufacturers to maintain larger clinical trial cohorts than under the preceding Medical Device Directive. Laboratories sourcing MDR-compliant materials face certificate transition deadlines through 2028, with notified body backlog creating approval bottlenecks for smaller formulators. German and French dental associations are responding by consolidating preferred supplier lists to reduce compliance verification overhead.
Dental laboratories are consolidating procurement authority into dedicated supply chain functions that negotiate resin contracts based on validated batch consistency metrics rather than per-unit pricing. This professionalization displaces the traditional technician-driven purchasing model where material selection followed hardware manufacturer recommendations. The shift is most pronounced in Netherlands and Belgium, where laboratory group purchasing organizations now aggregate demand across fifty-plus member facilities to extract quality-guaranteed supply agreements.
Dental Materials for 3D Printing Market Segmentation
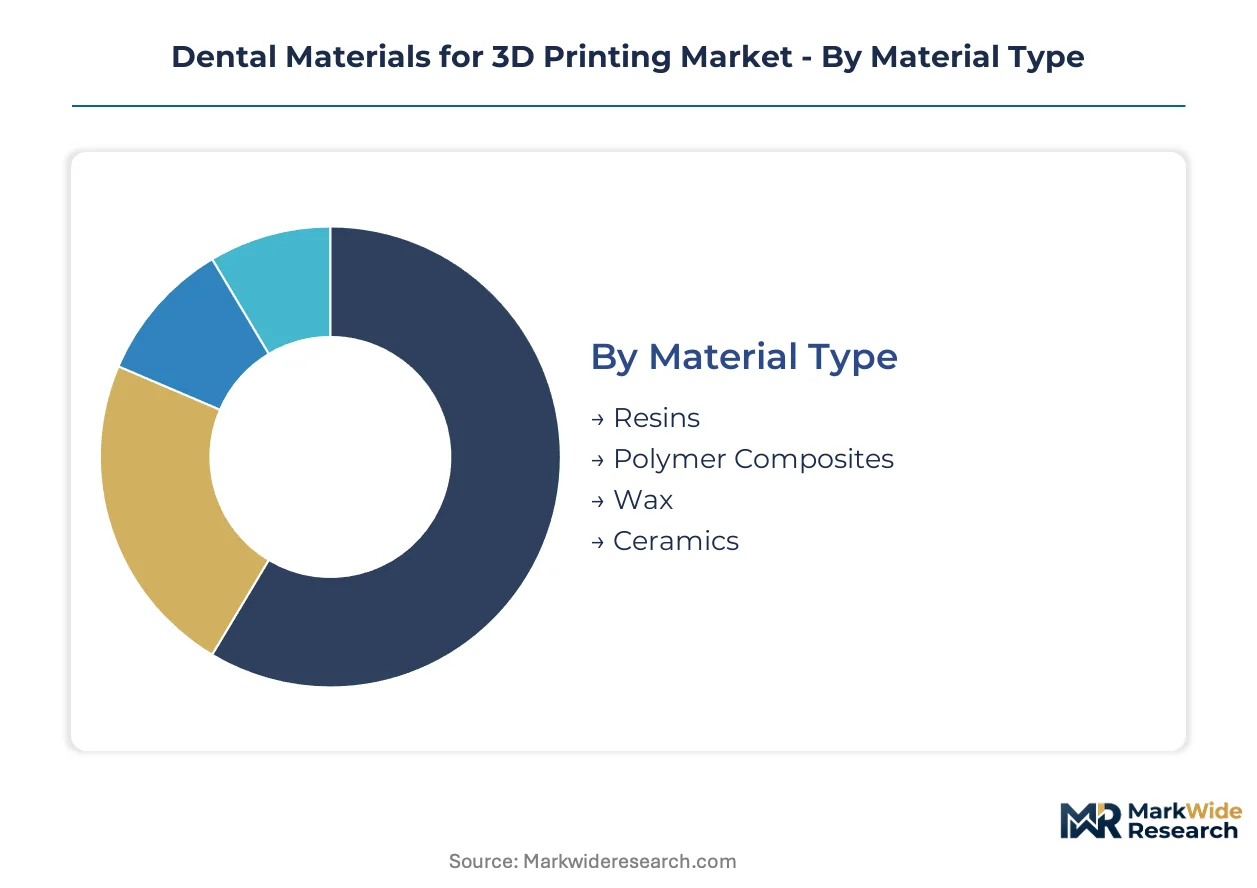
Material selection in dental 3D printing determines regulatory pathway complexity, biocompatibility testing burden, and end-use applicability. Laboratories structure procurement around validated material-printer combinations that satisfy ISO 10993 and FDA 510(k) requirements for patient contact duration.
Material Type:
FDA Class II clearance timelines diverge substantially across material chemistries, with permanent restorative formulations facing extended cytotoxicity validation against temporary or wax-based alternatives.
- Resins:Photopolymerizable acrylate and methacrylate formulations dominate chairside workflows through vat photopolymerization systems. Demand concentrates in German dental laboratories pursuing same-day crown production, constrained by specialty monomer supply concentration among Japanese and German chemical suppliers.
- Polymer Composites:Ceramic-filled hybrid systems deliver flexural strength approaching milled glass ceramics for definitive restorations. Laboratories in Switzerland and the Netherlands are adopting these formulations to collapse traditional two-appointment workflows into single-visit dentistry.
- Wax:Burn-out formulations optimized for investment casting of metal frameworks and ceramic-fused-to-metal restorations.
- Ceramics:Alumina and zirconia suspensions for high-strength definitive applications requiring metal-free aesthetics.
Resins handle the majority of throughput; polymer composites are gaining share fastest as laboratories pursue definitive restoration capabilities without milling infrastructure.
Application:
Clinical workflow economics vary sharply by restoration complexity, with single-unit restorations enabling chairside production while multi-unit prostheses favor centralized laboratory manufacturing.
- Crowns:Single-tooth restorations represent the highest volume application, with digital workflows compressing production to under two hours. German and Swiss laboratories lead adoption of printed definitive crowns using ceramic-filled resins.
- Bridges:Multi-unit fixed prostheses demand higher mechanical reliability and connector strength specifications. Centralized high-throughput laboratories in Stuttgart and Munich cluster process these through validated open-platform resin systems.
- Dentures:Full and partial removable prostheses utilizing biocompatible base resins and characterized teeth.
- Orthodontic Devices:Clear aligner production and indirect bonding trays represent expanding application scope.
Crowns generate the highest absolute volume; orthodontic devices are expanding most quickly as direct aligner manufacturing bypasses traditional thermoforming.
Technology:
Hardware selection locks laboratories into specific material ecosystems, with open-platform strategies increasingly displacing proprietary consumable models.
- SLA:Laser-based vat photopolymerization delivers highest resolution for margin-critical crown applications. German laboratories favor industrial SLA systems for production consistency.
- SLS:Powder bed fusion enables nylon and PEEK frameworks for removable partial dentures and surgical guides.
- FDM:Filament extrusion serves low-cost prototyping and educational applications with limited clinical throughput.
- DLP:Projector-based vat systems offer speed advantages for full-arch models and aligner manufacturing.
SLA retains premium positioning for definitive restorations; DLP is climbing fastest on aligner production scaling.
End User:
Capital deployment and regulatory compliance capabilities segment end users into distinct procurement authority structures.
- Dental Clinics:Chairside systems require compact footprints and simplified workflows for same-day delivery. Stuttgart-area clinics integrate intraoral scanners with validated printer-resin combinations.
- Dental Laboratories:High-throughput facilities in Germany, Switzerland, and the Netherlands consolidate procurement through group purchasing organizations demanding batch consistency guarantees.
- Research Institutions:Academic dental schools and materials science departments drive next-generation formulation development.
- Educational Institutions:Training programs build digital design competency pipelines for technician workforce development.
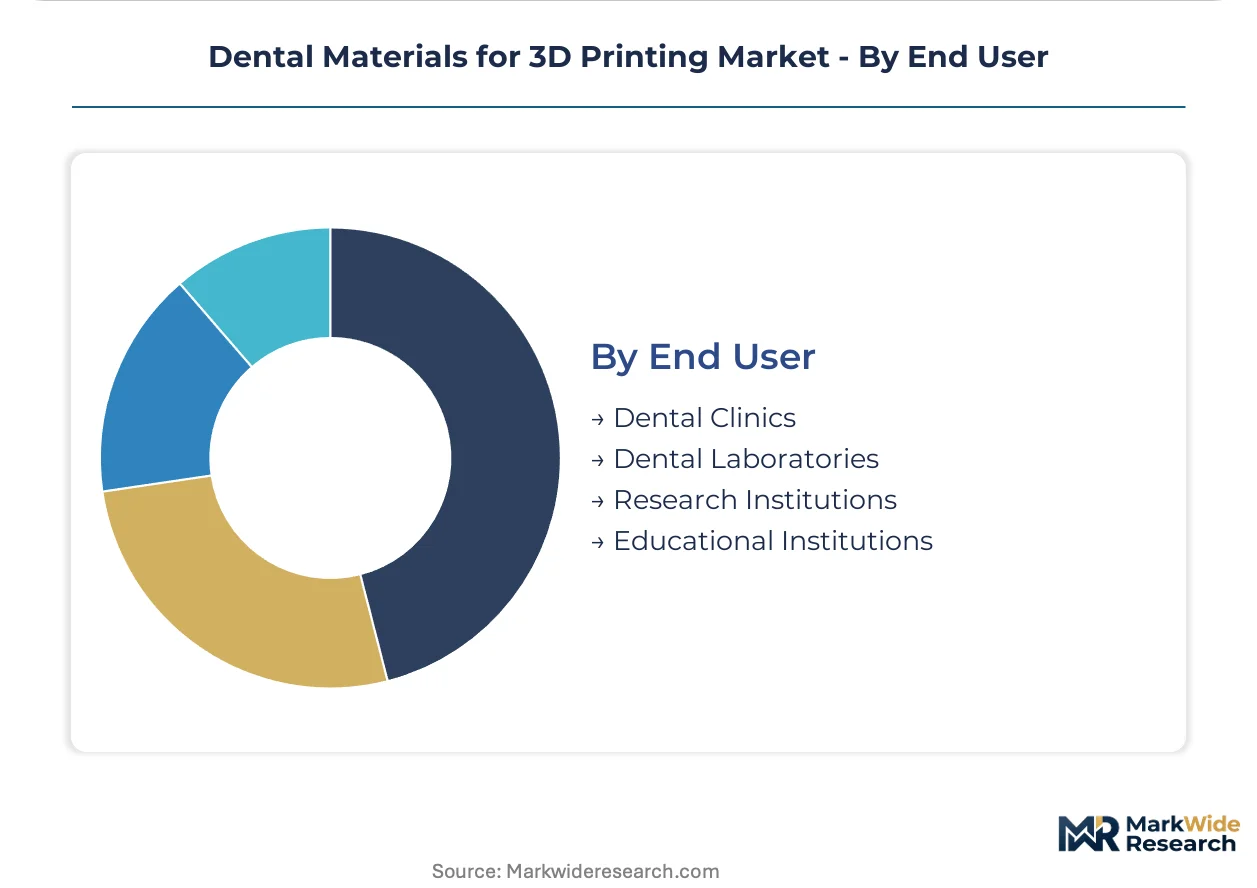
Dental laboratories command the dominant share of material volume; clinics are expanding fastest as chairside economics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dental laboratories consume ceramic-filled resins for definitive crowns at triple the per-capita rate of US counterparts, where chairside workflows still favor temporary materials. Swiss and Dutch facilities cluster around group purchasing organizations that enforce batch consistency standards unknown in fragmented Asian markets.
Germany
Laboratories in Stuttgart and Munich drive photopolymer resin consumption for same-day crown production, with technician wages compressing adoption timelines for smaller facilities. BfArM oversight of EU MDR compliance creates certificate bottlenecks through 2028, favoring established formulators with clinical trial infrastructure. The Baden-Württemberg precision manufacturing corridor concentrates digital dentistry expertise and resin validation capabilities.
United States
FDA 510(k) clearance pathways attract resin manufacturers seeking rapid market entry, though Class II device timelines still demand 12-18 month biocompatibility validation. Dental clinics in California and Texas deploy chairside systems for single-visit restorations, outpacing laboratory adoption rates. The Greater Boston area anchors academic research partnerships between dental schools and materials science departments.
Switzerland
Swissmedic requirements for permanent restorative materials exceed EU baseline standards, creating premium positioning for validated ceramic composite formulations. Laboratory networks in Zurich and Geneva consolidate procurement through quality-guaranteed supply agreements rather than per-unit pricing. The Basel pharmaceutical manufacturing ecosystem spills over into dental resin formulation expertise.
India
CDSCO alignment with ISO 13485 standards opens regulatory runway for imported resin systems as domestic digital dentistry infrastructure scales. Dental laboratories in Maharashtra and Karnataka modernize through government medical device manufacturing incentives. Mumbai-Pune corridor clusters concentrate technician training programs and CAD software adoption.
Japan
PMDA medical device regulations enforce extended clinical evaluation timelines that delay ceramic composite commercialization versus Western markets. Dental laboratories in Tokyo and Osaka maintain hybrid workflows combining printed wax patterns with traditional casting. The Nagoya industrial belt supplies specialty acrylate monomers to domestic and international resin formulators.
Dental Materials for 3D Printing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hardware-software bundling determining procurement authority in high-throughput laboratories. The upper tier commands premium positioning through validated open-platform ecosystems that decouple material selection from printer manufacturer constraints. Mid-sized specialists compete on resin formulation differentiation and regional regulatory expertise. Dominant competitive moves include strategic partnerships between resin formulators and laboratory group purchasing organizations, plus backward integration into specialty monomer supply by integrated chemical firms.
Among hardware-integrated leaders, Stratasys and 3D Systems exemplify the bundled ecosystem archetype that dominates North American chairside deployments. EOS GmbH anchors the industrial-grade production tier for centralized laboratory networks in Germany and Switzerland. Formlabs occupies a position bridging accessible desktop systems with professional validation standards, representing the specialist tier's challenge to integrated leaders.
| Leading Market Players |
|---|
| Stratasys |
| 3D Systems |
| Formlabs |
| Desktop Metal |
| Carbon |
| Renishaw |
| EOS GmbH |
| EnvisionTEC GmbH |
| Dentsply Sirona |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at high-throughput dental laboratories in Stuttgart and Munich compresses per-unit resin costs while elevating price floors for smaller facilities lacking batch scale. This asymmetry concentrates procurement leverage among group purchasing organizations that negotiate validated supply agreements based on ISO 13485 compliance tiers rather than per-kilogram pricing.
Pricing Analysis
Contract structures in dental materials stratify across annual volume commitments, spot purchases for formulation trials, and project-based engagements for custom biocompatibility validation. Price differentiation separates FDA 510(k) cleared permanent restorative resins from temporary material tiers, with certification grade and geographic delivery cost as primary drivers. Pricing pressure stems from milled zirconia substitution in high-volume crown applications, forcing resin formulators to bundle technical support. Mid-sized laboratories exhibit highest price sensitivity due to capital constraints for chairside workflow integration.
Supply Chain Analysis
Inbound logistics costs for specialty acrylate monomers from Nagoya and Ludwigshafen fluctuate with container availability on Asia-Europe trade lanes, compressing margins for resin formulators without captive chemical production. Geographic supply concentration centers on Japan and Germany for monomer inputs, with the Netherlands and Switzerland for formulation and finishing. Raw material dependencies include photoinitiators from BASF and ceramic fillers from Saint-Gobain. Single-source vulnerability in specialty monomer supply creates allocation risk during chemical sector shocks. Distribution runs through laboratory group purchasing organizations and direct manufacturer partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as chairside workflow adoption splinters demand across mid-sized laboratories lacking digital design competency, creating niches for specialized resin formulators with regulatory fast-track capabilities.
For Market Incumbents: Shield market position through backward integration into specialty monomer supply and accelerated MDR clinical trial cohorts. Ceramic-filled hybrid formulations from emerging Asian competitors threaten premium positioning in definitive restoration segments. Certification investment in ISO 10993 extended validation protocols preserves preferred supplier status with German group purchasing organizations.
For New Entrants and Emerging Players: FDA 510(k) pre-submission pathways offer fastest clearance timelines for resin formulations targeting temporary crown applications. White-space expansion concentrates in Indian dental laboratory modernization and direct clear aligner manufacturing bypassing thermoforming. Go-to-market positioning through open-platform printer compatibility lowers hardware bundling barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors resin formulators with validated batch consistency infrastructure and EU MDR vigilance capabilities. Long-term viability rests on clinical evaluation data assets that compound regulatory moats. Acquisition targets include ceramic composite specialists with Swissmedic clearance and backward-integrated monomer producers. Signal to watch: notified body backlog resolution accelerating smaller formulator consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Open-Platform Resin Validation | Decouples material procurement from Stratasys and 3D Systems hardware ecosystems. |
| Backward Monomer Integration | Captures margin from Nagoya chemical suppliers exposed to allocation volatility. |
| MDR Clinical Trial Expansion | Builds certificate buffers against BfArM backlog through 2028 transition deadlines. |
| India CDSCO Registration | Establishes regulatory runway as Maharashtra laboratory infrastructure scales. |
| Group Purchasing Organization Partnership | Locks batch-guaranteed supply contracts with Netherlands and Belgium laboratory networks. |
Research Methodology
Desk research of FDA 510(k) device listings, ISO 13485 certification databases, and dental laboratory trade association membership records preceded structured interviews with resin formulation chemists, dental laboratory procurement managers, and notified body auditors. Primary fieldwork with Stuttgart and Munich laboratory technicians validated workflow adoption timelines. Secondary sources included BfArM MDR guidance documents, CDSCO medical device rules, and customs trade data for specialty acrylate monomer flows. Bottom-up resin consumption estimates triangulated against top-down dental restoration procedure volumes.
Variance decomposition across material type, application, technology, and end-user segments shaped the analytical framework over the projection horizon. Modeled dimensions included permanent versus temporary restoration classification, chairside versus centralized laboratory workflow, and open-platform versus proprietary printer ecosystem. CAGRs derived from segment-level adoption curves weighted by regulatory clearance timelines. Industry-specific inputs captured EU MDR certificate transition deadlines and FDA biocompatibility validation bottlenecks.
Decision-makers should treat outputs as directional under assumptions of sustained ISO 13485 harmonization and stable specialty monomer supply from Japanese and German chemical producers; material deviation in regulatory alignment or input cost volatility would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Dental Bonding Agent Market
Dental Materials
Sensitive Toothpaste Market
Dental Materials
Fluoride Materials Market
Dental Materials
Dental Fiber Posts Market
Dental Materials
Dental Composites Market
Dental Materials
Artificial Teeth Market
Dental Materials
Dental Wax Market
Dental Materials
Cold Light Teeth Whitening Kit Market
Dental Materials
Solid Toothpaste Market
Dental Materials
Global Dental Cements Market
Dental Materials
Nanotechnology Toothpaste Formulations Market
Dental Materials
Teeth Whitening Market
Dental Materials
Global Dental Zirconia Block Market
Dental Materials
Global Dental Bone Void Filler Market
Dental Materials
Dental Fiberglass Posts Market