
 Amino Acid Chelates Market | 2026-2036
Amino Acid Chelates Market Size, Share, and Industry Trends Forecast 2026-2036
Amino Acid Chelates Market Analytics
The EU Green Deal is broadening demand for bioavailable mineral formulations that reduce environmental discharge from livestock and crop operations. Albion Minerals leverages its specialized chelation technology to occupy premium positions in human nutrition and animal health channels. Balchem Corporation sustains manufacturing scale across North American and European production facilities. BASF SE anchors its portfolio with macromolecule chelate lines serving pharmaceutical and agricultural end users.
Amino acid chelates are coordination compounds formed when mineral ions bind to amino acid ligands through coordinate covalent bonds, typically achieving 1:1 or 2:1 molar ratios that enhance intestinal absorption compared to inorganic mineral salts. Their primary industrial purpose centers on delivering essential minerals with higher bioavailability for nutritional fortification in living organisms. Mineral chelates dominate current volume flows due to established use in animal feed premixes and agricultural fertilizers, while trace element chelates represent the fastest-expanding category as livestock producers and nutraceutical companies prioritize selenium, zinc, and chromium formulations. Powder forms retain the largest share of commercial shipments, though liquid chelates are gaining traction in precision agriculture applications requiring foliar spray compatibility.
The European Food Safety Authority (EFSA) evaluates chelated mineral safety and efficacy claims under feed additive regulations, directly influencing product registration timelines and label permissions for manufacturers seeking EU market access. India's FSSAI and BIS frameworks govern chelate purity standards and food-grade certifications, creating compliance thresholds that filter supplier participation in domestic nutraceutical and food additive channels. The US FDA and EPA jointly oversee chelated mineral applications across pharmaceutical and agricultural domains, with the latter regulating runoff implications from fertilizer use. Stakeholders must monitor evolving bioavailability validation requirements and regional certification reciprocity agreements to optimize manufacturing location decisions and registration investment sequencing.
Market Dynamics
The EU Green Deal's tightening restrictions on inorganic mineral runoff are accelerating livestock producer migration toward bioavailable chelated formulations that reduce environmental discharge while maintaining nutritional efficacy.
Growth Catalysts
- EU Green Deal nutrient discharge limits:Agricultural operations across Germany, France, and the Netherlands face binding caps on zinc and copper runoff, redirecting fertilizer and feed additive procurement toward chelated alternatives with lower soil mobility.
- Precision livestock farming:Automated feeding systems in dairy and poultry operations now integrate liquid chelate dosing modules that optimize trace mineral delivery based on real-time animal health metrics.
- India PLI scheme for nutritional ingredients:Domestic manufacturing incentives are attracting fermentation and chelation capacity investments to serve South Asian nutraceutical and animal feed premix demand.
Market Restraints
- Glycine and methionine price volatility:Amino acid ligand costs fluctuate with natural gas and agricultural commodity cycles, compressing margin visibility for chelate producers lacking backward integration into ligand synthesis.
- EFSA feed additive registration timelines:Novel chelate formulations face 18-36 month safety and efficacy evaluation windows that delay revenue recognition and tie up regulatory capital.
- Inorganic mineral salt substitution:Sulfate and oxide mineral forms retain cost advantages in price-sensitive bulk feed applications, limiting chelate penetration in commodity livestock segments.
Strategic Opportunities
- India BIS certification pathways:Early movers securing food-grade and feed-grade chelate certifications under Bureau of Indian Standards protocols gain preferential access to domestic nutraceutical contract manufacturing demand.
- Foliar spray precision agriculture:Liquid amino acid chelate formulations compatible with drone-assisted application equipment are opening high-value crop segments including viticulture and protected greenhouse cultivation.
- Biotechnology convergence:Microbial fermentation-derived amino acids combined with electrochemical mineral chelation are enabling carbon footprint reductions that align with EU CSRD disclosure requirements.
Industry Challenges
- Analytical method standardization gaps:Inconsistent bioavailability measurement protocols across EFSA, FDA, and FSSAI jurisdictions complicate multi-regional product registration and label claim substantiation.
- Chelate stability validation:Feed mill and fertilizer manufacturers require documented shelf-life performance data under varying temperature and humidity conditions that exceed current industry certification baselines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amino Acid Chelates Market |
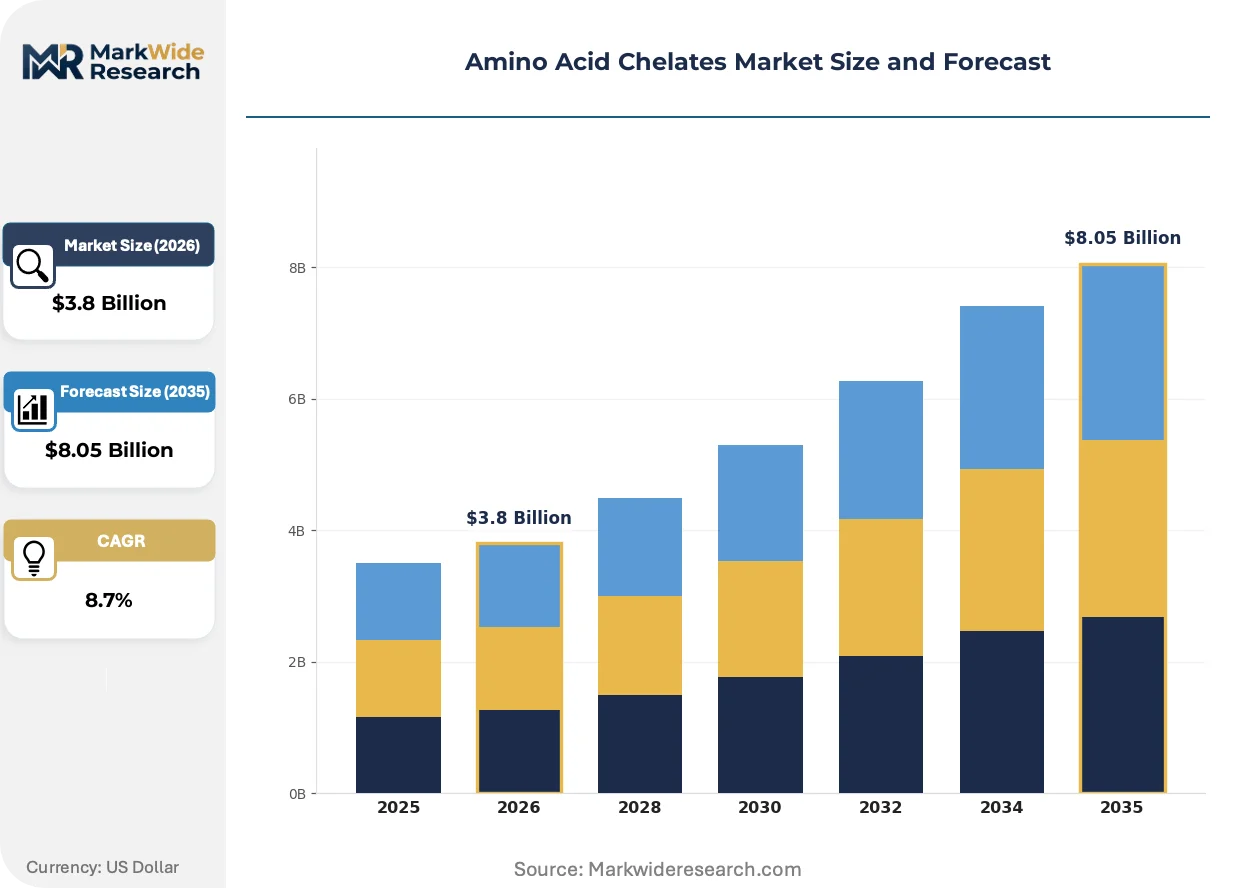
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
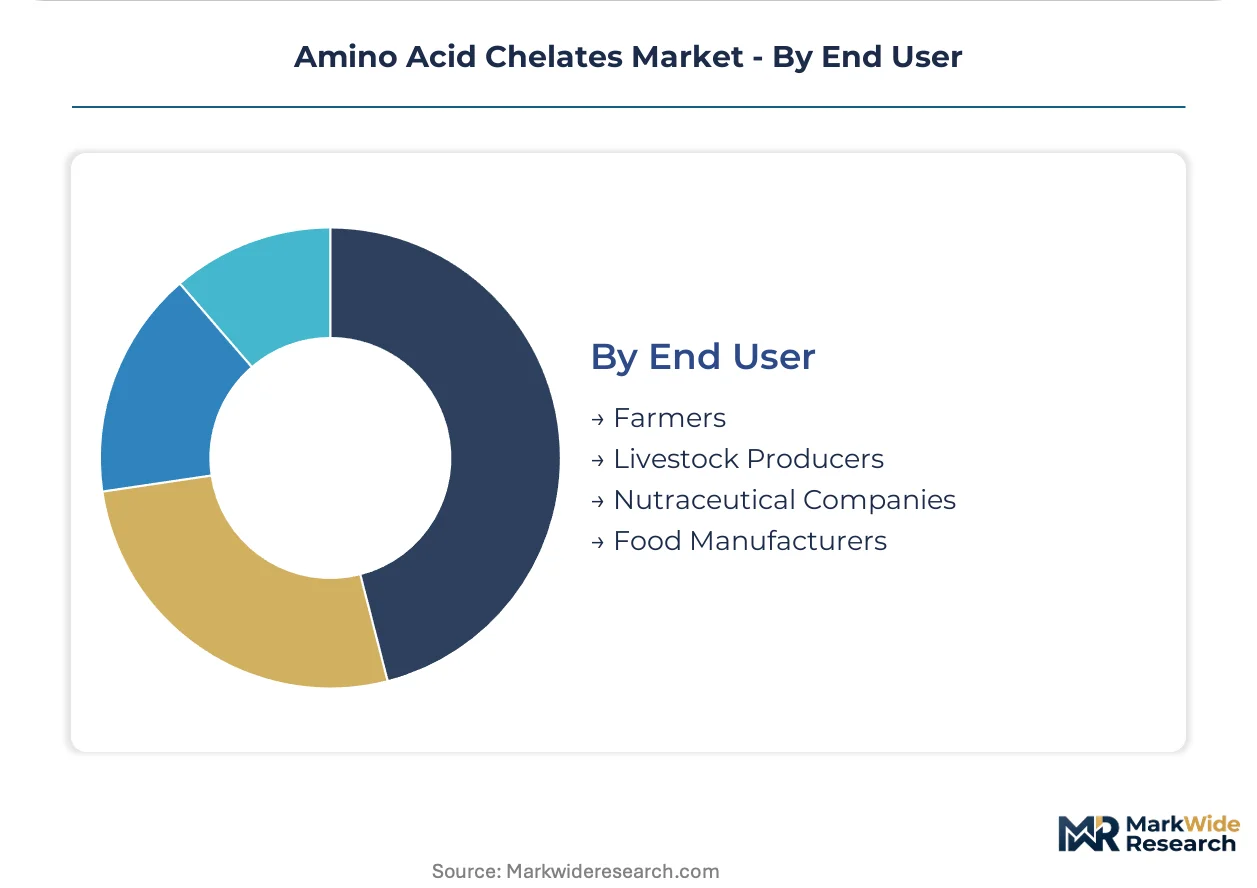
| Segmentation | Product Type: Mineral Chelates, Trace Element Chelates, Macromolecule Chelates, Others Application: Agriculture, Animal Feed, Food Additives, Pharmaceutical Form: Powder, Liquid, Granules, Tablets End User: Farmers, Livestock Producers, Nutraceutical Companies, Food Manufacturers |
| Companies Covered | Titan Biotech Ltd, Peptech Bioscience Ltd, Ava Chemicals, Chaitanya Biologicals Private Limited, Prathisha Industries, Albion Minerals, Balchem Corporation, BASF SE, Nouryon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amino Acid Chelates Market Evolving Landscape
Electrochemical synthesis methods and ligand diversification are compressing production costs while regulatory pressure on mineral bioavailability claims is intensifying validation requirements across feed and food channels.
Hybrid glycinate-methionate chelate complexes are consolidating technical preference among premix formulators seeking balanced solubility and absorption kinetics. Poultry and swine nutrition teams in Brazil and Thailand are adopting these dual-ligand systems at accelerating rates. The technology is consolidating supplier margins around performance-differentiated formulations rather than commodity mineral salts.
REACH authorization requirements for certain inorganic mineral compounds are redirecting European fertilizer and feed additive procurement toward chelated alternatives with favorable environmental fate profiles. German and Dutch agricultural cooperatives now mandate chelate documentation in supplier sustainability scorecards. Specialty crop producers in Spain and Italy are responding fastest, integrating foliar zinc and manganese chelates into integrated pest management protocols.
Direct procurement relationships between livestock integrators and chelate manufacturers are displacing traditional distributor intermediaries in North American broiler and layer operations. Large-scale protein producers in the US Southeast and Midwest now negotiate multi-year supply agreements with verified bioavailability specifications. This channel compression is most visible in vertically integrated poultry systems where trace mineral consistency directly impacts flock uniformity metrics.
Amino Acid Chelates Market Segmentation

Product differentiation across chelation technologies and formulation formats determines bioavailability performance and regulatory compliance pathways. Livestock integrators and specialty crop producers prioritize specific mineral-ligand combinations based on absorption kinetics and environmental discharge profiles.
Product Type:
Mineral chelates command upgrade priority as livestock operations replace sulfate and oxide salts with bioavailable alternatives that satisfy EU Green Deal runoff restrictions.
- Mineral Chelates:Coordination complexes of calcium, magnesium, and iron with glycine or methionine ligands dominate commercial volumes in animal feed premixes. German and Dutch dairy cooperatives mandate these formulations in supplier sustainability scorecards to comply with binding zinc and copper discharge caps.
- Trace Element Chelates:Selenium, zinc, and chromium complexes deliver targeted nutritional intervention at lower inclusion rates. Precision livestock farming systems in the US Midwest integrate liquid selenium chelate dosing modules that adjust delivery based on real-time flock uniformity metrics.
- Macromolecule Chelates:Peptide-bound mineral complexes serve pharmaceutical applications requiring extended release kinetics.
- Others:Emerging hybrid glycinate-methionate complexes consolidate technical preference among Brazilian and Thai premix formulators.
Volume placements concentrate in mineral chelates; the faster expansion belongs to trace element chelates.
Application:
Cost tier differentiation separates commodity bulk feed applications from premium pharmaceutical and nutraceutical channels where bioavailability validation commands price premiums.
- Animal Feed:Chelated trace minerals replace inorganic salts in poultry, swine, and ruminant diets to improve feed conversion efficiency. Vertically integrated US broiler operations negotiate multi-year supply agreements with verified bioavailability specifications, displacing traditional distributor intermediaries.
- Agriculture:Foliar zinc and manganese chelates integrate into integrated pest management protocols for Spanish viticulture and Italian protected greenhouse cultivation. Drone-assisted application equipment drives liquid formulation adoption in precision agriculture segments.
- Food Additives:Iron and zinc chelates fortify processed foods in India, where FSSAI purity standards filter supplier participation.
- Pharmaceutical:Macromolecule chelates serve extended-release mineral supplementation with documented shelf-life performance requirements.
Commercial volumes flow heaviest through animal feed channels; agriculture applications are climbing the fastest as foliar spray adoption accelerates.
Form:
Supply concentration favors powder processing infrastructure, though liquid capabilities attract premium positioning in precision application segments.
- Powder:Dry chelate blends retain manufacturing scale advantages across North American and European production facilities. Feed mill integration requires documented flowability and homogeneity under varying temperature and humidity conditions.
- Liquid:Solution formulations enable drone-compatible foliar application and automated dosing system integration. Precision livestock farming modules in automated dairy operations favor liquid chelates for real-time trace mineral adjustment.
- Granules:Agglomerated forms reduce dust generation during bulk handling operations.
- Tablets:Compressed formats serve direct-to-consumer nutraceutical channels with dosage standardization requirements.
Production gravity centers on powder formats; liquid chelates gain share fastest in precision agriculture and automated livestock systems.
End User:
Customer type determines procurement sophistication, with livestock integrators and nutraceutical companies driving specification intensity versus commodity farmer price sensitivity.
- Livestock Producers:Large-scale protein producers in the US Southeast and Midwest anchor demand for verified bioavailability specifications. Direct manufacturer relationships replace distributor channels as flock uniformity metrics tie mineral consistency to operational outcomes.
- Nutraceutical Companies:Contract manufacturers in India seek BIS-certified food-grade chelates to serve domestic and export markets. PLI scheme incentives attract fermentation and chelation capacity investments to Maharashtra and Gujarat industrial corridors.
- Farmers:Specialty crop producers in Spain and Italy respond fastest to foliar chelate integration, while commodity grain operations retain price-sensitive inorganic salt preferences.
- Food Manufacturers:Processed food fortification programs in India and Southeast Asia drive iron and zinc chelate procurement under national nutrition initiatives.
Procurement volumes concentrate with livestock producers; nutraceutical companies are expanding most quickly as India manufacturing incentives reshape supply geography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's industrial corridors around Mumbai and Pune concentrate India's fermentation and chelation capacity investments, drawing domestic and foreign capital under PLI scheme incentives for nutritional ingredient manufacturing.
United States
Vertically integrated poultry operations across Georgia and Arkansas negotiate multi-year chelate supply agreements with verified bioavailability specifications. The FDA and EPA jointly oversee agricultural and pharmaceutical applications, with runoff regulations tightening in Chesapeake Bay watershed states. Midwest dairy cooperatives in Wisconsin and Minnesota integrate automated liquid chelate dosing systems into precision livestock farming infrastructure.
Germany
Dairy and swine producers in Lower Saxony and Bavaria mandate chelated mineral documentation in supplier sustainability scorecards to satisfy EU Green Deal discharge caps. EFSA feed additive registration timelines extend 18-36 months for novel formulations. The Cologne-Düsseldorf industrial cluster hosts pharmaceutical-grade macromolecule chelate production serving extended-release applications.
India
Contract nutraceutical manufacturers in Maharashtra and Gujarat seek BIS-certified food-grade chelates under FSSAI purity standards. The PLI scheme for nutritional ingredients attracts fermentation capacity to serve South Asian animal feed premix demand. Hyderabad's life sciences corridor anchors electrochemical synthesis research for carbon footprint reduction.
Brazil
Poultry and swine nutrition teams in São Paulo and Paraná states adopt hybrid glycinate-methionate chelate complexes at accelerating rates. ANVISA governs feed additive registrations with bioavailability validation requirements. The São Paulo industrial belt concentrates premix formulation capacity serving Mercosur livestock integration.
Netherlands
Intensive livestock operations in Gelderland and North Brabant face binding zinc and copper runoff limits under EU Green Deal implementation. Dutch agricultural cooperatives mandate chelate environmental fate documentation in procurement protocols. The Rotterdam port cluster facilitates ligand import flows for European chelation manufacturing.
Amino Acid Chelates Market Competitive Landscape
Premium-margin players sit above commodity-margin players across bioavailability validation and regulatory certification dimensions, with the vendor base stratifying between technology-differentiated specialists and scale-driven mineral processors. The competitive field organizes around three archetypes: integrated chemical conglomerates with macromolecule capabilities, mid-scale chelation technology specialists, and regional fermentation-based manufacturers. Dominant competitive moves include backward integration into amino acid ligand synthesis and strategic positioning for India BIS certification pathways.
Among India-based biological manufacturers, Titan Biotech Ltd and Peptech Bioscience Ltd occupy positions within the fermentation-derived specialty tier, while Albion Minerals anchors the premium technology segment with specialized chelation intellectual property. These three exemplify divergent strategic postures: domestic scale manufacturing under PLI incentives versus proprietary absorption-enhancement positioning.
| Leading Market Players |
|---|
| Titan Biotech Ltd |
| Peptech Bioscience Ltd |
| Ava Chemicals |
| Chaitanya Biologicals Private Limited |
| Prathisha Industries |
| Albion Minerals |
| Balchem Corporation |
| BASF SE |
| Nouryon |
| Others |
Value Network & Pricing Analysis
Backward integration into amino acid ligand synthesis anchors both supply security and margin protection for chelate manufacturers facing glycine and methionine cost cycles. Captive production of these organic inputs insulates formulators from natural gas and agricultural commodity volatility while supporting premium positioning in EFSA-validated feed additive tiers.
Pricing Analysis
Value-based pricing tied to documented feed conversion efficiency anchors the premium tier for EFSA-registered glycinate and methionate chelates. Three-tier pricing structure across premium, standard, and economy levels separates validated bioavailability grades from commodity mineral salts. Cost compression in standard tiers is intensifying because sulfate and oxide substitutes retain procurement preference among price-sensitive bulk feed operations. Livestock integrators in vertically integrated poultry systems show least price sensitivity due to flock uniformity metrics, while commodity grain farmers in developing markets resist chelate premiums.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for South Asian nutraceutical and animal feed premix channels. Manufacturing gravity draws from China for glycine ligands, from Germany and the Netherlands for precision chelation equipment, and from the US Midwest for selenium and chromium mineral sources. Single-source vulnerability concentrates in electrochemical synthesis technology licensed from European specialists. Distribution runs through direct procurement relationships displacing traditional distributor intermediaries in North American broiler operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The amino acid chelates market sits in a technology-transition phase as electrochemical synthesis methods displace conventional chemical chelation. Hybrid glycinate-methionate complexes are consolidating technical preference among premix formulators seeking balanced absorption kinetics.
For Market Incumbents: Extend EFSA registration portfolios to capture 18-36 month safety evaluation windows as competitive moats. Backward integration into fermentation-derived amino acid production secures ligand supply against methionine price volatility. Channel control through direct procurement relationships with livestock integrators defends margin position against distributor disintermediation threats. For New Entrants and Emerging Players: E-commerce-enabled B2B platforms offer low-friction entry into Indian nutraceutical contract manufacturing demand. White-space targets concentrate in BIS-certified food-grade chelates for domestic fortification programs and drone-compatible liquid formulations for precision viticulture in Spain and Italy. Technical partnerships with Maharashtra-based fermentation facilities accelerate PLI scheme qualification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated chemical conglomerates seeking macromolecule chelate capabilities. Long-term viability favors technology-differentiated specialists with proprietary absorption validation protocols over commodity mineral processors. The signal to watch is EFSA registration reciprocity agreements that compress multi-regional approval timelines and reward early certification investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ligand Synthesis | Captive glycine and methionine production insulates margins from agricultural commodity cycles. |
| EFSA Feed Additive Registration | Validated bioavailability claims unlock premium pricing in EU Green Deal compliance channels. |
| India BIS Certification Pathway | Food-grade and feed-grade certifications secure preferential access to PLI scheme incentives. |
| Precision Agriculture Formulation Development | Liquid chelates compatible with drone-assisted application open high-value viticulture segments. |
| Direct Procurement Relationship Building | Manufacturer-integrator agreements displace distributor intermediaries in US poultry channels. |
Research Methodology
Multi-period observation of EFSA registration timelines, PLI scheme investment flows, and livestock feed conversion metrics anchored the trend analysis, supplemented by interviews with chelate manufacturing plant managers, procurement leads at premix formulators, regulatory affairs directors, and agricultural cooperative technical officers. Secondary validation drew from EFSA feed additive opinions, BIS certification registries, EU Green Deal implementation documents, and customs trade data for glycine and methionine imports. Bottom-up capacity assessments and top-down demand projections were triangulated against channel shipment patterns.
Input-output matrices mapped mineral-ligand combinations against end-use absorption requirements, application formats, and regional regulatory clusters across the analysis window. Segmentation dimensions modeled included chelation technology type, formulation format, end-use industry, and geographic production hub. CAGRs were derived from trend extrapolation of validated bioavailability adoption rates and precision agriculture equipment penetration. Forecast inputs incorporated EU Green Deal discharge limit implementation schedules and India manufacturing incentive disbursement trajectories.
Inputs from EFSA, BIS, and FSSAI regulatory filings were available through the study window; gaps in proprietary bioavailability measurement protocols introduce uncertainty bands around multi-regional product registration timelines. Forecasts reflect assumptions about certification reciprocity progression and ligand cost cycle stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
US Potassium Methylate Market
Functional Chemicals
L-Cysteine Market
Functional Chemicals
Asparagine Market
Functional Chemicals
Amino Acids Market
Functional Chemicals
Global Tert-Amylbenzene Market
Functional Chemicals
Carbomer Market
Functional Chemicals
Global Glutamic Acid Market
Functional Chemicals
Sodium Methylate Market
Functional Chemicals
Serine Amino Acid Market
Functional Chemicals
Phthalimide Market
Functional Chemicals
Ortho-Phthalaldehyde Market
Functional Chemicals
Lauric Acid Market
Functional Chemicals
Sodium Lauroyl Glutamate Market
Functional Chemicals
Glutaraldehyde Market
Functional Chemicals
Urea Formaldehyde Market
Functional Chemicals
Para-Aminophenol Market