
 Europe Fumaric Acid Market | 2026-2036
Europe Fumaric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fumaric Acid Market Intelligence
Malic acid substitution in beverage acidulation is repositioning fumaric acid as a cost-competitive alternative across European formulations. Polynt S.p.A. leverages its integrated maleic anhydride platform to anchor supply security for downstream fumaric acid production. ESIM Chemicals GmbH specializes in pharmaceutical-grade refinement, occupying a premium tier with GMP-certified output. Bartek Ingredients Inc. extends its North American expertise into European distribution, navigating regulatory complexity through localized warehousing.
Fumaric acid is a dicarboxylic acid with the molecular formula C4H4O4, produced industrially via catalytic isomerization of maleic acid or through fermentation of renewable carbohydrates; it functions primarily as an acidulant, pH modifier, and chemical intermediate across food, resin, and pharmaceutical systems. The food grade segment dominates volume offtake, sustained by clean-label demand from bakery and beverage manufacturers seeking alternatives to synthetic acidulants. Bio-based production routes represent the fastest-growing structural category, though industrial grade powder forms still command the largest margin pool through resins and unsaturated polyester applications. Granular and crystalline forms are gaining traction in pharmaceutical end uses where dissolution precision and handling properties determine formulation acceptance.
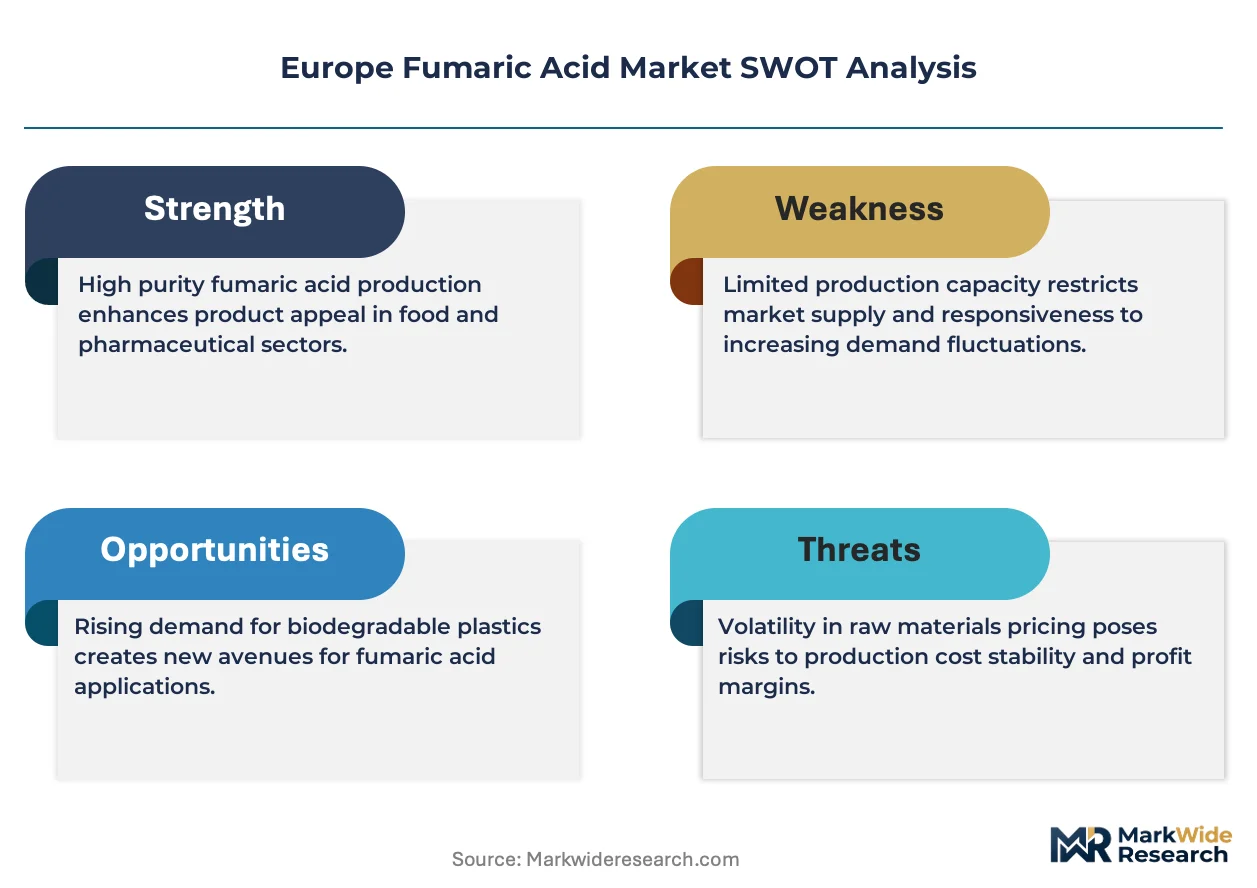
REACH registration requirements and the EU Green Deal's sustainable chemistry frameworks are tightening feedstock traceability and carbon intensity thresholds for fumaric acid entering European commerce. ECHA substance evaluation protocols and the F-Gas Regulation's indirect pressure on petrochemical-derived inputs are steering producers toward fermentation-based and bio-based certification pathways. The EU AI Act's emerging supply chain transparency mandates will soon extend to chemical batch documentation, adding compliance layers for importers. Stakeholders must monitor bio-based certification cost curves and maleic anhydride feedstock volatility to preserve margin structures through the forecast horizon.
Market Dynamics
REACH registration requirements and the EU Green Deal's bio-based chemical mandates are redirecting formulation priorities toward sustainable feedstocks, compressing margins for petrochemical-derived fumaric acid while elevating certified bio-based alternatives.
Growth Catalysts
- Clean-label bakery demand:Manufacturers across Germany and France are replacing synthetic acidulants with fumaric acid in dough conditioning applications.
- REACH compliance premiums:Registered bio-based fumaric acid commands preferential placement in EU procurement frameworks for food and pharmaceutical applications.
- Maleic anhydride feedstock security:Integrated petrochemical complexes in the Netherlands and Belgium ensure stable precursor supply for industrial-grade production.
Market Restraints
- Malic acid substitution:Beverage manufacturers in Spain and Italy are switching to malic acid for acidulation, eroding fumaric acid's cost advantage in soft drinks.
- Feedstock price volatility:Maleic anhydride prices fluctuate with naphtha and benzene markets, destabilizing production economics for synthetic fumaric acid.
- Fermentation yield limitations:Current bio-based production routes using Rhizopus oryzae achieve lower titers than petrochemical processes, constraining scale-up.
Strategic Opportunities
- Polish pharmaceutical manufacturing:Warsaw's expanding generics sector offers untapped demand for USP-grade fumaric acid in tablet formulations.
- EU AI Act supply chain transparency:Batch-level documentation requirements will favor producers with integrated digital traceability systems.
- Unsaturated polyester resins for wind energy:Denmark and Germany's offshore wind buildout is driving demand for corrosion-resistant composites using fumaric acid-derived resins.
Industry Challenges
- Bio-based certification timelines:Obtaining EU Ecolabel and USDA BioPreferred recognition requires 18-24 month validation cycles that delay market entry.
- Pharmaceutical GMP compliance:EMA's updated ICH Q7 guidelines demand costly facility upgrades for active pharmaceutical ingredient-grade production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fumaric Acid Market |
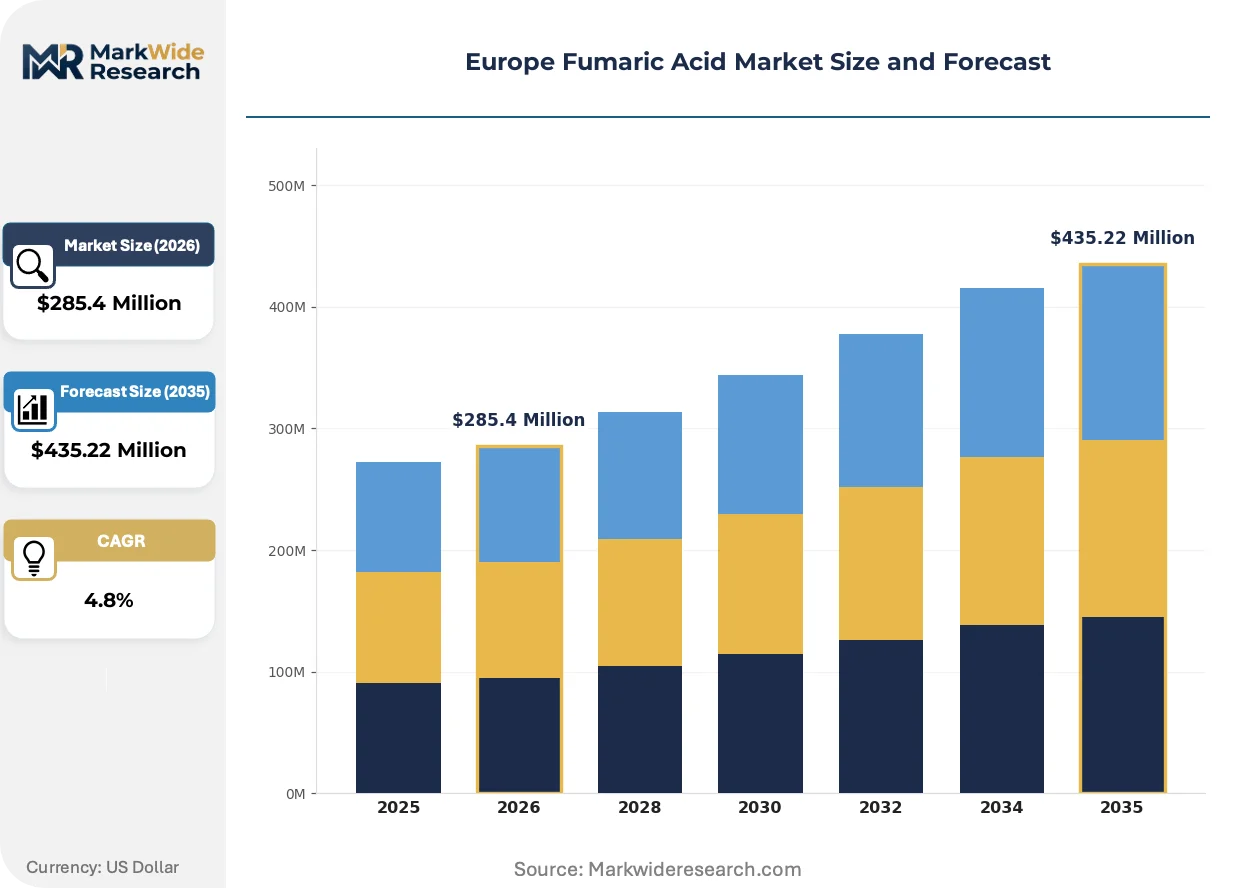
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Bio-Based Application: Beverages, Food Additives, Resins, Cosmetic Products Form: Powder, Liquid, Granular, Crystalline End User: Food Industry, Chemical Manufacturing, Cosmetics Sector, Pharmaceuticals |
| Companies Covered | Merck KGaA, Thirumalai Chemicals Ltd, ESIM Chemicals GmbH, Prinova Group LLC, Anmol Chemicals, Polynt S.p.A., Bartek Ingredients Inc., UPC Group, Fuso Chemical Co. Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fumaric Acid Market Strategic Shifts & Innovations
Fermentation-based production routes and digital supply chain verification are restructuring competitive advantage in European fumaric acid supply. These shifts favor producers with integrated bio-refinery capabilities and transparent carbon accounting systems.
Continuous fermentation technology using metabolically engineered Aspergillus strains is decentralizing production economics away from centralized petrochemical hubs. Specialty chemical producers in Scandinavia are piloting modular 5,000-tonne facilities that slash capital intensity versus traditional maleic anhydride routes. This distributed manufacturing model is compressing freight costs and enabling regional supply security for food-grade applications.
ECHA's substance evaluation protocols under REACH are tightening purity specifications for fumaric acid used in food contact materials. The regulatory pressure is forcing importers to establish EU-based testing laboratories or partner with certified European distributors. Pharmaceutical-grade suppliers are responding by segregating production lines to prevent cross-contamination with industrial-grade output.
Direct contracting between fumaric acid producers and European bakery chains is displacing traditional distributor relationships. Large manufacturers in Germany and the United Kingdom are negotiating multi-year supply agreements with fixed pricing and sustainability certifications. This channel consolidation is most visible in the clean-label segment, where traceability requirements exceed what commodity traders can deliver.
Europe Fumaric Acid Market Segmentation
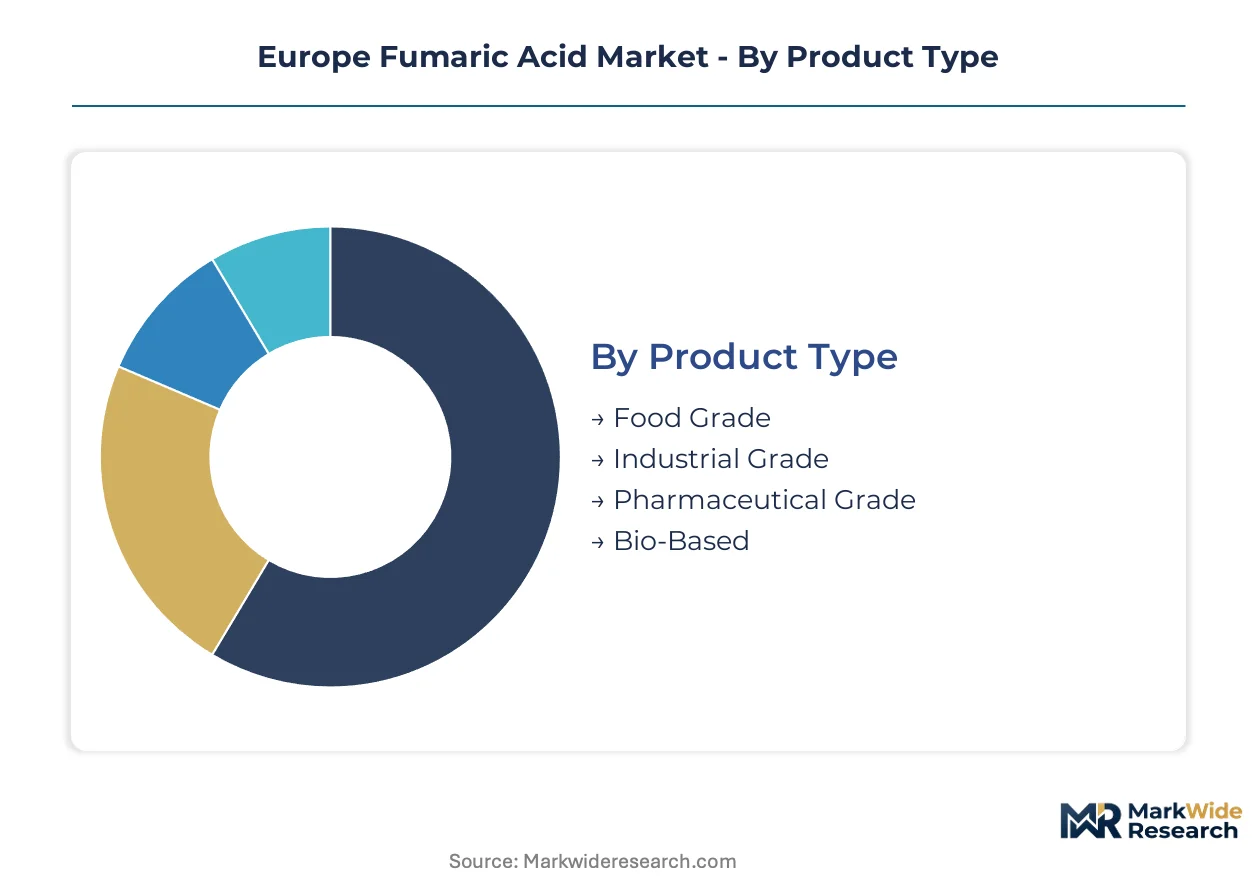
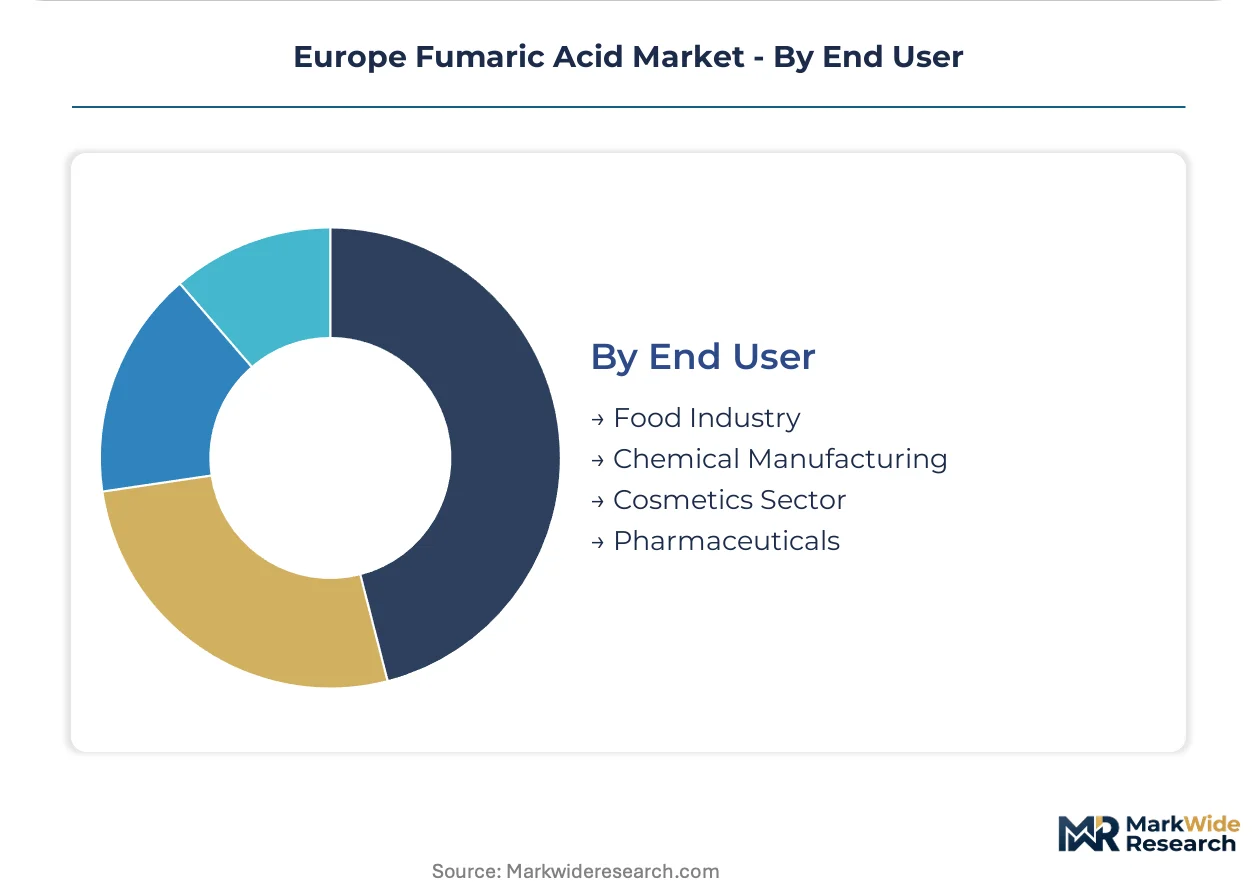
Formulation requirements across European food, pharmaceutical, and industrial sectors create divergent purity and certification demands. Each segment commands distinct margin structures and regulatory compliance burdens.
Product Type:
Upgrade cycles from petrochemical to certified bio-based production are reshaping procurement specifications across buyer categories.
- Food Grade:Fumaric acid meeting EFSA purity specifications serves acidulation and dough conditioning in clean-label bakery applications. German and French manufacturers prioritize REACH-registered supply chains for bread improvers and confectionery formulations.
- Industrial Grade:Technical-grade material with controlled moisture content feeds unsaturated polyester resin production for composite manufacturing. Netherlands and Belgium chemical clusters anchor volume offtake through integrated maleic anhydride supply.
- Pharmaceutical Grade:USP/EP-compliant material for tablet binders and enteric coatings.
- Bio-Based:Fermentation-derived acid carrying EU Ecolabel or USDA BioPreferred certification.
Volume placements concentrate in Industrial Grade; the faster expansion belongs to Bio-Based.
Application:
Cost tier differentiation separates commodity acidulation from premium functional additives.
- Food Additives:Dough strengtheners and pH modifiers replace synthetic acidulants in clean-label European bakery production. EFSA-approved applications in German rye bread and French pastry segments drive specification tightening.
- Resins:Unsaturated polyester formulations for corrosion-resistant composites leverage fumaric acid's reactivity with glycols. Denmark and Germany offshore wind tower manufacturing anchors industrial demand.
- Beverages:Acidulation for fruit-flavored soft drinks and powdered drink mixes.
- Cosmetic Products:pH adjustment in skincare and haircare formulations.
Resins capture the largest volume share; Food Additives are climbing the fastest.
Form:
Handling properties and dissolution kinetics determine form selection across end-use environments.
- Powder:Free-flowing particulate with defined particle size distribution dominates bulk industrial handling. Resin manufacturers in Belgium and the Netherlands prefer pneumatic conveyance compatibility.
- Crystalline:High-purity solid with controlled morphology enables precise dosing in pharmaceutical tablet compression. Warsaw generics manufacturers specify crystal habit for dissolution profile consistency.
- Liquid:Aqueous solutions for automated dosing systems.
- Granular:Low-dust agglomerated form for food processing hygiene.
Powder maintains volume leadership; Crystalline posts the steepest expansion trajectory.
End User:
Customer type segmentation maps certification requirements to facility audit standards.
- Food Industry:Bakery chains and ingredient blenders across Germany, France, and the United Kingdom negotiate multi-year contracts with fixed pricing and traceability documentation. Clean-label positioning demands REACH-registered, non-GMO supply.
- Pharmaceuticals:EMA ICH Q7-compliant API manufacturers and finished dosage form producers require segregated production lines. Polish and Hungarian generics sectors drive USP-grade volume growth.
- Chemical Manufacturing:Resin compounders and specialty chemical producers.
- Cosmetics Sector:Formulators serving EU 1223/2009 cosmetic regulation compliance.
Food Industry commands current volume; Pharmaceuticals is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antwerp-Rotterdam's chemical corridor concentrates maleic anhydride feedstock supply for fumaric acid production. REACH registration clusters and EU Green Deal incentives anchor investment decisions across Northwestern Europe. National pharmaceutical and food manufacturing bases drive differentiated demand patterns.
Germany
Bavaria's bakery ingredient manufacturers source REACH-registered fumaric acid for clean-label dough conditioners. The EU Green Deal's bio-based mandates accelerate fermentation-derived acid adoption in pharmaceutical applications. North Rhine-Westphalia's chemical cluster hosts integrated maleic anhydride-to-fumaric acid production for industrial resin feedstock.
France
Parisian confectionery producers specify EFSA-compliant acidulants for premium pastry applications. ANSM pharmaceutical guidelines tighten purity requirements for tablet excipient-grade material. The Lyon-Grenoble chemical corridor anchors specialty resin manufacturing for automotive composites.
Netherlands
Rotterdam's petrochemical hub secures naphtha-derived maleic anhydride supply for industrial-grade fumaric acid output. ECHA substance evaluation protocols force importers to establish EU-based testing laboratories. The Randstad region concentrates food-grade distribution warehousing for pan-European bakery chains.
Poland
Warsaw's expanding generics sector drives USP-grade fumaric acid demand for tablet binder applications. The country's central location enables cost-competitive distribution into Eastern European pharmaceutical markets. Silesian chemical processors increasingly blend imported acid for regional resin compounders.
Belgium
Antwerp's integrated chemical complex maintains captive maleic anhydride supply for fumaric acid derivative production. Flemish food technology institutes pilot bio-based fermentation routes using regional sugar beet feedstock. The Port of Antwerp's customs infrastructure facilitates third-country acid imports for re-export across the Benelux.
Europe Fumaric Acid Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments. The vendor base organizes around three tiers: integrated petrochemical producers with captive feedstock, pharmaceutical-grade refiners with GMP certification, and regional distributors with localized warehousing. Strategic differentiation centers on REACH registration status, bio-based certification, and supply chain traceability systems. Capacity expansion and backward integration into maleic anhydride represent the dominant competitive moves.
Among German chemical conglomerates, Merck KGaA exemplifies the pharmaceutical-grade specialist archetype with its Darmstadt-based life sciences platform. Polynt S.p.A. represents the integrated petrochemical model through its Italian maleic anhydride-to-derivatives chain. ESIM Chemicals GmbH occupies a position as a mid-scale European refiner serving regional pharmaceutical and food additive demand.
| Leading Market Players |
|---|
| Merck KGaA |
| Thirumalai Chemicals Ltd |
| ESIM Chemicals GmbH |
| Prinova Group LLC |
| Anmol Chemicals |
| Polynt S.p.A. |
| Bartek Ingredients Inc. |
| UPC Group |
| Fuso Chemical Co. Ltd |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's bio-based chemical mandates gate qualified supply and premium-tier pricing access, as REACH-registered fermentation-derived fumaric acid commands placement premiums while petrochemical routes face margin compression. Buyers in German bakery and Polish pharmaceutical sectors now require carbon intensity documentation as a condition of contract eligibility.
Pricing Analysis
Short lead-time premiums distinguish pharmaceutical-grade crystalline shipments to Warsaw generics manufacturers from spot powder transactions in Belgian resin compounders. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified USP material from technical-grade industrial powder and unregistered commodity imports. Price differentiation hinges on certification tier and volume scale, with REACH-registered bio-based acid commanding sustained premiums. Cost compression in petrochemical-derived grades is intensifying because maleic anhydride feedstock volatility destabilizes synthetic production economics. Food industry buyers exhibit highest price sensitivity, while pharmaceutical formulators prioritize supply security over unit cost.
Supply Chain Analysis
REACH registration and bio-based certification requirements restrict qualified supply to producers with validated EU-based testing infrastructure and segregated production lines. Manufacturing concentrates in Germany, the Netherlands, and Belgium, where integrated petrochemical complexes anchor maleic anhydride feedstock security for industrial-grade output. Supply draws from naphtha-derived precursors, sugar beet fermentation feedstock, and imported maleic acid intermediates. Single-source vulnerability runs through Rotterdam's maleic anhydride hub, where concentrated production creates chokepoint exposure. Distribution runs through Antwerp-Rotterdam chemical corridor warehousing for pan-European fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race, with maleic anhydride feedstock security emerging as the decisive upstream lever separating margin-stable incumbents from cost-exposed competitors.
For Market Incumbents: To counter malic acid substitution in beverage acidulation, Polynt S.p.A. and integrated petrochemical producers should deepen captive maleic anhydride supply through capacity addition in North Rhine-Westphalia. Certification investment in EU Ecolabel and USDA BioPreferred pathways defends premium positioning against fermentation-based challengers.For New Entrants and Emerging Players: Begin with Polish pharmaceutical manufacturing, where Warsaw's expanding generics sector offers underpenetrated USP-grade demand with less entrenched supplier relationships. Target food-grade bio-based production for German bakery chains seeking direct contracting alternatives to commodity traders, leveraging modular fermentation facilities for regional supply security.
For Investors and Strategic Acquirers: ECHA substance evaluation protocol tightening is the leading indicator that qualified supply scarcity will intensify, favoring acquisition of mid-scale refiners with existing REACH registration and EU-based testing infrastructure. Target producers with integrated digital traceability systems aligned to EU AI Act batch documentation mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Maleic Anhydride | Captive feedstock supply from Rotterdam petrochemical complexes insulates margin structures from naphtha volatility. |
| Bio-Based Certification Program | EU Ecolabel and USDA BioPreferred recognition unlocks preferential placement in German clean-label procurement frameworks. |
| Long-Term Supply Agreement | Multi-year fixed-price contracts with Bavarian bakery chains displace commodity trader intermediation. |
| Capacity Expansion | Modular 5,000-tonne fermentation facilities in Scandinavia enable distributed manufacturing with compressed freight economics. |
| Joint Venture | Partnerships with Flemish food technology institutes accelerate sugar beet-derived production route commercialization. |
Research Approach
Independent corroboration across primary interviews with plant managers at maleic anhydride complexes, procurement leads at German bakery manufacturers, distribution channel partners in the Randstad region, and technical R&D directors at specialty resin compounders underwrites the qualitative findings. Secondary validation draws from customs and trade data, Cefic sector reports, SEC 10-K filings of listed chemical producers, and ECHA substance evaluation databases. Bottom-up volume estimates from end-use consumption patterns triangulate against top-down production capacity assessments across the analysis window.
Rate-of-change decomposition separates volume growth from price trajectory movements across the modeling period. The analytical framework segments by grade tier, end-use industry, packaging format, and regional production hub. CAGRs derive from fitted growth curves against historical consumption patterns, incorporating maleic anhydride feedstock price indices and bio-based certification penetration rates as key forecast inputs.
Underlying measurement precision varies by segment; pharmaceutical-grade and bio-based categories carry tighter precision than commodity industrial powder due to more concentrated producer bases and transparent certification audit trails. Forecasts reflect documented assumptions regarding REACH enforcement intensity and EU Green Deal implementation pace. A model refresh is warranted upon material change in maleic anhydride feedstock economics or ECHA substance evaluation protocol scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Global L-Arginine Market
Functional Chemicals
Functional Polymer Market
Functional Chemicals
Acrylamide Monomer Market
Functional Chemicals
Carbomer Market
Functional Chemicals
Furan Dicarboxylic Methyl Ester (FDME) Market
Functional Chemicals
Paraformaldehyde Market
Functional Chemicals
Transfluthrin Market
Functional Chemicals
L-Alanyl-L-Glutamine Market
Functional Chemicals
Amino Acid Chelates Market
Functional Chemicals
Sodium Methylate Market
Functional Chemicals
Adipamide Market
Functional Chemicals
Chlorobutanol Market
Functional Chemicals
Threonine Acids Market
Functional Chemicals
Glutamine Market
Functional Chemicals
Lauric Arginate Market
Functional Chemicals
Global Tert-Amylbenzene Market