
 Lauric Arginate Market | 2026-2036
Lauric Arginate Market Size, Share, and Industry Trends Forecast 2026-2036
Lauric Arginate Market Analytics
A capital-intensity divergence between integrated manufacturers and formulation specialists is reorganizing competitive dynamics in lauric arginate supply. Vedeqsa (LAMIRSA Group) leverages captive esterification capabilities to control raw material conversion costs, while BASF SE anchors its position through broad antimicrobial portfolios that cross-sell into food and personal care channels. Kerry differentiates by embedding lauric arginate into turnkey preservation systems for meat and poultry processors.
Lauric arginate is a cationic surfactant synthesized from lauric acid and L-arginine, typically delivered as a powder or liquid concentrate with minimum active content specifications for antimicrobial efficacy. Its primary commercial purpose centers on inhibiting Gram-positive and Gram-negative bacteria in processed foods, extending shelf life without altering sensory profiles. Powder formulations dominate current volume owing to stability in dry-blend operations and lower freight costs, while liquid emulsions represent the fastest-growing product type as beverage manufacturers seek pourable, metered dosing solutions. Food preservation commands the largest application share, though personal care formulators are expanding uptake as paraben alternatives face regulatory pressure across multiple jurisdictions.
FDA food additive regulations and EFSA safety evaluations shape product approval timelines and label claims for lauric arginate in the United States and European markets, while China's SAMR implements distinct GB standards for antimicrobial food contact substances that require separate toxicological dossiers. ISO 22000 and FSSC 22000 certification requirements further filter supplier eligibility for multinational food manufacturers. Stakeholders must monitor evolving maximum permitted levels in ready-to-eat categories and preemptively align manufacturing investments with pending regulatory harmonization initiatives.
Market Dynamics
Clean-label mandates from FDA and EFSA are compressing synthetic antimicrobial shelf space, forcing reformulation cycles that favor lauric arginate's regulatory pre-approval status and sensory neutrality in processed protein applications.
Growth Catalysts
- Paraben phase-outs in personal care:ECHA restrictions on endocrine-disrupting preservatives are redirecting cosmetic formulators toward cationic surfactant alternatives with established safety dossiers.
- US poultry processor consolidation:Large meatpacking operations are standardizing on lauric arginate as a listeria control agent in ready-to-eat deli meats to satisfy retail audit requirements.
- GB standard alignment in China:SAMR's evolving food contact substance rules are creating compliance incentives for domestic manufacturers to adopt internationally validated antimicrobial chemistries.
Market Restraints
- L-arginine feedstock volatility:Fermentation-derived amino acid supply disruptions in Southeast Asia create input cost instability for esterification operations.
- Concentrated esterification capacity:European specialist manufacturers control critical conversion technology, exposing buyers to single-source risk during capacity constraints.
- Nisin price competition:Established bacteriocin alternatives with deeper formulation history constrain premium pricing power in dairy preservation applications.
Strategic Opportunities
- Beverage metering systems:Liquid emulsion formats are capturing draft beverage lines where pourable dosing equipment enables real-time antimicrobial adjustment.
- Plant-based protein gaps:Alternative meat formulators lack validated preservation protocols, creating first-mover advantage for suppliers offering application-specific technical support.
- ISO 22000 certification arbitrage:Mid-tier suppliers in India and Brazil can displace unqualified competitors by securing multinational food safety certifications ahead of regional peers.
Industry Challenges
- Toxicological dossier compilation:Expanding into new food categories requires jurisdiction-specific safety studies that strain smaller suppliers' regulatory affairs capabilities.
- Liquid emulsion stability:Maintaining active content specifications during temperature-variable shipping demands capital investment in cold-chain infrastructure that many distributors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lauric Arginate Market |
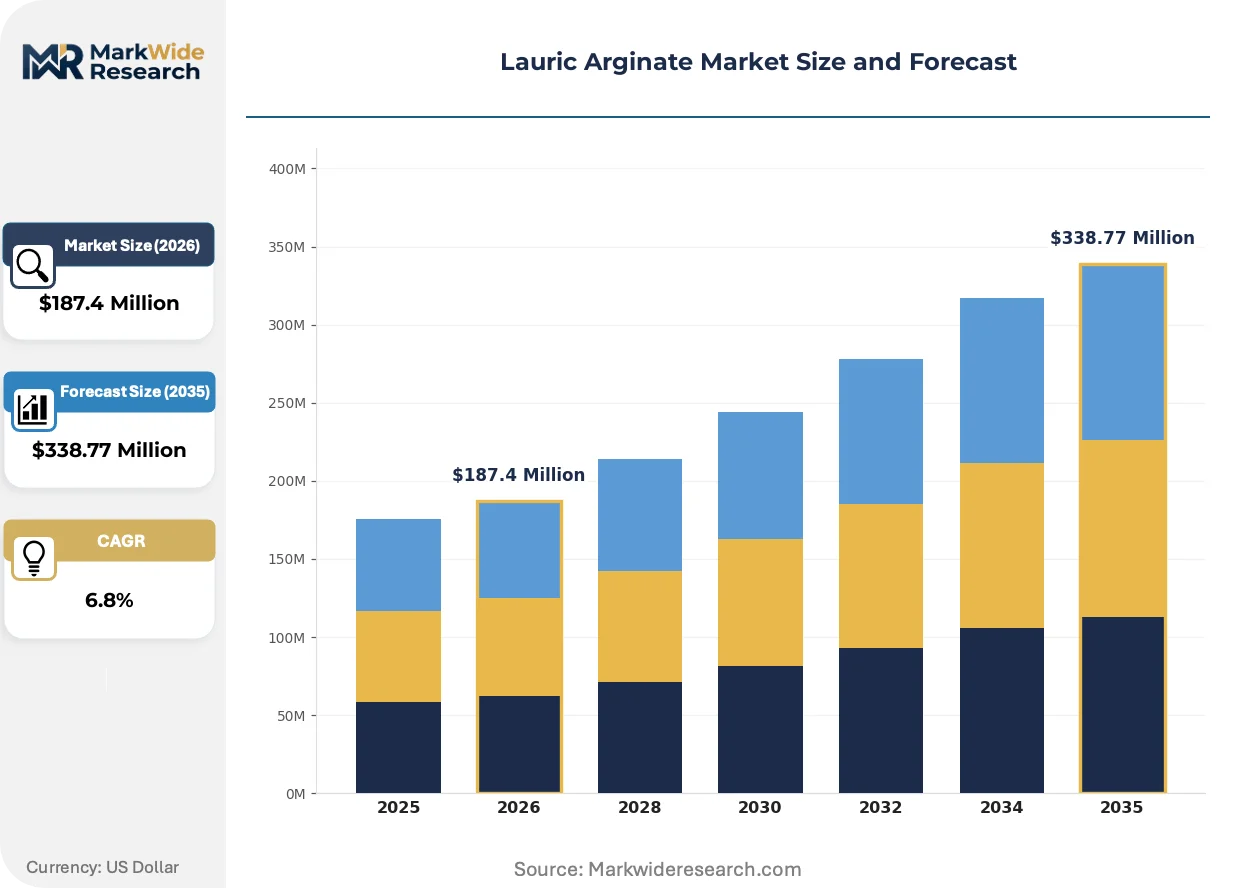
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Liquid, Emulsion Application: Food Preservation, Personal Care, Pharmaceuticals, Animal Feed End User: Food Industry, Cosmetic Manufacturers, Healthcare Providers, Agriculture Sector Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Vedeqsa (LAMIRSA Group), DuPont, Jungbunzlauer Suisse AG, Shandong Aoyou Biological Technology Co., Ltd., Kerry, BASF SE, TCI Chemicals Pvt. Ltd., A&B Ingredients, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lauric Arginate Market Evolving Landscape
Microencapsulation technologies are fragmenting the traditional powder-versus-liquid dichotomy, enabling targeted release profiles that match antimicrobial activity to specific spoilage organism risk windows in complex food matrices.
Encapsulated lauric arginate systems are decomposing the conventional trade-off between thermal processing tolerance and immediate antimicrobial availability. Retort-stable microspheres now permit incorporation into shelf-stable meal components without premature activity loss during sterilization cycles. Ready-meal manufacturers in Germany and Japan are piloting these formats to replace benzoate-sorbate blends in retort pouches.
EFSA's 2023 re-evaluation of food additive safety margins is compressing maximum permitted levels for legacy antimicrobials across ready-to-eat categories. The regulatory consequence is a reformulation scramble among European processed meat suppliers seeking alternatives with favorable toxicological profiles. Italian and Spanish cured meat producers are accelerating lauric arginate trials to preempt stricter sodium benzoate restrictions anticipated in 2025-2026.
Ingredient specification protocols are tightening among multinational food manufacturers consolidating supplier bases under unified procurement frameworks. Category managers now mandate FSSC 22000 certification plus validated kill-step data as baseline qualification criteria, displacing spot-market purchasing relationships. This behavioral shift is most visible in US and Canadian poultry processing, where three-processor concentration has standardized technical requirements across former regional supply chains.
Lauric Arginate Market Segmentation
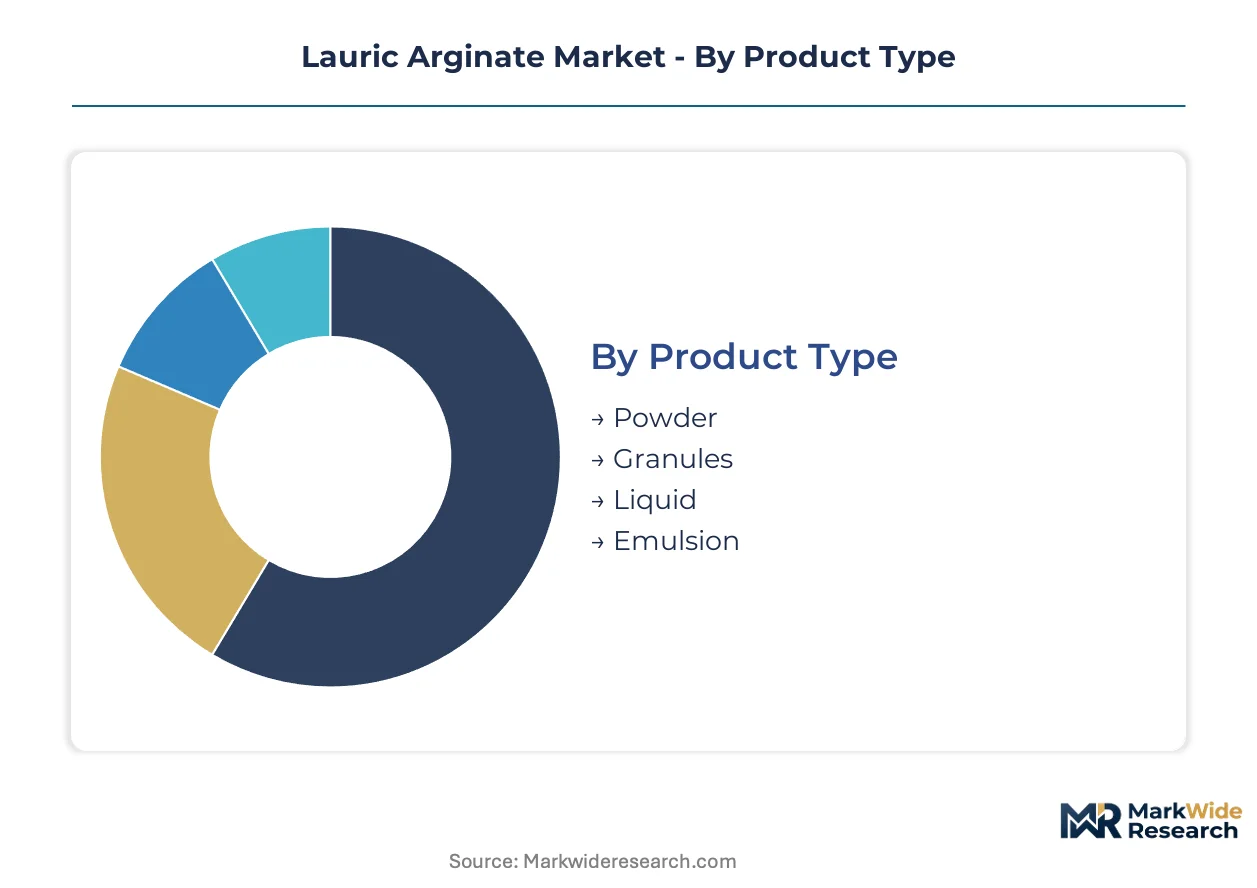
Segmentation in lauric arginate reveals where substitution pressure from nisin, benzoates, and parabens concentrates most intensely. Suppliers calibrate formulation support and certification investments differently across each divide.
Product Type:
Powder formats face the strongest substitute threat from liquid emulsions as beverage processors retrofit metering equipment, while granular intermediates compete with direct-compression alternatives in dry-blend operations.
- Powder:Dry crystalline form with standardized active content specifications for meat and poultry dry rub applications. US poultry processors favor powder for compatibility with existing blending lines and lower freight costs versus liquid alternatives, though thermal stability during retort processing remains a formulation constraint.
- Liquid:Pourable concentrate enabling real-time antimicrobial dosing in draft beverage systems. German and Japanese ready-meal manufacturers are piloting liquid formats to replace benzoate-sorbate blends in retort pouches where microencapsulation compatibility matters.
- Granules:Intermediate particle size for direct-compression tablet operations in pharmaceutical excipient applications.
- Emulsion:Stabilized colloidal dispersion requiring cold-chain integrity during distribution to maintain active specifications.
Powder retains volume leadership; liquid holds the steepest expansion curve.
Application:
Cost tier stratification separates premium-positioned personal care formulators from commodity-pressured food preservation buyers, with pharmaceutical applications occupying a narrow high-margin niche.
- Food Preservation:Primary commercial use inhibiting Gram-positive and Gram-negative bacteria in processed proteins. Italian and Spanish cured meat producers are accelerating lauric arginate trials to preempt EFSA's anticipated sodium benzoate restrictions, while US deli meat processors standardize on the ingredient for listeria control under retail audit protocols.
- Personal Care:Paraben replacement in cosmetic formulations facing ECHA endocrine-disruptor restrictions. ECHA's regulatory pressure is redirecting cosmetic formulators toward cationic surfactant alternatives with established safety dossiers, creating formulation service opportunities for suppliers with toxicological data packages.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient applications requiring validated kill-step documentation.
- Animal Feed:Antimicrobial supplementation for livestock gut health management under veterinary oversight.
Food preservation dominates absolute volume; personal care is expanding most quickly.
End User:
Customer type determines procurement sophistication, with multinational food manufacturers imposing unified FSSC 22000 requirements that filter supplier eligibility differently than spot-market agricultural buyers.
- Food Industry:Processed meat, poultry, and ready-meal manufacturers requiring validated antimicrobial efficacy data. Three-processor concentration in US and Canadian poultry processing has standardized technical requirements across former regional supply chains, displacing uncertified spot-market relationships.
- Cosmetic Manufacturers:Formulators seeking paraben alternatives with sensory neutrality in emulsion systems.
- Healthcare Providers:Compounding pharmacies and topical preparation facilities with specialized antimicrobial needs.
- Agriculture Sector:Feed mills and livestock operations with price-sensitive bulk purchasing patterns.
Food industry commands procurement scale; cosmetic manufacturers are gaining share fastest.
Distribution Channel:
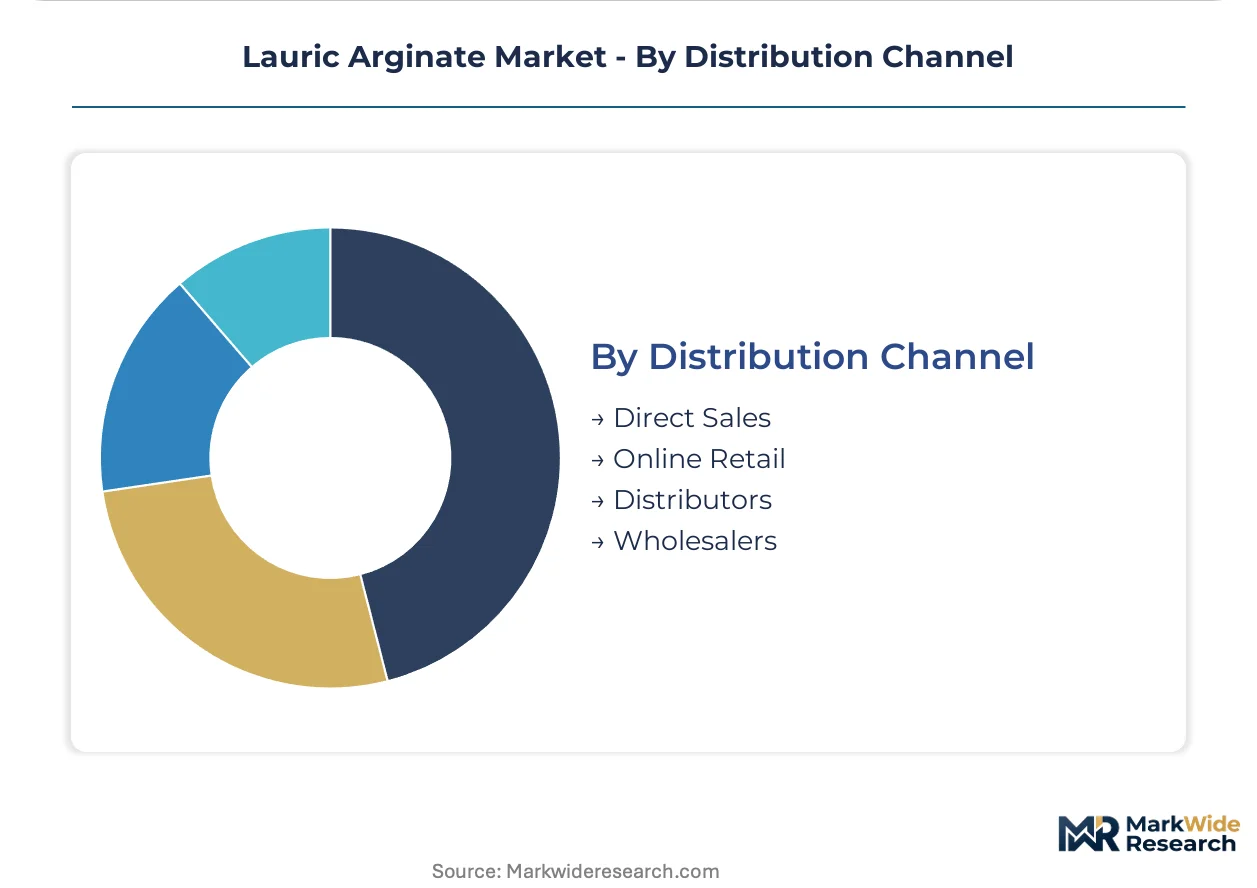
Supply concentration in European esterification specialists shapes channel power, with direct relationships favored for technical formulations and distributors carrying standardized powder grades.
- Direct Sales:Technical account management for turnkey preservation system integration. Kerry embeds lauric arginate into direct-supplied preservation systems for meat and poultry processors, capturing value through formulation services rather than commodity ingredient margins.
- Distributors:Regional inventory positioning for standardized powder grades with lower technical support requirements.
- Online Retail:Small-volume personal care ingredient sourcing with limited regulatory documentation.
- Wholesalers:Bulk aggregation for agricultural and feed applications with minimal specification differentiation.
Direct sales anchor premium formulations; distributors handle commodity volume flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate low price elasticity for certified preservation systems, while agricultural feed buyers in Brazil and spot-market processors in India drive hard bargains on commodity powder grades.
United States
US poultry processors concentrate procurement through three dominant meatpackers that mandate FSSC 22000 certification plus validated listeria kill-step documentation. FDA food additive regulations grant lauric arginate pre-approved status for ready-to-eat deli meats, accelerating substitution of benzoate-sorbate blends. Chicago and Atlanta processing corridors standardize technical requirements across former regional supply chains.
Germany
German ready-meal manufacturers pilot microencapsulated lauric arginate formats to replace legacy antimicrobials in retort pouches. EFSA's 2023 re-evaluation of food additive safety margins compresses maximum permitted levels for sodium benzoate, creating reformulation urgency. Bavarian and Baden-Württemberg food technology clusters drive encapsulated format development.
China
Domestic manufacturers adopt internationally validated antimicrobial chemistries as SAMR evolves GB standards for food contact substances. Fermentation-derived L-arginine supply disruptions in Southeast Asia create input cost volatility for esterification operations. Yangtze River Delta chemical parks concentrate captive esterification capacity.
Japan
Japanese beverage processors retrofit metering equipment for liquid emulsion formats enabling real-time antimicrobial dosing in draft systems. METI guidance on clean-label food additives aligns with consumer preference shifts away from synthetic preservatives. Osaka-Kobe industrial corridor hosts pilot programs for retort-stable microsphere incorporation.
Brazil
Brazilian feed mills and agricultural buyers pursue price-sensitive bulk purchasing patterns with minimal specification differentiation. ANVISA regulatory pathways for novel food antimicrobials lag US and EU approval timelines, constraining premium product penetration. São Paulo state agribusiness clusters dominate regional distribution flows.
Lauric Arginate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive esterification capabilities separating price-setters from price-takers. The upper tier controls critical conversion technology and raw material sourcing, while formulation specialists compete on application-specific technical service. Two archetypes dominate: integrated chemical manufacturers with backward control over amino acid supply, and turnkey preservation system integrators embedding lauric arginate into broader antimicrobial portfolios. Competitive moves center on certification arbitrage—securing FSSC 22000 and ISO 22000 credentials ahead of regional peers—and microencapsulation technology licensing to capture retort-processing applications.
Within the integrated manufacturing tier, Vedeqsa (LAMIRSA Group) and BASF SE exemplify divergent strategic positions. Vedeqsa leverages captive esterification capabilities to control raw material conversion costs, while BASF SE anchors its market presence through broad antimicrobial portfolios that cross-sell into adjacent personal care channels. Kerry occupies a distinct position among formulation specialists, embedding lauric arginate into turnkey preservation systems for protein processors rather than competing on commodity ingredient margins.
| Leading Market Players |
|---|
| Vedeqsa (LAMIRSA Group) |
| DuPont |
| Jungbunzlauer Suisse AG |
| Shandong Aoyou Biological Technology Co., Ltd. |
| Kerry |
| BASF SE |
| TCI Chemicals Pvt. Ltd. |
| A&B Ingredients |
| Evonik Industries AG |
| Others |
Value Network & Pricing Analysis
L-arginine substitution for petrochemical-derived antimicrobials simultaneously redistributes esterification capacity toward Southeast Asian fermentation hubs and compresses margin structures for European specialist manufacturers dependent on legacy synthetic input chains.
Pricing Analysis
Formulation service contracts drive lifetime value capture beyond commodity ingredient margins. Three-tier pricing structure across FSSC 22000-certified premium, ISO 22000-standard, and uncertified economy levels separates multinational food manufacturers from regional processors. Cost compression in economy powder grades is intensifying because Brazilian feed mills and Indian spot-market buyers negotiate bulk aggregates with minimal specification differentiation. Food industry procurement teams demonstrate lowest price elasticity, while agricultural buyers drive hardest bargain.
Supply Chain Analysis
Spain and Germany anchor captive esterification capacity for lauric arginate conversion, while China concentrates fermentation-derived L-arginine feedstock production. The supply chain draws from lauric acid palm kernel oil sources, L-arginine fermentation biomass, and specialized cationic surfactant processing equipment. Single-source vulnerability concentrates in European specialist manufacturers controlling critical conversion technology. Distribution runs through direct technical account relationships for turnkey preservation systems and regional distributors for standardized powder grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against nisin bacteriocin alternatives and benzoate-sorbate legacy antimicrobials that threaten to compress premium pricing power across dairy and ready-to-eat meat applications.
For Market Incumbents: Secure FSSC 22000 certification arbitrage ahead of regional peers in India and Brazil to displace unqualified competitors from multinational food manufacturer procurement frameworks. Anchor backward integration into L-arginine fermentation supply to buffer Southeast Asian feedstock volatility that strains esterification cost structures. For New Entrants and Emerging Players: Anchor in plant-based protein preservation protocols where alternative meat formulators lack validated antimicrobial standards and first-mover technical support commands premium positioning. Target beverage metering system retrofits in German and Japanese draft lines where liquid emulsion compatibility enables real-time dosing differentiation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed formulation specialists holding microencapsulation technology licenses for retort-stable applications. Five-to-ten year viability hinges on regulatory harmonization momentum across FDA, EFSA, and SAMR jurisdictions. Watch EFSA sodium benzoate restriction timelines as inflection signal for European reformulation scramble acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Retort-stable formats capture German and Japanese ready-meal manufacturers replacing benzoate-sorbate blends. |
| Backward Integration into L-Arginine Supply | Fermentation capacity buffers Southeast Asian feedstock disruptions that destabilize esterification economics. |
| FSSC 22000 Certification Investment | Multinational food manufacturer procurement frameworks filter supplier eligibility ahead of regional competitors. |
| Turnkey Preservation System Integration | Technical service bundling captures value beyond commodity margins in US poultry processor consolidation. |
| Liquid Emulsion Cold-Chain Infrastructure | Temperature-variable shipping capabilities maintain active specifications for beverage metering equipment retrofits. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across lauric arginate manufacturing and downstream application. Primary interviews engaged plant managers at esterification facilities, procurement leads at meat and poultry processors, regulatory affairs directors navigating FDA and EFSA additive approvals, and technical R&D heads developing microencapsulation formats. Secondary validation drew from FDA food additive petitions, EFSA safety evaluations, SAMR GB standard filings, and customs trade data on L-arginine feedstock flows. Bottom-up volume modeling triangulated against top-down antimicrobial preservative market sizing.
Across the analysis window, projections incorporated product type segmentation by powder, liquid, granule, and emulsion formats; application segmentation across food preservation, personal care, pharmaceuticals, and animal feed; and end-user segmentation distinguishing multinational food manufacturers from regional processors. CAGRs were derived from elasticity-adjusted substitution rates of synthetic antimicrobials and clean-label regulatory compression timelines. Industry-specific inputs included EFSA re-evaluation schedules for legacy preservatives and US poultry processor consolidation patterns standardizing technical requirements.
Material uncertainties — L-arginine fermentation supply disruptions, EFSA maximum permitted level revisions, and SAMR GB standard alignment delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization momentum and substitution elasticity in processed protein applications. Recalibration cycles align with material shifts in clean-label mandate enforcement and antimicrobial resistance policy developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Carbomer Market
Functional Chemicals
Phthalimide Market
Functional Chemicals
Global L-Arginine Market
Functional Chemicals
Heptanoic Acid Market
Functional Chemicals
Propylparaben Market
Functional Chemicals
Citrate Market
Functional Chemicals
Global Methylal Market
Functional Chemicals
Para-Aminophenol Market
Functional Chemicals
Tartrazine Market
Functional Chemicals
Asia-Pacific Amino Acids Market
Functional Chemicals
Isophthaloyl Chloride Market
Functional Chemicals
Furan Dicarboxylic Methyl Ester (FDME) Market
Functional Chemicals
Global Glutamic Acid Market
Functional Chemicals
Glutaraldehyde Market
Functional Chemicals
Europe Fumaric Acid Market
Functional Chemicals
L-Cysteine Market