
 Vitamin C Serum Market | 2026-2036
Vitamin C Serum Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin C Serum Market Insights
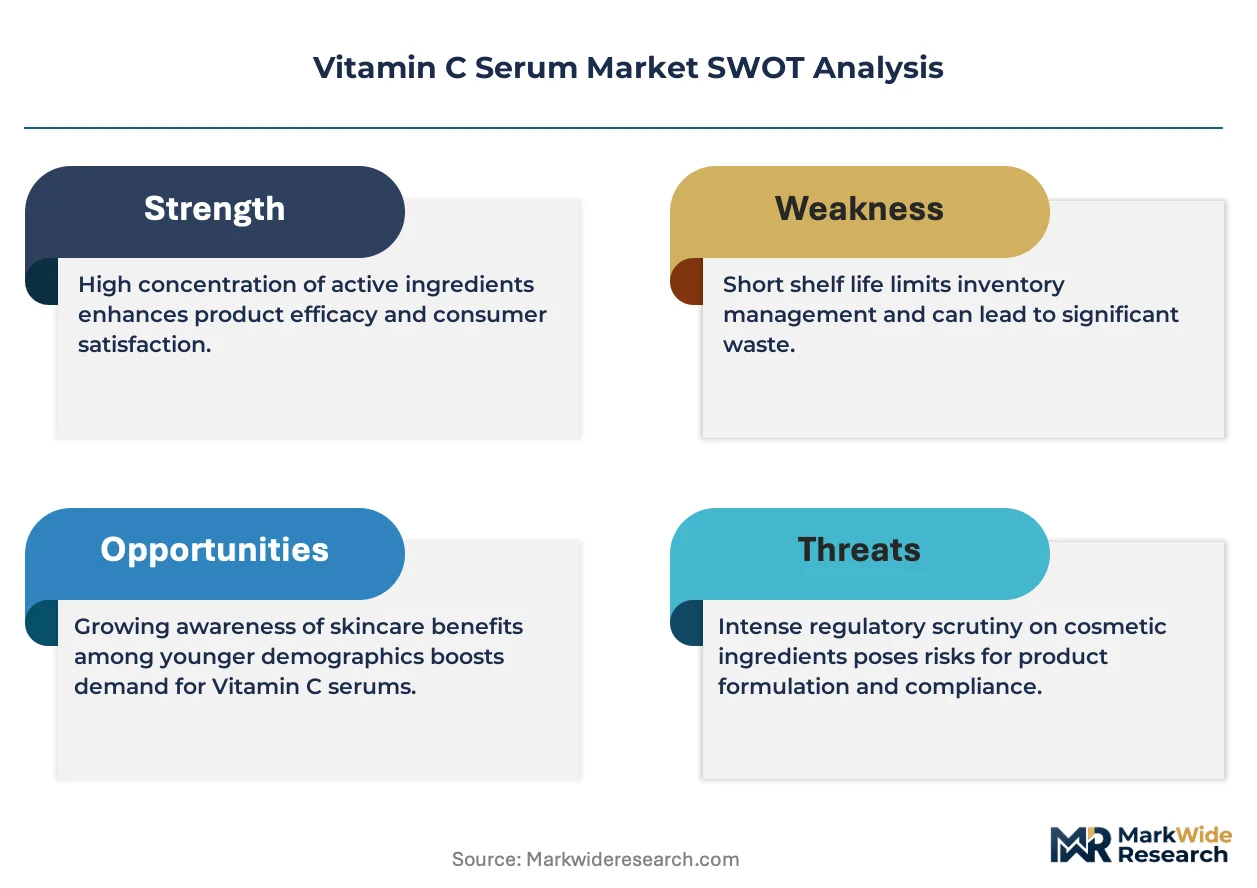
Encapsulation technology is narrowing the gap between lab-grade L-ascorbic acid potency and shelf-stable consumer formulations. L'Oréal S.A. leverages its dermatological science division to anchor clinical credibility in professional channels. Shiseido Company Limited sustains Japanese precision manufacturing standards for oxidation-controlled production. Estée Lauder Companies Inc. competes through prestige retail distribution and physician-office partnerships.
Vitamin C serum is a topical antioxidant formulation typically containing L-ascorbic acid or its derivatives at concentrations between five and twenty percent, designed to neutralize free radicals and stimulate collagen synthesis in skin tissue. The product type dimension shows serum formats capturing the highest margin pools due to consumer perception of clinical efficacy and faster absorption profiles. Concentration tiers reveal that fifteen and twenty percent segments attract premium pricing while five percent formulations serve entry-level and sensitive-skin categories. Packaging type influences oxidation risk, with airless pump bottles and amber glass droppers dominating premium positioning against sachet and tube alternatives in mass-market distribution.
The EU Cosmetic Product Regulation and REACH framework govern ingredient safety and stability claims across European formulation labs, while the FDA oversees cosmetic labeling and structure-function boundaries in the United States. China's NMPA requires pre-market registration for functional cosmetic claims including antioxidant efficacy, creating compliance costs that favor established multinationals with regulatory affairs infrastructure. Stakeholders must monitor evolving photostability testing standards and clean beauty certification requirements as retail buyers and dermatology partners sharpen due diligence protocols.
Market Dynamics
Encapsulation chemistry is compressing the performance gap between pharmaceutical-grade L-ascorbic acid and mass-market shelf stability, forcing reformulation cycles across contract manufacturers and brand labs alike.
Growth Catalysts
- EU Cosmetic Product Regulation:Tightening stability documentation requirements for antioxidant claims are filtering out undercapitalized competitors and consolidating shelf space for compliant formulators in France and Germany.
- Dermatology clinic protocols:Professional channel adoption in Seoul and Manhattan is creating pull-through demand for maintenance-grade home use serums at 15-20% concentration tiers.
- Liposomal delivery systems:Phospholipid encapsulation methods developed for pharmaceutical transdermal applications are migrating into cosmetic manufacturing, extending viable shelf life from three to twelve months.
Market Restraints
- L-ascorbic acid oxidation kinetics:Unstable molecular structure requires nitrogen-blanketed production environments and cold-chain distribution, elevating unit economics 40-60% above derivative alternatives.
- Raw material concentration:Bulk ascorbic acid supply clusters with three Chinese chemical processors, exposing formulators to export license volatility and input cost spikes.
- China NMPA functional cosmetic registration:Pre-market antioxidant efficacy dossiers demand 18-24 month approval timelines and six-figure testing investments, blocking mid-tier brand entry.
Strategic Opportunities
- Men's grooming verticals:Underpenetrated male skincare segments in South Korea and the United States present white space for simplified, non-gendered serum positioning at 10% entry concentrations.
- Physician-dispensed channels:Medical spa and aesthetic clinic partnerships offer margin protection against retail price compression while building clinical credibility.
- Biodegradable encapsulation polymers:Convergence of microplastic-free mandates and sustained-release technology opens premium positioning for marine-safe shell formulations.
Industry Challenges
- Photostability validation protocols:ISO 24443 sunscreen-adjacent testing standards for antioxidant photoprotection claims require specialized irradiation chambers and 12-week stability studies that strain R&D budgets.
- Cross-functional talent scarcity:Formulation chemists with combined expertise in cosmetic stability and dermatological efficacy evidence are concentrated in Basel, Seoul, and New Jersey, driving compensation premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin C Serum Market |
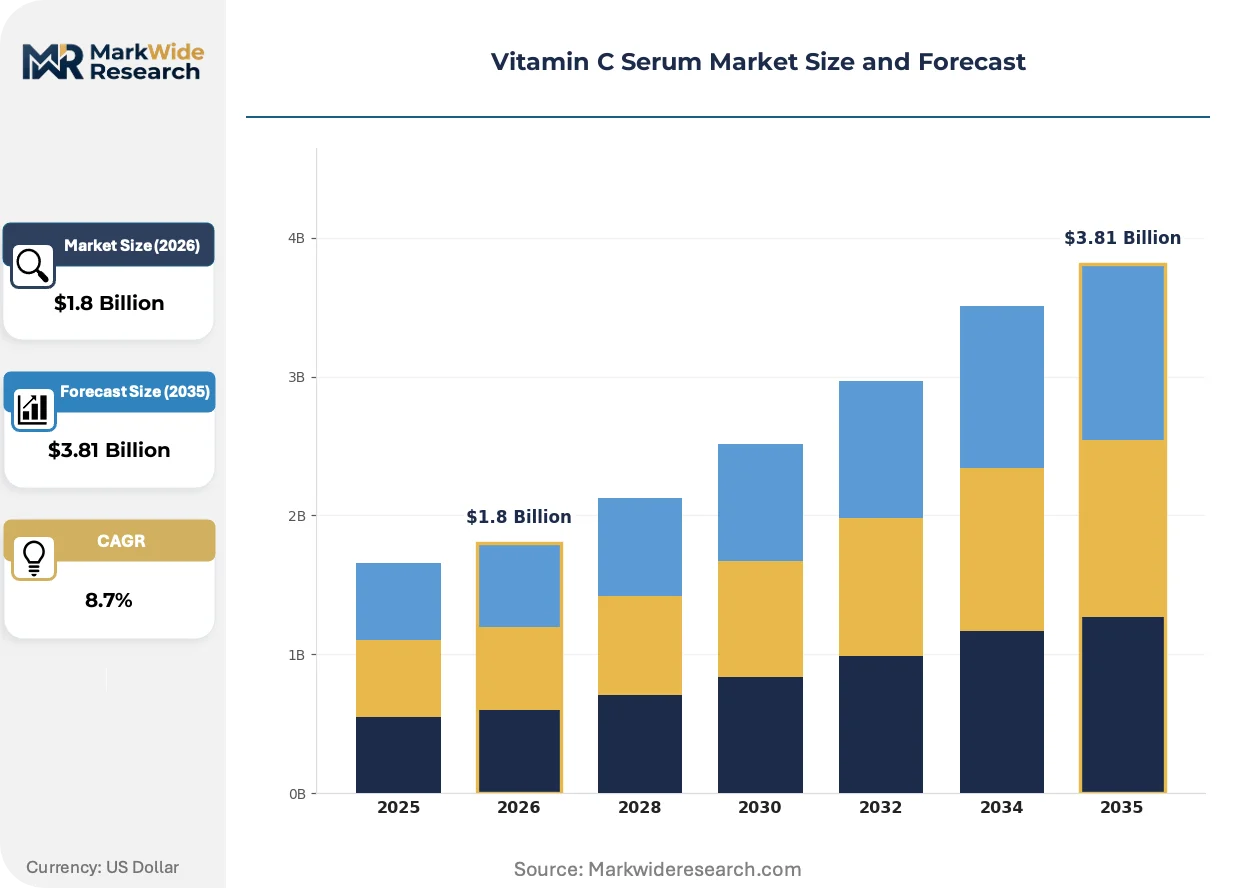
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serum, Cream, Lotion, Gel Concentration: 5%, 10%, 15%, 20% Packaging Type: Dropper Bottle, Pump Bottle, Sachet, Tube End User: Women, Men, Salons, Beauty Clinics |
| Companies Covered | L'Oréal S.A., Galderma S.A., Amorepacific Group Inc., KOSÉ Corporation, Clarins Inc., Unilever plc, Shiseido Company Limited, Beiersdorf AG, Estée Lauder Companies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin C Serum Market Trends and Innovations
Active ingredient delivery science and regulatory documentation standards are compressing product development timelines while fragmenting competitive advantage between manufacturing scale and clinical substantiation capabilities.
Liposomal and niosomal encapsulation technology is migrating from oncology transdermal patches into cosmetic serum manufacturing. Korean contract manufacturers in Gyeonggi-do province are retrofitting pharmaceutical-grade clean rooms for beauty production. This technology is compressing the oxidation timeline that previously limited L-ascorbic acid distribution to refrigerated professional channels.
China's NMPA implemented updated guidelines for functional cosmetic claims documentation in 2021, requiring stability data across three temperature-humidity conditions. Domestic brands in Shanghai and Hangzhou are building in-house regulatory affairs teams rather than relying on third-party registration agents. Multinational entrants without existing NMPA infrastructure are ceding shelf space to established local players with dossier libraries.
Subscription-based replenishment models are displacing traditional retail replenishment cycles in the United States direct-to-consumer channel. Serum brands with loyalty-program data infrastructure are capturing 18-month customer lifetime values versus 4-6 months for retail-only competitors. This pattern concentrates in California and New York metro markets where same-day delivery logistics enable just-in-time restocking.
Vitamin C Serum Market Segmentation
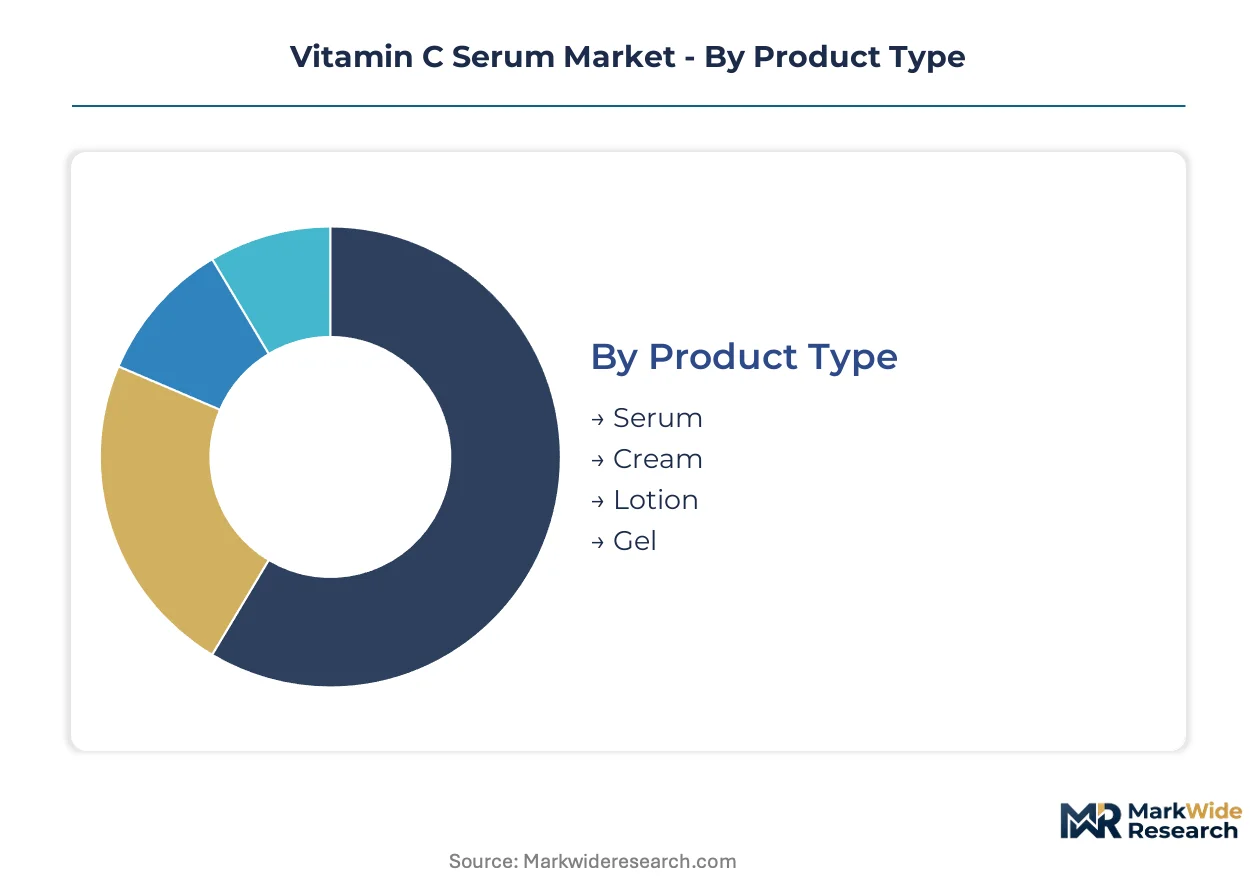
Segmentation in the Vitamin C serum market determines margin capture, shelf positioning, and regulatory pathway complexity. Concentration tiers and packaging formats directly influence oxidation risk management and distribution channel eligibility.
Product Type:
After-sales service intensity varies sharply across formats, with serum users requiring stability troubleshooting and concentration guidance that cream and lotion buyers rarely demand.
- Serum:Water-based formulations with molecular weights below 500 Daltons enable dermal penetration rates unmatched by emulsion alternatives. Demand clusters in Seoul's Gangnam district dermatology clinics and Manhattan's Upper East Side medical spas, where physicians prescribe maintenance protocols following laser resurfacing procedures. The format commands premium shelf placement in Sephora and Olive Young retail networks due to perceived clinical credibility.
- Cream:Oil-in-water emulsions incorporating occlusive agents that buffer L-ascorbic acid against environmental degradation. French pharmacy chains in Paris and Lyon stock concentration-tiered cream lines alongside thermal spring water brands, serving sensitive-skin demographics seeking antioxidant benefits without irritation risk.
- Lotion:Lightweight fluid textures targeting body application and humid climate markets. Thai and Vietnamese consumers in Bangkok and Ho Chi Minh City favor lotion formats for daily photoprotection regimens.
- Gel:Silicone-free aqueous matrices favored by acne-prone demographics. South Korean male grooming specialists in Busan deploy gel formats for post-shave antioxidant recovery protocols.
Serum holds the largest share; momentum sits with cream as pharmacy channel expansion accelerates across Southern Europe.
Concentration:
Cost tier stratification maps directly to customer acquisition economics, with entry-level concentrations subsidizing trial conversion and professional-grade tiers extracting lifetime value.
- 5%:Threshold concentration for measurable collagen synthesis stimulation without erythema induction. Japanese consumers in Osaka and Fukuoka favor this tier for daily morning use under sunscreen layers, driving volume through drugstore chains like Matsumoto Kiyoshi.
- 10%:Balanced efficacy-to-tolerance ratio capturing first-time upgraders from derivative formulations. Australian consumers in Sydney and Melbourne purchase this tier through Priceline pharmacy loyalty programs.
- 15%:Clinical threshold for physician-dispensed protocols. Los Angeles and Miami medical aesthetics practices stock this concentration for post-peel home maintenance, requiring refrigeration and nitrogen-flushed packaging that elevates unit economics.
- 20%:Maximum tolerable L-ascorbic acid concentration before pro-oxidant effects emerge. Seoul's Cheongdam-dong luxury dermatology clinics prescribe this tier for melasma management, with patients signing informed consent documentation for potential tingling sensations.
15% concentration anchors professional channel revenue; 5% formulations are expanding most quickly through mass-market digital commerce.
Packaging Type:
Volume throughput and margin protection diverge across packaging investments, with airless systems requiring capital expenditure that tube formats avoid.
- Dropper Bottle:Amber glass construction with rubber bulb dispensers dominates prestige positioning. German consumers in Munich and Hamburg associate dropper application with apothecary authenticity, supporting price premiums in Douglas perfumery chains.
- Pump Bottle:Airless vacuum systems eliminating headspace oxygen exposure. Italian manufacturers in Lombardy specialize in mono-material pump bodies compliant with EU Single-Use Plastics Directive recycling mandates.
- Sachet:Single-use foil laminates for travel retail and sampling programs. Dubai Duty Free and Singapore Changi Airport stock sachet formats for Southeast Asian transit passengers seeking TSA-compliant antioxidant options.
- Tube:Laminated aluminum-plastic barriers for mass-market distribution. Brazilian consumers in São Paulo purchase tube formats through Magazine Luiza e-commerce flash sales.
Pump bottle holds the largest share; sachet formats are gaining share fastest through airline retail and subscription box sampling.
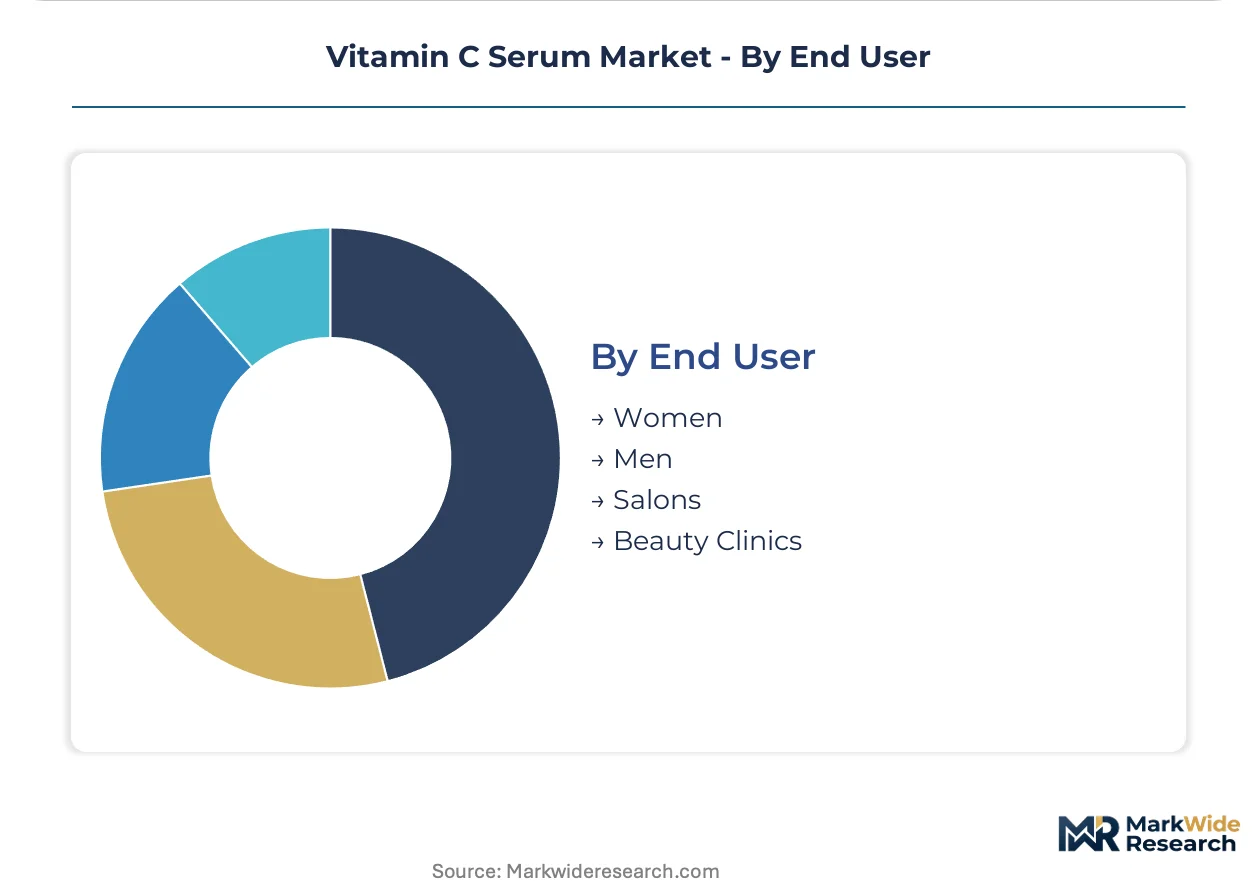
End User:
Customer type determines formulation complexity, with professional channels demanding batch traceability that direct-to-consumer brands rarely provide.
- Women:Primary demographic driving 65-75% of category volume across all geographies. Brazilian women in Rio de Janeiro and São Paulo incorporate Vitamin C into multi-step routines alongside niacinamide and retinoid layering.
- Men:Underpenetrated segment responding to simplified positioning. South Korean male consumers in Seoul's Jongno district purchase 10% concentration serums through Olive Young men's grooming sections, often as first skincare purchases beyond basic cleansers.
- Salons:Licensed esthetician channels requiring wholesale pricing and educational support. French beauty institutes in Lyon and Marseille stock professional-only 20% concentrations for facial treatment add-ons.
- Beauty Clinics:Physician-supervised settings with liability documentation requirements. New York State dermatology practices maintain lot numbers and stability certificates for malpractice insurance compliance.
Women hold the largest share; beauty clinics are climbing the fastest as medical aesthetics integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean contract manufacturers export professional-grade encapsulated serums to dermatology clinics in Manhattan and Beverly Hills, establishing a trans-Pacific trade corridor for clinical antioxidant formulations.
United States
Medical aesthetics practices in Los Angeles and Miami drive physician-dispensed 15% concentration protocols. FDA cosmetic labeling requirements govern structure-function claims for collagen synthesis marketing. New York State dermatology clusters in Manhattan maintain batch traceability systems for malpractice insurance compliance.
South Korea
Seoul's Gangnam district dermatology clinics prescribe 20% concentration melasma treatments with informed consent documentation. MFDS regulates functional cosmetic stability claims through pre-market efficacy dossiers. Gyeonggi-do province contract manufacturers retrofit pharmaceutical clean rooms for liposomal encapsulation production.
France
Paris pharmacy chains stock concentration-tiered cream lines alongside thermal spring water brands for sensitive-skin demographics. EU Cosmetic Product Regulation and REACH framework govern antioxidant stability documentation across formulation labs. Lyon beauty institutes maintain professional-only 20% concentrations for facial treatment add-ons.
China
Shanghai and Hangzhou domestic brands build in-house NMPA regulatory affairs teams to manage functional cosmetic registration timelines. NMPA requires 18-24 month approval cycles for antioxidant efficacy claims with six-figure testing investments. Yangtze River Delta formulation labs concentrate clean beauty certification expertise.
Japan
Osaka and Fukuoka consumers favor 5% threshold concentrations for daily morning sunscreen layering. METI and PMDA oversee cosmetic safety standards and quasi-drug classification boundaries. Matsumoto Kiyoshi drugstore chains drive volume through loyalty-program infrastructure.
Vitamin C Serum Market Competitive Landscape
On the supply side, the industry is consolidating around multinationals with captive regulatory affairs infrastructure and pharmaceutical-grade manufacturing capabilities. Tiered competition separates prestige dermatology-channel specialists from mass-market derivative formulators. Three archetypes dominate: science-anchored dermatology brands, precision-manufacturing Japanese houses, and scale-driven consumer goods conglomerates. Capacity expansion in Korean contract manufacturing and strategic partnerships between encapsulation technology licensors and brand labs represent the dominant competitive vectors.
Within the science-anchored tier, L'Oréal S.A. and Galderma S.A. exemplify dermatological credibility strategies, while Shiseido Company Limited occupies a position representing Japanese precision manufacturing standards for oxidation-controlled production. Estée Lauder Companies Inc. anchors prestige retail distribution archetypes through physician-office channel partnerships.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Galderma S.A. |
| Amorepacific Group Inc. |
| KOSÉ Corporation |
| Clarins Inc. |
| Unilever plc |
| Shiseido Company Limited |
| Beiersdorf AG |
| Estée Lauder Companies Inc. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Korean pharmaceutical-grade clean rooms drives supplier prioritization toward 15-20% concentration tiers, compressing margins on mass-market derivatives while elevating pricing power for encapsulated L-ascorbic acid formats.
Pricing Analysis
Prior-generation unencapsulated serum pricing anchors entry tiers at 5% concentrations, while next-generation liposomal delivery commands 40-60% premiums at professional-grade potency. Three-tier pricing structure across premium, standard, and economy levels separates physician-dispensed protocols from pharmacy-channel creams and mass-market sachets. Cost compression in derivative formulations is intensifying because Chinese bulk ascorbic acid processors face export license volatility. Price-sensitive mass-market consumers in Brazil and Southeast Asia gravitate toward tube and sachet formats, while Seoul dermatology clinics absorb premium pump-bottle pricing without volume elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates raw material procurement risk for North American formulators. Bulk ascorbic acid supply clusters with three Chinese chemical processors, while Korean contract manufacturers in Gyeonggi-do province control pharmaceutical-grade encapsulation capacity. Nitrogen-blanketed production environments and cold-chain distribution rest on specialized logistics partnerships with temperature-validated carriers. Distribution runs through dermatology clinic direct accounts in Seoul and Manhattan, pharmacy chains in Paris and Lyon, and e-commerce flash-sale platforms in São Paulo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards formulators who command both oxidation-stability science and regulatory dossier expertise, yet talent pools with combined cosmetic-chemistry and dermatological-evidence capabilities remain thin in Basel, Seoul, and New Jersey clusters.
For Market Incumbents: Harden clinical credibility moats by deepening physician-office channel partnerships in Los Angeles and Miami medical aesthetics practices. Expand captive regulatory affairs infrastructure to preempt NMPA functional cosmetic registration delays that block mid-tier competitors. Prioritize backward integration into liposomal encapsulation polymer sourcing to secure marine-safe biodegradable shell supply against microplastic-free mandate acceleration. For New Entrants and Emerging Players: Male grooming verticals in South Korea and the United States present underpenetrated white space for simplified 10% concentration positioning with non-gendered packaging. Australian pharmacy loyalty programs offer accessible trial conversion mechanics for first-time upgraders from derivative formulations. Deploy subscription-based replenishment models with same-day delivery logistics to capture 18-month customer lifetime values in California and New York metro markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade encapsulation manufacturing as Korean contract manufacturers retrofit clean rooms for beauty production. Long-term viability favors targets with established NMPA dossier libraries and Seoul-based dermatology clinic relationships over pure-brand plays without regulatory infrastructure. Monitor liposomal encapsulation patent expiration schedules as inflection indicators for manufacturing cost curves.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Korean pharmaceutical transdermal expertise migrates into cosmetic shelf-stability extension. |
| Physician-Dispensed Channel Expansion | Los Angeles medical aesthetics practices anchor malpractice-insurance-compliant batch traceability systems. |
| NMPA Regulatory Affairs Buildout | Shanghai domestic brands capture shelf space from multinationals lacking pre-market registration infrastructure. |
| Biodegradable Polymer Development | Marine-safe shell formulations satisfy EU microplastic-free mandates while enabling sustained-release positioning. |
| Subscription Replenishment Infrastructure | California same-day delivery logistics compress restocking cycles to just-in-time patterns. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with formulation chemists, regulatory affairs directors, dermatology clinic procurement managers, and contract manufacturing executives; and secondary validation against MFDS functional cosmetic filings, NMPA registration databases, EU Cosmetic Product Regulation stability documentation, and customs trade records for bulk ascorbic acid movements. Bottom-up concentration-tier volume modeling triangulated against top-down macroeconomic demand elasticity assumptions.
Forecast inputs span concentration tiers, packaging format oxidation-risk profiles, channel-specific margin structures, and regional regulatory pathway complexity across the analysis window. CAGRs derive from segment-level volume buildups adjusted for encapsulation technology adoption curves and professional-channel protocol expansion rates. Modeled variables include liposomal delivery penetration in Seoul dermatology clinics and subscription-program customer lifetime value differentials in United States direct-to-consumer channels.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Korean contract manufacturers or accelerated NMPA registration streamlining would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
DNA-Based Skin Care Products Market
Skincare
Self-Tanning Care Market
Skincare
US Acne Treatment Market
Skincare
Ampoule Cream Market
Skincare
Hyaluronic Acid Personal Care Products Market
Skincare
Anti-Aging Services Market
Skincare
Acne Treatment Market
Skincare
Cosmeceutical Ingredients Market
Skincare
Global Anti-Aging Products and Services Market
Skincare
Facial Erythema Treatment Market
Skincare
Organic Skincare Products Market
Skincare
Skin Bioactive Market
Skincare
Facial Cleansing Balm Market
Skincare
Natural Skin Care Products Market
Skincare
Germany Skincare Product Market
Skincare
Global Scar Removal Treatment Market