
 Facial Skincare Market | 2026-2036
Facial Skincare Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Skincare Market Analysis
The premium facial skincare tier is rebalancing around biotechnology-derived actives and personalized diagnostics, while commodity segments compete on volume and accessibility. L'Oréal SA leverages its dermatological science pipeline to sustain pricing power across prestige channels. Estée Lauder anchors its portfolio in heritage luxury positioning with concentrated serum formats. Shiseido dominates East Asian innovation ecosystems through advanced fermentation-derived ingredients.
Facial skincare encompasses topical formulations designed to cleanse, protect, and improve skin barrier function through active ingredients delivered at specified pH levels and molecular weights. These products serve both therapeutic and aesthetic purposes in daily consumer regimens and professional treatment protocols. Moisturizers and serums command the deepest margin pools due to repeat purchase frequency and premium positioning potential. Organic and natural formulations are accelerating fastest as clean beauty certifications reshape consumer trust architectures. Synthetic segments retain volume leadership in mass-market channels where cost efficiency governs procurement.
FDA oversight of cosmetic safety claims, REACH chemical registration requirements in Europe, and China's NMPA ingredient approval pathways collectively elevate compliance costs while filtering market entrants. These frameworks push brands toward pre-market testing investments and supply chain documentation that smaller competitors struggle to fund. Stakeholders must monitor evolving microbiome-related claim restrictions and biotech ingredient classifications that could redraw competitive boundaries.
Market Dynamics
Biotechnology-derived actives and fermentation-based ingredient platforms are compressing development cycles while forcing legacy formulators to rebuild R&D infrastructure around molecular precision rather than botanical extraction traditions.
Growth Catalysts
- EU Green Deal chemical transparency mandates:REACH registration expansions are accelerating clean beauty certification adoption across European distribution channels.
- South Korean fermentation biotechnology:Advanced bio-processing facilities in Seoul and Incheon are exporting ingredient platforms to Western prestige brands.
- Preventive skincare routines among Gen Z demographics:Early-age barrier protection protocols are extending consumer lifetime value curves in North American and Asian markets.
Market Restraints
- Raw material concentration in East Asian biotech suppliers:Single-source dependency for specialized fermentation extracts creates vulnerability to regional production disruptions.
- REACH compliance cost escalation:Small and mid-sized formulators face prohibitive pre-market testing investments for novel active ingredients.
- Clinical validation requirements for microbiome claims:Evidentiary standards for live culture and postbiotic formulations remain undefined across major regulatory jurisdictions.
Strategic Opportunities
- India's emerging prestige distribution infrastructure:Mumbai and Delhi luxury retail expansions are creating first-mover positioning for biotechnology-positioned entrants.
- AI-driven skin diagnostics convergence:Computer vision and spectrometry integration enables personalized serum formulation at point-of-sale.
- Brazil's ANVISA accelerated approval pathways:Streamlined biotechnology ingredient registrations are opening Latin American market access for fermentation-derived actives.
Industry Challenges
- Fermentation process scale-up engineering:Translating laboratory yields to industrial bioreactor consistency requires specialized biochemical engineering talent pools concentrated in South Korea and Switzerland.
- Cross-jurisdictional claim harmonization:Divergent FDA, EMA, and NMPA positions on live culture safety are forcing parallel clinical study investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Skincare Market |
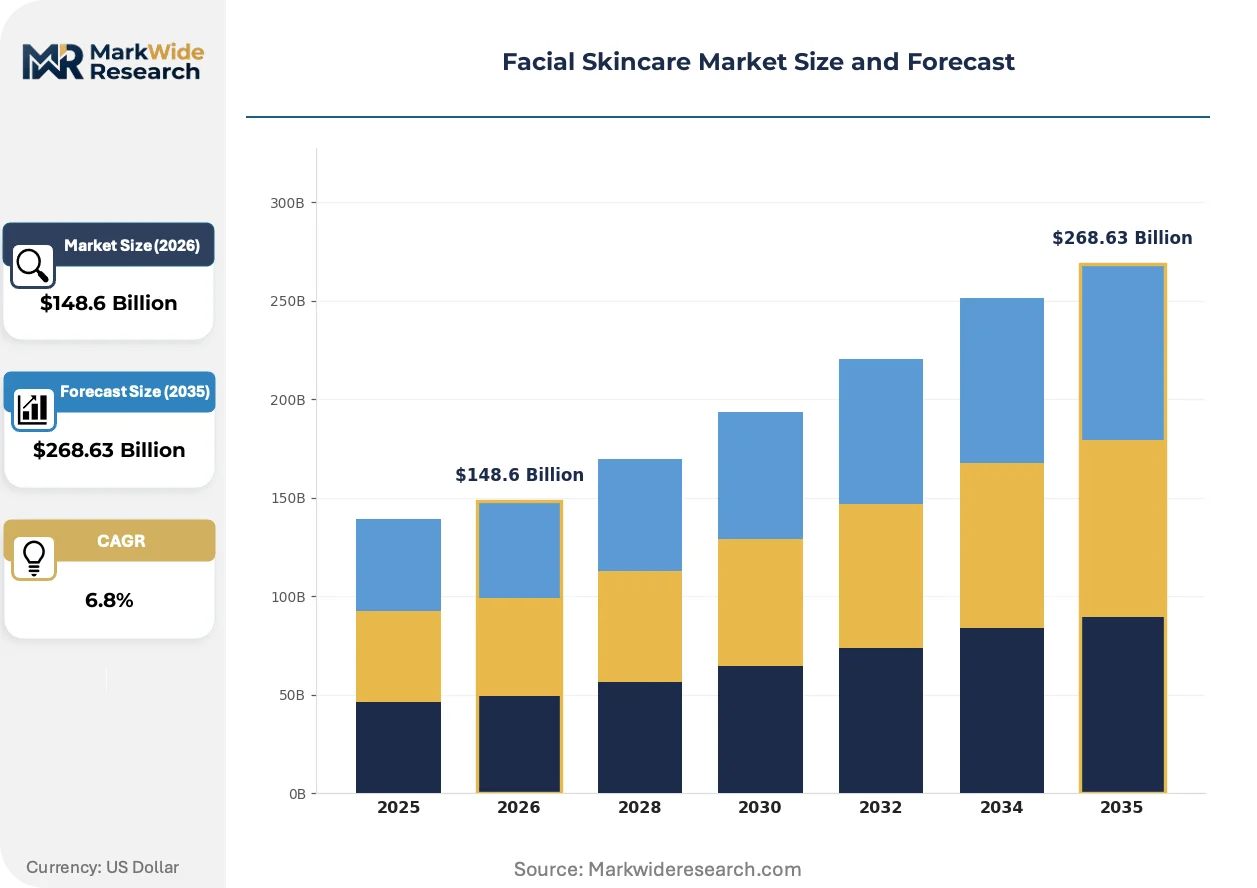
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $268.63 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Serums, Cleansers, Exfoliators Formulation Type: Organic, Natural, Synthetic, Mineral Skin Type: Oily, Dry, Sensitive, Combination Application Method: Topical, Mask, Treatment, Essential Oils |
| Companies Covered | L'Oréal SA, The Procter & Gamble Company, The Estée Lauder Companies Inc., Unilever PLC, Beiersdorf AG, Shiseido Company Limited, Johnson & Johnson Services Inc., Coty Inc., Amorepacific Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Skincare Market Emerging Trajectories
Precision biotechnology is displacing conventional extraction methods across active ingredient sourcing, while regulatory frameworks force simultaneous transparency and safety documentation investments.
Bioreactor-cultured collagen and elastin alternatives are converging with traditional peptide synthesis to create hybrid active platforms with superior skin penetration profiles. Prestige brands in Seoul and Paris are adopting these materials for next-generation serum launches. The technology is converging with microencapsulation delivery systems to enable time-release functionality previously unattainable with plant-derived equivalents.
REACH chemical registration expansions under the EU Green Deal are mandating full supply chain disclosure for cosmetic ingredients. Formulators must now document origin, processing, and degradation pathways for every active compound. European prestige segments are responding by restructuring procurement around vertically integrated biotechnology suppliers with captive fermentation capacity.
Direct-to-consumer diagnostic ecosystems are replacing counter-based skin consultations as the primary channel for personalized product matching. AI-powered imaging applications in Shanghai and Los Angeles are capturing facial microbiome and barrier function data to algorithmically recommend regimen combinations. This shift is most pronounced among millennial and Gen Z cohorts in urban Chinese and North American markets where digital-native purchasing patterns dominate.
Facial Skincare Market Segmentation
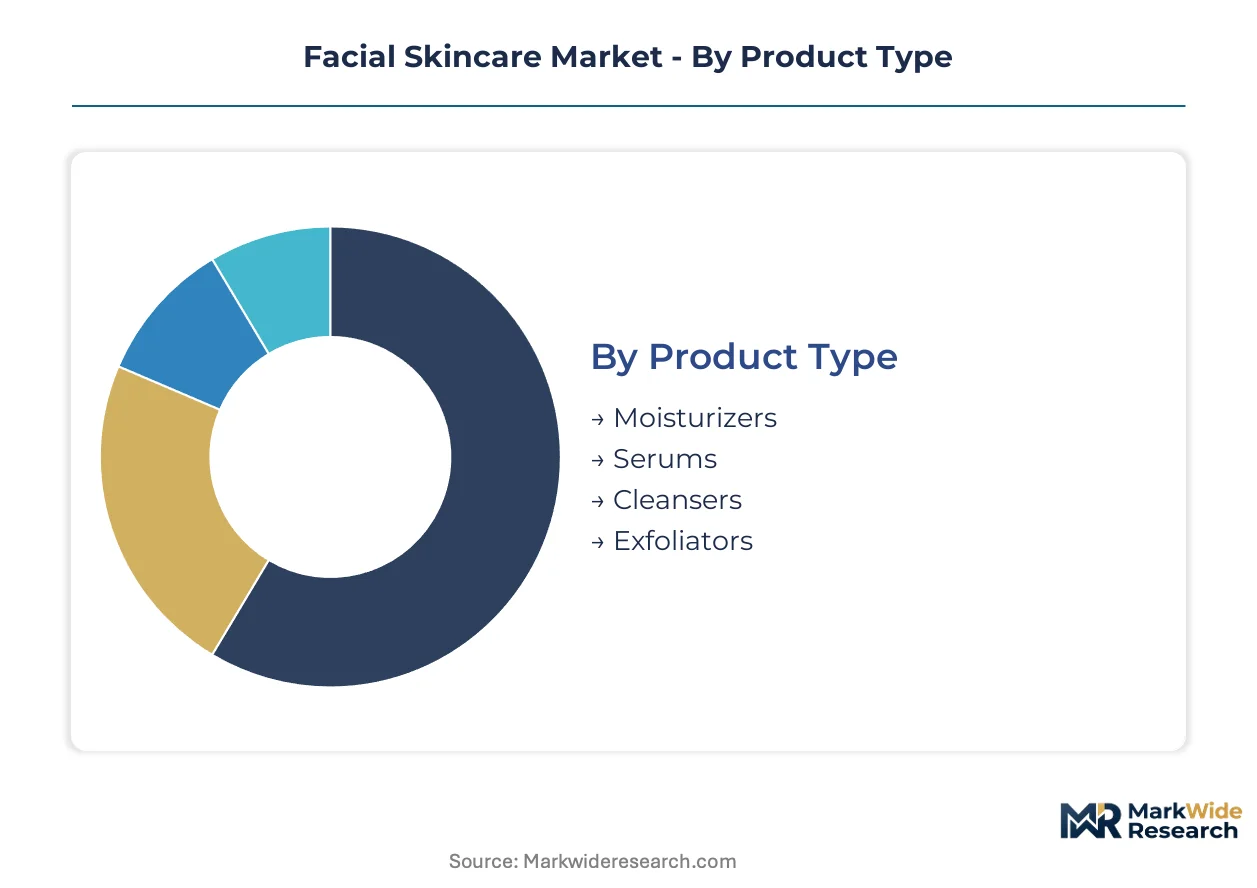
Facial skincare segmentation reflects divergent consumer priorities across efficacy claims, ingredient provenance, and skin condition specificity. Formulators align R&D investments and distribution channel selection with these category boundaries to capture margin pools and repeat purchase frequency.
Product Type:
Purchase frequency and margin depth drive consumer selection across daily-use versus treatment-oriented formats.
- Moisturizers:Emulsion-based formulations combining humectants, occlusives, and emollients at specified oil-water ratios. Demand concentrates in North American prestige retail where barrier repair claims support premium positioning. Repeat purchase cycles sustain the deepest margin pools in facial skincare.
- Serums:Low-viscosity concentrates delivering high-actives at targeted molecular weights for dermal penetration. South Korean consumers anchor global volume through multi-step regimen adoption. Concentrated formats command per-ounce pricing premiums that fund biotechnology R&D amortization.
- Cleansers:Surfactant-based or oil-based formulations for sebum and environmental particulate removal. Mass-market channels in India and Brazil drive volume scale.
- Exfoliators:Chemical acid or physical particle formulations for stratum corneum turnover. Professional treatment protocols in European dermatology clinics sustain medical-grade demand.
Volume sits with moisturizers; growth tilts toward serums.
Formulation Type:
Ingredient sourcing transparency is reshaping procurement patterns and certification requirements across price tiers.
- Organic:Certified formulations meeting USDA or ECOCERT standards for agricultural ingredient provenance. European distribution channels under EU Green Deal mandates are accelerating adoption. Clean beauty certifications command 15-40% price premiums in prestige segments.
- Natural:Botanically derived actives without synthetic processing aids. Urban Chinese millennials and Gen Z cohorts in Shanghai and Beijing are concentrating demand. Regulatory ambiguity around "natural" claim definitions creates compliance friction in multi-jurisdictional launches.
- Synthetic:Laboratory-engineered actives including peptides, retinoids, and stabilized vitamins. Mass-market cost efficiency governs procurement in Southeast Asian and Latin American channels.
- Mineral:Inorganic UV filters and pigment formulations for photoprotection and tone correction. Australian and South African markets with high UV index exposure sustain specialized demand.
Volume sits with synthetic formulations; expansion is accelerating fastest for organic certification tiers.
Skin Type:
Condition-specific targeting enables clinical positioning and dermatological channel access.
- Oily:Sebum-regulating formulations with salicylic acid or niacinamide actives. Southeast Asian humid climates and teenage demographics in Mexico concentrate demand.
- Dry:Lipid-replenishing ceramide and squalane concentrates. Aging populations in Japan and Germany sustain medical-aesthetic crossover sales.
- Sensitive:Fragrance-free, minimal-ingredient protocols for barrier-compromised skin. Pediatric and post-procedure applications in French pharmacy channels anchor volume.
- Combination:Zone-differentiated or balancing formulations addressing simultaneous oily T-zone and dry cheek conditions. Working-age professionals in urban India and Indonesia drive trial and conversion.
Volume sits with combination skin targeting; growth tilts toward sensitive skin protocols as barrier health education expands.
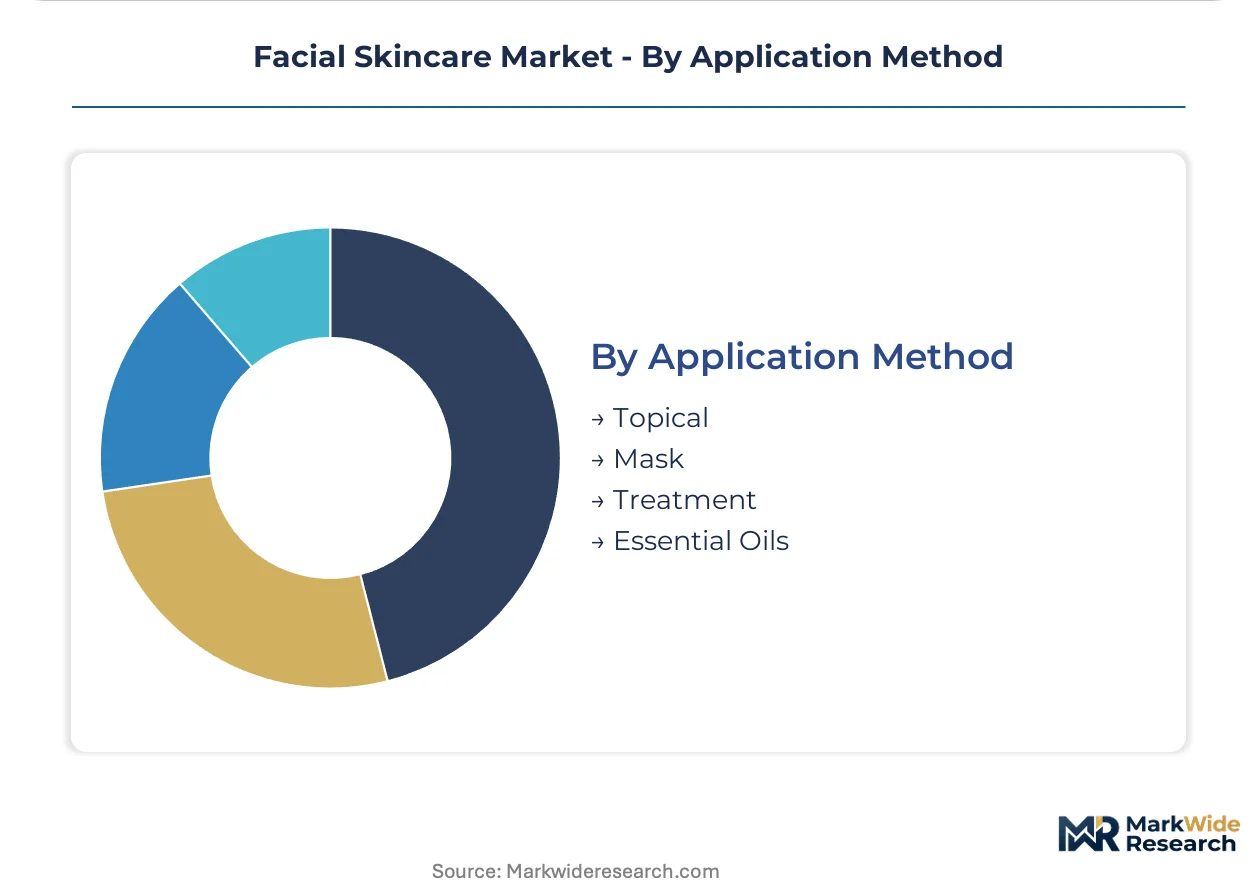
Application Method:
Ritual complexity and time investment segment consumers across daily maintenance versus intensive treatment occasions.
- Topical:Direct skin application of creams, lotions, and fluids without intermediary tools. Universal daily-use format dominates mass-market volume in all geographies.
- Mask:Occlusive or rinse-off treatments for concentrated active delivery. South Korean sheet mask innovation continues setting global product benchmarks.
- Treatment:Professional-grade protocols including peels, microdermabrasion, and LED therapy adjuncts. US medical spa and dermatology clinic channels sustain premium pricing.
- Essential Oils:Aromatherapeutic facial applications with botanical distillates. Wellness-oriented consumers in California and British Columbia concentrate niche demand.
Volume sits with topical application; growth tilts toward mask formats as at-home treatment occasions multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors biotechnology ingredient production for facial skincare, with fermentation facilities in Incheon and Songdo exporting active platforms to Western prestige brands. Regulatory divergence across FDA, EMA, and NMPA jurisdictions fragments compliance pathways. Consumer demand clusters in urban corridors where digital diagnostics and multi-step regimens concentrate.
United States
Gen Z preventive skincare routines drive volume in Los Angeles and New York metro corridors, with medical spa channels sustaining premium treatment protocol demand. FDA cosmetic safety claim oversight elevates pre-market testing investments for microbiome-related formulations. Boston and San Francisco biotech clusters incubate fermentation-derived active startups seeking dermatological channel access.
South Korea
Seoul-Incheon fermentation biotechnology exports set global ingredient benchmarks for peptide and collagen alternatives. MFDS regulatory frameworks accelerate novel active approvals while REACH-aligned documentation supports European export compliance. Gangnam district prestige retail concentrates K-beauty innovation diffusion through flagship experience centers.
China
Shanghai and Beijing millennial cohorts anchor demand for AI-driven skin diagnostics and personalized serum matching. NMPA ingredient approval pathways filter market entrants through extended safety documentation requirements. Yangtze River Delta manufacturing clusters supply synthetic active intermediates for domestic and Southeast Asian formulation houses.
Germany
REACH chemical registration expansions under EU Green Deal mandates restructure procurement toward vertically integrated biotechnology suppliers. Hamburg and Düsseldorf distribution channels concentrate clean beauty certification adoption across prestige segments. Bavarian biochemical engineering talent pools support industrial bioreactor scale-up for fermentation-derived actives.
India
Mumbai and Delhi luxury retail expansions create first-mover positioning for biotechnology-positioned entrants targeting emerging prestige distribution. BIS cosmetic standards and CDSCO ingredient oversight elevate compliance documentation requirements for imported actives. Maharashtra pharmaceutical manufacturing corridors repurpose fermentation capacity toward skincare active production.
Facial Skincare Market Vendor Landscape
Capital-heavy biotechnology producers compete with asset-light brand designers across the facial skincare value chain. The market structure concentrates in three tiers: integrated conglomerates with captive R&D pipelines, regional specialists leveraging geographic ingredient sourcing advantages, and digital-native direct-to-consumer entrants. Strategic archetypes include fermentation biotechnology vertically integrated players, heritage luxury houses anchored in serum concentrate formats, and AI-diagnostic platform operators. Dominant competitive moves span M&A for biotechnology acquisition and strategic partnerships with East Asian ingredient suppliers.
Within the integrated conglomerate tier, L'Oréal SA and The Estée Lauder Companies Inc. exemplify divergent positioning archetypes. L'Oréal SA represents dermatological science pipeline operators sustaining pricing power across prestige channels. Estée Lauder occupies heritage luxury positioning with concentrated serum format concentration. Shiseido Company Limited anchors East Asian innovation ecosystem representation through advanced fermentation-derived ingredient platforms.
| Leading Market Players |
|---|
| L'Oréal SA |
| The Procter & Gamble Company |
| The Estée Lauder Companies Inc. |
| Unilever PLC |
| Beiersdorf AG |
| Shiseido Company Limited |
| Johnson & Johnson Services Inc. |
| Coty Inc. |
| Amorepacific Corp. |
| Others |
Supply Flow & Price Mechanics
Captive fermentation capacity in South Korean biotech clusters anchors pricing power for prestige serum formats, while outsourced botanical extraction governs commodity moisturizer margins. REACH documentation requirements and single-source peptide dependencies are compressing mid-tier formulators between compliance cost escalation and raw material concentration risk.
Pricing Analysis
Value-based pricing tied to clinical efficacy claims and dermatological channel access separates premium biotechnology-positioned serums from mass-market moisturizers. Certification grade under EU Green Deal mandates and brand heritage in heritage luxury houses drive price differentiation across European and East Asian prestige retail. Pricing pressure stems from fermentation process scale-up engineering bottlenecks that elevate unit costs for novel collagen alternatives. Mass-market synthetic segments exhibit highest buyer price sensitivity; prestige biotechnology tiers retain inelastic demand among preventive skincare adopters.
Supply Chain Analysis
Dual-sourcing requirements for specialized fermentation extracts remain unmet across Western formulators dependent on Seoul-Incheon biotech corridors. Geographic supply concentration centers on South Korea, China, and Switzerland for peptide platforms, bioreactor engineering, and precision biochemical processing. Raw material dependencies include fermentation-derived collagen alternatives, stabilized vitamin actives, and microencapsulation delivery polymers. Single-source vulnerability for advanced bio-processing creates exposure to regional production disruptions. Distribution runs through vertically integrated biotechnology suppliers with captive R&D pipelines serving prestige brand houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The facial skincare market is becoming a vertical-integration race. Players are pursuing backward integration into fermentation biotechnology to secure captive supply of peptide and collagen alternatives.
For Market Incumbents: Anticipate margin compression from digital-native diagnostic platforms by securing exclusive biotechnology supplier agreements and accelerating in-house bioreactor capacity. L'Oréal SA and Estée Lauder should prioritize R&D pipeline consolidation around fermentation-derived actives before REACH compliance costs filter smaller competitors. Defensive patent positioning around microbiome claim formulations will pre-empt regulatory ambiguity. For New Entrants and Emerging Players: Enter via India's emerging prestige distribution infrastructure in Mumbai and Delhi, where biotechnology-positioned positioning faces limited incumbent saturation. AI-driven skin diagnostics convergence in Shanghai and Los Angeles offers white-space for algorithmic serum-matching platforms. A direct-to-consumer diagnostic ecosystem go-to-market angle bypasses legacy retail gatekeeping. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated conglomerates seeking fermentation biotechnology capabilities. Long-term viability favors vertically integrated players with captive bioreactor capacity and REACH-aligned documentation infrastructure. The signal to watch is NMPA ingredient approval pathway streamlining for live culture formulations, which would redraw competitive boundaries for microbiome-positioned entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Acquisition | Captive fermentation capacity secures peptide supply chains against Seoul-Incheon concentration risk. |
| AI Diagnostic Platform Integration | Computer vision deployment in Shanghai and Los Angeles enables personalized serum formulation at scale. |
| REACH Compliance Certification | EU Green Deal documentation supports European prestige channel access and filters undercapitalized competitors. |
| India Prestige Distribution Expansion | Mumbai and Delhi luxury retail openings create first-mover positioning for biotechnology-positioned entrants. |
| Microbiome Claim Clinical Validation | FDA and EMA evidentiary investments preempt regulatory restriction on live culture formulations. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this facial skincare market analysis. Primary interviews with biotechnology R&D directors, prestige brand procurement leads, dermatology clinic purchasing managers, and fermentation facility operations heads combined with FDA cosmetic filings, REACH registration databases, MFDS approval records, and NMPA ingredient submissions. Bottom-up triangulation across product type, formulation certification, and skin condition specificity validated top-down market sizing.
Data-stream reconciliation across shipment volumes, retail audit data, and biotechnology supplier capacity disclosures informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, formulation certification tier, skin condition targeting, and application method, with regional regulatory clusters capturing FDA, EMA, and NMPA pathway divergence. CAGRs were derived from trend extrapolation calibrated against fermentation biotechnology adoption curves and Gen Z preventive skincare penetration patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA approval pathway delays or East Asian biotech supply disruptions. Deviation in REACH chemical registration expansion timelines or microbiome claim evidentiary standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
After Sun Care Products Market
Skincare
Medicine Skin Care Market
Skincare
Retinoids Market
Skincare
Incontinence Skin Care Products Market
Skincare
Mineral Sunscreen Market
Skincare
Hyaluronic Acid Personal Care Products Market
Skincare
Global Cosmetic Skin Care Market
Skincare
Organic Skincare Products Market
Skincare
Skin Care Emulsion Market
Skincare
Cosmeceuticals Market
Skincare
Peel Off Face Mask Market
Skincare
Cystic Acne Market
Skincare
Asia Pacific Traditional Chinese Herbal Medicine for Face-Care Market
Skincare
Africa Cosmeceutical Market
Skincare
Revitalizing Skin Wands Market
Skincare
Skin Grafting System Market