
 ASEAN Sensitive Skin Care Market | 2026-2036
ASEAN Sensitive Skin Care Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Sensitive Skin Care Market Outlook
Single-serve ampoule and mini-serum bundling is shifting buyer choice across pharmacy and online channels in Southeast Asia. L'Oréal SA leverages its dermatological testing infrastructure to sustain premium positioning in Thai drugstore networks. Beiersdorf AG anchors its Nivea Sensitive line through aggressive shelf-space competition in Indonesian supermarkets. Johnson & Johnson Services Inc differentiates via pediatric clinician endorsements that resonate with first-time parents in Malaysian urban centers.
Sensitive skin care denotes topical formulations engineered with reduced irritant profiles, typically excluding common allergens such as synthetic fragrances, alcohol denat, and certain preservatives like methylisothiazolinone, while maintaining epidermal barrier function through ceramide or niacinamide enrichment. These products serve consumers with compromised skin barriers, rosacea, eczema, or post-procedure sensitivity requiring non-reactive maintenance protocols. Moisturizers and serums occupy the dominant value share as consumers layer multiple hydration steps, while fragrance-free formulations command margin premiums due to costlier raw material sourcing and stability testing. Online retail channels are expanding fastest, though specialty stores retain higher conversion rates for premium hypoallergenic lines.
ASEAN Cosmetics Directive harmonization, Thailand's FDA cosmetic registration requirements, and Indonesia's BPOM ingredient notification system collectively elevate compliance costs for new market entrants while rewarding established players with regulatory dossier depth. These frameworks mandate safety assessments that disproportionately burden smaller domestic brands, consolidating shelf access for multinational portfolios with dedicated regulatory affairs teams. Stakeholders must monitor evolving halal certification standards for skincare ingredients, as Malaysia's JAKIM and Indonesia's MUI expand cosmetic-specific guidelines that will reshape formulation choices and sourcing decisions across the regional supply base.
Market Dynamics
ASEAN Cosmetics Directive harmonization is compressing formulation timelines while fragmenting competitive access, as multinational incumbents leverage pre-built regulatory dossiers to secure shelf space ahead of domestic challengers.
Growth Catalysts
- Jakarta-Surabaya corridor demand concentration:Urban millennials in Indonesia's primary metropolitan axis are driving hypoallergenic facial serum adoption through pharmacy chain expansion and dedicated sensitive-skin retail aisles.
- ASEAN Cosmetics Directive ingredient disclosure:Harmonized transparency requirements across member states are accelerating consumer trust in fragrance-free formulations and pushing brands toward dermatologically tested protocols.
- Barrier-repair ceramide technology:Advanced lipid-replacement formulations are capturing preference among rosacea and eczema sufferers seeking non-reactive maintenance regimens.
Market Restraints
- Specialty raw material cost volatility:Fragrance-free stabilizers and pharmaceutical-grade ceramides command premium sourcing costs that compress margin structures for mid-tier formulators.
- Regulatory dossier concentration:Thailand's FDA cosmetic registration requirements and Indonesia's BPOM ingredient notification system disproportionately burden smaller domestic brands lacking dedicated compliance teams.
- Halal certification complexity:Malaysia's JAKIM and Indonesia's MUI are expanding cosmetic-specific guidelines that force reformulation cycles and disrupt established supply relationships.
Strategic Opportunities
- Vietnam pharmacy channel underpenetration:Ho Chi Minh City and Hanoi retail networks remain underserved for dedicated sensitive-skin product lines compared to Indonesian and Thai benchmarks.
- Single-serve ampoule bundling:Mini-serum packaging formats are creating trial-to-loyalty conversion pathways through e-commerce subscription models and pharmacy promotional sets.
- Pediatric clinician endorsement protocols:First-time parent segments in Malaysian urban centers respond to dermatological validation, opening white space beyond adult-focused positioning.
Industry Challenges
- Stability testing capacity scarcity:Extended validation timelines for preservative-free formulations strain in-house quality assurance teams and third-party laboratory availability.
- Cross-border e-commerce compliance friction:Divergent national notification requirements between Thailand, Indonesia, and Malaysia complicate unified regional digital distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Sensitive Skin Care Market |
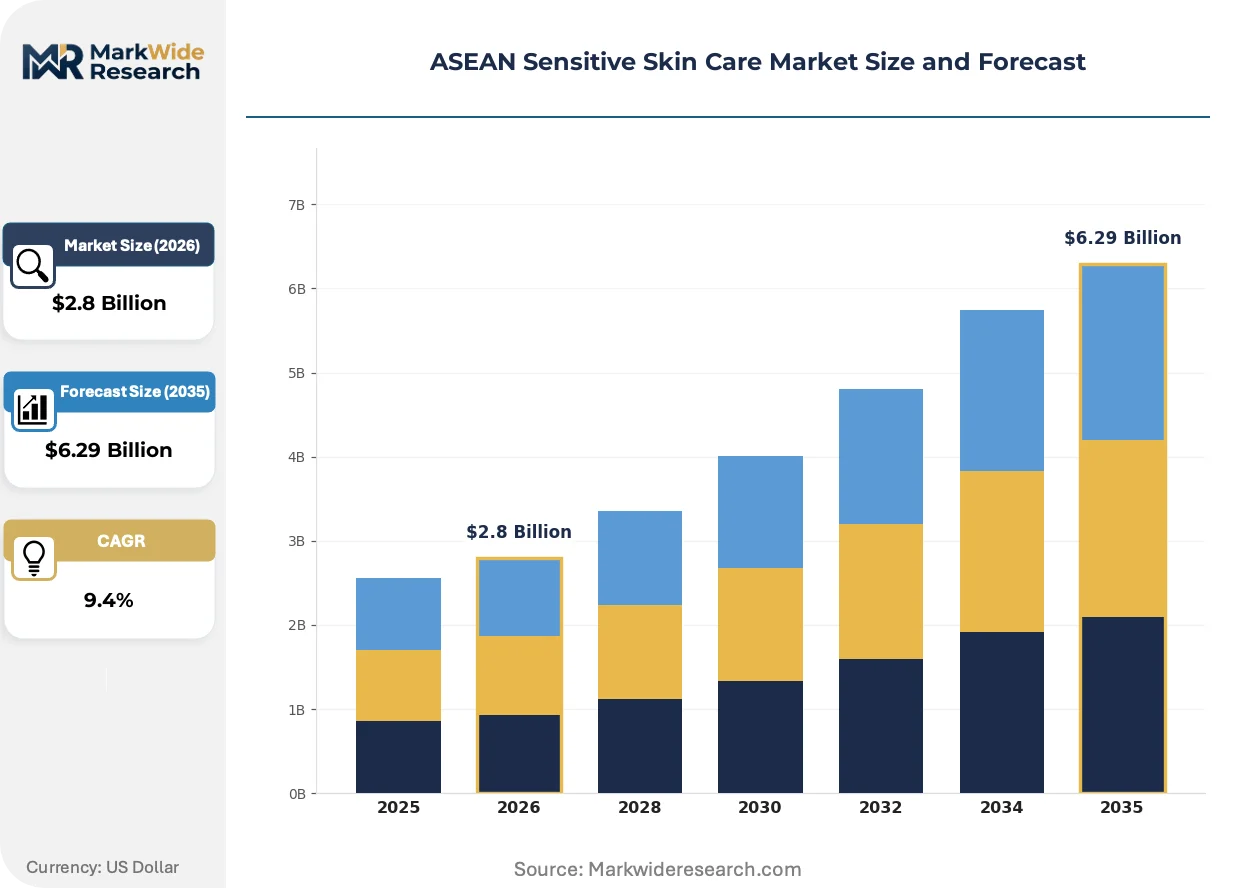
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Sunscreens, Cleansers, Serums End User: Adults, Children, Babies, Seniors Formulation: Organic, Natural, Hypoallergenic, Fragrance-Free Distribution Channel: Online Retail, Drugstores, Supermarkets, Specialty Stores |
| Companies Covered | Beiersdorf AG, GlaxoSmithKline PLC, L'Oréal SA, La Roche-Posay, Shiseido Company Limited, Unilever PLC, Galderma Laboratories LP, Kenvue Inc, Johnson & Johnson Services Inc, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Sensitive Skin Care Market Strategic Shifts
Formulation science and channel architecture are converging to reshape how sensitive-skin products reach Southeast Asian consumers, with technology adoption and regulatory alignment driving competitive separation.
Microbiome-supporting prebiotic ingredients are integrating into barrier-repair moisturizers as brands respond to dermatological research on skin flora balance. Thai and Indonesian millennial buyers are adopting these formulations faster than prior generation ceramide-only products. This ingredient shift is integrating clinical credibility into mass-market positioning, compressing the traditional prestige-mass divide.
ASEAN Cosmetics Directive harmonization is mandating standardized safety assessment documentation across member states, elevating compliance infrastructure as a competitive moat. Thailand's FDA and Indonesia's BPOM are cross-referencing dossier submissions, reducing redundant testing but raising entry barriers. Fragrance-free and preservative-free categories face the steepest documentation requirements, advantaging portfolios with pre-established regulatory depth.
Urban pharmacy chains are unbundling after-sales dermatological consultation from product purchase, replacing traditional counter-staff recommendations with certified skin advisor appointments. Bangkok metropolitan area Watsons and Guardian locations are piloting this model, with Jakarta-Surabaya chains following. Malaysian consumers in Kuala Lumpur and Penang show strongest response to appointment-based skin assessment, driving higher conversion on premium hypoallergenic lines.
ASEAN Sensitive Skin Care Market Segmentation
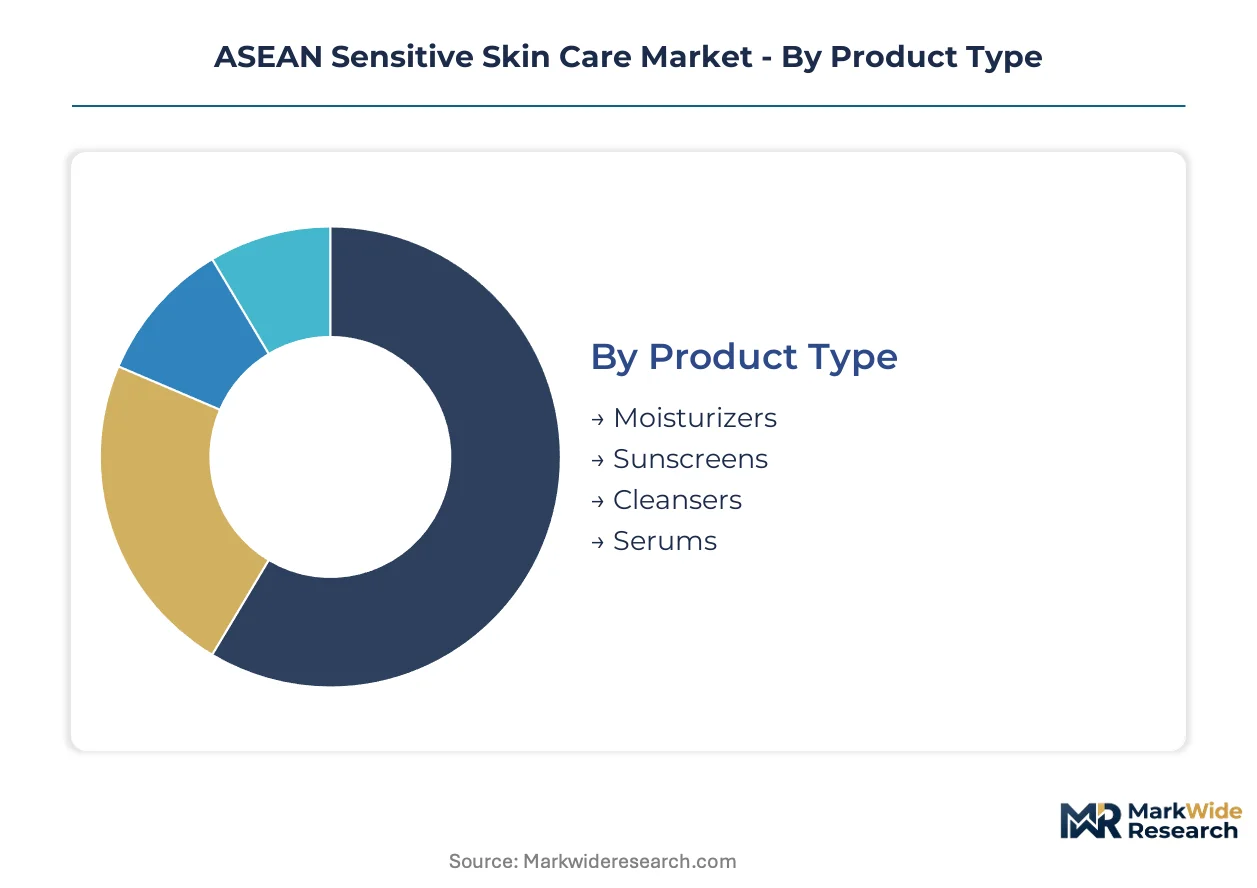
Sensitive skin care formulations in Southeast Asia require precise regulatory alignment across Indonesia's BPOM, Thailand's FDA, and Malaysia's NPRA notification pathways. Segmentation reveals where certification burdens concentrate and which product categories command premium positioning through dermatological validation.
Product Type:
Indonesia's BPOM and Thailand's FDA impose tiered documentation requirements: moisturizers and serums face extended stability testing for preservative-free claims, while sunscreens require additional SPF verification protocols.
- Moisturizers:Barrier-repair formulations enriched with ceramides and niacinamide dominate pharmacy shelf space in Jakarta and Bangkok. Urban millennials across Indonesia's primary metropolitan axis layer multiple hydration steps, driving volume concentration in 50-100ml tube and jar formats.
- Serums:Concentrated active delivery systems in single-serve ampoule formats command margin premiums through e-commerce subscription models. Ho Chi Minh City and Hanoi retail networks remain comparatively underserved against Indonesian and Thai benchmarks.
- Sunscreens:Mineral-filter formulations for reactive skin require SPF verification under Thailand's FDA cosmetic registration.
- Cleansers:pH-balanced milk and gel formats support the multi-step routines prevalent in Malaysian urban centers.
Leading the category by volume: Moisturizers. Growing fastest: Serums.
End User:
Adult segments absorb the highest per-capita spending on dermatologically tested protocols, while pediatric positioning demands clinician endorsement infrastructure that only established players maintain.
- Adults:Urban millennial women in Jakarta-Surabaya and Bangkok metropolitan corridors drive hypoallergenic facial serum adoption through pharmacy chain expansion. This segment absorbs the majority of premium fragrance-free formulation spending.
- Babies:First-time parents in Kuala Lumpur and Penang respond to pediatric dermatologist validation, opening white space beyond adult-focused positioning. Johnson & Johnson leverages clinician endorsement protocols in this segment.
- Children:School-age eczema management requires gentle cleansers and moisturizers with simplified ingredient lists.
- Seniors:Post-menopausal skin barrier degradation drives demand for lipid-replacement formulations in Thai urban centers.
Highest revenue per user: Adults. Steepest expansion trajectory: Babies.
Formulation:
Raw material sourcing costs and stability testing timelines vary sharply: organic certification requires supply chain audit depth, while hypoallergenic claims demand extended patch-test documentation.
- Hypoallergenic:Formulations engineered with reduced irritant profiles exclude methylisothiazolinone and synthetic fragrances. These products serve rosacea and eczema sufferers seeking non-reactive maintenance regimens across ASEAN pharmacy networks.
- Fragrance-Free:Premium positioning reflects costlier stabilizer sourcing and extended stability validation timelines. L'Oréal SA sustains drugstore premium placement through pre-built dermatological testing infrastructure.
- Organic:Supply chain audit requirements for ASEAN organic certification compress margins for smaller domestic brands.
- Natural:Plant-derived positioning without full organic certification occupies mid-tier pricing in Indonesian supermarkets.
Widest margin spread: Fragrance-Free. Tightest supply base: Organic.
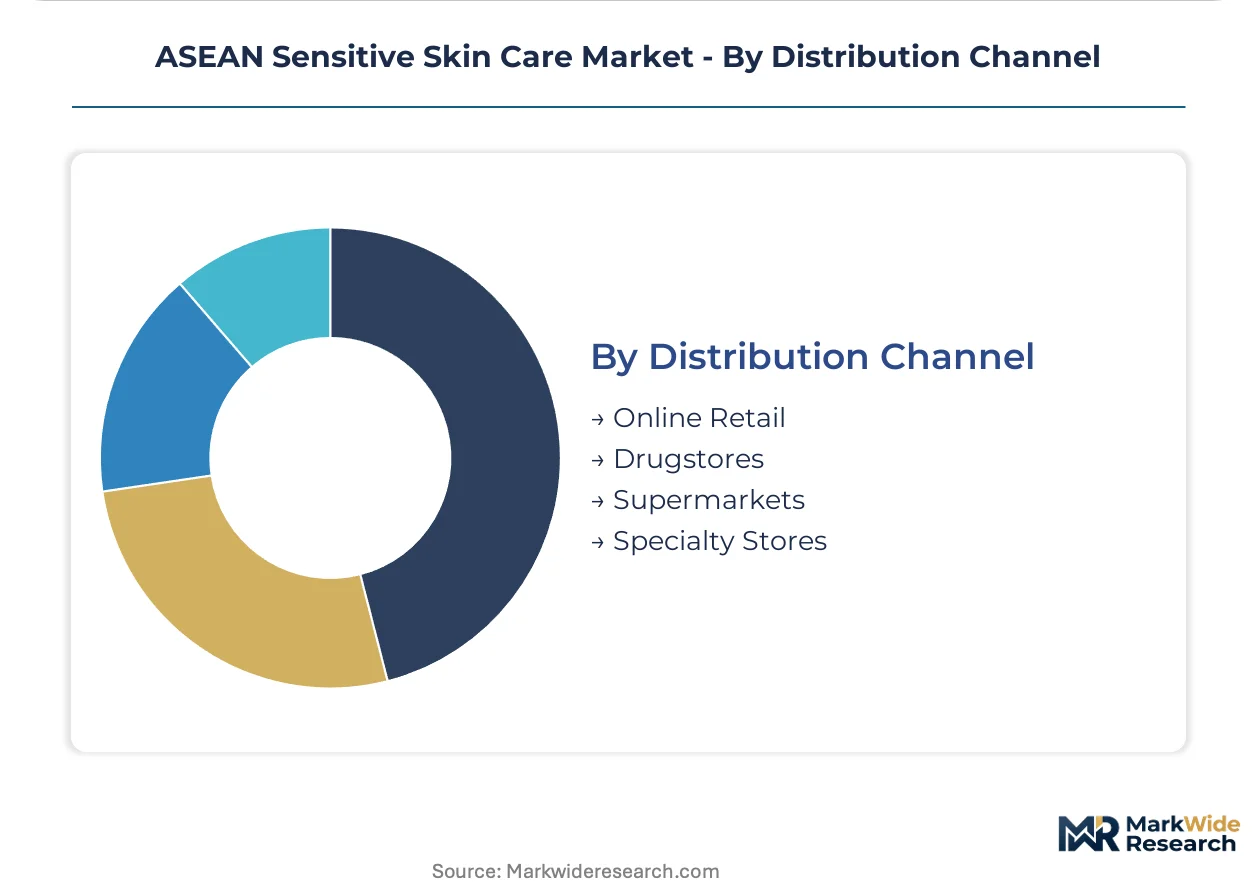
Distribution Channel:
Channel selection determines compliance friction: cross-border e-commerce faces divergent national notification requirements between Thailand, Indonesia, and Malaysia, while physical retail demands shelf-space competition against entrenched multinational portfolios.
- Specialty Stores:Dedicated sensitive-skin aisles in Bangkok Watsons and Guardian locations achieve higher conversion rates on premium hypoallergenic lines. Certified skin advisor appointments are replacing traditional counter-staff recommendations.
- Online Retail:E-commerce subscription models for single-serve ampoule bundling are expanding fastest, though unified regional digital distribution strategies remain complicated by regulatory fragmentation.
- Drugstores:Pharmacy chain expansion in Jakarta-Surabaya concentrates demand for barrier-repair moisturizers.
- Supermarkets:Beiersdorf AG anchors mass-market positioning through aggressive shelf-space competition in Indonesian hypermarkets.
Highest conversion rate: Specialty Stores. Expanding most quickly: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Jakarta-Surabaya corridor anchors regional demand concentration through pharmacy chain expansion and dedicated sensitive-skin retail infrastructure. Thailand's Bangkok metropolitan area and Vietnam's emerging urban centers follow as secondary growth poles.
Indonesia
Jakarta-Surabaya corridor millennials drive hypoallergenic facial serum adoption through pharmacy chain expansion and dedicated sensitive-skin aisles. BPOM ingredient notification requirements mandate extended stability documentation for preservative-free formulations. Surabaya retail networks concentrate demand for barrier-repair moisturizers in 50-100ml formats.
Thailand
Bangkok metropolitan area pharmacy chains pilot certified skin advisor appointments replacing traditional counter-staff recommendations. FDA cosmetic registration requirements demand SPF verification for mineral-filter sunscreens targeting reactive skin. Watsons and Guardian locations achieve higher conversion rates on premium fragrance-free lines.
Vietnam
Ho Chi Minh City and Hanoi retail networks remain comparatively underserved for dedicated sensitive-skin product lines against Indonesian benchmarks. The country's national pharmaceutical regulator cross-references dossier submissions with Thai and Indonesian counterparts under ASEAN harmonization. Pharmacy channel expansion in these urban centers creates trial-to-loyalty conversion pathways for single-serve ampoule bundling.
Malaysia
Kuala Lumpur and Penang consumers show strongest response to appointment-based skin assessment driving premium hypoallergenic conversion. JAKIM cosmetic-specific halal certification guidelines force reformulation cycles and disrupt established supply relationships. First-time parent segments in these urban centers respond to pediatric dermatologist validation protocols.
Singapore
Specialty store concentration supports highest regional conversion rates for premium hypoallergenic lines through dermatological consultation infrastructure. The city-state's national health regulator maintains stringent safety assessment standards that elevate compliance costs for new entrants. Orchard Road retail clusters concentrate demand for microbiome-supporting prebiotic formulations.
ASEAN Sensitive Skin Care Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across pharmacy, supermarket, and e-commerce channels. The market structure tilts toward multinational portfolios with dedicated regulatory affairs teams and pre-built dermatological testing infrastructure. Three archetypes dominate: European dermatological heritage brands, Japanese precision-formulation houses, and American mass-market incumbents with clinician endorsement networks. Competitive moves concentrate on shelf-space competition in Indonesian hypermarkets and single-serve ampoule bundling through e-commerce subscription models.
Within the dermatological heritage tier, L'Oréal SA and La Roche-Posay exemplify European players leveraging pre-built testing infrastructure for premium drugstore placement. Beiersdorf AG anchors mass-market positioning through aggressive Indonesian supermarket presence. Johnson & Johnson Services Inc occupies the pediatric-validation archetype, while Shiseido Company Limited represents Japanese precision-formulation expertise. These three anchors collectively illustrate how geographic origin and corporate structure shape competitive positioning across ASEAN pharmacy networks.
| Leading Market Players |
|---|
| Beiersdorf AG |
| GlaxoSmithKline PLC |
| L'Oréal SA |
| La Roche-Posay |
| Shiseido Company Limited |
| Unilever PLC |
| Galderma Laboratories LP |
| Kenvue Inc |
| Johnson & Johnson Services Inc |
| Others |
Value Chain & Pricing Dynamics
Urban millennial procurement preferences for fragrance-free, preservative-free formulations are forcing manufacturers toward pharmaceutical-grade ceramide sourcing and extended stability testing protocols, compressing margins for mid-tier players while rewarding established portfolios with pre-built dermatological testing infrastructure.
Pricing Analysis
Short lead-time premiums for preservative-free stabilizers and fragrance-free raw materials stratify pricing across premium, standard, and economy tiers, with fragrance-free formulations commanding the widest spreads due to costlier sourcing and validation timelines. Certification grade and volume scale drive differentiation, with BPOM-notified, JAKIM-halal-certified SKUs priced above uncertified equivalents. Cost compression in mid-tier segments intensifies as domestic brands struggle to absorb specialty raw material volatility. Pharmacy chains and e-commerce subscription buyers exhibit divergent sensitivity: institutional procurement negotiates volume discounts, while direct-to-consumer channels absorb premium positioning.
Supply Chain Analysis
Regional distribution centers in Singapore and Bangkok anchor hub-and-spoke patterns serving Jakarta-Surabaya, Ho Chi Minh City, and Kuala Lumpur retail networks. Pharmaceutical-grade ceramide production concentrates in Japan, South Korea, and Germany, with fragrance-free stabilizer sourcing tethered to Swiss and French specialty chemical houses. Single-source vulnerability in prebiotic microbiome ingredients exposes formulators to regulatory restriction risks from evolving ASEAN Cosmetics Directive documentation requirements. Distribution runs through pharmacy chain consolidation in Indonesia and Thailand, with cross-border e-commerce fragmenting last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN Cosmetics Directive harmonization functions as a cost-of-compliance moat, with pre-built regulatory dossier depth separating multinational incumbents from capital-constrained domestic challengers facing disproportionate BPOM and FDA notification burdens.
For Market Incumbents: Acquire regional distribution infrastructure and certified skin advisor appointment systems to lock in pharmacy chain shelf space ahead of domestic challengers. Deepen backward integration into pharmaceutical-grade ceramide sourcing to defend against specialty raw material cost volatility threatening margin structures. Anchor position through aggressive Indonesian supermarket presence and Thai drugstore network expansion. For New Entrants and Emerging Players: Microbiome-supporting prebiotic technology offers a technology-first wedge into the Vietnamese pharmacy channel, where Ho Chi Minh City and Hanoi retail networks remain comparatively underserved against Indonesian benchmarks. Target single-serve ampoule bundling through e-commerce subscription models as the most penetrable format, leveraging halal certification gaps in pediatric segments to differentiate from established clinician endorsement networks. For Investors and Strategic Acquirers: The window for entry favors portfolios with dedicated regulatory affairs teams and pre-existing dermatological testing infrastructure. Long-term viability hinges on compliance depth rather than formulation novelty, with acquisition candidates screened for BPOM dossier completeness and JAKIM halal certification progress. Monitor evolving MUI cosmetic-specific guidelines as the inflection indicator for supply chain disruption and forced reformulation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Expansion | BPOM and FDA notification depth secures shelf access ahead of fragmented domestic competition. |
| Halal Certification Acceleration | JAKIM and MUI cosmetic-specific compliance opens Malaysian and Indonesian pediatric segments. |
| Single-Serve Ampoule Launch | Mini-serum bundling creates trial-to-loyalty conversion through e-commerce subscription models. |
| Pediatric Clinician Partnership | Dermatologist validation protocols capture first-time parent spending in Kuala Lumpur and Penang. |
| Pharmacy Channel Expansion | Watsons and Guardian certified skin advisor appointments drive premium hypoallergenic conversion. |
Study Parameters
Document review covered ASEAN Cosmetics Directive implementation guidance, BPOM ingredient notification databases, and Thai FDA cosmetic registration filings, complemented by interviews with brand managers at multinational dermatological heritage houses, category buyers at Jakarta-Surabaya pharmacy chains, regulatory affairs leads at European personal care conglomerates, and supply planners at Singapore regional distribution hubs. Secondary validation drew from Nielsen retail audit data, customs import records for pharmaceutical-grade ceramides, and SEC 10-K segment disclosures. Bottom-up demand modeling and top-down market sizing triangulated volume estimates.
Historical consumption patterns were cross-referenced against panel input from procurement officers and channel sales heads to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, end user demographic, formulation certification tier, and distribution channel. CAGRs were derived from trend extrapolation adjusted for regulatory implementation timelines and channel penetration trajectories. Forecast inputs incorporated pharmacy chain expansion plans, e-commerce subscription adoption curves, and halal certification pipeline visibility.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ASEAN Cosmetics Directive enforcement or abrupt JAKIM guideline revisions. Outputs reflect documented assumptions regarding urban millennial spending persistence and pharmacy channel consolidation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Facial Massage Cream Market
Skincare
Asia Pacific Traditional Chinese Herbal Medicine for Face-Care Market
Skincare
Anti-Aging Services Market
Skincare
Global Anti-Aging Products and Services Market
Skincare
Skin Resurfacing Market
Skincare
Self-Tanning Care Market
Skincare
After Sun Care Products Market
Skincare
Sun-Care Wipes Market
Skincare
Personalized Skin Care Products Market
Skincare
Skin Care Body Products Market
Skincare
Europe Functional Cosmetics Market
Skincare
Global Skin Tears Treatment Market
Skincare
Skin Barrier Market
Skincare
Skin Care Emulsion Market
Skincare
Facial Cleansing Balm Market
Skincare
Hyaluronic Acid Personal Care Products Market