
 Biocellulose Mask Market | 2026-2036
Biocellulose Mask Market Size, Share, and Industry Trends Forecast 2026-2036
Biocellulose Mask Market Insights
South Korean fermentation-based producers is restructuring biocellulose sheet capacity to serve medical aesthetics channels. Amorepacific anchors premium positioning through dedicated dermatology distribution. L'Oréal extends its biocellulose R&D footprint across Asian formulation centers. Taiki specializes in private-label biocellulose substrate manufacturing for European skincare brands.
Biocellulose masks are ultra-fine nanofiber sheets synthesized through microbial fermentation of glucose, typically achieving fiber diameters below 20 nanometers that enable superior skin adhesion and serum retention. The material serves primarily as a high-performance delivery vehicle for active cosmeceutical ingredients in professional and at-home skincare protocols. Sheet mask formats dominate volume as consumers prioritize single-use convenience, while hydrogel variants capture margin pools in premium spa and clinic channels. Dermatologists represent the fastest-growing target segment as post-treatment protocols standardize biocellulose for barrier recovery.
FDA cosmetic labeling requirements and EU REACH compliance on fermentation-derived substrates shape product claims and import pathways for biocellulose mask suppliers. China's NMPA cosmetic registration rules and South Korea's MFDS functional cosmetic standards determine market access timelines and clinical substantiation burdens. Stakeholders must track evolving biopolymer classification debates across major regulatory regimes to anticipate reformulation mandates and certification costs.
Market Dynamics
Fermentation substrate standardization under EU Green Deal mandates is compressing supply timelines for biocellulose mask producers, forcing simultaneous retooling of glucose sourcing and clinical claim substantiation across multiple regulatory regimes.
Growth Catalysts
- EU Green Deal substrate mandates:Biodegradable fermentation feedstock requirements are accelerating substrate innovation among European suppliers and creating certification premiums for compliant producers.
- Post-procedure dermatology protocols:South Korean medical aesthetics chains now stock biocellulose masks as standard aftercare, normalizing clinical-grade home use.
- China tier-one city demand concentration:Medical aesthetics penetration in Shanghai, Beijing, and Shenzhen is pulling biocellulose mask volumes through clinic-to-retail channel bridges.
Market Restraints
- Glucose feedstock cost volatility:Agricultural commodity price swings directly compress margins for fermentation-based biocellulose substrate producers.
- South Korean production concentration:Fermentation capacity clustering around Seoul-Incheon corridor creates single-point vulnerability for global biocellulose sheet supply.
- EU REACH compliance friction:Registration requirements for novel fermentation-derived biopolymers extend import timelines and raise working capital requirements for non-European suppliers.
Strategic Opportunities
- India medical aesthetics underpenetration:Biocellulose mask adoption in Mumbai and Delhi dermatology clinics remains below 15% of South Korean penetration rates.
- SAMR cosmetic registration streamlining:China's 2024 pilot fast-track for biopolymer-based functional cosmetics reduces NMPA approval cycles by 30%.
- Biopolymer-nanocellulose hybrid R&D:Convergence of microbial fermentation with plant-derived nanocellulose is opening texture and sustainability positioning gaps.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiology expertise for high-purity biocellulose production concentrates in South Korean and Japanese research institutes.
- Clinical substantiation capex intensity:MFDS functional cosmetic claims require controlled trials costing $500K-$2M per SKU for barrier-recovery positioning.
- Multi-regulatory certification stacking:Simultaneous FDA cosmetic labeling, EU REACH, and NMPA registration creates 18-24 month market access timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biocellulose Mask Market |
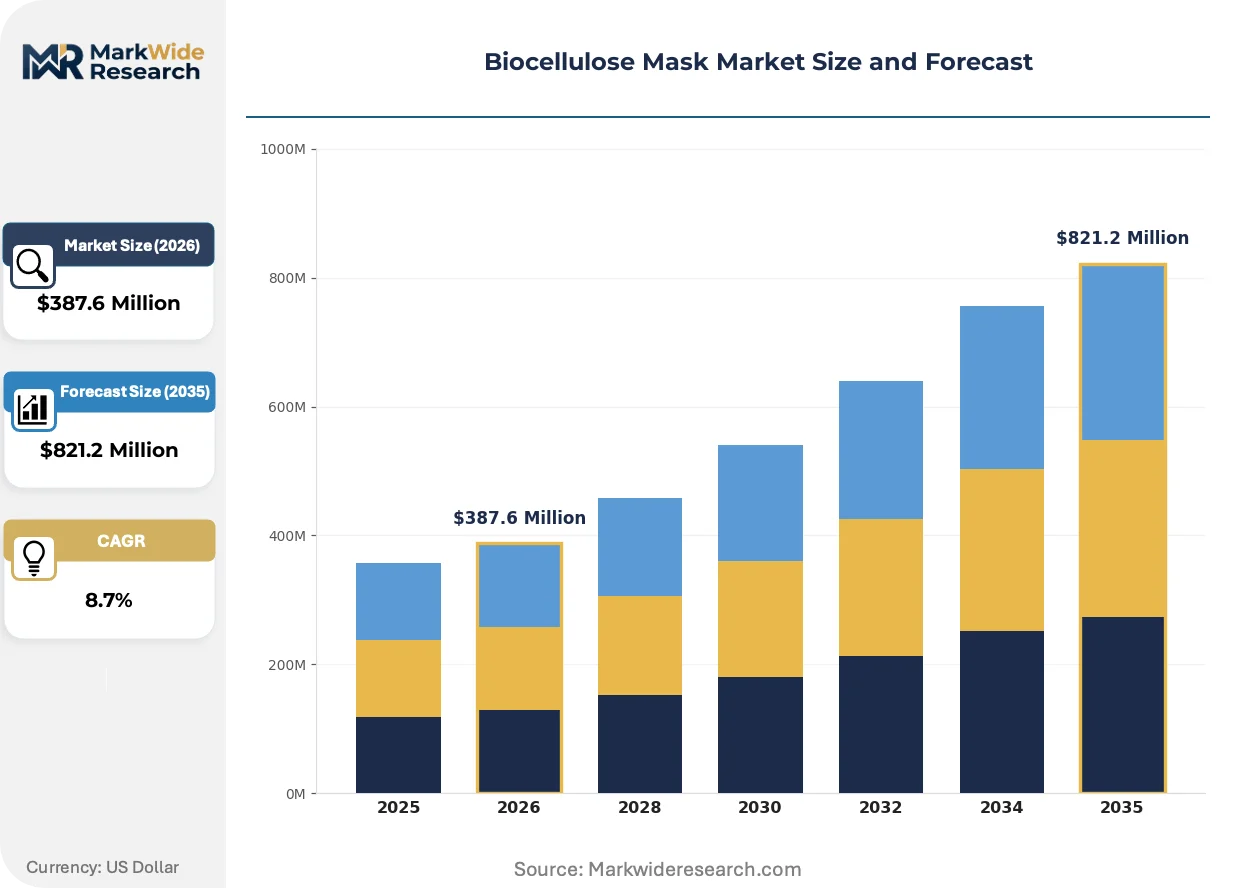
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogel, Cream Mask, Sheet Mask, Peel-Off Mask Target Segment: Skincare Enthusiasts, Spa Professionals, Retail Customers, Dermatologists Distribution Channel: Online Retail, Beauty Stores, Pharmacies, Direct Sales Application Area: Anti-Aging, Hydration, Acne Treatment, Skin Repair |
| Companies Covered | TCI Group, L'Oréal, Taiki, Jainam Invamed, ELOV Cosmetics, Procter & Gamble, Biocrown, Beihao Biochemical Technology Co. Ltd, Amorepacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biocellulose Mask Market Trends and Innovations
Continuous fermentation process automation is collapsing production cycle times while nanofiber diameter control below 15 nanometers is opening new clinical positioning claims for skin barrier repair.
Precision fermentation with metabolically optimized Komagataeibacter strains is rewriting yield economics for biocellulose substrate manufacturing. Medical aesthetics chains in Seoul and Singapore are adopting these enhanced sheets for post-laser protocol standardization. The technology is compressing the cost gap between biocellulose and conventional hydrogel masks while preserving clinical-grade performance premiums.
EU REACH Article 57 SVHC candidate list expansion for fermentation byproducts is tightening purity thresholds for biocellulose imports into European cosmetic formulation centers. German and French skincare brands now require third-party biopolymer origin certification. The regulatory pressure is most acute for private-label substrate suppliers serving mid-tier European brands without in-house compliance teams.
Clinic-direct subscription models are displacing traditional retail distribution for biocellulose mask aftercare protocols. Seoul-based dermatology chains bundle 30-day post-procedure kits directly to patients, bypassing pharmacy and e-commerce intermediaries. This channel shift concentrates volume with vertically integrated manufacturers capable of lot-traceable clinical packaging.
Biocellulose Mask Market Segmentation
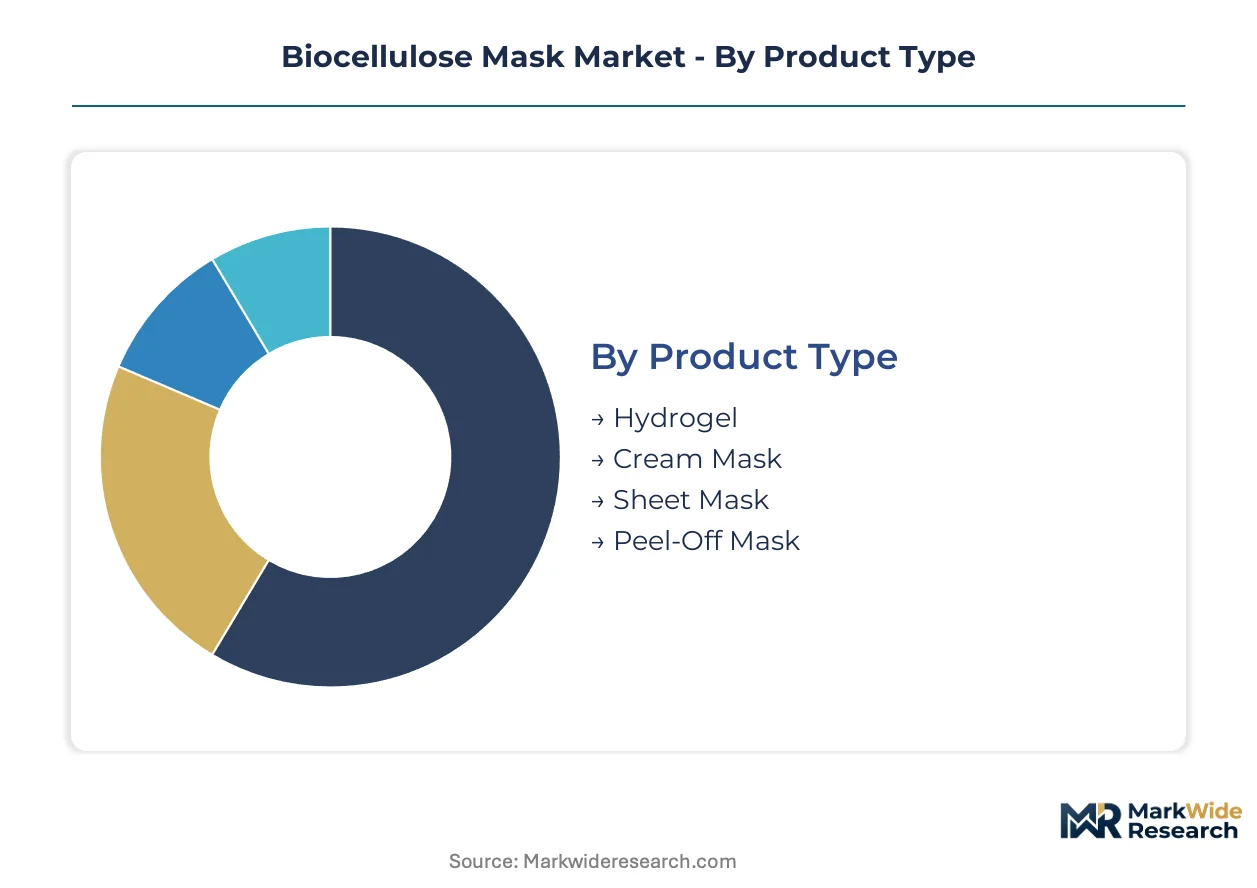
Biocellulose mask producers calibrate formulation density and fiber architecture to match distinct usage occasions and professional credential requirements. Segment boundaries blur as medical aesthetics chains push clinical-grade formats into at-home protocols.
Product Type:
Production capacity clusters around fermentation facilities capable of controlling nanofiber diameter below 20 nanometers, with substrate purity determining which channels manufacturers can access.
- Sheet Mask:Ultra-fine nanofiber sheets synthesized through Komagataeibacter fermentation achieve fiber diameters below 20 nanometers. Demand concentrates in Seoul and Shanghai medical aesthetics chains where post-laser protocols now standardize biocellulose for barrier recovery. Single-use convenience drives volume through clinic-to-retail channel bridges.
- Hydrogel:Cross-linked polymer matrices infused with biocellulose nanofibers deliver extended serum release kinetics. Premium spa and clinic channels in Singapore and Dubai capture margin pools through 60-90 minute treatment protocols. Texture differentiation supports professional service pricing premiums.
- Cream Mask:Biocellulose particulate suspensions in emulsion bases enable brush-applied protocols for esthetician-administered treatments.
- Peel-Off Mask:Fermentation-derived cellulose films with controlled peel resistance target at-home users seeking visible exfoliation cues.
Today's leader: Sheet Mask. Tomorrow's challenger: Hydrogel.
Target Segment:
Credential requirements and claim substantiation burdens segment the addressable market by professional license status and purchase authority.
- Dermatologists:Licensed physicians prescribing post-procedure recovery protocols drive fastest adoption as South Korean clinic chains bundle 30-day aftercare kits. MFDS functional cosmetic claims for barrier-recovery positioning require controlled trials, concentrating procurement with vertically integrated manufacturers capable of lot-traceable clinical packaging.
- Spa Professionals:Licensed estheticians performing non-ablative facial treatments seek texture differentiation for service menu premiums. Bangkok and Mumbai luxury hotel spas adopt biocellulose protocols to differentiate from commodity hydrogel alternatives.
- Skincare Enthusiasts:Self-directed consumers with ingredient literacy purchase through cross-border e-commerce platforms.
- Retail Customers:Mass-market purchasers respond to single-unit trial pricing and influencer endorsement.
Dermatologists command procurement authority. Spa Professionals expand accessible volume.
Distribution Channel:
Channel economics shift as clinic-direct subscriptions disintermediate traditional wholesale intermediaries and compress working capital cycles.
- Direct Sales:Clinic-direct subscription models bundle post-procedure kits to patients, bypassing pharmacy and e-commerce intermediaries. Seoul-based dermatology chains concentrate volume with manufacturers capable of clinical-grade lot traceability.
- Online Retail:Cross-border platforms serve skincare enthusiasts seeking Korean and Japanese professional brands unavailable through domestic wholesale.
- Beauty Stores:Sephora and comparable retailers stock premium biocellulose formats adjacent to professional skincare lines.
- Pharmacies:Drugstore chains in China's tier-one cities allocate shelf space to NMPA-registered functional cosmetic SKUs.
Direct Sales captures margin. Online Retail scales reach.
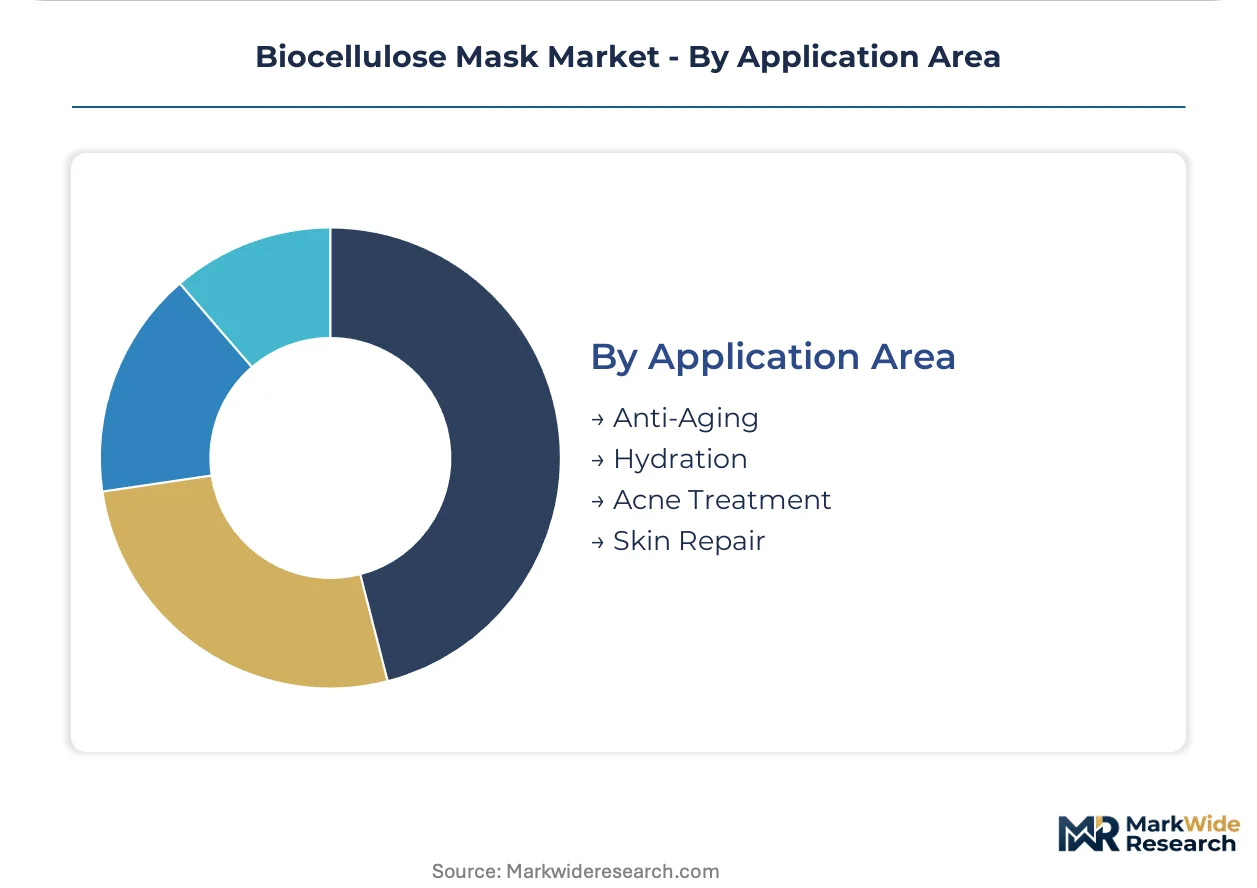
Application Area:
Clinical claim substantiation investments determine which positioning territories manufacturers can defend against functional cosmetic competitors.
- Skin Repair:Post-procedure barrier recovery protocols require MFDS and NMPA functional cosmetic registration, creating certification moats around clinical channel access. Controlled trial data for transepidermal water loss reduction supports premium pricing in dermatology settings.
- Hydration:Immediate occlusion and serum delivery effects require minimal clinical substantiation, enabling rapid SKU proliferation across price tiers.
- Anti-Aging:Collagen synthesis claims trigger stricter regulatory scrutiny in EU and Chinese markets.
- Acne Treatment:Sebum regulation positioning competes with established pharmaceutical alternatives.
Skin Repair defends premium positioning. Hydration scales volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting biocellulose substrate production toward jurisdictions with streamlined biopolymer classification frameworks. Manufacturers now site fermentation capacity where REACH-equivalent compliance costs and clinical claim substantiation timelines diverge most sharply from end-market pricing power.
South Korea
Seoul-Incheon corridor fermentation facilities supply medical aesthetics chains with post-laser protocol sheets. MFDS functional cosmetic standards mandate controlled trials for barrier-recovery claims, concentrating procurement with vertically integrated producers capable of lot-traceable clinical packaging. Gangnam district dermatology clinics now bundle 30-day biocellulose aftercare kits as standard discharge protocol.
China
Shanghai and Beijing medical aesthetics penetration pulls biocellulose volumes through clinic-to-retail channel bridges. NMPA cosmetic registration rules determine market access timelines, though SAMR's 2024 pilot fast-track for biopolymer-based functional cosmetics compresses approval cycles. Yangtze River Delta formulation centers source fermentation substrates from captive Zhejiang suppliers.
France
Paris-based luxury skincare houses drive demand for third-party biopolymer origin certification. EU REACH Article 57 SVHC candidate list expansion for fermentation byproducts tightens purity thresholds for biocellulose imports. Grasse region cosmetic formulation clusters now require German and Swiss laboratory verification of substrate biodegradability credentials.
United States
FDA cosmetic labeling requirements shape product claims for biocellulose masks entering professional dermatology channels. California and New York medical spa chains adopt Korean-imported clinical-grade formats for post-peel recovery protocols. Miami and Los Angeles aesthetics clinics concentrate early adoption of subscription-based aftercare kit distribution.
Japan
Tokyo-Osaka metropolitan esthetic salons seek texture differentiation through biocellulose hydrogel variants. METI standards for biopolymer-based cosmetics align with domestic fermentation expertise concentrated in Kansai industrial corridors. Osaka-based substrate suppliers serve both domestic spa channels and export markets across Southeast Asia.
Biocellulose Mask Market Competitive Landscape
South Korean producers anchor the clinical-grade tier; European specialists hold premium positioning through sustainability certification. The vendor base stratifies across fermentation-capability depth, with Seoul-Incheon corridor facilities commanding medical aesthetics procurement through MFDS-registered SKUs. Three archetypes dominate: vertically integrated fermentation houses with captive substrate production, private-label substrate specialists serving brand owners, and multinational beauty conglomerates with distributed R&D footprints. Capacity expansion and regulatory certification stacking represent the dominant competitive moves, as manufacturers simultaneously pursue NMPA, FDA, and REACH compliance to compress multi-regional market access timelines.
Within the fermentation-house archetype, Amorepacific and TCI Group exemplify vertically integrated positioning through dedicated dermatology distribution and precision fermentation capabilities. Taiki occupies a specialist role in private-label biocellulose substrate manufacturing, serving European skincare brands seeking outsourced compliance management. L'Oréal represents multinational R&D footprint expansion, with formulation centers across Asian markets adapting biocellulose protocols to regional regulatory requirements.
| Leading Market Players |
|---|
| TCI Group |
| L'Oréal |
| Taiki |
| Jainam Invamed |
| ELOV Cosmetics |
| Procter & Gamble |
| Biocrown |
| Beihao Biochemical Technology Co. Ltd |
| Amorepacific |
| Others |
Pricing and Supply Chain Analysis
Glucose feedstock costs cascade through biocellulose substrate manufacturing, compressing margins at fermentation houses while channel markups stratify final mask pricing across dermatology clinic, spa, and retail tiers. Agricultural commodity volatility in corn and sugarcane belts translates directly into working capital pressure for Seoul-Incheon corridor producers serving EU and Chinese medical aesthetics channels.
Pricing Analysis
Distributor margin layers separate fermentation substrate costs from end-market pricing, with clinic-direct subscription models capturing margin pools that traditional retail markups surrender to pharmacy and e-commerce intermediaries. Three-tier pricing structure across premium, standard, and economy levels reflects MFDS functional cosmetic certification grade and nanofiber diameter control precision. Pricing pressure stems from glucose feedstock cost volatility squeezing fermentation house margins. Dermatology clinic procurement shows lowest price sensitivity due to bundled aftercare kit economics, while mass retail customers respond acutely to single-unit trial pricing.
Supply Chain Analysis
Freight cost differentials between Seoul-Incheon corridor fermentation facilities and Yangtze River Delta formulation centers advantage Zhejiang-based captive substrate suppliers serving domestic Chinese medical aesthetics chains. Supply concentrates in South Korea, China, and Japan, with raw material dependencies on agricultural glucose feedstocks, pharmaceutical-grade fermentation nutrients, and clinical-grade packaging films. Single-source vulnerability clusters around Komagataeibacter strain banks and precision fermentation expertise concentrated in Korean research institutes. Distribution runs through clinic-direct subscription models displacing traditional wholesale intermediaries in Seoul and Singapore post-procedure protocol channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biocellulose mask manufacturing rewards geographic arbitrage between South Korean fermentation expertise and Chinese regulatory streamlining under SAMR's biopolymer fast-track pilot, with cost differentials in clinical claim substantiation timelines exceeding eighteen months.
For Market Incumbents: Lock in dermatology channel control through backward integration into precision fermentation capacity and exclusive 30-day aftercare kit bundling contracts with Seoul Gangnam district clinic chains. Counter emerging private-label substrate specialists from Japan by accelerating MFDS functional cosmetic SKU registration for barrier-recovery claims requiring controlled trial investments that mid-tier competitors cannot replicate. For New Entrants and Emerging Players: Medical aesthetics chains in Mumbai and Delhi represent the most penetrable white-space target, with biocellulose mask adoption running below fifteen percent of South Korean penetration rates. Enter through private-label substrate partnerships with European skincare brands seeking outsourced REACH compliance management, leveraging Taiki's specialist model as a channel template rather than direct competitor confrontation. For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation scale-up talent scarcity meets multi-regulatory certification stacking costs that compress eighteen-to-twenty-four month market access timelines. Target vertically integrated fermentation houses with captive Zhejiang or Seoul-Incheon substrate production and existing NMPA-FDA-REACH registration stacks. Watch for SAMR biopolymer fast-track expansion beyond pilot phase as inflection signal for Chinese market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Komagataeibacter strain optimization collapses production cycle times while preserving clinical-grade nanofiber architecture. |
| Multi-Regulatory Certification Stacking | Simultaneous NMPA, FDA, and REACH registration compresses market access timelines for vertically integrated producers. |
| Clinic-Direct Subscription Models | Seoul dermatology chains bundle 30-day aftercare kits, bypassing pharmacy intermediaries and capturing margin pools. |
| Biopolymer-Nanocellulose Hybrid R&D | Convergence of microbial fermentation with plant-derived nanocellulose opens texture and sustainability positioning gaps. |
| EU Green Deal Substrate Compliance | Biodegradable fermentation feedstock certification creates premium positioning for European market access. |
Research Methodology
Coverage spans South Korea, China, Japan, France, and the United States, with primary inputs from each market's medical aesthetics procurement managers, fermentation facility operations directors, dermatology clinic chain purchasing committees, and regulatory affairs specialists handling NMPA, MFDS, and REACH submissions. Secondary validation draws from SAMR cosmetic registration databases, EU ECHA REACH Article 57 SVHC candidate list updates, MFDS functional cosmetic approval records, and trade flow data tracking biocellulose substrate movements between Zhejiang formulation centers and Seoul-Incheon fermentation corridors. Bottom-up triangulation across fermentation capacity utilization rates and top-down cross-checks against medical aesthetics procedure volumes anchored market sizing.
Rate-of-change decomposition across the analysis window segmented volume and value trajectories by product type, target segment credential requirements, distribution channel economics, and application area claim substantiation intensity. Modeled dimensions included sheet versus hydrogel format splits, dermatologist versus spa professional versus retail customer procurement authority tiers, and skin repair versus hydration positioning territories. CAGRs derived from procedure volume elasticities, channel shift coefficients, and regulatory approval cycle compressions under SAMR's biopolymer pilot.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU REACH Article 57 SVHC list expansion for fermentation byproducts, glucose feedstock agricultural commodity volatility, and precision fermentation talent migration patterns from Korean research institutes. Forecasts reflect assumptions on regulatory streamlining continuity and medical aesthetics chain consolidation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Hyaluronic Acid Personal Care Products Market
Skincare
Global Anti-Aging Products and Services Market
Skincare
Dermocosmetics Market
Skincare
Facial Massage Cream Market
Skincare
Rice Water Skincare Market
Skincare
Marine Retinol Market
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Skin Barrier Market
Skincare
Peel Off Face Mask Market
Skincare
Natural Skin Care Products Market
Skincare
CBD Skincare Products Market
Skincare
Skin Replacement Market
Skincare
Personalized Skin Care Products Market
Skincare
Skin Bioactive Market
Skincare
Asia-Pacific Skincare Market
Skincare
Herbal Skincare Products Market