
 Sun-Care Wipes Market | 2026-2036
Sun-Care Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Sun-Care Wipes Market Analytics
Buyer concentration among outdoor enthusiasts and travel retailers is consolidating as seasonal purchasing shifts toward year-round portable skin protection. Johnson & Johnson leverages its dermatology heritage to sustain credibility in SPF-infused formulations. Procter & Gamble anchors mass-market distribution through pharmacy and supermarket networks across North America and Europe. Edgewell Personal Care differentiates via specialized after-sun and moisturizing variants targeting post-activity recovery scenarios.
Sun-care wipes are pre-moistened nonwoven substrates impregnated with UV filters, soothing botanical extracts, or humectants, manufactured through hydroentangled or thermal-bonded fiber processes to achieve pH-balanced skin contact and adequate wet strength for single-use application. SPF-infused wipes dominate value contribution due to higher active-ingredient loading and regulatory compliance costs, while biodegradable wipes represent the fastest-expanding structural segment as compostable fiber substrates displace conventional petrochemical-based materials. After-sun wipes occupy a mature niche with steady pharmacy channel demand but limited innovation velocity compared to multifunctional moisturizing variants.
FDA sunscreen monograph requirements and EPA regulations on active ingredient environmental fate shape formulation choices and labeling obligations for US-market products. EU REACH restrictions on chemical UV filters and the EU Green Deal's plastics reduction targets are accelerating substrate material transitions and packaging redesigns across European supply chains. Stakeholders must monitor evolving regulatory divergence between jurisdictions to determine whether to standardize formulations globally or maintain region-specific product architectures.
Market Dynamics
The EU SUP Directive's ban on single-use plastics is redirecting R&D investment toward biodegradable substrates and compostable packaging formats, forcing substrate manufacturers to rebuild supply chains around cellulose and polylactic acid alternatives.
Growth Catalysts
- Outdoor recreation participation:Hikers, campers, and beachgoers are driving portable UV protection demand as year-round activity patterns replace seasonal sun-care purchasing cycles.
- REACH chemical restrictions:EU limitations on oxybenzone and octinoxate UV filters are accelerating mineral-based SPF formulation innovation and clean-label product differentiation.
- Pharmacy channel expansion:German dermatology clinics and pharmacy chains are actively stocking SPF-infused and after-sun wipe formulations, creating professional endorsement pathways.
Market Restraints
- Biodegradable substrate cost premiums:Compostable fiber substrates command 40-60% higher input costs than petrochemical-based nonwovens, compressing margin structures for mid-tier producers.
- Active ingredient supply concentration:Zinc oxide and titanium dioxide nanoparticle production concentrates among Chinese specialty chemical suppliers, creating import dependency risks for Western formulators.
- Moisture retention technical limits:Hydroentangled cellulose structures achieve inferior wet strength and evaporation resistance compared to synthetic fiber blends, limiting shelf stability.
Strategic Opportunities
- Post-activity recovery segmentation:Multifunctional moisturizing variants combining humectants with cooling botanicals are penetrating gym and sports retail channels previously unserved by traditional sun-care.
- EU Green Deal packaging mandates:The EU's plastics reduction targets are creating first-mover advantages for brands achieving home-compostable certification before 2027 enforcement deadlines.
- Travel retail channel innovation:Airport duty-free and airline amenity kit procurement is opening premium positioning opportunities for TSA-compliant single-use formats.
Industry Challenges
- Formulation chemist talent scarcity:The intersection of cosmetic chemistry, nonwoven engineering, and regulatory compliance requires hybrid expertise that outpaces current training pipeline output.
- FDA-EPA dual compliance timelines:US-market products face asynchronous review cycles between FDA sunscreen monograph updates and EPA environmental fate assessments, delaying launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sun-Care Wipes Market |
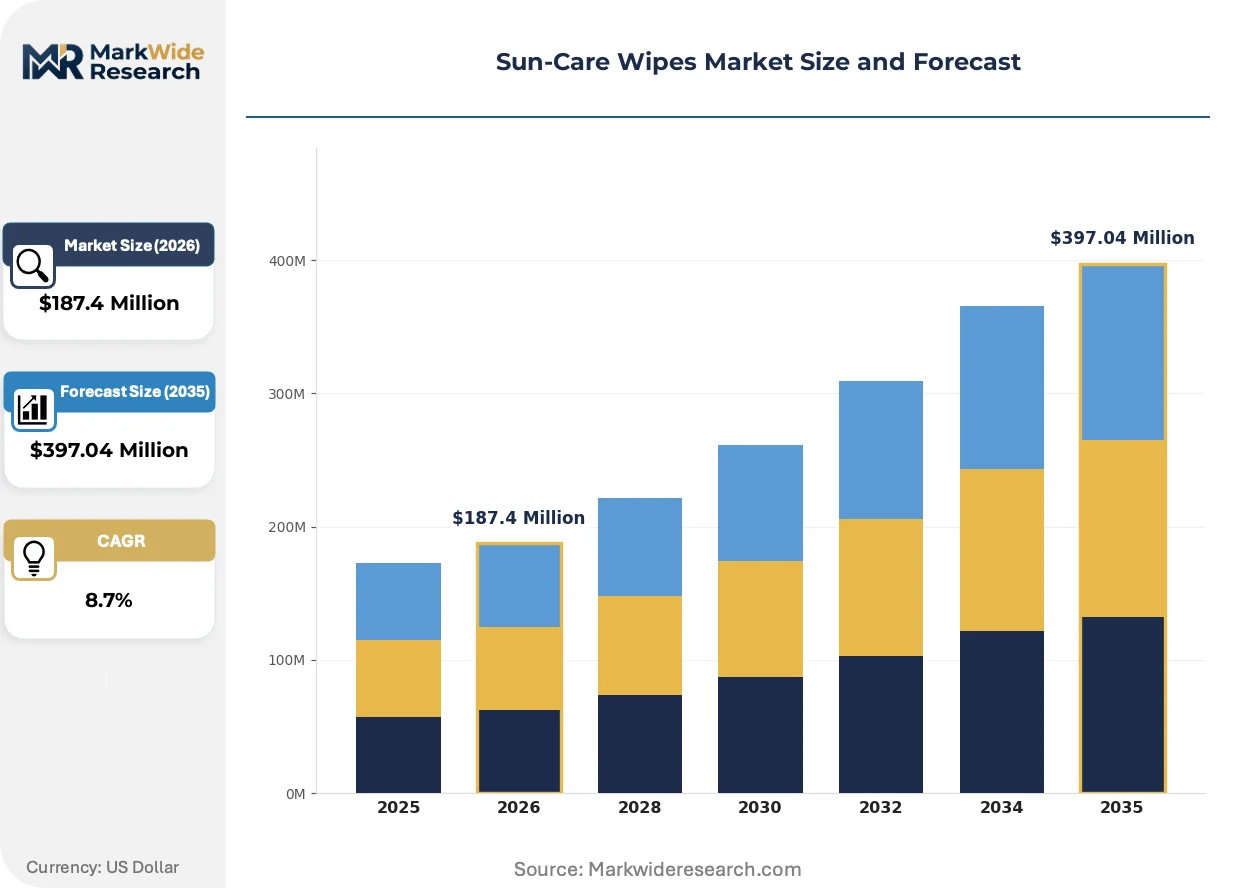
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizing Wipes, SPF-Infused Wipes, After-Sun Wipes, Biodegradable Wipes End User: Consumers, Hospitals, Spas, Outdoor Enthusiasts Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores Packaging Type: Single-Use Packs, Multi-Packs, Travel Packs, Eco-Friendly Packaging |
| Companies Covered | Johnson & Johnson, Procter & Gamble, Edgewell Personal Care, Kimberly Clark Corporation, Diamond Wipes International, Nice-Pak Products, Inc., Rockline Industries, Beiersdorf, Unicharm International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sun-Care Wipes Market Evolving Landscape
Material science breakthroughs and regulatory pressure are converging to redefine product architecture, with substrate innovation outpacing formulation advancement as the primary competitive battleground.
Hydroentangled cellulose fiber technology is consolidating market positioning as the dominant biodegradable substrate solution for wet wipe applications. Outdoor enthusiasts and travel retailers are adopting these formats at accelerating rates due to compostability claims and retail shelf placement advantages. The technology is consolidating supply chain relationships around Nordic and Brazilian pulp suppliers with certified sustainable forestry credentials.
EU REACH restrictions on chemical UV filters are forcing systematic reformulation across European supply chains. The industrial consequence is a pivot toward mineral-based SPF systems requiring specialized dispersion technologies to maintain efficacy in wipe formats. German and French formulators are most affected, responding with dedicated R&D facilities for nanoparticle stabilization.
Buyer concentration among pharmacy chains is compressing traditional distributor margins and shifting negotiation leverage toward private-label development. Direct procurement relationships between dermatology clinics and contract manufacturers are displacing wholesale intermediaries in Germany and Austria. This pattern is most visible in the DACH region, where pharmacy consolidation has created three dominant retail buyers controlling category access.
Sun-Care Wipes Market Segmentation
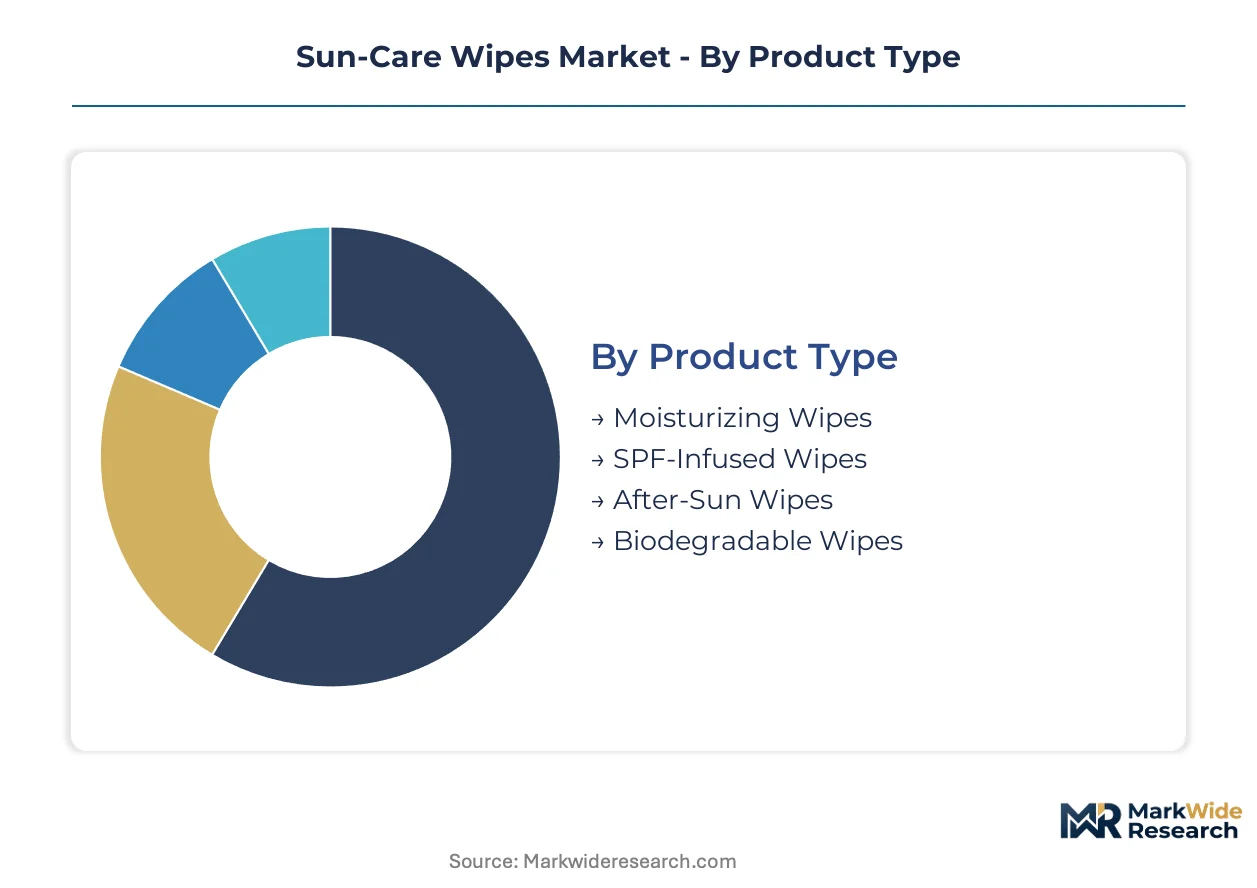
Sun-care wipe manufacturers must navigate divergent certification pathways across SPF-infused, biodegradable, and medical-grade formulations. Each product category carries distinct regulatory burdens that reshape R&D allocation and margin structures.
Product Type:
FDA sunscreen monograph compliance and EU REACH chemical restrictions impose tiered approval burdens across formulations, with mineral-based SPF systems facing the most stringent nanoparticle safety documentation.
- SPF-Infused Wipes:Nonwoven substrates impregnated with zinc oxide or titanium dioxide UV filters require FDA monograph alignment and nanoparticle dispersion stability testing. Demand concentrates among German pharmacy chains where dermatology clinics drive professional endorsement and premium positioning.
- Biodegradable Wipes:Hydroentangled cellulose or polylactic acid substrates certified for home compostability under EU Green Deal timelines. Outdoor enthusiasts in Nordic hiking corridors and Brazilian coastal regions are adopting these formats fastest as retail shelf placement advantages compound.
- Moisturizing Wipes:Humectant-rich formulations targeting post-activity skin recovery with aloe vera and glycerin blends.
- After-Sun Wipes:Soothing botanical extracts for sun-exposed skin, concentrated in mature pharmacy channels with limited innovation velocity relative to multifunctional variants.
Leading the category by volume: SPF-Infused Wipes. Growing fastest: Biodegradable Wipes.
End User:
Customer archetypes span from price-sensitive mass consumers to institutional procurement with stringent stability and documentation requirements.
- Outdoor Enthusiasts:Hikers, campers, and beachgoers purchasing year-round portable UV protection. This segment commands the steepest expansion trajectory as seasonal purchasing cycles collapse into continuous activity patterns across temperate and tropical zones.
- Consumers:Mass-market households seeking convenience-driven sun protection for family beach outings and daily commuting.
- Hospitals:Clinical settings requiring pH-balanced, hypoallergenic formulations with batch-level traceability for post-procedure skin care.
- Spas:Wellness facilities prioritizing premium botanical ingredients and aesthetic packaging for retail resale.
Volume concentration: Consumers. Fastest-climbing demand: Outdoor Enthusiasts.
Distribution Channel:
Channel economics vary sharply between direct-to-consumer digital platforms and intermediated retail with slotting fee structures.
- Pharmacies:German and Austrian dermatology clinics and pharmacy chains actively stock SPF-infused and after-sun formulations, creating professional endorsement pathways with margin premiums over mass retail.
- Online Retail:Direct-to-consumer platforms capturing subscription-based replenishment and review-driven discovery for niche biodegradable formats.
- Supermarkets:Mass-market volume concentration with compressed margins and intense private-label competition.
- Specialty Stores:Outdoor gear retailers and travel accessory boutiques targeting premium positioning for TSA-compliant travel packs.
Dominant by volume: Supermarkets. Expanding most quickly: Pharmacies.
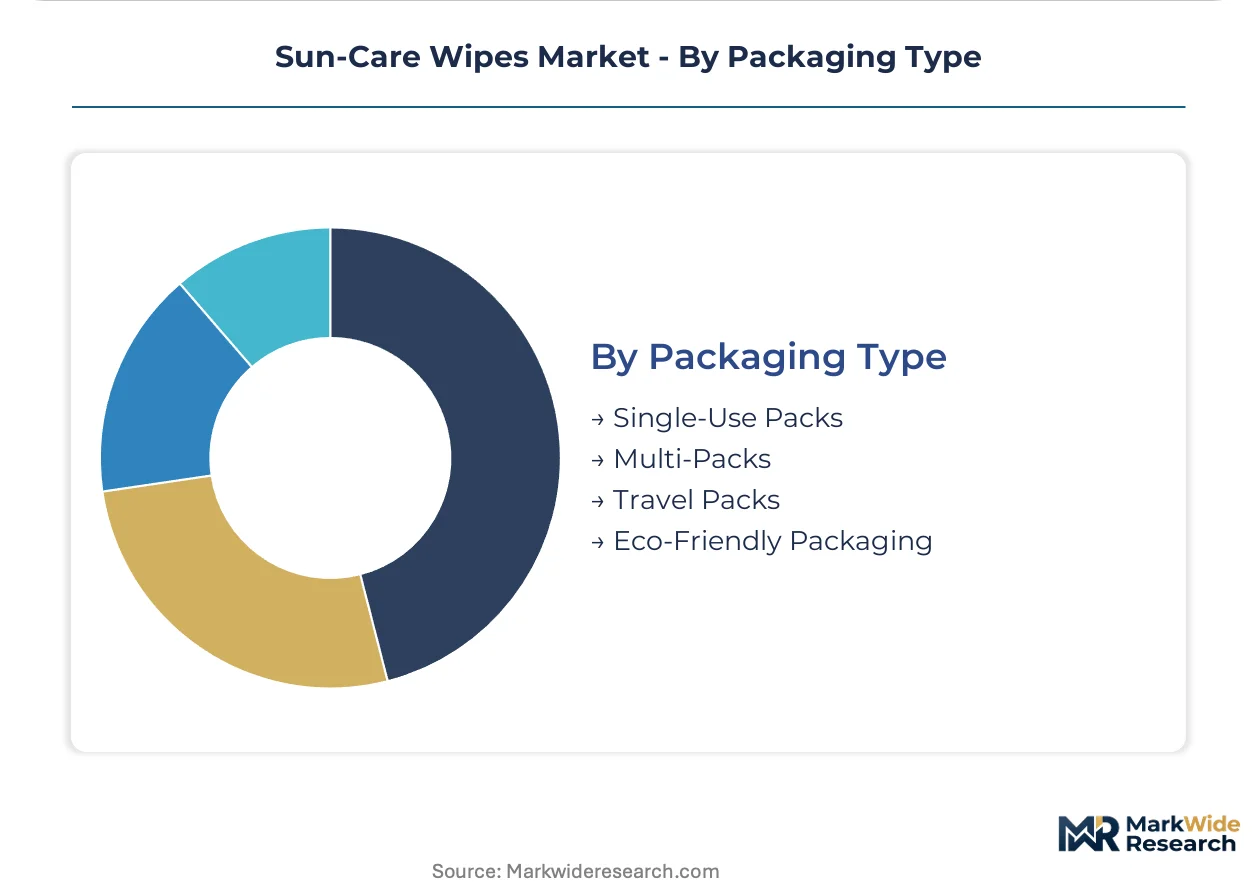
Packaging Type:
Packaging innovation centers on moisture retention engineering and compliance with evolving plastics reduction mandates.
- Eco-Friendly Packaging:Home-compostable films and cellulose-based wrappers aligned with EU SUP Directive timelines. First-mover brands achieving certification before enforcement deadlines are securing retail placement advantages in German and French markets.
- Travel Packs:TSA-compliant single-use formats targeting airline amenity kit procurement and airport duty-free channels.
- Single-Use Packs:Individual sachets optimized for gym bag and pocket portability with extended shelf stability requirements.
- Multi-Packs:Bulk formats for household stockpiling with resealable moisture barriers.
Volume leader: Multi-Packs. Gaining share fastest: Eco-Friendly Packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmacy chains and dermatology clinics concentrate demand for SPF-infused formulations, while Nordic and Brazilian pulp suppliers anchor biodegradable substrate supply chains. Outdoor recreation participation in temperate and tropical zones is collapsing seasonal purchasing into year-round portable protection demand.
Germany
DACH region pharmacy consolidation has created three dominant retail buyers controlling category access through direct procurement with contract manufacturers. EU REACH restrictions on oxybenzone and octinoxate UV filters are forcing systematic reformulation toward mineral-based SPF systems. Frankfurt and Munich host dedicated R&D facilities for nanoparticle stabilization in wipe formats.
United States
FDA sunscreen monograph requirements and EPA regulations on active ingredient environmental fate shape formulation choices for mass-market and professional channels. Asynchronous review cycles between FDA monograph updates and EPA environmental fate assessments delay launch windows. Johnson & Johnson leverages dermatology heritage to sustain credibility in SPF-infused formulations distributed through pharmacy networks.
Brazil
Coastal outdoor enthusiasts are adopting biodegradable formats fastest as retail shelf placement advantages compound. The country's national pharmaceutical regulator aligns with Mercosur standards for cosmetic product registration. São Paulo and Rio de Janeiro manufacturing clusters process cellulose from certified sustainable forestry operations in the Southeast region.
France
ANSM oversight of cosmetic safety and CNIL data protection requirements affect digital distribution platforms for direct-to-consumer brands. EU Green Deal packaging mandates are creating first-mover advantages for brands achieving home-compostable certification. Lyon and Paris formulators are pivoting toward mineral-based SPF systems requiring specialized dispersion technologies.
China
Zinc oxide and titanium dioxide nanoparticle production concentrates among specialty chemical suppliers, creating import dependency risks for Western formulators. NMPA cosmetic registration requirements and GB standards for nonwoven materials shape local manufacturing specifications. Yangtze River Delta wet wipe producers are rebuilding supply chains around cellulose alternatives to conventional petrochemical-based substrates.
Sun-Care Wipes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable certification and pharmacy channel positioning. The vendor base spans multinational consumer goods conglomerates with dermatology heritage, specialized personal care manufacturers, and contract wet wipe producers. Three archetypes dominate: mass-market anchors with supermarket and pharmacy networks, biodegradable specialists with sustainable forestry supply chains, and private-label contract manufacturers serving retail buyer consolidation. Competitive moves center on M&A for nanoparticle dispersion capabilities and strategic partnerships with Nordic pulp suppliers for compostable substrate access.
Within the mass-market anchor tier, Johnson & Johnson and Procter & Gamble exemplify dermatology-credentialed positioning through established pharmacy relationships. Edgewell Personal Care occupies a specialist position in after-sun and moisturizing variants targeting post-activity recovery scenarios. Among contract manufacturers, Diamond Wipes International and Nice-Pak Products, Inc. represent the private-label infrastructure serving consolidated retail buyers in Germany and North America.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Procter & Gamble |
| Edgewell Personal Care |
| Kimberly Clark Corporation |
| Diamond Wipes International |
| Nice-Pak Products, Inc. |
| Rockline Industries |
| Beiersdorf |
| Unicharm International |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between home-compostable biodegradable formats and conventional petrochemical-based wipes manifests in both margin capture and supply chain configuration, with EU Green Deal compliance timelines concentrating procurement leverage among Nordic pulp suppliers and German pharmacy chains while compressing mid-tier producer economics.
Pricing Analysis
Volume concentration in mass-market multi-packs generates thin margins, while SPF-infused pharmacy-tier formats sustain premium positioning through dermatology endorsement. Price differentiation rests on biodegradability certification tier and mineral-based active ingredient loading. Cost compression in biodegradable substrates is intensifying because cellulose fiber premiums run 40-60% above synthetic alternatives. Mass-market consumers exhibit highest price sensitivity; German dermatology clinics demonstrate lowest.
Supply Chain Analysis
Workforce availability constraints in Yangtze River Delta wet wipe manufacturing clusters are redirecting cellulose substrate investments toward Brazilian and Nordic pulp operations. Raw material dependencies center on zinc oxide nanoparticles, titanium dioxide dispersions, and hydroentangled cellulose fiber. Single-source vulnerability concentrates in Chinese specialty chemical suppliers for mineral UV filters. Distribution runs through pharmacy chain direct procurement and consolidated retail buyer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where EU SUP Directive compliance costs and biodegradable substrate R&D investments are forcing sub-scale producers toward exit or acquisition.
For Market Incumbents: Acquire nanoparticle dispersion technology capabilities to secure mineral-based SPF formulation stability in wipe formats. Johnson & Johnson and Procter & Gamble should deepen backward integration into certified sustainable pulp supply from Nordic suppliers to defend margin position against private-label encroachment in German pharmacy channels.
For New Entrants and Emerging Players: EU REACH restrictions on oxybenzone and octinoxate in France and Germany open a window for mineral-based SPF wipe launches with clean-label positioning. Target outdoor enthusiast segments in Nordic hiking corridors and Brazilian coastal regions through specialty retail partnerships and compostability certification as the primary go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with biodegradable specialists holding home-compostable certification and established Nordic pulp supply agreements given EU Green Deal packaging mandate enforcement timelines. Long-term viability over the next decade hinges on substrate material transition completion. Watch for inflection signals in German pharmacy chain private-label procurement shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Certification | EU SUP Directive compliance secures retail placement in German and French pharmacy chains. |
| Mineral-Based SPF Formulation Development | REACH chemical restrictions in Europe force pivot from oxybenzone and octinoxate systems. |
| Direct Pharmacy Chain Procurement | DACH region consolidation creates three dominant buyers controlling category access. |
| Sustainable Pulp Supply Integration | Nordic and Brazilian certified forestry credentials anchor compostable fiber substrate sourcing. |
| Post-Activity Recovery Line Extension | Multifunctional moisturizing variants penetrate gym and sports retail channels previously unserved. |
Research Methodology
Multi-period observation of biodegradable substrate adoption rates, pharmacy channel stocking patterns, and mineral-based SPF formulation launches anchored the trend analysis, supplemented by interviews with wet wipe manufacturing executives, cosmetic formulation chemists, dermatology clinic procurement managers, and sustainable forestry certification officers. Secondary validation drew from FDA sunscreen monograph filings, ECHA REACH restriction updates, EU Green Deal implementation timelines, and customs trade data for cellulose fiber imports. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Segment-weighting across product type, end user archetype, distribution channel, and packaging format dimensions structured the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves applied to each segment's historical trajectory and forward-looking driver elasticity. Industry-specific forecast inputs included outdoor recreation participation indices and EU SUP Directive compliance cost estimates for substrate conversion.
The model assumes a particular technology adoption path for hydroentangled cellulose fiber substrates; alternative pathways for polylactic acid or novel biopolymer materials would alter the outlook for biodegradable segment penetration. Forecasts reflect documented assumptions regarding regulatory enforcement timing and mineral UV filter dispersion stability. Material deviation in EU Green Deal packaging mandate implementation or REACH chemical restriction expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Allantoin Extract for Skincare Products Market
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Asia-Pacific Cosmeceutical Market
Skincare
Global Physician Dispensed Cosmeceuticals Market
Skincare
Facial Mist Market
Skincare
Skin Boosters Market
Skincare
Global Healthcare Wipes Market
Skincare
Germany Skincare Product Market
Skincare
Skincare Serums Market
Skincare
Cosmeceutical Ingredients Market
Skincare
Facial Massage Cream Market
Skincare
Marine Retinol Market
Skincare
Facial Cleansing Balm Market
Skincare
Medicine Skin Care Market
Skincare
Asia-Pacific Skincare Market
Skincare
Body Scrub Market