
 Skin Resurfacing Market | 2026-2036
Skin Resurfacing Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Resurfacing Market Intelligence
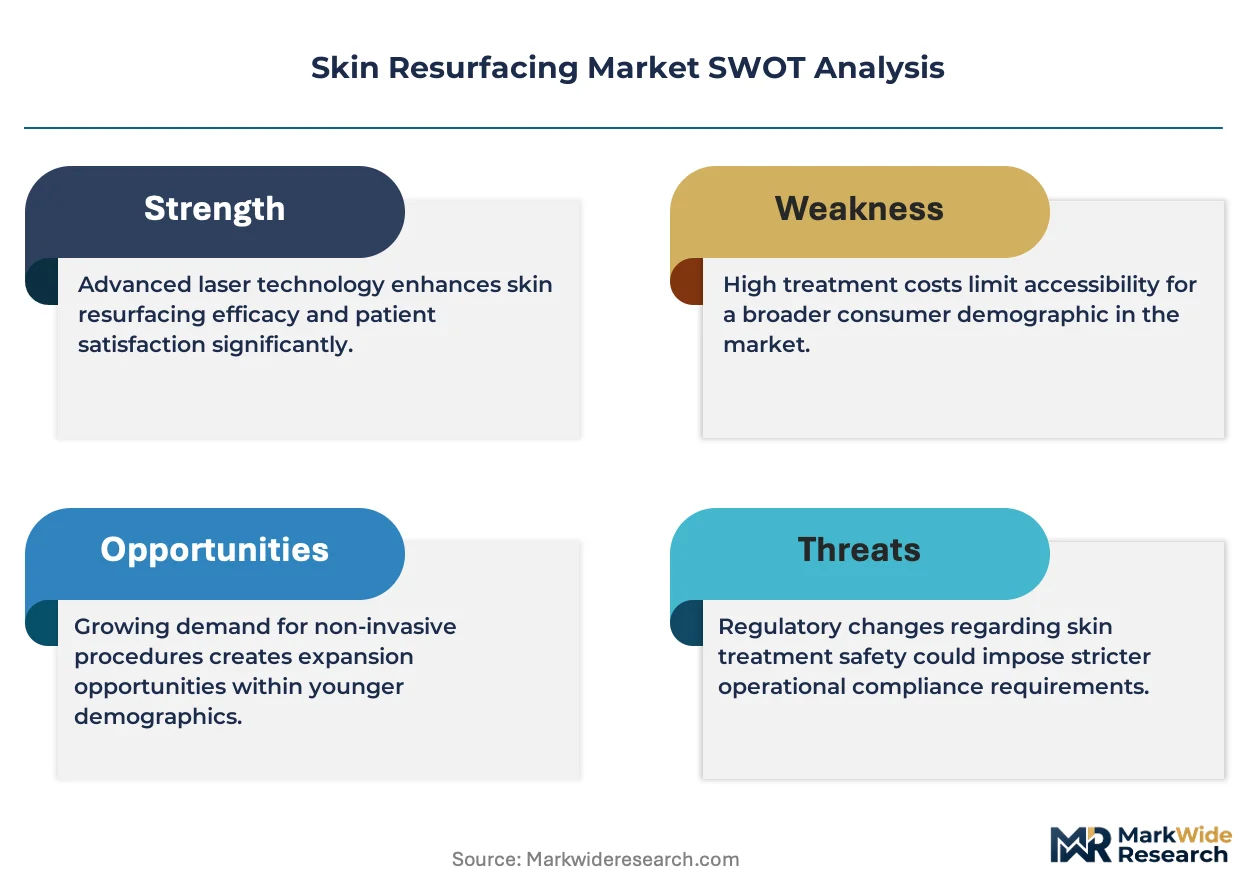
The split between premium fractional laser platforms and commodity chemical peel services is recalibrating how clinics allocate capital and price procedures. Alma Lasers leverages its multi-wavelength platform architecture to serve both hospital systems and independent medspas across multiple continents. Lutronic anchors its position through deep R&D investment in picosecond and non-ablative modalities that command higher per-session pricing.
Skin resurfacing encompasses controlled removal or remodeling of epidermal and dermal tissue through thermal, chemical, or mechanical means to improve texture, tone, and scar appearance; laser treatments utilize precise wavelength delivery measured in nanometers to vaporize tissue columns while sparing adjacent zones for accelerated healing. Laser treatments capture the dominant share of clinic capital expenditure due to higher reimbursement and patient retention rates, while chemical peels sustain volume leadership in at-home and mobile service channels where lower price points expand addressable reach. Microdermabrasion occupies a mature position with compressed margins, though demand persists among younger demographics seeking maintenance rather than corrective outcomes.
FDA 510(k) premarket notification requirements shape device commercialization timelines and clinical evidence burdens for manufacturers seeking US market entry, while the EU Medical Device Regulation imposes stricter conformity assessment procedures that favor established players with robust quality management systems. Clinicians and procurement officers must weigh total cost of ownership against upgrade pathways as wavelength versatility and cooling technology become decisive competitive variables.
Market Dynamics
The fractional laser segment is compressing recovery timelines from weeks to days, forcing dermatology clinics to reconfigure treatment protocols and capital allocation around same-day patient throughput rather than extended care cycles.
Growth Catalysts
- Non-ablative wavelength expansion:Clinics in Seoul and Dubai are adding picosecond platforms that reduce erythema duration, attracting executive patients who cannot accommodate extended downtime.
- FDA 510(k) pathway streamlining:Energy-based device manufacturers are achieving faster market entry through predicate device comparisons, accelerating platform refresh cycles for installed base upgrades.
- Medspa channel proliferation:Aesthetic chains in Miami are deploying mobile fractional units to corporate campuses, converting lunchtime appointment windows into high-margin procedure slots.
Market Restraints
- Consumable cost volatility:Handpiece tip replacement cycles for fractional CO2 systems create unpredictable per-procedure economics that squeeze margin predictability at independent clinics.
- EU MDR conformity burden:Stricter clinical evidence requirements for energy-based devices are extending European commercialization timelines by 18-24 months for manufacturers lacking established quality management systems.
- At-home chemical peel substitution:Professional-grade acid formulations available through direct-to-consumer channels are capturing maintenance-seeking patients who previously scheduled quarterly clinic visits.
Strategic Opportunities
- Combination protocol expansion:Sequential delivery of radiofrequency microneedling followed by fractional laser is commanding premium pricing in Dubai's luxury dermatology segment by addressing both laxity and texture in single sessions.
- India's tier-2 city penetration:Rising disposable income in Hyderabad and Pune is creating first-mover advantages for chains establishing branded resurfacing centers ahead of local competitor consolidation.
- Telemedicine pre-qualification:Virtual consultation platforms are reducing no-show rates and optimizing laser scheduling density by filtering candidates before capital-intensive device time allocation.
Industry Challenges
- Laser safety officer certification scarcity:Qualified clinical trainers capable of supervising multi-wavelength platforms command compensation premiums that inflate fixed costs for expanding clinic networks.
- Legacy EMR integration friction:Procedural documentation requirements for FDA adverse event reporting do not map cleanly to existing practice management software, forcing manual workflow workarounds.
- Device depreciation acceleration:Compressed upgrade cycles for cooling technology and wavelength modularity are stranding capital investments faster than historical seven-year amortization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Resurfacing Market |
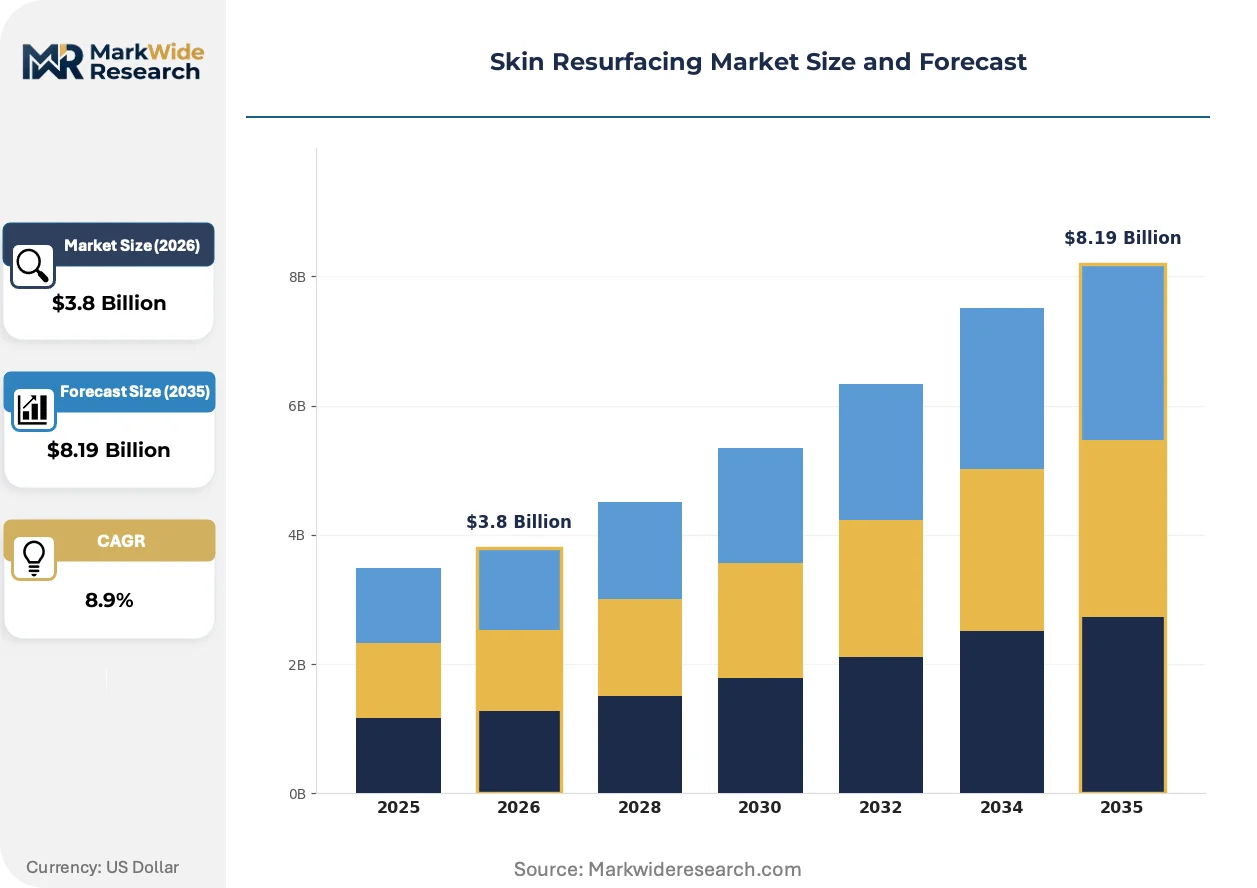
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.19 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Treatments, Chemical Peels, Microdermabrasion, Dermabrasion Delivery Mode: In-Clinic, At-Home, Mobile Services, Online Consultations Skin Type: Oily, Dry, Sensitive, Combination Age Group: Teens, Adults, Middle-Aged, Seniors |
| Companies Covered | Alma Lasers, Lutronic, Candela Medical, InMode, Cutera, Lumenis, Sciton, Fotona, Cynosure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Resurfacing Market Strategic Shifts & Innovations
Precision energy delivery is displacing one-size-fits-all resurfacing protocols, with wavelength tunability and real-time tissue feedback becoming the baseline for competitive platform design rather than premium positioning.
Picosecond pulse duration technology is rewriting treatment paradigms for melasma and post-inflammatory hyperpigmentation by confining thermal damage to sub-epidermal targets. Dermatology groups in Seoul are replacing traditional Q-switched nanosecond platforms with these systems at replacement rates exceeding historical equipment cycles. The structural consequence is a compression in per-session pricing power for legacy ablative modalities that cannot match downtime profiles.
EU MDR Article 10 clinical evaluation requirements are elevating post-market surveillance burdens for fractional laser manufacturers seeking CE marking renewal. Device sponsors must now maintain systematic literature review protocols and PMCF study commitments that smaller competitors cannot resource. Hospital procurement departments in Germany and France are prioritizing suppliers with established MDR technical documentation, consolidating vendor lists ahead of certificate expiration deadlines.
Subscription-based device access models are displacing traditional capital purchase arrangements for independent medspas. Alma Lasers and Lutronic are piloting per-procedure leasing programs in Miami and Dubai that bundle consumables, training, and software updates into predictable monthly outflows. This shift is most visible among aesthetic chains with 3-5 location footprints where balance sheet preservation outweighs long-term ownership economics.
Skin Resurfacing Market Segmentation
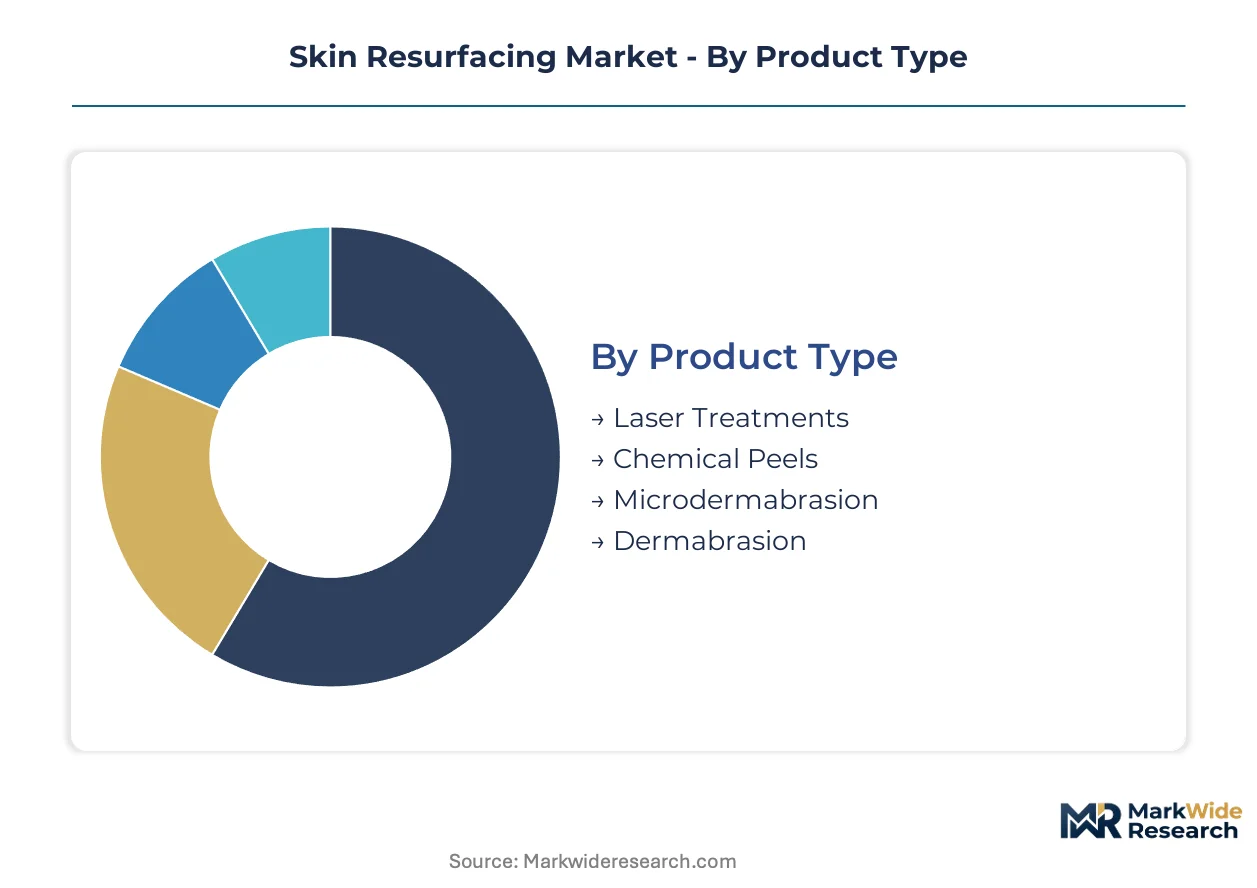
Segmentation in skin resurfacing determines capital allocation priorities across clinic networks and shapes how device manufacturers configure wavelength portfolios. Treatment modality selection directly governs reimbursement pathways, patient throughput economics, and regulatory compliance burdens.
Product Type:
Supply concentration clusters around energy-based platforms with higher technical barriers to entry, while commoditized chemical services fragment across price-competitive channels.
- Laser Treatments:Fractional CO2, erbium:YAG, and picosecond platforms deliver precise thermal injury through wavelength-specific tissue vaporization. Demand concentrates in Seoul and Miami dermatology groups seeking same-day patient turnover with minimal erythema downtime. FDA 510(k) predicate pathways accelerate platform upgrades for installed bases.
- Chemical Peels:Acid-based exfoliation using glycolic, salicylic, or trichloroacetic acid formulations removes epidermal layers through controlled keratolysis. Volume leadership persists in at-home and mobile service channels across Dubai's executive wellness programs where lower price points expand addressable reach.
- Microdermabrasion:Mechanical exfoliation via aluminum oxide crystals or diamond-tip abrasion occupies mature positioning with compressed margins.
- Dermabrasion:Surgical-grade mechanical resurfacing using rotating wire brushes targets deep acne scarring and rhytides in hospital-based dermatology departments.
Today's leader: Laser Treatments. Tomorrow's challenger: Chemical Peels.
Delivery Mode:
Channel economics diverge sharply between capital-intensive clinic infrastructure and asset-light mobile deployment.
- In-Clinic:Fixed-location delivery through dermatology practices and medspas with installed laser platforms, trained clinical staff, and regulated procedure rooms. Patient retention hinges on cooling technology sophistication and wavelength versatility across Seoul, Miami, and Dubai clusters.
- At-Home:Direct-to-consumer chemical peel kits and microdermabrasion devices bypass clinical supervision. Regulatory oversight varies by jurisdiction, with FDA cosmetic versus medical device classifications determining marketing claims and distribution channels.
- Mobile Services:Fractional laser units deployed to corporate campuses and residential addresses. Miami aesthetic chains convert lunchtime windows into procedure slots using portable cooling systems and generator power.
- Online Consultations:Telemedicine pre-qualification filters candidates before capital-intensive device allocation, reducing no-show rates and optimizing scheduling density.
Channel expansion favors Mobile Services. Margin sustainability favors In-Clinic.
Skin Type:
Phototype-responsive protocol design separates premium platform positioning from one-size-fits-all service commoditization.
- Oily:Sebum-rich epidermis responds to salicylic acid peels and non-ablative laser sequences that minimize post-inflammatory hyperpigmentation risk in higher Fitzpatrick scale populations.
- Dry:Dehydrated stratum corneum demands gentler modalities with enhanced cooling protocols to prevent barrier disruption and prolonged erythema.
- Sensitive:Reactive skin types restrict wavelength selection and mandate extended patch testing, compressing throughput for clinics serving this segment.
- Combination:Mixed T-zone and cheek presentations require customizable treatment zones, driving demand for multi-modality platforms with real-time parameter adjustment.
Protocol complexity peaks with Combination. Volume concentration sits with Oily.
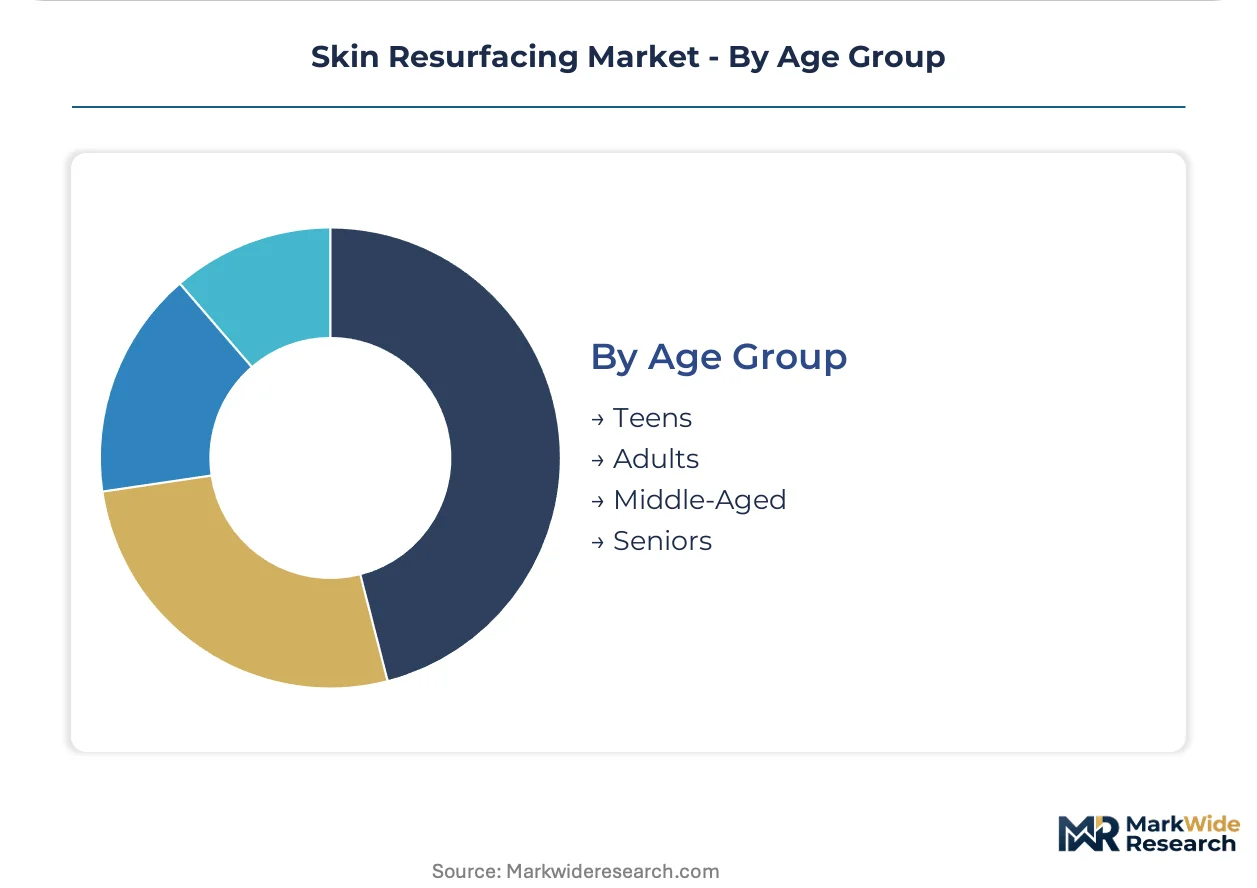
Age Group:
Demographic targeting reshapes marketing spend and procedure bundling across aesthetic chains.
- Teens:Acne scar prevention and early intervention protocols, constrained by parental consent requirements and limited disposable income.
- Adults:Preventive maintenance and early photodamage correction, driving subscription model adoption for fractional laser packages.
- Middle-Aged:Corrective procedures for established rhytides and texture irregularities command premium pricing in Dubai luxury dermatology segments.
- Seniors:Deep wrinkle and actinic damage treatment, with comorbidity screening requirements extending consultation timelines.
Revenue concentration: Middle-Aged. Fastest volume climb: Adults.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's fractional laser density in Seoul exceeds Miami's installed base per capita, yet Dubai commands higher per-session pricing for combination protocols. This divergence reflects how regional wealth concentration and regulatory pathways reshape capital deployment strategies across aesthetic markets.
United States
Miami dermatology groups drive mobile fractional laser deployment to corporate campuses, converting lunchtime windows into procedure slots. FDA 510(k) predicate pathways accelerate platform upgrades for installed bases. The Southeast Florida cluster anchors national demand for same-day patient throughput with minimal erythema protocols.
South Korea
Seoul's Gangnam district concentrates picosecond platform adoption at replacement rates exceeding historical equipment cycles. MFDS streamlined medical device approvals compress commercialization timelines for wavelength-modular systems. Dermatology chains in the capital prioritize non-ablative modalities that reduce downtime for executive patients.
United Arab Emirates
Dubai's luxury dermatology segment commands premium pricing for sequential radiofrequency microneedling and fractional laser protocols. MOHAP device registration requirements favor established manufacturers with robust quality management systems. The Jumeirah clinic cluster attracts medical tourism flows from GCC and South Asian markets.
Germany
Hospital procurement departments in Berlin and Munich prioritize suppliers with established EU MDR technical documentation. Article 10 clinical evaluation requirements elevate post-market surveillance burdens for fractional laser manufacturers. The Baden-Württemberg industrial corridor concentrates precision optics manufacturing for laser platform components.
India
Hyderabad and Pune emerge as tier-2 penetration targets for branded resurfacing center expansion ahead of local competitor consolidation. CDSCO medical device registration timelines create first-mover advantages for chains with established quality systems. Rising disposable income in Telangana and Maharashtra reshapes addressable patient demographics.
Skin Resurfacing Market Key Industry Players
Top-tier vendors anchor the premium platform segment, while mid-scale specialists occupy wavelength-specific niches. The market structure concentrates around multi-wavelength platform architects and picosecond modality innovators. Strategic archetypes include installed-base upgrade specialists, subscription leasing pioneers, and combination protocol enablers. Competitive moves center on per-procedure financing models and MDR technical documentation consolidation.
Within the multi-wavelength platform tier, Alma Lasers and Lutronic exemplify divergent R&D investment strategies. Alma Lasers represents the hospital-medspa dual-channel archetype with continental-spanning deployment. Lutronic occupies a position within the picosecond and non-ablative specialization vector. Candela Medical anchors the legacy installed-base upgrade pathway. These three entities collectively illustrate how wavelength versatility and cooling technology differentiation determine procurement officer prioritization.
| Leading Market Players |
|---|
| Alma Lasers |
| Lutronic |
| Candela Medical |
| InMode |
| Cutera |
| Lumenis |
| Sciton |
| Fotona |
| Cynosure |
| Others |
Cost & Logistics Intelligence
Qualified laser safety officers concentrated in Seoul and Miami command compensation premiums that widen the spread between premium-tier fractional platforms and economy chemical peel services. Labor-cost differentials between established dermatology clusters and emerging tier-2 markets directly stratify per-session pricing across clinic networks.
Pricing Analysis
The bundled-vs-unbundled service split separates subscription-based device access from traditional capital purchase arrangements. Three-tier pricing structure across premium, standard, and economy levels reflects cooling technology sophistication and wavelength versatility. Price differentiation hinges on FDA 510(k) clearance tier and after-sales training bundling. Cost compression in the standard tier intensifies as at-home chemical peel formulations capture maintenance-seeking patients. Independent medspas exhibit highest price sensitivity; luxury dermatology chains in Dubai show least.
Supply Chain Analysis
Regional distribution centers in Germany, South Korea, and the United States anchor hub-and-spoke patterns for precision optics and laser platform components. Manufacturing draws from Baden-Württemberg's industrial corridor for optical assemblies, Seoul's precision electronics cluster for control systems, and Miami's logistics infrastructure for Americas distribution. Supply chain risk centers on single-source vulnerability for picosecond pulse generation modules. Distribution runs through authorized dealer networks with direct hospital procurement bypass for large health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: FDA 510(k) pathway streamlining in the United States compresses commercialization timelines versus EU MDR conformity burdens that extend European entry by 18-24 months for comparable platforms.
For Market Incumbents: Lock in installed-base upgrade cycles through predicate device pathways before MDR certificate expiration deadlines consolidate vendor lists. Deepen wavelength modularity R&D to defend against picosecond platform substitution. Prioritize MDR technical documentation investment to secure hospital procurement preference in Germany and France. For New Entrants and Emerging Players: CDSCO streamlined pathways in India open a window for tier-2 city penetration ahead of local competitor consolidation in Hyderabad and Pune. Target mobile service deployment to corporate campuses where lunchtime appointment windows convert into high-margin procedure slots. Pursue per-procedure leasing programs to bypass capital-intensive balance sheet requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among wavelength-specific specialists lacking EU MDR documentation breadth. Long-term viability favors multi-platform architects with hospital-medspa dual-channel presence. Watch MDR certificate expiration deadlines as inflection indicator for vendor list consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Secures hospital procurement preference ahead of CE marking renewal deadlines in Germany. |
| Per-Procedure Leasing Program Launch | Preserves balance sheet capacity for aesthetic chains with 3-5 location footprints. |
| Picosecond Platform Upgrade | Replaces legacy Q-switched systems at replacement rates exceeding historical equipment cycles. |
| Mobile Service Channel Expansion | Converts corporate lunchtime windows into procedure slots using portable cooling systems. |
| Telemedicine Pre-Qualification Platform | Reduces no-show rates and optimizes laser scheduling density in Miami and Seoul clusters. |
Research Approach
Bottom-up clinic throughput modeling reconciled against top-down device shipment tracking forms the analytical core. Primary interviews with dermatology practice owners, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combine with secondary validation through FDA 510(k) filings, MFDS approval databases, EU MDR notified body registers, and hospital procurement contract disclosures. Triangulation between demand-side procedure volume estimates and supply-side manufacturer production data anchors forecast integrity.
Input-output matrices map wavelength platform adoption rates against patient demographic shifts and regulatory pathway timelines across the projection horizon. Segmentation dimensions encompass treatment modality, delivery mode, skin type responsiveness, and age group targeting. CAGRs derive from fitted growth curves applied to procedure volume trajectories and per-session pricing trends. Industry-specific forecast inputs include fractional laser installed base replacement cycles and chemical peel formulation regulatory reclassification risk.
Revisions become necessary when EU MDR enforcement intensity escalates, FDA predicate device pathways narrow, or at-home device efficacy claims trigger regulatory reclassification. Forecasts reflect documented assumptions regarding reimbursement stability and clinician training pipeline expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Skin Toner Market
Skincare
Vitamin C Serum Market
Skincare
Facial Massage Cream Market
Skincare
Ultrasound Skin Cleaners Market
Skincare
Fragrance-Free Skin Care Products Market
Skincare
Facial Erythema Treatment Market
Skincare
Bangladesh Skin Care Products Market
Skincare
Natural Skin Care Products Market
Skincare
Retinol Skincare Product Market
Skincare
Germany Skincare Product Market
Skincare
Body Scrub Market
Skincare
Asia Pacific Traditional Chinese Herbal Medicine for Face-Care Market
Skincare
Skin Bioactive Market
Skincare
Skin Care Emulsion Market
Skincare
Dermocosmetics Market
Skincare
Hand Care Market