
 Carbon Black for Packaging Market | 2026-2036
Carbon Black for Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Black for Packaging Market Analysis
Market Context
The carbon black for packaging market is pivoting on a widening split between premium specialty grades and commodity furnace blacks. Orion Engineered Carbons leverages its European manufacturing base to dominate high-purity grades for food-contact films. Birla Carbon sustains cost leadership across commodity volumes serving Asian flexible packaging converters.
Technical Definition and Segments
Carbon black for packaging consists of colloidal carbon particles produced through partial combustion or thermal decomposition of hydrocarbons, typically with particle sizes ranging from 10 to 100 nanometers and surface areas between 25 and 150 m²/g, engineered to provide ultraviolet protection, conductivity, and deep coloration in polymer substrates. Masterbatch carbon black leads value capture due to its pre-dispersed format that reduces downstream processing costs for film extruders. Specialty carbon black posts the fastest structural expansion as pharmaceutical blister packs and personal care tubes demand FDA-compliant low-extractable grades.
Regulatory Frame and Outlook
REACH in Europe and FDA food-contact regulations in the United States constrain permissible polycyclic aromatic hydrocarbon levels and extraction thresholds, forcing reformulation investments that favor suppliers with certified testing laboratories. BIS certification requirements in India add another compliance layer for imported carbon black entering food packaging supply chains. Stakeholders must monitor evolving state-level extended producer responsibility laws that could mandate recycled content thresholds affecting virgin carbon black loading rates.
Market Dynamics
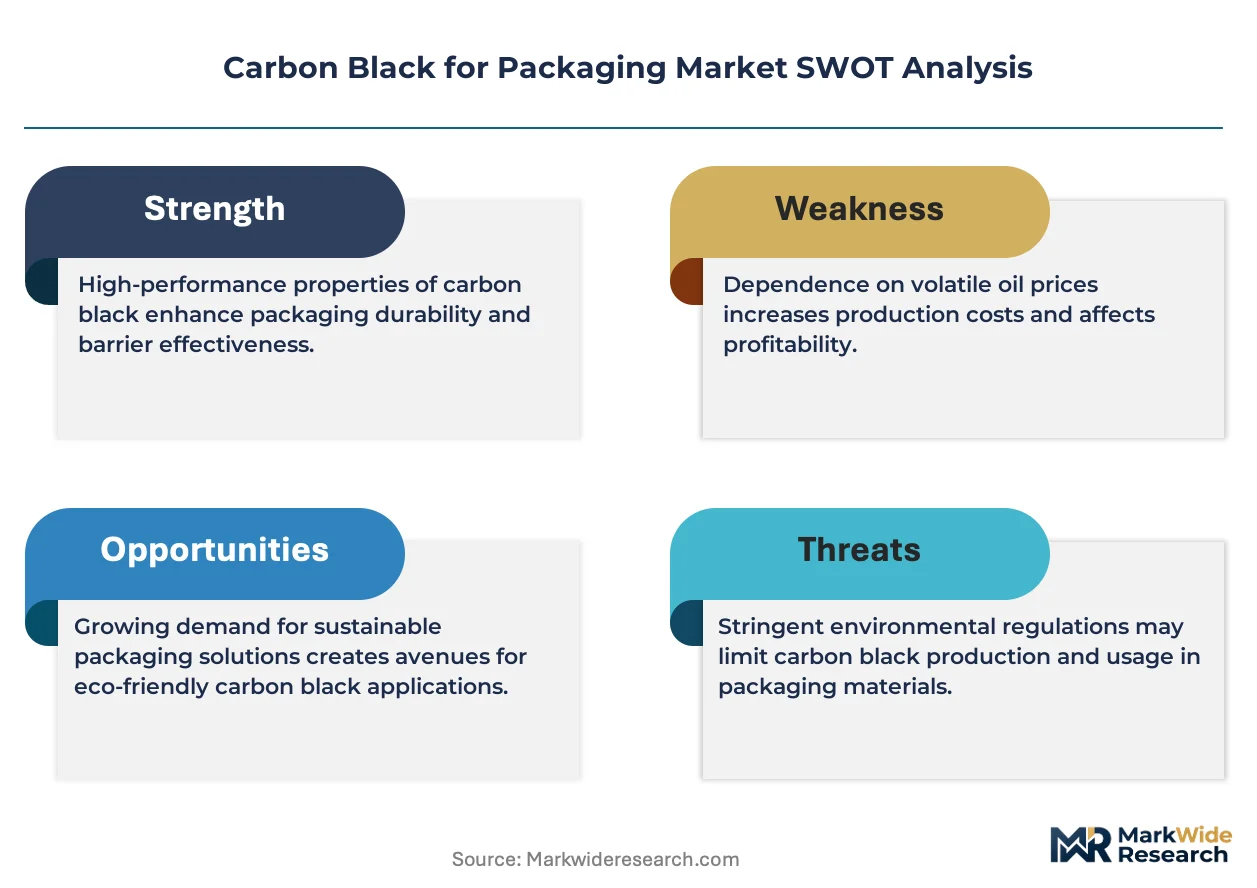
REACH compliance costs and the EU Green Deal are forcing carbon black suppliers to reformulate toward lower-PAH grades, splitting the market between certified specialty producers and commodity furnace black suppliers facing stranded asset risk.
Growth Catalysts
- Food-contact film expansion:Brand owners in Germany and France demand deeper black opacity and UV protection for premium flexible packaging, pulling high-purity masterbatch grades into meat and cheese barrier films.
- REACH Article 33 enforcement:ECHA's tightened polycyclic aromatic hydrocarbon thresholds are accelerating converter migration from uncertified imports to European-manufactured specialty carbon blacks with documented supply chain transparency.
- Blister pack pharmaceutical growth:FDA-compliant low-extractable grades are capturing volume as North American and European drug manufacturers reshore packaging production from Asia-Pacific.
Market Restraints
- Feedstock volatility:Carbon black production depends on heavy aromatic oils and coal tar distillates, exposing margins to European natural gas price spikes and Russian supply disruptions.
- Supply concentration in furnace black:Commodity-grade capacity clusters in China and India, creating geographic single-source risk for flexible packaging converters in Southeast Asia.
- Technical ceiling in thin-gauge films:Standard furnace blacks agglomerate below 20-micron thickness, limiting loading rates in downgauged polyethylene terephthalate and polypropylene structures.
Strategic Opportunities
- Indian food packaging formalization:BIS certification requirements for imported carbon black create protected market space for domestic producers investing in food-contact testing laboratories.
- Post-consumer recycled content mandates:EU Green Deal packaging regulations will require recycled polymer integration, opening demand for carbon blacks engineered to mask color inconsistency in mixed-recycle streams.
- Conductive anti-static films:Electronics packaging in South Korea and Japan is adopting acetylene black-loaded polyethylene for electrostatic discharge protection, diverting from traditional amine-based additives.
Industry Challenges
- Extractables testing capacity:FDA and EFSA migration studies require 12-18 month certification timelines, throttling new grade commercialization for pharmaceutical and infant food segments.
- Dispersion equipment retrofit costs:Masterbatch producers face capital outlays for twin-screw extruder upgrades to handle ultra-fine specialty grades without thermal degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Black for Packaging Market |
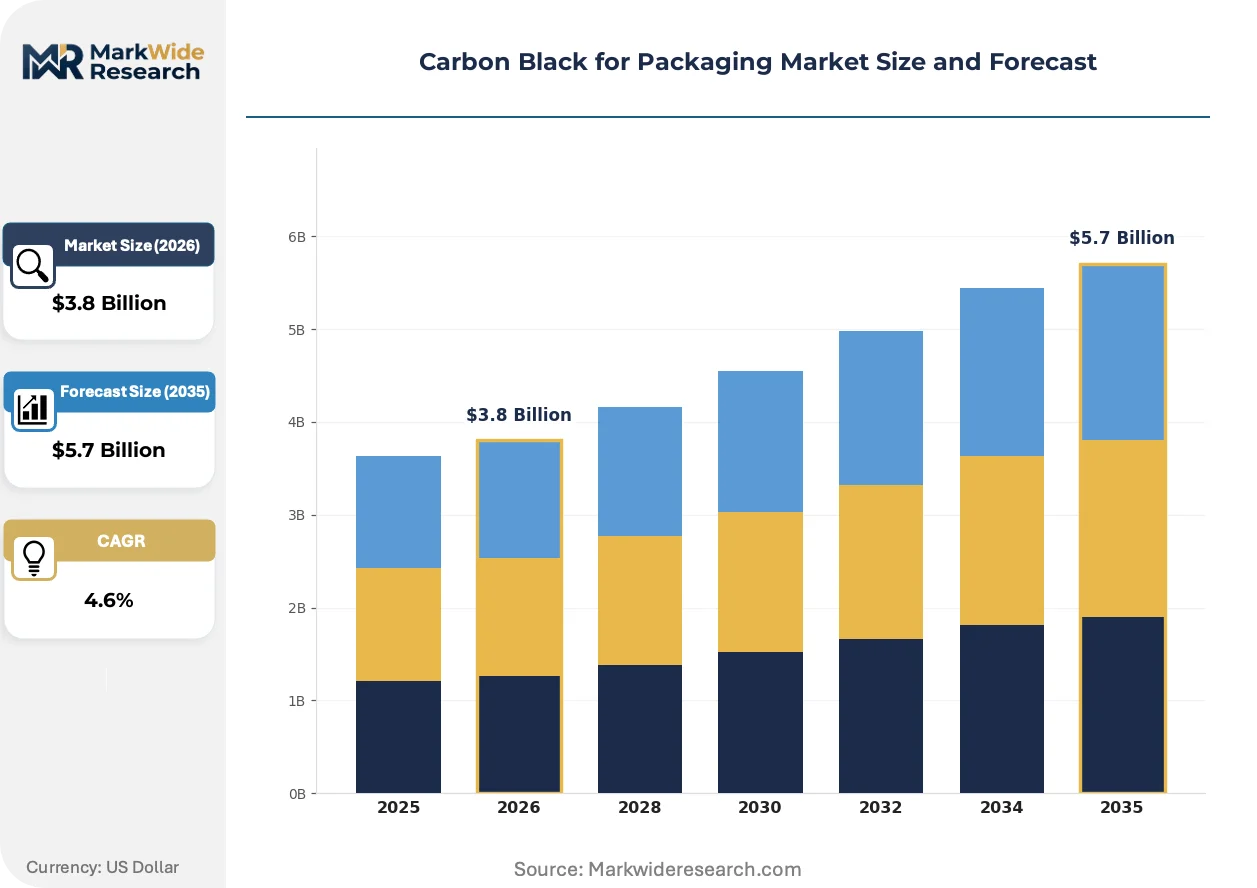
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Carbon Black, High-Performance Carbon Black, Specialty Carbon Black, Masterbatch Carbon Black Application: Flexible Packaging, Rigid Packaging, Labels, Coatings End User: Food & Beverage, Personal Care, Pharmaceuticals, Consumer Goods Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Orion Engineered Carbons, Birla Carbon, Cabot Corporation, Continental Carbon, Tokai Carbon, Phillips Carbon Black Ltd., Asahi Carbon, OCI Company Ltd., Omsk Carbon Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Black for Packaging Market Emerging Trajectories
Carbon black for packaging is bifurcating into two technical trajectories: premium grades engineered for regulatory compliance and commodity volumes competing on feedstock arbitrage. This split is compressing mid-tier supplier margins while rewarding integrated producers with captive testing capabilities.
Surface-functionalized carbon black is consolidating technical leadership in high-barrier flexible packaging. Plasma oxidation and silane coupling treatments enable covalent bonding with polar polymers like ethylene vinyl alcohol and polyamide. German and Italian converters are adopting these grades for meat packaging with extended shelf-life requirements. The technology is consolidating supplier power toward integrated producers with in-house surface chemistry R&D, marginalizing toll-compounding distributors.
REACH Annex XVII restrictions on PAH content in consumer goods are tightening enforcement across EU member states. ECHA's 2023 guidance document lowered actionable thresholds for benzo(a)pyrene and related compounds in food-contact materials. Specialty carbon black producers with certified testing laboratories in Germany and Belgium are capturing volume from commodity importers facing border rejection. The regulatory pressure is accelerating backward integration among major flexible packaging groups.
Converter procurement is fragmenting across grade-specific supply agreements rather than single-source annual contracts. Large European flexible packaging groups are splitting carbon black purchasing between a primary specialty supplier for food-contact films and secondary commodity sources for industrial overwrap. This dual-source model is visible in Germany's converter landscape, where high-barrier meat packaging demands certified grades while pallet wrap tolerates lower-specification furnace blacks. The shift is compressing volume discounts and elevating logistics coordination costs.
Carbon Black for Packaging Market Segmentation
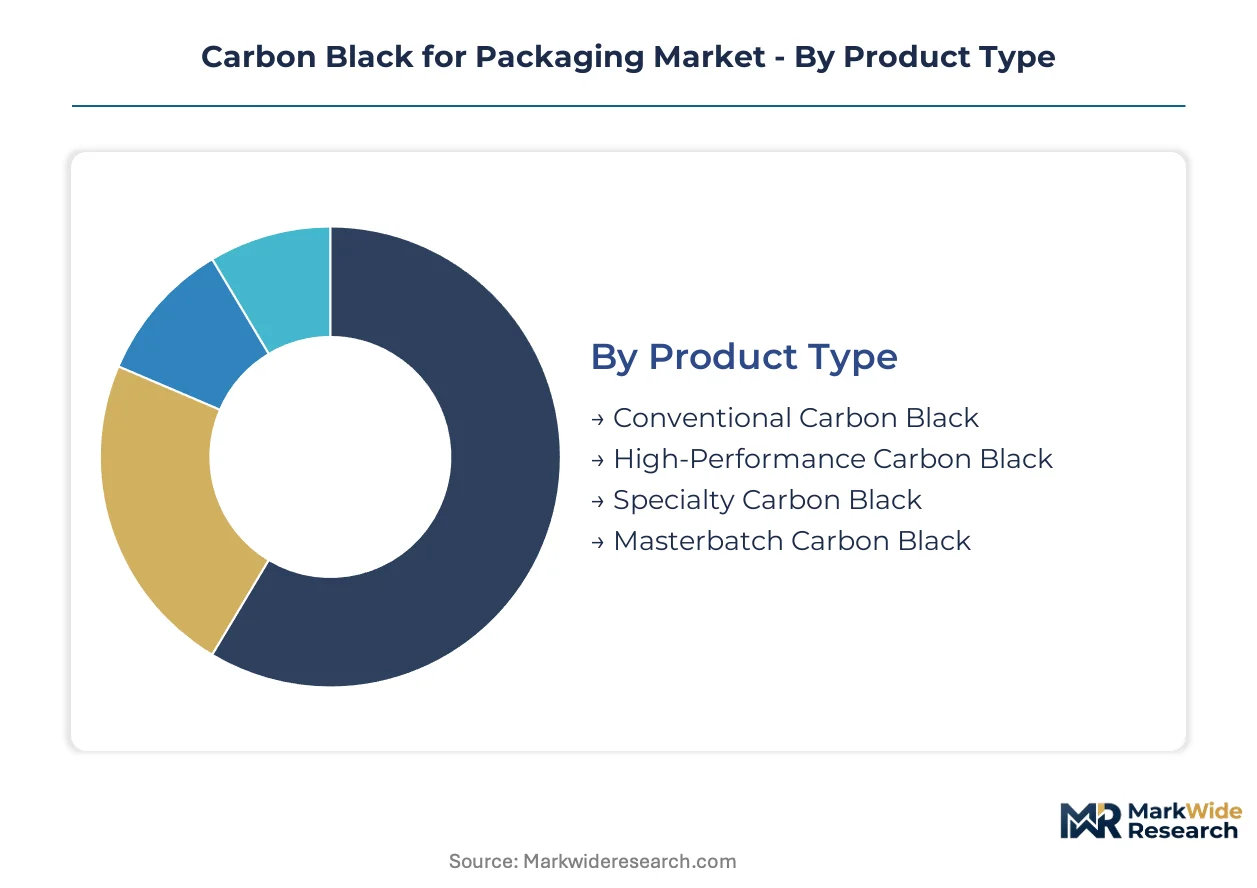
Carbon black for packaging segments by technical specification, regulatory compliance tier, and downstream processing format. Each category reflects distinct capital requirements and margin structures that reshape supplier competitive positioning.
Product Type:
Capital intensity varies sharply across production technologies, with furnace black requiring continuous reactor investment while surface-functionalized grades demand integrated R&D laboratories.
- Masterbatch Carbon Black:Pre-dispersed pellets concentrate 40-50% carbon black loadings in polymer carriers, eliminating downstream compounding steps for film extruders. German and Italian converters of meat and cheese barrier films favor masterbatch formats to reduce thermal degradation risks during thin-gauge processing.
- Specialty Carbon Black:Low-extractable grades engineered for FDA and EFSA food-contact compliance command premium positioning. Pharmaceutical blister pack reshoring in North America and Europe is pulling these grades into high-barrier applications with documented supply chain transparency.
- Conventional Carbon Black:Standard furnace blacks serve industrial overwrap and pallet stretch films where regulatory thresholds are less stringent.
- High-Performance Carbon Black:Acetylene and thermal blacks deliver conductivity for anti-static electronics packaging in South Korea and Japan.
Most installed capacity flows through Conventional Carbon Black. Expansion is steepest in Specialty Carbon Black.
Application:
Volume concentration tracks flexible packaging converter investment patterns, with rigid formats requiring different dispersion equipment and thermal management.
- Flexible Packaging:Multi-layer films for meat, cheese, and snack applications dominate carbon black consumption. REACH Article 33 enforcement is accelerating migration to certified grades in France and Germany, where brand owners demand deeper black opacity combined with UV protection.
- Rigid Packaging:Injection-molded containers and thermoformed trays for dairy and prepared foods utilize masterbatch concentrates. Downgauging trends in polyethylene terephthalate structures are testing dispersion limits of standard furnace blacks.
- Labels:Pressure-sensitive and shrink-sleeve applications require fine particle sizes for printability.
- Coatings:Barrier lacquers for metalized films incorporate carbon black for conductivity and color consistency.
Flexible Packaging holds the dominant share of current volume. Rigid Packaging is gaining share fastest as dairy brands adopt black-tinted premium positioning.
End User:
Regulatory stringency and extractables testing requirements create tiered customer profiles with divergent procurement behaviors.
- Food & Beverage:The largest demand concentration, spanning fresh meat barriers, cheese packaging, and snack films. EU Green Deal packaging regulations and extended producer responsibility laws are forcing reformulation toward lower-PAH grades with certified migration testing.
- Pharmaceuticals:Blister packs and sachets demand FDA-compliant low-extractable carbon blacks with 12-18 month certification timelines. North American and European drug manufacturers are reshoring packaging production, tightening supplier qualification requirements.
- Personal Care:Tubes and jars for cosmetics require color consistency and regulatory documentation.
- Consumer Goods:Industrial overwrap and non-food applications tolerate commodity-grade specifications.
Food & Beverage channels the majority of volume. Pharmaceuticals posts the steepest expansion trajectory as reshoring accelerates.
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and geographic proximity to compounding infrastructure.
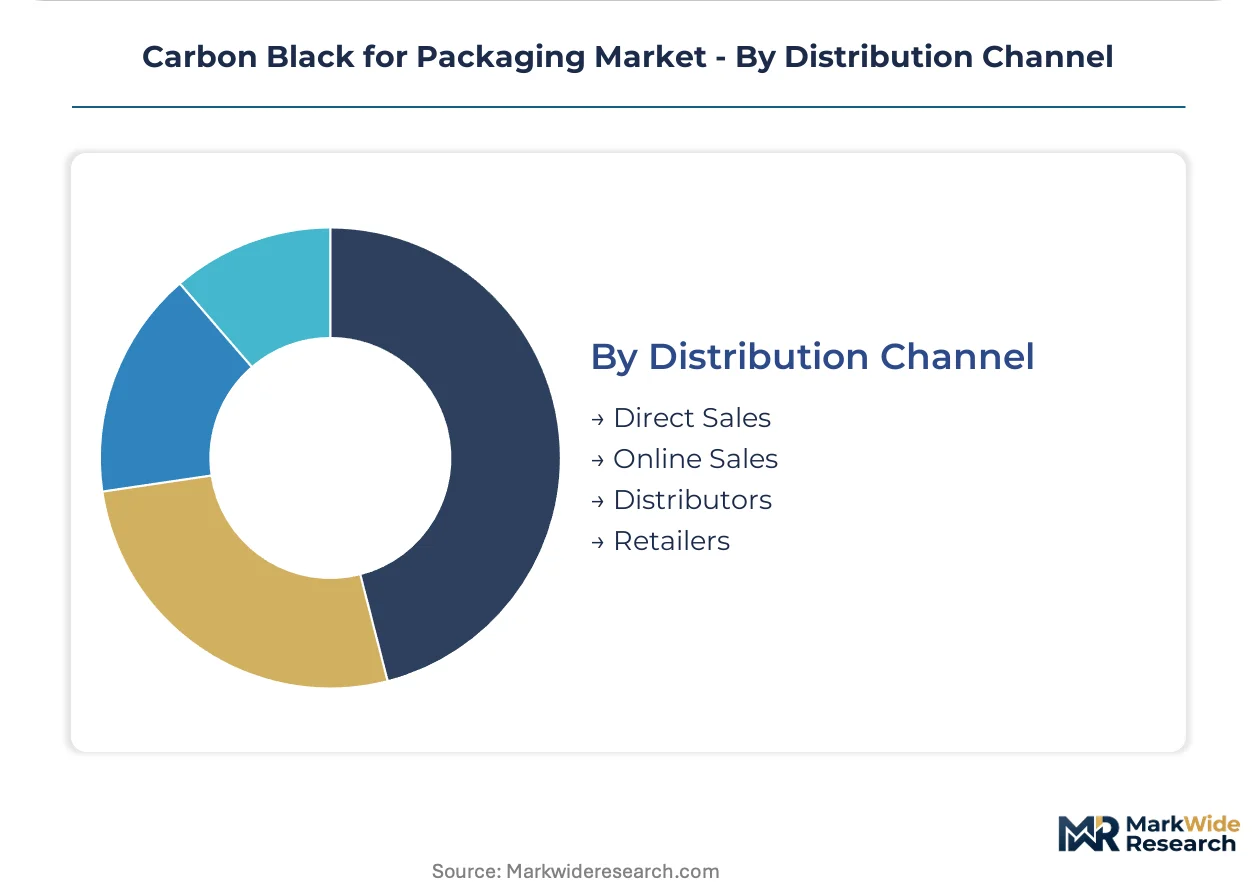
- Distributors:Regional stocking points dominate procurement for mid-sized European flexible packaging converters seeking technical support and just-in-time delivery. German distributors are consolidating specialty grade portfolios as REACH compliance documentation becomes a competitive differentiator.
- Direct Sales:Large-volume converters and multinational packaging groups negotiate grade-specific supply agreements directly with manufacturers. Dual-source models are emerging, splitting food-contact films and industrial applications between separate suppliers.
- Online Sales:Digital platforms serve small-batch and specialty grade sampling for R&D laboratories.
- Retailers:Limited to aftermarket and maintenance-repair-operations segments.
Distributors handle the largest share of transaction volume. Direct Sales is climbing the fastest as major converters consolidate procurement under strategic supply agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and regulatory compliance officers cluster in Germany's Rhine-Ruhr corridor, anchoring European carbon black formulation expertise. Japanese process engineers dominate acetylene black production for electronics packaging. Indian quality control specialists concentrate in Gujarat's chemical belt around food-contact certification.
Germany
High-barrier meat and cheese flexible packaging converters in Baden-Württemberg and North Rhine-Westphalia demand REACH-certified low-PAH masterbatch grades. ECHA's 2023 guidance tightening benzo(a)pyrene thresholds accelerates migration from uncertified imports. The Rhine-Ruhr industrial corridor hosts compounding facilities serving premium food-contact film producers.
United States
Pharmaceutical blister pack reshoring pulls FDA-compliant low-extractable carbon blacks into New Jersey and North Carolina manufacturing zones. FDA migration study requirements enforce 12-18 month certification timelines that throttle new grade commercialization. The Mid-Atlantic pharmaceutical packaging cluster tightens supplier qualification protocols.
China
Commodity furnace black capacity concentrates around Bohai Rim and Yangtze River Delta flexible packaging converter zones. The country's national standards regulator enforces GB food-contact material safety specifications for imported carbon black. Shandong Province hosts integrated production facilities serving domestic masterbatch compounders.
India
BIS certification requirements for imported carbon black create protected market space for domestic producers investing in food-contact testing laboratories. Gujarat's chemical belt concentrates quality control specialists around polymer compounding infrastructure. Maharashtra's flexible packaging converters demand documented supply chain transparency for snack and dairy applications.
South Korea
Electronics packaging manufacturers in Gyeonggi Province adopt acetylene black-loaded polyethylene for electrostatic discharge protection. The national industrial technology regulator supports conductive film development through standards alignment with IEC specifications. The Seoul Capital Area anchors anti-static film converter investment diverting from amine-based additives.
Carbon Black for Packaging Market Vendor Landscape
Top-tier vendors anchor premium specialty grades, while commodity furnace black suppliers compete on feedstock arbitrage. The market structure splits between integrated producers with captive testing laboratories and toll-compounding distributors facing margin compression. Three archetypes dominate: European-based regulatory compliance specialists, Asian-scale commodity producers, and regional masterbatch compounders. Competitive moves center on backward integration into carbon black manufacturing and geographic expansion through distributor network consolidation.
Within the integrated specialty tier, Orion Engineered Carbons and Birla Carbon occupy positions exemplifying divergent strategic approaches. Orion Engineered Carbons represents the European regulatory compliance archetype with manufacturing proximity to REACH enforcement zones. Birla Carbon exemplifies scale-driven commodity leadership with cost positioning across Asian flexible packaging markets. Cabot Corporation anchors the North American pharmaceutical-grade segment with FDA-certified production infrastructure.
| Leading Market Players |
|---|
| Orion Engineered Carbons |
| Birla Carbon |
| Cabot Corporation |
| Continental Carbon |
| Tokai Carbon |
| Phillips Carbon Black Ltd. |
| Asahi Carbon |
| OCI Company Ltd. |
| Omsk Carbon Group |
| Others |
Supply Flow & Price Mechanics
Surface-functionalized carbon black production is displacing standard furnace black capacity in European compounding facilities, simultaneously elevating unit economics for REACH-certified grades and concentrating supply power among integrated producers with captive R&D laboratories. This technical transition compresses margins for toll-compounding distributors while rewarding manufacturers with in-house plasma oxidation capabilities.
Pricing Analysis
Bundled certification-and-testing services separate premium specialty grades from commodity furnace blacks sold on per-kilogram spot terms. Three-tier pricing structure across premium, standard, and economy levels reflects PAH compliance tier, extractables documentation depth, and masterbatch dispersion quality. Cost compression in commodity furnace black is intensifying because Chinese capacity expansion outpaces Southeast Asian converter demand growth. Industrial overwrap buyers exhibit highest price sensitivity; pharmaceutical blister pack manufacturers show lowest sensitivity due to FDA-mandated qualification costs.
Supply Chain Analysis
Dual-sourcing requirements now dominate procurement protocols at major European flexible packaging groups, mandating separate qualification of specialty and commodity suppliers to mitigate border rejection risks. Manufacturing concentrates in Germany, China, and India, with heavy aromatic oils and coal tar distillates feeding reactor operations. Single-source vulnerability runs through Russian feedstock disruptions and European natural gas price spikes. Distribution runs through regional masterbatch compounders stocking pre-dispersed pellets for just-in-time film extruder delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Germany and France create protected pricing umbrellas for domestic producers against lower-PAH-uncertified Asian imports.
For Market Incumbents: Deploy certification laboratory expansion to defend against commodity importers facing ECHA border rejection. Backward integration into surface-functionalized carbon black production protects margin position as plasma oxidation technology consolidates supplier power. Channel control through exclusive masterbatch distribution agreements in Baden-Württemberg converter clusters limits toll-compounder encroachment.
For New Entrants and Emerging Players: Enter via BIS-certified domestic production in Gujarat's chemical belt, where import documentation requirements create protected market space for food-contact testing investments. Indian snack and dairy packaging formalization represents the most penetrable geography. Go-to-market angle centers on documented supply chain transparency for Maharashtra converters seeking just-in-time masterbatch delivery.
For Investors and Strategic Acquirers: Roll-up economics work for regional masterbatch compounders with captive testing capabilities because converter procurement fragmentation elevates logistics coordination costs above standalone profitability thresholds. Long-term viability favors integrated producers with FDA and EFSA migration study infrastructure. Watch ECHA enforcement intensity across EU member states as inflection indicator for specialty grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Black Manufacturing | Captive supply of REACH-certified grades secures margin against import price volatility. |
| Food-Contact Testing Laboratory Investment | BIS and FDA compliance documentation opens protected procurement channels in India and North America. |
| Surface Functionalization R&D Partnership | Plasma oxidation capabilities enable covalent bonding with EVOH and polyamide barrier films. |
| Dual-Source Supply Agreement Structuring | Split procurement between specialty and commodity grades reduces qualification risk for converters. |
| Post-Consumer Recycled Content Grade Development | EU Green Deal mandates create demand for carbon blacks masking mixed-recycle color inconsistency. |
Methodological Framework
Coverage spans Germany, United States, China, India, and South Korea, with primary inputs from each region combining interviews with carbon black plant managers, flexible packaging procurement leads, pharmaceutical regulatory affairs directors, masterbatch compounder technical R&D heads, and food-contact testing laboratory quality control specialists. Secondary validation draws from ECHA guidance documents, FDA food-contact substance notifications, BIS certification registries, customs and trade flow data, and SEC filings of listed chemical producers. Bottom-up volume modeling triangulates against top-down value estimates across grade tiers.
Rate-of-change decomposition separates volume growth from price mix effects across the analysis window, with segmentation dimensions including product type (masterbatch, specialty, conventional, high-performance), application format (flexible, rigid, labels, coatings), end-user industry (food and beverage, pharmaceuticals, personal care, consumer goods), and distribution channel (distributors, direct sales, online, retail). CAGRs derive from regression analysis of historical consumption patterns against converter capacity expansion and regulatory enforcement timelines. Industry-specific forecast inputs include REACH Annex XVII PAH threshold evolution and pharmaceutical packaging reshoring announcements.
Inputs from ECHA enforcement databases and FDA migration study registries were available through the study window; gaps in real-time converter inventory positioning introduce uncertainty bands around quarterly demand estimates. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and feedstock price trajectories. Deviation in EU Green Deal implementation pace or Russian natural gas supply restoration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Specialty Monomer Market
Specialty Compounds
Global Sulfur Hexafluoride Market
Specialty Compounds
Global Compound Management Market
Specialty Compounds
United States Caustic Potash Market
Specialty Compounds
Strontium Nitrate Market
Specialty Compounds
High Performance Foam Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
North America Lithium Compound Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
Germany Collagen Market
Specialty Compounds
Triallyl Isocyanurate Market
Specialty Compounds
Middle East and Africa Specialty Chemicals Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Low Density Sheet Moulding Compound (SMC) Market
Specialty Compounds
Global Antifreeze Proteins Market
Specialty Compounds
Argan Oil Market