
 Global Customized Premixes Market | 2026-2036
Global Customized Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Customized Premixes Market Foresight
China is tilting toward large-scale premix capacity expansion to serve domestic livestock consolidation and regional export demand. Glanbia PLC leverages its dairy nutrition heritage to anchor premium vitamin and mineral premix supply for European food and beverage clients. BASF SE sustains technology leadership in antioxidant premix formulations through dedicated biotechnology R&D platforms. Corbion N.V. specializes in enzyme premix development for animal feed applications, competing on fermentation-derived ingredient purity.
Customized premixes constitute precisely blended combinations of vitamins, minerals, amino acids, enzymes, and functional additives manufactured to client-specified nutritional profiles and inclusion rates. These formulations typically achieve homogeneity through multi-stage mixing, microencapsulation, or spray-drying processes to ensure stability during feed processing and storage. Animal Nutrition applications dominate volume throughput, reflecting structural reliance on premix-dependent compound feed for industrial livestock and aquaculture operations. Food and Beverage premix demand is accelerating fastest, driven by fortified product lines targeting mineral and vitamin enrichment in processed foods and functional beverages. Powder form retains the largest share of manufacturing output due to cost-efficient handling, extended shelf stability, and compatibility with bulk feed milling infrastructure.
FDA guidelines on new dietary ingredient notifications and FSMA preventive controls shape premix entry requirements for US food and pharmaceutical channels. EFSA feed additive evaluations and REACH chemical safety protocols govern ingredient approval and environmental release standards across European supply chains. China's SAMR and GB standards enforce compositional labeling and contaminant limits for domestically produced and imported premix products. Stakeholders must monitor divergence between regional maximum permitted levels for trace minerals and vitamins, as formulation flexibility becomes the decisive capability for cross-border market access.
Market Dynamics
Livestock consolidation across Southeast Asia and Eastern Europe is compressing premix procurement into fewer, larger compound feed manufacturers with exacting specification requirements and zero-defect quality mandates.
Growth Catalysts
- EU Green Deal traceability mandates:Feed operators across Germany and the Netherlands are reformulating premix compositions to document carbon intensity and ingredient provenance, opening premium pricing tiers for certified low-carbon suppliers.
- Integrated aquaculture scaling:Vietnamese pangasius and shrimp producers are deploying vitamin-enriched premix programs to accelerate harvest cycles and reduce mortality in intensive pond systems.
- Microencapsulation stability advances:Heat-sensitive vitamin coatings now survive extrusion temperatures above 90°C, enabling premix inclusion in pelleted feeds previously restricted to mash or liquid applications.
Market Restraints
- Vitamin A and E input volatility:Feed-grade retinol and tocopherol prices swing with Chinese chemical intermediate availability, squeezing premix margin predictability for European and North American blenders.
- Single-source enzyme dependence:Fermentation-derived phytase and carbohydrase concentrates flow from a handful of Danish and Dutch biotech facilities, creating geographic concentration risk for global premix formulators.
- EFSA additive re-evaluation timelines:Pending safety reviews for copper and zinc compounds in animal nutrition are forcing premature reformulation investments ahead of confirmed maximum permitted level changes.
Strategic Opportunities
- Indonesian smallholder poultry penetration:Independent broiler farms on Java and Sumatra remain underserved by precision nutrition, presenting white-space for mobile premix distribution and on-farm mixing advisory services.
- Plant-based beverage fortification:Oat and almond milk processors in the United States and United Kingdom are sourcing mineral premixes to match dairy nutritional equivalence claims in competitive retail positioning.
- Dual carbon goals in China:SAMR labeling incentives for low-carbon feed products are accelerating domestic demand for premixes with verified supply chain emissions data and renewable energy processing credentials.
Industry Challenges
- Cross-contaminant detection protocols:Premix facilities handling both ruminant and non-ruminant formulations face escalating analytical testing burdens under FDA BSE feed rule enforcement and customer audit requirements.
- Legacy ERP integration with batch traceability:Mid-sized blenders struggle to retrofit manufacturing execution systems for real-time ingredient genealogy tracking demanded by EU feed hygiene regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Customized Premixes Market |
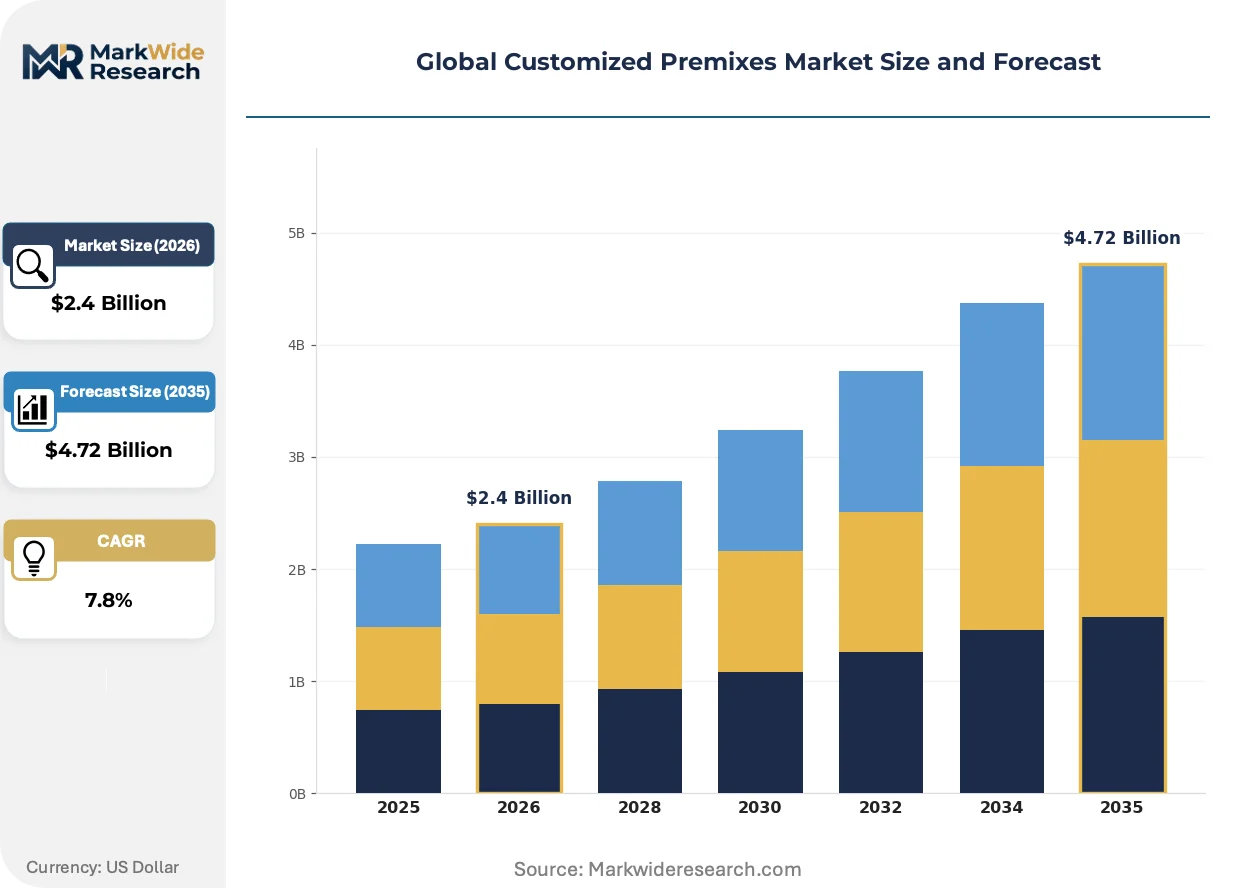
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Animal Nutrition, Food & Beverage, Pharmaceuticals, Agriculture, Personal Care Product Type: Vitamin Premixes, Mineral Premixes, Enzyme Premixes, Antioxidant Premixes, Amino Acid Premixes End User: Dairy Farms, Feed Manufacturers, Medicinal Manufacturers, Crop Producers, Cosmetic Companies Form: Powder, Granules, Liquid Concentrates, Tablets, Pellets |
| Companies Covered | Koninklijke DSM N.V., Glanbia PLC, BASF SE, Cargill Incorporated, Archer Daniels Midland Company, Corbion N.V., Prinova Group LLC, Jubilant Life Sciences Limited, Nutreco N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Customized Premixes Market Shifts & Advancements
Digital formulation platforms and biotechnology-derived additives are compressing development cycles and enabling mass-customization of micronutrient blends previously constrained by minimum efficient scale economics.
Precision dosing software is virtualizing premix specification workflows. Large feed manufacturers in Brazil and Thailand are deploying cloud-based formulation engines that adjust vitamin and mineral matrices in real-time based on raw material assay variations. This virtualization is collapsing the traditional 4-6 week custom premix development cycle into 48-hour turnaround commitments, forcing smaller blenders to license comparable platforms or retreat to commodity standard-grade products.
REACH chemical safety dossier updates are tightening impurity disclosure thresholds for trace mineral premixes entering European supply chains. ECHA substance evaluation working groups are requesting expanded toxicological data on cobalt and selenium compound specifications, compelling premix suppliers to re-qualify raw material sources and absorb third-party testing costs. The animal nutrition segment faces the steepest compliance burden, with several major compounders accelerating supplier consolidation to reduce audit complexity.
Buyer concentration among integrated poultry and aquaculture operators is compressing contract structures toward performance-guaranteed supply agreements. Vietnamese and Indonesian feed groups are unbundling technical advisory from product supply, selecting premix vendors based on flock outcome metrics rather than ingredient cost per ton. This behavioral shift is most visible in Mekong Delta shrimp farming clusters, where survival-rate-linked pricing models are displacing traditional fixed-margin contracts.
Global Customized Premixes Market Segmentation
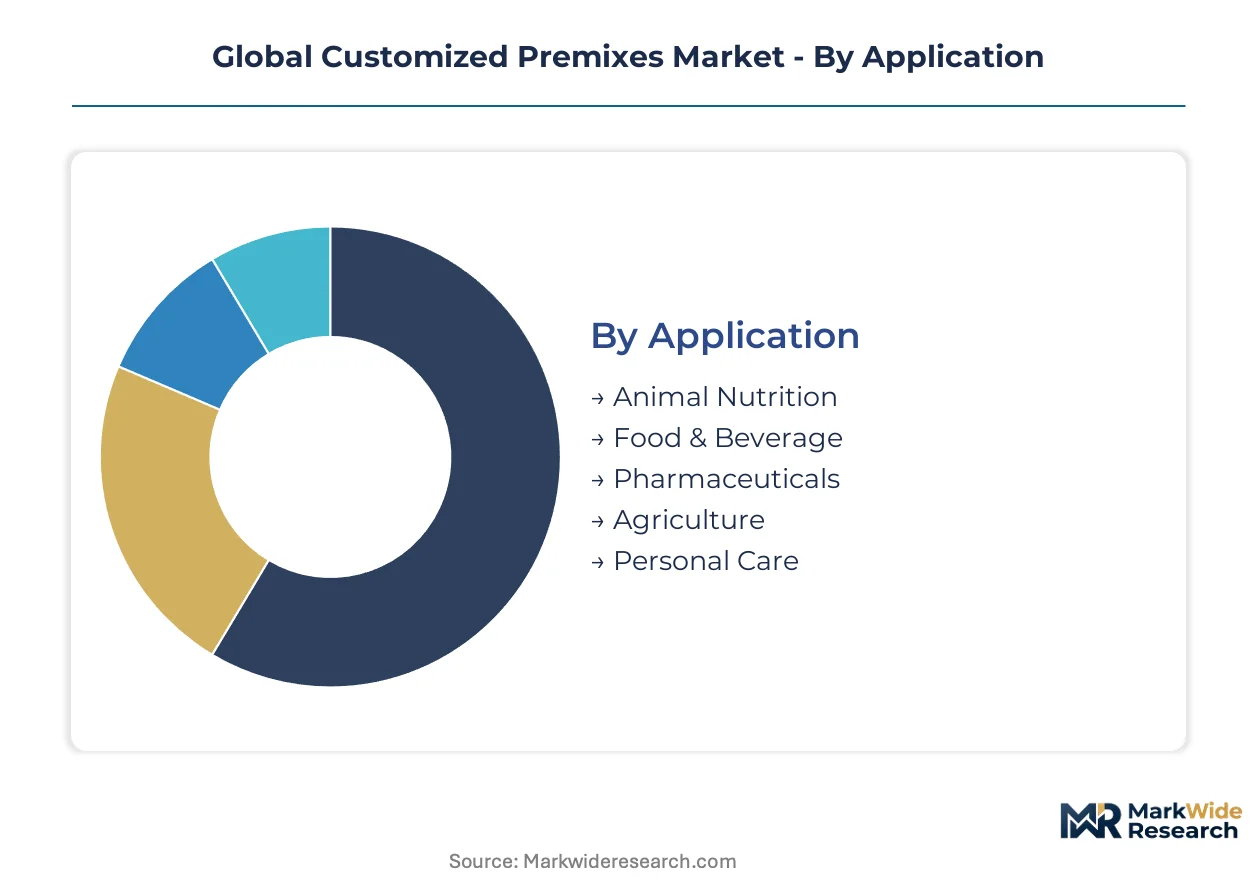
Premix segmentation determines formulation complexity, regulatory pathway, and margin structure. Application focus dictates ingredient stability requirements and certification burdens. Product type governs raw material sourcing concentration and biotechnology intensity.
Application:
End-use concentration shapes volume scale and technical service intensity across customer relationships.
- Animal Nutrition:Formulations blend vitamins, minerals, amino acids, and enzymes to precise inclusion rates for livestock and aquaculture feed. Vietnamese pangasius and Indonesian broiler operations drive procurement consolidation toward outcome-guaranteed supply contracts.
- Food & Beverage:Fortification premixes achieve mineral and vitamin enrichment in processed foods and functional beverages through microencapsulation for stability. Oat and almond milk processors in the United States and United Kingdom source these to match dairy nutritional equivalence claims.
- Pharmaceuticals:Excipient-grade premixes meet USP and EP monograph specifications for tablet and capsule formulations.
- Agriculture:Foliar and soil-applied nutrient premixes address micronutrient deficiency in high-value crop systems.
- Personal Care:Cosmetic-grade vitamin and antioxidant premixes supply skin and hair formulation houses with pre-dispersed active complexes.
Animal Nutrition holds installed capacity. Food & Beverage is rotating up the share rankings.
Product Type:
Technology intensity and raw material provenance create tiered competitive positions across premix categories.
- Vitamin Premixes:Multi-vitamin matrices require heat-stable coatings and moisture barriers to survive feed processing. Feed-grade retinol and tocopherol price volatility from Chinese intermediate availability squeezes margin predictability for European and North American blenders.
- Enzyme Premixes:Fermentation-derived phytase and carbohydrase concentrates enable nutrient digestibility improvements in monogastric feeds. Danish and Dutch biotech facilities supply the majority of global concentrate output, creating geographic concentration risk for formulators.
- Mineral Premixes:Trace element blends achieve homogeneity through carrier selection and particle size matching for feed distribution uniformity.
- Antioxidant Premixes:Synergistic blends of synthetic and natural antioxidants protect feed lipids and vitamins from oxidative degradation.
- Amino Acid Premixes:Crystalline lysine, methionine, and threonine premixes optimize protein efficiency in intensive livestock systems.
Vitamin Premixes dominate production volume. Enzyme Premixes are climbing the fastest on biotechnology premium capture.
End User:
Customer scale and technical sophistication determine service model and contract structure preferences.
- Feed Manufacturers:Compound feed mills procure customized premixes to achieve nutritional specification compliance with minimal in-house micro-ingredient handling. Southeast Asian operations are compressing supplier bases toward zero-defect quality mandates.
- Medicinal Manufacturers:Pharmaceutical and nutraceutical firms source excipient and active premixes under GMP and HACCP protocols.
- Dairy Farms:Large-scale operations deploy premixes in total mixed rations for herd productivity optimization.
- Crop Producers:Specialty agriculture operations apply foliar nutrient premixes for yield and quality enhancement.
- Cosmetic Companies:Formulation houses source pre-dispersed vitamin complexes for skincare and haircare product development.
Feed Manufacturers anchor procurement volume. Medicinal Manufacturers are expanding specification requirements fastest.
Form:
Physical state governs handling infrastructure compatibility, shelf stability, and inclusion method flexibility.
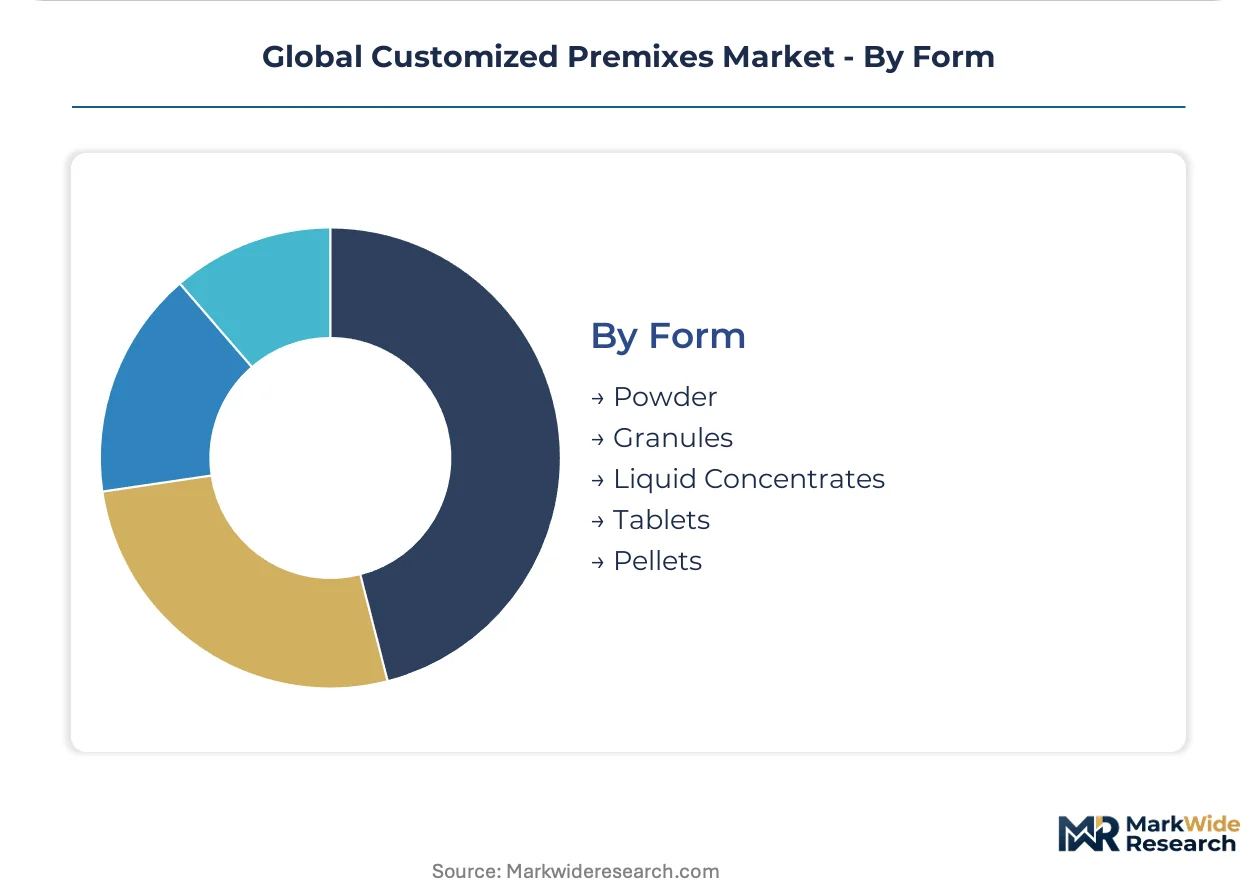
- Powder:Free-flowing premix formulations achieve cost-efficient handling, extended shelf stability, and compatibility with bulk feed milling infrastructure across industrial compound feed operations.
- Liquid Concentrates:Pumpable suspensions enable post-pelleting application and uniform distribution in high-moisture feed systems.
- Granules:Agglomerated forms reduce dust generation and improve flowability for automated dosing equipment.
- Tablets:Compressed premix formats serve pharmaceutical and nutraceutical direct compression requirements.
- Pellets:Extruded premix carriers protect heat-sensitive actives during pelleting processes.
Powder retains manufacturing dominance. Liquid Concentrates are gaining share fastest on aquaculture and pet food application expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA feed additive evaluations anchor European compliance architecture, while SAMR labeling standards and FDA preventive controls shape parallel pathways in Asia-Pacific and North American supply chains respectively.
China
Domestic livestock consolidation drives large-scale premix capacity expansion across Shandong and Guangdong provinces. SAMR enforces GB standards for compositional labeling and contaminant limits on all domestically produced and imported premix products. The Yangtze River Delta hosts integrated poultry operations scaling vitamin-enriched nutrition programs with verified supply chain emissions data.
Germany
Compound feed manufacturers reformulate premix compositions to document carbon intensity under EU Green Deal traceability mandates. EFSA feed additive re-evaluations for copper and zinc compounds force premature reformulation investments ahead of confirmed maximum permitted level changes. The Lower Saxony corridor concentrates ruminant premix facilities facing escalating analytical testing burdens under BSE feed rule enforcement.
United States
Oat and almond milk processors source mineral premixes to match dairy nutritional equivalence claims in fortified beverage lines. FDA guidelines on new dietary ingredient notifications and FSMA preventive controls shape premix entry requirements for food and pharmaceutical channels. California's Central Valley dairy operations deploy premixes in total mixed rations for herd productivity optimization.
Vietnam
Pangasius and shrimp producers deploy vitamin-enriched premix programs to accelerate harvest cycles and reduce mortality in intensive pond systems. The country's national feed regulator monitors maximum permitted levels for trace minerals and vitamins in aquaculture applications. The Mekong Delta anchors survival-rate-linked pricing models displacing traditional fixed-margin contracts among integrated operators.
Indonesia
Independent broiler farms on Java and Sumatra remain underserved by precision nutrition, creating white-space for mobile premix distribution networks. The central agricultural ministry oversees feed safety protocols for smallholder poultry penetration programs. Surabaya and Medan industrial zones concentrate mid-sized blenders struggling to retrofit manufacturing execution systems for real-time ingredient genealogy tracking.
Global Customized Premixes Market Competitive Landscape
Vertically integrated nutrition conglomerates and specialized biotechnology formulators split the market into contrasting capability tiers. The vendor base concentrates around compound feed heritage players with captive raw material sourcing and fermentation-derived ingredient specialists with purity premiums. Three archetypes dominate: diversified agribusiness giants with global distribution infrastructure, mid-sized regional blenders with formulation flexibility, and biotechnology pure-plays with enzyme and antioxidant R&D platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves, with European players securing fermentation capacity through long-term offtake agreements and Asian operators building domestic premix plants to serve livestock consolidation.
Within the diversified agribusiness tier, Koninklijke DSM N.V. and Cargill Incorporated exemplify scale-driven positions spanning human and animal nutrition applications. BASF SE occupies a biotechnology-focused niche with antioxidant formulation heritage. These three entities represent contrasting strategic postures: DSM's Dutch cooperative structure, Cargill's privately held American grain-trading lineage, and BASF's German chemical conglomerate scale. Each anchors distinct competitive vectors—DSM through micronutrient precision, Cargill through feed-to-fork integration, and BASF through process chemistry expertise—without overlapping core positioning.
| Leading Market Players |
|---|
| Koninklijke DSM N.V. |
| Glanbia PLC |
| BASF SE |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Corbion N.V. |
| Prinova Group LLC |
| Jubilant Life Sciences Limited |
| Nutreco N.V. |
| Others |
Supply & Pricing Matrix
Chinese chemical intermediate concentration for feed-grade retinol and tocopherol anchors margin volatility downstream, compressing European and North American blenders between input cost swings and fixed contract obligations to integrated poultry operators.
Pricing Analysis
Geographic price spreads widen between vitamin premix formulations sourced from Shandong Province blenders and European fermentation-derived enzyme premixes from Danish and Dutch facilities. Three-tier pricing structure across premium, standard, and economy levels separates certified low-carbon premixes with EU Green Deal documentation from commodity-grade vitamin matrices and small-batch custom formulations. Pricing pressure stems from Chinese intermediate availability swings squeezing margin predictability for retinol-dependent formulations. Feed manufacturers in Vietnam and Indonesia exhibit highest price sensitivity due to survival-rate-linked contract structures, while pharmaceutical excipient buyers tolerate premium positioning for USP and EP monograph compliance.
Supply Chain Analysis
Contract manufacturing concentration rests with integrated agribusiness giants operating captive premix facilities across the Netherlands, Germany, and China's Yangtze River Delta corridor. Raw material sourcing draws from Chinese vitamin intermediate producers, Danish and Dutch fermentation-derived enzyme concentrates, and Brazilian amino acid crystallization plants. Single-source vulnerability concentrates in phytase and carbohydrase supply from Scandinavian biotech facilities. Distribution runs through compound feed mill direct procurement with technical advisory bundling, supplemented by mobile distribution networks penetrating Indonesian smallholder poultry operations on Java and Sumatra.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated poultry and aquaculture operators across Southeast Asia, compressing premix procurement into fewer compound feed manufacturers with outcome-guaranteed contract demands.
For Market Incumbents: Entrench formulation flexibility capabilities to navigate EFSA additive re-evaluation timelines for copper and zinc compounds. Deepen backward integration into Chinese vitamin intermediate sourcing to buffer retinol and tocopherol price volatility. Capture premium positioning through EU Green Deal carbon intensity certification investments that open traceability-mandated pricing tiers. For New Entrants and Emerging Players: Pursue mobile premix distribution and on-farm mixing advisory services targeting independent broiler farms across Java and Sumatra. Plant-based beverage fortification in the United States and United Kingdom offers penetrable white-space for mineral premix suppliers matching dairy nutritional equivalence claims. Lead with technical service bundling rather than ingredient cost competition to differentiate from established compound feed heritage players. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized regional blenders struggling to retrofit manufacturing execution systems for EU feed hygiene genealogy tracking requirements. Long-term viability favors biotechnology pure-plays with captive fermentation capacity and antioxidant R&D platforms over commodity vitamin formulators exposed to Chinese intermediate volatility. Watch EFSA maximum permitted level decisions for copper and zinc compounds as regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Fermentation Capacity Offtake | Danish and Dutch biotech facilities lock in enzyme concentrate supply security for global formulators. |
| Domestic Premix Plant Construction | Shandong and Guangdong province capacity serves Chinese livestock consolidation and regional export demand. |
| Cloud-based Formulation Platform Licensing | Brazilian and Thai feed manufacturers deploy precision dosing software collapsing development cycles to 48-hour turnaround. |
| EU Green Deal Carbon Certification | German and Dutch operators document ingredient provenance opening premium pricing tiers for low-carbon suppliers. |
| Mobile Distribution Network Expansion | Indonesian smallholder poultry penetration on Java and Sumatra addresses precision nutrition white-space. |
Research Methodology
Cross-validation between executive interviews and trade data anchors the qualitative findings. Primary fieldwork engaged compound feed procurement directors, premix plant managers, regulatory affairs leads at biotechnology formulators, and aquaculture nutrition specialists across Vietnam and Indonesia. Secondary validation drew from EFSA feed additive evaluation databases, SAMR GB standards filings, customs trade records for vitamin intermediate flows, and SEC disclosures from diversified agribusiness conglomerates. Bottom-up capacity assessments triangulated against top-down demand modeling from livestock and aquaculture production statistics.
Calibration against historical price volatility patterns for feed-grade retinol and tocopherol refined the projection framework. Segmentation dimensions modeled include application focus, product type technology intensity, end-user scale and sophistication, and physical form compatibility. CAGRs derived from slope analysis of installed capacity expansion announcements and buyer concentration trends across the projection horizon. Industry-specific inputs incorporated EFSA re-evaluation timeline scenarios and Chinese dual carbon goal compliance incentives.
Sensitivities concentrate around EFSA maximum permitted level revisions for trace minerals, Chinese intermediate supply disruptions, and survival-rate-linked contract adoption rates in Mekong Delta shrimp farming. Forecasts reflect documented assumptions on livestock consolidation trajectories and biotechnology platform adoption curves. Quarterly review of EFSA additive evaluation working group outputs and SAMR labeling incentive program adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Latin America Hydroxypropyl Methylcellulose Market
Specialty Compounds
Global Specialty Amines Market
Specialty Compounds
Global Molding Compounds Market
Specialty Compounds
Galactoarabinan Market
Specialty Compounds
GCC Specialty Chemicals Market
Specialty Compounds
Stannous Chloride Market
Specialty Compounds
Specialty Sorbents Market
Specialty Compounds
Polypropylene Compounds Market
Specialty Compounds
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market
Specialty Compounds
Asia-Pacific Chromatography Resins Market
Specialty Compounds
Thionyl Chloride Market
Specialty Compounds
Hypalon Market
Specialty Compounds
Silicone Potting Compounds Market
Specialty Compounds
Sodium Stannate Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Middle East and Africa Color Masterbatch Market