
 Germany Collagen Market | 2026-2036
Germany Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Collagen Market Foresight
Multi-source procurement from certified European abattoirs is pivoting away from single-origin bovine reliance as German manufacturers hedge against supply disruption. Gelita AG leverages its Eberbach production complex to sustain integrated gelatin-to-peptide conversion. Darling Ingredients Inc. competes through its European rendering network, while Ewald-Gelatine GmbH anchors specialty pharmaceutical-grade output from its Bavarian facility.
Collagen comprises triple-helical protein structures extracted through acid or enzymatic hydrolysis of animal connective tissues, yielding molecular weights from 50 to 300 kDa for applications spanning edible films to hemostatic sponges. Hydrolyzed collagen dominates volume due to its cold-water solubility and neutral taste profile, yet collagen peptides command premium positioning in sports nutrition and clinical nutrition segments where bioactive di- and tripeptide content drives efficacy claims. Marine-sourced collagen from North Sea fisheries is gaining share in cosmetic applications despite higher raw material costs, while bovine and porcine categories retain pharmaceutical dominance through established pharmacopeial monographs.
BfArM enforces batch-release testing for collagen-based medical devices under the EU MDR framework, pushing manufacturers toward ISO 13485-certified quality systems. The German Animal By-Products Regulation, implementing EC 1069/2009, restricts sourcing geography and traceability documentation for Category 3 materials used in human applications. Stakeholders must monitor evolving EFSA opinions on novel collagen extraction methods and assess whether enzymatic processing innovations will trigger reclassification under food additive or novel food pathways.
Market Dynamics
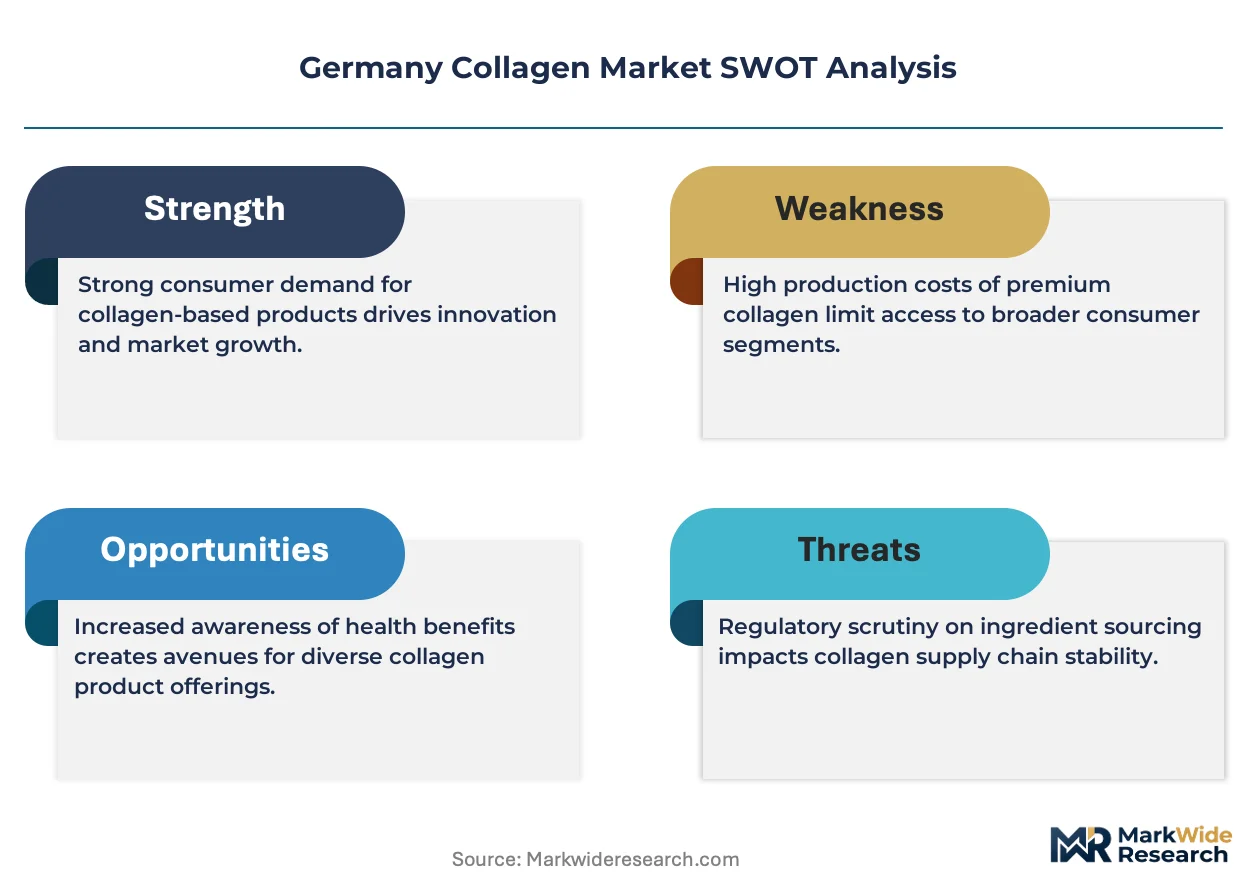
EU Medical Device Regulation (MDR) batch-release mandates are compressing certification timelines for Bavarian and Baden-Württemberg manufacturers, forcing upstream quality system investments before revenue recognition.
Growth Catalysts
- Wound-healing matrix demand:Pharmaceutical formulators in the Rhine-Main cluster are expanding collagen uptake for drug-delivery systems and hemostatic applications, pulling volume from adjacent biomaterial categories.
- EC 1069/2009 traceability requirements:The German Animal By-Products Regulation implementation is professionalizing sourcing documentation, enabling Category 3 material flows into higher-value pharmaceutical channels.
- Enzymatic hydrolysis advancement:Peptide extraction technologies are unlocking bioactive di- and tripeptide fractions for clinical nutrition, creating premium positioning opportunities distinct from commodity gelatin.
Market Restraints
- Bovine sourcing concentration:Reliance on certified European abattoirs for Type I collagen creates geographic supply vulnerability during livestock disease outbreaks or transport disruptions.
- BfArM implantable purity benchmarks:Germany's federal drug and medical device institute enforces escalating endotoxin and viral clearance standards that extend validation cycles and freeze working capital.
- Marine collagen cost structure:North Sea fishery raw material premiums of 40-60% above bovine equivalents constrain cosmetic segment expansion despite superior consumer perception.
Strategic Opportunities
- Porcine pharmacopeial diversification:EP and USP monograph alignment for porcine-derived collagen is enabling dual-source qualification that hedges against single-species regulatory restrictions.
- ISO 13485-certified contract manufacturing:Frankfurt-area toll processors are capturing export pharmaceutical clients seeking EU MDR-compliant production without captive facility investment.
- EFSA novel food pathway preparation:Enzymatic processing innovations may trigger reclassification discussions, opening food additive and functional food channels beyond current medical device and supplement boundaries.
Industry Challenges
- Peptide characterization skill scarcity:Analytical chemistry and mass spectrometry expertise for molecular weight distribution verification is concentrated among legacy gelatin specialists, constraining new entrant scale-up.
- Dual-use facility capex intensity:Simultaneous food-grade and pharmaceutical-grade production lines require segregated HVAC and water systems that demand 18-24 month construction timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Collagen Market |
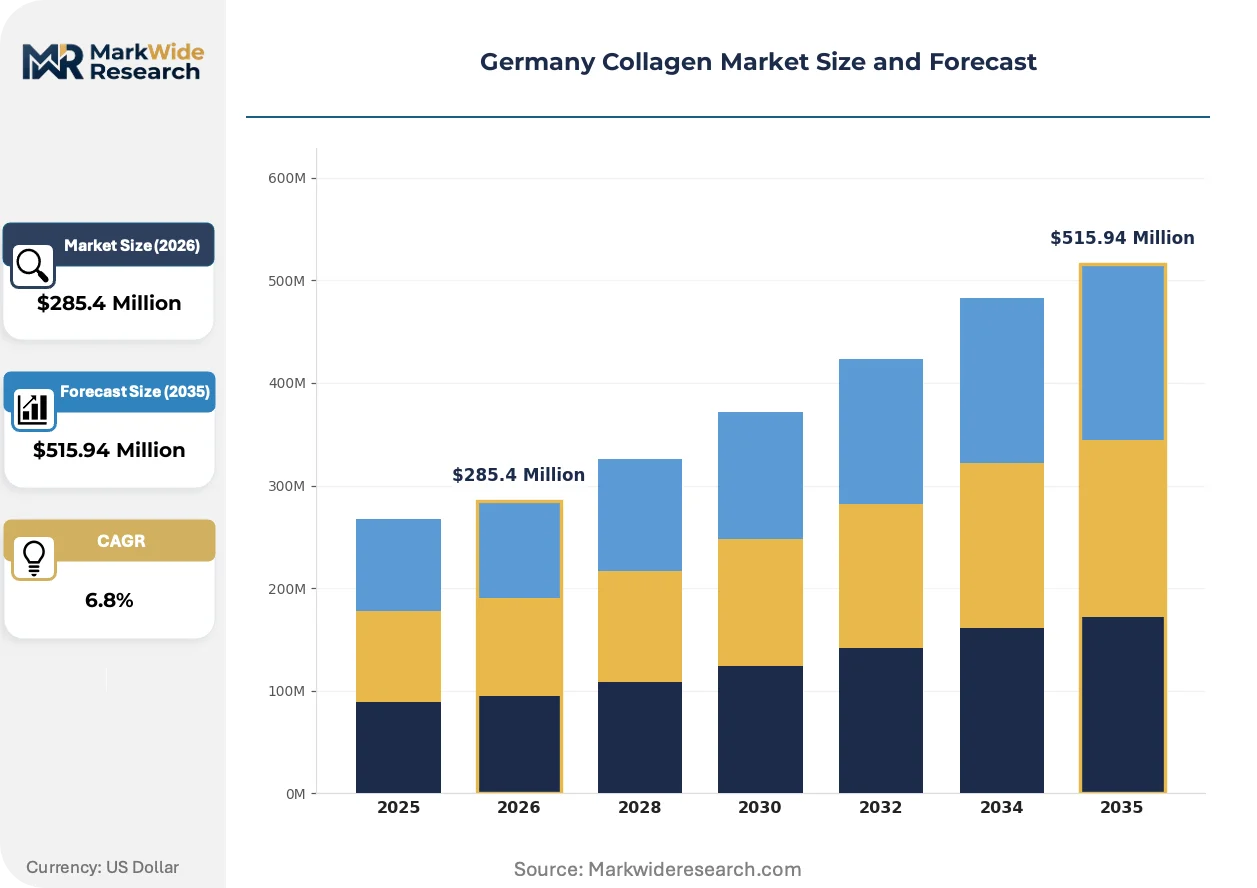
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Peptides, Collagen Powder Application: Food & Beverages, Pharmaceuticals, Cosmetics, Nutraceuticals Source: Bovine, Porcine, Marine, Poultry Form: Powder, Liquid, Capsule, Tablet |
| Companies Covered | Gelita AG, Darling Ingredients Inc., Italgelatine S.p.A., LAPI GELATINE S.p.a., Tessenderlo Group, Ewald-Gelatine GmbH, Cooke Inc., Nagase & Co., Ltd., Innocoll Pharmaceuticals Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Collagen Market Shifts & Advancements
Automation of quality control workflows is compressing batch-release timelines while enzymatic processing innovations are fragmenting traditional gelatin-to-peptide value chains across German manufacturing clusters.
Continuous flow enzymatic hydrolysis is automating molecular weight fractionation that previously required batch-wise acid processing. Mid-scale Bavarian processors are adopting these systems to serve pharmaceutical clients demanding narrow 50-100 kDa specifications. The technology is automating peptide standardization that formerly demanded manual chromatographic separation, reducing labor cost structures by half in qualified facilities.
BfArM's tightened interpretation of EU MDR Annex I general safety and performance requirements is mandating real-time endotoxin monitoring for implantable collagen matrices. Device manufacturers now face unannounced inspections of sterilization validation protocols that previously followed self-certified schedules. The regulatory shift most affects Baden-Württemberg orthopedic scaffold producers, who are consolidating supplier bases to reduce audit surface area.
Direct sourcing contracts between Frankfurt pharmaceutical formulators and Eberbach-area production complexes are displacing traditional merchant gelatin distribution channels. Buyers are consolidating annual volumes with single-source peptide suppliers who maintain dedicated quality agreements and reserved production slots. This pattern concentrates most visibly in the wound-care segment, where hemostatic sponge manufacturers require lot-to-lot consistency that spot-market purchasing cannot guarantee.
Germany Collagen Market Segmentation
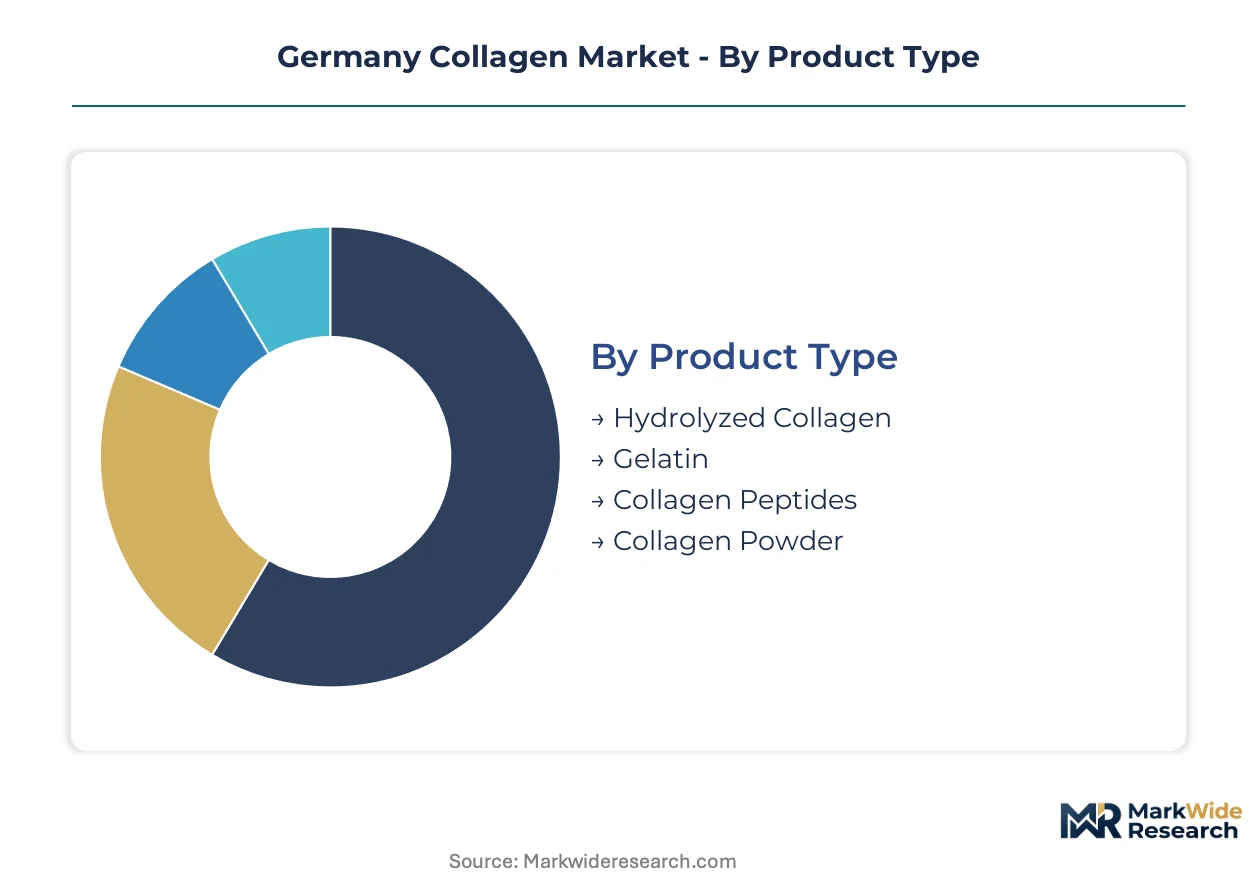
Collagen segmentation in Germany reflects divergent capital requirements across pharmaceutical-grade extraction, food-grade processing, and cosmetic formulation lines. Manufacturers must align facility investments with the purity benchmarks and certification timelines demanded by each segment tier.
Product Type:
Capital intensity peaks in peptide fractionation infrastructure, where enzymatic hydrolysis systems and chromatographic separation equipment demand 18-24 month deployment cycles.
- Hydrolyzed Collagen:Acid or enzymatic hydrolysis yields cold-water soluble proteins with molecular weights spanning 50-300 kDa. Demand concentrates in sports nutrition and clinical nutrition segments across the Rhine-Main cluster, driven by bioactive di- and tripeptide content requirements.
- Collagen Peptides:Narrow molecular weight fractions, typically 50-100 kDa, command premium positioning in pharmaceutical drug-delivery systems and wound-healing matrices. Bavarian processors are adopting continuous flow enzymatic systems to serve BfArM-regulated medical device manufacturers with lot-to-lot consistency mandates.
- Gelatin:Partial hydrolysis of collagen yields thermoreversible gels for edible films and capsule shells. Eberbach-area production complexes anchor supply for Frankfurt pharmaceutical formulators seeking integrated gelatin-to-peptide conversion.
- Collagen Powder:Spray-dried or freeze-dried formats serve cosmetic and nutraceutical blending operations. Powder specifications vary by particle size distribution and moisture content per end-use application.
Most installed capacity flows through Hydrolyzed Collagen. Expansion is steepest in Collagen Peptides.
Application:
Application mix determines regulatory pathway complexity, with pharmaceutical and medical device channels imposing the most stringent quality system burdens.
- Pharmaceuticals:Wound-healing matrices, hemostatic sponges, and drug-delivery systems require ISO 13485-certified production and BfArM batch-release testing under EU MDR. Baden-Württemberg orthopedic scaffold producers are consolidating supplier bases to reduce audit surface area.
- Food & Beverages:Edible films, gelling agents, and functional food ingredients operate under less stringent EC 1069/2009 Category 3 traceability requirements. Gelita AG leverages Eberbach integration to serve commodity and specialty food channels simultaneously.
- Cosmetics:Topical formulations and nutricosmetics favor marine-sourced collagen from North Sea fisheries despite 40-60% raw material premiums over bovine equivalents. Consumer perception drives share gains even as cost structures constrain mass-market penetration.
- Nutraceuticals:Dietary supplements and clinical nutrition products bridge food and pharmaceutical regulatory boundaries. EFSA novel food pathway discussions may reclassify enzymatic processing innovations, opening additional channel access.
Pharmaceuticals commands the highest capital deployment per revenue unit. Nutraceuticals is gaining share fastest.
Source:
Source selection shapes geographic supply vulnerability and pharmacopeial qualification pathways for German manufacturers.
- Bovine:Type I collagen from certified European abattoirs dominates pharmaceutical-grade supply. Reliance on single-species sourcing creates exposure to livestock disease outbreaks and transport disruptions.
- Porcine:EP and USP monograph alignment enables dual-source qualification that hedges against bovine-specific regulatory restrictions. Ewald-Gelatine GmbH anchors specialty pharmaceutical-grade porcine output from its Bavarian facility.
- Marine:North Sea fishery-derived collagen gains traction in cosmetic applications through superior consumer perception despite higher input costs. Extraction requires specialized de-mineralization and odor-removal processing lines.
- Poultry:Avian-sourced collagen remains niche, primarily serving halal-certified cosmetic and nutraceutical formulations where mammalian sources face religious or cultural restrictions.
Bovine retains the largest qualified supply base. Marine is climbing the fastest.
Form:
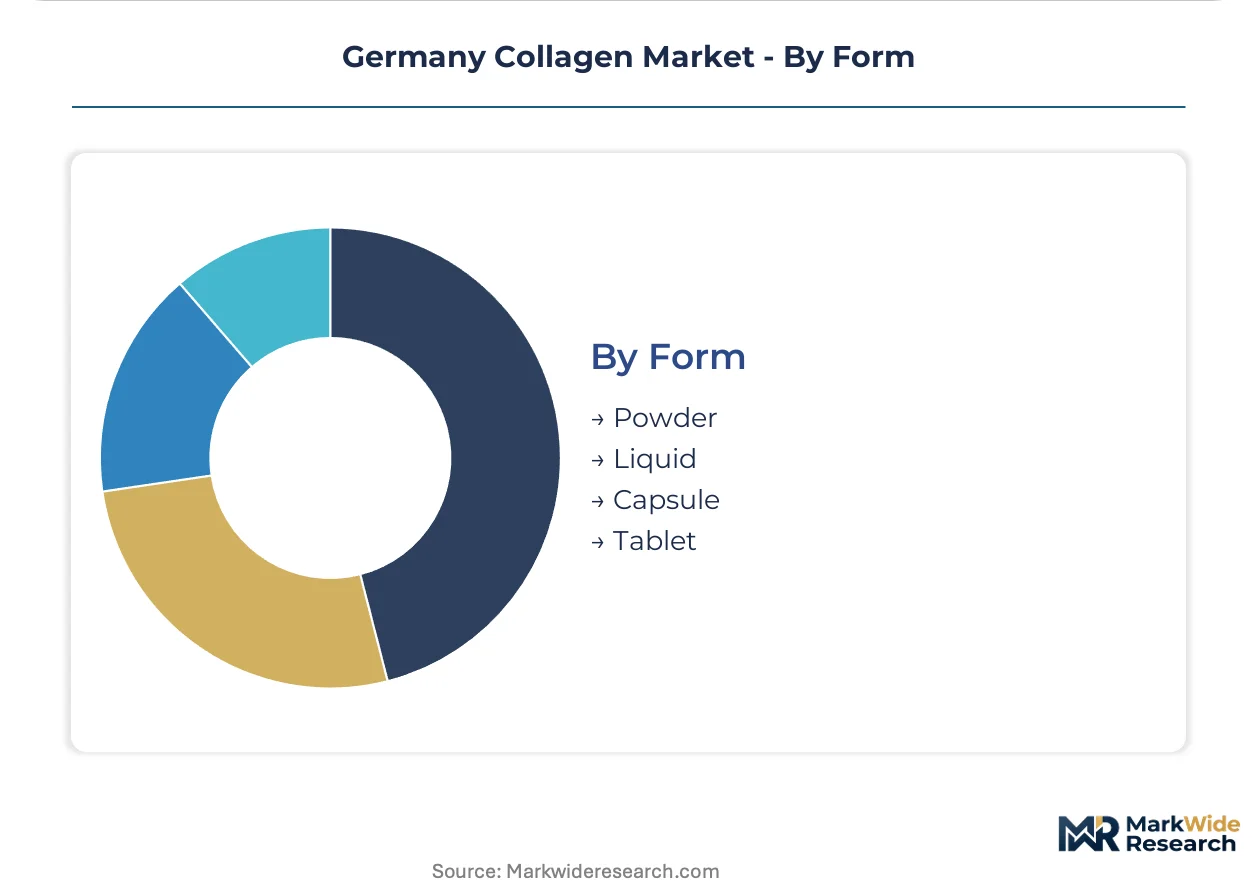
Form factor determines packaging, stability, and dosing flexibility across end-use applications.
- Powder:Bulk dry blends dominate food, nutraceutical, and cosmetic manufacturing inputs. Powder handling requires controlled humidity environments and segregated pneumatic conveying systems.
- Liquid:Ready-to-drink formulations and cosmetic serums demand aseptic filling lines and preservative system validation. Shorter shelf life constrains distribution radius.
- Capsule:Hard gelatin and hydroxypropyl methylcellulose shells encapsulate collagen for precise dosing in supplement applications. Capsule filling equipment scales from laboratory to high-speed rotary formats.
- Tablet:Compressed formulations with binders and disintegrants serve convenience-oriented nutraceutical consumers. Tablet tooling and coating systems add capital requirements beyond powder processing.
Powder captures the majority of production volume. Liquid is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps are reshaping production geography as German manufacturers face stricter BfArM oversight than neighboring jurisdictions, prompting some contract processing to migrate toward EU member states with streamlined MDR implementation timelines while domestic facilities absorb premium-tier certification investments.
Bavaria
Wound-healing matrix demand from Baden-Württemberg orthopedic scaffold producers and pharmaceutical formulators drives collagen peptide consumption. The German Animal By-Products Regulation enforces Category 3 material traceability documentation that professionalizes sourcing channels. The Eberbach production complex anchors integrated gelatin-to-peptide conversion for Frankfurt-area pharmaceutical clients.
Baden-Württemberg
Orthopedic scaffold manufacturers consolidate supplier bases to reduce EU MDR audit surface area amid tightened BfArM interpretation of Annex I safety requirements. ISO 13485-certified quality systems are becoming mandatory for implantable biomaterial suppliers. Stuttgart-area device producers are unannounced inspection targets for sterilization validation protocols.
Hesse
The Rhine-Main cluster around Frankfurt concentrates contract manufacturing demand from both domestic and export pharmaceutical clients seeking toll processing without captive facility investment. EC 1069/2009 traceability requirements enable Category 3 material flows into higher-value pharmaceutical channels. Direct sourcing contracts are displacing traditional merchant gelatin distribution.
North Rhine-Westphalia
Industrial gelatin demand from food-grade processing and edible film applications sustains commodity-scale operations. The state's logistics infrastructure supports multi-source procurement from certified European abattoirs. Cologne-Düsseldorf corridor distributors serve as intermediaries for bovine collagen hedging strategies against supply disruption.
Lower Saxony
Marine collagen processing from North Sea fishery inputs is gaining share in cosmetic applications despite raw material premiums. Specialized de-mineralization and odor-removal processing lines require dedicated capital deployment. Bremen-area facilities are developing extraction capabilities for superior consumer perception segments.
Germany Collagen Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue enzymatic processing specialization and marine-source differentiation. The market structure consolidates around legacy gelatin specialists with pharmacopeial qualification heritage and mid-scale Bavarian processors adopting continuous flow systems. Three archetypes dominate: integrated gelatin-to-peptide converters, toll-processing contract manufacturers, and marine-source cosmetic specialists. Capacity expansion and dual-source species qualification represent the dominant competitive moves as manufacturers hedge against single-origin regulatory restrictions.
Among integrated production specialists, Gelita AG anchors the Eberbach complex as an exemplar of captive supply chain control, while Ewald-Gelatine GmbH occupies a position within Bavarian pharmaceutical-grade specialization. Darling Ingredients Inc. represents the rendering-network archetype competing through European raw material access. These three entities exemplify distinct strategic postures: facility integration, geographic specialization, and upstream network scale.
| Leading Market Players |
|---|
| Gelita AG |
| Darling Ingredients Inc. |
| Italgelatine S.p.A. |
| LAPI GELATINE S.p.a. |
| Tessenderlo Group |
| Ewald-Gelatine GmbH |
| Cooke Inc. |
| Nagase & Co., Ltd. |
| Innocoll Pharmaceuticals Limited |
| Others |
Supply & Pricing Matrix
North Sea fishery raw material premiums flow downstream through cosmetic segment pricing tiers, compressing margin structures for marine-sourced collagen processors while reinforcing bovine-derived pharmaceutical-grade positioning. Enzymatic hydrolysis capital intensity at Bavarian mid-scale facilities concentrates cost recovery in narrow molecular weight peptide fractions serving BfArM-regulated medical device channels.
Pricing Analysis
Input-cost pass-through from certified European abattoir sourcing dominates contract negotiations for Type I collagen, with Category 3 material traceability documentation adding compliance premiums to pharmaceutical-grade quotations. Pricing stratifies across pharmaceutical-certified, food-grade, and cosmetic-tier quality levels, with ISO 13485 certification commanding substantial premiums over EC 1069/2009 Category 3 baselines. Cost compression in commodity gelatin segments intensifies as Eberbach-area integrated producers leverage captive supply advantages. Nutraceutical buyers exhibit highest price sensitivity due to discretionary purchase patterns, while orthopedic scaffold manufacturers prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Workforce availability constraints in Bavarian and Baden-Württemberg manufacturing clusters tether capacity expansion timelines to 18-24 month construction cycles for segregated pharmaceutical-grade production lines. Supply concentrates in Germany, Netherlands, and Belgium for enzymatic processing infrastructure, with raw material sourcing drawing from certified European abattoirs and North Sea fisheries. Single-species bovine reliance creates livestock disease outbreak vulnerability. Distribution runs through direct sourcing contracts between Frankfurt pharmaceutical formulators and Eberbach-area production complexes, displacing traditional merchant gelatin channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German manufacturers face geographic-arbitrage pressure as neighboring EU jurisdictions implement streamlined EU MDR timelines, creating cost-of-compliance gaps that incentivize contract processing migration while domestic facilities absorb premium-tier certification investments.
For Market Incumbents: Deploy backward integration into certified European abattoir networks to secure Category 3 material flows against livestock disease disruption. Consolidate supplier audit bases to reduce BfArM unannounced inspection exposure for Baden-Württemberg orthopedic scaffold clients. Expand enzymatic hydrolysis capacity in Bavarian facilities to capture pharmaceutical peptide premium positioning. For New Entrants and Emerging Players: Begin with marine-sourced cosmetic formulations targeting North Sea fishery inputs, where consumer perception premiums offset raw material cost structures. Target toll-processing contracts for Frankfurt-area pharmaceutical clients seeking EU MDR-compliant production without captive facility investment. Pursue EFSA novel food pathway preparation for enzymatic processing innovations. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485-certified quality systems and pharmacopeial qualification heritage concentrate among legacy gelatin specialists. Long-term viability favors mid-scale Bavarian processors with continuous flow enzymatic capabilities and dual-source species qualification. Monitor EFSA opinions on novel collagen extraction methods as inflection signal for food additive channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source Species Qualification | Porcine EP/USP monograph alignment hedges German manufacturers against bovine-specific regulatory restrictions. |
| ISO 13485 Certification Investment | BfArM batch-release mandates under EU MDR require quality system upgrades for implantable biomaterial suppliers. |
| Continuous Flow Enzymatic Hydrolysis | Bavarian processors automate molecular weight fractionation to serve pharmaceutical lot-to-lot consistency requirements. |
| Direct Sourcing Contract Consolidation | Frankfurt pharmaceutical formulators displace merchant gelatin channels with dedicated quality agreements. |
| EFSA Novel Food Pathway Preparation | Enzymatic processing innovations may reclassify collagen for food additive and functional food channel access. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical formulators, contract manufacturing executives, regulatory affairs specialists, and biomedical procurement managers with secondary validation from BfArM guidance documents, EU MDR implementation notices, EFSA scientific opinions, and EC 1069/2009 traceability filings. Bottom-up volume modeling across hydrolyzed collagen, collagen peptides, gelatin, and powder segments triangulated against top-down industry aggregation.
Segment-weighting approaches distributed value and volume across product type, application, source, and form dimensions, with pharmaceutical-grade extraction, food-grade processing, and cosmetic formulation lines receiving distinct capital intensity coefficients. CAGRs derived from trend extrapolation of enzymatic processing adoption rates and wound-healing matrix demand expansion across the analysis window. Forecast inputs incorporated BfArM regulatory interpretation shifts and Eberbach-area production complex capacity utilization patterns.
Several conditions sit outside the modeled scope, including unannounced EU MDR enforcement severity changes, livestock disease outbreak scenarios affecting certified European abattoir supply, and EFSA reclassification decisions on novel extraction methods. Forecasts reflect documented assumptions regarding regulatory stability and species sourcing availability. Material deviation in BfArM inspection intensity or Category 3 material traceability requirements warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Europe Microencapsulation Market
Specialty Compounds
Chromium Phosphate Market
Specialty Compounds
Silicone Potting Compounds Market
Specialty Compounds
China Collagen Market
Specialty Compounds
Hydroxypropyl Methylcellulose Market
Specialty Compounds
Potassium Derivatives Market
Specialty Compounds
Small Molecules Innovator Contract Development and Manufacturing Organization Market
Specialty Compounds
Thionyl Chloride Market
Specialty Compounds
Strontium Nitrate Market
Specialty Compounds
Specialty Monomer Market
Specialty Compounds
Global Compound Management Market
Specialty Compounds
Global Specialty Zeolites Market
Specialty Compounds
Strontium Chloride Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Filler Masterbatch Market