
 Chromatography Silica Resins Market | 2026-2036
Chromatography Silica Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Chromatography Silica Resins Market Analysis
Preparative liquid chromatography is tilting toward high-purity functional silica with controlled pore architectures for biomolecule separation. Merck KGaA leverages its integrated life sciences platform to anchor supply relationships with biopharma contract manufacturers across Europe and North America. Osaka Soda Co. Limited specializes in hard silica matrices engineered for high-pressure operation, while W.R. Grace and Company dominates manufacturing scale through its chromatography-grade silica production network.
Chromatography silica resins comprise porous silicon dioxide particles with defined particle size distributions, surface areas ranging from 300 to 700 square meters per gram, and pore diameters calibrated for target analyte dimensions, functioning as stationary phases that separate compounds based on differential adsorption and elution behavior in liquid chromatography systems. Functional silica leads product type demand because surface chemistries including C18, amino, and cyano modifications command premium pricing in peptide and oligonucleotide purification workflows. Pharmaceuticals anchors application demand with biotech representing the fastest-expanding segment as gene therapy and mRNA manufacturing scales require resin volumes that dwarf traditional small-molecule batch sizes.
FDA enforces current Good Manufacturing Practice standards that dictate resin lot-to-lot consistency and extractables profiles for chromatography materials contacting parenteral drug substances, while EMA's MDR and REACH frameworks impose traceability and substance registration obligations on silica resin suppliers serving European pharmaceutical manufacturers. ISO 9001 quality management certification functions as a baseline market access requirement rather than a differentiator among established suppliers. Stakeholders must monitor how EMA's evolving guidance on continuous manufacturing impacts resin lifecycle validation protocols and supplier qualification timelines.
Market Dynamics
FDA and EMA purity mandates for injectable biologics are forcing chromatography resin suppliers to validate extractables profiles and lot-to-lot consistency at unprecedented stringency, compressing supplier qualification timelines and concentrating procurement among certified manufacturers.
Growth Catalysts
- Gene therapy manufacturing scale-up:Viral vector purification workflows require resin volumes that dwarf traditional small-molecule batches, pulling high-purity functional silica into multi-ton annual procurement cycles.
- REACH substance registration:ECHA's traceability framework for silica resins contacting parenteral substances locks in supplier relationships with European pharmaceutical contract manufacturers.
- Continuous processing adoption:Biopharma manufacturers are retrofitting batch chromatography suites with simulated moving bed systems, demanding resins engineered for cyclic loading durability.
Market Restraints
- Tetraethyl orthosilicate cost volatility:Sol-gel silica precursor prices fluctuate with semiconductor-grade silicon metal markets, squeezing margin on chromatography-grade production.
- Supplier concentration in Germany and Japan:Three manufacturers control over 70% of high-purity spherical silica capacity, creating single-source vulnerability for CMO qualification programs.
- Protein A resin substitution:Affinity capture media for monoclonal antibodies is displacing silica-based ion exchange in upstream purification trains.
Strategic Opportunities
- Indian biopharma manufacturing expansion:CDSCO's streamlined biosimilar approval pathways are attracting multinational CMOs that require validated resin supply chains.
- Oligonucleotide therapeutics surge:Synthetic RNA manufacturing scales are creating demand for wide-pore silica engineered for 20-mer to 100-mer separation.
- Single-use chromatography integration:Pre-packed column formats are converging with disposable flow path technologies, opening resin-as-a-service distribution models.
Industry Challenges
- Analytical method transfer expertise:Biopharma quality teams lack personnel proficient in resin extractables validation under USP <665> and <1665> guidelines.
- Multi-year supplier qualification timelines:FDA's risk-based approach to cGMP material qualification extends resin approval cycles beyond typical RFP windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromatography Silica Resins Market |
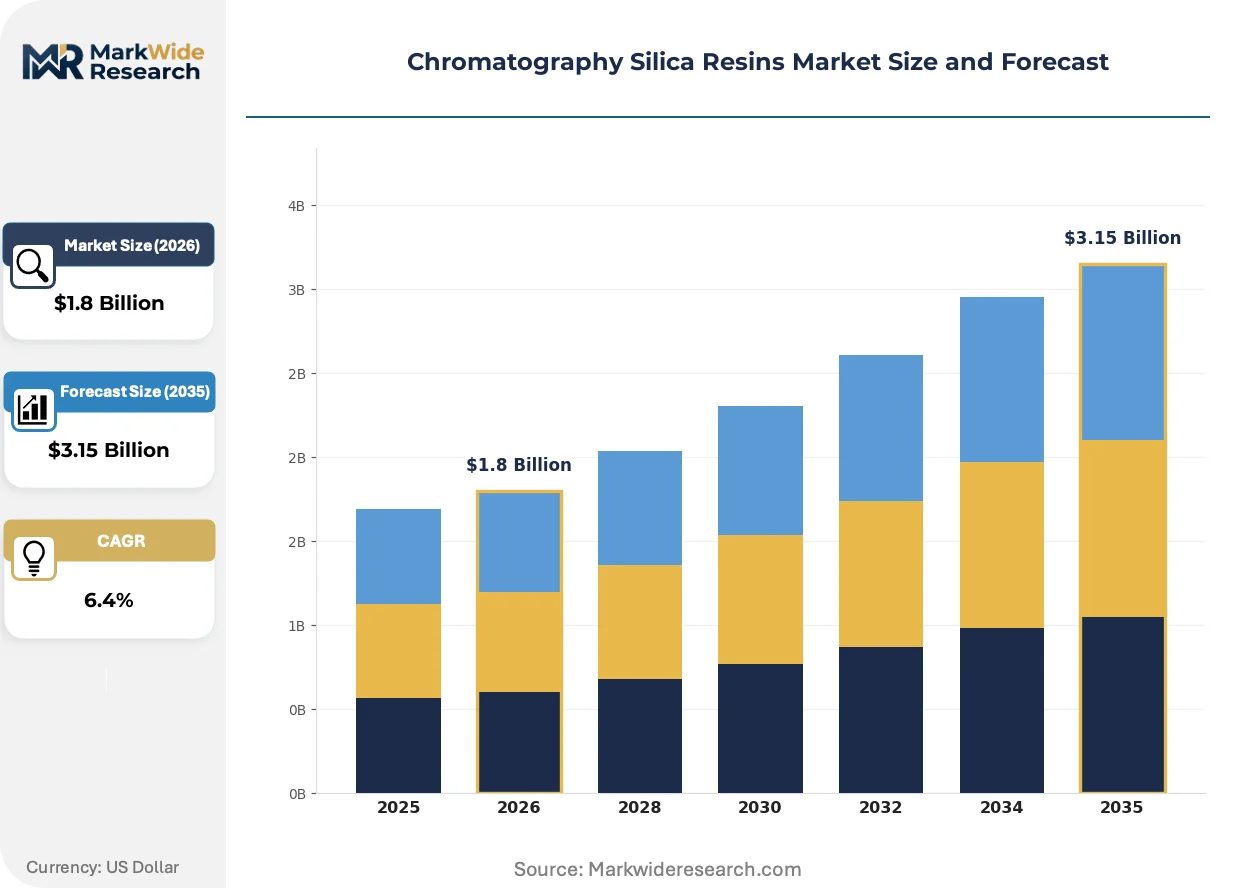
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium Silica, Hard Silica, Functional Silica, Powdered Silica Application: Pharmaceuticals, Biotech, Food & Beverage, Environmental Testing Form: Bulk Powder, Pre-Packed Columns, Media Kits, Resins End User: Research Laboratories, Quality Control Labs, Educational Institutions, Industry Manufacturers |
| Companies Covered | W.R. Grace and Company, Osaka Soda Co. Limited, Merck KGaA, Alfa Aesar, SiliCycle Inc., Sorbead India, Sepax Technologies Inc., AGC Group, Sisco Research Laboratories Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromatography Silica Resins Market Emerging Trajectories
Preparative chromatography is migrating from batch elution toward continuous capture platforms, compressing resin cycle times and demanding particle architectures that withstand mechanical stress across thousands of regeneration cycles.
Surface functionalization chemistry is migrating from traditional C18 and amino modifications toward mixed-mode ligands that combine ion exchange and hydrophobic interaction sites. Biopharma process developers at contract manufacturing organizations are adopting these resins to reduce column count in multi-step purification trains. The technology is migrating from analytical method development into production-scale peptide and oligonucleotide workflows, enabling platform processes that slash validation overhead.
EMA's Medical Device Regulation framework now classifies certain chromatography columns as Class IIa devices when used in diagnostic manufacturing, imposing design dossier requirements on resin suppliers. European CMOs serving in-vitro diagnostic manufacturers must now maintain technical files documenting silica resin biocompatibility. The regulation is forcing resin producers to expand quality management systems beyond ISO 9001 into ISO 13485 medical device certification.
Biopharma procurement teams are consolidating resin specifications across global manufacturing networks, replacing site-specific formulations with corporate master agreements. Large molecule CMOs are pressuring suppliers to accept outcome-based qualification contracts that tie payment to batch consistency metrics. This pattern concentrates most visibly in Germany and the United States, where multi-site biologics manufacturers are rationalizing supplier panels to reduce audit burden.
Chromatography Silica Resins Market Segmentation
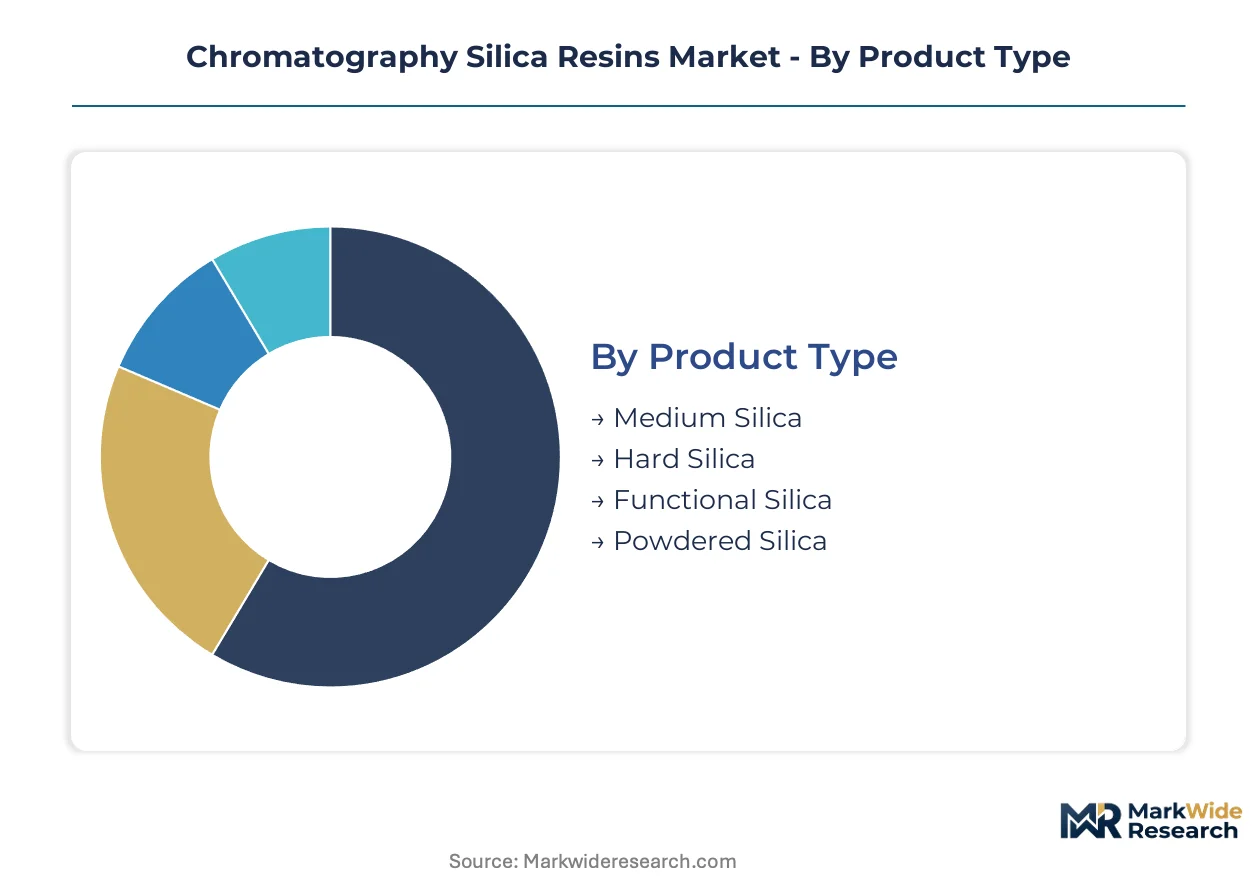
Segmentation in chromatography silica resins reveals how purification workflows diverge across pressure tolerances, surface chemistries, and packaging formats. Procurement cycles vary dramatically between bulk powder for process development and pre-packed columns for GMP manufacturing.
Product Type:
Functional silica turns inventory fastest in peptide and oligonucleotide workflows, while hard silica cycles slowest due to extended validation timelines in high-pressure systems.
- Functional Silica:Surface-modified particles bearing C18, amino, cyano, or mixed-mode ligands enable selective biomolecule capture. Biopharma contract manufacturers in Germany and the United States concentrate procurement here for monoclonal antibody and gene therapy purification, driven by FDA and EMA extractables validation requirements that lock in supplier relationships.
- Hard Silica:Dense, non-porous matrices engineered for mechanical stability above 100 bar operation. Osaka Soda Co. Limited anchors supply for simulated moving bed continuous chromatography systems, where cyclic loading durability determines resin replacement cycles.
- Medium Silica:Intermediate porosity materials balancing surface area with pressure drop characteristics. Academic and early-stage process development labs favor this grade for method scouting.
- Powdered Silica:Unfunctionalized raw material for in-house surface modification or non-critical separations. Lowest price point segment with minimal regulatory documentation.
Functional silica anchors the volume base while hard silica gains share at the steepest rate as continuous processing adoption accelerates.
Application:
Cost tier separation is pronounced: biotech commands premium pricing for GMP-grade materials while environmental testing operates at commodity economics.
- Pharmaceuticals:Small-molecule active pharmaceutical ingredient purification drives baseline demand for standard reversed-phase grades. FDA cGMP compliance mandates dominate procurement specifications, with lot-to-lot consistency requirements extending supplier qualification timelines.
- Biotech:Viral vector, mRNA, and gene therapy manufacturing requires resin volumes orders of magnitude above traditional batches. EMA's REACH substance registration framework creates supplier lock-in for European CMOs serving parenteral biologics.
- Food & Beverage:Natural product isolation and contaminant detection applications. Less stringent purity requirements permit broader supplier qualification.
- Environmental Testing:Pesticide, PFAS, and pollutant analysis in water and soil matrices. Price-sensitive segment with high analytical throughput but low per-test resin consumption.
Pharmaceuticals maintains the largest installed base though biotech demonstrates the steepest expansion trajectory as gene therapy manufacturing scales.
Form:
Customer type dictates packaging: bulk powder serves method development while pre-packed columns dominate validated manufacturing.
- Pre-Packed Columns:Ready-to-use formats with validated performance certificates and extractables documentation. Biopharma quality control labs and CMOs standardize on these to eliminate packing variability and reduce batch release timelines.
- Bulk Powder:Unpackaged resin for self-packing or large-scale process development. Research laboratories and early-phase biotech process groups favor this form for flexibility in column dimension optimization.
- Media Kits:Standardized resin quantities paired with buffer systems and protocols. Educational institutions and method transfer groups value the reduced experimental design burden.
- Resins:Terminology overlap with bulk powder; typically denotes catalog-grade materials without column hardware. Industry manufacturers integrate these into captive packing operations.
Pre-packed columns capture the value pool while bulk powder retains volume leadership in discovery-phase applications.
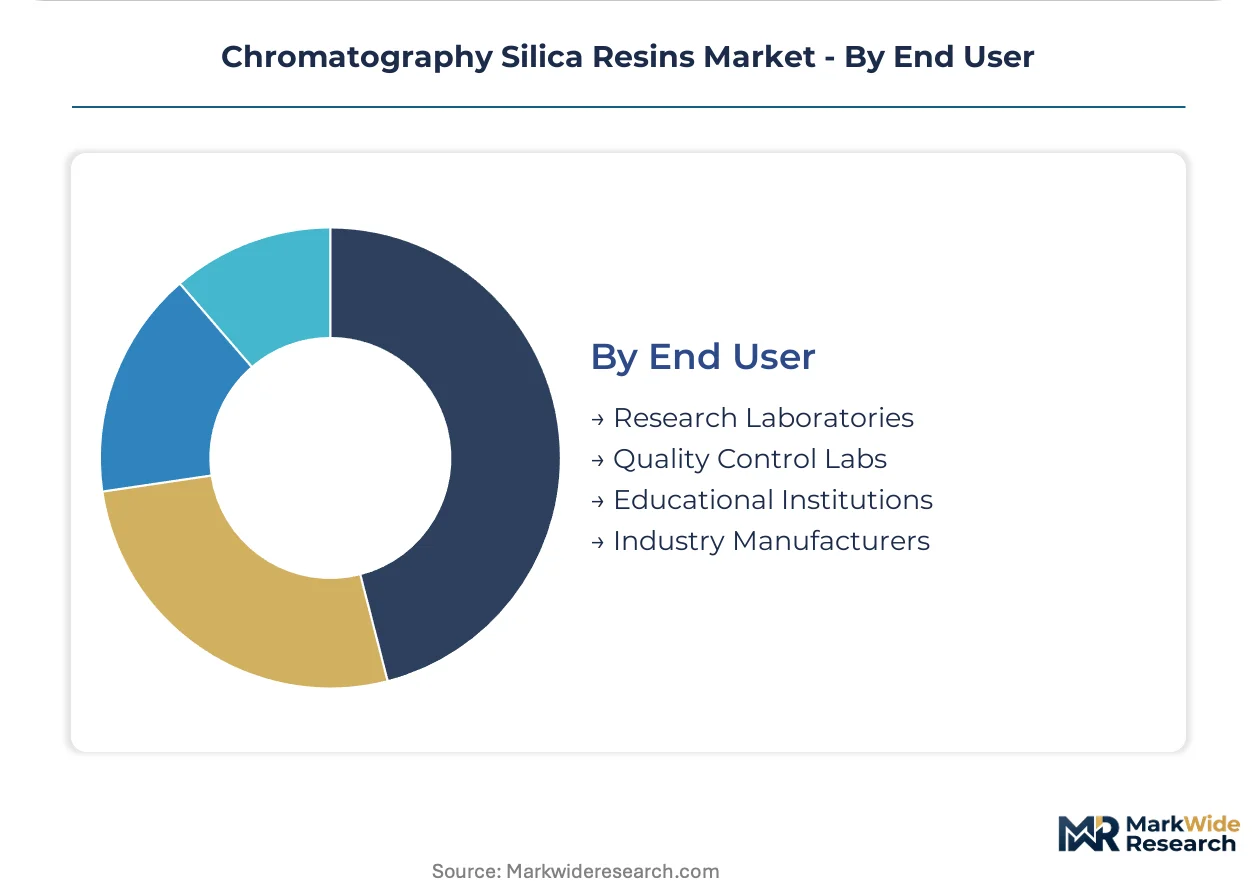
End User:
Procurement authority varies: industry manufacturers hold multi-year supply agreements while educational institutions purchase through distributor catalogs.
- Industry Manufacturers:Biopharma, diagnostic, and fine chemical producers with validated supply chains and audit requirements. FDA and EMA regulatory submissions drive resin specification rigidity and supplier consolidation.
- Quality Control Labs:Analytical testing facilities requiring consistent batch performance for release assays. ISO 17025 accreditation demands documented resin traceability.
- Research Laboratories:Academic and government institutions with flexible sourcing and price sensitivity. Method development focus prioritizes technical support over regulatory documentation.
- Educational Institutions:Teaching labs with standardized curriculum requirements. Lowest specification tier with emphasis on safety data sheet availability and hazard communication.
Industry manufacturers dominate absolute consumption while quality control labs expand most quickly as in-process testing requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German silica resin manufacturers export high-purity functional grades to United States biopharma contract manufacturers, establishing the dominant transatlantic trade corridor in chromatography materials.
United States
FDA cGMP mandates for injectable biologics drive demand for validated extractables documentation among Boston and San Francisco biotech clusters. The agency's risk-based material qualification protocols compress supplier approval timelines. Greater Boston anchors contract manufacturing scale-up for gene therapy viral vector purification.
Germany
EMA REACH substance registration requirements lock European pharmaceutical manufacturers into certified resin supply relationships. ECHA traceability frameworks impose lot-to-lot consistency obligations on silica suppliers. North Rhine-Westphalia concentrates multi-site biologics manufacturing rationalizing supplier panels to reduce audit burden.
Japan
PMDA pharmaceutical manufacturing standards align with ICH Q7 guidelines governing chromatography resin validation. METI industrial policy supports domestic silica precursor supply security for high-pressure chromatography systems. Osaka anchors specialized hard silica production for simulated moving bed continuous processing platforms.
India
CDSCO streamlined biosimilar approval pathways attract multinational contract manufacturing organizations requiring validated resin supply chains. DGFT import documentation frameworks govern silica resin customs clearance for pharmaceutical applications. Maharashtra biotech parks scale downstream processing capacity for export-oriented biologics production.
Switzerland
Swissmedic pharmaceutical manufacturing inspections enforce resin extractables validation for parenteral drug contact materials. The country's precision chemical sector maintains specialty silica modification capabilities for peptide purification workflows. Basel pharmaceutical cluster demands pre-packed column formats with certified performance documentation.
Chromatography Silica Resins Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Three manufacturers concentrate over seventy percent of high-purity spherical silica capacity, creating single-source vulnerability for contract manufacturer qualification programs. Strategic archetypes divide between integrated life sciences conglomerates, specialized silica matrix engineers, and regional catalog suppliers. Competitive moves center on backward integration into sol-gel precursor supply and outcome-based qualification contracts tying payment to batch consistency metrics.
Within the integrated conglomerate tier, Merck KGaA and W.R. Grace and Company anchor supply relationships through captive life sciences platforms and manufacturing scale networks respectively. Osaka Soda Co. Limited occupies the specialized engineering position for high-pressure operation matrices. These three exemplify how geographic concentration in Germany and Japan shapes competitive positioning around regulatory certification depth rather than price differentiation.
| Leading Market Players |
|---|
| W.R. Grace and Company |
| Osaka Soda Co. Limited |
| Merck KGaA |
| Alfa Aesar |
| SiliCycle Inc. |
| Sorbead India |
| Sepax Technologies Inc. |
| AGC Group |
| Sisco Research Laboratories Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
North Rhine-Westphalia's high-purity spherical silica production cluster anchors global supply capacity, concentrating pricing leverage among German manufacturers who command premium positioning in FDA-validated resin tiers. Contract manufacturing organizations in Boston and Basel face compressed procurement timelines as this geographic concentration limits alternative sourcing for cGMP-grade functional silica.
Pricing Analysis
Cost-plus contracts with tetraethyl orthosilicate indexation dominate long-term supply agreements between resin manufacturers and biopharma contract manufacturers. Three-tier pricing structure across GMP-certified premium, ISO-validated standard, and research-grade economy levels separates procurement tiers by extractables documentation depth. Pricing pressure stems from semiconductor-grade silicon metal volatility transmitting into sol-gel precursor costs. Academic and early-stage biotech laboratories exhibit highest price sensitivity, while viral vector manufacturers accept premium positioning for lot-to-lot consistency guarantees.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from German and Japanese manufacturers lock European and North American contract manufacturers into multi-year procurement relationships. Production concentrates in Germany, Japan, and the United States, with tetraethyl orthosilicate, high-purity silicon metal, and functionalization reagents as critical feedstocks. Single-source vulnerability pervades high-pressure hard silica grades where Osaka's specialized capacity lacks qualified alternatives. Distribution runs through direct technical sales teams for GMP tiers and distributor networks for research-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chromatography silica resins market is recovering from a cyclical trough driven by gene therapy manufacturing capital deployment waves. Biopharma capacity buildouts for viral vector production are pulling resin demand through a sustained expansion phase.
For Market Incumbents: Insulate qualification relationships by embedding field application scientists within contract manufacturing organizations to accelerate method transfer timelines. Backward integration into sol-gel precursor production reduces exposure to semiconductor-grade silicon metal volatility. Protein A resin substitution in monoclonal antibody capture threatens silica-based ion exchange volumes, demanding defensive positioning in oligonucleotide and peptide purification workflows where mixed-mode ligands retain technical superiority.
For New Entrants and Emerging Players: Build out extractables validation capabilities to serve Indian biopharma manufacturing expansion where CDSCO pathways attract multinational CMOs requiring certified supply chains. Wide-pore silica for synthetic RNA manufacturing represents the most penetrable white space, with 20-mer to 100-mer separation specifications still lacking established platform suppliers. Target pre-packed column formats with disposable flow path integration as the go-to-market angle, offering resin-as-a-service distribution models that reduce customer capital burden.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized silica matrix engineers with ISO 13485 medical device certification depth over commodity producers. Long-term viability hinges on continuous processing adoption sustaining demand for cyclic-loading durable resins. Acquisition targets should demonstrate validated supplier relationships with European CMOs serving EMA-registered parenteral biologics. Watch EMA guidance on continuous manufacturing as the signal for accelerated resin lifecycle validation protocol changes that would favor incumbent technical service capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sol-Gel Precursors | Captive tetraethyl orthosilicate supply insulates margin from semiconductor-grade silicon metal volatility. |
| ISO 13485 Medical Device Certification | EMA MDR classification of diagnostic chromatography columns creates regulatory barrier for uncertified competitors. |
| Pre-Packed Column Format Expansion | Disposable flow path convergence opens resin-as-a-service models reducing CMO capital deployment. |
| Field Application Scientist Embedding | Onsite extractables validation support compresses multi-year supplier qualification timelines for FDA submissions. |
| Wide-Pore Silica Capacity Addition | Synthetic RNA manufacturing scales demand engineered pore architectures for 20-mer to 100-mer separation. |
Methodological Framework
A spread of perspectives from biopharma process development directors, regulatory affairs specialists, contract manufacturing procurement leads, and chromatography equipment engineers converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation through FDA cGMP guidance documents, EMA REACH substance registration databases, USP <665> and <1665> extractables protocols, and SEC filings from listed life sciences conglomerates. Bottom-up resin volume estimates from individual biopharma manufacturing facilities triangulated against top-down chromatography media market assessments.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling functional silica, hard silica, medium silica, and powdered silica grades against pharmaceutical, biotech, food and beverage, and environmental testing applications. Segmentation by product type, application, form, and end user informed volume allocation, with CAGRs derived from regression analysis of historical biopharma capital expenditure cycles and gene therapy manufacturing capacity announcements. Forecast inputs incorporated EMA continuous manufacturing guidance evolution and CDSCO biosimilar approval pathway throughput.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by semiconductor materials suppliers or disruptive entrants from Indian specialty chemical manufacturers would shift outcomes. Macroeconomic contraction in biotech venture financing, regulatory delays in gene therapy approvals, or technological breakthroughs in membrane-based purification alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Global Black Masterbatch Market
Specialty Compounds
Potassium Derivatives Market
Specialty Compounds
Plasma Powder Market
Specialty Compounds
Phenylacetyl Chloride Market
Specialty Compounds
GCC Specialty Chemicals Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Spackling Paste Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
Organosulfur Compounds Market
Specialty Compounds
Polypeptide Market
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Global Engineering Plastic Compounds Market
Specialty Compounds
Strontium Chloride Market
Specialty Compounds
North America Lithium Compound Market