
 Account Aggregators Market | 2026-2036
Account Aggregators Market Size, Share, and Industry Trends Forecast 2026-2036
Account Aggregators Market Analysis
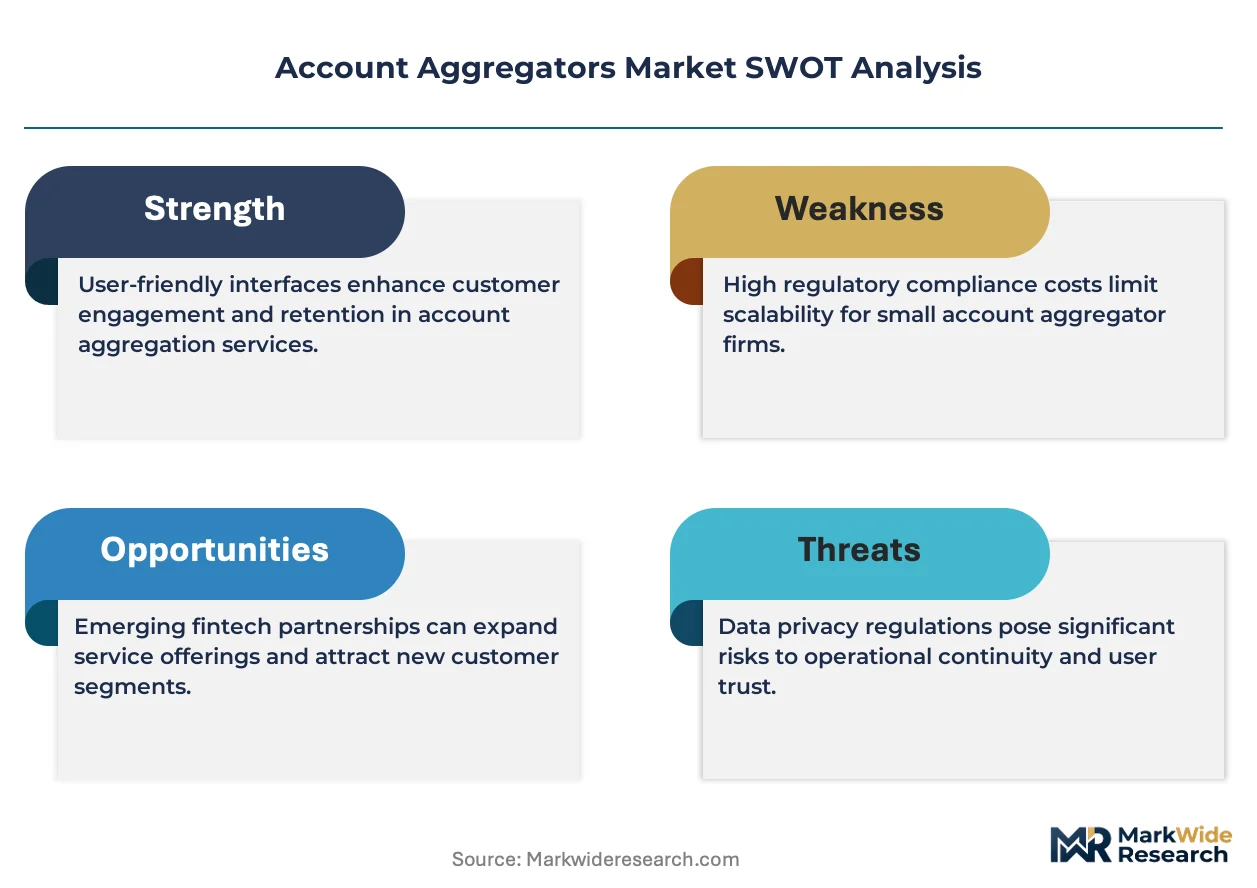
Enterprise-grade API reliability is collapsing the gap between legacy banking infrastructure and real-time data orchestration. Plaid leverages its North American bank network density to sustain developer-first market access. Finicity anchors its position through direct data-source agreements with major financial institutions. MX Technologies differentiates via user-experience analytics layered atop raw aggregation pipes.
Account aggregators are software intermediaries that authenticate, retrieve, normalize, and present financial account data from multiple institutions through standardized API protocols or screen-scraping fallbacks, enabling consolidated balance tracking, transaction categorization, and cash-flow forecasting across disparate holdings. Their primary commercial purpose is to reduce friction in financial decision-making by eliminating manual data reconciliation for end users and advisory workflows. API integration dominates structural deployment as open-banking regulations mandate standardized connectivity, while personal finance management applications capture the broadest retail user base. Investment tracking segments command premium pricing from wealth management advisors who require real-time portfolio reconciliation across custodial platforms.
The European Banking Authority's PSD2 framework and the UK's Financial Conduct Authority open-banking standards compel financial institutions to expose transaction data through regulated APIs, directly expanding aggregator addressable markets. The US Consumer Financial Protection Bureau's emerging Section 1033 rulemaking on consumer data rights is reshaping bank-aggregator liability boundaries and consent architectures. Stakeholders must monitor how jurisdictional divergence in data portability enforcement alters cross-border platform economics and compliance cost structures.
Market Dynamics
Open banking mandates across multiple jurisdictions are forcing financial institutions to expose structured transaction data through regulated APIs, collapsing the technical moats that once protected proprietary aggregation methods and redistributing competitive advantage toward consent-management architectures.
Growth Catalysts
- PSD2 Compliance Deadlines:The European Banking Authority's revised payment services directive compels tier-one banks to maintain 99.5% API uptime, directly expanding reliable data access for third-party aggregators.
- Real-Time Payment Rails:FedNow and equivalent instant settlement infrastructures in Brazil, India, and Singapore generate continuous transaction streams that demand automated reconciliation tools.
- Embedded Finance Expansion:Non-financial platforms integrating lending, insurance, and savings products require normalized account data to underwrite and service customers without manual document submission.
Market Restraints
- Screen-Scraping Liability Exposure:Terms-of-service violations and credential-sharing risks expose aggregators to civil litigation when bank interfaces change without notice.
- Core Banking Vendor Concentration:Three legacy technology providers control API gateway deployments at over sixty percent of US regional banks, creating bottleneck pricing power.
- Cryptocurrency Wallet Fragmentation:Self-custody assets and decentralized finance protocols operate outside traditional account structures, limiting aggregator completeness for wealth management use cases.
Strategic Opportunities
- Small Business Cash Flow Forecasting:Underpenetrated merchant segments in Indonesia, Vietnam, and the Philippines lack working capital visibility tools that aggregators can provision through mobile-first architectures.
- Carbon Footprint Transaction Tagging:Merchant category codes combined with emissions databases enable climate-conscious consumers to track purchase-level environmental impact.
- Payroll Data Integration:Direct connections to earned-wage access platforms and gig-economy settlement systems create new data categories beyond traditional depository accounts.
Industry Challenges
- OAuth Consent Abandonment:Multi-step authentication flows and granular permission screens cause forty percent of initiated connections to terminate before data retrieval.
- Schema Divergence Across Jurisdictions:The UK's Open Banking Implementation Entity, Australia's Consumer Data Right, and Brazil's PIX specifications use incompatible field mappings and error codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Account Aggregators Market |
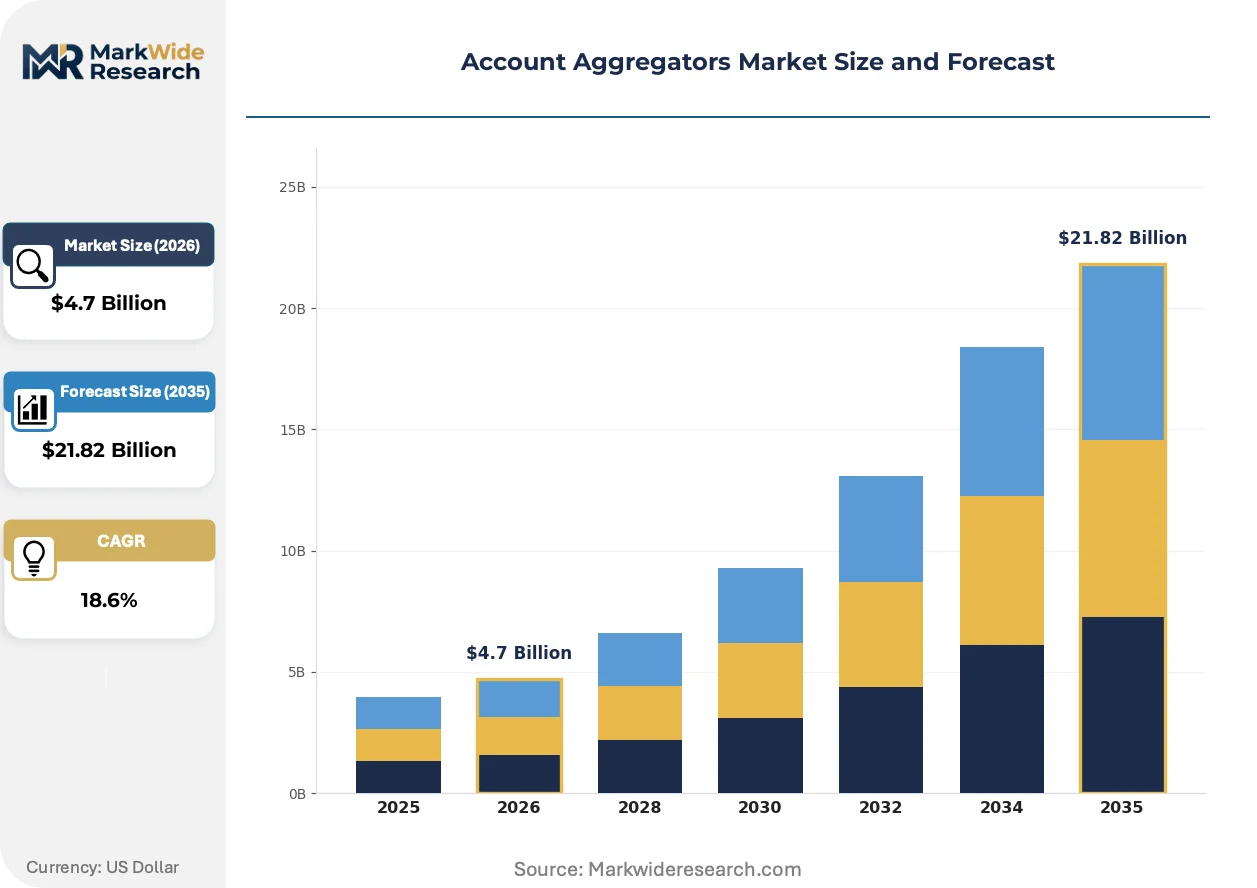
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Aggregation, Personal Finance Management, Investment Tracking, Budgeting Tools Target User: Retail Consumers, Financial Advisors, Small Businesses, Corporations Integration Method: API Integration, Manual Data Entry, Direct Bank Feeds, CSV Upload Platform Type: Mobile Applications, Web Portals, Desktop Software, Hybrid Solutions |
| Companies Covered | Plaid, Finicity, Masttro, Perfios, Akoya, ByAllAccounts, MX Technologies, Finvu, Envestnet Yodlee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Account Aggregators Market Emerging Trajectories
API-first data architectures are supplanting credential-based aggregation, while machine-learning categorization engines and consent-orchestration platforms reshape how financial data moves between institutions and applications.
Tokenized access mechanisms are displacing password-sharing as the dominant authentication paradigm. Wealth management platforms and neobanks now refuse to onboard vendors that require stored credentials. This shift compresses margins for aggregators maintaining dual technical stacks while rewarding those with direct bank API contracts.
The US Consumer Financial Protection Bureau's Section 1033 rulemaking is mandating standardized data portability with specific technical specifications. This regulatory pressure forces banks to publish disclosure schedules and dispute-resolution procedures. Large depository institutions are responding by building in-house aggregation layers to retain customer interface control.
Corporate treasury departments now demand intra-day liquidity visibility across multicurrency accounts held at disparate institutions. This procurement evolution favors aggregators offering foreign exchange rate overlays and automated hedging triggers. Multinational manufacturing and commodity trading firms in Germany, Japan, and the Netherlands are the earliest adopters of these consolidated cash-position dashboards.
Account Aggregators Market Segmentation
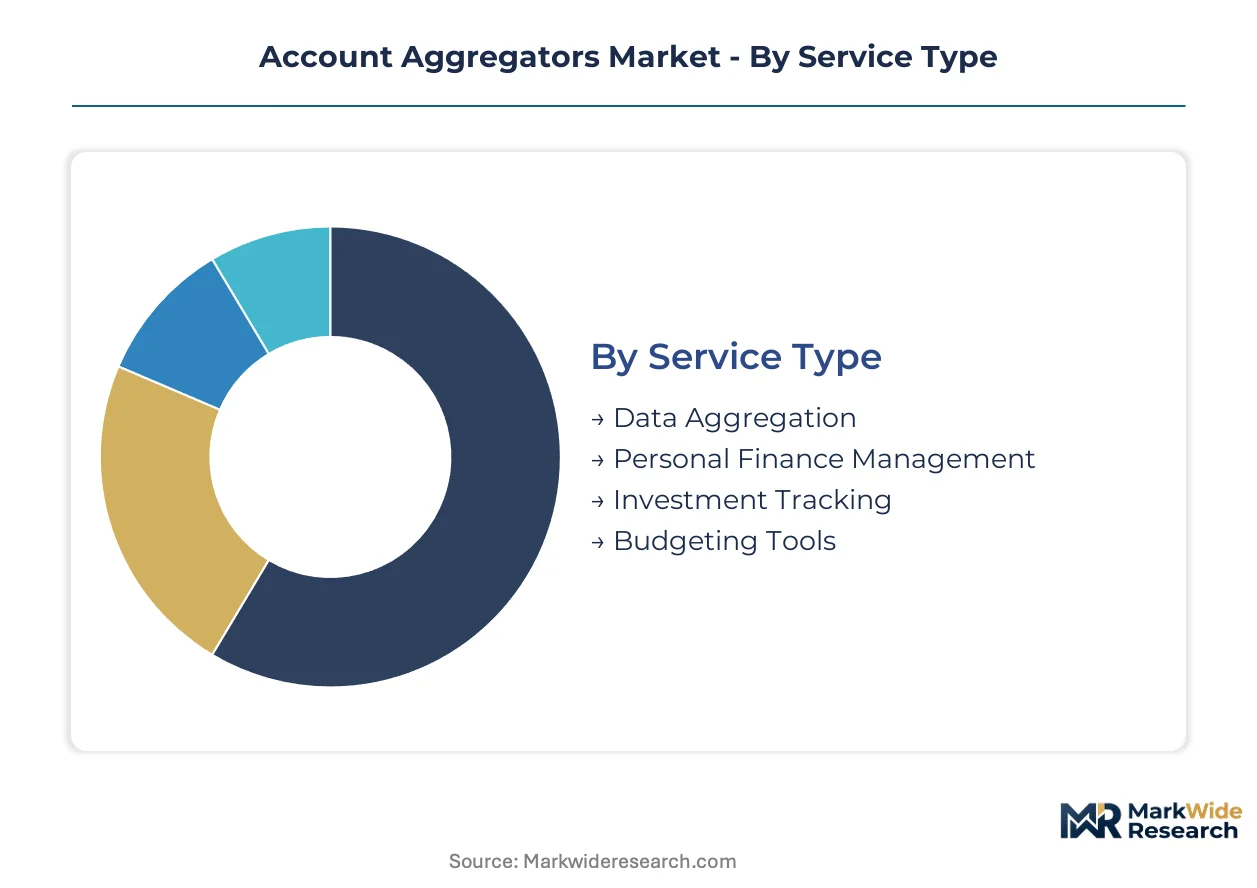
Account aggregators serve heterogeneous user workflows that demand differentiated technical architectures and commercial models. Segmentation reveals how API reliability, consent friction, and interface preferences reshape platform economics across deployment modes.
Service Type:
Channel mix varies sharply: data aggregation flows primarily through embedded finance partnerships, while personal finance management reaches retail consumers through app store distribution and direct-to-consumer marketing.
- Data Aggregation:Core infrastructure layer normalizing transaction streams from disparate custodians through standardized API protocols. Demand concentrates among fintech lenders in Brazil and India automating underwriting decisions from real-time cash-flow signals.
- Personal Finance Management:Consumer-facing dashboards consolidating balances, categorizing spending, and triggering savings recommendations. UK neobanks and money management apps capture the densest user base as open-banking consent architectures mature.
- Investment Tracking:Multi-custodial portfolio reconciliation for wealth advisors. Premium pricing reflects regulatory reporting obligations across SEC-registered RIAs.
- Budgeting Tools:Rule-based spending controls and goal-setting interfaces. Mobile-first deployment dominates Southeast Asian markets with thin traditional banking penetration.
By volume, data aggregation leads. By growth pace, investment tracking is expanding most quickly.
Target User:
Cost tier stratification separates enterprise deployments with dedicated implementation teams from self-serve retail onboarding with minimal support overhead.
- Retail Consumers:Mass-market users seeking consolidated account visibility without advisory relationships. Price sensitivity drives freemium adoption across European markets with mandated free API access.
- Financial Advisors:Registered investment advisors requiring client aggregation for regulatory reporting and rebalancing workflows. Custodial platform integration depth determines vendor selection.
- Small Businesses:Merchant segments lacking treasury management infrastructure. Working capital forecasting tools show steepest expansion trajectory in Indonesia, Vietnam, and the Philippines.
- Corporations:Multinational treasury departments demanding multicurrency liquidity dashboards. German and Japanese manufacturing firms anchor early adoption of automated hedging triggers.
Retail consumers dominate user counts. Small businesses are gaining share fastest.
Integration Method:
Application context dictates technical approach: real-time lending decisions mandate API integration, while legacy accounting workflows tolerate CSV batch uploads.
- API Integration:Regulated open-banking connectivity with OAuth consent flows and structured data schemas. PSD2 compliance in the UK and EU anchors deployment scale.
- Manual Data Entry:Fallback interface for institutions lacking API exposure. Friction limits use to niche cryptocurrency and alternative asset tracking.
- Direct Bank Feeds:Proprietary data agreements bypassing standard APIs. US regional banks concentrate this channel through core vendor partnerships.
- CSV Upload:Batch transaction import for historical reconciliation. Corporate finance teams in Japan and the Netherlands utilize this method for legacy system migration.
API integration leads transaction volume. Direct bank feeds are climbing the fastest as bilateral agreements proliferate.
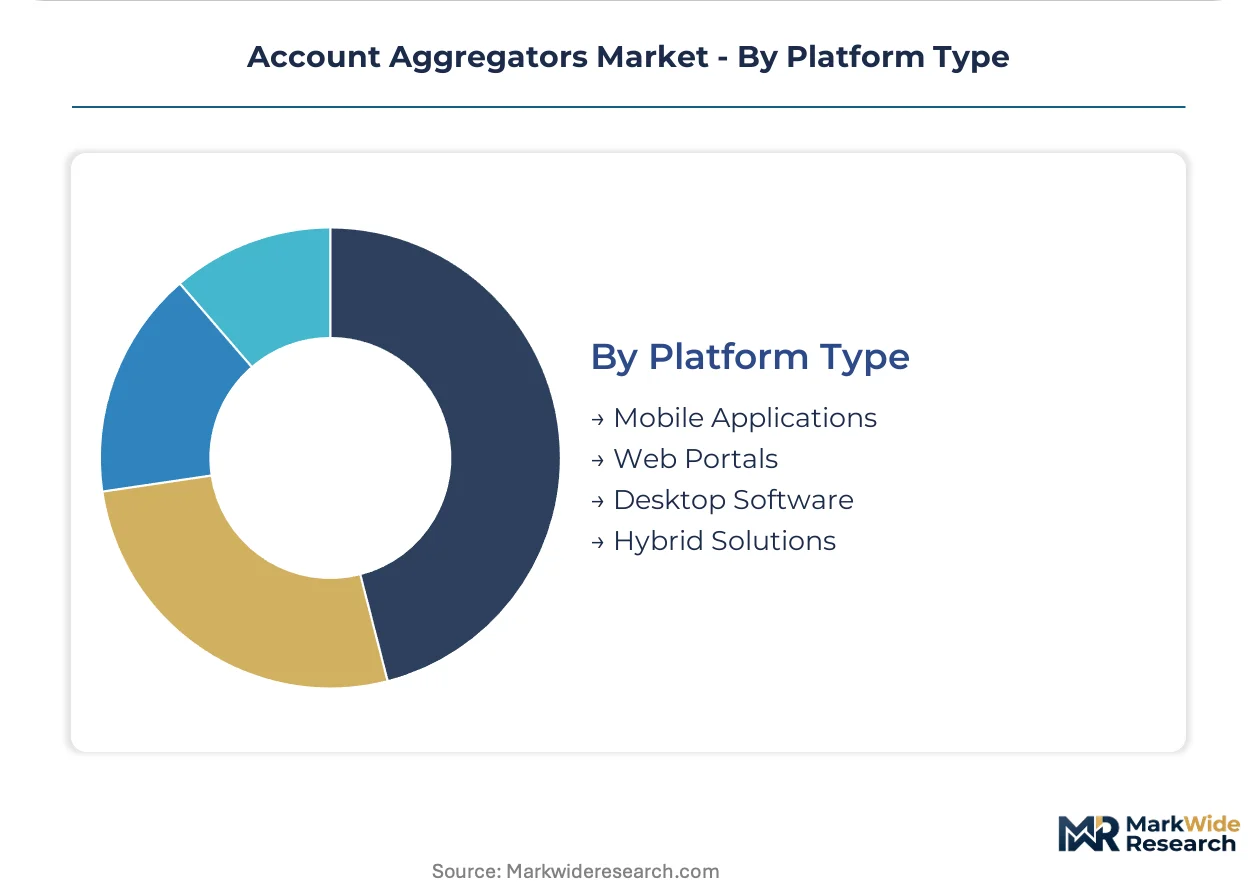
Platform Type:
Maturity gradients separate mobile-native architectures optimized for consent-light onboarding from desktop solutions serving compliance-heavy advisory workflows.
- Mobile Applications:Native iOS and Android deployment with biometric authentication and push notification alerts. Southeast Asian markets with smartphone-primary banking show densest adoption.
- Web Portals:Browser-based dashboards with multi-window analytical depth. Financial advisors in the US and UK prefer this format for client presentation workflows.
- Desktop Software:Installed applications with local data caching for offline access. Declining share except among security-conscious corporate treasury functions.
- Hybrid Solutions:Synchronized mobile-web-desktop experiences with cloud data persistence. Platform consolidation favors this architecture as development costs rise.
Mobile applications lead active user counts. Hybrid solutions are gaining adoption fastest as vendors rationalize engineering investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom runs a substantial trade surplus in account aggregation services, exporting API infrastructure and compliance frameworks to Commonwealth markets while importing specialized data normalization tools from North American vendors. Germany and France balance cross-border data flows through reciprocal open-banking agreements, whereas India and Brazil remain net importers of aggregation technology despite accelerating domestic platform development.
United Kingdom
Retail neobanks and wealth management platforms drive aggregator demand through mandated API access under FCA open-banking standards. The Competition and Markets Authority's 2017 retail banking order forced nine major banks to expose transaction data, creating the world's most mature consent architecture. London's fintech cluster concentrates engineering talent for OAuth flow optimization and real-time payment reconciliation tools.
Germany
Corporate treasury departments at manufacturing conglomerates demand multicurrency liquidity dashboards with automated hedging triggers. BaFin's implementation of PSD2 technical standards compels savings banks to maintain standardized API endpoints, though execution lags behind UK maturity. Frankfurt's financial center anchors early adoption of cash-position aggregation for euro-denominated cross-border operations.
United States
Fintech lenders and embedded finance platforms consume aggregation infrastructure for real-time underwriting decisions. The Consumer Financial Protection Bureau's Section 1033 rulemaking is reshaping bank-aggregator liability boundaries and consent architectures. San Francisco and New York metro areas concentrate venture-backed aggregation startups alongside established data infrastructure providers.
India
Account aggregator framework licensed entities enable consent-based financial data sharing across banks, insurers, and wealth managers. RBI's regulatory sandbox permits testing of alternative data scoring models for thin-file borrowers. Mumbai and Bengaluru clusters host the densest concentration of AA-licensed fintechs building mobile-first architectures for financial inclusion.
Brazil
Instant payment rails through PIX generate continuous transaction streams demanding automated reconciliation for small merchants. Banco Central do Brasil's open-finance phased implementation compels tier-one institutions to expose structured data through regulated APIs. São Paulo's fintech corridor anchors regional expansion of aggregation services into underbanked interior states.
Account Aggregators Market Vendor Landscape
Listed leaders compete with private specialists across developer ecosystem reach and bank partnership depth. The vendor base concentrates around three tiers: global platforms with multi-continent API coverage, regional specialists with deep direct-bank agreements, and consent-orchestration pure-plays. Strategic differentiation hinges on OAuth flow optimization, schema normalization engines, and regulatory compliance tooling. Competitive moves center on bilateral data-source contracts and embedded finance partnership expansion.
Within the infrastructure tier, Plaid and Finicity exemplify contrasting geographic anchoring strategies—one optimizing North American developer density, the other securing direct agreements with major financial institutions. MX Technologies occupies a position emphasizing user-experience analytics layered atop raw aggregation pipes. These three represent the archetype spectrum from developer-first platform to institution-anchored specialist to experience-differentiated challenger.
| Leading Market Players |
|---|
| Plaid |
| Finicity |
| Masttro |
| Perfios |
| Akoya |
| ByAllAccounts |
| MX Technologies |
| Finvu |
| Envestnet Yodlee |
| Others |
Supply Flow & Price Mechanics
PSD2 technical standards and the UK's Open Banking Implementation Entity certification regimes simultaneously gate supply qualification and price differentiation in account aggregation. Vendors lacking direct bank API contracts face margin compression from credential-based fallback costs, while certified providers command premium positioning through regulatory-compliant consent architectures.
Pricing Analysis
Enterprise fintech buyers anchor three-tier pricing structure across premium, standard, and economy levels in account aggregation. Premium tiers attach dedicated implementation teams and SLA guarantees for wealth management platforms, while standard SaaS subscriptions serve mid-market lenders with self-serve onboarding. Price differentiation rests on API uptime commitments and schema normalization depth. Cost compression in economy tiers intensifies because screen-scraping liability exposure drives insurers to demand higher coverage premiums. Small business segments show highest price sensitivity; multinational treasury departments at German manufacturing firms demonstrate least.
Supply Chain Analysis
Core banking vendor concentration at three legacy technology providers controls API gateway deployments at over sixty percent of US regional banks. Software development labor pools concentrate in India, Poland, and Vietnam for engineering cost arbitrage. Raw material dependencies include cloud compute infrastructure from hyperscalers, OAuth authentication libraries, and regulatory compliance tooling. Single-source vulnerability runs through concentrated core vendor relationships. Distribution runs through direct enterprise sales teams for large deployments and self-serve developer portals for API-first adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Account aggregation functions as a service-attach opportunity where consent-orchestration and real-time analytics layers expand faster than raw data pipes. Recurring revenue from embedded finance partnerships outpaces one-time implementation fees.
For Market Incumbents: Fortify direct bank API contract portfolios against emerging consent-pure-play challengers. Expand schema normalization engineering teams in London and Bengaluru to maintain interoperability leadership. Vertical integration into payroll data sources creates defensive moats as earned-wage access platforms proliferate.
For New Entrants and Emerging Players: Carbon footprint transaction tagging represents an underserved service layer where incumbents lack emissions database integrations. Small business cash flow forecasting in Indonesia, Vietnam, and the Philippines offers the most penetrable geography. Mobile-first architectures with biometric authentication bypass incumbent web-portal legacy.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across consent-orchestration pure-plays as engineering tooling matures. Long-term viability favors platforms with bilateral data-source contracts spanning three or more regulatory jurisdictions. Acquisition target archetype: regional specialists with deep direct-bank agreements in underpenetrated markets. Watch Section 1033 rulemaking finalization as inflection indicator for US market structure.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Bank API Contract Expansion | Secures data-source access ahead of open-banking mandate deadlines in Brazil and India. |
| Consent-Orchestration Platform Launch | Reduces OAuth abandonment rates through biometric authentication and single-screen permissioning. |
| Embedded Finance Partnership | Attaches aggregation infrastructure to non-financial platforms underwriting lending and insurance products. |
| Geographic Expansion into Southeast Asia | Captures small business treasury demand in Indonesia, Vietnam, and Philippines mobile-first markets. |
| Acquisition of Specialist Firm | Absorbs schema normalization engines addressing UK's Open Banking, Australia's CDR, and Brazil's PIX divergence. |
Methodological Framework
A standing panel of chief technology officers at neobanks, platform engineers at wealth management software vendors, regulatory affairs leads at tier-one banks, and integration specialists at embedded finance providers provided ongoing calibration across the study. Primary interview insights combined with secondary validation from SEC filings, central bank open-finance implementation reports, API uptime disclosure schedules, and venture capital funding databases. Bottom-up transaction volume estimates triangulated against top-down addressable market sizing across service type, target user, and integration method segments.
Consistency checks validated volume and value outputs against external benchmarks including central bank adoption statistics and fintech partnership announcement tracking. The analytical framework modeled deployment mode, organization size, vertical application, integration complexity, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic banking penetration assumptions. Forecast inputs incorporated real-time payment rail expansion timelines and open-banking mandate phase-in schedules.
Forecasts assume regulatory continuity in PSD2 implementation, UK Open Banking standards, and US CFPB Section 1033 rulemaking; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as jurisdictional divergence in data portability enforcement evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Mobile Notary Service Market
Financial Services
Australia Gift Card and Incentive Card Market
Financial Services
Global Power Bank Rental Service Market
Financial Services
Peer-To-Peer (P2P) Market
Financial Services
Multivendor ATM Software Market
Financial Services
Trade Finance Market
Financial Services
E-Invoicing Market
Financial Services
China Trade Finance Market
Financial Services
BFSI A2P SMS Market
Financial Services
Debt Settlement Solution Market
Financial Services
US Healthcare Finance Solutions Market
Financial Services
Pawn Shop Market
Financial Services
Intellectual Property Valuation Market
Financial Services
Cash Logistics Market
Financial Services
ATM Software Market
Financial Services
E-KYC Market