
 Global Cryptocurrency Custody Software Market | 2026-2036
Global Cryptocurrency Custody Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cryptocurrency Custody Software Market Foresight
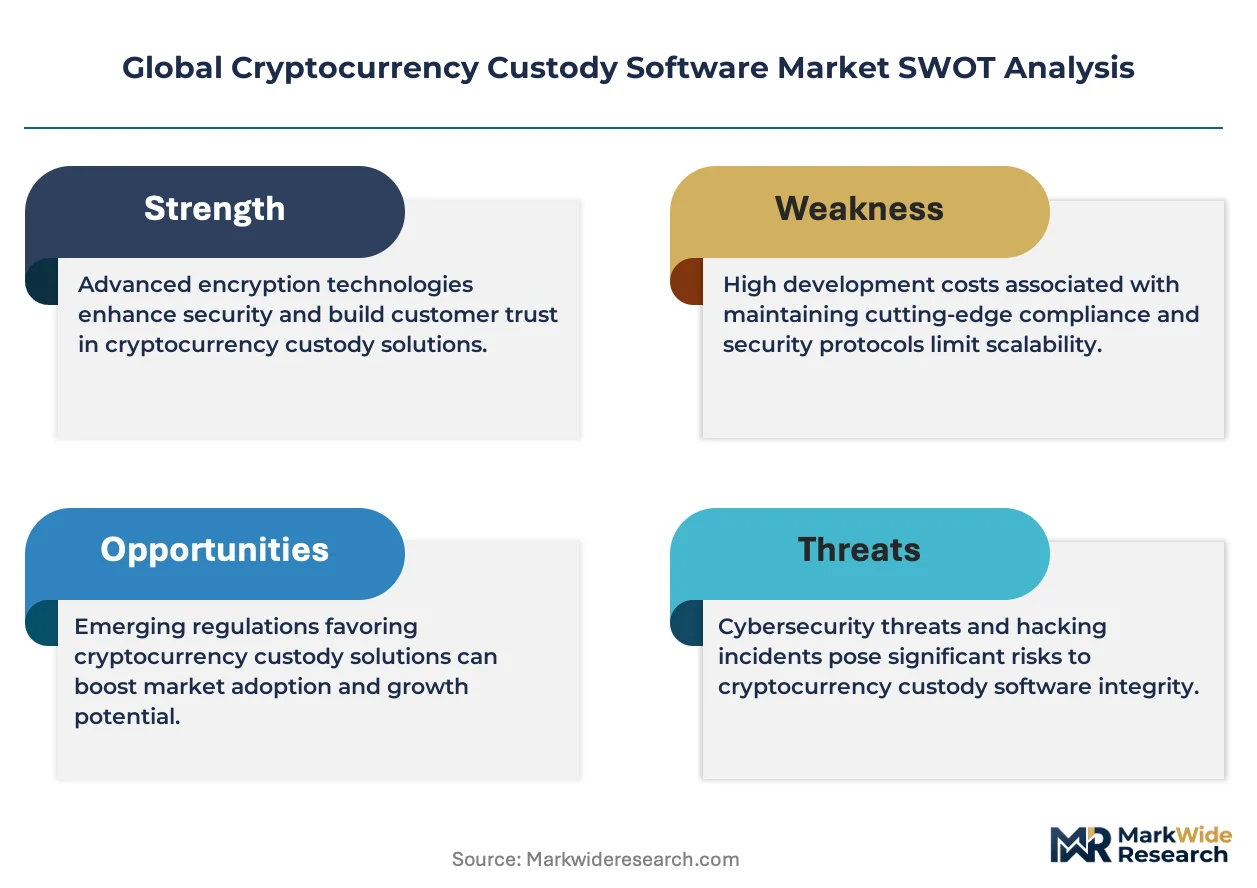
ISO 27001 certification is bifurcating the competitive landscape into qualified institutional-grade providers and excluded entrants. Fireblocks leverages multi-party computation patents to sustain technology leadership in transaction signing workflows. BitGo anchors its position through geographic dominance across North American exchange integrations. Coinbase Custody differentiates via regulatory licensing depth across multiple state money transmitter frameworks.
Cryptocurrency custody software encompasses cryptographic key management, cold storage orchestration, and policy-enforced transaction authorization systems engineered to protect private keys against theft, loss, or unauthorized access. The architecture typically integrates hardware security modules generating and storing keys within FIPS 140-2 Level 3 or higher certified physical enclosures, with software layers enforcing multi-signature quorum rules and real-time compliance monitoring. Cloud-based deployment configurations capture the fastest expansion trajectory as hedge funds and venture capital firms prioritize operational agility over physical infrastructure ownership. Hardware security modules within the solution type dimension command concentrated margin pools due to semiconductor supply constraints and certification complexity. Compliance solutions are accelerating as MiCA, SEC custody rule proposals, and Singapore MAS licensing requirements mandate auditable key control documentation.
The US SEC, European Banking Authority, and Monetary Authority of Singapore each impose distinct custody rule frameworks that reshape product roadmaps and market access eligibility. SEC staff accounting bulletins require qualified custodians to maintain exclusive possession of private keys, forcing software architecture redesigns for shared-control models. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether to build modular compliance engines or region-specific platform variants.
Market Dynamics
Multi-party computation architectures are fragmenting legacy hardware security module dependencies as institutional asset managers demand key recovery workflows without single points of failure. This technical shift forces custody software vendors to rebuild cryptographic stacks around distributed signing protocols.
Growth Catalysts
- MiCA Compliance Mandates:The European Union's Markets in Crypto-Assets framework requires auditable key control documentation, compelling asset managers to upgrade custody infrastructure ahead of enforcement deadlines.
- Singapore MAS Licensing:The Monetary Authority of Singapore's digital payment token service licensing regime attracts hedge fund administrators seeking regulatory clarity for Asia-Pacific fund structures.
- Institutional Onboarding Velocity:Pension fund trustees and endowment investment committees are mandating qualified custodian relationships before allocating to digital asset strategies.
Market Restraints
- Semiconductor Supply Constraints:FIPS 140-2 Level 3 certified hardware security modules face allocation bottlenecks from specialized foundry capacity concentrated in Taiwan and South Korea.
- Qualified Custodian Capital Requirements:The US SEC staff accounting bulletins impose net worth and insurance thresholds that exclude regional bank trust departments from digital asset custody.
- Interoperability Fragmentation:Proprietary key derivation paths across Ethereum, Bitcoin, and Solana force redundant infrastructure investment without unified signing standards.
Strategic Opportunities
- Brazilian Pension Fund Entry:Previdencia Privada regulators are drafting custody guidelines for complementary pension entities, opening Latin America's largest institutional capital pool.
- Decentralized Finance Integration:Smart contract-based lending protocols require non-custodial wallet interfaces that bridge institutional compliance engines with on-chain yield strategies.
- Carbon-Neutral Cold Storage:Renewable-powered data centers in Norway and Iceland attract environmental mandate-driven asset owners seeking custody with verified emissions profiles.
Industry Challenges
- Cryptographic Engineer Scarcity:Zero-knowledge proof implementation and secure multi-party computation protocol development require specialized talent pools concentrated at Israeli and Swiss academic institutions.
- State-by-State Licensing Complexity:US money transmitter licenses require separate applications across Wyoming, New York, and Texas, each with distinct surety bond and examination protocols.
- Legacy Core Banking Integration:Mainframe-based custody accounting systems at traditional trust banks lack API architectures for real-time blockchain balance reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cryptocurrency Custody Software Market |
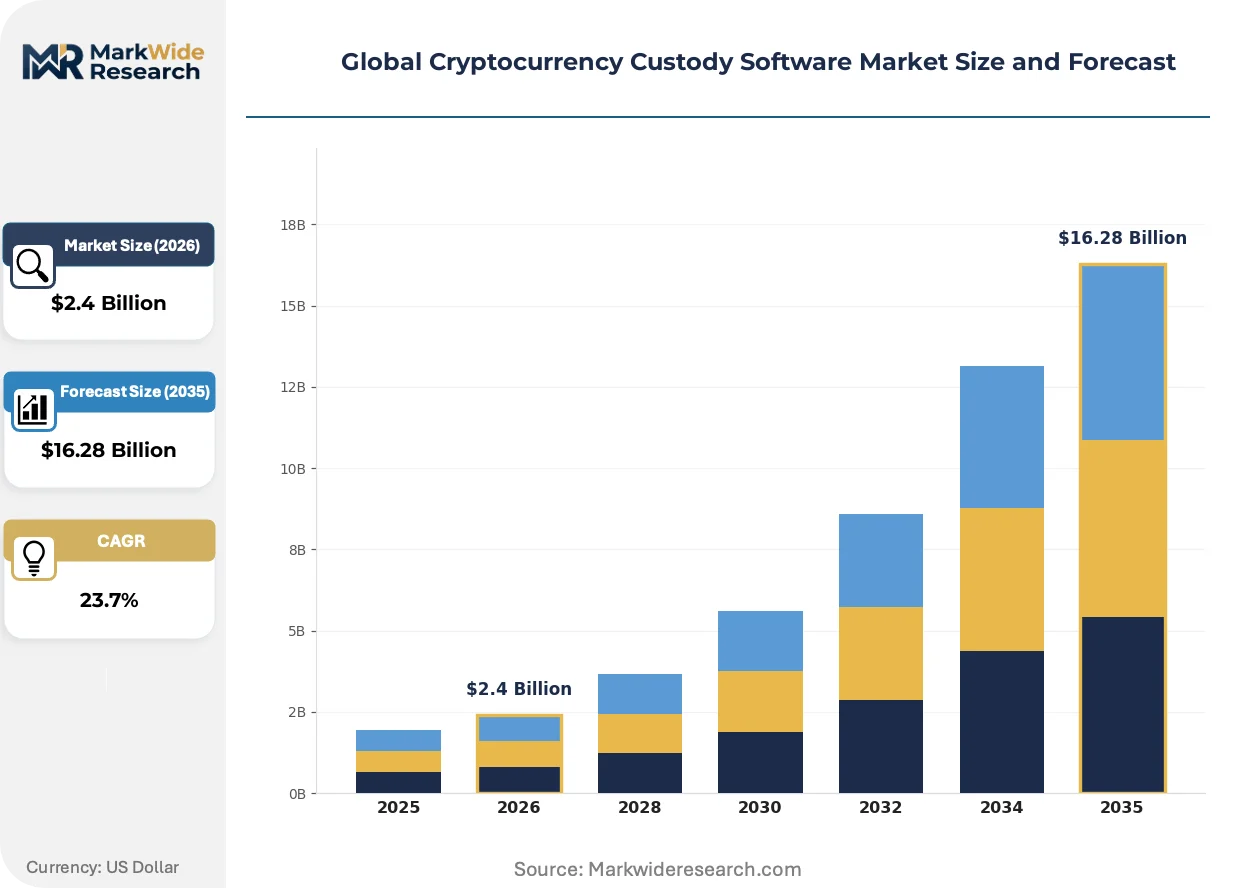
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $16.28 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services Solution Type: Multi-Signature Wallets, Hardware Security Modules, Key Management Systems, Transaction Analytics, Compliance Solutions Use Case: Digital Asset Protection, Institutional Trading, Compliance Monitoring, Secure Transaction Signing, Portfolio Management End User: Cryptocurrency Exchanges, Asset Managers, Hedge Funds, Family Offices, Venture Capital Firms |
| Companies Covered | Fidelity Digital Assets, Fireblocks, BitGo, Komainu, Zodia Custody, Coinbase Custody, Anchorage Digital, Cobo, Gemini Custody, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cryptocurrency Custody Software Market Shifts & Advancements
Software-defined custody architectures are supplanting appliance-centric delivery models as asset managers prioritize API-first integration over physical infrastructure ownership. This reconfiguration compresses deployment timelines and expands addressable buyer segments beyond mega-institutions.
Threshold signature schemes using distributed key generation are displacing traditional multi-signature wallet implementations across hedge fund prime brokerage relationships. Family offices with sub-hundred-million dollar allocations now access institutional-grade key protection without hardware procurement overhead. The technology is displacing incumbent wallet providers that built around HSM-centric architectures and annual hardware refresh cycles.
REACH chemical substance restrictions on semiconductor manufacturing inputs are extending hardware security module lead times for European custody software deployments. The European Chemicals Agency's candidate list updates force module vendors to reformulate encapsulant compounds and re-certify FIPS compliance. German and Swiss private banks are accelerating software-only custody evaluations to circumvent hardware supply uncertainty.
Subscription-based pricing for key management services is replacing perpetual license structures among venture capital fund administrators. Annual recurring revenue models align vendor incentives with operational uptime guarantees rather than upfront implementation completion. This shift concentrates most visibly in Cayman Islands and Delaware domiciled fund structures where operational expense treatment carries tax optimization benefits.
Global Cryptocurrency Custody Software Market Segmentation
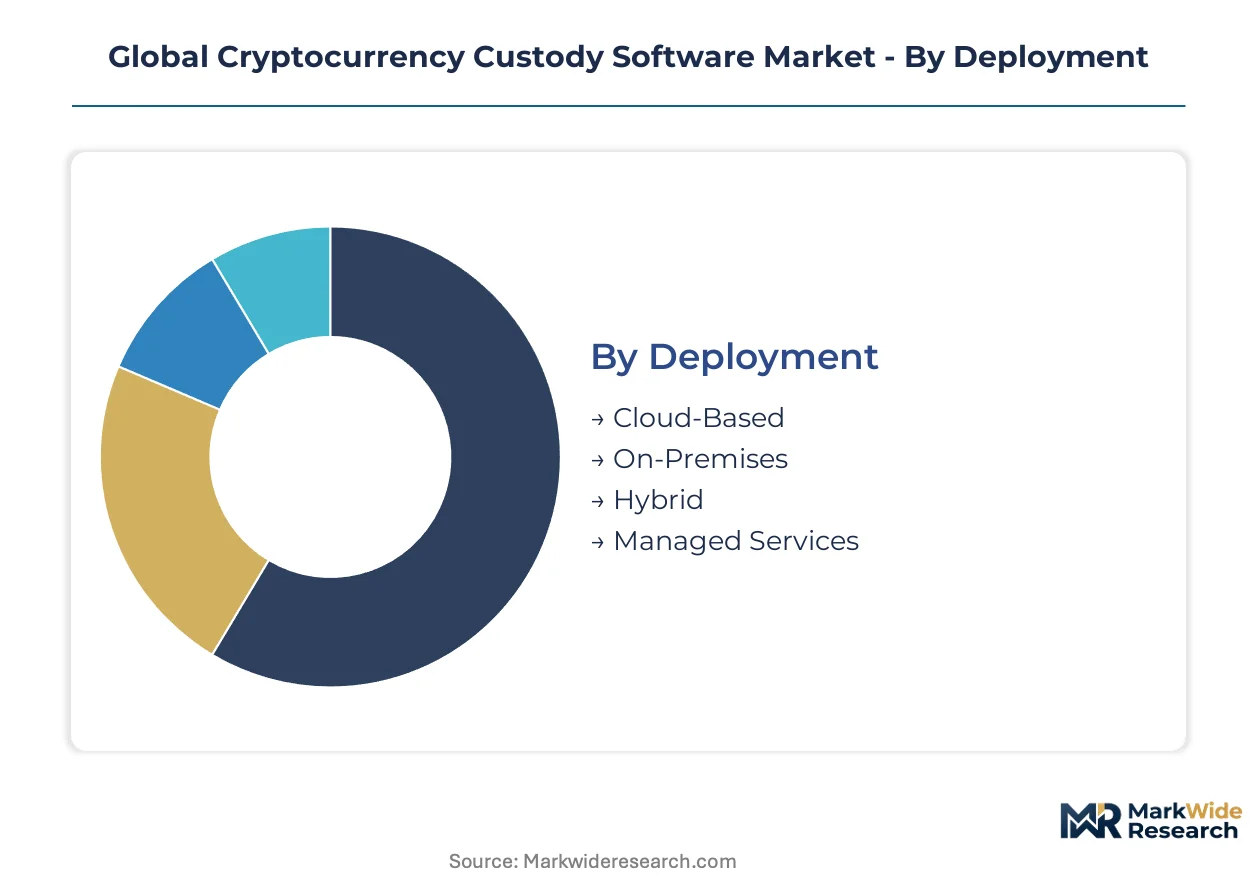
Segmentation in cryptocurrency custody software reveals how regulatory mandates reshape procurement priorities across deployment architectures and solution types. Institutional buyers select configurations based on jurisdictional custody rule frameworks rather than technical specifications alone.
Deployment:
Regulatory differentiation between qualified custodian requirements in the United States, Singapore, and Switzerland directly dictates deployment architecture selection for asset managers seeking cross-border fund structuring.
- Cloud-Based:API-first configurations enable hedge funds and venture capital firms to operationalize digital asset strategies without physical infrastructure capital expenditure. Singapore MAS licensing guidelines explicitly accommodate cloud-resident key management for licensed digital payment token service providers, accelerating adoption among Asia-Pacific fund administrators.
- On-Premises:Air-gapped cold storage infrastructure satisfies SEC staff accounting bulletin requirements for exclusive possession of private keys by qualified custodians. US pension fund trustees mandate on-premises HSM clusters before allocating to cryptocurrency strategies, concentrating demand among state-regulated trust banks.
- Hybrid:Combines cloud-based policy orchestration with on-premises key generation for institutions navigating divergent regulatory treatments across operating jurisdictions.
- Managed Services:Third-party operational responsibility appeals to family offices lacking dedicated cryptographic engineering capabilities.
Established volume favors On-Premises; emerging adoption favors Cloud-Based.
Solution Type:
Cost tier stratification separates semiconductor-dependent hardware modules from software-native alternatives as supply constraints reshape procurement economics.
- Multi-Signature Wallets:Threshold signature schemes distribute signing authority across geographically separated key shares, eliminating single points of failure. Cayman Islands-domiciled hedge funds prioritize multi-signature architectures for operational resilience in prime brokerage relationships.
- Hardware Security Modules:FIPS 140-2 Level 3 certified physical enclosures generate and protect keys within tamper-responsive semiconductor packages. Taiwan and South Korean foundry capacity constraints extend lead times for European private banks, forcing German and Swiss institutions toward software-only evaluations.
- Key Management Systems:Software layers enforce cryptographic policy, key rotation schedules, and access logging across institutional workflows.
- Transaction Analytics:Real-time monitoring surfaces anomalous signing patterns and compliance deviations for audit trail generation.
- Compliance Solutions:Automated documentation engines address MiCA auditable key control mandates and SEC examination protocols.
Margin concentration sits with Hardware Security Modules; steepest expansion trajectory belongs to Compliance Solutions.
Use Case:
Customer type maturity determines which use cases command implementation priority across buyer organizations.
- Digital Asset Protection:Cold storage orchestration and disaster recovery protocols secure private keys against theft, loss, and operational failure. Swiss private banks structure multi-vault geographic distribution across Zurich, Geneva, and Liechtenstein facilities for catastrophe resilience.
- Institutional Trading:Low-latency signing infrastructure supports high-frequency execution across centralized exchange integrations. Singapore-based proprietary trading firms demand sub-second transaction authorization for arbitrage strategies.
- Compliance Monitoring:Continuous surveillance of key access events against regulatory rule sets generates examination-ready documentation.
- Secure Transaction Signing:Policy-enforced authorization workflows prevent unauthorized transfers through multi-party approval quorums.
- Portfolio Management:Unified visibility across wallet balances and positions enables consolidated reporting for investment committees.
Foundation use case is Digital Asset Protection; Institutional Trading shows fastest uptake among new entrants.
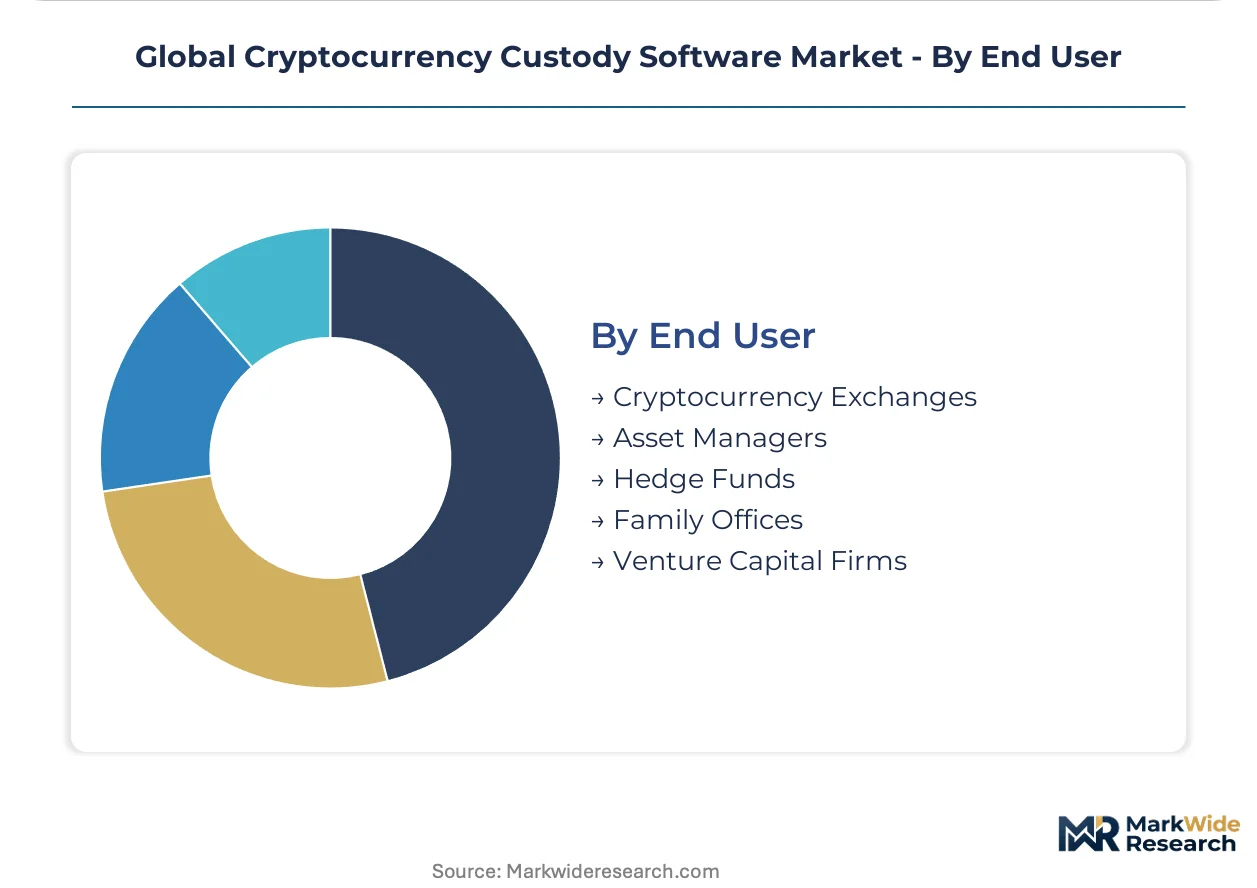
End User:
Geography concentration aligns end user segments with specific licensing regime development stages.
- Cryptocurrency Exchanges:Native custody infrastructure requirements dominate procurement volumes as trading platforms seek to reduce third-party dependency. US exchange operators navigate state-by-state money transmitter licensing complexity across Wyoming, New York, and Texas regimes.
- Asset Managers:MiCA framework compliance deadlines compel European UCITS and AIFM structures to upgrade custody infrastructure ahead of enforcement.
- Hedge Funds:Prime brokerage integration demands drive threshold signature adoption for operational efficiency.
- Family Offices:Sub-hundred-million dollar allocations now access institutional-grade protection through software-defined custody without hardware procurement overhead.
- Venture Capital Firms:Subscription-based pricing models align operational expense treatment with fund administration tax optimization in Delaware and Cayman domiciles.
Procurement volume concentrates with Cryptocurrency Exchanges; fastest penetration rate appears among Family Offices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hedge fund administrators and pension fund trustees concentrate procurement decisions in jurisdictions with crystallized licensing regimes. The United States, Singapore, Switzerland, Germany, and the United Kingdom each impose distinct custody rule frameworks that reshape software architecture requirements.
United States
State-regulated trust banks and qualified custodians drive infrastructure investment across Wyoming, New York, and Texas. SEC staff accounting bulletins mandate exclusive possession of private keys, forcing redesigns for shared-control models. The Greater Boston cluster hosts custody software engineering centers serving pension fund mandates.
Singapore
Monetary Authority of Singapore licensing attracts Asia-Pacific fund administrators seeking regulatory clarity for digital payment token services. Cloud-resident key management receives explicit regulatory accommodation. The Marina Bay financial district concentrates custody technology procurement for hedge fund prime brokerage relationships.
Switzerland
Swiss private banks structure multi-vault geographic distribution across Zurich, Geneva, and Liechtenstein for catastrophe resilience. FINMA guidelines on digital asset custody shape vendor qualification criteria. The Crypto Valley Zug cluster anchors blockchain infrastructure development for institutional wallet solutions.
Germany
BaFin crypto custody licensing requirements compel asset managers to upgrade infrastructure ahead of enforcement deadlines. REACH chemical restrictions on semiconductor inputs extend hardware security module lead times. Frankfurt-based private banks accelerate software-only custody evaluations to circumvent supply uncertainty.
United Kingdom
FCA registration requirements for cryptoasset firms reshape procurement priorities among London-domiciled hedge funds. Institutional trading desks demand low-latency signing infrastructure for arbitrage strategies. The City of London cluster concentrates compliance solution development for MiCA-aligned documentation engines.
Global Cryptocurrency Custody Software Market Competitive Landscape
Player mix skews toward technology-native specialists with cryptographic engineering depth and regulated financial institutions with trust banking heritage. The vendor base separates into three strategic archetypes: multi-party computation patent holders, geographic exchange integrators, and regulatory licensing aggregators. M&A activity concentrates on cryptographic talent acquisition and regional license portfolio assembly. Strategic partnerships between software vendors and hardware security module manufacturers address semiconductor supply constraints.
Within the technology-native tier, Fireblocks and BitGo exemplify divergent competitive positioning. Fireblocks represents the multi-party computation patent archetype with distributed signing protocol specialization. BitGo anchors the geographic exchange integration archetype through North American trading platform relationships. Coinbase Custody occupies a position bridging technology development with regulatory licensing depth across multiple state money transmitter frameworks.
| Leading Market Players |
|---|
| Fidelity Digital Assets |
| Fireblocks |
| BitGo |
| Komainu |
| Zodia Custody |
| Coinbase Custody |
| Anchorage Digital |
| Cobo |
| Gemini Custody |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts with FIPS 140-2 Level 3 hardware security module manufacturers lock in semiconductor allocation for European private banks while capping unit cost escalation. These agreements tether pricing visibility to Taiwan and South Korean foundry output schedules, forcing custody software vendors to preload component costs into multi-year service agreements.
Pricing Analysis
Cost-plus contracts indexed to semiconductor spot markets dominate hardware-dependent deployments, while subscription-based SaaS tiers capture software-native alternatives. Three-tier pricing structure across enterprise, mid-market, and emerging manager levels separates FIPS-certified HSM bundles from API-first configurations. Pricing pressure stems from REACH chemical compliance extending module lead times and forcing expedited procurement premiums. Family offices and venture capital firms show highest price sensitivity, whereas pension fund trustees prioritize certification depth over unit economics.
Supply Chain Analysis
Hardware security module inventory cycles now stretch eighteen to twenty-four months for European deployments due to encapsulant compound reformulation requirements. Semiconductor fabrication concentrates in Taiwan and South Korea, with specialized packaging operations anchored in Germany and Switzerland. Supply chain risk centers on single-source dependency for tamper-responsive physical enclosures. Distribution runs through direct vendor relationships with private banks and hedge fund administrators, bypassing traditional IT channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across MiCA, SEC, and MAS frameworks creates white-space opportunities for modular compliance engines. Asset managers now demand jurisdiction-specific platform variants rather than universal deployments.
For Market Incumbents: Shield market position through exclusive FIPS 140-2 Level 3 hardware partnerships that lock out software-only competitors from pension fund mandates. Accelerate backward integration into cryptographic engineering talent pools concentrated at Israeli and Swiss academic institutions. Prioritize state-by-state money transmitter license accumulation across Wyoming, New York, and Texas to raise competitive barriers. For New Entrants and Emerging Players: Anchor in Brazilian Previdencia Privada custody guidelines as Latin America's largest institutional capital pool opens to digital asset strategies. Target carbon-neutral cold storage demand from environmental mandate-driven asset owners in Norway and Iceland. Pursue API-first go-to-market positioning that compresses deployment timelines for Cayman Islands-domiciled fund structures. For Investors and Strategic Acquirers: Capital is best deployed toward multi-party computation patent holders with distributed signing protocol specialization, as threshold signature schemes displace legacy HSM architectures. Long-term viability hinges on cryptographic engineering depth rather than regulatory license accumulation alone. Watch for MiCA enforcement deadline acceleration as the inflection indicator for European infrastructure upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Party Computation Patent Acquisition | Secures distributed signing protocol leadership against threshold signature competitors. |
| State Money Transmitter License Portfolio Assembly | Builds regulatory moats across Wyoming, New York, and Texas custody markets. |
| Hardware Security Module Manufacturing Partnership | Guarantees FIPS 140-2 Level 3 supply allocation amid Taiwan foundry constraints. |
| Carbon-Neutral Data Center Certification | Captures ESG-mandated asset owner demand in Norway and Iceland facilities. |
| Smart Contract Custody Bridge Development | Connects institutional compliance engines with decentralized finance yield protocols. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with custody software executives, cryptographic engineering leads, hedge fund operational officers, and trust bank compliance directors; and secondary validation against SEC staff accounting bulletins, MiCA technical standards, Singapore MAS licensing guidelines, FIPS 140-2 certification databases, and semiconductor trade flow records. Bottom-up deployment estimates across cloud, on-premises, and hybrid configurations triangulated against top-down market sizing from institutional asset allocation surveys.
Across the projection horizon, the analytical framework modeled deployment architecture, solution type, use case maturity, and end-user regulatory jurisdiction. CAGRs derived from segment-level adoption curves weighted by licensing regime development stages. Forecast inputs incorporated hardware security module lead time trajectories and pension fund trustee mandate velocity.
Material uncertainties — semiconductor supply disruption, regulatory enforcement timeline shifts, and cryptographic protocol standardization outcomes — sit outside the modeled envelope. Forecasts reflect documented assumptions about institutional onboarding rates and jurisdictional rule convergence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Crypto Art Market
Digital Assets and Cryptocurrency Finance
United States Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Global Bitcoin and Cryptocurrency Wallets Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Digital Asset Trading Platform Market
Digital Assets and Cryptocurrency Finance
Digital Currency Wallet Market
Digital Assets and Cryptocurrency Finance
NFT Analytics Tools Market
Digital Assets and Cryptocurrency Finance
Bitcoin Exchange Market
Digital Assets and Cryptocurrency Finance
Digital Finance Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchange Platform Market
Digital Assets and Cryptocurrency Finance
Automated Trading Market
Digital Assets and Cryptocurrency Finance
Global Digital Vault Market
Digital Assets and Cryptocurrency Finance
Asset Tokenization Software Market
Digital Assets and Cryptocurrency Finance
Crypto Wallet Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Market
Digital Assets and Cryptocurrency Finance
Investor ESG Software Market