
 Pawn Shop Market | 2026-2036
Pawn Shop Market Size, Share, and Industry Trends Forecast 2026-2036
Pawn Shop Market Analysis
Market Context
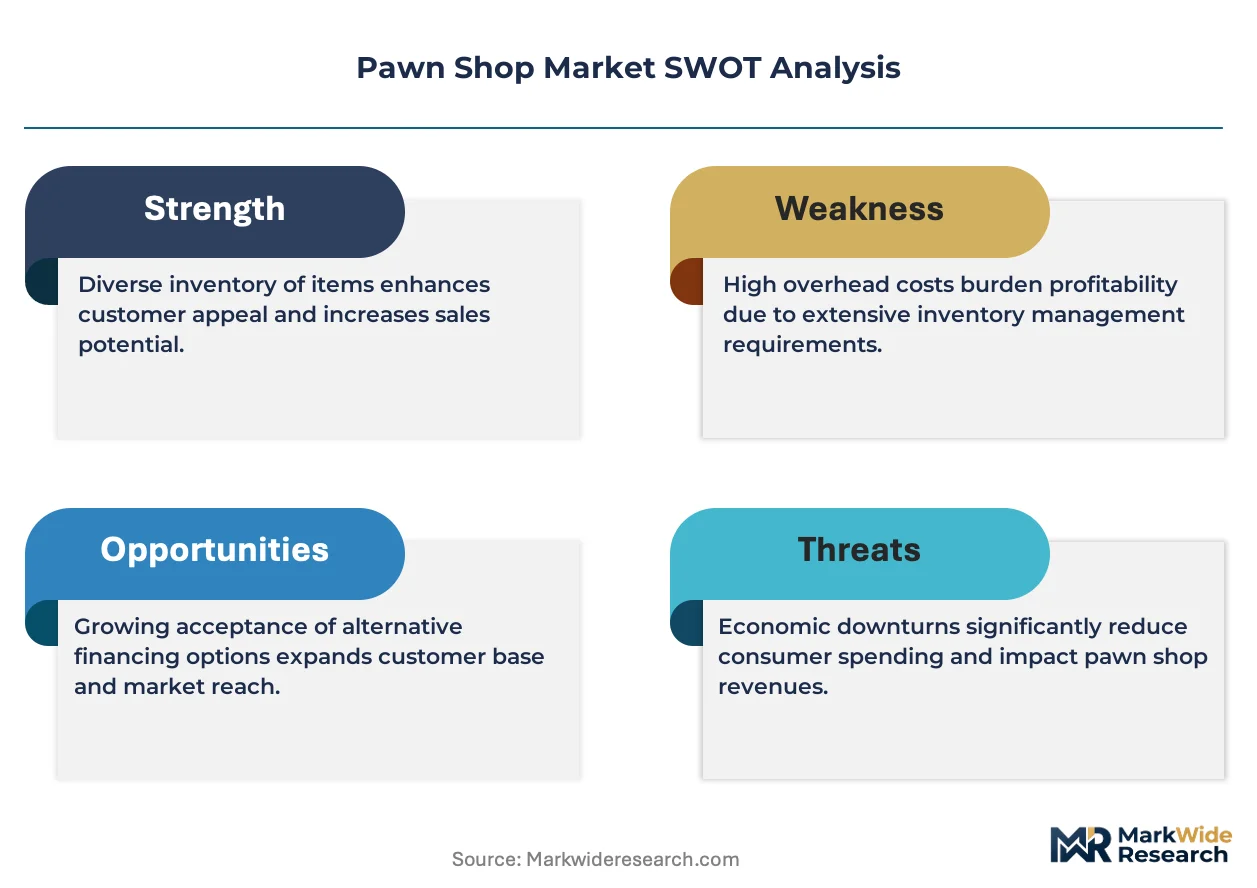
Collateral valuation software is realigning what pawn operators sell, shifting from pure lending to hybrid fintech-enabled service bundles. FirstCash leverages its brick-and-mortar density across Texas and Mexico to sustain geographic dominance in pawn lending. EZCorp differentiates through diversified financial services beyond traditional collateral loans. Gold & Silver Pawn Shop anchors brand strength via media-driven tourism traffic that extends into collectible retail.
Technical Definition and Segments
A pawn shop is a licensed financial and retail establishment that provides secured short-term loans against personal property collateral, typically holding items for 30- to 90-day redemption windows with regulated interest rate ceilings and storage obligations. The operator's core commercial purpose bridges liquidity gaps for underbanked populations while monetizing forfeited collateral through secondary retail. Jewelry dominates product type transaction volume as the most liquid and universally accepted collateral class. Electronics represents the fastest-growing product segment as device refresh cycles accelerate and resale channels mature. Small transaction sizes concentrate margin pools through high-frequency, low-default lending mechanics.
Regulatory Frame and Outlook
The US Consumer Financial Protection Bureau, state-level pawnbroker licensing boards, and the IRS Form 8300 reporting requirement collectively shape operational compliance burdens and capital reserve standards across the industry. State usury caps and municipal zoning ordinances directly determine market access density and per-store revenue ceilings in key operating territories. Stakeholders must monitor pending federal small-dollar lending rulemakings and state legislative sessions for collateral interest rate adjustments that could compress unit economics or trigger portfolio repricing.
Market Dynamics
Collateral valuation algorithms are compressing appraisal cycles from hours to minutes, forcing pawn operators to restructure staffing models and floor layouts around automated intake stations rather than traditional glass-counter interactions.
Growth Catalysts
- CFPB Disclosure Modernization:Streamlined federal reporting requirements reduce administrative overhead for multi-state operators, freeing capital for store expansion.
- Electronics Refresh Acceleration:Compressed smartphone and laptop replacement cycles expand forfeited inventory pools with higher-margin resale velocity than traditional jewelry collateral.
- Texas-Florida Metro Density:Population concentration across Houston, Dallas, Miami, and Tampa corridors sustains transaction volume for underbanked small business owners seeking bridge liquidity.
Market Restraints
- State Usury Ceilings:Municipal interest rate caps in California and New York directly compress per-loan profitability and deter market entry.
- Gold Price Volatility:Input cost swings for precious metal collateral force dynamic loan-to-value recalibration and inventory risk.
- Digital Payment Substitution:Earned wage access apps and paycheck advance platforms erode core pawn lending demand among prime underbanked segments.
Strategic Opportunities
- Unbanked Corridor Penetration:Secondary metro markets in Alabama, Mississippi, and Louisiana show pawn density gaps relative to banking desert maps.
- Hybrid Fintech Bundles:Convergence of point-of-sale lending APIs with physical collateral holding creates integrated liquidity products.
- IRS Form 8300 Automation:Regulatory tailwind from federal cash reporting digitization favors operators investing in integrated compliance software stacks.
Industry Challenges
- Appraisal Specialist Scarcity:Gemological expertise and vintage electronics authentication skills command wage premiums that strain unit economics.
- Legacy POS Integration:Core banking system interoperability with modern collateral valuation APIs requires expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pawn Shop Market |
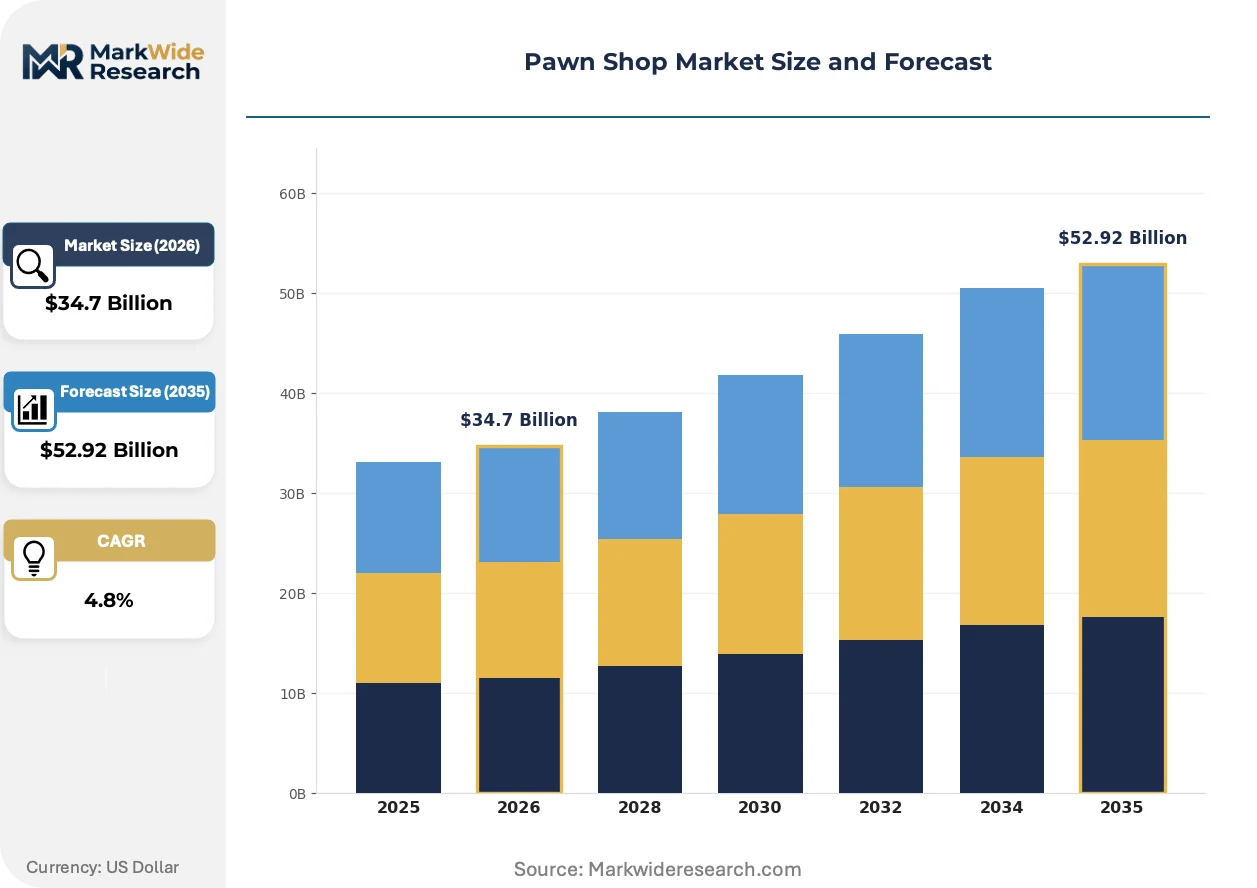
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $52.92 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pawn Loans, Retail Sales, Buyback Services, Layaway Plans Customer Type: Consumers, Investors, Collectors, Small Business Owners Product Type: Jewelry, Electronics, Firearms, Musical Instruments Transaction Size: Small, Medium, Large, High-Value |
| Companies Covered | American Jewelry and Loan, Dollar Financial Group Global Corporation, FirstCash, Pawngo, Browns Pawnbrokers, EZCorp, Gold & Silver Pawn Shop, UltraPawn, Cash America International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pawn Shop Market Emerging Trajectories
Automated collateral assessment tools are redrawing competitive boundaries between traditional pawnbrokers and fintech lenders, with physical footprint advantage now competing against algorithmic speed.
Machine vision appraisal systems are absorbing the routine valuation workload for standardized electronics and precious metals. Small business owners and gig economy workers now expect sub-five-minute collateral decisions. This compression is absorbing front-counter labor costs while forcing operators to retrain staff toward complex collectible authentication and customer retention functions.
The US Consumer Financial Protection Bureau's pending small-dollar lending rulemakings are tightening disclosure granularity requirements for annual percentage rate presentations. State pawnbroker licensing boards are responding with preemptive compliance workshops. Multi-state operators face the steepest adaptation burden as they harmonize reporting across divergent municipal zoning and interest rate regimes.
Buyers are consolidating liquidity sourcing around single-provider relationships rather than transactional shop-hopping. Pawn operators respond with loyalty-structured redemption pricing and digital pawn ticket management. This behavioral consolidation concentrates most visibly in Florida and Texas metro corridors where underbanked population density supports premium location strategies.
Pawn Shop Market Segmentation
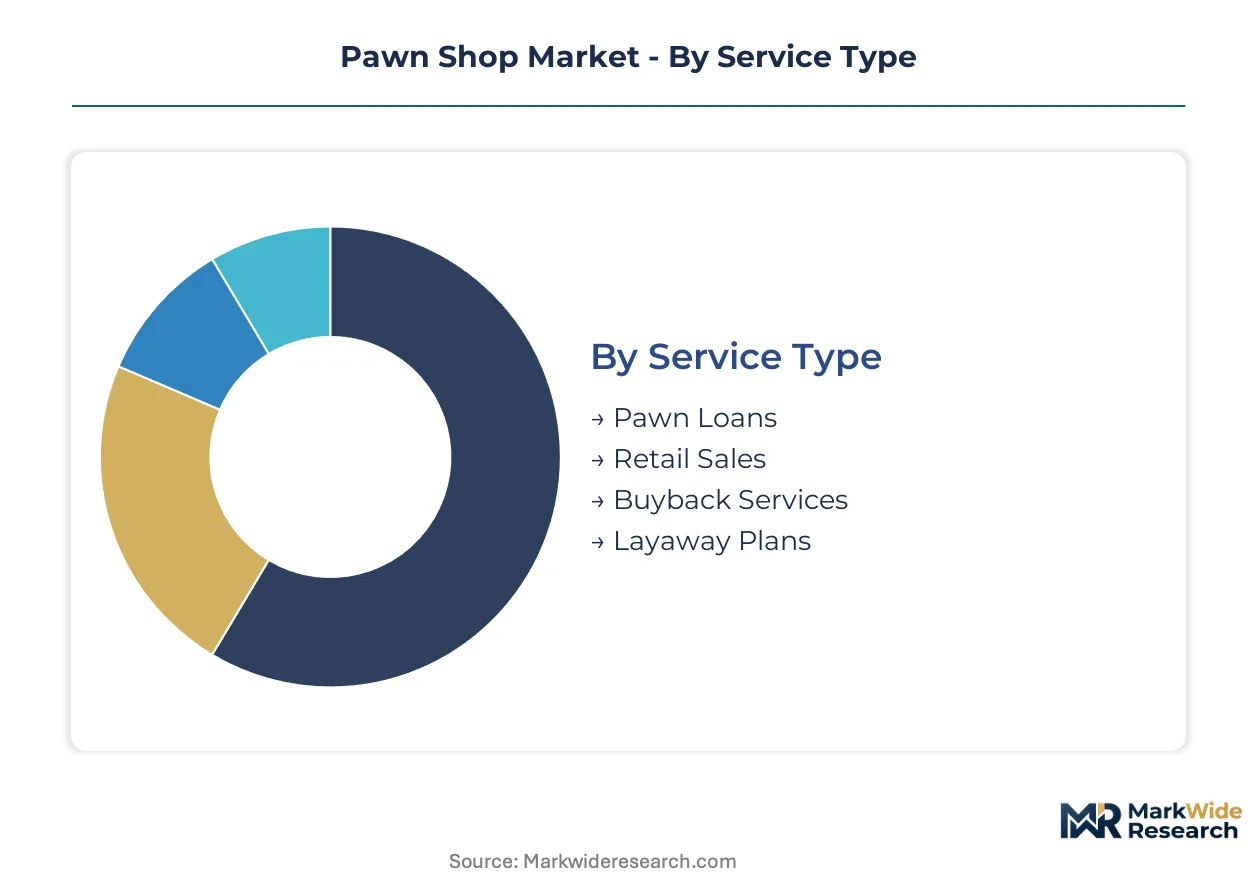
Pawn operators structure operations around four distinct segmentation axes that determine capital deployment, inventory risk profiles, and customer acquisition economics. Each dimension creates divergent margin pools and compliance exposure that shape competitive positioning across metro markets.
Service Type:
Pawn loans demand the heaviest upfront capital reserves due to state-mandated liquidity requirements and forfeited collateral holding periods. Retail sales require lower working capital but higher floor space investment and authentication expertise.
- Pawn Loans:Secured short-term lending against personal property collateral with regulated interest rate ceilings and 30- to 90-day redemption windows. Demand concentrates among underbanked small business owners in Houston and Dallas corridors where bridge liquidity needs spike during seasonal cash flow gaps.
- Retail Sales:Secondary market monetization of forfeited collateral through physical storefront and digital channels. Florida metro markets show the strongest velocity here, driven by tourism traffic and collectible buyer density in Miami and Tampa.
- Buyback Services:Direct purchase agreements with immediate cash settlement, common for precious metals and standardized electronics. Texas operators leverage this for rapid inventory turns.
- Layaway Plans:Structured payment programs for high-ticket items, requiring minimal capital but extended customer relationship management.
Pawn loans absorb the bulk of installed capacity; retail sales are expanding most quickly.
Customer Type:
Customer mix determines default risk curves and average transaction values, with institutional buyers commanding volume discounts and individual consumers driving frequency.
- Small Business Owners:Bridge liquidity seekers with collateral pools spanning equipment and inventory, generating larger average tickets but irregular redemption patterns. Concentration is heaviest in southeastern banking deserts.
- Consumers:Individual borrowers seeking emergency cash against personal assets, forming the high-frequency base with predictable seasonal spikes around tax refund and holiday periods.
- Investors:Portfolio buyers of precious metals and numismatic assets, demanding certified authentication and price transparency tools.
- Collectors:Niche buyers of vintage instruments, firearms, and memorabilia, requiring specialized staff expertise and extended holding periods for rare inventory.
Consumers anchor transaction volume; small business owners are climbing the fastest as gig economy participation expands.
Product Type:
Collateral category dictates appraisal complexity, storage security requirements, and resale channel maturity, with precious metals offering the most liquid exit paths.
- Jewelry:Gold, silver, and gemstone collateral with universal acceptance and established spot pricing mechanisms. Texas and Florida operators maintain dedicated gemological staff to handle estate pieces and designer goods.
- Electronics:Smartphones, laptops, and gaming equipment with compressed depreciation curves and rapid obsolescence risk. Demand is surging in Miami and Tampa where device refresh cycles outpace national averages.
- Firearms:Regulated collateral requiring Federal Firearms License holding and enhanced storage protocols, common in rural Texas markets.
- Musical Instruments:Vintage and professional-grade equipment with highly variable valuation, demanding specialized authentication networks.
Jewelry holds the dominant share of collateral value; electronics are gaining share fastest.
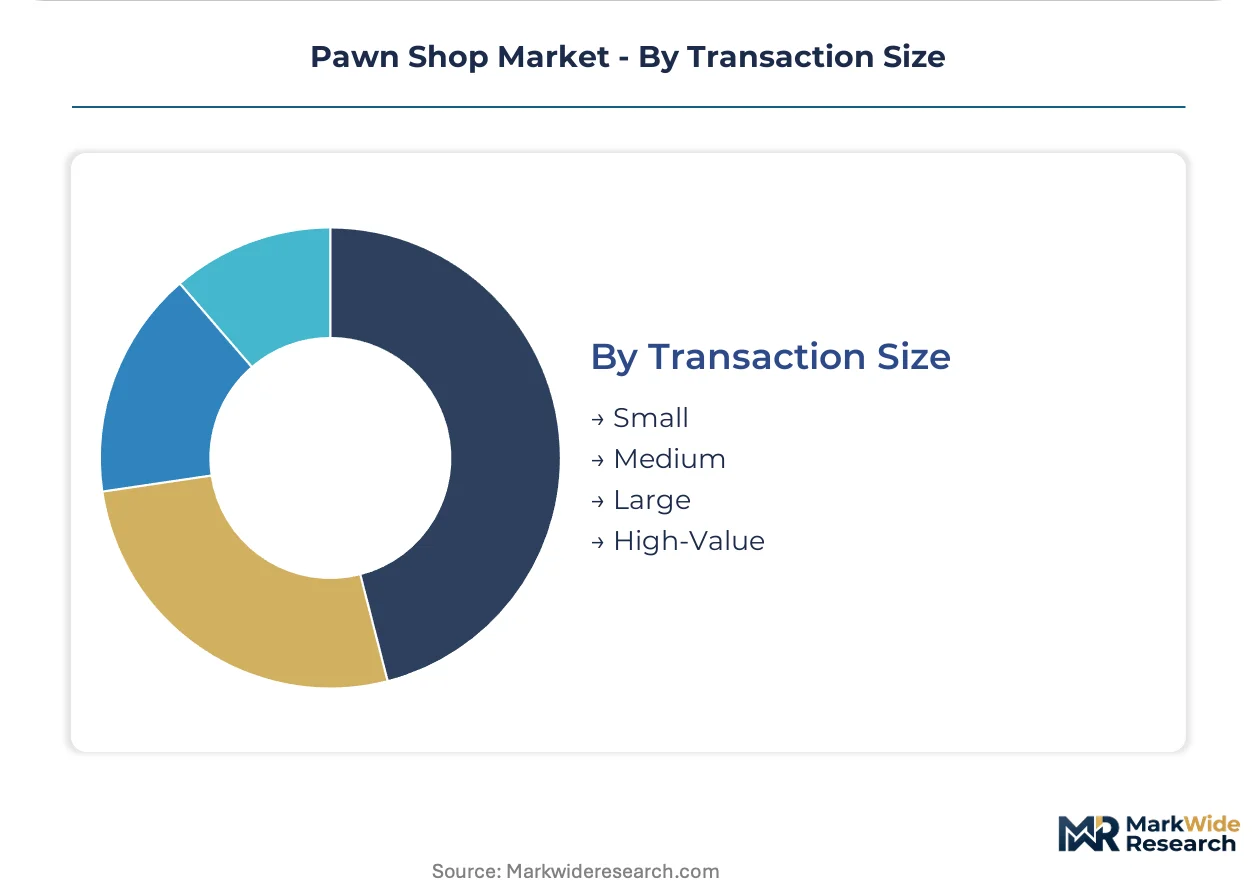
Transaction Size:
Ticket stratification aligns with customer credit profiles and collateral liquidity, with smaller loans generating margin through volume and larger loans requiring bespoke risk assessment.
- Small:Sub-five-hundred-dollar loans against standardized electronics and basic jewelry, processed through automated valuation systems with minimal staff intervention.
- Medium:Five-hundred to two-thousand-dollar range spanning quality firearms and mid-tier jewelry, requiring manager approval and detailed documentation.
- Large:Two-thousand to ten-thousand-dollar collateral pools including estate jewelry and professional equipment, demanding specialist appraisal and extended holding protocols.
- High-Value:Exceeding ten-thousand-dollar transactions for rare collectibles and significant precious metal holdings, handled through centralized valuation hubs.
Small transactions absorb the bulk of unit volume; high-value is expanding most quickly among affluent liquidity seekers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the dominant share of pawn services while Mexico anchors cross-border operational integration. Production of pawn lending infrastructure—valuation technology, compliance software, and point-of-sale systems—concentrates in Texas and Florida metro corridors.
United States
Bridge liquidity demand from underbanked small business owners in Houston and Dallas sustains transaction density. The Consumer Financial Protection Bureau enforces evolving disclosure rules that reshape compliance costs for multi-state operators. Miami and Tampa corridors show premium location strategies concentrating tourism-driven collectible retail.
Mexico
Cross-border operational integration with Texas markets expands forfeited inventory pools and customer acquisition channels. Mexico's national pawnbroker licensing framework imposes capital reserve standards that favor established operators. Northern border states including Nuevo León and Chihuahua anchor geographic dominance through brick-and-mortar density.
Canada
Municipal zoning ordinances in Ontario and British Columbia determine market access density and per-store revenue ceilings. Health Canada oversees secondary retail protocols for regulated collateral categories including firearms. Toronto and Vancouver metro areas concentrate demand from gig economy workers seeking emergency liquidity.
United Kingdom
Estate jewelry and vintage collectible authentication drives specialist appraisal demand in London and Birmingham corridors. The Financial Conduct Authority shapes operational compliance burdens through consumer credit licensing requirements. England's banking deserts in post-industrial regions sustain pawn lending as bridge liquidity infrastructure.
Australia
Precious metal collateral liquidity and spot pricing mechanisms anchor transaction volume in Sydney and Melbourne. The Australian Securities and Investments Commission regulates small-dollar lending disclosure requirements. Queensland and Western Australia show emerging density gaps relative to underbanked population maps.
Pawn Shop Market Vendor Landscape
Top-tier vendors anchor geographic density through brick-and-mortar networks, while mid-tier specialists compete on authentication expertise and niche collectible verticals. The vendor base structures around three strategic archetypes: scale-driven multi-state operators, fintech-enabled hybrid platforms, and media-anchored destination retailers. Consolidation pressures favor operators with integrated compliance software stacks. Portfolio diversification into buyback services and layaway plans represents the dominant competitive move alongside automated collateral valuation deployment.
Within the scale-driven tier, FirstCash and EZCorp exemplify multi-state operational models, while Gold & Silver Pawn Shop occupies a position as a media-anchored destination retailer. These three companies represent divergent strategic archetypes: geographic density concentration, diversified financial services bundling, and tourism-driven brand extension. Each anchors a distinct competitive vector without direct overlap in core positioning.
| Leading Market Players |
|---|
| American Jewelry and Loan |
| Dollar Financial Group Global Corporation |
| FirstCash |
| Pawngo |
| Browns Pawnbrokers |
| EZCorp |
| Gold & Silver Pawn Shop |
| UltraPawn |
| Cash America International |
| Others |
Supply Flow & Price Mechanics
State-level usury cap enforcement gates both qualified supply and premium-tier pricing access, with operators in Texas and Florida leveraging regulatory arbitrage to command rate premiums while California and New York entrants face compressed margin ceilings that deter market participation.
Pricing Analysis
Margin tightening in sub-five-hundred-dollar loan tiers reflects automated valuation system deployment that strips front-counter labor premiums from standardized electronics collateral. Three-tier pricing structure across premium estate jewelry, standard mid-tier goods, and economy electronics segments anchors rate differentiation, with gemological certification and FFL holding commanding spreads. Cost compression accelerates in electronics-heavy portfolios as device depreciation curves outpace loan-to-value recalibration cycles. Small business owners show lowest price sensitivity due to bridge liquidity urgency, while gig economy workers exhibit highest elasticity to rate transparency tools.
Supply Chain Analysis
Appraisal specialist scarcity in Houston and Dallas metro corridors constrains inventory throughput velocity for operators scaling automated intake stations. Supply concentration rests on Mexico-Texas cross-border forfeited goods flows, India-sourced precious metal assay equipment, and domestic FFL-licensed secure transport networks. Gold price volatility and smartphone obsolescence risk constitute primary input cost uncertainties. Distribution runs through brick-and-mortar density networks complemented by digital resale channel partnerships with authenticated collectible platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pawn shop market consolidation accelerates as CFPB disclosure modernization raises compliance fixed costs beyond single-state operator carrying capacity, forcing portfolio aggregation toward scaled multi-state platforms.
For Market Incumbents: Extend geographic density in Alabama and Mississippi banking deserts before fintech-enabled hybrid entrants capture underbanked small business owner relationships. Acquire automated collateral valuation API capabilities to compress appraisal cycles below five-minute thresholds that gig economy workers now expect. Defend against earned wage access app substitution by bundling physical collateral holding with point-of-sale lending integrations. For New Entrants and Emerging Players: Enter via IRS Form 8300 automation software stacks that incumbent operators lack capital to develop internally, capturing compliance service revenue streams alongside lending operations. Target secondary Florida metro corridors outside Miami-Tampa core where tourism-driven collectible retail density remains underdeveloped. Pursue white-label fintech partnerships that embed collateral valuation into gig economy worker payment platforms. For Investors and Strategic Acquirers: Pending federal small-dollar lending rulemakings tightening APR disclosure granularity is the leading indicator that compliance-integrated operators will command acquisition premiums over legacy POS-dependent portfolios. Long-term viability centers on operators with brick-and-mortar density spanning Texas-Mexico corridors and automated valuation deployment runway. Watch for state legislative sessions introducing collateral interest rate adjustments as forced portfolio repricing triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Collateral Valuation Deployment | Machine vision appraisal systems absorb routine electronics workload while compressing front-counter labor costs. |
| IRS Form 8300 Compliance Software Integration | Federal cash reporting digitization favors operators with integrated regulatory technology stacks. |
| Texas-Florida Metro Density Expansion | Underbanked population concentration in Houston and Dallas sustains transaction volume premiums. |
| Hybrid Fintech Bundle Development | Convergence of physical collateral holding with point-of-sale lending APIs creates integrated liquidity products. |
| Precious Metals Authentication Certification | Gemological expertise investment commands estate jewelry margin pools in Miami tourism corridors. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this pawn shop market analysis, cross-referenced with primary interviews conducted with pawnbroker licensing board officials, multi-state operator compliance officers, and secondary retail platform executives. National Pawnbrokers Association transaction surveys, CFPB small-dollar lending disclosures, and state-level usury cap legislative databases provided volume and pricing benchmarks. Bottom-up store-level revenue modeling triangulated against top-down metro market liquidity demand estimates derived from banking desert population maps.
Granularity-level modeling disaggregated projections across service type, customer archetype, collateral category, and transaction size tiers throughout the forecast period. CAGRs were derived from historical transaction velocity patterns, forfeiture rate trends, and electronics depreciation curve assumptions. Regulatory scenario analysis incorporated pending federal disclosure rulemakings and state legislative session calendars as forecast sensitivity inputs.
Revisions become necessary when CFPB final rulemakings materially alter APR presentation requirements, gold price volatility exceeds historical bands, or earned wage access platforms achieve sufficient penetration to displace core pawn lending demand. Material deviation in these named triggers warrants pause and re-evaluation of consolidation timing assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Mobile Notary Public Market
Financial Services
E-KYC Market
Financial Services
United States Credit Agency Market
Financial Services
Asia-Pacific Factoring Services Market
Financial Services
Intellectual Property Valuation Market
Financial Services
North America B2B Legal Services Market
Financial Services
Europe B2C Legal Services Market
Financial Services
United States Payroll Services Market
Financial Services
Global Management Consulting Services Market
Financial Services
Investment Trading Software Market
Financial Services
North America B2C Legal Services Market
Financial Services
Currency Exchange Bureau Software Market
Financial Services
Outsource Debt Collection Services Market
Financial Services
India Trade Finance Market
Financial Services
Multivendor ATM Software Market
Financial Services
BFSI A2P SMS Market