
 ATM Software Market | 2026-2036
ATM Software Market Size, Share, and Industry Trends Forecast 2026-2036
ATM Software Market Intelligence
India's rural banking infrastructure push is narrowing the deployment gap between urban and semi-urban ATM networks. Diebold Nixdorf leverages its integrated hardware-software stack to dominate large-bank contracts across South Asia. NCR Atleos sustains cloud-based ATM management platforms that reduce branch dependency for regional financial institutions. KAL specializes in multivendor software that frees banks from single-manufacturer lock-in across heterogeneous machine fleets.
ATM software comprises the operating systems, middleware, and application layers that control cash dispensing, card reader authentication, network connectivity, and transaction routing in automated teller machines. These systems typically run on embedded Windows or Linux kernels with PCI-compliant encryption modules to protect cardholder data during financial exchanges. Security and transaction management segments command premium pricing due to escalating fraud vectors and regulatory audit requirements. Cloud-based deployment models are expanding fastest as banks seek centralized fleet monitoring and over-the-air patch distribution.
The Reserve Bank of India's ATM cybersecurity guidelines and PCI DSS standards enforced by card networks shape product certification requirements and market access conditions for software vendors. BIS specifications for electronic payment systems and RBI's financial inclusion mandates collectively determine feature priorities for domestic deployments. Stakeholders must weigh cloud migration timelines against legacy on-premises infrastructure amortization schedules.
Market Dynamics
The migration from Windows 7 to Linux-based ATM operating systems is compressing vendor timelines and forcing banks to reassess long-term software contracts as end-of-life deadlines approach.
Growth Catalysts
- PCI DSS 4.0 compliance mandates:Card networks in North America are accelerating encryption upgrades across ATM fleets, compelling banks to refresh software stacks ahead of certification deadlines.
- India's rural financial inclusion directives:The Reserve Bank of India requires banks to deploy interoperable ATMs in unbanked districts, generating concentrated demand for localized software solutions.
- Cloud-native transaction processing:Regional financial institutions are abandoning branch-centric infrastructure for centralized fleet management platforms that enable remote diagnostics and patch deployment.
Market Restraints
- Semiconductor supply concentration:Embedded encryption module production clusters in Taiwan and South Korea create vulnerability for ATM manufacturers dependent on PCI-compliant hardware.
- Legacy protocol fragmentation:Proprietary communication standards from 1990s-era ATM hardware persist in installed bases, complicating multivendor software integration.
- Substitution by mobile banking:Unified Payments Interface adoption in India and similar real-time payment rails elsewhere are reducing cash withdrawal frequency at physical terminals.
Strategic Opportunities
- Underpenetrated semi-urban India:Tier-2 and Tier-3 cities remain underserved relative to urban ATM density, creating whitespace for localized software deployments with vernacular interfaces.
- Video teller machine convergence:Integration of biometric authentication with two-way video banking is opening new service revenue streams beyond cash dispensing.
- EU Green Deal alignment:Energy efficiency mandates for financial infrastructure are creating demand for power-optimized ATM software that reduces idle-state consumption.
Industry Challenges
- Embedded systems talent scarcity:Banks and vendors face acute shortages of engineers proficient in both real-time operating systems and modern cryptographic protocols.
- EMV certification bottlenecks:Laboratory testing queues for chip card compliance are extending deployment timelines by six to nine months for software updates.
- Heterogeneous fleet integration:Acquired banks often operate mixed hardware generations from multiple manufacturers, complicating unified software management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ATM Software Market |
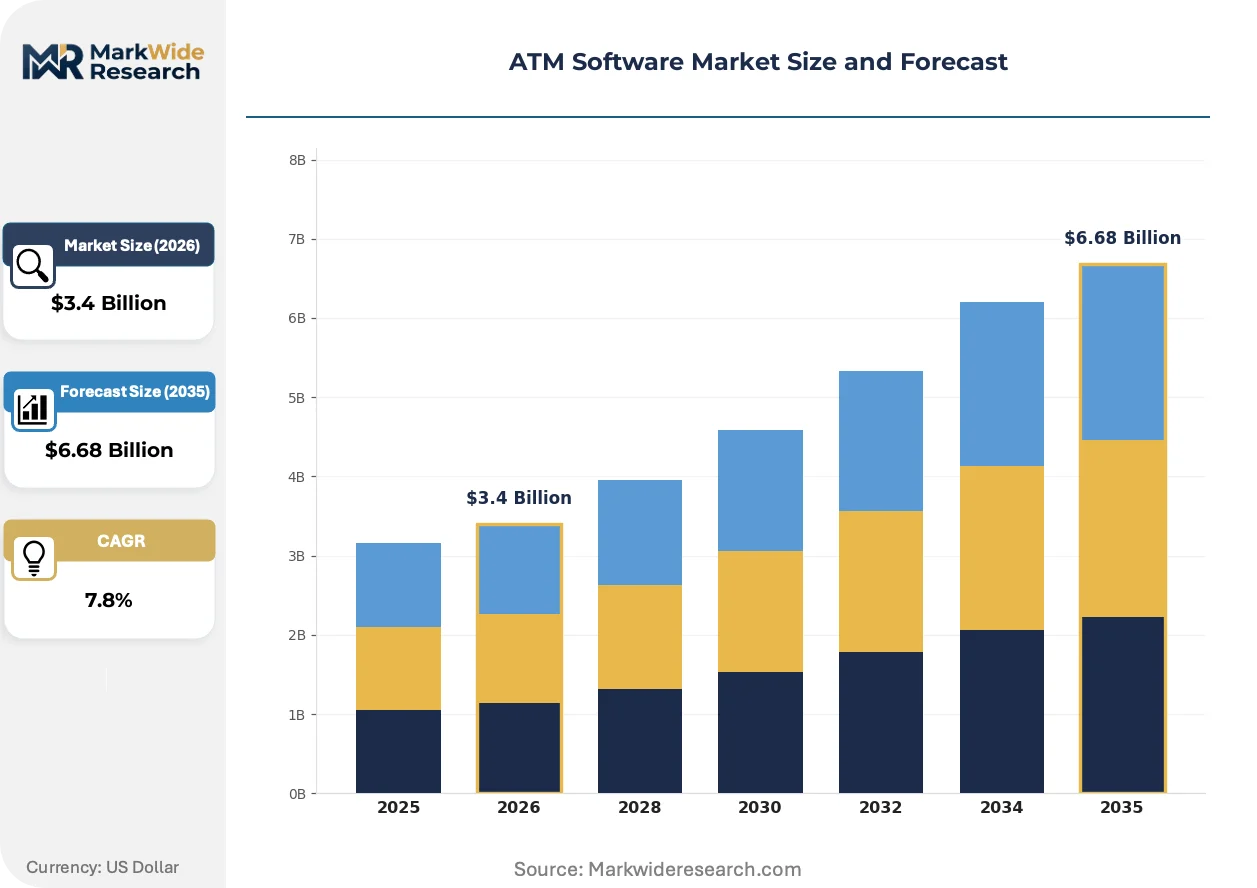
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.68 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multivendor, Integrated, Security, Transaction Management Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Financial Institutions, Retail Chains, ATM Manufacturers, Service Providers Feature: Remote Monitoring, Analytics, User Authentication, Cash Management |
| Companies Covered | ESQ Data Solutions, Diebold Nixdorf, KAL, OKI Electric Industry, NCR Atleos, Euronet Software Solutions, Serquo, Hitachi-Omron Terminal Solutions, Auriga, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ATM Software Market Strategic Shifts & Innovations
Software-defined ATM architectures are decoupling application logic from hardware dependencies, enabling faster feature deployment and reducing vendor lock-in across heterogeneous machine fleets.
Containerization is collapsing the traditional boundary between ATM edge software and core banking systems. Microservices architectures allow banks to deploy transaction modules independently, reducing regression testing cycles. Tier-1 financial institutions in Singapore and Germany are piloting Kubernetes-orchestrated ATM workloads that treat cash dispensers as IoT endpoints rather than isolated appliances.
REACH chemical restrictions and EU F-Gas Regulation are pressuring ATM manufacturers to eliminate refrigerants in cash vault cooling systems. Software-controlled thermal management algorithms now optimize compressor cycles to maintain bill integrity while complying with phasedown schedules. European deployment specifications increasingly require environmental impact disclosures in procurement tenders.
Subscription pricing for ATM software licenses is displacing perpetual purchase models across mid-market banks. Hardware-as-a-service arrangements bundle software maintenance with equipment refresh cycles, transferring obsolescence risk to vendors. This shift is most pronounced in Brazil and Mexico, where regional banks prioritize operational expenditure predictability over capital ownership.
ATM Software Market Segmentation
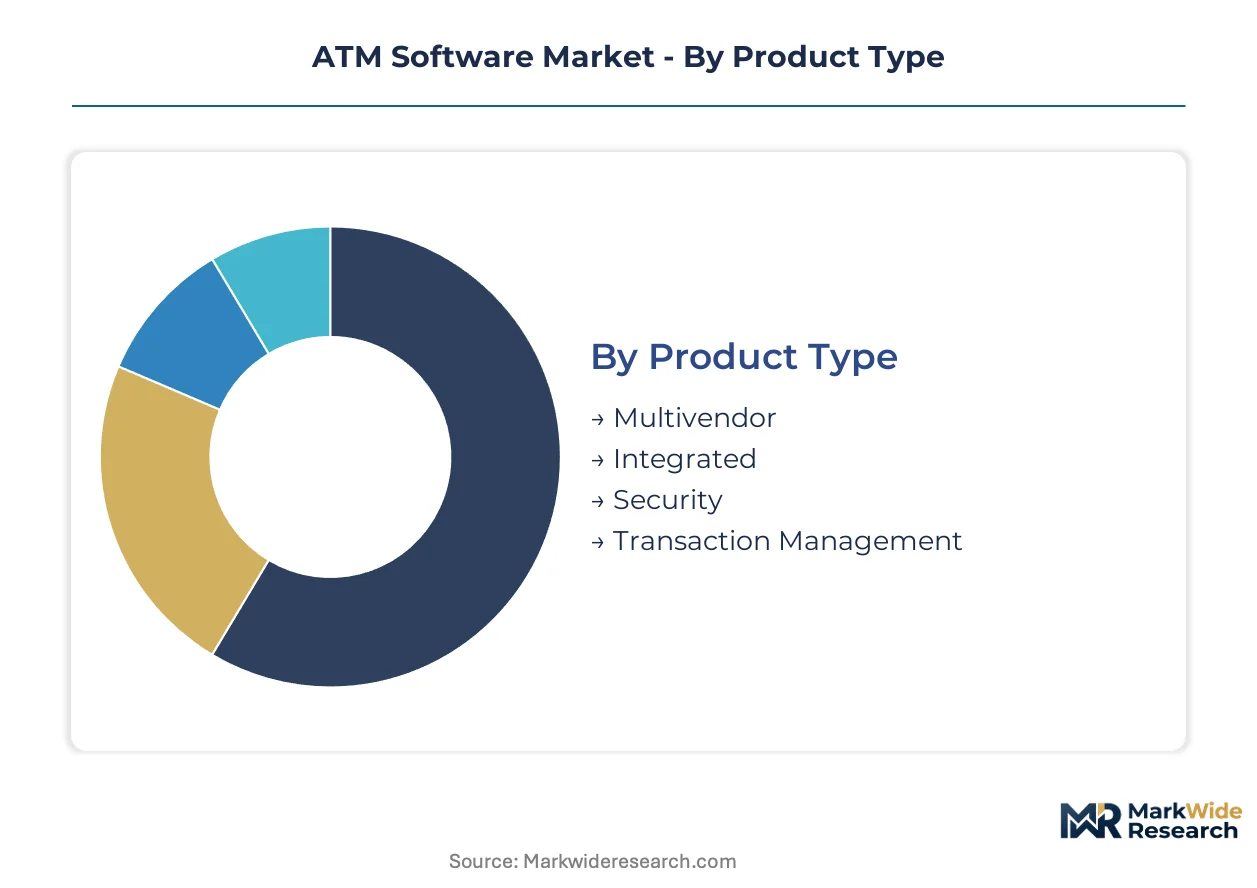
ATM software purchasing patterns diverge sharply between large banks seeking unified fleet control and regional institutions prioritizing cost flexibility. Segmentation reveals how deployment architecture, security requirements, and operational scale reshape vendor selection criteria across heterogeneous buyer profiles.
Product Type:
Cost tier structures the competitive landscape, with premium security modules commanding multiples of basic transaction processing licenses.
- Multivendor:Middleware abstraction layers enable banks to operate mixed hardware fleets from Diebold Nixdorf, NCR, and Hyosung through standardized APIs. Tier-1 institutions in India and Germany are consolidating around this architecture to escape single-vendor lock-in and accelerate procurement cycles.
- Integrated:Bundled hardware-software stacks from single manufacturers dominate large-bank contracts where support simplicity outweighs flexibility premiums. South Asian public sector banks favor these deployments for reduced integration testing overhead under RBI compliance timelines.
- Security:PCI DSS 4.0 encryption modules and biometric authentication layers protect cardholder data during financial exchanges. Demand concentrates in North American markets where card network mandates drive replacement cycles.
- Transaction Management:Core routing and settlement engines process cash dispensing, balance inquiries, and fund transfers across ATM networks. Regional banks in Brazil prioritize these modules for interoperability with real-time payment rails.
Integrated stacks command the established base. The steepest expansion runs through multivendor solutions.
Deployment Model:
Application architecture determines where computational load resides—centralized data centers, distributed edge nodes, or intermediate hybrid configurations.
- On-Premises:Legacy infrastructure maintained within bank-owned data centers persists where regulatory data sovereignty requirements prohibit cloud migration. German and Swiss institutions retain these deployments under strict financial sector supervision.
- Cloud-Based:Centralized fleet management platforms enable over-the-air patch distribution and remote diagnostics without branch technician dispatch. Mid-market banks in Mexico and Colombia are abandoning capital-intensive ownership for subscription models.
- Hybrid:Sensitive transaction processing remains on-premises while analytics and monitoring shift to cloud environments. This architecture satisfies RBI data localization mandates while capturing operational efficiency gains.
- Edge Computing:Distributed processing at ATM endpoints reduces latency for biometric authentication and video teller services. Singaporean banks pilot these deployments for real-time fraud detection.
On-premises retains the legacy installed base. Cloud-based deployments are climbing the fastest as operational expenditure predictability displaces capital ownership preferences.
End User:
Customer type dictates feature prioritization, with financial institutions demanding compliance depth and retail chains optimizing for throughput simplicity.
- Financial Institutions:Banks and credit unions require comprehensive audit trails, multi-factor authentication, and integration with core banking systems. India's rural inclusion directives are expanding this segment through mandated interoperable ATM deployments in unbanked districts.
- Retail Chains:Supermarkets and convenience stores deploy stripped-down cash dispensing units with minimal staff intervention. Brazilian retail networks favor these installations for customer foot traffic generation rather than fee revenue.
- ATM Manufacturers:Original equipment producers license embedded software for pre-installation on new hardware shipments. Taiwanese and South Korean component suppliers bundle these licenses with encryption module sales.
- Service Providers:Independent ATM operators manage third-party machine fleets through white-label software platforms. This segment concentrates in European markets where regulatory caps on interchange fees drive outsourcing economics.
Financial institutions anchor volume demand. Service providers represent the most rapid ascent as independent ATM deployment accelerates.
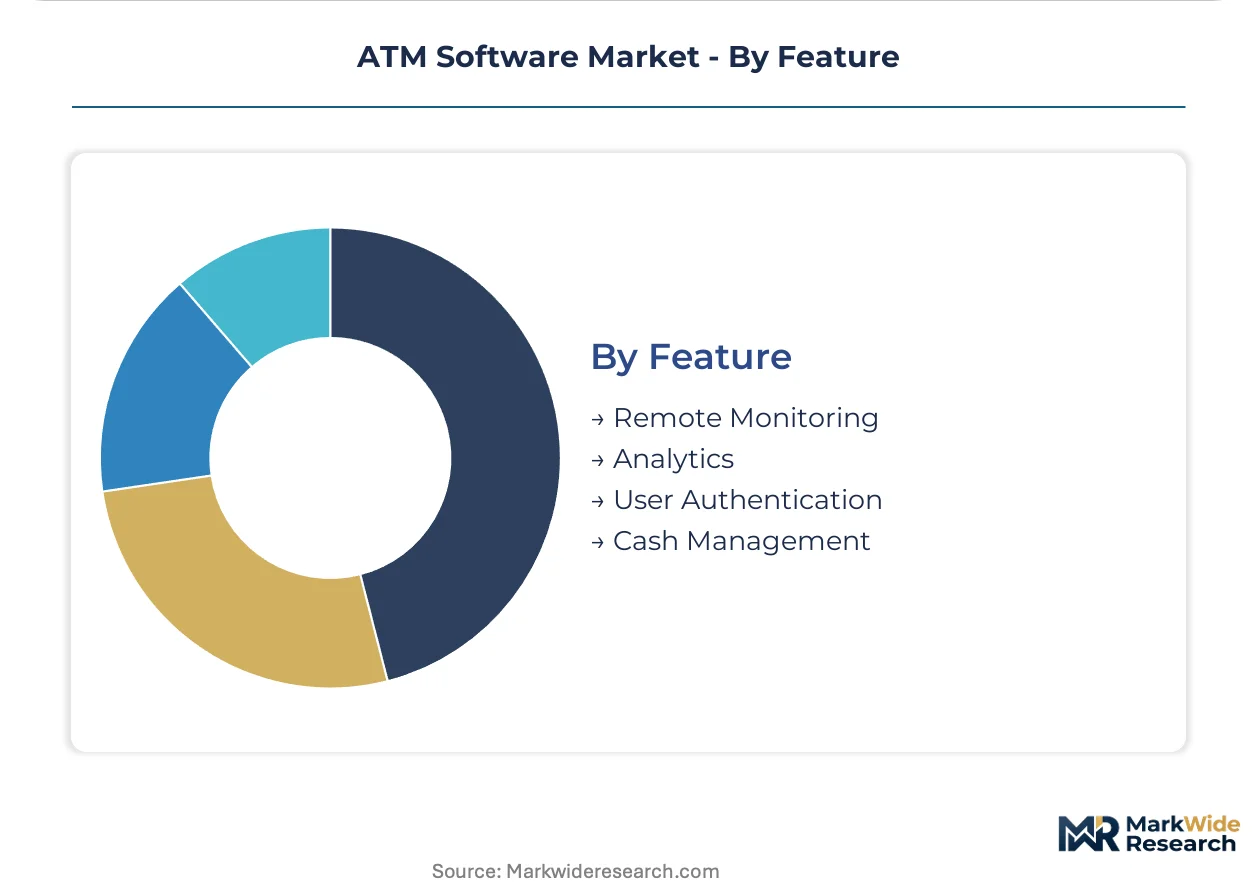
Feature:
Maturity gradients separate established cash management functions from emerging analytics capabilities requiring data infrastructure investment.
- Remote Monitoring:Real-time status dashboards track machine health, cash levels, and network connectivity across distributed fleets. German Sparkassen deploy these systems to reduce technician dispatch frequency in rural service territories.
- Analytics:Transaction pattern analysis and predictive maintenance algorithms optimize cash replenishment schedules. Singaporean banks leverage these tools for demand forecasting across heterogeneous urban and suburban networks.
- User Authentication:Biometric verification and behavioral analytics strengthen security beyond PIN entry. Indian deployments increasingly incorporate Aadhaar-linked fingerprint recognition for financial inclusion verification.
- Cash Management:Denomination optimization and vault balancing algorithms minimize idle currency and replenishment costs. This foundational capability remains standard across all deployment tiers.
Cash management holds the dominant share. Analytics capabilities are expanding most quickly as data infrastructure investments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys ATM software for rural financial inclusion under central bank mandates, while Germany and the United States prioritize security compliance and cloud migration for existing urban fleets. This consumption-mix differential shapes divergent vendor feature priorities across major markets.
India
Rural interoperable ATM deployment concentrates demand in semi-urban districts where banks must satisfy RBI financial inclusion directives. BIS specifications for electronic payment systems govern certification requirements for domestic software vendors. Mumbai and Bengaluru anchor development centers where vendors localize vernacular interfaces for Tier-2 and Tier-3 city rollouts.
United States
PCI DSS 4.0 compliance deadlines are accelerating encryption stack refreshes across regional bank fleets. Card network mandates from Visa and Mastercard enforce certification timelines that compress vendor delivery schedules. Chicago and Charlotte host concentrated procurement decision-making for large-bank integrated stack contracts.
Germany
Sparkassen and cooperative banks retain on-premises infrastructure under strict financial sector supervision that limits cloud migration. EU F-Gas Regulation and REACH chemical restrictions shape environmental compliance requirements for ATM hardware-software bundles. Frankfurt and Munich concentrate vendor technical support operations for Central European deployments.
Brazil
Regional banks prioritize subscription pricing models that convert capital expenditure to predictable operational outlays for ATM fleet management. ANVISA and central bank regulations govern payment system interoperability standards. São Paulo anchors independent ATM operator growth where white-label software platforms expand third-party fleet management.
Singapore
Video teller machine pilots and biometric authentication integration drive edge computing deployments for real-time fraud detection. Monetary Authority of Singapore guidelines shape cybersecurity frameworks for ATM network operators. The city-state's banking cluster serves as a testbed for Kubernetes-orchestrated ATM workloads treating cash dispensers as IoT endpoints.
ATM Software Market Key Industry Players
Capability concentration sits with specialized middleware developers; scale advantage sits with integrated hardware-software conglomerates. The market structures around three tiers: multivendor abstraction specialists, bundled stack providers, and regional service integrators. Strategic moves center on cloud-native platform development and multivendor fleet management contracts that reduce single-manufacturer dependency.
Within the integrated hardware-software tier, Diebold Nixdorf and NCR Atleos occupy positions reflecting long-established banking relationships. KAL represents the multivendor specialization archetype, exemplifying middleware approaches that free financial institutions from single-source equipment commitments. These three anchors illustrate the competitive tension between bundled simplicity and procurement flexibility that shapes contract negotiations.
| Leading Market Players |
|---|
| ESQ Data Solutions |
| Diebold Nixdorf |
| KAL |
| OKI Electric Industry |
| NCR Atleos |
| Euronet Software Solutions |
| Serquo |
| Hitachi-Omron Terminal Solutions |
| Auriga |
| Others |
Cost & Logistics Intelligence
Asia-Europe container freight corridors transmit semiconductor module cost volatility directly into ATM encryption hardware landed costs, compressing margins for security software bundles while amplifying price spreads between integrated stack vendors and multivendor middleware providers.
Pricing Analysis
North American ATM software contracts trade at substantial premiums to Indian rural deployment pricing due to PCI DSS 4.0 certification overhead and liability coverage requirements. Subscription SaaS-tiered models now dominate mid-market procurement in Brazil and Mexico, displacing perpetual licenses as regional banks prioritize operational expenditure predictability over capital ownership. Price differentiation hinges on EMV certification grade and after-sales service bundling depth. Pricing pressure stems from mobile banking substitution eroding transaction volume economics at physical terminals. Retail chains exhibit highest price sensitivity, while large banks absorbing compliance costs demonstrate lowest.
Supply Chain Analysis
US export-control restrictions on advanced encryption processors limit hardware-software bundle configurations available to certain non-aligned markets, forcing architectural workarounds that extend certification timelines. Embedded security module production concentrates in Taiwan, South Korea, and Germany, drawing from specialized foundry capacity and PCI-compliant firmware development ecosystems. Critical dependencies include ARM-based secure enclaves, tamper-resistant cryptographic processors, and Windows-to-Linux migration toolkits. Single-source vulnerability pervades Taiwan semiconductor output for encryption chipsets. Distribution runs through OEM direct sales for integrated stacks and value-added resellers for multivendor middleware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ATM software has matured into a service-attach business where recurring security patch subscriptions and cloud management platforms expand faster than underlying hardware refresh cycles, rewarding vendors who embed ongoing operational dependencies into initial procurement.
For Market Incumbents: Insulate installed base relationships through backward integration into encryption module firmware development, reducing exposure to Taiwan supply concentration. Deepen certification investment in RBI-compliant rural deployment toolkits to preempt Indian public sector bank consolidation. Channel control through exclusive technician training programs raises switching costs for heterogeneous fleet operators.
For New Entrants and Emerging Players: Tier-3 Indian cities with vernacular interface requirements present the most penetrable whitespace, as incumbent localization efforts lag RBI deployment mandates. White-label video teller modules for European independent ATM operators exploit regulatory caps on interchange fees driving outsourcing economics. Go-to-market through hardware-as-a-service bundling with Brazilian regional banks converts capital expenditure sensitivity into recurring revenue capture.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with dormant ATM software divisions lacking cloud-native platform investment. Long-term viability centers on multivendor fleet management capabilities as bank consolidation produces heterogeneous hardware estates. Monitor Kubernetes-orchestrated ATM workload adoption rates in Singapore and Germany as inflection signal for containerization platform valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Enables centralized patch distribution for RBI-compliant rural fleets across India. |
| Multivendor Middleware Development | Breaks Diebold-NCR hardware lock-in for German Sparkassen heterogeneous estates. |
| Biometric Authentication Integration | Supports Aadhaar-linked verification for Indian financial inclusion directives. |
| Video Teller Convergence | Opens service revenue streams beyond cash dispensing for Singaporean banks. |
| Subscription Pricing Transition | Converts Brazilian regional bank capex sensitivity into predictable recurring revenue. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with ATM software product managers, bank IT procurement officers, encryption module engineering leads, and independent ATM operator fleet directors. Secondary validation drew from RBI circulars on payment system security, PCI SSC certification databases, BIS electronic payment specifications, and SEC filings of publicly traded ATM manufacturers. Bottom-up deployment tracking across India, Germany, Brazil, Singapore, and the United States combined with top-down market sizing triangulation anchored volume estimates.
Calibration against historical EMV migration timelines and Windows 7 end-of-life replacement curves informed trajectory assumptions across the analysis window. Segmentation dimensions modeled include deployment architecture, security certification tier, end-user institution scale, and regional regulatory cluster. CAGRs derived from logistic adoption curve fitting for cloud-native platforms and linear projection for compliance-driven replacement cycles. Forecast inputs incorporated RBI rural deployment targets and EU F-Gas Regulation hardware refresh implications.
Practitioners should monitor semiconductor export-control expansion and mobile payment transaction growth rates for early signals of demand elasticity shifts. Forecasts reflect assumptions about PCI DSS certification timeline stability and central bank financial inclusion mandate continuity. Material shifts in Taiwan supply chain access or UPI adoption velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
North America Financial Advisory Services Market
Financial Services
Africa Lottery Market
Financial Services
BFSI A2P SMS Market
Financial Services
LAMEA Financial Services Software Market
Financial Services
Reverse Factoring Market
Financial Services
US Online Trading Platform Market
Financial Services
Banknote Counters Market
Financial Services
Debt Settlement Solution Market
Financial Services
Banking Cloud Services Market
Financial Services
Global Power Bank Rental Service Market
Financial Services
Foreign Exchange Services Market
Financial Services
Spain E-Brokerage Market
Financial Services
Hyperinflation System Market
Financial Services
Global Product Cost Management Market
Financial Services
Silver Economy Market
Financial Services
Currency Exchange Software Market