
 Cash Logistics Market | 2026-2036
Cash Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Cash Logistics Market Intelligence
Software-defined cash monitoring is expanding the addressable scope of contracts beyond physical transport. Brink's Company leverages its proprietary fleet telemetry to anchor multi-year service agreements with national retail chains. Loomis AB sustains processing margins through automated sorting investments in European hubs. GardaWorld competes on geographic coverage, operating armored networks across fragmented municipal markets where density economics favor incumbents.
Cash logistics encompasses the secure physical movement, processing, and storage of currency and valuables through armored vehicles, vault facilities, and automated handling systems operating under strict chain-of-custody protocols. Cash transport commands the largest revenue share due to fuel, labor, and insurance intensity, while ATM services represent the fastest-expanding segment as financial institutions outsource replenishment cycles to reduce fleet capital. Biometric security integration in vault access systems is reshaping technology procurement patterns, with retailers and casinos driving specification upgrades.
The US Department of Transportation and the Transportation Security Administration impose route-security and driver-certification standards that elevate compliance costs for interstate operators. India's RBI mandates cash-handling audit trails that push banks toward outsourced processing partners with certified infrastructure. Stakeholders must weigh the durability of physical cash demand against central bank digital currency timelines when committing to vault and fleet expansion decisions.
Market Dynamics
Central bank digital currency pilots are compressing long-term vault demand while simultaneously forcing incumbents to retool processing infrastructure for hybrid physical-digital cash handling.
Growth Catalysts
- RBI Cash-Handling Mandates:India's central bank requires certified audit trails for currency processing, pushing financial institutions toward outsourced partners with compliant vault infrastructure.
- Casino Biometric Upgrades:Gaming operators in Macau and Las Vegas are driving specification upgrades for vault access systems, expanding contract values for security integrators.
- Fleet Telematics Convergence:Armored vehicle operators deploy real-time route optimization and chain-of-custody tracking, anchoring multi-year service agreements with retail chains.
Market Restraints
- Diesel Price Volatility:Fuel constitutes the largest variable cost in armored transport operations, with margin compression acute on fixed-price municipal contracts.
- Driver Certification Bottlenecks:The US Transportation Security Administration imposes stringent background-check timelines that constrain fleet expansion velocity.
- Digital Payment Substitution:Mobile wallet penetration in urban India and Brazil reduces ATM transaction frequency, lengthening replenishment cycles.
Strategic Opportunities
- India's Urban Corridor:ATM penetration lags deposit growth in Mumbai-Delhi-Bangalore corridor, creating whitespace for outsourced replenishment services.
- Automated Sorting Convergence:Machine vision and robotics integration in European processing hubs enables same-day fitness sorting at reduced labor intensity.
- Software-Defined Monitoring:Cloud-based cash visibility platforms allow providers to extend contracts beyond physical transport into treasury advisory services.
Industry Challenges
- Armored Vehicle Fleet Modernization:Euro VI emission standards and ballistic certification upgrades require capital deployment exceeding typical contract durations.
- Legacy Core Banking Integration:ATM replenishment APIs must interface with decades-old mainframe systems at tier-two Indian banks, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cash Logistics Market |
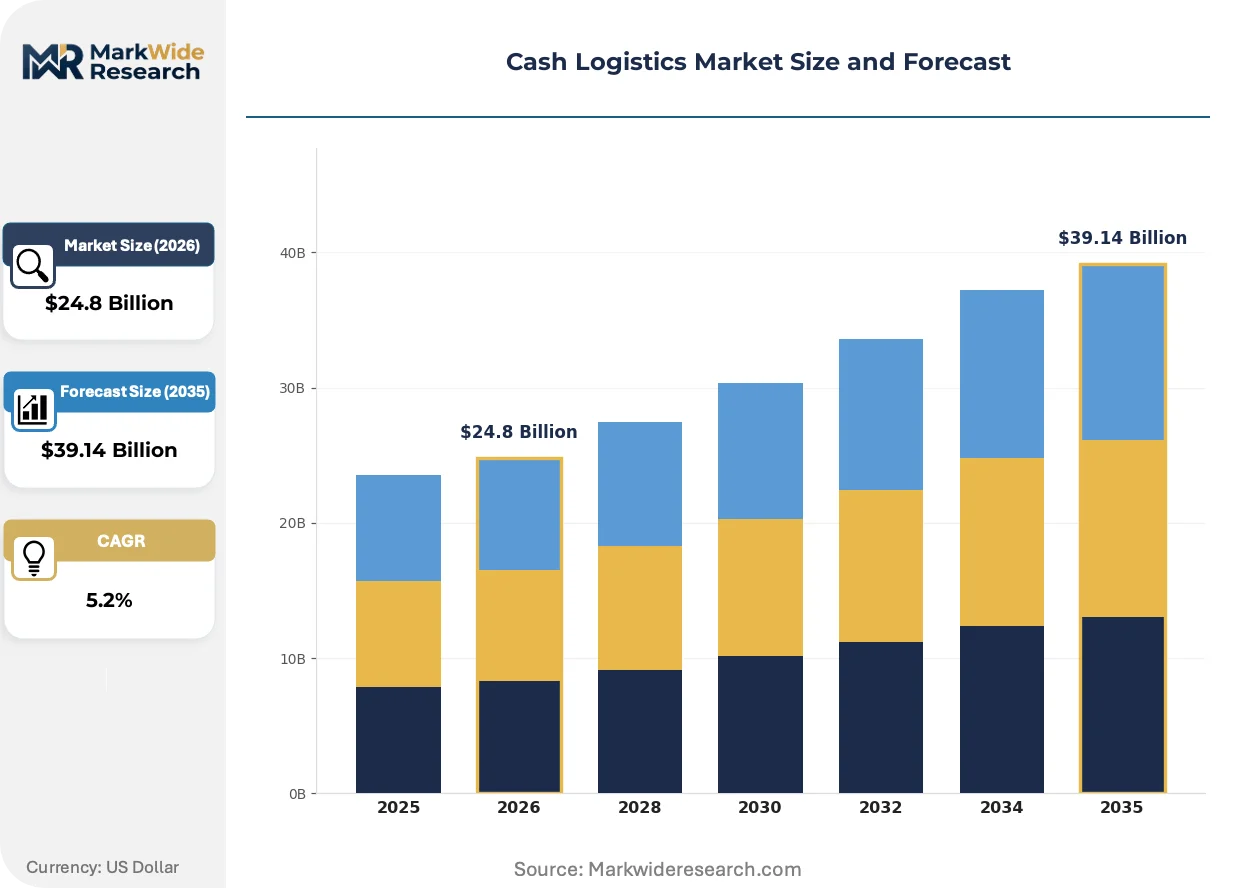
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $39.14 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cash Transport, Cash Processing, ATM Services, Vault Services End User: Retailers, Banks, Government Agencies, Casinos Technology: Automated Cash Handling, Mobile Cash Solutions, Online Tracking, Biometric Security Application: Retail Cash Management, Emergency Cash Supply, Currency Exchange, Event Cash Handling |
| Companies Covered | Brink’s Company, Loomis AB, GardaWorld, Prosegur Cash, G4S, CMS Info Systems, Cash Logistik Security AG, Securitas AB, Dunbar Armored, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cash Logistics Market Strategic Shifts & Innovations
Biometric authentication systems and predictive analytics platforms are redefining security specifications and operational workflows across vault and transport operations.
Computer vision-based fitness sorting is absorbing manual inspection tasks in high-volume currency processing centers. European central banks and commercial cash handlers are deploying these systems to handle polymer note authentication and automated counterfeit detection. The technology is absorbing labor hours previously dedicated to manual sorting while compressing processing turnaround times for retail deposit aggregation.
India's RBI mandates granular cash-handling audit trails that reshape technology procurement patterns for outsourced processing partners. Financial institutions must demonstrate end-to-end chain-of-custody documentation, elevating compliance costs for uncertified operators. National banks and urban cooperative banks are consolidating vendor relationships toward providers with certified infrastructure.
Retail treasury departments are unbundling cash-handling contracts from bundled security services, creating discrete procurement categories for transport, processing, and vault storage. Large-format grocery and big-box chains in the United States and Germany now issue separate RFPs for each function, compressing incumbent margins while opening entry points for specialized providers. This pattern is most visible among national retail chains with centralized treasury operations.
Cash Logistics Market Segmentation
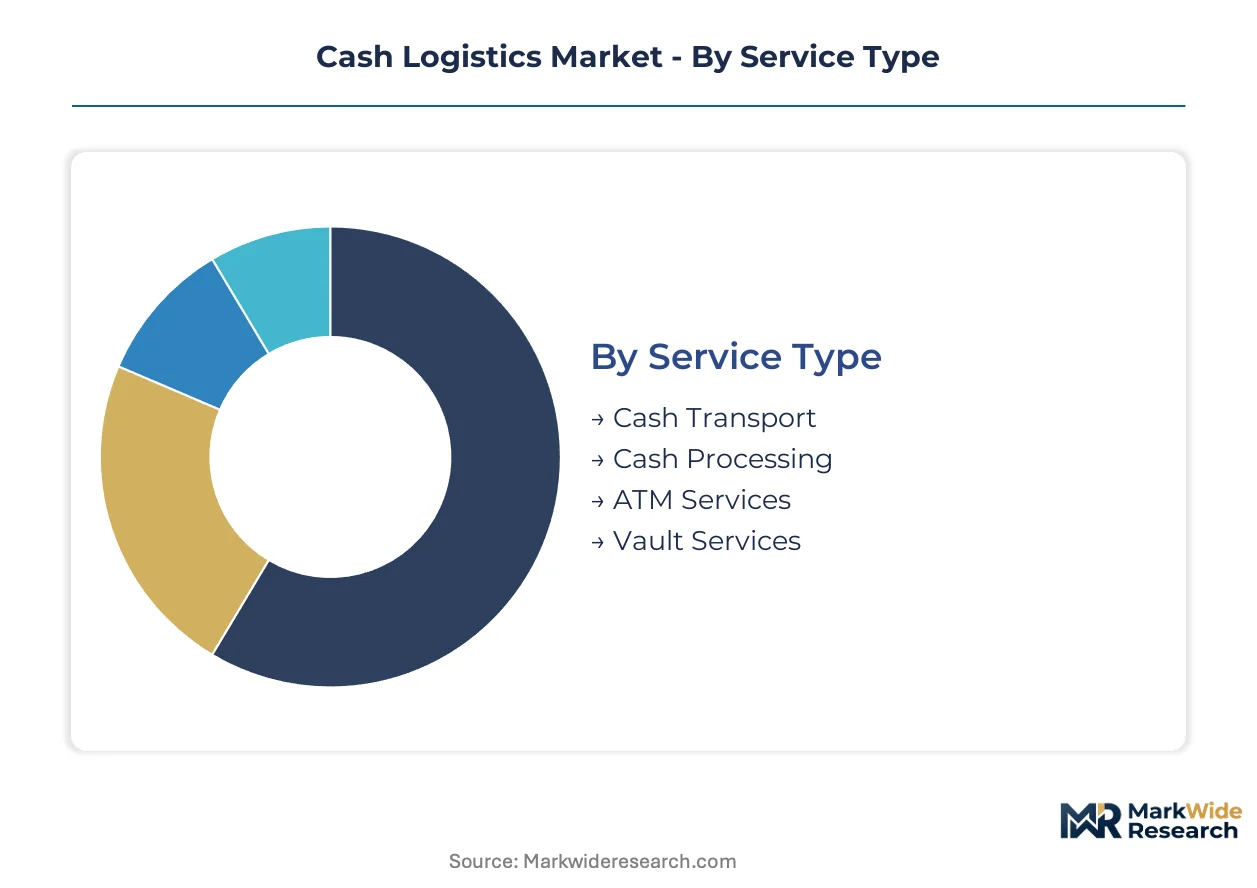
Cash logistics providers structure service portfolios around risk intensity, regulatory exposure, and capital requirements. Segmentation reveals where armored fleet economics dominate versus where software margins expand contract lifetime value.
Service Type:
Buyer differentiation hinges on whether institutions outsource capital-intensive fleet operations or retain control over high-security vault functions.
- Cash Transport:Armored vehicle fleets move currency between bank branches, retail locations, and federal reserve facilities. Demand concentrates in India's urban corridor where ATM replenishment cycles strain bank-owned fleet capacity and RBI audit mandates favor certified third-party operators.
- Cash Processing:High-volume sorting, fitness grading, and counterfeit detection occur in centralized facilities. European central banks and commercial handlers deploy machine vision systems to compress turnaround times for polymer note authentication.
- ATM Services:Outsourced replenishment, first-line maintenance, and cash forecasting reduce fleet capital for tier-two banks.
- Vault Services:Secure storage with biometric access protocols serves retailers and gaming operators requiring insured custody without proprietary infrastructure.
Volume sits with Cash Transport; growth tilts toward ATM Services.
End User:
Procurement sophistication varies sharply between regulated financial institutions and commercial operators managing working capital cycles.
- Retailers:Grocery and big-box chains unbundle transport, processing, and storage into discrete RFPs. Large-format operators in Germany and the United States issue separate contracts per function, compressing bundled security margins.
- Banks:National and urban cooperative banks in India consolidate vendor relationships toward RBI-certified processing partners with end-to-end audit trail capabilities.
- Government Agencies:Municipal treasuries and tax collection services require armored transport for revenue collection routes.
- Casinos:Gaming operators in Macau and Las Vegas drive biometric vault access specifications, expanding contract values for security integrators.
Revenue concentrates with Banks; margin expansion favors Casinos.
Technology:
Technology procurement patterns split between hardware investments with depreciation cycles and cloud platforms extending contract scope.
- Automated Cash Handling:Robotics and machine vision absorb manual sorting labor in high-volume processing centers. European hubs deploy these systems for same-day fitness grading at reduced labor intensity.
- Biometric Security:Fingerprint and iris authentication systems reshape vault access specifications. Retailers and gaming operators mandate these upgrades for high-value storage contracts.
- Mobile Cash Solutions:Armored fleet operators deploy handheld devices for real-time deposit verification and chain-of-custody documentation.
- Online Tracking:Cloud-based visibility platforms allow providers to extend contracts into treasury advisory services beyond physical transport.
Deployment scale favors Automated Cash Handling; specification intensity clusters on Biometric Security.
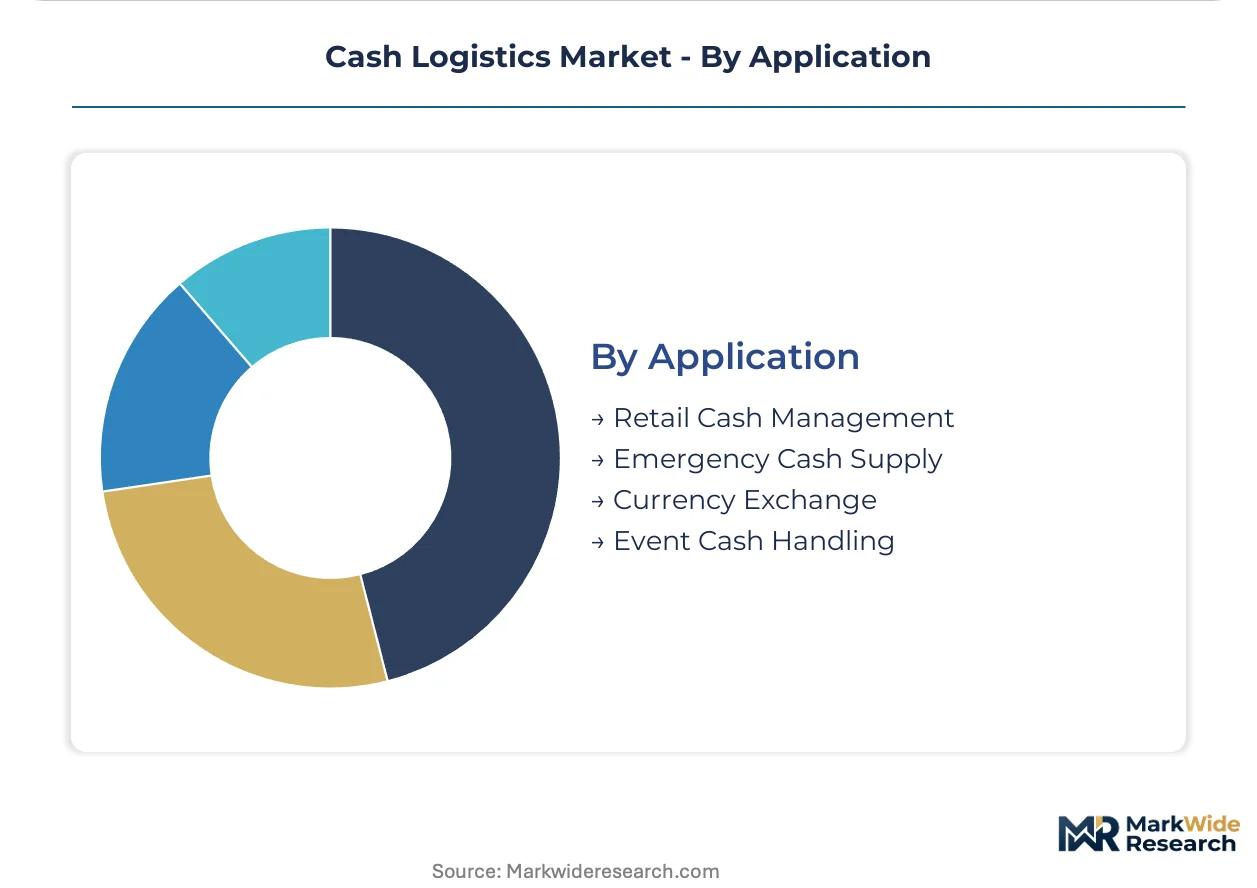
Application:
Application segmentation reflects whether cash logistics serves predictable operational cycles or event-driven demand spikes.
- Retail Cash Management:Scheduled collection and deposit services anchor recurring revenue through multi-year service agreements with national chains.
- Emergency Cash Supply:Disaster response and banking system continuity contracts require pre-positioned vault capacity and rapid deployment protocols.
- Currency Exchange:Bureau operations and cross-border remittance handlers need high-frequency processing for foreign denomination sorting.
- Event Cash Handling:Temporary infrastructure for festivals, sporting events, and elections demands surge fleet capacity with short-contract durations.
Contract duration stabilizes with Retail Cash Management; rate premiums attach to Emergency Cash Supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors the most concentrated cash logistics activity worldwide, with the Mumbai-Delhi-Bangalore corridor generating outsized demand for ATM replenishment and vault services as deposit growth outpaces installed machine base.
United States
Casino operators in Las Vegas and Atlantic City drive biometric vault access upgrades, expanding contract values for security integrators serving gaming properties. The Transportation Security Administration enforces stringent driver certification timelines that constrain fleet expansion velocity for interstate armored operators. Armored transport demand concentrates in the Northeast Corridor linking New York, Philadelphia, and Boston, where municipal treasury contracts sustain route density economics.
India
Urban cooperative banks and national banks consolidate vendor relationships toward outsourced partners as RBI mandates granular audit trails for currency handling. The Reserve Bank of India requires end-to-end chain-of-custody documentation, elevating compliance costs for uncertified operators. The Mumbai-Delhi-Bangalore corridor exhibits the widest ATM penetration gap relative to deposit growth, creating whitespace for third-party replenishment services.
Germany
Large-format retail chains in the Rhine-Ruhr and Bavarian industrial zones unbundle cash-handling contracts into discrete procurement categories for transport, processing, and vault storage. The country's central bank and commercial handlers deploy machine vision systems for polymer note authentication and automated fitness grading. Frankfurt and Munich processing hubs absorb manual sorting labor through robotics integration, compressing turnaround times for retail deposit aggregation.
Brazil
Central bank digital currency pilots prompt incumbents to retool processing infrastructure for hybrid physical-digital cash handling while physical cash demand persists in informal commerce corridors. The central bank's monetary authority oversees compliance frameworks that shape outsourcing decisions among tier-two financial institutions. São Paulo's metropolitan treasury operations and Rio de Janeiro's gaming-tourism clusters sustain armored fleet utilization rates above national averages.
United Kingdom
Retail treasury departments in London and the Southeast issue separate RFPs for cash transport, processing, and vault storage, compressing bundled security margins while opening entry points for specialized providers. The Financial Conduct Authority and Prudential Regulation Authority supervise outsourcing arrangements that influence vendor consolidation patterns among building societies and challenger banks. The Midlands and North England manufacturing belts sustain scheduled collection services through multi-year agreements with national grocery chains.
Cash Logistics Market Key Industry Players
Capital-heavy operators maintaining owned armored fleets compete with asset-light service integrators outsourcing vehicle capacity to regional subcontractors. The market structure tilts toward consolidation at the national level, with three to five providers dominating country-specific contract awards. Strategic archetypes separate into fleet-scale incumbents anchoring multi-year retail agreements, technology-forward processors leveraging automated sorting investments, and geographic specialists capturing fragmented municipal markets. Dominant competitive moves include strategic partnerships with retail treasury departments and portfolio diversification into software-defined monitoring platforms.
Within the fleet-scale tier, Brink's Company, Loomis AB, and GardaWorld occupy positions exemplifying contrasting geographic and technological strategies. Brink's represents the telemetry-integrated operator leveraging proprietary fleet data to anchor service agreements. Loomis exemplifies the European processing-focused archetype with automated hub investments. GardaWorld sits within the geographic coverage specialist category, operating across fragmented municipal markets where density economics favor established incumbents.
| Leading Market Players |
|---|
| Brink's Company |
| Loomis AB |
| GardaWorld |
| Prosegur Cash |
| G4S |
| CMS Info Systems |
| Cash Logistik Security AG |
| Securitas AB |
| Dunbar Armored |
| Others |
Cost & Logistics Intelligence
National retail chains in the United States and Germany unbundle cash-handling contracts into discrete procurement categories, shifting pricing power toward buyers who pit specialized transport, processing, and vault providers against one another in competitive bidding.
Pricing Analysis
Value-based pricing anchored to ATM uptime guarantees and vault access response times dominates service agreements between cash logistics providers and financial institutions. Three-tier pricing structure across premium, standard, and economy levels separates RBI-certified operators with end-to-end audit capabilities from uncertified regional players. Pricing pressure stems from diesel price volatility eroding margins on fixed-price municipal armored transport contracts. Tier-two banks in India exhibit highest price sensitivity due to capital constraints, while gaming operators in Macau and Las Vegas prioritize biometric security specifications over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with ballistic steel armor plating suppliers concentrated in Sweden, Germany, and the United States. Armored vehicle manufacturing draws from specialized chassis providers, custom armor fabricators, and integrated security system suppliers. Supply chain risk centers on Euro VI emission certification delays constraining fleet modernization timelines. Distribution runs through national hub-and-spoke networks with regional vault facilities serving last-mile deposit aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's RBI mandates for granular cash-handling audit trails create a cost-of-compliance moat that favors incumbent operators with certified infrastructure investments, raising barriers for uncertified entrants.
For Market Incumbents: Deploy fleet telemetry convergence as the primary defensive lever. Integrate proprietary route optimization platforms with retail treasury systems to anchor multi-year service agreements against asset-light competitors. Accelerate automated sorting investments in European processing hubs to sustain margin compression from unbundled procurement patterns. For New Entrants and Emerging Players: Begin with ATM replenishment services in India's Mumbai-Delhi-Bangalore corridor, where penetration gaps relative to deposit growth create whitespace before incumbent capacity expansion. Target urban cooperative banks consolidating vendor relationships toward RBI-certified partners. Pursue partnership-based entry with regional armored fleet subcontractors rather than owned-vehicle capital deployment. For Investors and Strategic Acquirers: The window for entry favors technology-forward processors with machine vision and biometric security capabilities over pure-play fleet operators. Long-term viability hinges on hybrid physical-digital infrastructure positioning ahead of central bank digital currency timelines. Monitor RBI certification expansion patterns as the signal indicating vendor consolidation velocity among Indian financial institutions.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Security Integration | Gaming operators in Macau and Las Vegas mandate vault access upgrades, expanding contract values for security integrators. |
| Automated Sorting Investment | European central banks and commercial handlers deploy machine vision systems for polymer note authentication and fitness grading. |
| Fleet Telematics Platform | Real-time route optimization anchors multi-year service agreements with national retail chains seeking chain-of-custody visibility. |
| Software-Defined Monitoring | Cloud-based cash visibility platforms extend provider contracts beyond physical transport into treasury advisory services. |
| Geographic Coverage Expansion | Fragmented municipal markets in Brazil and India favor operators with established armored network density economics. |
Research Approach
Independent corroboration across armored fleet operators, bank treasury executives, and casino security directors underwrites the qualitative findings in this study. Primary interviews with vault infrastructure managers, RBI compliance officers, and retail procurement leads combined with secondary validation from central bank regulatory filings, customs trade data on armored vehicle imports, and SEC disclosures from listed cash logistics providers. Bottom-up service-line revenue builds and top-down macroeconomic anchors triangulate market sizing.
Comparable-period anchoring to historical armored fleet utilization rates and ATM transaction frequency trends established the forecast framework baseline across the analysis window. Segmentation dimensions modeled include service type, end-user vertical, technology deployment tier, and regional regulatory cluster. CAGRs derive from logistic curve fitting to ATM penetration saturation patterns and vault capacity expansion timelines. Diesel price volatility assumptions and central bank digital currency adoption curves inform scenario-weighted outputs.
Underlying measurement precision varies by segment; cash transport and ATM services carry tighter precision than emerging software-defined monitoring categories due to established reporting conventions. Forecasts reflect assumptions about physical cash demand durability and regulatory certification expansion that could revise trajectories if central bank digital currency timelines accelerate or RBI mandates tighten audit trail specifications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Europe B2B Legal Services Market
Financial Services
Spain E-Brokerage Market
Financial Services
Europe Factoring Services Market
Financial Services
Saas Escrow Services Market
Financial Services
Currency Management Market
Financial Services
Intellectual Property Valuation Market
Financial Services
China Financial Services Software Market
Financial Services
Financial Services Software Market
Financial Services
North America B2B Legal Services Market
Financial Services
Virtual Account Management Software Market
Financial Services
Africa Factoring Services Market
Financial Services
Peer-To-Peer (P2P) Market
Financial Services
Banknote Counters Market
Financial Services
United States Payroll Services Market
Financial Services
Hyperinflation System Market
Financial Services
Belgium Gift Card and Incentive Card Market