
 Peer-To-Peer (P2P) Market | 2026-2036
Peer-To-Peer (P2P) Market Size, Share, and Industry Trends Forecast 2026-2036
Peer-To-Peer (P2P) Market Analytics
Asian fintech infrastructure buildout is realigning competitive dynamics across the P2P ecosystem. BitPay leverages cryptocurrency payment rails to sustain cross-border transaction volume. Zopa anchors consumer lending specialization through proprietary credit scoring algorithms. Turo competes in vehicle-sharing by controlling fleet-owner onboarding standards across North American and European cities.
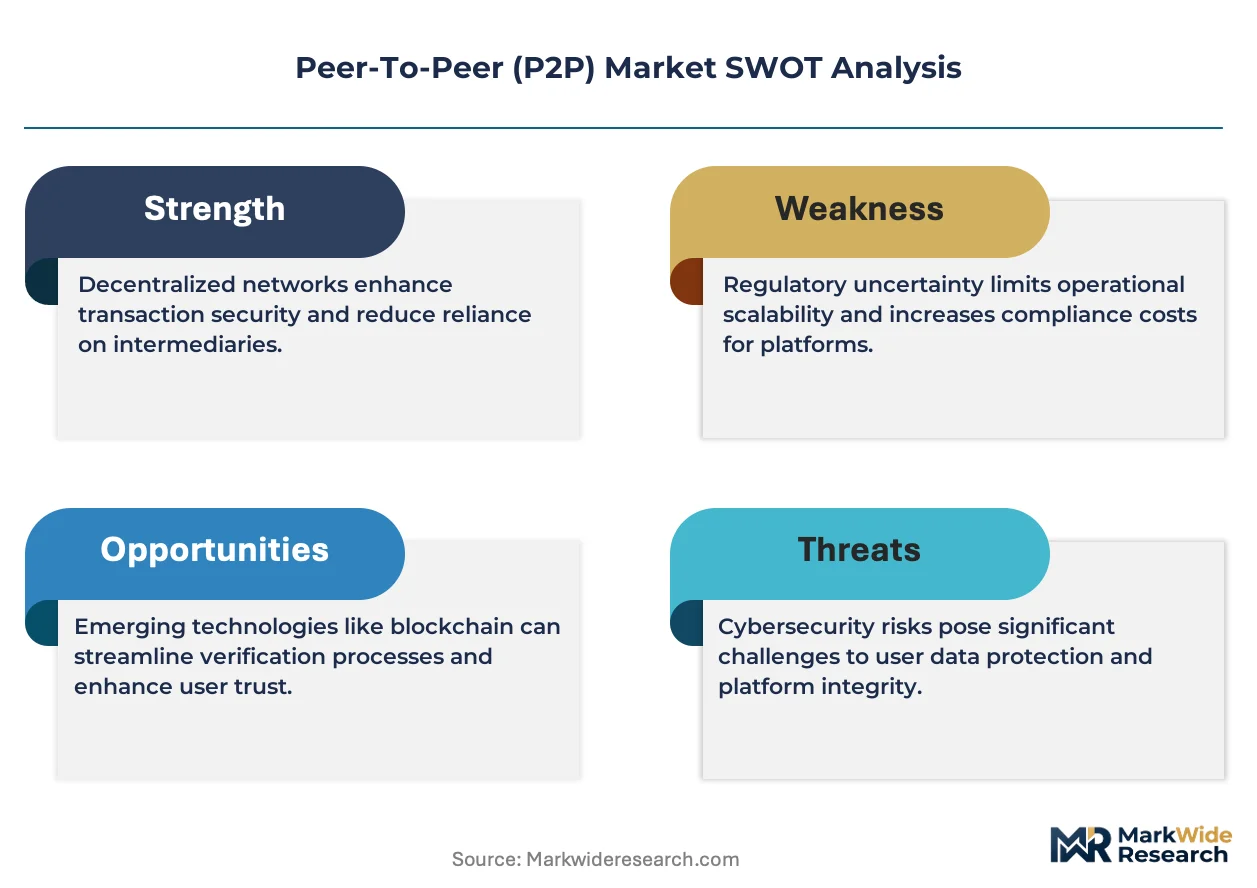
Peer-to-peer systems enable direct exchange of assets, services, or data between counterparties without centralized intermediaries, typically operating through distributed network protocols that authenticate transactions via cryptographic verification or reputation-based mechanisms. These platforms serve commercial purposes spanning decentralized finance, collaborative consumption, and permissionless content distribution. Lending platforms command substantial margin pools due to interest-spread economics and origination fee structures. Blockchain technology segments attract capital allocation intensity as smart contract automation reduces settlement friction. File sharing maintains mature adoption curves among enterprise users seeking bypass of centralized cloud storage costs.
FDA oversight of health data marketplaces, SEC registration requirements for tokenized securities platforms, and EU GDPR data portability mandates collectively shape product architecture and market access thresholds for P2P operators. The EU AI Act introduces additional compliance layers for algorithmic credit decisions deployed across European jurisdictions. Stakeholders must monitor evolving central bank digital currency integrations that could either disintermediate or formalize existing P2P payment corridors.
Market Dynamics
Blockchain infrastructure maturation is compressing settlement latency across lending, payments, and asset exchange protocols, forcing incumbent platforms to rearchitect around smart contract automation or cede margin to decentralized competitors.
Growth Catalysts
- SEC registration frameworks for tokenized securities:Clarity around digital asset classification in the United States reduces legal uncertainty for platform operators seeking institutional capital participation.
- Small business credit demand:Enterprises with limited banking relationships bypass traditional intermediaries, driving origination volume through algorithmic underwriting engines.
- Cross-border payment corridors:Remittance corridors between the United States, Mexico, and the Philippines leverage cryptocurrency rails to undercut correspondent banking fees.
Market Restraints
- Energy input volatility:Proof-of-work consensus mechanisms face cost pressure from electricity price swings in mining-intensive jurisdictions.
- Supplier concentration in cloud infrastructure:Platform uptime depends on three dominant hyperscale providers, creating systemic availability risk.
- EU GDPR data portability mandates:Cross-border data flows require jurisdictional segmentation, fragmenting user bases and increasing compliance overhead.
Strategic Opportunities
- India fintech infrastructure buildout:Unified Payments Interface integration creates real-time settlement rails for domestic P2P payment expansion.
- Central bank digital currency interoperability:Platforms positioning for FedNow and digital euro integration capture formalized payment corridor status.
- AI-driven credit scoring convergence:Machine learning models combined with alternative data sources reduce default rates in thin-file borrower segments.
Industry Challenges
- Smart contract auditor scarcity:Security review bottlenecks delay platform launches and increase vulnerability to exploit-driven losses.
- Legacy core banking integration:On-ramp friction with established financial institutions constrains user acquisition velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peer-To-Peer (P2P) Market |
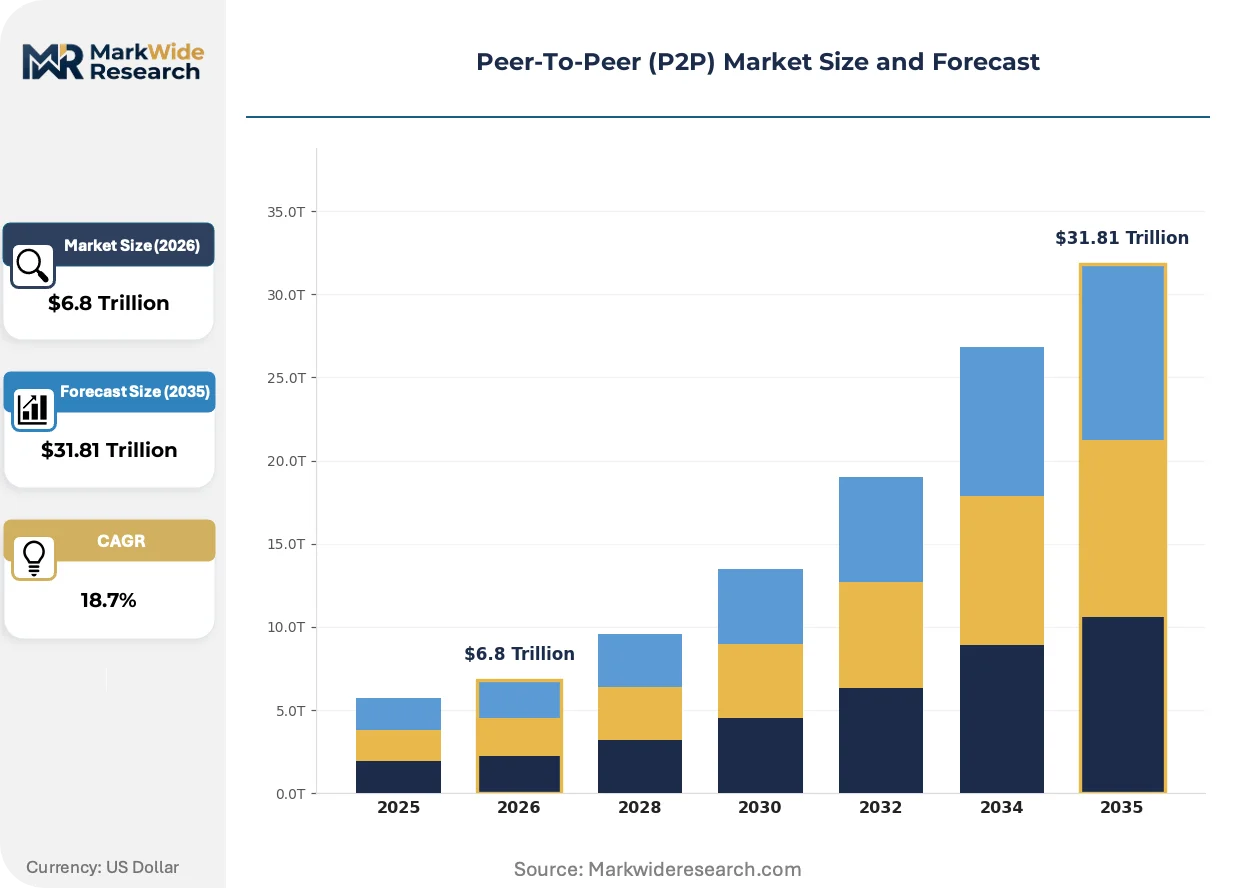
| Market Size in 2026 | $6.8 Trillion |
| Market Size in 2035 | $31.81 Trillion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, File Sharing, Lending Platforms, Content Distribution Technology: Blockchain, Distributed Ledger, Centralized Database, Smart Contracts End User: Consumers, Small Businesses, Freelancers, Nonprofits Deployment Model: Cloud-Based, On-Premises, Hybrid, Mobile Application |
| Companies Covered | BitPay, Pickle, Zopa, Estateguru, Skillshare, Turo, Finery Markets, Primex Finance, Beehive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peer-To-Peer (P2P) Market Evolving Landscape
Distributed ledger architectures are displacing centralized clearing models across lending and payment verticals, while regulatory clarity in major economies accelerates institutional capital deployment into previously informal exchange mechanisms.
Smart contract automation is integrating escrow, collateral management, and interest distribution into self-executing protocols. Decentralized finance platforms deploy these tools to eliminate manual reconciliation overhead. The technology is integrating settlement finality directly into transaction execution, compressing counterparty risk windows from days to minutes.
The EU AI Act imposes algorithmic transparency requirements on automated credit decisions deployed across European jurisdictions. Lenders must document training data provenance and model explainability. Consumer-facing platforms in Germany, France, and the Netherlands are restructuring underwriting workflows to accommodate audit trail mandates before enforcement deadlines.
Buyer preference is rotating toward non-custodial wallet solutions that retain private key control. Institutional treasurers and high-net-worth individuals drive demand for self-custody infrastructure. This pattern concentrates in the United States where regulatory ambiguity around exchange custody has accelerated hardware wallet adoption among sophisticated counterparties.
Peer-To-Peer (P2P) Market Segmentation
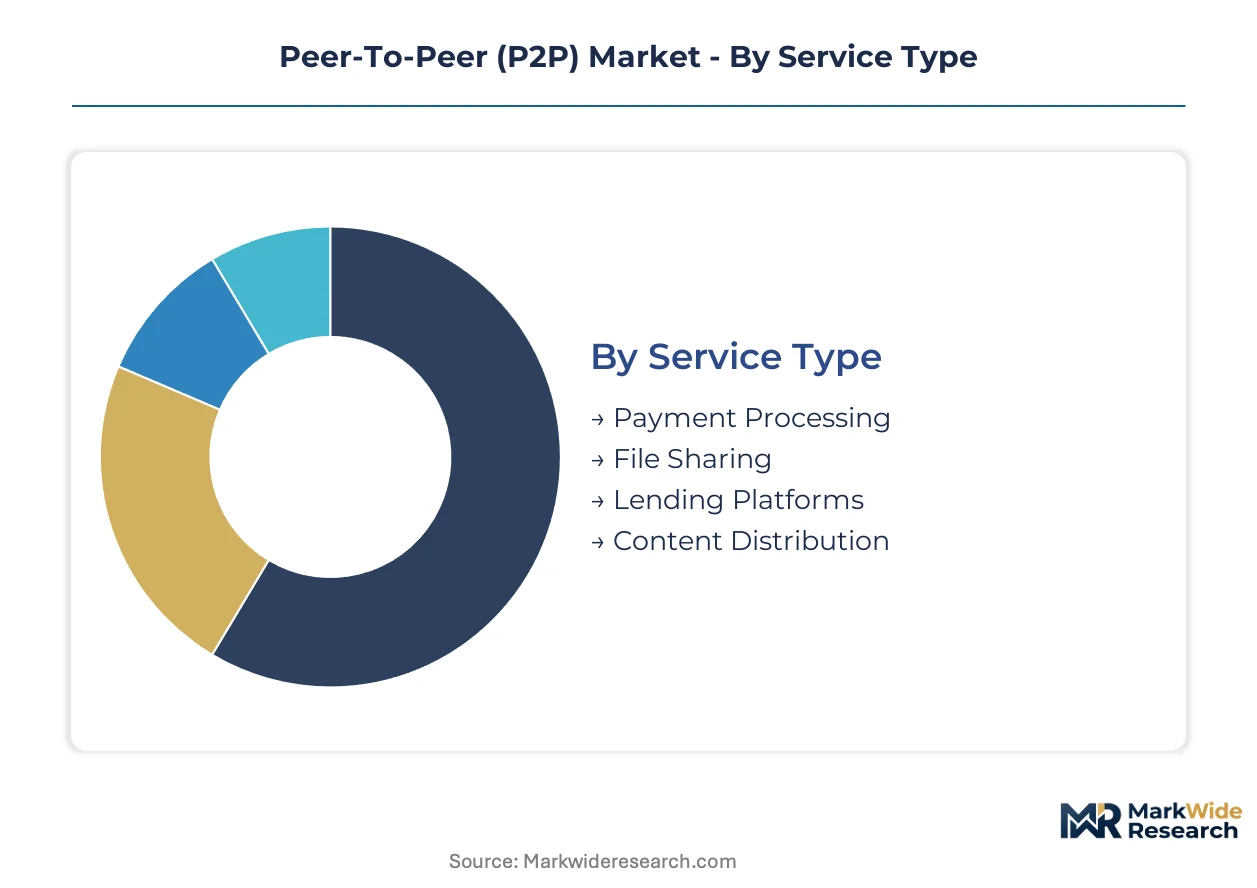
Platform operators architect distinct service configurations to match counterparty risk profiles, settlement velocity requirements, and jurisdictional compliance burdens. Segmentation reveals where margin pools concentrate and which technology stacks capture institutional capital deployment.
Service Type:
Standardized payment rails compete with bespoke lending architectures for platform development resources across the customization spectrum.
- Payment Processing:Real-time settlement protocols handle fiat-to-cryptocurrency conversion and cross-border remittance corridors. Demand clusters among freelancers in the United States and Mexico seeking to bypass correspondent banking delays. Regulatory clarity from the SEC on digital asset classification accelerates institutional onboarding.
- Lending Platforms:Algorithmic underwriting engines match borrowers with capital pools through proprietary credit scoring models. Small businesses with limited banking relationships drive origination volume. Interest-spread economics and origination fee structures command substantial margin pools relative to other verticals.
- File Sharing:Distributed storage architectures enable enterprise users to circumvent centralized cloud costs. Mature adoption curves characterize this segment.
- Content Distribution:Permissionless distribution mechanisms serve creators seeking direct audience monetization without platform intermediation.
Most installed capacity flows through Payment Processing. Expansion is steepest in Lending Platforms.
Technology:
Cost tier separation between capital-intensive blockchain infrastructure and lean centralized alternatives shapes competitive entry barriers.
- Blockchain:Proof-of-work and proof-of-stake consensus mechanisms enable trustless transaction validation without intermediary custody. Mining-intensive jurisdictions face electricity price volatility that compresses operator margins. Capital allocation intensity runs highest here as smart contract automation reduces settlement friction.
- Smart Contracts:Self-executing protocols integrate escrow, collateral management, and interest distribution into immutable code. Decentralized finance platforms deploy these tools to eliminate manual reconciliation overhead. Settlement finality compresses counterparty risk windows from days to minutes.
- Distributed Ledger:Permissioned network architectures serve enterprise consortia requiring known validator sets.
- Centralized Database:Traditional relational architectures persist where regulatory compliance demands audit trail centralization.
Most development resources flow through Blockchain. Smart Contracts are gaining share fastest.
End User:
Customer type stratification separates thin-file borrowers from established enterprises with collateral depth.
- Small Businesses:Enterprises with limited banking relationships bypass traditional intermediaries for working capital access. Algorithmic underwriting engines process alternative data sources to assess creditworthiness. Demand concentrates where fintech infrastructure and regulatory sandboxes have accelerated platform maturation.
- Freelancers:Independent contractors leverage cross-border payment corridors to receive compensation without correspondent banking fees. Remittance corridors between the United States, Mexico, and the Philippines show highest activity.
- Consumers:Individual counterparties utilize P2P systems for personal payments and collaborative consumption.
- Nonprofits:Mission-driven organizations access donation rails with reduced processing overhead.
Most transaction volume originates with Small Businesses. Freelancers show the steepest expansion trajectory.
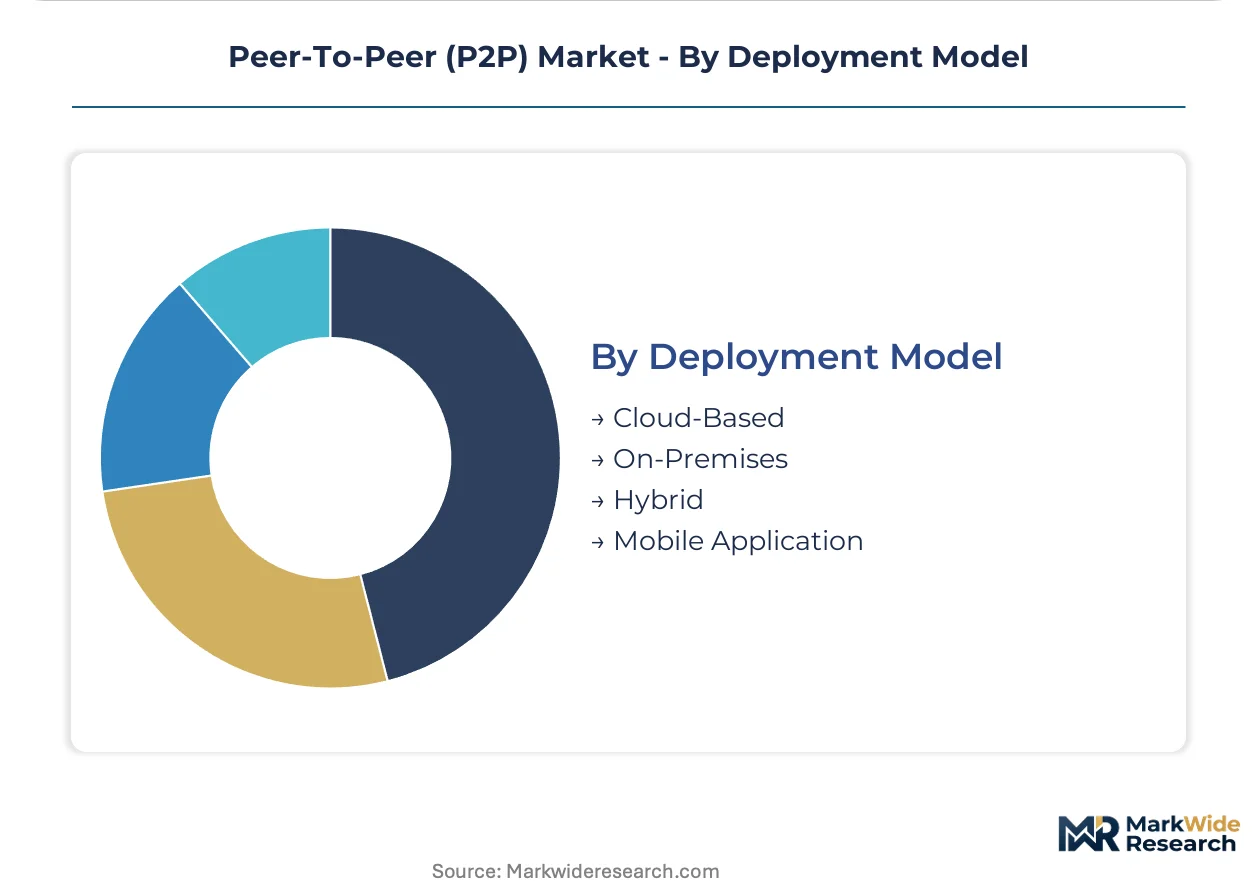
Deployment Model:
Volume concentration in hyperscale cloud infrastructure creates systemic availability risk that hybrid architectures attempt to mitigate.
- Cloud-Based:Hyperscale provider dependence dominates platform uptime architecture. Three dominant suppliers create concentration risk that operators address through multi-region redundancy. Regulatory sandboxes in the United States have accelerated cloud-native platform maturation.
- Mobile Application:Smartphone-native interfaces capture consumer-facing transaction volume through biometric authentication and push notification settlement confirmation. India fintech infrastructure buildout through Unified Payments Interface integration creates real-time settlement rails for domestic expansion.
- Hybrid:Mixed architectures balance sensitive data on-premises with compute-intensive operations in cloud environments.
- On-Premises:Self-managed infrastructure persists where data sovereignty mandates require jurisdictional segmentation.
Most new platform launches deploy through Cloud-Based infrastructure. Mobile Application shows the fastest climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting P2P platform development toward jurisdictions with clearer digital asset frameworks, as operators migrate from high-compliance-cost environments to regulatory sandboxes offering faster licensing pathways and reduced legal uncertainty.
United States
Institutional capital deployment concentrates where SEC registration frameworks provide clarity on tokenized securities classification. Small businesses in Texas and Florida drive lending platform origination volume through algorithmic underwriting engines. The SEC's digital asset guidance reduces legal uncertainty for operators seeking institutional participation.
Germany
EU AI Act compliance requirements reshape automated credit decision workflows across Berlin and Frankfurt financial centers. Consumer-facing platforms restructure underwriting processes to accommodate algorithmic transparency mandates before enforcement deadlines. BaFin oversight creates structured pathways for licensed P2P payment operators.
United Kingdom
Freelancer payment corridors between London and emerging markets leverage cryptocurrency rails to bypass correspondent banking delays. The Financial Conduct Authority's regulatory sandbox accelerates platform maturation for domestic P2P lending expansion. Manchester and Birmingham clusters show concentrated demand from thin-file borrower segments.
India
Unified Payments Interface integration creates real-time settlement rails for domestic P2P payment expansion among small businesses in Mumbai and Bangalore. RBI oversight of fintech licensing channels capital toward compliant platform operators. The country's national payment regulator prioritizes interoperability standards that reduce fragmentation.
Singapore
Cross-border remittance corridors between Singapore and Southeast Asian markets attract platform operators seeking stable regulatory environments. The Monetary Authority of Singapore's digital asset framework provides licensing clarity for institutional-facing P2P infrastructure. The city-state's fintech cluster concentrates blockchain development resources.
Peer-To-Peer (P2P) Market Competitive Landscape
United States platforms anchor one tier of the competitive structure; European specialists hold differentiated positions in lending automation and payment processing. The vendor base separates into three tiers: capital-intensive blockchain infrastructure operators, algorithmic underwriting specialists, and niche vertical platforms. Strategic archetypes include cryptocurrency payment rail providers, proprietary credit scoring engine developers, and fleet-owner onboarding standard setters. Dominant competitive moves center on smart contract automation integration and regulatory sandbox positioning.
Within the payment processing archetype, BitPay exemplifies cryptocurrency rail deployment for cross-border volume. Zopa occupies a position among algorithmic credit scoring specialists serving consumer lending segments. Turo represents the vertical-specific platform tier through vehicle-sharing infrastructure standards. These three anchors illustrate how geographic origin and service specialization stratify competitive positioning across the ecosystem.
| Leading Market Players |
|---|
| BitPay |
| Pickle |
| Zopa |
| Estateguru |
| Skillshare |
| Turo |
| Finery Markets |
| Primex Finance |
| Beehive |
| Others |
Value Network & Pricing Analysis
Smart contract auditor concentration in Eastern Europe and South Asia widens pricing-tier spreads between institutional-grade platforms and retail-facing alternatives, as labor-cost differentials in security review capacity translate directly to platform launch timelines and compliance premiums.
Pricing Analysis
Direct-to-platform transaction fees bypass distributor margin layers entirely, compressing cost structures relative to traditional financial intermediaries. Pricing stratifies across institutional, professional, and retail tiers based on settlement velocity requirements and custody insurance levels. Cost compression in retail payment processing intensifies because cryptocurrency rail operators undercut correspondent banking fees by eliminating intermediary settlement layers. Freelancers in cross-border remittance corridors exhibit highest price sensitivity, while institutional treasurers prioritize settlement finality over fee minimization.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud infrastructure concentrated in the United States, Ireland, and Singapore, where three dominant providers anchor platform uptime architecture. Blockchain node operations draw from specialized semiconductor fabrication in Taiwan, mining equipment manufacturing in China, and renewable energy inputs from Nordic hydroelectric grids. Tariff exposure on mining hardware shipments between China and North American hosting facilities threatens margin stability at proof-of-work operators. Distribution runs through API-first integration layers that embed payment rails directly into enterprise ERP and accounting software stacks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Peer-To-Peer market compounds steadily as algorithmic underwriting engines displace traditional credit assessment, embedding recurring revenue streams through interest-spread economics and origination fee structures.
For Market Incumbents: Anticipate regulatory fragmentation across European and Asian jurisdictions by pre-positioning compliance architecture for divergent AI transparency mandates and data localization requirements. Consolidate smart contract audit relationships in Eastern Europe before talent scarcity drives review costs upward. Prioritize FedNow and digital euro integration to capture formalized payment corridor status before central bank digital currency interoperability becomes table stakes. For New Entrants and Emerging Players: The price-point gap between premium institutional lending platforms and economy-tier retail payment processors creates entry space for mid-market algorithmic underwriting specialists targeting thin-file small businesses in India and Southeast Asia. Underpenetrated freelancer payment corridors between the United Kingdom and Philippines offer lowest competitive density. Lead with mobile-native onboarding and biometric KYC to bypass legacy core banking integration friction. For Investors and Strategic Acquirers: Fintech infrastructure consolidators are the most active acquirer in this space, seeking proprietary credit scoring engines and licensed payment operators with regulatory sandbox track records. Long-term viability rests on platform ability to automate compliance overhead rather than absorb it as operational cost. Watch central bank digital currency interoperability announcements as the signal indicating which payment rail operators will retain corridor relevance versus face disintermediation.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Contract Automation Integration | Settlement finality compression from days to minutes eliminates counterparty risk windows at decentralized lending protocols. |
| Regulatory Sandbox Positioning | Early licensing in SEC, BaFin, and MAS frameworks reduces legal uncertainty for institutional capital participation. |
| Algorithmic Underwriting Engine Development | Machine learning models trained on alternative data sources reduce default rates in thin-file borrower segments. |
| Cross-Border Payment Rail Expansion | Cryptocurrency settlement corridors between United States, Mexico, and Philippines undercut correspondent banking fees. |
| Non-Custodial Wallet Infrastructure Buildout | Self-custody solutions retain private key control for institutional treasurers seeking regulatory ambiguity protection. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with platform engineering leads, regulatory compliance officers at fintech operators, credit risk modelers at algorithmic lenders, and procurement managers at enterprise cloud infrastructure providers with secondary validation against SEC registration filings, EU regulatory impact assessments, RBI fintech licensing records, and UPI transaction volume disclosures. Bottom-up platform revenue aggregation and top-down addressable market sizing were triangulated for consistency.
Historical reference periods anchored the projection horizon to observed adoption curves across blockchain infrastructure deployment, algorithmic credit decision penetration, and central bank digital currency pilot programs. Segmentation dimensions modeled include service type, underlying technology stack, end-user archetype, and deployment model complexity. CAGRs were derived from fitted growth curves calibrated to regulatory milestone timing and capital deployment velocity. Forecast inputs incorporated smart contract audit capacity constraints and cloud infrastructure availability thresholds.
Caveats apply where central bank digital currency interoperability announcements, AI Act enforcement deadline shifts, or energy input volatility in mining-intensive jurisdictions could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
North America B2C Legal Services Market
Financial Services
Latin America Factoring Services Market
Financial Services
Saas Escrow Services Market
Financial Services
Global Executive Search (Headhunting) Market
Financial Services
Europe Financial Advisory Services Market
Financial Services
Africa Lottery Market
Financial Services
Factoring Services Market
Financial Services
India Legal Services Market
Financial Services
Pawn Shop Market
Financial Services
North America Management Consulting Services Market
Financial Services
Reverse Factoring Market
Financial Services
Broker Affiliate Programs Market
Financial Services
Direct Selling Market
Financial Services
Europe Factoring Services Market
Financial Services
Multivendor ATM Software Market
Financial Services
Global Temporary Labor Market