
 E-Invoicing Market | 2026-2036
E-Invoicing Market Size, Share, and Industry Trends Forecast 2026-2036
E-Invoicing Market Intelligence
Subscription-based validation and compliance layers is decoupling pure software licenses from recurring revenue in e-invoicing. SAP SE leverages its ERP installed base to anchor government-mandated clearance model integrations across Continental Europe. Oracle Corporation competes through embedded financials suites that extend invoice automation into procurement and treasury workflows. Basware Corporation specializes in hybrid deployment architectures that navigate strict data residency requirements in Nordic public sector accounts.
E-invoicing denotes the structured digital exchange of bill and payment data between supplier and buyer systems, typically via XML or UBL formats validated against tax authority schemas before commercial settlement. The primary purpose is to reduce manual processing latency, eliminate paper archiving burdens, and enable real-time fiscal transparency for audit and VAT collection. Cloud-based deployment leads absolute spend as mid-market enterprises abandon on-premises maintenance overhead for API-first platforms with automatic regulatory updates. The SME end-user segment represents the fastest-growing addressable pool, though margin concentration remains with large enterprise accounts requiring multi-entity, multi-country workflow orchestration across manufacturing and retail verticals.
Italy's Agenzia delle Entrate enforces FatturaPA XML standards for domestic transactions, while Saudi Arabia's ZATCA mandates phased e-invoicing integration with its Fatoora platform, directly shaping product roadmaps for clearance-centric vendors. Brazil's Nota Fiscal Eletrônica framework, administered by state finance secretariats, requires pre-issuance authorization and creates asymmetric compliance complexity for foreign entrants. Stakeholders must monitor whether emerging economies adopt clearance models versus post-audit reporting architectures, as this regulatory choice determines platform architecture investments and partnership requirements for the next decade.
Market Dynamics
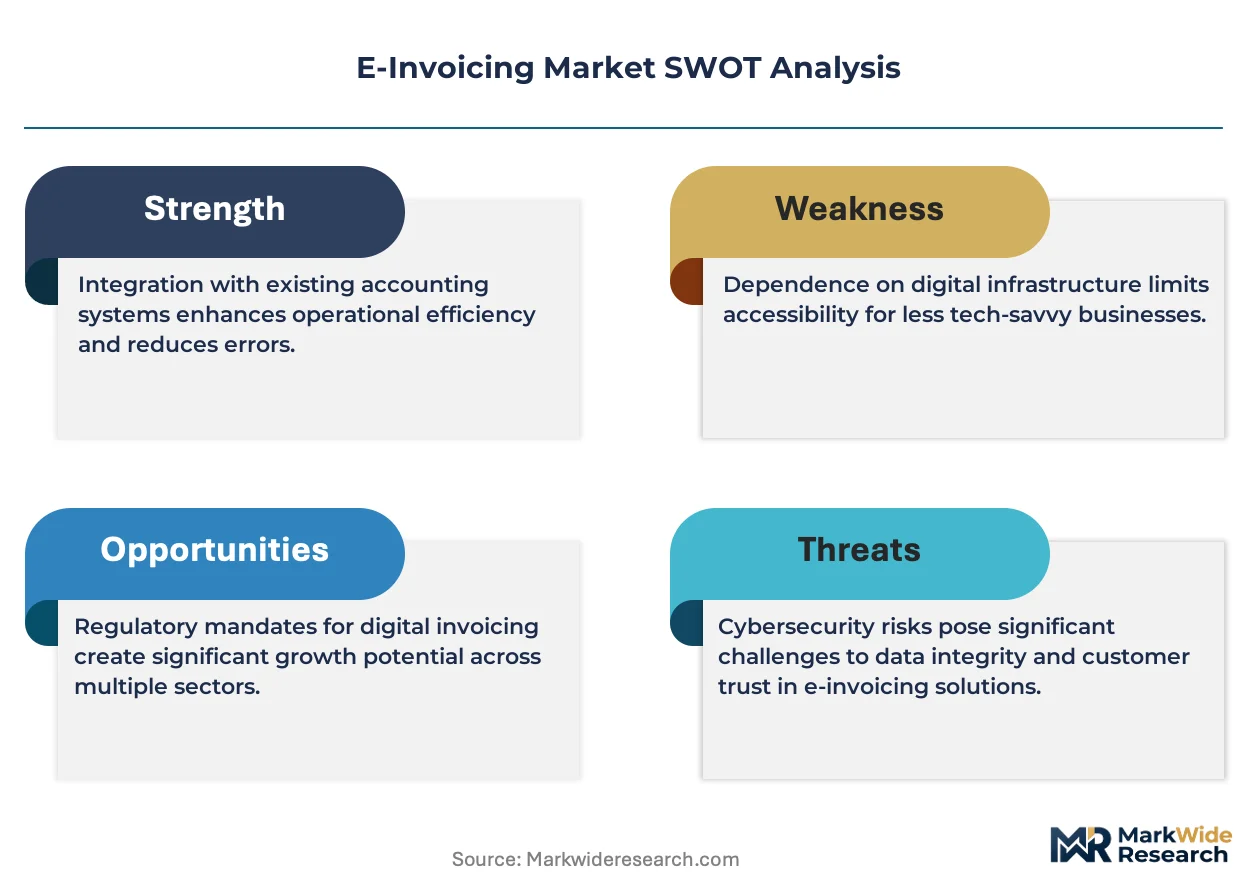
Clearance-model mandates from tax authorities are forcing platform vendors to rearchitect their systems for real-time government validation, privileging API-native providers over legacy batch-processing incumbents.
Growth Catalysts
- PEPPOL Network Expansion:EU member states are adopting this interoperability framework for cross-border B2G and B2B transactions, standardizing XML-based invoice exchange across national boundaries.
- Fatoora Platform Mandates:Saudi Arabia's ZATCA requires phased integration for domestic businesses, creating immediate demand for Arabic-language clearance solutions with QR-code generation capabilities.
- Real-time VAT Reporting:Manufacturers and retailers are replacing monthly filings with continuous transaction reporting to tax authorities, eliminating reconciliation backlogs.
Market Restraints
- Schema Fragmentation:Brazil's Nota Fiscal Eletrônica uses state-level variations that multiply compliance complexity for foreign platform entrants seeking national coverage.
- Data Residency Requirements:Nordic public sector contracts mandate on-premise or sovereign-cloud deployments, constraining pure-SaaS expansion in high-value government accounts.
- Legacy ERP Lock-in:Enterprises running decade-old on-premise financial systems face prohibitive migration costs to API-first e-invoicing architectures.
Strategic Opportunities
- SME Segment Penetration:Mid-market retailers in Germany and France remain underserved by enterprise-focused vendors, creating whitespace for simplified self-service onboarding.
- ViDA Reform Alignment:The EU's VAT in the Digital Age package mandates e-invoicing for intra-community transactions, requiring platform upgrades across member states.
- Blockchain-anchored Verification:Immutable ledger integration with UBL formats is emerging as a fraud-prevention layer for high-value B2B contracts in trade finance.
Industry Challenges
- Multi-format Mapping Complexity:Technical teams must maintain parallel validation pipelines for FatturaPA XML, UBL 2.1, and national variants simultaneously.
- Clearance Latency Management:Real-time tax authority response requirements compress processing windows to sub-second thresholds during peak billing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Invoicing Market |
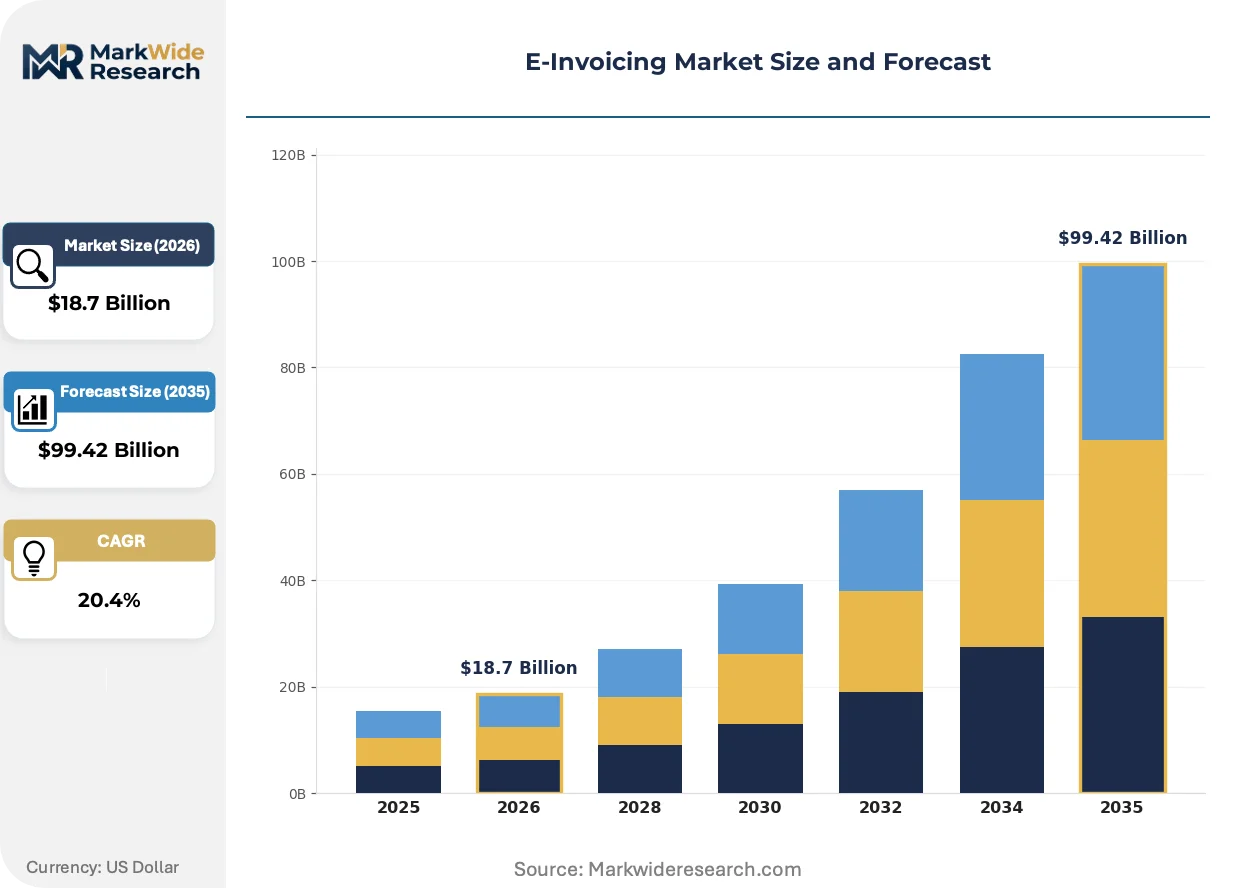
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $99.42 Billion |
| CAGR (2026 – 2036) | 20.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-based, On-premises, Hybrid, Mobile End User: Large Enterprises, SMEs, Government, Freelancers Payment Method: Credit/Debit Cards, Bank Transfers, Digital Wallets, Checks Industry Vertical: Retail, Manufacturing, Healthcare, Education |
| Companies Covered | SAP SE, Oracle Corporation, Basware Corporation, Coupa Software Inc, Sage Group plc, Tradeshift Holdings Inc, International Business Machines Corporation, Comarch SA, Pagero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Invoicing Market Strategic Shifts & Innovations
Distributed ledger architectures and API standardization are converging to reshape how invoice data flows between private enterprise systems and government clearance platforms.
Blockchain-based invoice verification is decentralizing trust mechanisms in high-value supply chains. Automotive and aerospace manufacturers in Germany are piloting immutable audit trails for multi-tier supplier networks. This architecture is decentralizing the role of centralized clearinghouses in cross-border trade finance.
The EU's ViDA reform is accelerating mandatory e-invoicing timelines for intra-community B2B transactions. Member state tax authorities must harmonize technical specifications by 2030, compressing vendor certification cycles. Mid-market software providers are responding with pre-certified PEPPOL access point bundles.
Mid-market enterprises are consolidating vendor relationships from point solutions to integrated financial operations platforms. Retailers and manufacturers are replacing standalone e-invoicing modules with suites embedding procurement and treasury workflows. This consolidation is most visible in the Benelux region, where cross-border VAT complexity favors unified platform contracts.
E-Invoicing Market Segmentation
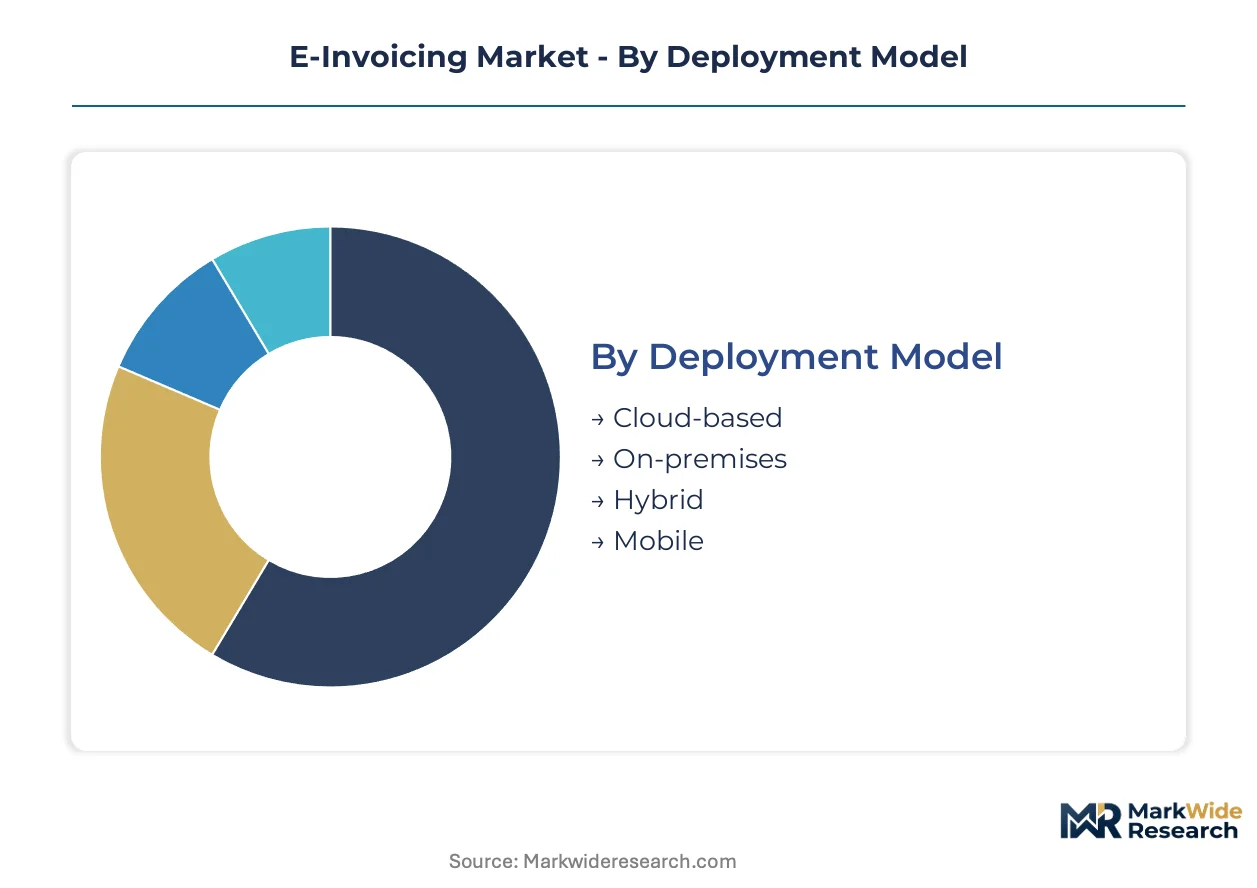
E-invoicing vendors architect their product portfolios around four distinct segmentation axes. Each dimension reflects divergent technical requirements, compliance burdens, and procurement behaviors that shape platform design and go-to-market strategy.
Deployment Model:
Standardization dominates at the infrastructure layer while customization proliferates at the integration edge across deployment architectures.
- Cloud-based:Multi-tenant SaaS architectures with automatic schema updates for PEPPOL, FatturaPA, and Fatoora compliance. Mid-market retailers in Germany and France favor this model for zero-maintenance VAT reporting. Leading the category by volume: Cloud-based. Growing fastest: Hybrid.
- On-premises:Single-tenant installations behind corporate firewalls with manual patch cycles for regulatory changes. Nordic public sector accounts in Sweden and Norway mandate this architecture for data sovereignty.
- Hybrid:Split processing with sensitive validation on-premise and clearance routing through cloud gateways. Manufacturers with multi-country ERP footprints adopt this to balance latency against residency rules.
- Mobile:Native iOS and Android applications with QR-code scanning for field sales teams and delivery confirmations. Freelancers and last-mile logistics operators drive adoption here.
Cloud-based deployments capture the majority of new contract value. Hybrid architectures are expanding most quickly as enterprises navigate conflicting data residency mandates across operating jurisdictions.
End User:
Contract complexity and implementation timelines stratify sharply across organizational scale, with procurement patterns diverging at each tier.
- Large Enterprises:Multi-entity deployments requiring workflow orchestration across SAP, Oracle, and Microsoft Dynamics environments. These accounts demand dedicated customer success teams and custom SLA terms. Automotive and aerospace manufacturers in Germany anchor this segment.
- SMEs:Self-service onboarding through pre-configured templates for single-country operations. French and German mid-market retailers represent the largest untapped pool, underserved by enterprise-focused vendors.
- Government:Mandatory B2G compliance deadlines in Italy, Saudi Arabia, and Brazil create captive demand with rigid technical specifications and extended procurement cycles.
- Freelancers:Lightweight mobile-first solutions with basic UBL 2.1 generation and minimal validation layers. This tier shows the steepest expansion trajectory as gig economy participation rises.
Large Enterprises contribute the highest absolute revenue per account. Freelancers are gaining share fastest as platform economics improve for micro-merchant onboarding.
Payment Method:
Settlement velocity and fraud exposure create divergent technical requirements across payment rails.
- Credit/Debit Cards:PCI-DSS compliant tokenization with real-time authorization hooks. E-commerce retailers in Italy and Spain favor this for immediate cash conversion.
- Bank Transfers:SEPA and SWIFT integration with automated reconciliation against invoice references. B2B manufacturers across the Benelux region prefer this for high-value contract settlements.
- Digital Wallets:API connections to PayPal, Apple Pay, and regional wallets with instant notification webhooks. Mobile-first freelancers and field service businesses drive adoption.
- Checks:Legacy paper-to-digital conversion services with OCR capture and manual exception handling. Declining share concentrated in long-tail industrial suppliers with aged procurement practices.
Bank Transfers process the highest transaction value. Digital Wallets are climbing the fastest as real-time payment infrastructure matures.
Industry Vertical:
Regulatory intensity and supply chain complexity create distinct capability requirements across sectors.
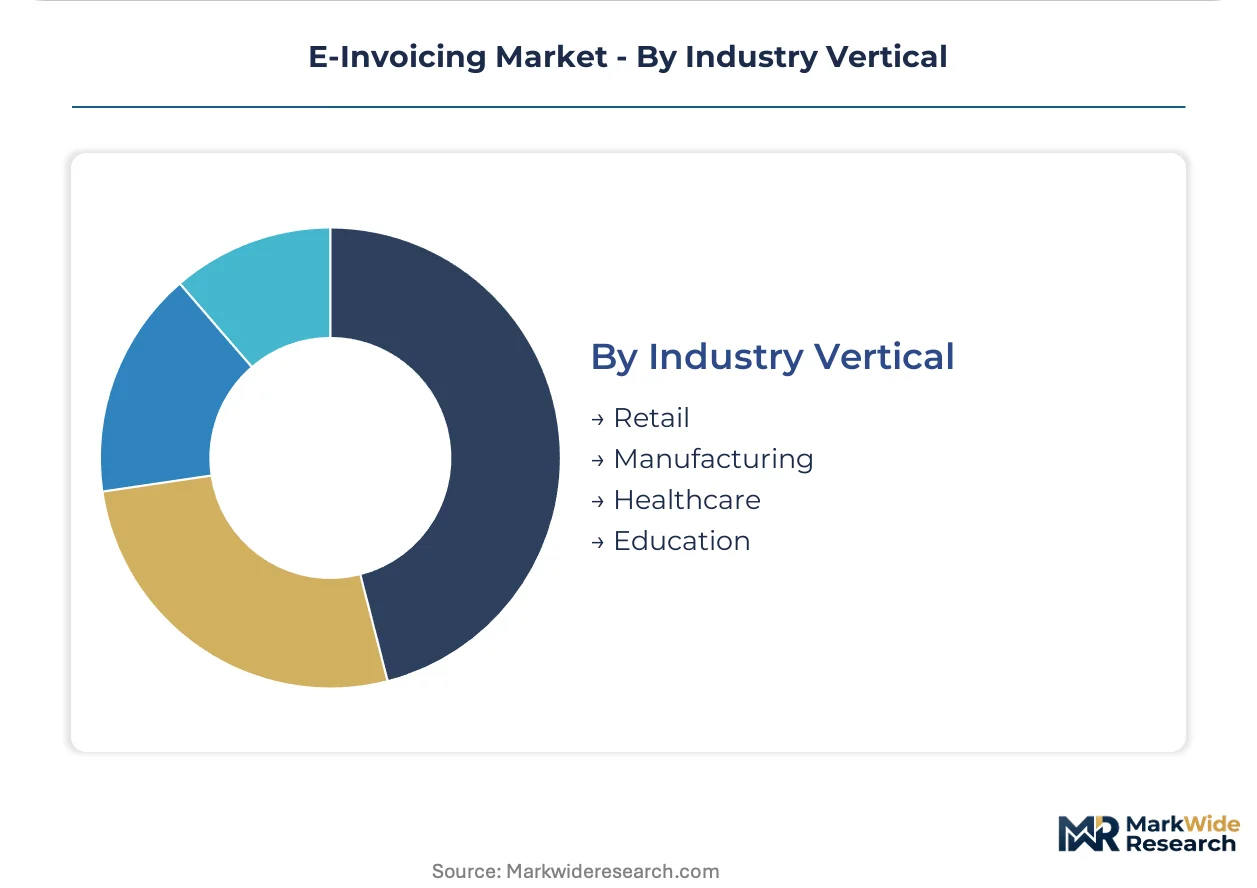
- Retail:High-volume, low-value transaction processing with seasonal peak handling and omnichannel return integration. Cross-border VAT complexity in the EU drives demand for automated PEPPOL routing.
- Manufacturing:Multi-tier supplier networks with milestone-based invoicing and advance payment structures. German automotive OEMs pilot blockchain-anchored verification for tier-n supplier transparency.
- Healthcare:HIPAA and GDPR-aligned archiving with patient data segregation from financial records. Hospital networks in France and Italy require specialized compliance modules.
- Education:Grant-funded procurement with restricted-use validation and public disclosure requirements. University systems in Saudi Arabia adopt Fatoora-integrated platforms for ZATCA reporting.
Retail generates the highest transaction volume. Healthcare is expanding most quickly as telemedicine platforms digitize patient billing workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy and Saudi Arabia consume the most advanced clearance-model platforms, while Germany and Brazil generate disproportionate vendor R&D investment. The production of e-invoicing software concentrates in ERP-anchored technology clusters across Central Europe and North America.
Italy
Domestic retailers and manufacturers drive demand for FatturaPA XML validation. The Agenzia delle Entrate enforces real-time submission for all B2B and B2G transactions. Milan anchors the largest concentration of compliance-integrated ERP deployments in Southern Europe.
Germany
Automotive OEMs and tiered supplier networks require PEPPOL-accessible multi-entity orchestration. The Federal Ministry of Finance aligns national standards with EU ViDA reform timelines. Stuttgart and Munich host the densest clusters of blockchain-anchored invoice verification pilots.
Saudi Arabia
Domestic wholesalers and construction contractors face phased Fatoora platform integration deadlines. ZATCA mandates QR-code generation and real-time clearance for all VAT-registered businesses. Riyadh concentrates Arabic-language platform development and government contract awards.
Brazil
State-level finance secretariats enforce Nota Fiscal Eletrônica pre-authorization for goods movement. Foreign platform entrants navigate asymmetric compliance complexity across 27 state variations. São Paulo anchors the largest captive demand for NF-e integrated tax reporting systems.
France
Mid-market retailers seek simplified onboarding for Chorus Pro B2G compliance and future B2B mandates. The Direction Générale des Finances Publiques prepares technical specifications for 2026 ViDA alignment. Paris hosts the most active PEPPOL access point certification activity in the Eurozone.
E-Invoicing Market Key Industry Players
Top-tier vendors anchor enterprise ERP integration, while mid-market specialists compete on self-service onboarding speed. The vendor base stratifies across three tiers: ERP-anchored incumbents with government clearance partnerships, best-of-breed workflow specialists, and API-native challengers. Dominant competitive moves include pre-certified PEPPOL access point bundling and hybrid deployment architecture development for data residency constraints.
Within the ERP-anchored tier, SAP SE and Oracle Corporation exemplify platform consolidation strategies that embed invoice automation into broader financial operations suites. Basware Corporation occupies a position among workflow specialists targeting hybrid deployment requirements in Nordic public sector accounts. These three entities represent the dominant archetypes shaping competitive dynamics: ERP extension, best-of-breed orchestration, and compliance-centric specialization.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Basware Corporation |
| Coupa Software Inc |
| Sage Group plc |
| Tradeshift Holdings Inc |
| International Business Machines Corporation |
| Comarch SA |
| Pagero |
| Others |
Cost & Logistics Intelligence
API gateway infrastructure costs cascade through subscription tiers as vendors balance real-time clearance latency requirements against multi-tenant SaaS economics, compressing margins for mid-market providers while enterprise accounts absorb premium pricing for dedicated throughput.
Pricing Analysis
Margin tightening in the mid-market SaaS tier reflects schema maintenance burdens across FatturaPA, Fatoora, and PEPPOL variants. Three-tier pricing structure across premium, standard, and economy levels segments by validation pipeline complexity and SLA guarantees. Cost compression accelerates because automatic regulatory update features became table stakes. SMEs exhibit highest price sensitivity, while automotive OEMs accept premium rates for multi-entity orchestration.
Supply Chain Analysis
Single-source vulnerability sits with Nordic sovereign cloud providers serving public sector accounts with data residency mandates. Software development concentrates in Germany, the United States, and Estonia. Raw material dependencies include cryptographic certificate services, XML validation engines, and QR-code generation libraries. Regulatory restriction risk looms as Brazil's state-level NF-e variations fragment compliance architecture. Distribution runs through API-first platform marketplaces and direct ERP integration partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified PEPPOL access point scarcity props pricing power for vendors with pre-approved interoperability status, constraining rapid supply expansion despite surging demand from ViDA-aligned enterprises.
For Market Incumbents: Lock in government clearance partnerships before Fatoora phase deadlines solidify vendor rosters. Deepen API-native architecture investments to displace legacy batch-processing competitors. Basware Corporation's hybrid deployment specialization in Nordic accounts demonstrates defensible positioning against pure-SaaS challengers. For New Entrants and Emerging Players: ViDA reform in France and Germany opens a window for simplified self-service onboarding targeting mid-market retailers underserved by enterprise-focused vendors. White space concentrates in Benelux cross-border VAT automation and Saudi Arabia Arabic-language compliance. Go-to-market leverage rests on pre-certified PEPPOL bundles with zero-configuration ERP connectors. For Investors and Strategic Acquirers: Distressed-cycle entries favor workflow specialists with hybrid deployment capabilities in Northern Europe. Long-term viability hinges on regulatory certification moats rather than feature differentiation. Watch ZATCA enforcement intensity in Saudi Arabia as inflection indicator for emerging market clearance-model adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| PEPPOL Access Point Certification | Pre-approved interoperability status unlocks EU public sector procurement pipelines. |
| Hybrid Deployment Architecture | Split processing satisfies Nordic data residency without sacrificing cloud scalability. |
| Fatoora Integration Partnership | Arabic-language QR-code clearance captures Saudi Arabia's phased mandate timeline. |
| Blockchain-anchored Verification | Immutable audit trails differentiate high-value B2B contract offerings in Germany. |
| SME Self-service Platform | Template-based onboarding penetrates France and Germany's underserved mid-market retailers. |
Research Approach
Document review covered regulatory filings from Italy's Agenzia delle Entrate, Saudi Arabia's ZATCA, and Brazil's state finance secretariats, complemented by interviews with platform engineering leads, ERP integration specialists, tax technology consultants, and procurement officers at automotive OEMs. Secondary validation drew from PEPPOL authority specifications, EU ViDA technical documentation, and customs data on cross-border digital service flows. Bottom-up contract value analysis triangulated against top-down market sizing from ERP vendor disclosures.
Segment-level outputs across deployment model, end-user scale, payment rail, and industry vertical dimensions fed into CAGR derivation through regression against regulatory mandate timelines and enterprise software spend patterns. API transaction volume trajectories and clearance-model adoption curves served as primary forecast inputs throughout the projection horizon.
Caveats apply where regulatory implementation delays or schema standardization failures could materially shift the outlook. Forecasts reflect assumptions about PEPPOL network expansion velocity and ViDA harmonization deadlines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
India Trade Finance Market
Financial Services
Financial Services Operational Risk Management Solution Market
Financial Services
Belgium Gift Card and Incentive Card Market
Financial Services
Reconciliation Software Market
Financial Services
China Factoring Services Market
Financial Services
Global Executive Search (Headhunting) Market
Financial Services
Online Investment Platform Market
Financial Services
Global Management Consulting Services Market
Financial Services
Spain E-Brokerage Market
Financial Services
Intellectual Property Rights and Royalty Management Market
Financial Services
Australia Online Gambling Market
Financial Services
Europe Financial Advisory Services Market
Financial Services
E-KYC Market
Financial Services
Cash Flow Market
Financial Services
Global Product Cost Management Market
Financial Services
BFSI A2P SMS Market