
 Australia Gift Card and Incentive Card Market | 2026-2036
Australia Gift Card and Incentive Card Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Gift Card and Incentive Card Market Outlook
The Australian Competition and Consumer Commission's gift card expiry minimums is recalibrating issuer product design across the sector. Woolworths Group Ltd. anchors supermarket distribution through its extensive in-store redemption network. Prezzee differentiates via app-native digital delivery that bypasses physical logistics entirely. TCN – The Card Network competes through white-label platform services for mid-tier retail brands.
Gift cards and incentive cards are stored-value instruments encoded with magnetic stripes, EMV chips, or QR-linked digital tokens, manufactured through PVC card printing or API-based cloud provisioning, designed to transfer purchasing power without cash exchange. Digital Cards are capturing the fastest expansion as mobile wallet penetration deepens, while Physical Cards retain dominance in supermarket and convenience store aisles where impulse purchases concentrate. Corporate Clients within the Customer Type dimension are generating outsized volume as enterprise HR and procurement teams consolidate vendor relationships.
The Reserve Bank of Australia's payments system oversight and ASIC's financial product disclosure requirements jointly govern stored-value facility licensing and consumer protections. The Australian Securities and Investments Commission mandates clear fee disclosure and dispute resolution pathways for reloadable products. Stakeholders must track how open banking data-sharing standards reshape digital card funding interoperability and loyalty program integration.
Market Dynamics
The Australian Competition and Consumer Commission's gift card expiry reforms are forcing issuers to redesign product economics around minimum three-year validity periods. This regulatory compression is absorbing margin buffers while accelerating digital wallet integration across Sydney and Melbourne payment corridors.
Growth Catalysts
- ASIC Stored-Value Facility Licensing:Clearer regulatory pathways for reloadable products are expanding corporate procurement volumes as HR departments consolidate vendor relationships under compliant frameworks.
- Mobile Wallet Penetration:API-based cloud provisioning is displacing PVC card printing logistics, reducing physical distribution costs for digital-native delivery platforms.
- Enterprise Reward Program Consolidation:Procurement teams across banking and telecommunications sectors are standardizing prepaid card disbursements for employee recognition and sales incentives.
Market Restraints
- Interchange Fee Compression:Reserve Bank of Australia payments system oversight is constraining issuer revenue margins on transaction processing.
- Physical Distribution Concentration:Supermarket and convenience store aisle dominance by Woolworths Group creates channel dependency for impulse gift card purchases.
- Fraud Vector Proliferation:QR-linked digital tokens face elevated scam risks that increase compliance costs and consumer dispute resolution burdens.
Strategic Opportunities
- Open Banking Data Standards:Account-to-account payment interoperability is enabling real-time card funding and loyalty program integration for fintech entrants.
- Regional Queensland and Western Australia:Underpenetrated digital wallet adoption outside Sydney-Melbourne corridors offers geographic expansion white space.
- White-Label Platform Services:Mid-tier retail brands seek outsourced card program management without captive technology investment.
Industry Challenges
- Legacy POS Integration Complexity:EMV chip and magnetic stripe acceptance infrastructure requires costly terminal upgrades for smaller merchants.
- Skill Scarcity in Cloud Provisioning:API architecture and tokenization security expertise commands premium compensation in tight Australian technology labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Gift Card and Incentive Card Market |
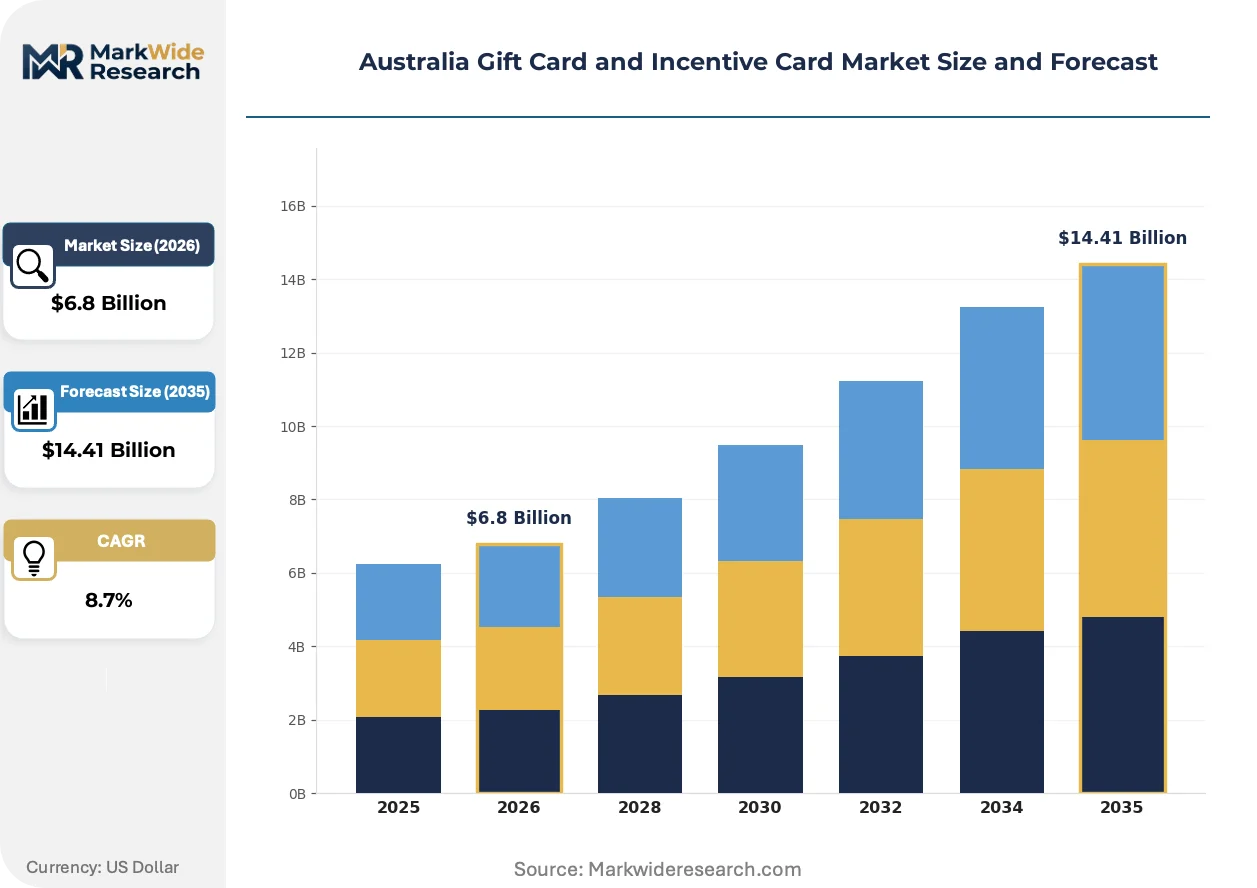
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Physical Cards, Digital Cards, Prepaid Cards, Reloadable Cards Customer Type: Retail Consumers, Corporate Clients, Non-profits, Event Organizers Distribution Channel: Online Retailers, Supermarkets, Convenience Stores, Specialty Stores Usage Purpose: Personal Gifts, Employee Incentives, Marketing Promotions, Loyalty Rewards |
| Companies Covered | Woolworths Group Ltd., JB Hi-Fi Ltd., Blackhawk Network, TCN – The Card Network, Edge Loyalty (Village Roadshow), Prezzee, Wesfarmers Ltd., Apple Inc., InComm Payments, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Gift Card and Incentive Card Market Strategic Shifts
Digital delivery mechanisms are compressing physical card logistics while regulatory mandates reshape product design economics. Three convergent developments are redefining competitive positioning across issuer and platform tiers.
API-based cloud provisioning is absorbing the middleware layer between issuer systems and consumer mobile wallets. Enterprise procurement teams are adopting these interfaces for bulk employee reward distribution. This technology compression is eliminating physical card manufacturing and postal fulfillment costs from corporate program economics.
The Australian Competition and Consumer Commission's three-year minimum expiry mandate is recalibrating breakage revenue models across reloadable and single-load products. Issuers are restructuring fee disclosures and dormancy charge schedules to maintain profitability under extended liability periods. White-label platform providers are absorbing these compliance redesign costs for mid-tier retail clients lacking in-house legal resources.
Corporate HR departments are consolidating vendor relationships around integrated reward and recognition platforms. Traditional single-purpose gift card procurement is yielding to bundled incentive management systems with analytics dashboards. This buying-pattern shift is most visible in Sydney and Melbourne financial services and telecommunications sectors where procurement centralization has advanced furthest.
Australia Gift Card and Incentive Card Market Segmentation
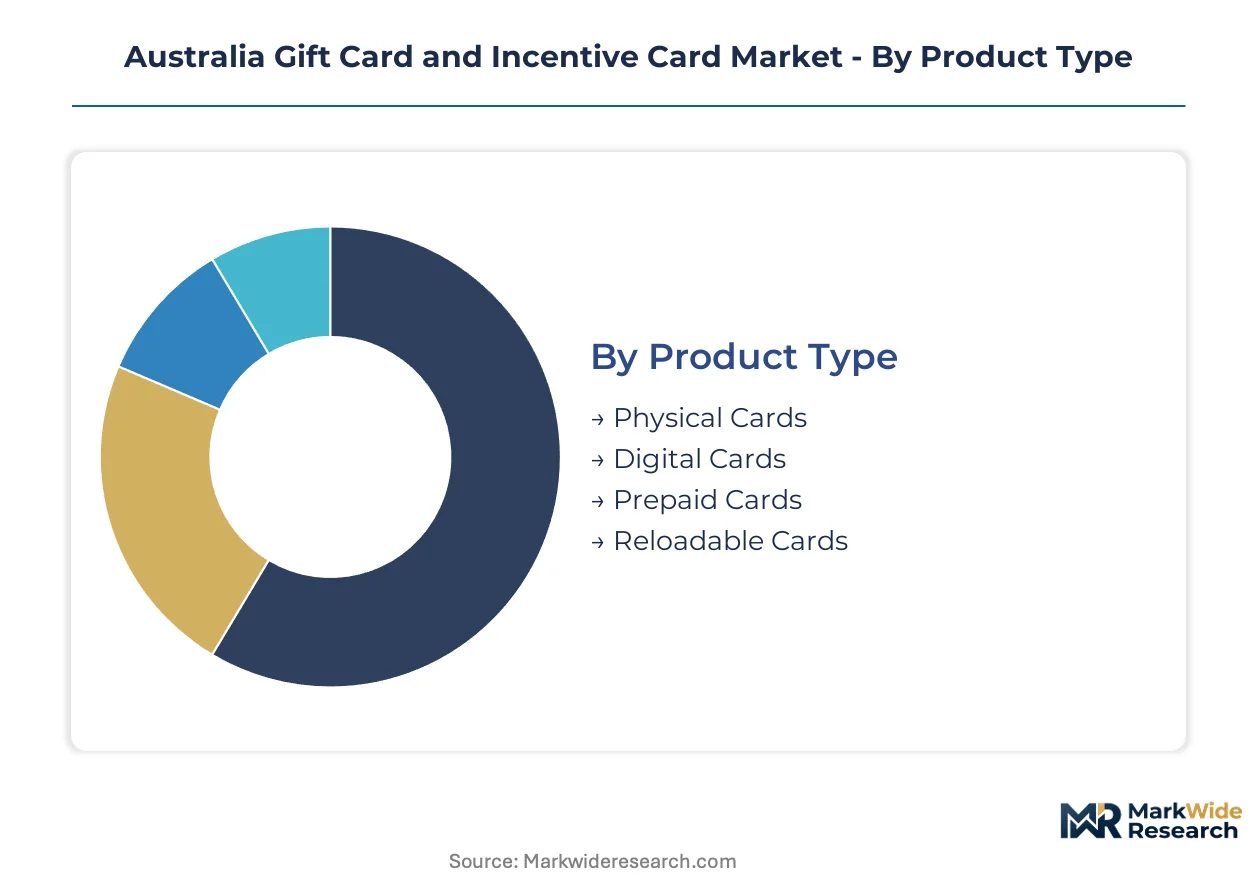
Segmentation in the Australian gift card market reveals how procurement patterns diverge between impulse retail purchases and structured corporate disbursements. Understanding these divides exposes where platform economics favor digital delivery over physical logistics.
Product Type:
Cost tier determines whether issuers absorb PVC manufacturing and postal fulfillment or capture margin through API-based provisioning.
- Physical Cards:Magnetic stripe and EMV chip credentials printed on PVC substrates dominate supermarket checkout aisles and convenience store displays. Woolworths Group's in-store network concentrates impulse purchase volume across Sydney and Melbourne metro corridors where breakage economics still justify production overhead.
- Digital Cards:QR-linked tokens delivered via API-to-wallet integration bypass physical logistics entirely. Mobile wallet penetration in Australian financial services and telecommunications sectors is compressing delivery costs for corporate reward programs that demand instant fulfillment.
- Prepaid Cards:Single-load stored-value instruments carry fixed denominations with ASIC-mandated fee disclosures.
- Reloadable Cards:Multi-use credentials require stored-value facility licensing under Reserve Bank of Australia oversight.
Volume sits with Physical Cards; growth tilts toward Digital Cards.
Customer Type:
Application context separates one-off gifting occasions from recurring enterprise disbursement workflows.
- Corporate Clients:HR departments and procurement teams within banking and telecommunications sectors consolidate vendor relationships around integrated reward platforms with analytics dashboards. Bulk disbursement contracts favor API-native delivery that eliminates per-unit handling costs.
- Retail Consumers:Individual purchasers respond to seasonal promotional cycles and in-store display placement. Supermarket aisle dominance by major retailers channels impulse buying toward physical credentials with immediate gratification.
- Non-profits:Charitable organizations leverage donated card inventory for fundraising auctions and donor recognition programs.
- Event Organizers:Conference and exhibition managers distribute promotional stored-value for attendee engagement and sponsor activation.
Procurement scale favors Corporate Clients; transaction frequency concentrates with Retail Consumers.
Distribution Channel:
Geographic penetration patterns expose where digital wallet adoption has displaced physical retail presence.
- Online Retailers:App-native platforms and browser-based marketplaces aggregate digital inventory from multiple issuers. Prezzee's direct-to-wallet delivery model exemplifies how cloud provisioning eliminates intermediary handling entirely.
- Supermarkets:Woolworths Group and competing chains maintain dedicated gift card fixtures that capture browsing-driven purchases. Physical presence in high-traffic retail environments sustains impulse buying despite digital alternatives.
- Convenience Stores:Extended operating hours and dense urban location networks serve last-minute gifting needs.
- Specialty Stores:Category-specific retailers distribute branded credentials tied to narrow merchandise assortments.
Transaction density clusters in Supermarkets; margin expansion favors Online Retailers.
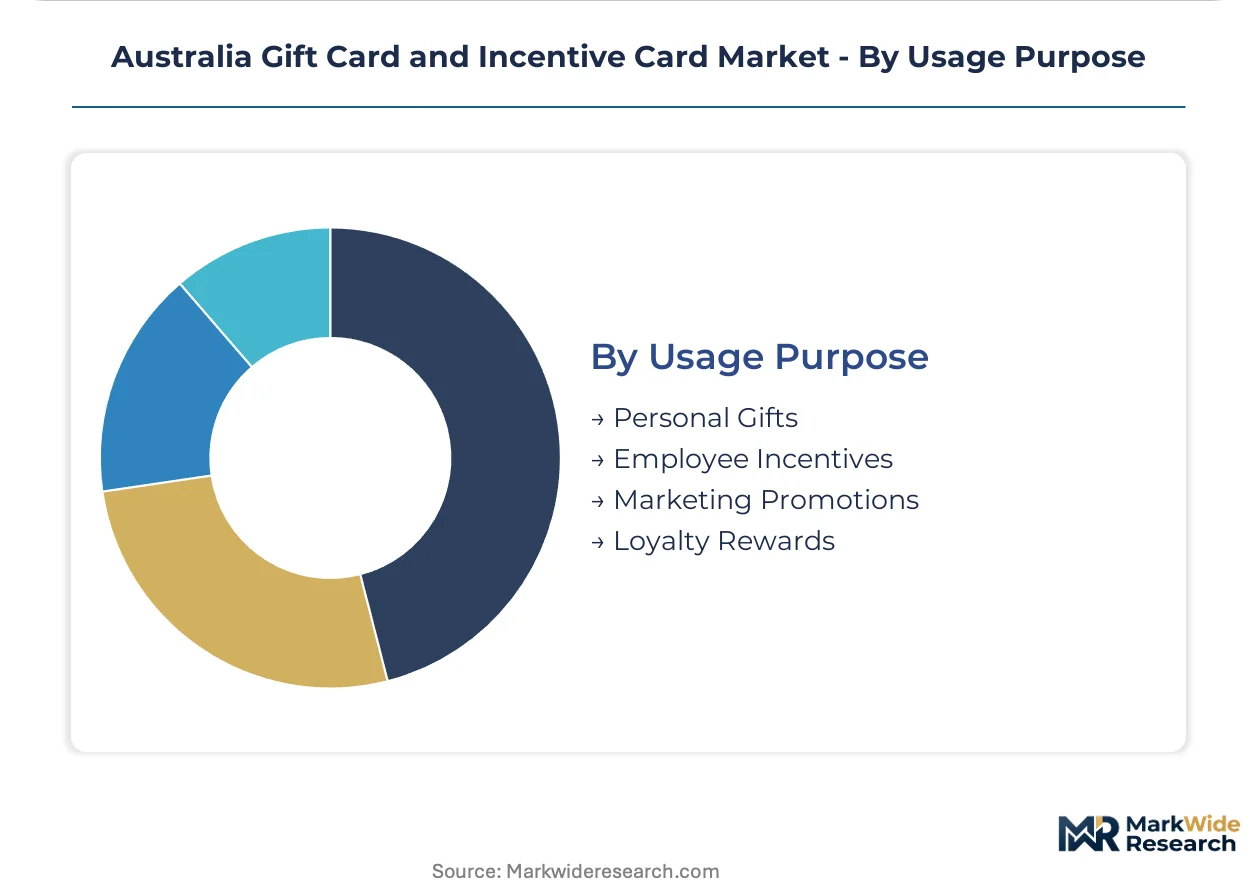
Usage Purpose:
Program design complexity varies from simple value transfer to integrated incentive management systems.
- Employee Incentives:Enterprise recognition programs demand bulk issuance, recipient tracking, and redemption analytics. Procurement centralization in Sydney and Melbourne financial services sectors favors platform providers offering consolidated reporting dashboards.
- Marketing Promotions:Customer acquisition campaigns require flexible denomination structures and co-branding capabilities. TCN – The Card Network's white-label services address mid-tier retail brands lacking captive program infrastructure.
- Personal Gifts:Occasion-driven purchasing concentrates around calendar events with predictable seasonal peaks.
- Loyalty Rewards:Program-integrated credentials link redemption to repeat purchase behavior and data collection objectives.
Contract value concentrates in Employee Incentives; redemption velocity peaks in Marketing Promotions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Card production concentrates in southeastern manufacturing corridors while consumption spreads across metropolitan and regional catchments. The Reserve Bank of Australia's payments system oversight creates uniform regulatory conditions nationally, though adoption velocity diverges sharply between capital cities and peripheral states.
New South Wales
Sydney's financial services sector drives corporate prepaid card procurement for employee reward programs. The Australian Securities and Investments Commission mandates stored-value facility licensing that filters issuer participation. Fintech clusters in Barangaroo and North Sydney concentrate API-native platform development for digital wallet integration.
Victoria
Melbourne's retail headquarters and banking institutions anchor bulk incentive card contracting. The Australian Competition and Consumer Commission's gift card expiry reforms force product redesign across reloadable and single-load instruments. Docklands and Southbank technology precincts host white-label platform providers serving mid-tier retail brands.
Queensland
Brisbane's corporate sector and Gold Coast tourism operators generate seasonal promotional card demand. The state's consumer protection framework mirrors federal standards while allowing regional enforcement variation. Underpenetrated digital wallet adoption outside SEQ creates geographic expansion white space for cloud-provisioning entrants.
Western Australia
Perth's mining sector procurement teams consolidate vendor relationships around compliant stored-value disbursements. Distance from eastern manufacturing centers elevates physical distribution costs for PVC-based products. Local fintech development remains nascent compared to Sydney-Melbourne corridors.
South Australia
Adelaide's mid-sized corporate base generates steady but lower-volume incentive program demand. The state's retail concentration lacks the scale of Woolworths Group and Wesfarmers Ltd. networks dominating eastern markets. Digital delivery platforms bypass traditional supermarket aisle dependence here more completely than elsewhere.
Australia Gift Card and Incentive Card Market Competitive Environment
The competitive structure tilts toward retail conglomerates with captive distribution networks. Supermarket and department store operators leverage in-store fixture dominance to channel impulse purchases, while technology-native platforms compete on API-based delivery economics. Two strategic archetypes predominate: integrated retail-distributors with physical aisle control, and cloud-native specialists with zero logistics overhead. Consolidation pressure runs through white-label service acquisitions and digital wallet partnership formation.
Among retail-integrated operators, Woolworths Group Ltd. and Wesfarmers Ltd. exemplify the physical distribution archetype through supermarket and convenience store network control. Prezzee occupies a position on the digital-native vector with app-to-wallet delivery that eliminates PVC manufacturing and postal fulfillment entirely. TCN – The Card Network sits within the white-label tier, providing outsourced program infrastructure for mid-tier brands lacking captive technology investment.
| Leading Market Players |
|---|
| Woolworths Group Ltd. |
| JB Hi-Fi Ltd. |
| Blackhawk Network |
| TCN – The Card Network |
| Edge Loyalty (Village Roadshow) |
| Prezzee |
| Wesfarmers Ltd. |
| Apple Inc. |
| InComm Payments |
| Others |
Value Chain & Pricing Dynamics
API-based cloud provisioning is displacing PVC card manufacturing and postal fulfillment simultaneously, compressing per-unit delivery costs for digital-native platforms while concentrating margin capture among technology-integrated issuers. The Australian Competition and Consumer Commission's three-year minimum expiry mandate is forcing product redesign economics that favor scaled operators capable of absorbing compliance overhead.
Pricing Analysis
Margin tightening in reloadable products reflects ASIC stored-value facility licensing costs and extended liability periods. Three-tier pricing structure across premium branded, standard retail, and economy private-label tiers segments buyer sophistication. Price differentiation rests on digital wallet integration depth and analytics dashboard sophistication. Corporate procurement teams demonstrate lowest price sensitivity due to bundled platform requirements, while retail consumers respond sharply to promotional discounting.
Supply Chain Analysis
Domestic-content mandates under Australian Securities and Investments Commission disclosure requirements are reshaping issuer sourcing toward locally compliant program management. PVC substrate production draws from China and Southeast Asian manufacturing hubs, while API development centers on Sydney and Melbourne technology precincts. Single-source vulnerability concentrates in EMV chip supply from Taiwan and South Korea. Distribution runs through supermarket captive networks and direct-to-wallet cloud provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australian gift card market operates as a cost-of-compliance story where ASIC's stored-value facility licensing creates a regulatory moat favoring incumbent platforms with established legal infrastructure and compliance teams.
For Market Incumbents: Anchor market position through vertical integration into white-label platform services for mid-tier retail brands lacking captive technology investment. Defend against API-native entrants by deepening Woolworths Group's supermarket aisle control and expanding analytics dashboard capabilities for corporate HR procurement teams. Prioritize certification investment in open banking data standards to maintain interoperability advantages. For New Entrants and Emerging Players: Launch via direct-to-wallet digital delivery targeting underpenetrated regional Queensland and Western Australia corridors outside Sydney-Melbourne saturation. Exploit geographic white space in Perth mining sector procurement and Brisbane-Gold Coast tourism promotional programs. Pursue partnership-based go-to-market positioning with regional bank loyalty program integration. For Investors and Strategic Acquirers: Exit pathways concentrate in white-label platform acquisition by retail conglomerates seeking outsourced card program infrastructure. Long-term viability favors scaled operators with ASIC licensing, corporate procurement relationships, and API-native delivery architecture. Watch open banking interoperability adoption velocity as the critical inflection signal for platform valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| White-Label Platform Acquisition | Mid-tier retail brands outsource card program management without captive technology investment. |
| Open Banking Integration | Real-time account-to-account funding enables loyalty program data sharing under Consumer Data Right standards. |
| Regional Geographic Expansion | Queensland and Western Australia corridors offer underpenetrated digital wallet adoption outside Sydney-Melbourne. |
| Corporate Procurement Consolidation | Banking and telecommunications HR departments standardize vendor relationships around compliant stored-value disbursements. |
| API-Native Delivery Infrastructure | Cloud provisioning eliminates PVC manufacturing and postal fulfillment costs from program economics. |
Study Parameters
Document review covered Reserve Bank of Australia payments system bulletins, ASIC regulatory guidance, and Australian Competition and Consumer Commission enforcement records, complemented by interviews with prepaid card program managers, corporate procurement officers, fintech platform engineers, and retail distribution channel heads. Secondary validation drew from ABS retail trade data, APRA financial institution statistics, and industry association membership disclosures. Bottom-up transaction volume estimates and top-down market sizing triangulated across primary and secondary sources.
Market value and volume outputs trace to segmented modeling across product type, customer archetype, distribution channel, and usage purpose dimensions throughout the forecast period. CAGRs derive from historical trajectory analysis adjusted for regulatory intervention impacts and technology adoption S-curves. Forecast inputs incorporate mobile wallet penetration curves, corporate HR platform consolidation rates, and open banking API deployment timelines.
Regulatory enforcement intensity, digital wallet adoption velocity, and interchange fee policy shifts are the dominant revision risks to modeled projections. Forecasts reflect documented assumptions regarding compliance cost absorption and technology migration patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
ATM Software Market
Financial Services
Global Product Cost Management Market
Financial Services
Banknote Counters Market
Financial Services
E-Invoicing Market
Financial Services
Healthcare Finance Solutions Market
Financial Services
South Korea Financial Services Software Market
Financial Services
E-Brokerage Market
Financial Services
Latin America Factoring Services Market
Financial Services
Digital Transformation in BFSI Market
Financial Services
BFSI Contact Center Analytics Market
Financial Services
Global Medical Equipment Financing Market
Financial Services
Global Financial Consulting Software Market
Financial Services
Hyperinflation System Market
Financial Services
Europe E-Brokerages Market
Financial Services
North America B2B Legal Services Market
Financial Services
South Korea Factoring Services Market