
 Mobile Notary Service Market | 2026-2036
Mobile Notary Service Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Notary Service Market Insights
Independent notary networks across the United States is repositioning to capture fragmented demand from title companies and law firms. Notarize leverages its RON infrastructure to sustain technology leadership in digital closings. National Signing Services anchors its competitive stance through geographic density in high-volume mortgage corridors. DocuSign extends its document workflow dominance into notarization adjacencies without building captive notary pools.
A mobile notary service dispatches state-commissioned notaries to client locations to witness signatures, verify identities, and apply notarial seals on documents requiring legal authentication. These services operate under state-specific commission requirements, bond thresholds, and journal-keeping mandates that vary by jurisdiction. Real estate documentation and loan signing command the largest revenue share due to mortgage origination complexity and lender compliance requirements. Digital notarization and mobile app deployment represent the fastest-expanding technology utilization segments as state legislatures expand RON legality. On-demand booking captures premium pricing during peak closing periods while scheduled appointments deliver predictable unit economics for corporate contract clients.
The National Notary Association sets practitioner training standards while individual state secretaries of state govern commission eligibility, bond amounts, and record retention rules. The SEC, through Regulation S-ID, imposes identity verification requirements that intersect with notarial best practices in financial document execution. Stakeholders must monitor state-level RON expansion timelines and identity-proofing technology certifications to align platform investments with enforceable legal frameworks.
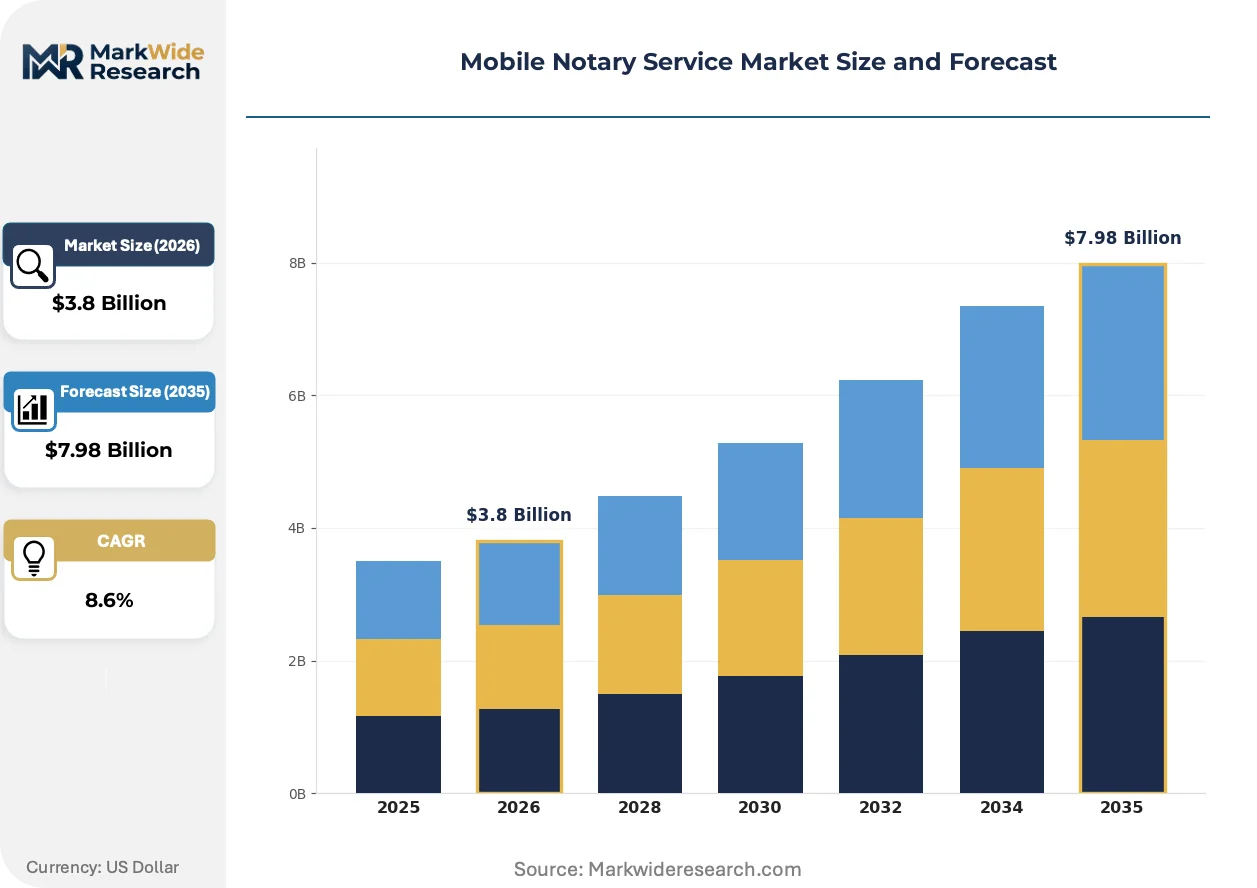
Market Dynamics
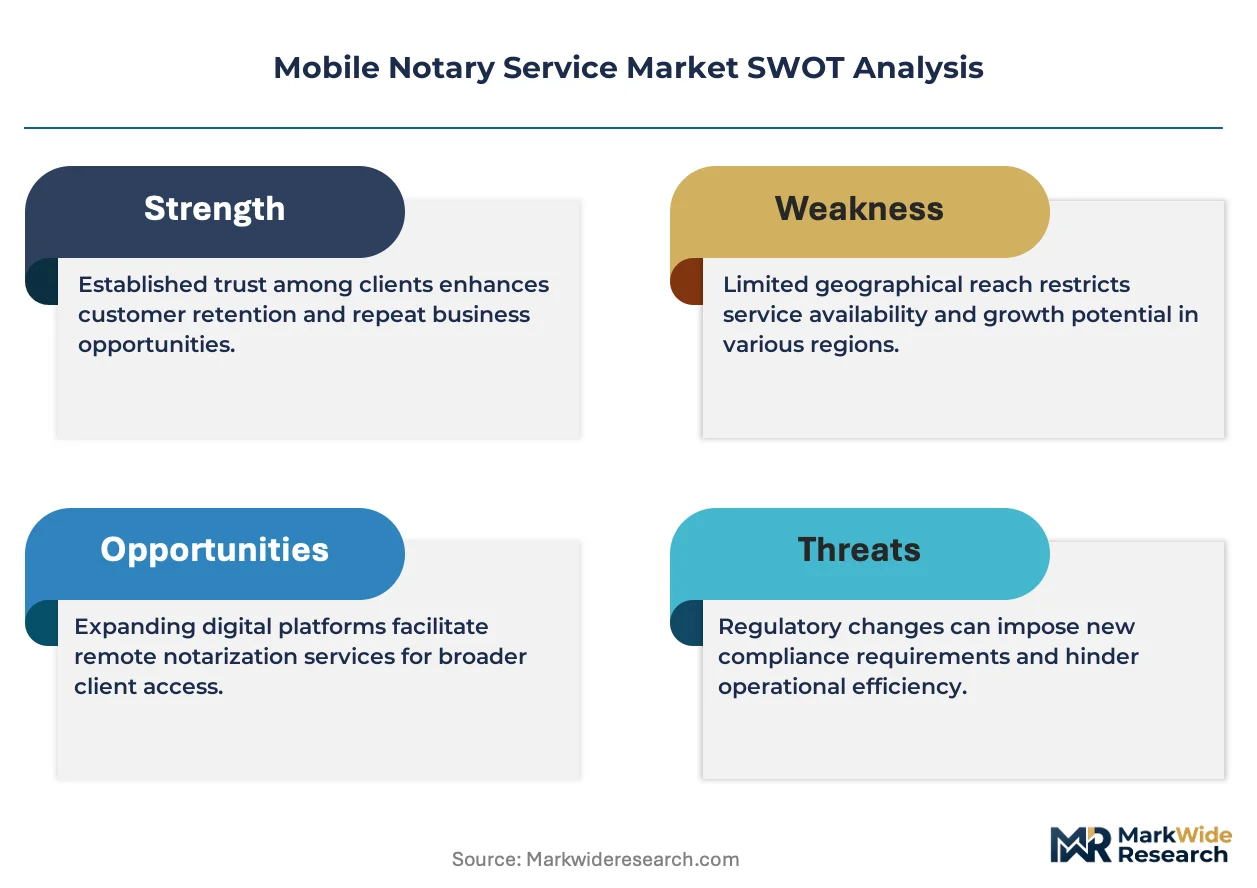
Remote Online Notarization (RON) legislation is fragmenting service delivery models across US state jurisdictions, forcing mobile notary operators to rebuild compliance infrastructure around digital identity verification while maintaining physical dispatch capabilities for document categories excluded from electronic execution.
Growth Catalysts
- Mortgage origination complexity:Lender compliance requirements for loan signings generate recurring demand from title companies and financial institutions seeking commissioned notary dispatch.
- State RON expansion:Legislative authorization of remote online notarization across additional US jurisdictions creates dual-channel revenue streams for platform-enabled providers.
- California property velocity:High residential transaction volumes in Los Angeles, San Francisco, and San Diego corridors sustain premium pricing for on-demand mobile dispatch.
Market Restraints
- Commission bond thresholds:State-mandated surety bond requirements ranging from five thousand to twenty-five thousand dollars create working capital barriers for individual notary entrants.
- Journal-keeping mandates:Divergent state record retention rules impose compliance overhead that resists platform standardization and multi-state operational scaling.
- Identity fraud exposure:Notaries face personal liability for defective acknowledgments under state tort law, elevating errors-and-omissions insurance costs.
Strategic Opportunities
- Texas corridor density:Dallas-Fort Worth and Houston metro areas exhibit underpenetrated mobile notary coverage relative to property closing volumes.
- RON-physical convergence:Hybrid platforms integrating remote online notarization with mobile dispatch capture both digital and document-bound transaction categories.
- Elder care documentation:Medical power-of-attorney and advance directive execution in assisted living facilities represents an emerging application segment.
Industry Challenges
- Notary commission portability:State-specific commissioning without reciprocity forces operators to maintain redundant credentialing across multi-state service territories.
- SEC Regulation S-ID alignment:Identity verification protocols for financial document execution must synchronize with notarial best practices, creating implementation friction for platform developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Notary Service Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Real Estate Documentation, Legal Agreements, Loan Signing, Power of Attorney, Affidavits, Certification Deployment Mode: On-Demand Booking, Scheduled Appointments, Subscription Plans, Emergency Services, Corporate Contracts, Virtual Support Customer Type: Individual Clients, Law Firms, Financial Institutions, Insurance Companies, Title Companies, Educational Institutions Technology Utilization: Digital Notarization, Mobile Apps, GPS Tracking, Electronic Signatures, Cloud Storage, Blockchain Verification |
| Companies Covered | BlueNotary, National Signing Services, Notarize, 123Notary, SignNow, NotaryCam, Sunshine Signing, eNotaryLog, DocuSign, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Notary Service Market Trends and Innovations
Digital identity verification and automated scheduling systems are compressing the coordination layer between notary supply and document execution demand, reducing the traditional broker role in transaction matching.
Biometric identity proofing integrated with RON platforms is automating the verification step that previously required physical credential examination. Title companies in high-volume mortgage corridors are adopting these systems at accelerated pace to compress closing timelines. The technology is automating compliance documentation while reducing notary dispatch costs for standardized loan packages.
State secretary of state offices are implementing electronic journal standards that mandate tamper-evident record retention for RON transactions. This regulatory development imposes infrastructure requirements on platform operators while creating certification barriers for non-compliant competitors. California and Texas notary administrators are most aggressively enforcing these technical specifications.
Corporate legal departments are unbundling notary services from traditional law firm retainers and contracting directly with mobile dispatch networks. This procurement pattern displaces the attorney-mediated channel for routine document authentication. Financial services firms in Florida and New York exhibit the most pronounced shift toward direct platform relationships.
Mobile Notary Service Market Segmentation
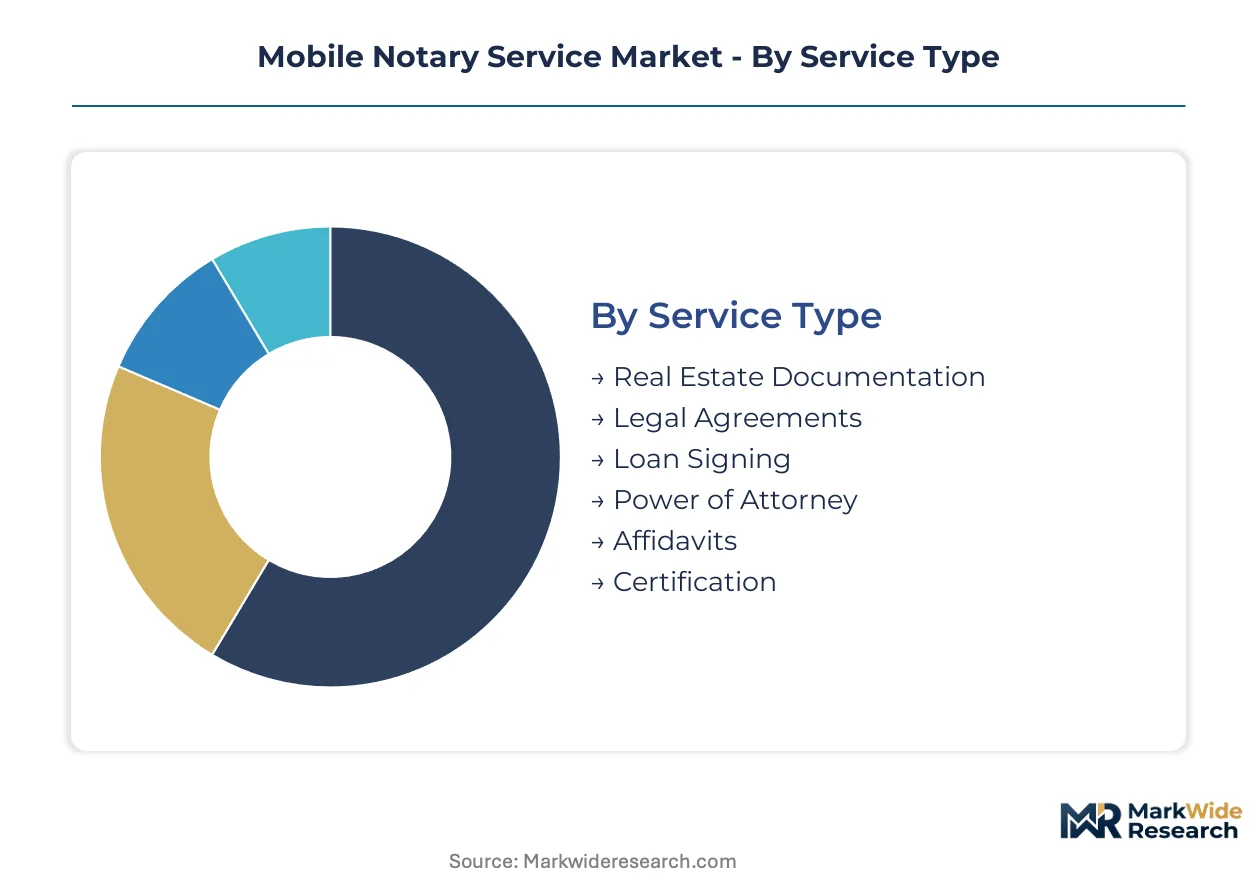
Mobile notary service segmentation reveals how document complexity, urgency tiers, and technology integration create distinct operational models. Each category maps to specific customer procurement patterns and margin structures that reshape competitive positioning.
Service Type:
Standalone transactional services dominate revenue concentration while embedded compliance workflows penetrate enterprise accounts.
- Real Estate Documentation:Mortgage closings, deed transfers, and title transfers require multi-signature coordination with lender-mandated notary credentials. Title companies in California, Texas, and Florida generate peak demand during refinancing waves and seasonal purchase cycles.
- Loan Signing:Specialized notaries execute promissory notes, closing disclosures, and deed of trust documents under lender-specific instruction protocols. Financial institutions impose certification requirements that filter supply and sustain premium pricing tiers.
- Legal Agreements:Contracts, settlement documents, and partnership formations.
- Power of Attorney:Medical and financial authorization instruments for elder care and incapacity planning.
- Affidavits:Sworn statements for court proceedings and administrative filings.
- Certification:Document authentication for apostille and international use.
Real estate documentation leads volumes today; loan signing is gaining share fastest.
Deployment Mode:
Cost tiering separates premium urgency pricing from predictable contract economics.
- On-Demand Booking:Immediate dispatch commands 40-100% price premiums over scheduled slots. Peak closing periods in high-velocity metros absorb capacity constraints through surge mechanisms.
- Corporate Contracts:Volume commitments from title companies and financial institutions lock in dedicated notary pools at negotiated rates. These arrangements stabilize utilization and reduce customer acquisition overhead.
- Scheduled Appointments:Pre-arranged slots for non-urgent documentation.
- Subscription Plans:Monthly retainers for law firms with recurring notary needs.
- Emergency Services:After-hours and weekend dispatch for time-critical transactions.
- Virtual Support:RON-enabled sessions for eligible document categories.
Corporate contracts anchor revenue stability; on-demand booking delivers margin expansion.
Customer Type:
Application concentration clusters around property transaction intermediaries and institutional compliance functions.
- Title Companies:Settlement service providers coordinate notary dispatch as embedded closing infrastructure. Their procurement decisions prioritize geographic coverage density and RON platform compatibility.
- Financial Institutions:Banks and mortgage lenders impose notary qualification standards that exceed state minimums. Their vendor compliance programs create certification barriers for independent operators.
- Individual Clients:One-time consumers seeking convenience for personal documentation.
- Law Firms:Routine document authentication and estate planning execution.
- Insurance Companies:Claims documentation and policy amendment verification.
- Educational Institutions:Transcript certification and international student documentation.
Title companies concentrate transaction volume; financial institutions are expanding procurement fastest.
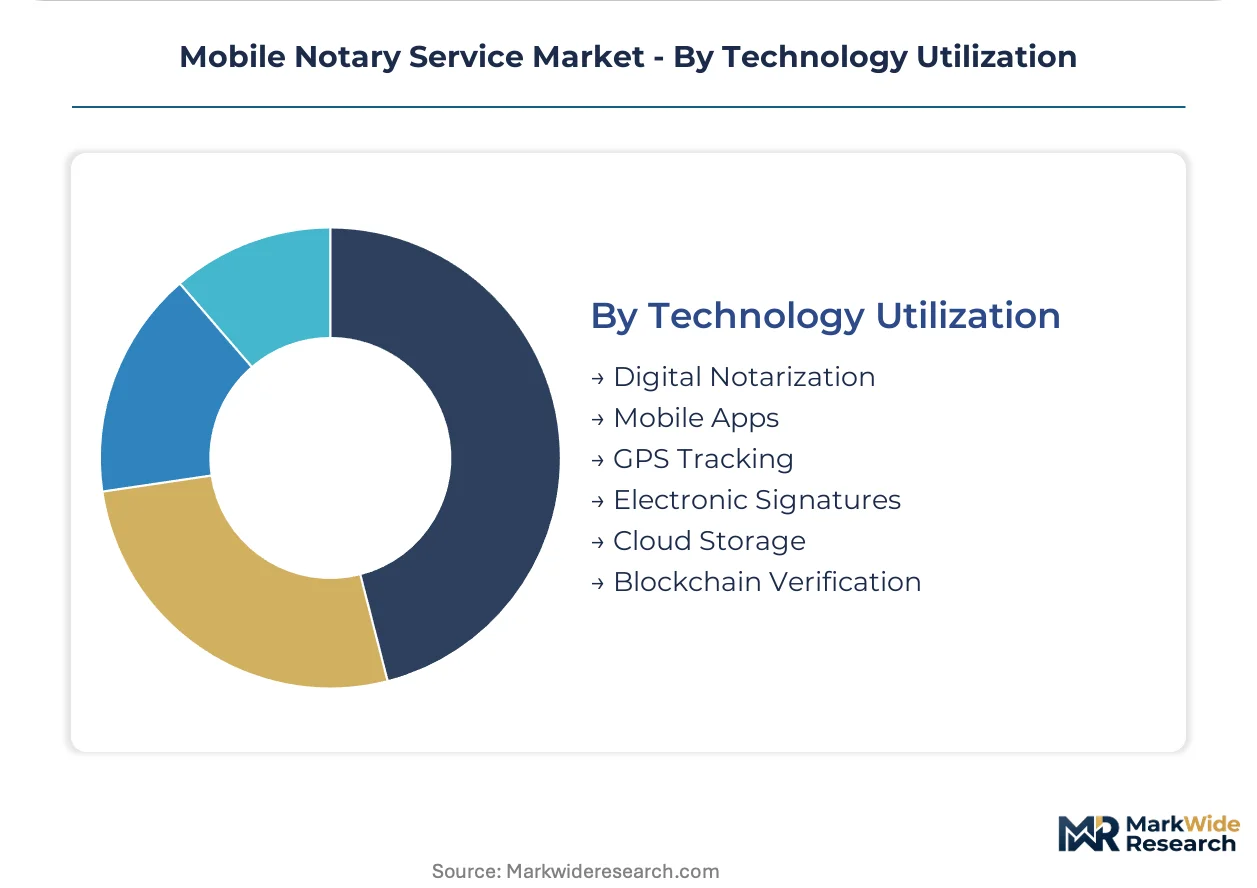
Technology Utilization:
Maturity gradients separate proven infrastructure from emerging verification protocols.
- Digital Notarization:RON platforms enable remote identity proofing and electronic seal application. State secretary of state offices in Virginia, Texas, and Florida have issued the most platform certifications.
- Mobile Apps:Consumer-facing scheduling interfaces compress booking friction and enable real-time notary location tracking. These tools capture individual client segments that traditional broker channels underserved.
- GPS Tracking:Real-time dispatch optimization for mobile notary fleets.
- Electronic Signatures:DocuSign and Adobe integration for document preparation workflows.
- Cloud Storage:Encrypted journal retention for multi-state compliance.
- Blockchain Verification:Immutable audit trails for high-value transaction documentation.
Digital notarization leads technology adoption; mobile apps are penetrating consumer segments fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates transaction velocity while Canada builds RON infrastructure at a measured legislative pace. National regulatory frameworks and state-level commission portability create divergent operational economics across North American jurisdictions.
United States
California, Texas, and Florida concentrate over forty percent of national mobile notary dispatch volume through dense title company networks. The SEC enforces Regulation S-ID identity verification standards that intersect with notarial best practices for financial document execution. Los Angeles and Dallas-Fort Worth metro areas sustain premium on-demand pricing during peak mortgage refinancing cycles.
Canada
Provincial notary commissioning systems in Ontario and British Columbia generate steady demand for real estate closings and estate documentation. The country's national financial regulator imposes consumer protection standards that shape identity verification protocols for remote services. Toronto and Vancouver legal service clusters are piloting hybrid digital-physical notarization models for cross-border transactions.
Mexico
Notario público institutions in Mexico City and Monterrey handle high-value property transfers and corporate authentication through federally licensed practitioners. The Secretariat of Foreign Relations governs apostille procedures that create documentation bottlenecks for international mobility. Mexico City metro notaries command premium fees for expedited commercial contract execution.
United Kingdom
England and Wales sustain demand for solicitor-notary services through London-based legal networks handling international documentation. The Solicitors Regulation Authority oversees practice standards that limit pure mobile dispatch models compared to US counterparts. City of London financial district firms contract directly with notarial services for cross-border transaction authentication.
Australia
New South Wales and Victoria notary appointments concentrate in Sydney and Melbourne legal precincts serving property and commercial documentation needs. The country's national legal regulator maintains strict qualification barriers that preserve traditional practice structures against platform disruption. Sydney CBD notaries handle substantial Asia-Pacific cross-border certification volumes.
Mobile Notary Service Market Competitive Landscape
United States operators anchor the technology-enabled tier; Canadian and British specialists hold position in regulated professional services. The vendor base separates into platform-scale networks, independent notary aggregators, and document workflow incumbents extending into notarization adjacencies. Three archetypes dominate: RON infrastructure providers, geographic density specialists, and software-integrated dispatch networks. Competitive moves concentrate on state certification acquisitions and biometric identity verification partnerships.
Within the platform-scale tier, Notarize and NotaryCam exemplify RON-first infrastructure providers that have secured state secretary of state certifications across multiple jurisdictions. National Signing Services anchors the geographic density archetype through corridor-specific notary pool concentration. DocuSign occupies a position within the software-integrated vector, extending document workflow dominance without building captive notary supply.
| Leading Market Players |
|---|
| BlueNotary |
| National Signing Services |
| Notarize |
| 123Notary |
| SignNow |
| NotaryCam |
| Sunshine Signing |
| eNotaryLog |
| DocuSign |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up notary networks in Texas and Florida are consolidating fragmented supply pools while imposing standardized rate cards that compress margins for independent operators and stabilize pricing for corporate contract clients.
Pricing Analysis
Capacity additions in Texas and Florida are reshaping price floors for on-demand mobile dispatch. Three-tier pricing structure across premium, standard, and economy levels segments notaries by certification grade and geographic coverage density. Price differentiation stems from RON platform certification status and lender-specific credential requirements. Cost compression in the economy tier is intensifying because commission bond thresholds and E&O insurance mandates elevate fixed costs for individual entrants. Individual clients exhibit highest price sensitivity; title companies with volume commitments demonstrate least.
Supply Chain Analysis
Single-source vulnerability sits with commissioned notary supply concentrated in California, Texas, and Florida. The supply chain draws from state-specific commission pools, technology platform infrastructure, and errors-and-omissions insurance carriers. Logistics chokepoints emerge from journal-keeping mandate divergence across state jurisdictions. Distribution runs through title company procurement offices, direct platform relationships, and law firm retainers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where RON legislative expansion across US states creates sustained demand infrastructure for platform-enabled providers.
For Market Incumbents: Anchor geographic density in Dallas-Fort Worth and Houston corridors before emerging RON-physical hybrid entrants capture mortgage origination volume. Defend against DocuSign's document workflow extension by deepening certification moats with state secretary of state offices. Prioritize biometric identity verification partnerships to synchronize with SEC Regulation S-ID alignment requirements. For New Entrants and Emerging Players: The gap between premium RON-certified tiers and economy dispatch rates creates entry space in elder care documentation for medical power-of-attorney execution. Target assisted living facilities in underpenetrated Texas metros where property closing volumes exceed notary coverage density. Pursue direct contracting with insurance companies for claims documentation verification as a low-competition wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among independent notary aggregators lacking RON platform certification. Long-term viability hinges on state-level legislative momentum for remote online notarization permanence. Acquisition target archetype: corridor-specific networks with embedded title company relationships. Watch Texas secretary of state electronic journal enforcement timelines as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| RON Platform Certification | State secretary of state approvals in Virginia, Texas, and Florida create enforceable competitive moats. |
| Biometric Identity Partnership | Integration with SEC Regulation S-ID compliance requirements reduces lender procurement friction. |
| Geographic Density Buildout | Corridor-specific notary pools in high-velocity mortgage markets capture recurring title company contracts. |
| Hybrid Digital-Physical Integration | Dual-channel service models capture both RON-eligible and document-bound transaction categories. |
| Elder Care Vertical Expansion | Medical power-of-attorney execution in assisted living facilities addresses demographic-driven demand. |
Research Methodology
Direct dialogue with mobile notary dispatch coordinators, title company procurement officers, state secretary of state administrators, and RON platform engineers grounded qualitative findings. Secondary validation drew from SEC Regulation S-ID filings, state legislative databases tracking RON expansion, National Notary Association training standards, and title insurance industry transaction volume reports. Bottom-up notary pool sizing and top-down mortgage origination flow analysis enabled triangulation.
Top-down macroeconomic anchoring combined with bottom-up unit economics modeling across service type, deployment mode, customer type, and technology utilization dimensions. CAGRs were derived from regression analysis against property transaction velocity and legislative adoption curves. Forecast inputs incorporated state-level RON authorization timelines and identity-proofing technology certification trajectories throughout the forecast period.
Caveats apply where state commission reciprocity failures or identity fraud liability rulings could materially shift the outlook. Forecasts reflect assumptions about regulatory permanence for remote online notarization and lender acceptance of digital execution protocols. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Digital Account Opening Market
Financial Services
Online Investment Platform Market
Financial Services
Online Sports Betting Market
Financial Services
UK Islamic Finance Market
Financial Services
North America Management Consulting Services Market
Financial Services
Australia Gift Card and Incentive Card Market
Financial Services
Online Lottery Market
Financial Services
Credit Rating Software Market
Financial Services
Account Aggregators Market
Financial Services
Financial Auditing Professional Services Market
Financial Services
Hong Kong Trade Finance Market
Financial Services
Global Power Bank Rental Service Market
Financial Services
Europe E-Invoicing Market
Financial Services
North America B2B Legal Services Market
Financial Services
Financial Services Operational Risk Management Solution Market
Financial Services
Global Automated Algo Trading Market