
 Trade Finance Market | 2026-2036
Trade Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Trade Finance Market Intelligence
Multi-sourced trade credit origination is restructuring how banks deploy balance-sheet capacity across correspondent networks. HSBC Holdings plc leverages its Asia-Pacific correspondent footprint to anchor documentary trade flows between Greater China and the Middle East. Citigroup Inc. competes through its institutional cash-management infrastructure, while Standard Chartered PLC specializes in frontier-market corridors where local-currency settlement complexity creates pricing power.
Trade finance encompasses the provision of credit, payment guarantees, and risk mitigation instruments—principally letters of credit, documentary collections, and receivables financing—that bridge the payment gap between export shipment and import receipt, typically governed by ICC Uniform Customs and Practice for Documentary Credits rules. Its primary commercial purpose is to substitute bank creditworthiness for counterparty risk in cross-border transactions where legal recourse spans multiple jurisdictions. Letter of credit services retain the largest revenue pool among service types, though transaction financing is expanding fastest as fintech platforms embed working-capital solutions directly into enterprise resource planning systems. SME client segments are gaining share as automated know-your-customer tooling reduces onboarding costs that previously excluded smaller traders.
Basel III endgame rules from the Basel Committee on Banking Supervision are elevating risk-weighted asset charges for trade exposures, nudging banks toward distribution and syndication models. The ICC Banking Commission's ongoing digital trade standardization work, alongside national implementations of the UNCITRAL Model Law on Electronic Transferable Records, is reshaping document verification workflows and compliance architecture. Stakeholders must monitor which regulatory jurisdictions adopt enforceable electronic bill-of-lading frameworks first, as this will determine where platform-based trade finance infrastructure achieves operational scale ahead of lagging markets.
Market Dynamics
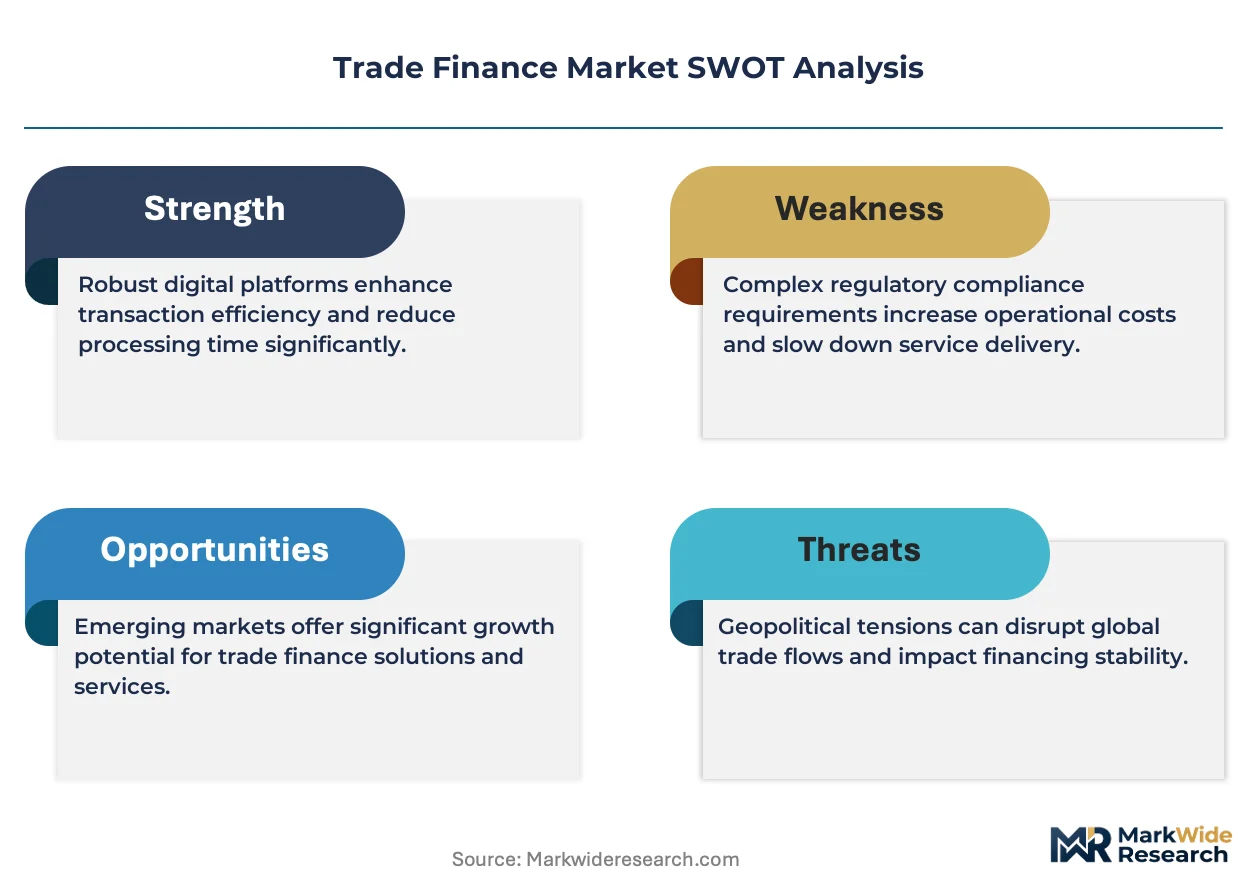
Basel III capital adequacy rules are compressing balance-sheet capacity at major trade finance banks, forcing a structural pivot toward distribution models and non-bank liquidity pools that reshape competitive positioning across correspondent networks.
Growth Catalysts
- India's Trade Receivables Discounting System:RBI's TReDS platform draws non-bank participants into documentary trade by digitizing invoice discounting for SME exporters. Transaction volumes through the platform accelerate working-capital access beyond traditional banking channels.
- Supply chain digitization:Enterprise resource planning integration with fintech platforms embeds trade finance instruments directly into procurement workflows. This convergence reduces onboarding friction for SME segments previously excluded by high KYC costs.
- Letters of credit:Documentary credit instruments retain the largest revenue pool among service types as cross-border transactions substitute bank creditworthiness for counterparty risk in multi-jurisdictional deals.
Market Restraints
- Risk-weighted asset charges:Basel III endgame rules from the Basel Committee on Banking Supervision elevate capital requirements for trade exposures. Major lenders face compressed returns on documentary trade assets.
- Balance-sheet concentration:Tier-1 banks in London, Singapore, and Hong Kong dominate correspondent liquidity. Smaller institutions struggle to compete for anchor mandates in high-volume corridors.
- Document verification costs:Paper-based bill-of-lading workflows persist in jurisdictions lagging UNCITRAL Model Law adoption. Compliance architecture for physical document checking consumes operational resources.
Strategic Opportunities
- Frontier-market corridors:Local-currency settlement complexity in Sub-Saharan Africa and Central Asia creates pricing power for specialists with on-ground banking licenses. These corridors remain underpenetrated by global trade finance platforms.
- Electronic transferable records:National implementations of the UNCITRAL Model Law enable enforceable digital bills of lading. First-mover jurisdictions will determine where platform-based infrastructure achieves operational scale.
- SME working-capital solutions:Automated KYC tooling reduces onboarding costs that previously excluded smaller traders. Fintech platforms embedding receivables financing into ERP systems capture this expanding segment.
Industry Challenges
- Legacy system integration:Banks maintaining mainframe-based trade operations face complexity connecting to distributed ledger platforms. API standardization across correspondent networks remains incomplete.
- Digital trade standardization:ICC Banking Commission's ongoing work on uniform rules for digital trade documents progresses slowly. Jurisdictional fragmentation in electronic signature recognition delays cross-border enforceability.
- Talent scarcity in trade operations:Documentary credit expertise concentrates among aging specialists. Succession planning for UCP 600 interpretation and discrepancy handling lags automation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trade Finance Market |
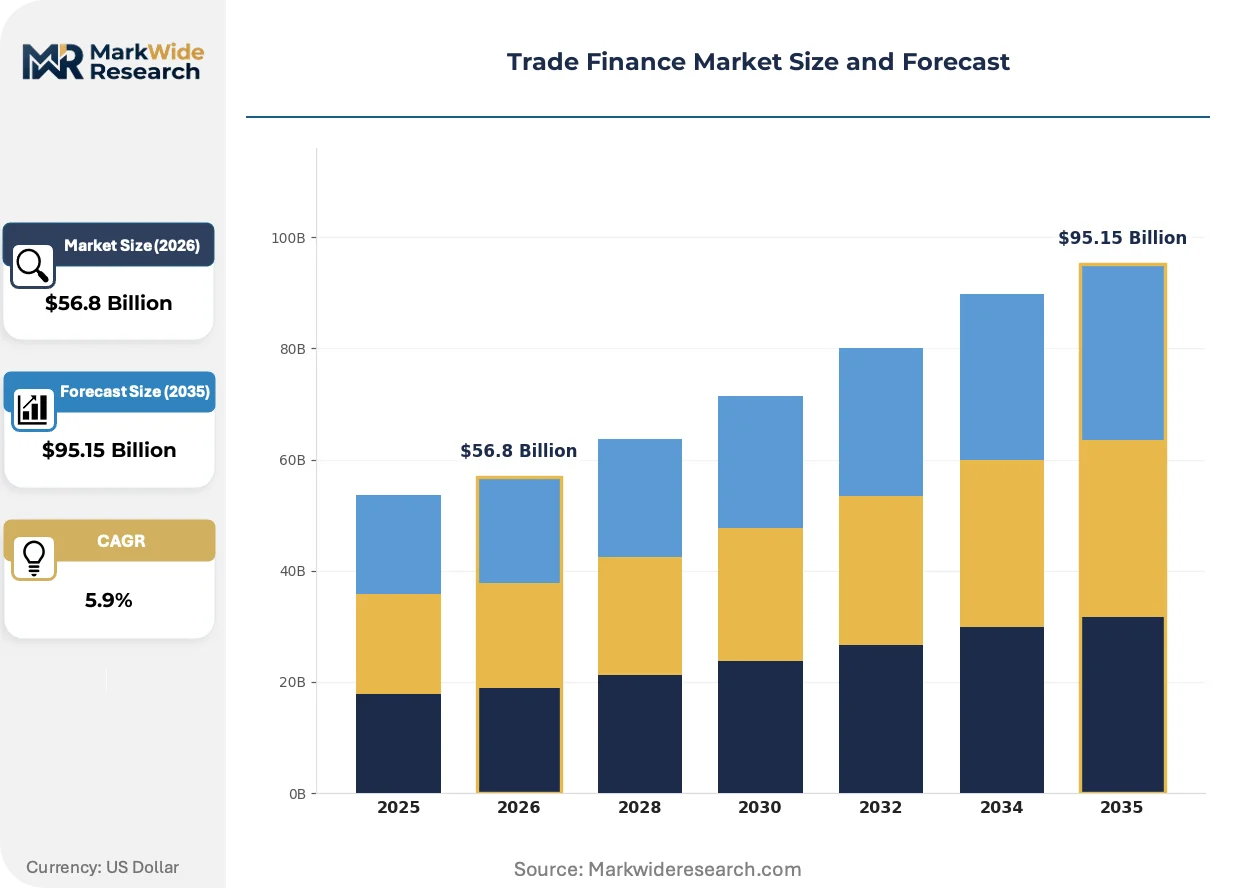
| Market Size in 2026 | $56.8 Billion |
| Market Size in 2035 | $95.15 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Letter of Credit, Export Financing, Import Financing, Transaction Financing Client Type: Corporates, Financial Institutions, SMEs, Startups Funding Source: Bank Financing, Private Equity, Trade Credit, Venture Capital Transaction Size: Small Scale, Medium Scale, Large Scale, Bulk Transactions |
| Companies Covered | HSBC Holdings plc, Citigroup Inc., BNP Paribas SA, Standard Chartered PLC, JPMorgan Chase & Co., Bank of America Corporation, DBS Bank Ltd., ING Groep, Santander Bank, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trade Finance Market Strategic Shifts & Innovations
Distributed ledger technology and artificial intelligence are converging to restructure document verification workflows, while regulatory adoption of electronic transferable records determines geographic winners in platform-based trade finance.
Blockchain-based trade finance platforms are automating letter-of-credit issuance and document matching through smart contracts that execute payment triggers upon verified shipment confirmation. Mid-market exporters in India and the United Arab Emirates adopt these tools fastest as their banks pilot API-connected distributed ledger networks. The technology is automating discrepancy checking that previously required manual review, compressing transaction settlement cycles from days to hours.
The European Union's Digital Operational Resilience Act and the UK's Electronic Trade Documents Act create enforceable frameworks for electronic bills of lading and promissory notes. These statutes remove legal barriers that previously forced banks to maintain parallel paper and digital workflows. Trade finance operations in London and Rotterdam respond by consolidating compliance architecture around platform-native document verification, reducing dual-system overhead.
Buyer concentration among large importers is compressing pricing power for documentary credit services as procurement teams centralize treasury functions and negotiate standardized terms across supplier bases. Regional trading houses in Southeast Asia displace traditional correspondent banking relationships with direct fintech platform connections. This pattern appears most visibly in Vietnam and Indonesia, where garment and electronics exporters bypass bank intermediaries for receivables financing embedded in logistics software.
Trade Finance Market Segmentation
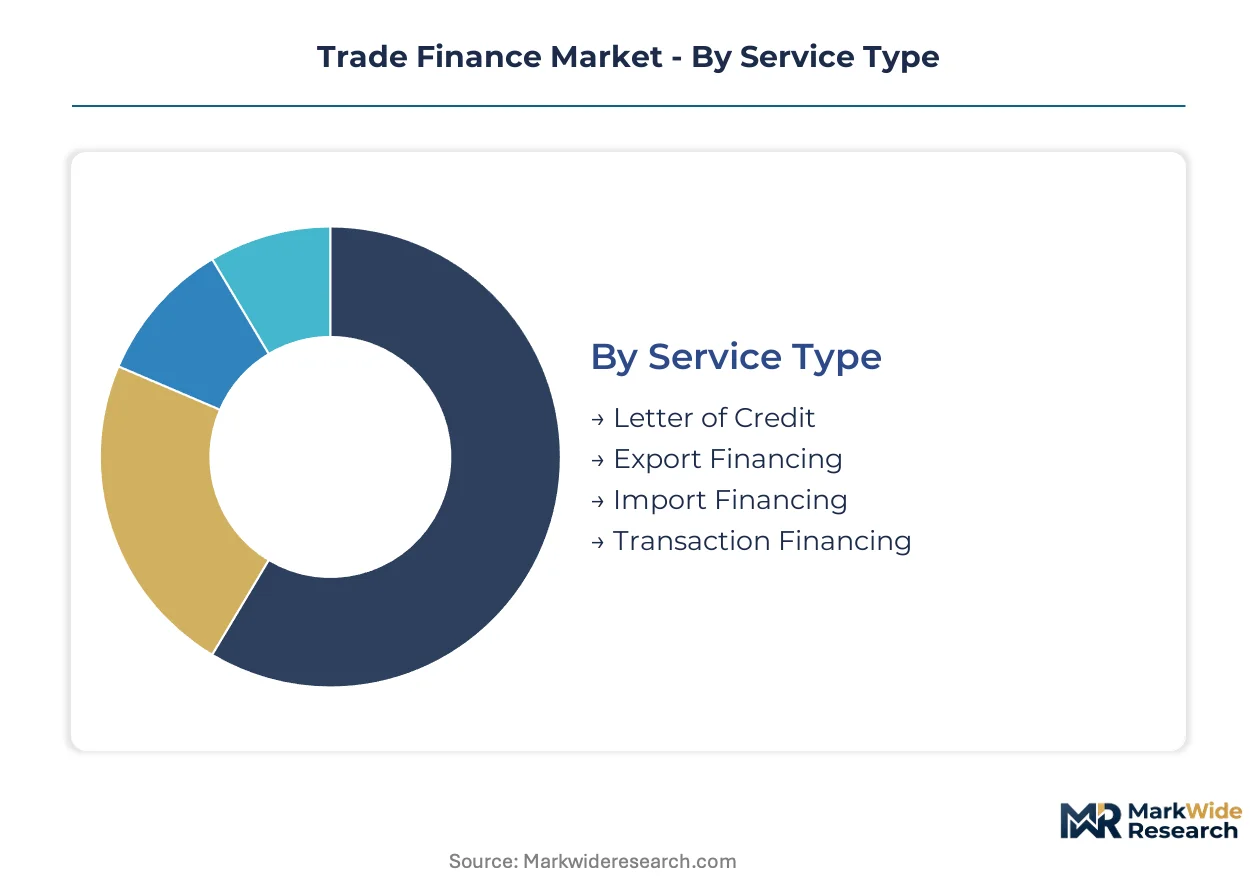
Trade finance instruments vary sharply in capital intensity, regulatory treatment, and counterparty risk profiles. Segmentation reveals which service lines absorb Basel III risk-weighting penalties and which client tiers drive platform-based automation.
Service Type:
Letters of credit carry ICC UCP 600 compliance burdens that documentary collections escape, while transaction financing faces lighter capital charges under standardized fintech origination.
- Letter of Credit:Documentary credit instruments substitute bank creditworthiness for buyer default risk through irrevocable payment undertakings governed by ICC rules. Demand concentrates in India and the United Arab Emirates as SME exporters require bank-backed assurance in multi-jurisdictional deals where legal recourse remains uncertain.
- Transaction Financing:Working-capital solutions embed directly into enterprise resource planning systems through API-connected fintech platforms. Growth concentrates among mid-market corporates in Vietnam and Indonesia as procurement teams centralize treasury functions and bypass traditional correspondent banking relationships.
- Export Financing:Pre-shipment credit and post-shipment receivables discounting backed by export credit agencies.
- Import Financing:Trust receipts and documentary collections financing inventory through the customs clearance cycle.
Leading the category by volume: Letter of Credit. Growing fastest: Transaction Financing.
Client Type:
Onboarding cost structures and know-your-customer automation thresholds determine which client tiers banks can serve profitably.
- SMEs:Automated KYC tooling and digital document verification compress acquisition costs that previously excluded smaller traders from bank channels. RBI's TReDS platform in India accelerates working-capital access for this segment beyond traditional banking infrastructure.
- Corporates:Large importers centralize procurement treasury functions and negotiate standardized terms across supplier bases. HSBC and Citigroup compete for anchor mandates through institutional cash-management infrastructure and Asia-Pacific correspondent footprints.
- Financial Institutions:Interbank confirmation lines and risk participation structures for correspondent banking networks.
- Startups:Early-stage ventures with limited trading history and thin collateral coverage.
SMEs represent the fastest-growing trajectory as platform automation erodes minimum viable deal size thresholds.
Funding Source:
Basel III risk-weighted asset charges push banks toward distribution models that tap non-bank liquidity pools.
- Bank Financing:Balance-sheet capacity at tier-1 lenders in London, Singapore, and Hong Kong faces compression from elevated capital requirements. Documentary trade returns compress as Basel Committee endgame rules elevate risk weights for trade exposures.
- Trade Credit:Supplier-financed open-account terms and inter-firm receivables programs. Growth concentrates in Southeast Asian garment and electronics supply chains as regional trading houses displace bank intermediaries with direct platform connections.
- Private Equity:Institutional capital deploying into trade finance funds and specialty lending platforms.
- Venture Capital:Early-stage funding for fintech platforms automating document verification and smart-contract settlement.
Bank Financing retains dominant share; Trade Credit climbs fastest as supply chain digitization accelerates.
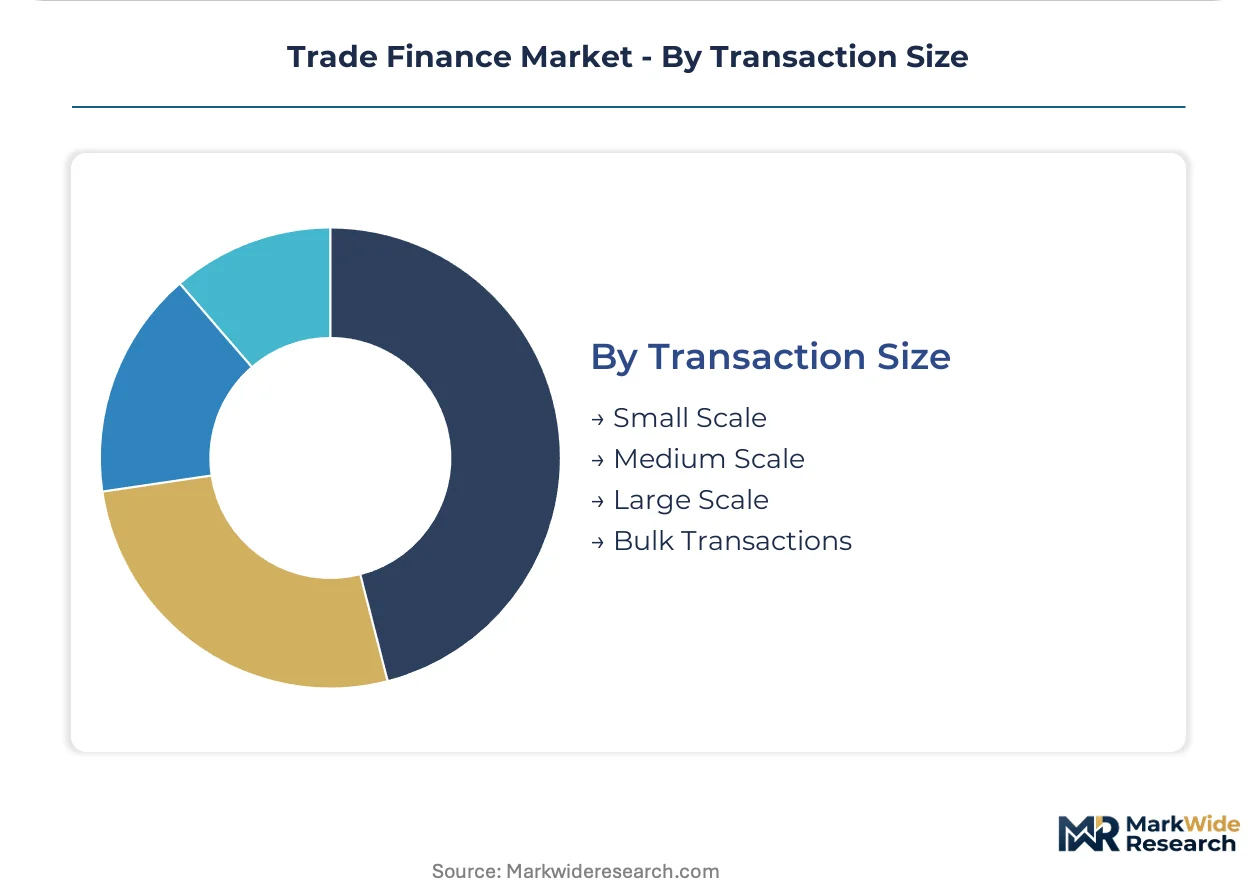
Transaction Size:
Deal scale determines eligibility for standardized platform origination versus bespoke structuring.
- Large Scale:Syndicated documentary credit facilities and multi-bank risk participation structures for commodity traders and industrial importers. Pricing power concentrates among tier-1 banks with correspondent network depth in Greater China-Middle East corridors.
- Small Scale:Invoice discounting and purchase-order financing for individual shipments. Fintech platforms in India and Indonesia capture this segment through ERP-embedded working-capital solutions that reduce onboarding friction.
- Medium Scale:Single-bank documentary credits and structured trade loans for established trading houses.
- Bulk Transactions:Programmatic financing across aggregated shipment portfolios.
Large Scale transactions dominate revenue; Small Scale deals expand most quickly through platform automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum reserves in the Middle East and iron ore deposits in Western Australia anchor the commodity-backed documentary credit flows that dominate regional trade finance deployment patterns.
United States
Energy exporters in Texas and Louisiana drive demand for pre-export financing instruments as crude and LNG shipments require bank-backed payment assurances. The SEC and OCC oversee capital adequacy for trade exposures at major money-center banks. Houston anchors commodity trade operations for oil and gas documentary credits.
India
SME garment manufacturers in Tamil Nadu and pharmaceutical exporters in Gujarat require working-capital solutions as supply chain digitization accelerates. RBI's TReDS platform draws non-bank participants into invoice discounting beyond traditional banking channels. Mumbai concentrates trade finance operations for cross-border rupee settlement.
United Arab Emirates
Gold refiners in Dubai and re-export traders in Jebel Ali Free Zone demand letters of credit for multi-jurisdictional deals spanning African and South Asian corridors. MOHAP and the central bank regulate electronic trade document frameworks. Dubai International Financial Centre hosts correspondent banking infrastructure for Middle East-Africa trade.
Singapore
Commodity traders and shipping operators require documentary credit facilities for bunker fuel and agricultural product flows through the Straits. MAS implements Basel III risk-weighting standards for trade asset exposures. The city-state anchors Asia-Pacific correspondent liquidity for Greater China-ASEAN corridors.
Germany
Automotive component suppliers and machinery exporters in Baden-Württemberg seek receivables financing as procurement centralization compresses payment terms. BaFin enforces EU-wide capital requirements for trade finance exposures. Frankfurt concentrates institutional cash-management infrastructure for euro-denominated trade instruments.
Trade Finance Market Key Industry Players
Balance-sheet syndication dominates the current landscape as tier-1 banks redistribute trade exposures to non-bank liquidity pools. The vendor base concentrates among Asia-Pacific and European money-center institutions with deep correspondent networks. Three archetypes define positioning: universal banks with institutional cash-management infrastructure, frontier-market specialists with local-currency licenses, and fintech platforms automating SME onboarding. Competitive moves center on API integration with enterprise resource planning systems and strategic partnerships with logistics platforms.
Within the universal bank tier, HSBC Holdings plc and Citigroup Inc. exemplify institutions leveraging Asia-Pacific correspondent footprints for documentary trade flows, while Standard Chartered PLC occupies a position as a frontier-market specialist. These entities represent contrasting approaches to geographic coverage and client segmentation in a market where Basel III capital charges compress returns on balance-sheet-intensive instruments.
| Leading Market Players |
|---|
| HSBC Holdings plc |
| Citigroup Inc. |
| BNP Paribas SA |
| Standard Chartered PLC |
| JPMorgan Chase & Co. |
| Bank of America Corporation |
| DBS Bank Ltd. |
| ING Groep |
| Santander Bank |
| Others |
Cost & Logistics Intelligence
Basel III capital adequacy mandates gate qualified supply for trade finance instruments, restricting balance-sheet-intensive documentary credit services to tier-1 banks with sufficient risk-weighted asset headroom while elevating pricing premiums for non-bank liquidity pools. Premium-tier pricing access concentrates among institutions that have secured correspondent banking licenses across India, Singapore, and the United Arab Emirates, where regulatory arbitrage on capital treatment creates tiered service availability.
Pricing Analysis
Documentary credit pricing bundles confirmation and negotiation services into headline spreads, while unbundled fintech platform fees for transaction financing expose working-capital costs to direct comparison. Pricing stratifies across premium correspondent-bank tiers, standard regional lender tiers, and economy non-bank platform tiers based on counterparty credit grade and jurisdictional enforcement risk. Pricing pressure stems from buyer concentration among large importers centralizing procurement treasury functions and negotiating standardized terms across supplier bases. SME exporters exhibit highest price sensitivity due to thin margin structures, while commodity traders with multi-jurisdictional legal recourse demonstrate lowest sensitivity.
Supply Chain Analysis
Reverse-logistics flows for trade finance documentation remain minimal, though electronic bill-of-lading frameworks in the United Kingdom and Singapore enable digital document re-issuance and amendment workflows that reduce physical document return requirements. Geographic supply concentration for trade finance liquidity draws from the United Kingdom, Singapore, and Hong Kong as anchor correspondent banking hubs. Raw material dependencies rest on iron ore flows from Western Australia, petroleum reserves from Saudi Arabia, and semiconductor components from Taiwan. Single-source vulnerability concentrates in tier-1 bank balance-sheet capacity as Basel III rules compress available documentary credit supply. Distribution runs through correspondent banking networks with SWIFT messaging infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trade finance is becoming a vertical-integration race as institutions pursue backward integration into data and document verification infrastructure to capture margin from automated discrepancy checking and smart-contract settlement.
For Market Incumbents: To counter fintech platform disintermediation in SME working-capital segments, tier-1 banks must deepen API integration with enterprise resource planning systems and consolidate compliance architecture around platform-native document verification. Capacity addition in India through RBI TReDS platform participation and certification investment in electronic transferable record frameworks under UNCITRAL Model Law implementations will defend correspondent banking relationships. For New Entrants and Emerging Players: Begin with invoice discounting for garment and electronics exporters in Vietnam and Indonesia, where procurement centralization has displaced traditional bank intermediaries with direct platform connections. The most penetrable segment comprises mid-market corporates with ERP-embedded working-capital needs; the optimal go-to-market angle partners with logistics software providers for receivables financing integration at customs clearance workflows. For Investors and Strategic Acquirers: First-mover jurisdiction adoption of enforceable electronic bill-of-lading frameworks is the leading indicator that platform-based trade finance infrastructure will achieve operational scale ahead of lagging markets. Long-term viability over the next decade favors specialists with local-currency settlement licenses in frontier-market corridors. Acquisition targets should display on-ground banking infrastructure in Sub-Saharan Africa or Central Asia combined with automated KYC tooling. Practitioners should monitor regulatory filings for UNCITRAL Model Law implementation status as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| API Integration with ERP Systems | Embedding trade finance into procurement workflows captures SME segments previously excluded by high onboarding costs. |
| Electronic Transferable Records Adoption | UNCITRAL Model Law implementations in Singapore and the United Kingdom remove legal barriers for digital bill-of-lading enforceability. |
| Correspondent Network Expansion | Deepening Asia-Pacific footprint anchors documentary credit flows between Greater China and Middle East commodity corridors. |
| Non-Bank Liquidity Partnerships | Distribution models tap institutional capital pools as Basel III risk-weighted asset charges compress balance-sheet returns. |
| Automated KYC Platform Development | Machine-learning document verification reduces acquisition costs for SME traders in India and Indonesia. |
Research Approach
Document review covered ICC Banking Commission rulemaking archives, Basel Committee on Banking Supervision regulatory filings, and national implementations of the UNCITRAL Model Law on Electronic Transferable Records, complemented by interviews with trade finance operations heads at tier-1 banks, documentary credit specialists at correspondent banking units, fintech platform product managers, and regulatory affairs officers at central banks in India, Singapore, and the United Arab Emirates. Secondary validation drew from SWIFT transaction flow data, central bank payment system statistics, and export credit agency disbursement reports. Bottom-up transaction volume estimates triangulated against top-down banking sector asset exposure data.
Segment-level projections across service type, client tier, funding source, and transaction size dimensions fed into analytical framework outputs over the projection horizon. CAGRs derived from trend extrapolation of digitization adoption curves, regulatory implementation timelines, and correspondent banking relationship migration patterns. Industry-specific forecast inputs incorporated RBI TReDS platform transaction velocity and API-connected distributed ledger pilot expansion rates in India and the United Arab Emirates.
Underlying measurement precision varies by segment; letter-of-credit volumes carry tighter precision due to SWIFT messaging traceability, while fintech platform transaction financing estimates reflect greater uncertainty given private company disclosure gaps. Forecasts incorporate assumptions around Basel III endgame implementation timing and electronic trade document legal recognition progress that could revise trajectory if regulatory delays emerge. Practitioners should monitor central bank regulatory filings for risk-weighting rule finalization and national legislative dockets for electronic transferable records adoption as early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
ATM Management Service Market
Financial Services
Islamic Finance Market
Financial Services
E-KYC Market
Financial Services
Germany E-Brokerage Market
Financial Services
Global Medical Equipment Financing Market
Financial Services
Smart Finance Services Market
Financial Services
Europe B2C Legal Services Market
Financial Services
Power Bank Sharing Services Market
Financial Services
China Trade Finance Market
Financial Services
Back-Office Outsourcing in Financial Services Market
Financial Services
LAMEA Financial Services Software Market
Financial Services
Solar Powered ATM Market
Financial Services
Intermediary Service Market
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
E-Invoicing Market
Financial Services
Financial Services Software Market