

Organ Preservation & Perfusion Products Market Size, Share, and Industry Trends Forecast 2026-2036
Organ Preservation & Perfusion Products Market Insights
EU Green Deal sustainability criteria for medical device procurement is shifting purchasing priorities across European transplant networks. TransMedics leverages integrated organ care systems to anchor its position in heart and lung transport. XVIVO competes through specialized perfusion solutions for marginal organ assessment. Paragonix Technologies differentiates via controlled-temperature shipping containers that extend preservation windows for distant donor matches.
Organ preservation and perfusion products encompass solutions and devices that maintain organ viability between procurement and transplantation through temperature-regulated storage, nutrient-enriched perfusion, or mechanical circulatory support. Static cold storage using University of Wisconsin or histidine-tryptophan-ketoglutarate solutions remains the baseline method, though machine perfusion now enables metabolic monitoring and therapeutic intervention during transport. Normothermic perfusion devices command premium positioning as transplant programs adopt ex-vivo organ assessment for expanded-criteria donors. Hypothermic oxygenated perfusion represents the fastest-growing technology segment as liver programs seek to reduce ischemic injury in donation-after-circulatory-death organs.
FDA breakthrough device designation pathways and EMA MDR compliance requirements shape product development timelines and clinical evidence standards for perfusion innovators. The country's national pharmaceutical regulator in France, ANSM, coordinates with EMA on organ transport container validation protocols that determine market access across EU member states. Stakeholders must monitor evolving reimbursement frameworks for machine perfusion as health technology assessment bodies in Germany and England evaluate cost-effectiveness against static cold storage baselines.
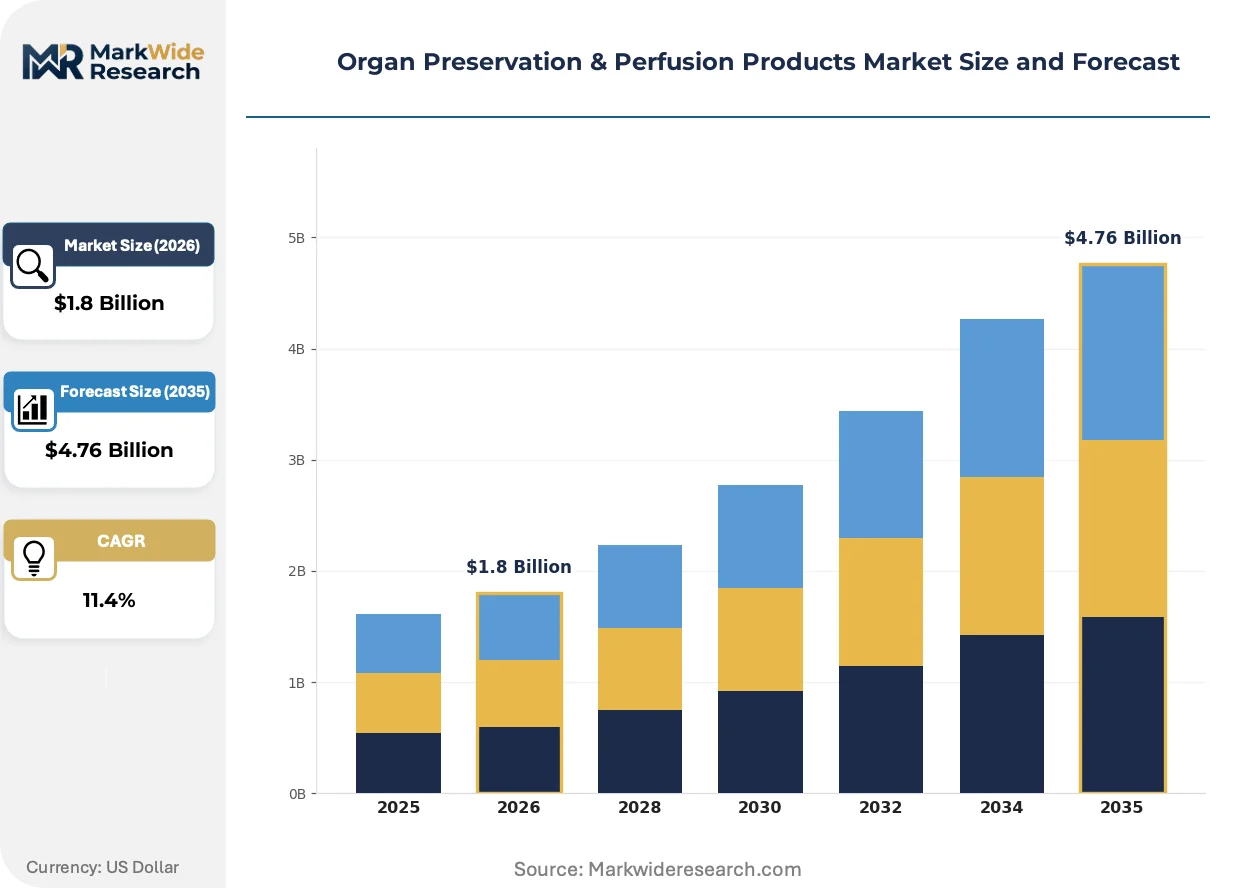
Market Dynamics
Machine perfusion systems are compressing procurement cycles for transplant centers as CMS reimbursement frameworks realign with FDA breakthrough device pathways, forcing capital allocation toward metabolic monitoring capabilities over static cold storage baselines.
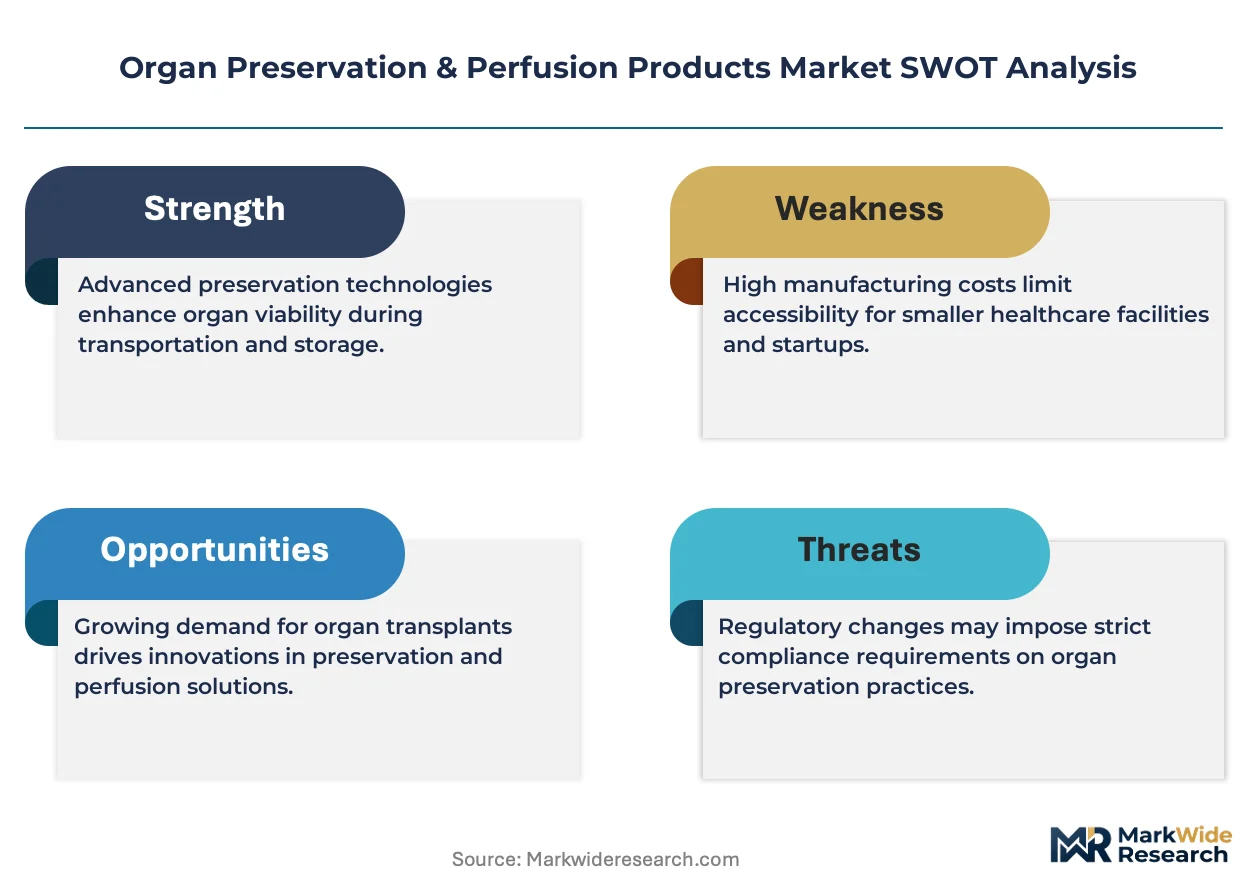
Growth Catalysts
- EMA MDR harmonization:Unified organ transport container validation protocols across EU member states are reducing regulatory friction for normothermic perfusion platform deployments in France, Germany, and the Netherlands.
- Expanded-criteria donor pools:Liver programs in the United States are integrating hypothermic oxygenated perfusion to recover marginal organs from donation-after-circulatory-death protocols.
- Metabolic assessment capabilities:Real-time lactate clearance monitoring during ex-vivo organ transport is enabling therapeutic intervention windows that static cold storage cannot replicate.
Market Restraints
- Perfusion consumable costs:Single-use organ cassettes and proprietary nutrient solutions create recurring expenditure burdens that exceed static cold storage baselines by substantial multiples.
- Supply concentration in Germany:Normothermic perfusion platform manufacturing clusters around Munich and Heidelberg create geographic vulnerability for procurement timelines.
- FDA breakthrough evidentiary thresholds:Clinical data requirements for metabolic monitoring claims extend product development timelines beyond typical medical device pathways.
Strategic Opportunities
- EU Green Deal procurement criteria:Sustainability mandates for medical device purchasing are creating preference windows for perfusion systems with reduced carbon footprint transport modalities.
- Heart-lung block preservation:Integrated thoracic organ care systems represent underpenetrated application space beyond isolated heart or lung protocols.
- Telemedicine integration:Remote monitoring of perfusion parameters during air transport is enabling centralized surgical command centers to assess organ viability prior to recipient preparation.
Industry Challenges
- Perfusionist workforce scarcity:Specialized training requirements for ex-vivo organ management outpace certified practitioner pipeline output in United States transplant centers.
- Legacy cold storage infrastructure:Hospital organ procurement organizations maintain sunk investments in static storage workflows that resist machine perfusion workflow reconfiguration.
- Interoperability standards:Proprietary data formats from competing perfusion device manufacturers block seamless electronic health record integration for metabolic trend analysis.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organ Preservation & Perfusion Products Market Trends and Innovations
Active metabolic intervention during transport is displacing passive preservation as the dominant paradigm, with real-time organ assessment capabilities reshaping how transplant programs evaluate marginal donor suitability.
Normothermic regional perfusion is overtaking static cold storage as the preferred modality for heart and lung transport among high-volume United States transplant centers. Academic medical centers in Boston and Houston are deploying integrated organ care systems that maintain physiologic temperature and metabolic activity during extended ischemic intervals. This technology is compressing geographic constraints on donor-recipient matching by extending viable transport windows from four hours to twelve hours.
REACH chemical safety frameworks and EU MDR clinical evidence requirements are elevating validation standards for perfusion solution formulations sold into European transplant networks. Manufacturers must now submit biocompatibility data for complete perfusion circuits rather than isolated components. Liver perfusion platforms face the steepest compliance burden given extended exposure durations and metabolic active ingredient complexity.
Transplant program purchasing committees are consolidating vendor relationships around full-service perfusion contracts that bundle device placement, consumable supply, and technical support. Independent organ procurement organizations in the United States Midwest are ceding equipment procurement authority to affiliated hospital systems with greater capital resources. This concentration is most visible in Illinois and Ohio, where three health systems now control perfusion platform selection for twelve previously autonomous OPOs.
Organ Preservation & Perfusion Products Market Segmentation
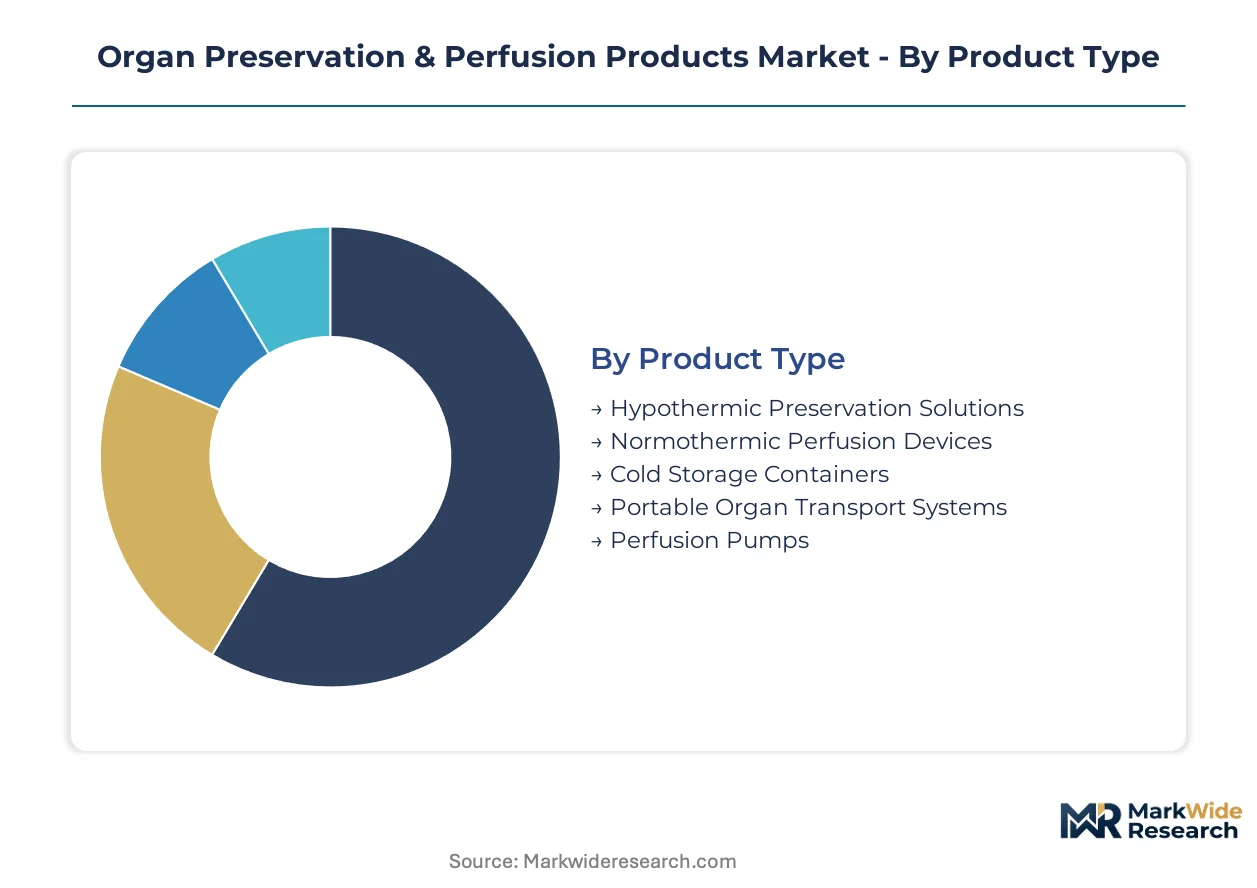
Segmentation in organ preservation and perfusion products reveals how technology integration depth varies from standalone consumables to complex embedded systems. Transplant programs make capital allocation decisions across these categories based on procedural volume, donor organ complexity, and reimbursement alignment.
Product Type:
Standalone solutions dominate procurement for low-volume centers, while integrated platforms anchor enterprise transplant programs seeking metabolic monitoring capabilities.
- Hypothermic Preservation Solutions:University of Wisconsin and histidine-tryptophan-ketoglutarate formulations remain the biochemical foundation for static cold storage protocols. Demand concentrates in organ procurement organizations across the United States Midwest, where legacy workflows resist capital-intensive machine perfusion transitions.
- Normothermic Perfusion Devices:Integrated organ care systems maintain physiologic temperature and metabolic activity through ex-vivo circulatory support. Procurement in Germany's transplant networks accelerates as EMA harmonized validation protocols reduce regulatory friction for platform deployments.
- Cold Storage Containers:Passive temperature-regulated shipping units serve as backup transport infrastructure.
- Portable Organ Transport Systems:Battery-powered mobile units enable ground and air ambulance deployment.
- Perfusion Pumps:Mechanical circulatory components integrate into larger platform architectures.
Volume placements concentrate in Hypothermic Preservation Solutions; the steepest expansion trajectory belongs to Normothermic Perfusion Devices.
Application:
Organ-specific preservation requirements create divergent technology preferences, with thoracic applications demanding more sophisticated metabolic support than abdominal organs.
- Liver Transplantation:Hypothermic oxygenated perfusion is displacing static cold storage as the preferred modality for donation-after-circulatory-death organs. United States academic medical centers in Houston and Boston lead adoption, driven by expanded-criteria donor recovery protocols and ischemic injury reduction targets.
- Heart Transplantation:Normothermic regional perfusion extends viable ischemic intervals from four hours to twelve hours, compressing geographic constraints on donor-recipient matching. Procurement in Illinois and Ohio health systems accelerates as consolidated vendor contracts bundle device placement with technical support.
- Kidney Transplantation:Machine perfusion enables viability assessment for marginal donor organs.
- Lung Transplantation:Ex-vivo lung perfusion platforms support extended criteria donor evaluation.
- Pancreas Transplantation:Preservation protocols adapt liver-derived hypothermic oxygenated techniques.
Procurement volume clusters in Liver Transplantation; Heart Transplantation claims the fastest share gain as thoracic programs consolidate around integrated care systems.
End User:
Customer type determines purchasing authority structure, with independent organ procurement organizations ceding equipment decisions to affiliated hospital systems.
- Transplant Centers:High-volume academic medical centers command capital budgets for normothermic platform acquisition and perfusionist workforce expansion. United States centers face CMS reimbursement realignment pressures that favor metabolic monitoring capabilities over static storage baselines.
- Organ Banks:Independent procurement organizations maintain cold storage infrastructure for geographic organ distribution networks.
- Research Laboratories:Preclinical testing facilities drive demand for specialized perfusion circuit components.
- Surgical Hospitals:Secondary transplant programs rely on outsourced organ transport services.
- Biotechnology Firms:Cell therapy developers adapt perfusion technologies for organoid and tissue engineering applications.
Capital deployment concentrates in Transplant Centers; Organ Banks represent the most price-sensitive segment with limited platform conversion appetite.
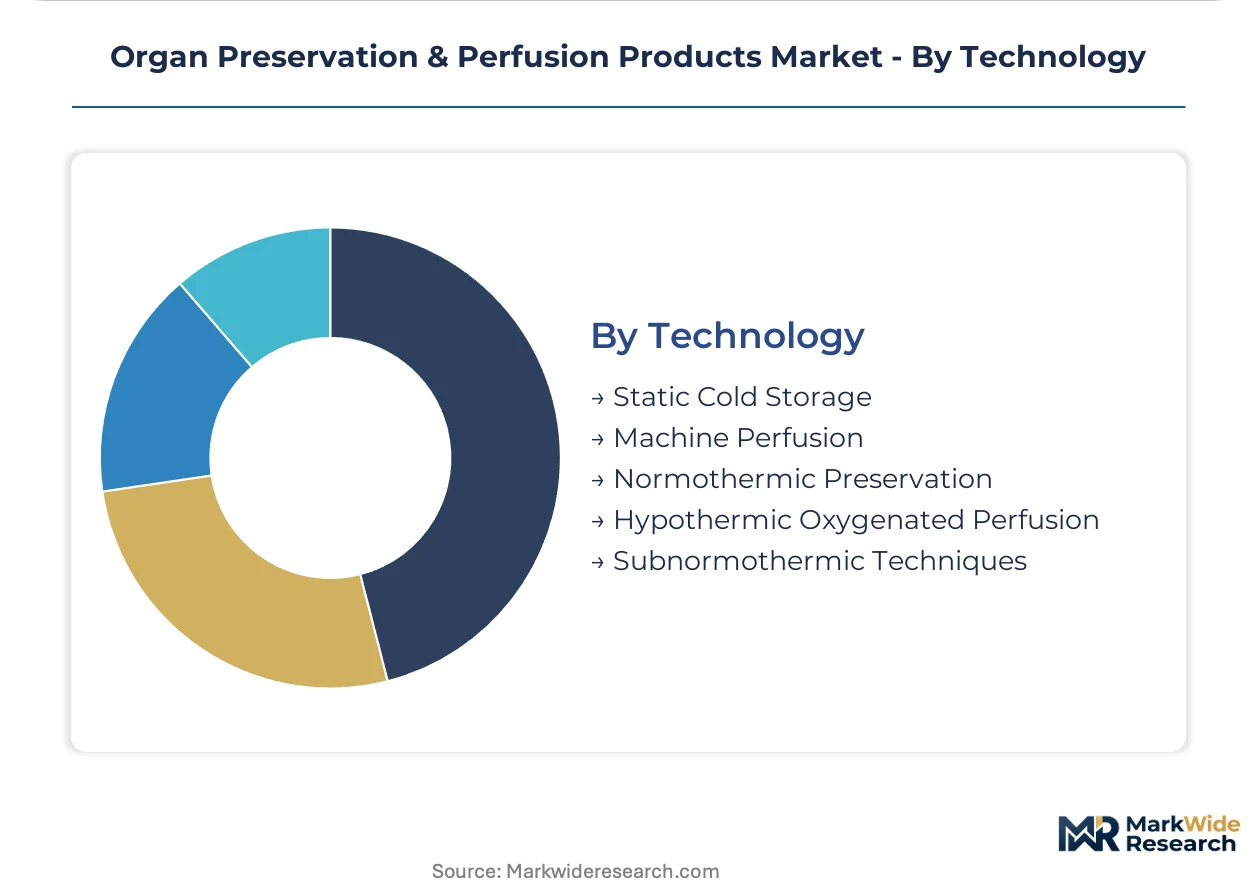
Technology:
Technology maturity spans decades-old static methods to emerging metabolic intervention platforms, with regulatory evidence requirements scaling with system complexity.
- Machine Perfusion:Active circulatory support with real-time metabolic monitoring enables therapeutic intervention during transport. FDA breakthrough device pathways demand extended clinical evidence timelines, slowing product development cycles for perfusion innovators seeking metabolic assessment claims.
- Hypothermic Oxygenated Perfusion:Temperature-reduced oxygen delivery reduces ischemic injury in extended preservation intervals. Liver programs in France coordinate with ANSM on transport container validation protocols that determine EU market access.
- Static Cold Storage:Passive hypothermic preservation remains the baseline method for standard-criteria donors.
- Normothermic Preservation:Physiologic temperature maintenance supports heart and lung viability assessment.
- Subnormothermic Techniques:Intermediate temperature protocols balance metabolic demand with oxygen consumption reduction.
Installed base dominance rests with Static Cold Storage; Hypothermic Oxygenated Perfusion is climbing the fastest as liver programs recover marginal donor organs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich and Heidelberg anchor European manufacturing clusters for normothermic perfusion platforms, while Houston and Boston academic medical centers drive United States adoption of metabolic monitoring systems. Transplant network procurement patterns diverge sharply across regulatory environments.
United States
CMS reimbursement realignment with FDA breakthrough device pathways is compressing procurement cycles for transplant centers. Academic medical centers in Houston and Boston lead hypothermic oxygenated perfusion adoption for donation-after-circulatory-death liver recovery. Illinois and Ohio health systems now control perfusion platform selection for twelve previously autonomous organ procurement organizations.
Germany
EMA harmonized organ transport container validation protocols are reducing regulatory friction for normothermic platform deployments. The EU Green Deal sustainability criteria for medical device procurement is shifting purchasing priorities across German transplant networks. Munich and Heidelberg manufacturing clusters concentrate normothermic perfusion platform production, creating geographic vulnerability for procurement timelines.
France
ANSM coordinates with EMA on transport container validation protocols that determine market access across EU member states. REACH chemical safety frameworks are elevating validation standards for perfusion solution formulations sold into French transplant networks. Paris-area transplant programs are consolidating vendor relationships around full-service perfusion contracts bundling device placement with technical support.
United Kingdom
Health technology assessment bodies in England are evaluating machine perfusion cost-effectiveness against static cold storage baselines. NHS transplant networks face EU MDR compliance requirements shaping product development timelines for perfusion innovators seeking market access. London academic medical centers are deploying integrated organ care systems that extend viable transport windows from four hours to twelve hours.
Netherlands
EMA MDR harmonization benefits Dutch transplant networks through unified organ transport container validation protocols. Amsterdam and Rotterdam transplant centers are integrating real-time lactate clearance monitoring during ex-vivo organ transport. Dutch organ procurement organizations are ceding equipment procurement authority to affiliated hospital systems with greater capital resources.
Organ Preservation & Perfusion Products Market Competitive Landscape
The competitive structure tilts toward integrated platform specialists with full-service contract capabilities. Vendor relationships concentrate around bundled offerings combining device placement, consumable supply, and technical support. Three archetypes dominate: integrated organ care system providers, specialized perfusion solution manufacturers, and controlled-temperature shipping container specialists. M&A activity and strategic partnerships represent the dominant competitive moves as players seek metabolic monitoring capabilities and geographic expansion.
Within the integrated platform tier, TransMedics and XVIVO exemplify divergent strategic positioning. TransMedics occupies a position anchoring heart and lung transport through integrated organ care systems. XVIVO represents specialized perfusion solutions for marginal organ assessment. Paragonix Technologies sits within the controlled-temperature shipping container segment, differentiating via preservation window extension for distant donor matches.
| Leading Market Players |
|---|
| TransMedics |
| XVIVO |
| Organ Recovery Systems |
| OrganOx |
| Paragonix Technologies |
| Bridge to Life |
| Dr. Franz Köhler Chemie |
| Preservation Solutions |
| Institut Georges Lopez |
| Others |
Pricing and Supply Chain Analysis
Proprietary nutrient solution formulations flow from German chemical manufacturers through perfusion platform OEMs to transplant centers, with single-source cassette designs anchoring premium pricing tiers against commodity cold storage baselines. The cost stack reflects regulatory validation burdens more than raw material inputs, concentrating margin capture with integrated system providers.
Pricing Analysis
Outcome-linked pricing anchors machine perfusion contracts, with transplant programs paying premium rates for metabolic monitoring capabilities that reduce organ discard rates. Price differentiation separates FDA breakthrough-designated platforms from CE-marked alternatives, while volume scale discounts concentrate among consolidated US health systems. Pricing pressure stems from CMS reimbursement lag against capital-intensive platform adoption, with independent organ procurement organizations exhibiting highest price sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Munich and Heidelberg manufacturing clusters for normothermic perfusion platform assembly. German precision component suppliers and US-based biocompatible polymer feedstock providers anchor upstream inputs. Supply chain risk centers on REACH chemical compliance timelines for perfusion solution formulations. Distribution runs through direct field service teams rather than third-party medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine perfusion systems are displacing static cold storage as the dominant preservation paradigm, with normothermic platforms replacing passive hypothermic methods across thoracic and liver transplant programs.
For Market Incumbents: Extend metabolic monitoring capabilities into telemedicine-integrated command centers that enable remote organ assessment during air transport. Consolidate perfusionist training programs to address workforce scarcity before emerging entrants capture service revenue. Deepen backward integration into proprietary nutrient solution manufacturing to defend margin position against consumable cost compression. For New Entrants and Emerging Players: Independent organ procurement organizations in the US Midwest represent the most penetrable buyer segment, given ceded procurement authority and limited capital resources for platform conversion. Target pancreas and kidney preservation protocols where hypothermic oxygenated techniques remain underdeveloped relative to liver applications. Pursue hospital system partnerships that bundle device placement with technical support contracts. For Investors and Strategic Acquirers: EMA MDR harmonization completion is the leading indicator that European normothermic platform deployments will accelerate beyond German transplant networks. Long-term viability favors integrated platform specialists with full-service contract capabilities over standalone consumable manufacturers. Watch for FDA breakthrough device designations paired with CMS reimbursement alignment as the signal for US market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS alignment with FDA breakthrough pathways determines US transplant center procurement cycles. |
| Hospital System Partnership | Consolidated vendor contracts in Illinois and Ohio health systems control twelve previously autonomous OPOs. |
| CE Marking Pathway | EMA MDR harmonization reduces regulatory friction for normothermic platform deployments across EU member states. |
| Software Companion Development | Real-time lactate clearance monitoring enables therapeutic intervention windows during ex-vivo transport. |
| Backward Integration | In-house production of proprietary nutrient solutions defends margin position against consumable cost pressure. |
Research Methodology
Document review covered FDA 510(k) filings, EMA MDR submission databases, and CMS Medicare reimbursement guidance, complemented by interviews with transplant surgeons, biomedical engineers, and organ procurement organization executives. Secondary sources included hospital procurement databases, GPO contracts, and EU Green Deal medical device procurement criteria. Bottom-up unit placement estimates were cross-validated against top-down market size triangulation.
Historical adoption curves for machine perfusion platforms were cross-referenced against expert panel input on reimbursement timing and regulatory pathway completion. The analytical framework modeled segmentation across product type, application, end user, and technology dimensions throughout the forecast period. CAGRs were derived from procedure volume growth, expanded-criteria donor pool expansion, and platform replacement cycles for legacy cold storage infrastructure.
Caveats apply where FDA breakthrough evidentiary thresholds or EMA MDR compliance delays could materially shift the outlook for metabolic monitoring claims. Forecasts reflect assumptions on CMS reimbursement alignment, perfusionist workforce expansion rates, and EU Green Deal sustainability criteria enforcement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.