
 Aviation Titanium Alloy Market | 2026-2036
Aviation Titanium Alloy Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Titanium Alloy Market Insights
Defense contractors are gaining share as commercial airlines defer widebody deliveries, and the Aviation Titanium Alloy Market is bifurcating between military and civilian procurement channels. ATI leverages its integrated titanium sponge-to-mill-product chain to serve Pratt & Whitney engine programs. VSMPO-AVISMA sustains dominance in forged billet supply through its Verkhnyaya Salda production complex. TIMET anchors North American aerospace grade capacity with dedicated melting operations in Nevada and Pennsylvania.
Aviation titanium alloys are titanium-based metallic materials, typically alloyed with aluminum, vanadium, or molybdenum, that achieve tensile strengths exceeding 1200 MPa while maintaining density roughly half that of steel, making them indispensable for structural and thermal applications in jet propulsion systems. Grade 5 titanium commands the largest volume share in airframe applications due to its balanced strength-to-weight ratio and established weldability credentials. Additive manufacturing represents the fastest-growing technology segment as Boeing and Safran qualify powder-bed fusion processes for engine bracket production. Powder metallurgy occupies a niche but high-margin position in near-net-shape compressor blades where material yield rates determine contract economics.
FAA airworthiness standards govern titanium alloy qualification timelines for structural applications, while EPA regulations on chlorination byproducts constrain sponge production economics at U.S. facilities. REACH compliance in Europe restricts certain vanadium leaching thresholds, affecting Grade 5 export certification costs for TIMET and ATI. Stakeholders must monitor additive manufacturing qualification protocols and defense procurement budget cycles to anticipate titanium alloy demand inflections.
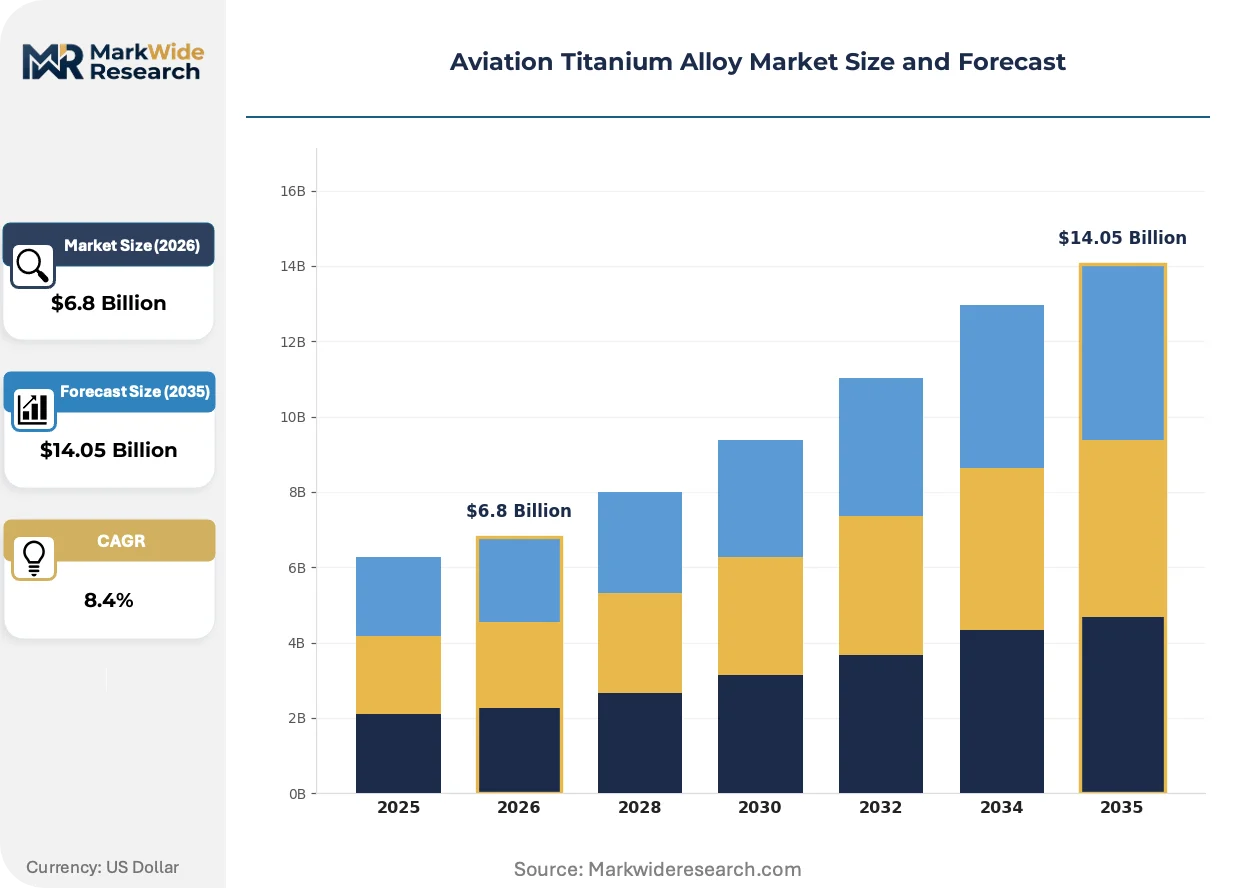
Market Dynamics
Additive manufacturing qualification timelines and defense procurement acceleration are compressing traditional titanium alloy supply chains while fragmenting demand across powder-based and wrought product channels.
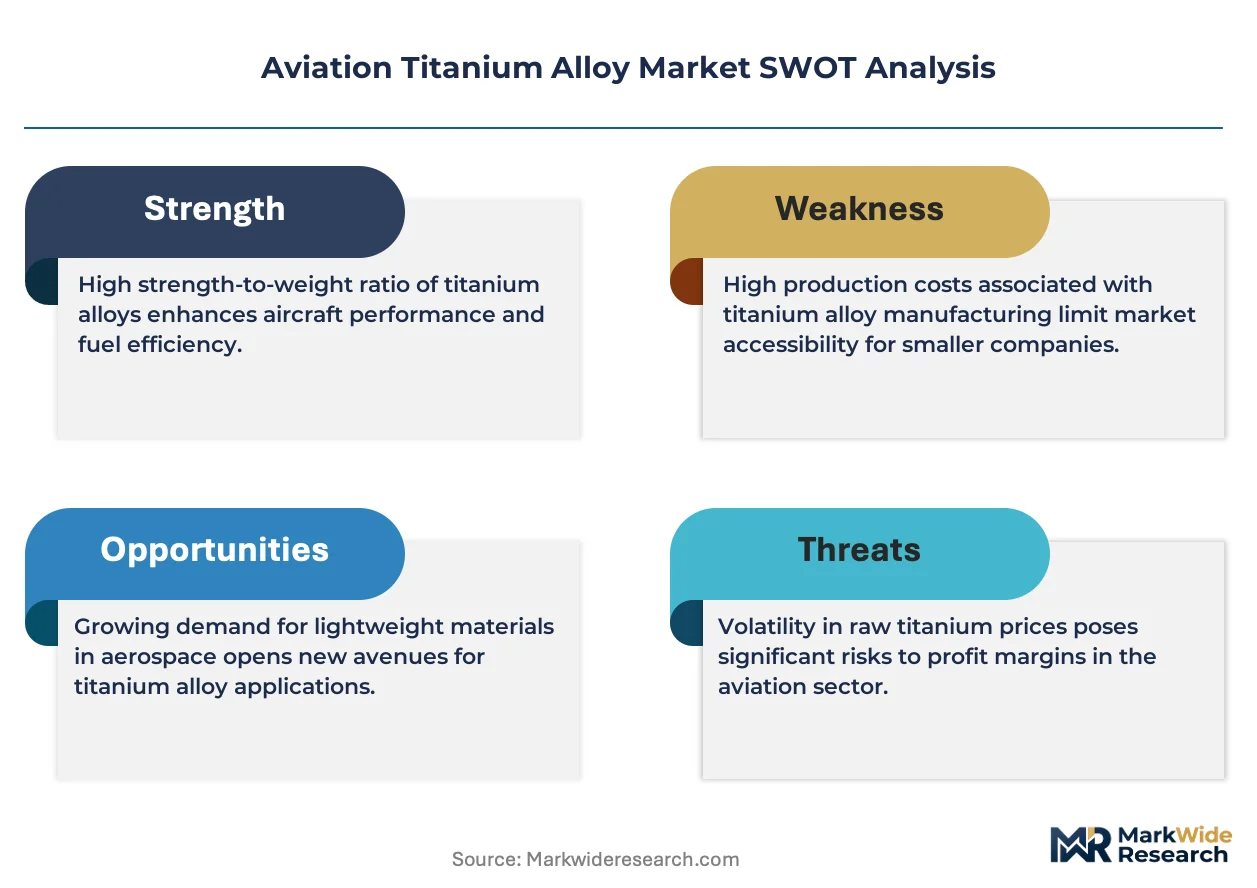
Growth Catalysts
- FAA airworthiness certification streamlining:Expedited qualification pathways for powder-bed fusion components reduce time-to-market for engine bracket applications.
- Next-generation fighter programs:Military aerospace procurement is expanding titanium alloy offtake for airframe and propulsion systems.
- Plasma cold hearth melting:Advanced refining technology improves ingot cleanliness for rotating engine components.
Market Restraints
- Sponge production concentration:Russian and Chinese suppliers control over half of global titanium sponge capacity, creating geopolitical supply vulnerability.
- Chlorination byproduct regulations:EPA emissions constraints on TiCl4 waste streams elevate production costs at U.S. sponge facilities.
- Superalloy substitution in hot sections:Nickel-based alloys displace titanium above 600°C in compressor aft stages.
Strategic Opportunities
- India defense localization:PLI scheme incentives and indigenization mandates create captive demand for aerospace-grade mill products.
- Near-net-shape blade casting:Ceramic mold investment casting reduces material yield loss in high-pressure compressor airfoils.
- EU Green Deal industrial funding:Carbon border adjustment mechanisms favor low-carbon titanium production routes.
Industry Challenges
- Non-destructive testing technician shortage:Ultrasonic and radiographic inspection capacity bottlenecks constrain throughput at forge shops.
- Dual-certification complexity:Simultaneous FAA and EASA qualification requirements extend development timelines for new alloy grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Titanium Alloy Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grade 5, Grade 23, Grade 9, Grade 12 Technology: Forging, Casting, Powder Metallurgy, Additive Manufacturing Application: Airframe, Engine Components, Landing Gear, Fasteners End User: Commercial Airlines, Defense Contractors, Aircraft Maintenance, Engine Manufacturers |
| Companies Covered | ATI (Allegheny Technologies Inc.), VSMPO-AVISMA Corporation, TIMET (Titanium Metals Corporation), Howmet Aerospace, Carpenter Technology Corporation, Kobe Steel, Ltd., Aubert & Duval, Toho Titanium Co., Ltd., Western Superconducting Technologies Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Titanium Alloy Market Trends and Innovations
Digital thread integration across the titanium value chain is compressing design-to-production cycles while enabling real-time quality traceability from sponge to finished component.
Powder metallurgy near-net-shape processing is fragmenting traditional forging economics. Boeing and Safran are qualifying titanium aluminide intermetallic blades produced via hot isostatic pressing for low-pressure turbine stages. This technology is fragmenting the forged billet supply base by reducing buy-to-fly ratios from eight-to-one toward two-to-one in selected airfoil geometries.
REACH vanadium leaching thresholds are tightening material certification requirements for Grade 5 titanium exports into European aerospace supply chains. ECHA substance restriction proposals are forcing TIMET and ATI to reformulate surface treatment chemistries and document full material provenance. German and French tier-one suppliers are now requiring REACH-compliant certificates of analysis for all titanium mill products.
Long-term offtake agreements are displacing spot market purchasing for aerospace-grade titanium sponge and master alloys. Tier-one engine manufacturers are locking in five-to-seven-year supply contracts directly with Russian and Japanese sponge producers. This pattern is most visible in the United States, where Pratt & Whitney and GE Aviation have secured dedicated capacity at Nevada and Pennsylvania melting facilities through 2030.
Aviation Titanium Alloy Market Segmentation
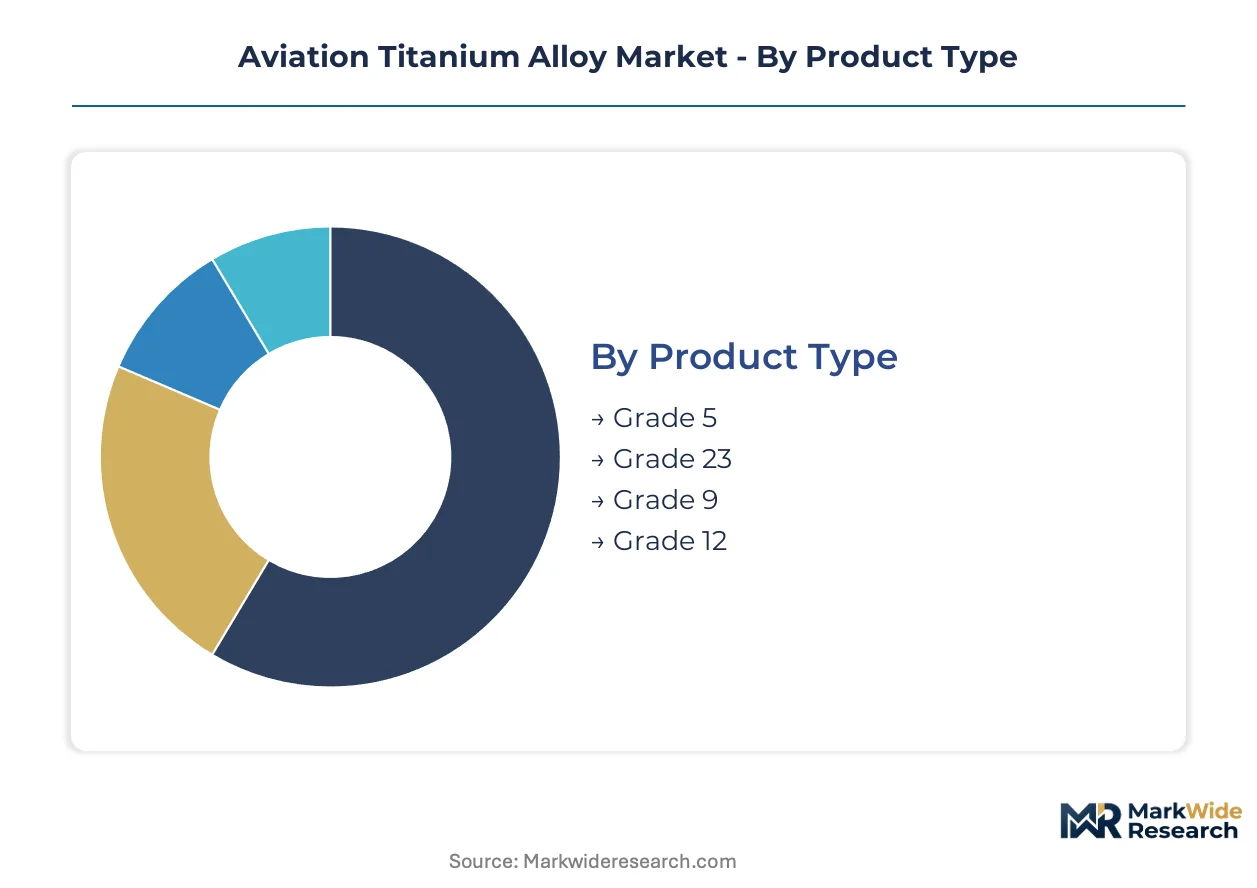
Titanium alloy procurement channels diverge sharply between military and civilian aerospace, with defense contractors locking in long-term offtake while commercial airlines negotiate spot-adjusted contracts. Understanding these segment boundaries clarifies where pricing power concentrates and where qualification barriers protect incumbent suppliers.
Product Type:
Domestic U.S. sponge-to-mill production favors Grade 5 and Grade 23 for engine programs, while export-oriented European supply chains emphasize REACH-compliant surface treatments across all grades.
- Grade 5:Aluminum-vanadium alloy achieving tensile strengths of 895 MPa with established weldability credentials for structural airframe assemblies. Boeing and Lockheed Martin programs in the United States absorb the majority of domestic mill product capacity, constrained by EPA chlorination byproduct limits on TiCl4 waste streams.
- Grade 23:Extra-low interstitial variant of Ti-6Al-4V optimized for fracture toughness in rotating engine components. Demand clusters around Pratt & Whitney and GE Aviation melting facilities in Nevada and Pennsylvania, where plasma cold hearth refining improves ingot cleanliness for disk and blade applications.
- Grade 9:Ti-3Al-2.5V alloy with enhanced cold formability for hydraulic tubing and seamless pipe in landing gear systems.
- Grade 12:Molybdenum-nickel stabilized grade for corrosion-resistant fasteners and chemical processing hardware in coastal operating environments.
Grade 5 holds the largest share; momentum sits with Grade 23 as engine manufacturers tighten cleanliness specifications for rotating hardware.
Technology:
Cost tiers separate legacy wrought processes from emerging powder-based methods, with near-net-shape technologies commanding premium pricing for material yield advantages.
- Forging:Conventional closed-die and isothermal pressing of wrought billet into structural brackets and landing gear beams. VSMPO-AVISMA's Verkhnyaya Salda complex in Russia and ATI's operations in the United States dominate forged billet supply for widebody programs, though geopolitical risk premiums now attach to Russian-origin material.
- Additive Manufacturing:Powder-bed fusion and directed energy deposition for topology-optimized engine brackets and ducting. Boeing and Safran qualification protocols in the United States and France are compressing traditional supply chains, with FAA streamlined certification pathways reducing time-to-market for flight-critical components.
- Casting:Investment casting of titanium aluminide intermetallics for low-pressure turbine blades, displacing forged billet in selected airfoil geometries.
- Powder Metallurgy:Hot isostatic pressing of pre-alloyed powder for near-net-shape compressor blades where buy-to-fly ratios determine contract economics.
Forging retains volume leadership; additive manufacturing is gaining share fastest as qualification timelines compress and powder supply chains mature.
Application:
Customer type splits demand between structural assemblies requiring damage tolerance certification and propulsion systems demanding thermal stability above 300°C.
- Engine Components:Compressor disks, blades, and casings operating between 200°C and 600°C where strength-to-weight ratios dominate material selection. TIMET and ATI melting operations in Pennsylvania and Nevada anchor North American supply for rotating hardware, with long-term offtake agreements locking in sponge capacity through 2030.
- Airframe:Fuselage frames, wing carry-through structures, and empennage assemblies where fatigue crack growth resistance governs alloy selection. Boeing 787 and Airbus A350 programs in the United States and France drive specification standards, with Grade 5 commanding preferred status for established weldability.
- Landing Gear:High-strength forgings for truck beams and piston cylinders subject to impact loading and corrosion exposure.
- Fasteners:Bolts, pins, and lugs requiring cold heading formability and galling resistance in thread interfaces.
Airframe claims the largest installed base; engine components are expanding most quickly as next-generation propulsion programs multiply part counts per engine.
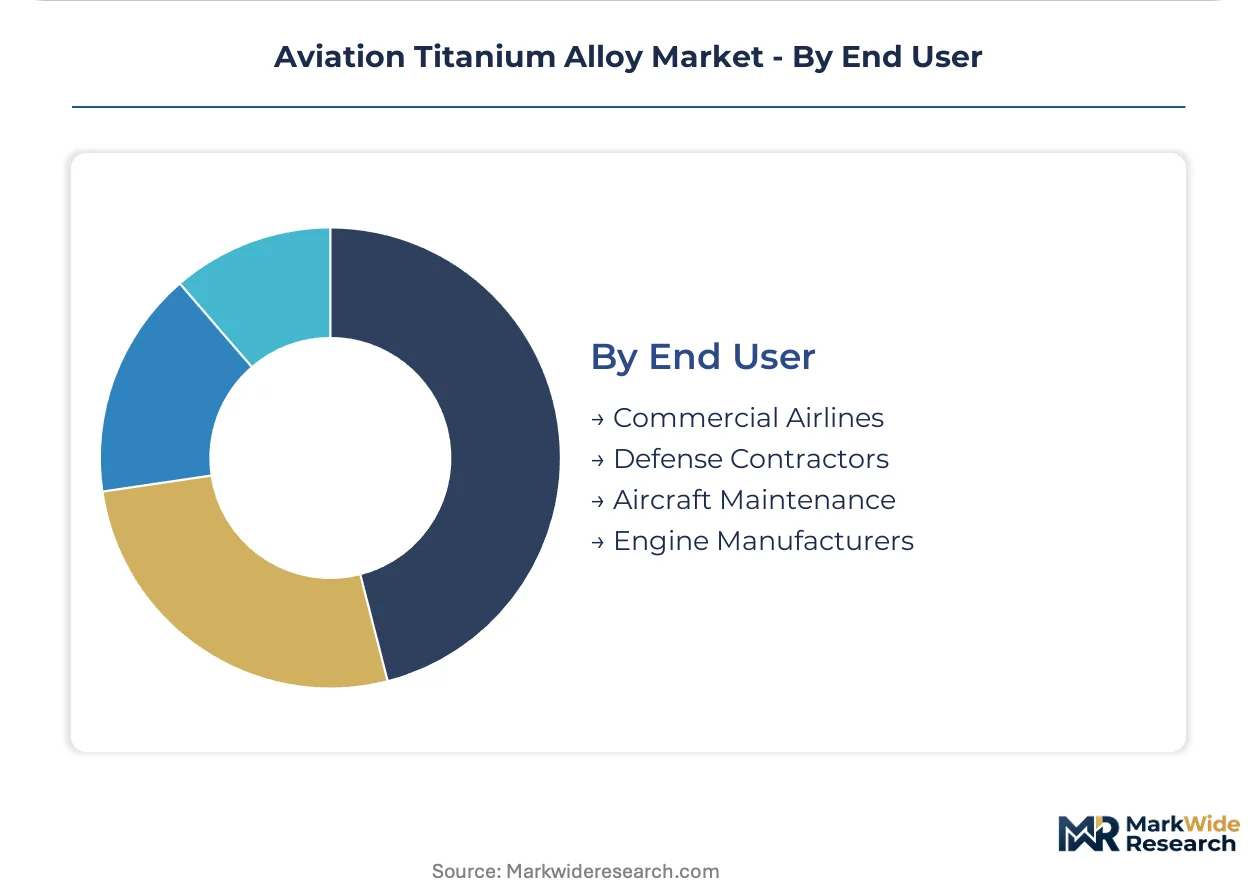
End User:
Procurement patterns separate defense budget cycles from commercial airline capital expenditure timing, with maintenance channels offering countercyclical demand stability.
- Defense Contractors:Lockheed Martin F-35 and next-generation fighter programs in the United States driving classified alloy specifications and captive supply chain investments. Congressional appropriation cycles create demand inflections, with titanium alloy procurement accelerating during production ramp phases.
- Commercial Airlines:Boeing and Airbus delivery schedules determining mill product demand for new aircraft builds. Widebody deferrals during fleet right-sizing periods shift volume temporarily toward narrowbody programs, fragmenting alloy specification requirements.
- Engine Manufacturers:Pratt & Whitney and GE Aviation in the United States qualifying dedicated melting capacity for rotating component cleanliness standards.
- Aircraft Maintenance:Repair station networks consuming mill products and fasteners for damage tolerance restoration, with demand insulating suppliers from new-build cyclicality.
Commercial airlines represent the largest addressable base; defense contractors are climbing the fastest as next-generation programs enter low-rate initial production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sponge production and mill product capacity cluster in the United States, Russia, and Japan, with downstream forging and additive manufacturing qualification concentrated in Western Europe and China. Defense procurement cycles and EPA emissions constraints on chlorination byproducts shape regional competitive positioning.
United States
Boeing and Lockheed Martin programs anchor domestic offtake for Grade 5 and Grade 23 alloys. FAA airworthiness directives govern qualification timelines for structural applications, while EPA regulations on TiCl4 waste streams elevate production costs at Nevada and Pennsylvania melting facilities. TIMET and ATI operations in these states supply rotating engine components under long-term Pratt & Whitney and GE Aviation contracts through 2030.
Russia
VSMPO-AVISMA's Verkhnyaya Salda complex sustains dominance in forged billet supply for widebody airframe programs. Geopolitical risk premiums now attach to Russian-origin material as Western defense contractors accelerate alternative sourcing. The Ural Mountains production cluster faces constrained access to European aerospace supply chains under REACH compliance documentation requirements.
Japan
Toho Titanium anchors sponge production capacity serving Asian engine manufacturers and airframe assemblers. METI industrial policy supports advanced melting technology development for rotating component cleanliness standards. Osaka-based forging operations supply near-net-shape compressor blades to regional tier-one suppliers.
China
Western Superconducting Technologies and state-owned titanium producers expand sponge-to-mill capacity for indigenous commercial aircraft programs. MIIT standards govern aerospace-grade certification timelines, while dual carbon goals constrain chlorination-based production economics. Xi'an and Baoji industrial clusters concentrate forging and additive manufacturing qualification for COMAC narrowbody builds.
France
Safran qualification protocols for powder-bed fusion components compress traditional supply chains for engine brackets and ducting. ECHA REACH vanadium leaching thresholds tighten material certification requirements for Grade 5 imports from TIMET and ATI. The Auvergne-Rhône-Alpes region hosts additive manufacturing research clusters advancing titanium aluminide intermetallic blade casting.
Aviation Titanium Alloy Market Competitive Landscape
Concentration sits with integrated sponge-to-mill producers and specialized forging houses serving defense and commercial aerospace channels. Three archetypes define competitive positioning: vertically integrated titanium producers controlling upstream sponge supply; precision forging specialists delivering high-integrity rotating components; and additive manufacturing technology licensors qualifying powder-based production methods. Capacity expansion and qualification protocol acceleration represent the dominant competitive moves as demand fragments across wrought and powder-based channels.
Within the integrated producer tier, ATI, VSMPO-AVISMA, and TIMET exemplify archetype positioning through captive control of melting and mill product operations. ATI represents North American aerospace-grade capacity with Pennsylvania and Nevada facilities. VSMPO-AVISMA occupies a position in forged billet supply anchored to Ural Mountains production infrastructure. TIMET sits within the premium-grade rotating component segment through dedicated plasma cold hearth refining capabilities. Howmet Aerospace and Carpenter Technology exemplify precision forging and specialty alloy positioning respectively.
| Leading Market Players |
|---|
| ATI (Allegheny Technologies Inc.) |
| VSMPO-AVISMA Corporation |
| TIMET (Titanium Metals Corporation) |
| Howmet Aerospace |
| Carpenter Technology Corporation |
| Kobe Steel, Ltd. |
| Aubert & Duval |
| Toho Titanium Co., Ltd. |
| Western Superconducting Technologies Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
FAA airworthiness certification and EPA emissions compliance gate both supplier qualification and price differentiation simultaneously, with certification tier separating premium-grade rotating components from standard structural mill products while chlorination byproduct constraints elevate domestic sponge production costs.
Pricing Analysis
FAA qualification tiering dictates the pricing tier structure across aerospace-grade titanium alloys, with plasma cold hearth refined Grade 23 commanding premium positioning over standard Grade 5 due to cleanliness specifications for rotating engine hardware. Price differentiation rests on certification level and volume scale, with long-term offtake agreements locking in five-to-seven-year contracts at Pratt & Whitney and GE Aviation melting facilities. Cost compression in wrought billet supply is intensifying because Russian-origin material carries geopolitical risk premiums. Defense contractors demonstrate lowest price sensitivity due to classified program budgets, while commercial airlines negotiate spot-adjusted contracts during fleet right-sizing periods.
Supply Chain Analysis
Strategic stockpiling of titanium sponge dominates inventory strategy among tier-one engine manufacturers, displacing just-in-time preferences given concentration risks in Russian and Chinese upstream capacity. Geographic supply concentrates in the United States, Russia, and Japan, with VSMPO-AVISMA's Verkhnyaya Salda complex and TIMET's Nevada operations anchoring bilateral supply dependencies. Raw material inputs draw from titanium tetrachloride feedstock, aluminum-vanadium master alloys, and pre-alloyed powders for additive manufacturing channels. Single-source vulnerability attaches to Russian sponge supply under Western sanctions exposure. Distribution runs through captive melting arrangements at Pennsylvania and Nevada facilities, with long-term contracts displacing spot market purchasing for aerospace-grade mill products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Additive manufacturing qualification acceleration represents an early-cycle expansion tailwind, with powder-bed fusion adoption expanding addressable demand beyond traditional wrought product channels as Boeing and Safran compress time-to-market for flight-critical components.
For Market Incumbents: Compound defensive positioning through captive sponge-to-mill integration and plasma cold hearth capacity additions at Nevada and Pennsylvania facilities. Nickel-based superalloy substitution above 600°C in compressor aft stages threatens titanium share in hot sections; counter through titanium aluminide intermetallic development for low-pressure turbine stages. Certification investment in FAA streamlined pathways for powder-bed fusion components protects margin structure against emerging additive specialists. For New Entrants and Emerging Players: Differentiate on REACH-compliant surface treatment chemistries for Grade 5 export certification into European aerospace supply chains. White-space targets sit with India defense localization under PLI scheme incentives, where indigenization mandates create captive demand for aerospace-grade mill products absent established domestic suppliers. Near-net-shape blade casting via ceramic mold investment casting offers the most penetrable technology segment, with buy-to-fly ratio economics determining contract awards. Go-to-market through tier-one supplier qualification partnerships with Safran or Pratt & Whitney additive manufacturing programs accelerates credibility. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision forging specialists serving narrowbody landing gear and fastener applications. Long-term viability frames around five-to-ten year defense procurement cycles and commercial fleet replacement waves. Acquisition targets center on additive manufacturing powder suppliers with Boeing or Safran qualification protocols in progress. The signal to watch is FAA certification timeline compression for powder-bed fusion components, which would inflect capital allocation toward qualified powder production capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Cold Hearth Capacity Expansion | TIMET and ATI refining investments improve ingot cleanliness for GE Aviation and Pratt & Whitney rotating disk contracts. |
| Additive Manufacturing Qualification | Boeing and Safran powder-bed fusion protocols compress traditional forging supply chains for engine bracket applications. |
| Long-term Sponge Offtake Agreements | Pratt & Whitney and GE Aviation lock in dedicated capacity at Nevada and Pennsylvania melting facilities through 2030. |
| REACH-Compliant Surface Treatment Reformulation | TIMET and ATI adapt chemistries to meet ECHA vanadium leaching thresholds for European aerospace supply chain access. |
| India Defense Localization Partnership | PLI scheme incentives attract mill product investment for indigenous fighter and engine programs under Ministry of Defence mandates. |
Research Methodology
Initial hypotheses were tested against primary input from titanium sponge procurement managers, aerospace forging operations directors, additive manufacturing qualification engineers, and defense program supply chain leads, and refined through secondary validation against FAA airworthiness directives, EPA emissions filings, ECHA REACH substance restrictions, and customs trade data for titanium mill products. Bottom-up demand modeling across engine component, airframe, and landing gear applications triangulated with top-down macro aerospace production forecasts.
Variance decomposition across the projection horizon isolates demand drivers by alloy grade, manufacturing technology, and end-user procurement channel. Segmentation dimensions modeled include product type, production technology, application function, and end-user category, with regional regulatory clusters capturing FAA, EASA, and MIIT certification pathway differences. CAGRs derive from production schedule analysis at Boeing, Lockheed Martin, and COMAC assembly lines, cross-referenced with engine OEM part count expansion for next-generation propulsion programs.
Material uncertainties — defense appropriation cycle delays, REACH restriction scope expansion, and additive manufacturing qualification timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained commercial widebody delivery recovery and defense procurement acceleration. Revision becomes warranted when Russian sponge supply disruption crosses thresholds triggering emergency stockpile releases or alternative sourcing mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Europe Aerospace Composites Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerospace Titanium Market
Aerospace and Aircraft Materials
Global Aerospace Insulation Market
Aerospace and Aircraft Materials
Global Composite Materials Aluminum Alloys Aerospace Market
Aerospace and Aircraft Materials
Aerospace High-Performance Alloys Market
Aerospace and Aircraft Materials
Global Aerospace and Defense Elastomers Market
Aerospace and Aircraft Materials
Europe Advanced Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Thermal Spray Coating Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
3D Printing for Aerospace Market
Aerospace and Aircraft Materials
Advanced Materials for Flying Cars Market
Aerospace and Aircraft Materials
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market
Aerospace and Aircraft Materials
Global Aerospace Metal Closed-Die Forging Market