
 GCC UHT Milk Market | 2026-2036
GCC UHT Milk Market Size, Share, and Industry Trends Forecast 2026-2036
GCC UHT Milk Market Intelligence
Veterinary technician and dairy processing specialist shortages across the Arabian Peninsula is bifurcating production capacity between large integrated operators and smaller brands dependent on imported expertise. Almarai leverages captive fodder-to-shelf operations across Saudi Arabia to sustain margin control. FrieslandCampina anchors European formulation know-how through its Gulf distribution partnerships. Al Rawabi Dairy differentiates via Emirati-origin sourcing and shorter declared supply loops.
Ultra-high temperature milk undergoes heating at 135-150°C for 2-5 seconds before aseptic packaging, yielding ambient-stable dairy with six-to-nine-month shelf life without refrigeration until opening. This thermal process serves institutional buyers and export-dependent Gulf states where cold-chain gaps persist in last-mile distribution. Whole milk occupies the dominant volume position among product types due to cultural preference for full-fat dairy in Gulf diets, while flavored milk segments attract younger demographics and school nutrition programs. Aseptic cartons lead packaging type demand because of their stacking efficiency and print branding surface, though plastic bottles gain traction in convenience store channels.
Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology enforce compositional standards and labeling rules that determine which formulations qualify for domestic shelf placement. Gulf Standardization Organization harmonization efforts reduce cross-border formulation friction for multi-country operators like Lactalis and Nestlé. Stakeholders must monitor evolving Gulf nutrition labeling mandates and halal certification reciprocity agreements that will determine which production facilities qualify for regional supply contracts.
Market Dynamics
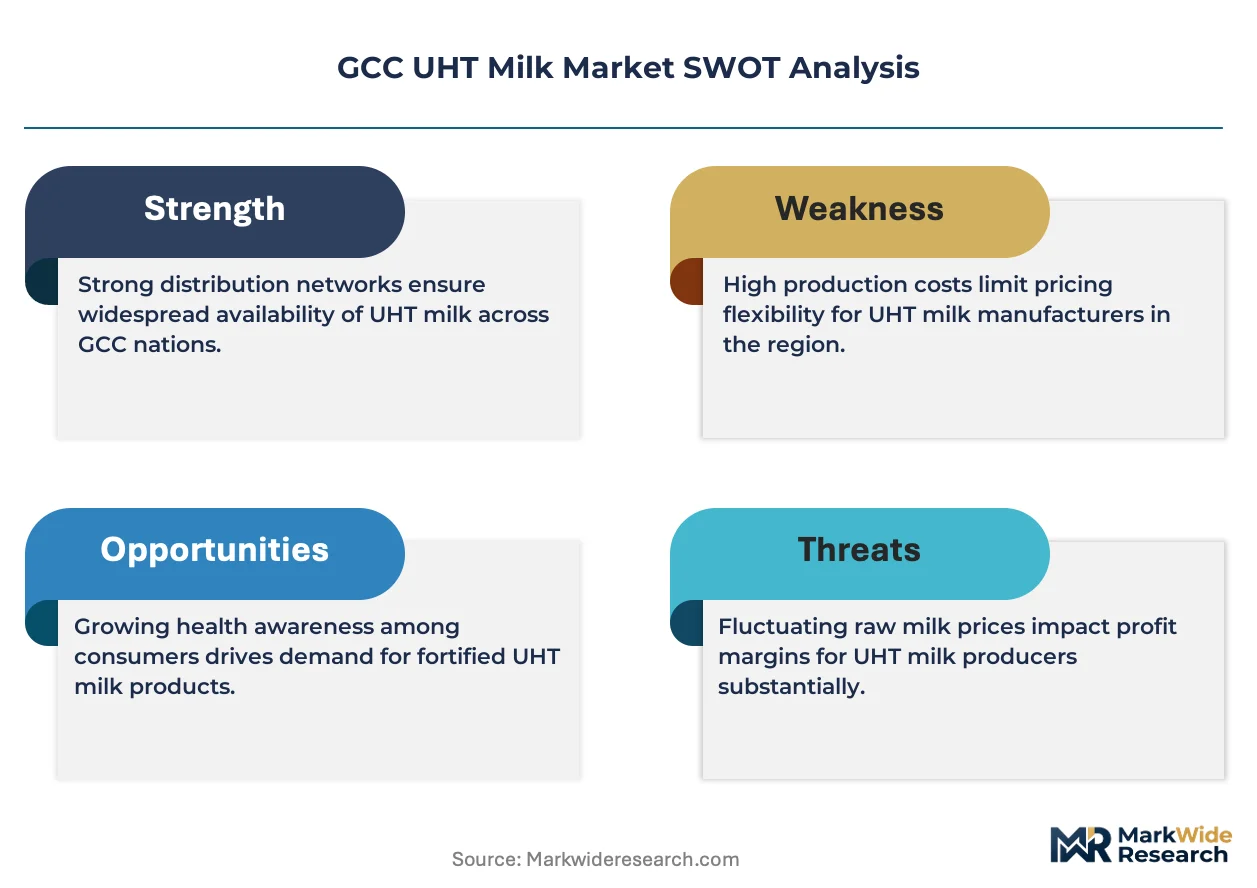
The Saudi Food and Drug Authority's tightening shelf-life labeling requirements are forcing reformulation investments across the GCC, concentrating production capacity among operators with captive technical expertise and compliant cold-chain infrastructure.
Growth Catalysts
- Tourism Infrastructure Expansion:Hospitality procurement teams across the Gulf are expanding refrigerated UHT inventory as Saudi Arabia and the UAE add hotel capacity. This institutional pull sustains volume growth independent of retail fluctuations.
- SFDA Harmonization Pressure:Saudi Food and Drug Authority rules on compositional standards are tightening, disqualifying marginal importers and clearing shelf space for compliant domestic and regional producers.
- ASEAN Export Pipeline:Aseptic packaging technology enables six-to-nine-month ambient stability, allowing Gulf producers to supply Southeast Asian markets where cold-chain gaps persist in last-mile distribution.
Market Restraints
- Veterinary Technician Scarcity:Dairy processing specialist shortages across the Arabian Peninsula constrain herd health management and milk quality consistency, particularly for smaller operators dependent on imported expertise.
- Fodder Import Dependence:Saudi Arabia and the UAE rely on imported alfalfa and feed grains, exposing margins to Red Sea shipping disruptions and currency fluctuation against dollar-denominated commodity contracts.
- Fresh Milk Substitution:Cold-chain improvements in Riyadh and Jeddah enable chilled dairy distribution, eroding UHT's traditional advantage in premium retail segments where taste preference dominates.
Strategic Opportunities
- Oman and Bahrain Underpenetration:Cold-chain retail density in Muscat and Manama lags the Riyadh-Jeddah corridor, creating first-mover positioning for aseptic carton distribution networks.
- School Nutrition Mandates:UAE and Saudi government school feeding programs are expanding flavored milk procurement specifications, opening institutional volume contracts with multi-year tenors.
- Halal Certification Reciprocity:Gulf Standardization Organization harmonization efforts are reducing cross-border formulation friction, enabling single-facility supply to multiple GCC markets under unified halal standards.
Industry Challenges
- Aseptic Packaging Technician Shortage:Gulf universities produce few graduates trained in ultra-high temperature system maintenance, forcing operators to recruit from South Asian technical institutes at premium compensation.
- Emirates Authority for Standardization Compliance Timelines:New labeling mandates require six-to-twelve-month reformulation and retesting cycles, freezing product line extensions during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC UHT Milk Market |
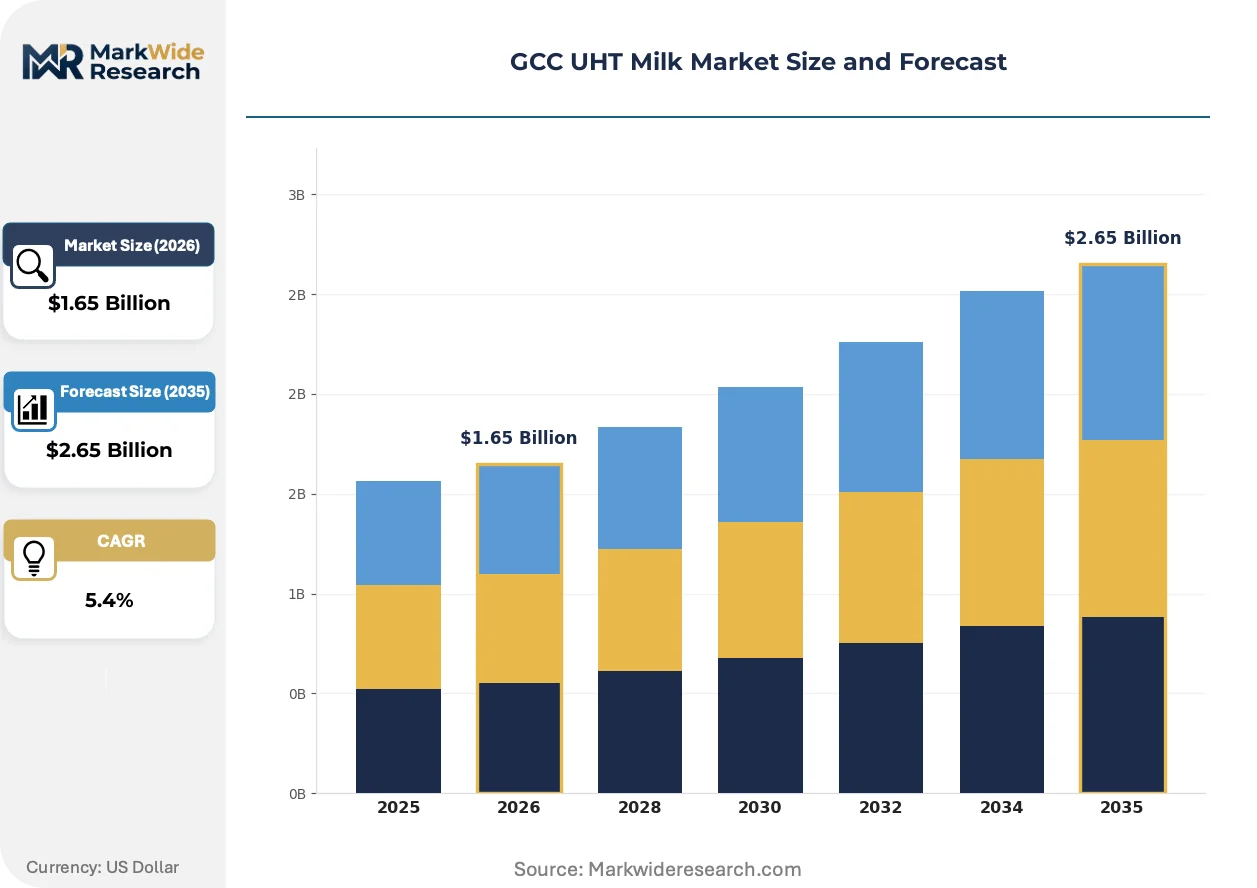
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Milk, Skim Milk, Flavored Milk, Semi-Skimmed Milk Packaging Type: Aseptic Cartons, Plastic Bottles, Plastic Pouches, Tetra Packs Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Wholesalers End User: Households, Cafes, Restaurants, Institutional Buyers |
| Companies Covered | Al Ain Dairy, Al Rawabi Dairy, Almarai, Nestlé, FrieslandCampina, SADAFCO, NADEC, Lactalis, Al Safi Danone, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC UHT Milk Market Strategic Shifts & Innovations
Processing technology and packaging formats are compressing traditional competitive advantages in the GCC UHT milk sector, with regulatory pressure and procurement centralization accelerating adoption curves.
Extended-shelf-life processing is decomposing the historical trade-off between ambient distribution reach and taste quality. Ultra-high temperature systems now integrate direct steam injection and vacuum cooling stages that reduce cooked-flavor formation. Saudi integrated operators are retrofitting Riyadh facilities with these systems to supply premium hotel and airline contracts. The technology is decomposing margin premiums previously captured by chilled dairy imports in Gulf urban centers.
SFDA and Emirates Authority for Standardization and Metrology are converging on front-of-pack nutrition labeling mandates that disclose added sugar content and fat percentages. This regulatory alignment forces reformulation of flavored milk lines targeting school nutrition programs. Manufacturers serving both Saudi Arabia and UAE markets are consolidating SKUs to reduce compliance fragmentation, compressing portfolio complexity for multi-country operators.
Institutional procurement centralization is consolidating buyer power across Gulf hospitality and education sectors. Hotel chains and school districts are shifting from distributor-mediated purchasing to direct manufacturer contracts with volume commitments and specification control. This channel compression is most visible in Dubai and Abu Dhabi, where government-backed procurement platforms aggregate demand from hundreds of individual institutions into tender packages that favor large-scale compliant suppliers.
GCC UHT Milk Market Segmentation
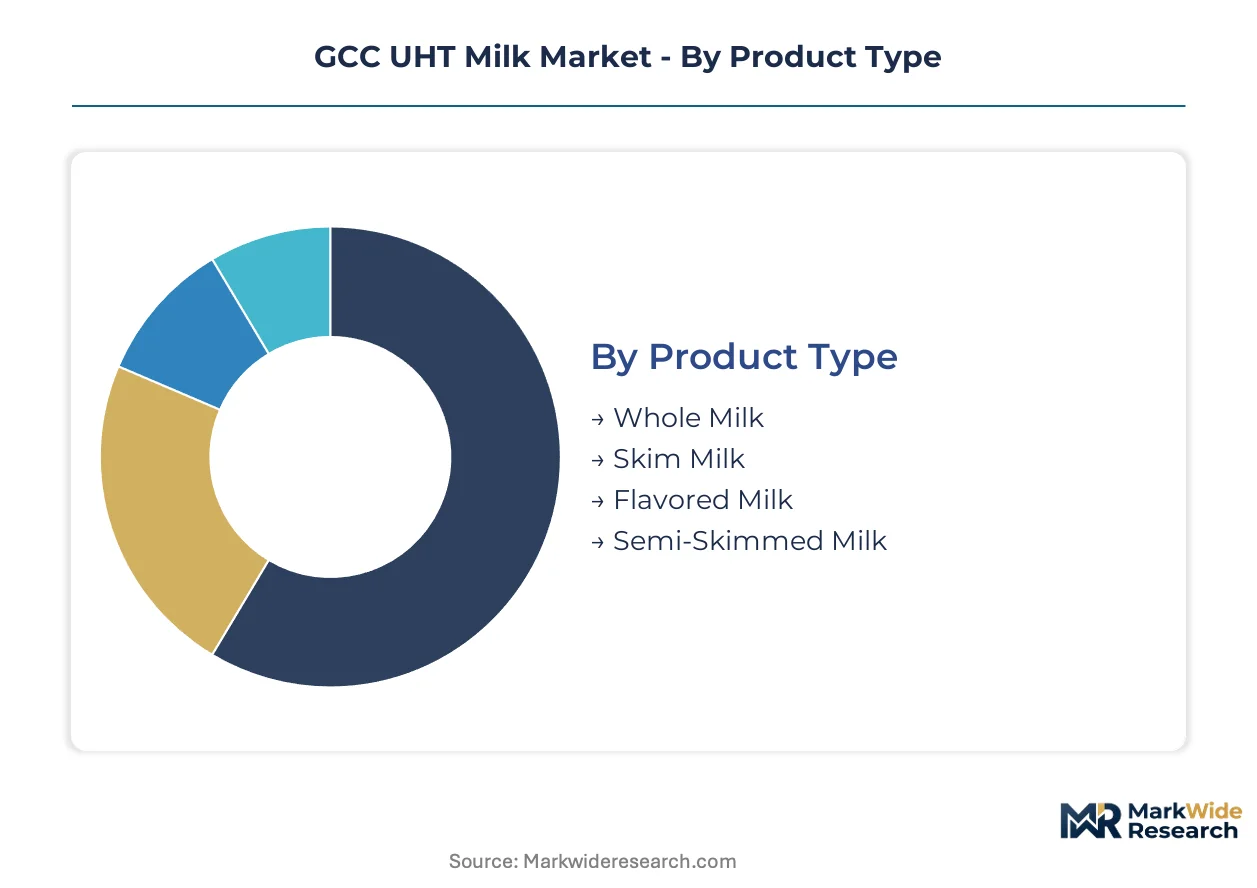
UHT milk segmentation in the GCC reveals divergent growth vectors between domestic consumption corridors and export-facing production. Understanding these splits allows operators to align formulation investments with channel-specific shelf-life and packaging requirements.
Product Type:
Domestic Gulf consumption gravitates toward full-fat formulations, while export-oriented production emphasizes lighter variants for Southeast Asian markets with different nutritional positioning.
- Whole Milk:Full-fat UHT dominates Saudi and UAE retail shelves due to cultural preference for creamy taste profiles in traditional coffee preparation. Riyadh-Jeddah corridor supermarkets stock this variant at triple the rate of reduced-fat alternatives, with hospitality procurement teams specifying it for hotel breakfast service.
- Flavored Milk:Chocolate and strawberry formulations are expanding through UAE and Saudi school nutrition programs, where government tenders specify vitamin-fortified, reduced-sugar recipes. Dubai's institutional procurement platforms aggregate multi-year supply contracts that favor compliant regional producers.
- Skim Milk:Health-conscious urban consumers in Abu Dhabi and Doha drive modest demand for zero-fat UHT in premium supermarket channels.
- Semi-Skimmed Milk:Mid-fat positioning attracts fitness-oriented demographics in Kuwait City gyms and wellness retail.
Whole milk commands the established base. The steepest expansion runs through flavored milk.
Packaging Type:
Cost tier differentiation separates premium hospitality supply from mass retail, with aseptic technology investments concentrating among integrated operators serving institutional buyers.
- Aseptic Cartons:Laminated paperboard with aluminum foil barriers enables six-to-nine-month ambient stability for export shipments to ASEAN markets lacking cold-chain infrastructure. Saudi integrated producers retrofit Riyadh facilities with direct steam injection systems to supply premium hotel and airline contracts through this format.
- Plastic Bottles:HDPE and PET formats gain traction in UAE convenience store channels where grab-and-go consumption dominates. Dubai petrol station retail chains specify 250ml and 500ml bottles with resealable caps for commuter traffic.
- Tetra Packs:Standard rectangular cartons serve price-sensitive household bulk purchasing in Saudi hypermarkets.
- Plastic Pouches:Flexible film packaging reduces unit costs for wholesale distribution to remote Omani and Bahraini retail with limited refrigerated display.
Aseptic cartons anchor export revenue. Plastic bottles are climbing the fastest in convenience channel penetration.
Distribution Channel:
Customer type fragmentation splits between centralized institutional procurement and fragmented retail, with channel compression favoring direct manufacturer relationships.
- Supermarkets:Saudi Arabia's Panda and UAE's Lulu Hypermarket chains dominate volume, deploying private-label UHT programs that pressure branded margins through shelf-space negotiations.
- Wholesalers:Traditional distribution networks serve smaller Omani and Bahraini retailers with bulk pallet sales and extended payment terms.
- Convenience Stores:24-hour urban outlets in Dubai Marina and Jeddah's Tahlia Street emphasize single-serve chilled UHT for immediate consumption.
- Online Retailers:Saudi e-commerce platforms and UAE grocery delivery apps are expanding subscription-based UHT replenishment for household bulk buyers.
Supermarkets retain the volume base. Online retailers show the steepest expansion trajectory.
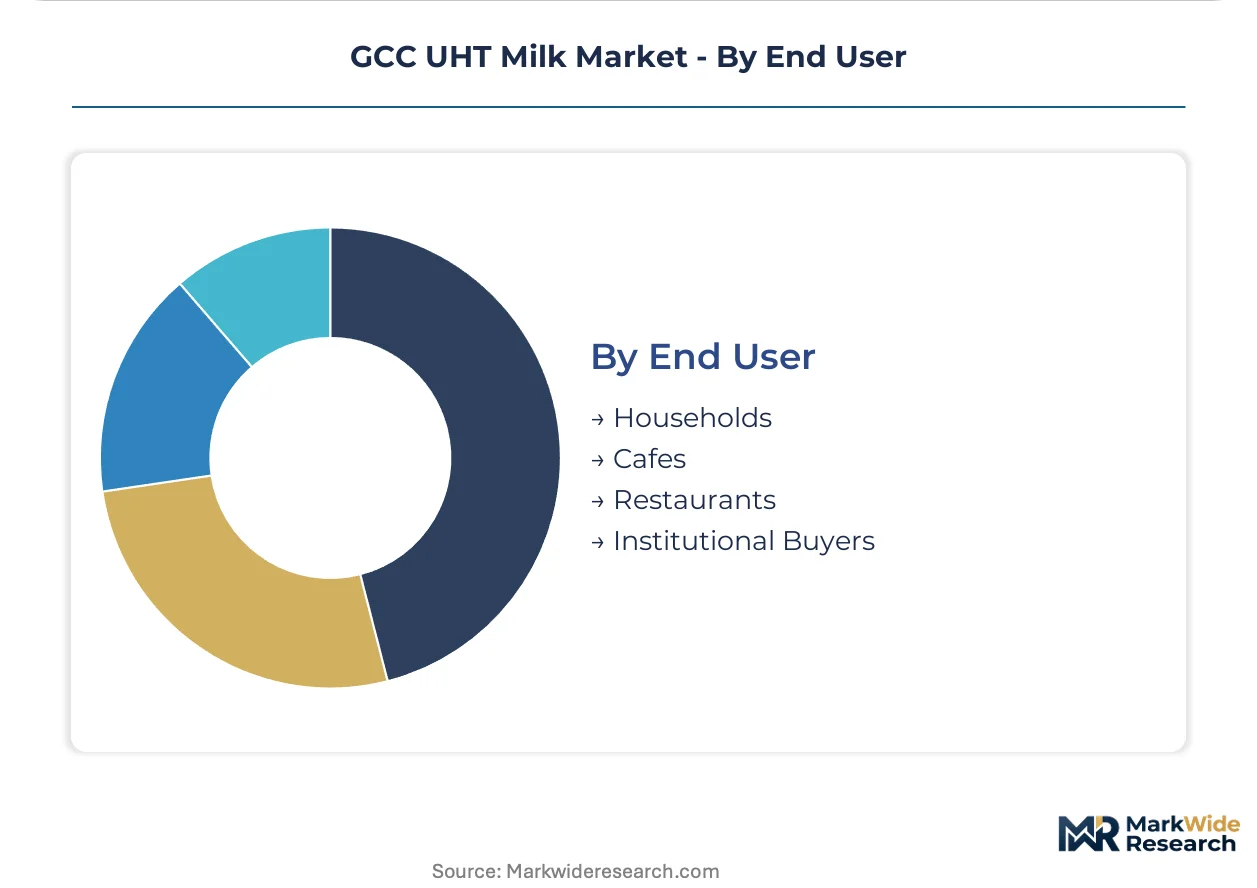
End User:
Application concentration varies sharply between stable household consumption and cyclical hospitality demand tied to Saudi tourism capacity expansion.
- Households:Family bulk purchasing of one-liter cartons sustains baseline production scheduling for Saudi and UAE dairy processors.
- Institutional Buyers:Government school feeding programs in Dubai and Riyadh specify flavored milk with halal certification and front-of-pack sugar disclosure.
- Restaurants:Casual dining chains in Jeddah's food courts require ambient-stable UHT for coffee and dessert preparation where refrigeration space is constrained.
- Cafes:Specialty coffee culture in Abu Dhabi and Doha creates niche demand for barista-grade UHT with specific fat content for foam stability.
Households anchor predictable demand. Institutional buyers are gaining share fastest through tender centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA shelf-life labeling mandates concentrate reformulation investments in Saudi Arabia, while UAE hospitality procurement platforms aggregate institutional demand across Dubai and Abu Dhabi. Cold-chain retail density gaps in Oman and Bahrain create positioning opportunities for aseptic distribution networks.
Saudi Arabia
Tourism capacity expansion in Riyadh and Jeddah drives hospitality procurement teams to expand refrigerated UHT inventory for hotel breakfast service. SFDA compositional standards and tightening shelf-life rules disqualify marginal importers, clearing shelf space for compliant domestic producers. The Riyadh-Jeddah corridor exhibits cold-chain retail density exceeding other Gulf states, with supermarkets stocking whole milk variants at triple the rate of reduced-fat alternatives.
United Arab Emirates
Dubai's government-backed procurement platforms aggregate demand from hundreds of institutions into tender packages favoring large-scale compliant suppliers. Emirates Authority for Standardization and Metrology front-of-pack nutrition labeling mandates force reformulation of flavored milk lines targeting school nutrition programs. Abu Dhabi's specialty coffee culture creates niche demand for barista-grade UHT with specific fat content for foam stability in premium cafe channels.
Oman
Cold-chain retail density in Muscat lags the Riyadh-Jeddah corridor, preserving UHT's ambient distribution advantage in last-mile segments. The country's national food safety regulator enforces halal certification standards that determine import eligibility for regional supply contracts. Wholesale distribution networks serve smaller retailers with bulk pallet sales and extended payment terms, favoring flexible film packaging formats.
Bahrain
Manama's underpenetrated retail infrastructure creates first-mover positioning for aseptic carton distribution networks targeting convenience store channels. Government school feeding programs specify vitamin-fortified, reduced-sugar flavored milk recipes in multi-year supply contracts. Traditional distribution relationships dominate procurement, with limited penetration of centralized institutional purchasing platforms seen in Dubai.
Kuwait
Fitness-oriented demographics in Kuwait City gyms and wellness retail drive modest demand for semi-skimmed and zero-fat UHT variants. The national standards body aligns with Gulf Standardization Organization harmonization efforts to reduce cross-border formulation friction for multi-country operators. Wholesalers maintain extended payment terms with smaller retailers, preserving cash-flow advantages for established distribution relationships.
GCC UHT Milk Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with production capacity bifurcating between operators with captive technical expertise and smaller brands dependent on imported veterinary and processing specialists. Saudi integrated operators leverage backward integration into captive fodder operations to sustain margin control against feed import volatility. European multinationals anchor formulation know-how through Gulf distribution partnerships. Dominant competitive moves include direct procurement platform relationships with hospitality and education sectors, and retrofit investments in direct steam injection systems for premium contract supply.
Within the integrated domestic tier, Almarai and Al Rawabi Dairy exemplify operators with Emirati and Saudi-origin sourcing strategies and shorter declared supply loops. Among European-based multinationals, FrieslandCampina and Lactalis occupy positions leveraging continental formulation expertise through regional distribution structures. Nestlé represents the diversified nutrition conglomerate archetype, sitting within portfolios where UHT milk serves institutional and retail channels as part of broader dairy category positioning.
| Leading Market Players |
|---|
| Al Ain Dairy |
| Al Rawabi Dairy |
| Almarai |
| Nestlé |
| FrieslandCampina |
| SADAFCO |
| NADEC |
| Lactalis |
| Al Safi Danone |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day fodder inventory buffers in Saudi integrated operations compress feed cost pass-through lag and anchor pricing power against Red Sea shipping volatility. This lead-time structure concentrates margin control among operators with captive alfalfa cultivation while exposing smaller brands to dollar-denominated commodity contract swings.
Pricing Analysis
Price spreads between Riyadh-Jeddah corridor supermarkets and Muscat wholesale channels reflect cold-chain density differentials rather than formulation quality. Three-tier pricing structure across premium hospitality, standard retail, and economy bulk segments stratifies by certification grade and volume commitment scale. Pricing pressure stems from private-label expansion at Panda and Lulu Hypermarket chains, compressing branded margins through shelf-space negotiations. Institutional buyers in Dubai procurement platforms exhibit lowest price sensitivity due to multi-year tender structures, while Omani wholesalers face highest sensitivity given extended payment terms and cash-flow constraints.
Supply Chain Analysis
Forty-five-day aseptic packaging material inventories in Saudi facilities buffer against European laminate supplier lead-time variability. Production concentrates in Saudi Arabia and the UAE, with backward integration into captive fodder operations in Al-Kharj and Al-Ain. Raw material dependencies include imported alfalfa from Argentina, feed grains from Black Sea origins, and aluminum foil barrier laminates from European converters. Single-source vulnerability runs through Red Sea shipping lanes for fodder imports. Distribution feeds from integrated dairy processors through government procurement platforms and traditional wholesale networks serving smaller Bahraini and Omani retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC UHT milk sits in early-cycle expansion as tourism capacity builds institutional procurement pipelines ahead of retail saturation. School nutrition mandates and hospitality inventory expansion create adoption tailwinds independent of household consumption fluctuations.
For Market Incumbents: Secure direct procurement platform relationships with Dubai and Riyadh government-backed tender aggregators to lock multi-year volume commitments before competitor retrofit investments reach scale. Deepen backward integration into captive fodder cultivation to buffer margin pressure from Red Sea shipping disruptions and dollar-denominated commodity volatility. SFDA shelf-life labeling compliance investments now separate sustainable operators from marginal importers facing disqualification. For New Entrants and Emerging Players: Differentiate on halal certification reciprocity and shorter declared supply loops targeting Bahrain and Oman where centralized procurement platforms remain underdeveloped. Muscat and Manama retail infrastructure gaps offer first-mover positioning for aseptic carton distribution networks before incumbent channel consolidation reaches these markets. Lead with flexible film packaging formats suited to wholesale distribution relationships dominant in these geographies. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because veterinary technician and dairy processing specialist shortages are bifurcating production capacity toward integrated operators with captive technical expertise. Target acquisition archetypes include Saudi and UAE mid-cap dairies with SFDA-compliant facilities and established fodder supply relationships. The signal to watch is Emirates Authority for Standardization and Metrology labeling mandate implementation timelines, which will freeze product line extensions and create distressed repositioning opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Steam Injection Retrofit | Riyadh facility upgrades enable premium hotel and airline contract supply through improved taste profiles. |
| Government Procurement Platform Registration | Dubai and Abu Dhabi tender aggregation favors large-scale compliant suppliers with multi-year volume commitments. |
| Halal Certification Reciprocity Investment | Gulf Standardization Organization harmonization reduces cross-border formulation friction for multi-country operators. |
| Captive Fodder Cultivation Expansion | Al-Kharj and Al-Ain backward integration buffers margin pressure from Red Sea shipping disruptions. |
| Flavored Milk Reformulation | SFDA and Emirates Authority front-of-pack sugar disclosure mandates force SKU consolidation for school nutrition program eligibility. |
Research Approach
Initial hypotheses were tested against primary input from dairy processing operations managers, hospitality procurement directors, veterinary health specialists, and SFDA regulatory affairs leads and refined through secondary validation. Primary fieldwork combined structured interviews across Saudi Arabia, UAE, Oman, and Bahrain with trade data from customs records and Gulf Standardization Organization harmonization documentation. Secondary sources included SFDA compositional standard filings, Emirates Authority for Standardization and Metrology labeling mandates, and hospitality sector procurement platform disclosures. Bottom-up volume estimates from facility-level production data triangulated against top-down demand aggregation from retail audit channels.
Variance decomposition across product type, packaging format, distribution channel, and end-user application segments anchored the analytical framework. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers including tourism capacity expansion and school nutrition program procurement volumes. Modeled inputs included cold-chain retail density indices, aseptic packaging technology adoption curves, and halal certification reciprocity agreement implementation timelines.
Forecasts assume regulatory continuity in SFDA and Emirates Authority for Standardization and Metrology regimes; material policy shifts would require re-modeling of reformulation investment cycles and import eligibility criteria. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Germany Dairy Market
Dairy Products
Reduced Fat Dairy Market
Dairy Products
Global Fresh Milk Market
Dairy Products
Fermented Milk Products Market
Dairy Products
Table Butter Market
Dairy Products
Asia-Pacific Cow Milk Minerals Market
Dairy Products
Buttermilk Powder Market
Dairy Products
Cheese Shreds Market
Dairy Products
Argentina Whey Protein Market
Dairy Products
Europe Drinkable Yogurt Market
Dairy Products
Dairy Products Market
Dairy Products
North America Fluid Milk Market
Dairy Products
Europe Milk Protein Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Soluble Milk Protein Market
Dairy Products
Fat-Filled Milk Powder Market