
 3LCD Projector Market | 2026-2036
3LCD Projector Market Size, Share, and Industry Trends Forecast 2026-2036
3LCD Projector Market Insights
Buyer concentration in the 3LCD projector space is broadening as K-12 districts and higher-education consortia consolidate procurement through cooperative purchasing agreements while corporate AV buyers fragment across hybrid-work satellite offices. Seiko Epson Corporation leverages its in-house LCD panel fabrication to control cost structures across portable and high-end projector lines. Sony Corporation differentiates through native 4K SXRD integration within its 3LCD architecture for premium home theater and event management deployments. Panasonic Holdings Corporation anchors professional installation markets with ruggedized chassis designs targeting ceiling-mount and outdoor configurations.
A 3LCD projector employs three individual liquid-crystal display panels—one each for red, green, and blue light paths—with a dichroic prism combining modulated wavelengths into a single full-color image projected through precision optics, typically achieving color brightness equal to white brightness measured in lumens. The technology serves commercial and industrial purposes spanning digital classrooms, boardroom presentations, immersive entertainment venues, and large-scale mapped projections where color accuracy and brightness uniformity outweigh single-chip DLP alternatives. Ultra-short throw installations lead volume growth as educators and corporate buyers eliminate shadow interference and reduce cabling complexity in constrained spaces. Laser-hybrid technology within the technology segment commands expanding margin pools as buyers prioritize twenty-thousand-hour maintenance-free operation over lamp replacement cycles. Portable projectors sustain steady replacement demand from mobile presenters and small-venue event management operators prioritizing transportability over lumen output.
The US Environmental Protection Agency regulates lamp disposal through universal waste rules affecting institutional buyers with large projector fleets, while the EU RoHS directive restricts hazardous substances in LCD panel manufacturing and REACH governs chemical transparency across projector supply chains. China's GB standards for electronic product energy efficiency and the EU Ecodesign requirements for standby power collectively push manufacturers toward laser and LED illumination architectures that minimize thermal load and power draw. Stakeholders must monitor how regional efficiency mandates and extended producer responsibility frameworks reshape component sourcing decisions and aftermarket service obligations across divergent regulatory jurisdictions.
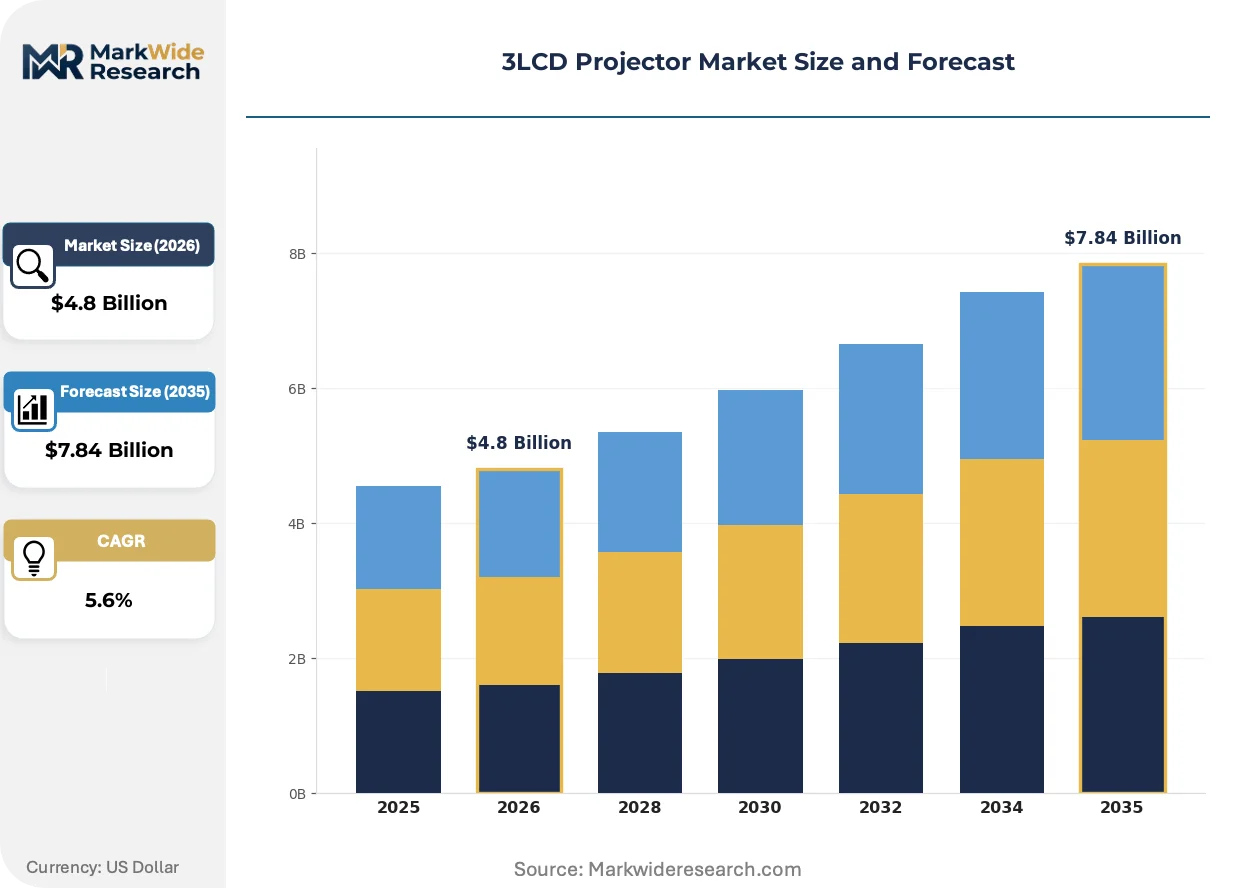
Market Dynamics
Laser-hybrid illumination is compressing replacement cycles across institutional projector fleets as buyers prioritize total cost of ownership over upfront capital expenditure in procurement decisions.
Growth Catalysts
- EU Ecodesign standby power mandates:Regulatory pressure from Brussels accelerates laser and LED adoption by penalizing thermal-heavy lamp architectures in institutional tenders.
- K-12 cooperative purchasing agreements:Education consortia in the United States consolidate volume procurement, expanding addressable unit sales for standardized classroom installations.
- Ultra-short throw optics:Shadow elimination in constrained Chinese classrooms and Japanese corporate huddle rooms drives specification upgrades during AV refresh cycles.
Market Restraints
- Phosphor wheel and laser diode supply concentration:Japanese and German component suppliers control critical subsystems, creating input bottlenecks during demand surges.
- Single-chip DLP substitution in price-sensitive segments:Texas Instruments' DLP technology captures portable and entry-level volume where color brightness parity matters less.
- Extended producer responsibility frameworks:EU WEEE directives impose end-of-life collection costs on manufacturers, compressing margins in economy-tier product lines.
Strategic Opportunities
- Immersive entertainment venue expansion:Projection mapping applications in Middle Eastern cultural districts and Southeast Asian theme parks create premium installation demand for high-lumen 3LCD chassis.
- India's digital classroom mandates:State-level education technology procurement programs under the country's National Education Policy drive volume opportunity in tier-2 and tier-3 cities.
- Cloud-based fleet management convergence:Integration of projector diagnostics with enterprise IT monitoring platforms enables recurring service revenue from corporate AV deployments.
Industry Challenges
- Optical engine calibration expertise shortage:Precision alignment of dichroic prisms and LCD panels requires specialized technicians, constraining service network expansion.
- Laser safety certification timelines:IEC 60825-1 compliance documentation delays product launches in regulated European and North American institutional channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3LCD Projector Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Projectors, Ultra-short Throw, Standard Projectors, High-end Projectors End User: Education, Corporate, Home Theater, Event Management Technology: LCD, LED, Laser, Hybrid Installation: Ceiling Mount, Wall Mount, Tabletop, Outdoor |
| Companies Covered | Seiko Epson Corporation, Sony Corporation, Panasonic Holdings Corporation, BenQ Corporation, Barco NV, Christie Digital Systems, Optoma Corporation, ViewSonic Corporation, LG Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3LCD Projector Market Trends and Innovations
Active reshaping of the 3LCD projector market centers on solid-state illumination architectures, regulatory efficiency mandates, and procurement consolidation patterns that favor lifecycle economics over initial acquisition cost.
Laser-phosphor hybrid engines are electrifying the transition from mercury lamp systems by delivering twenty-thousand-hour maintenance-free operation. Corporate AV managers in Germany and Japan specify these architectures for ceiling-mounted boardroom installations where access costs exceed hardware replacement. The technology is electrifying margin pools as manufacturers capture value through extended warranty and service contract bundling rather than consumables revenue.
China's GB standards for electronic product energy efficiency impose escalating standby power limits that lamp-based projectors cannot satisfy. Manufacturers reconfigure supply chains toward laser and LED illumination to maintain market access. Domestic Chinese brands and multinational suppliers alike accelerate R&D allocation to thermal management systems that minimize power draw during operation.
Enterprise buyers increasingly unbundle after-sales service from hardware procurement, negotiating direct relationships with regional AV integrators for maintenance and lamp replacement. This pattern disrupts traditional OEM service attach rates and shifts margin capture toward installation specialists. The behavior is most visible in United States higher-education consortia and German municipal government purchasing frameworks.
3LCD Projector Market Segmentation
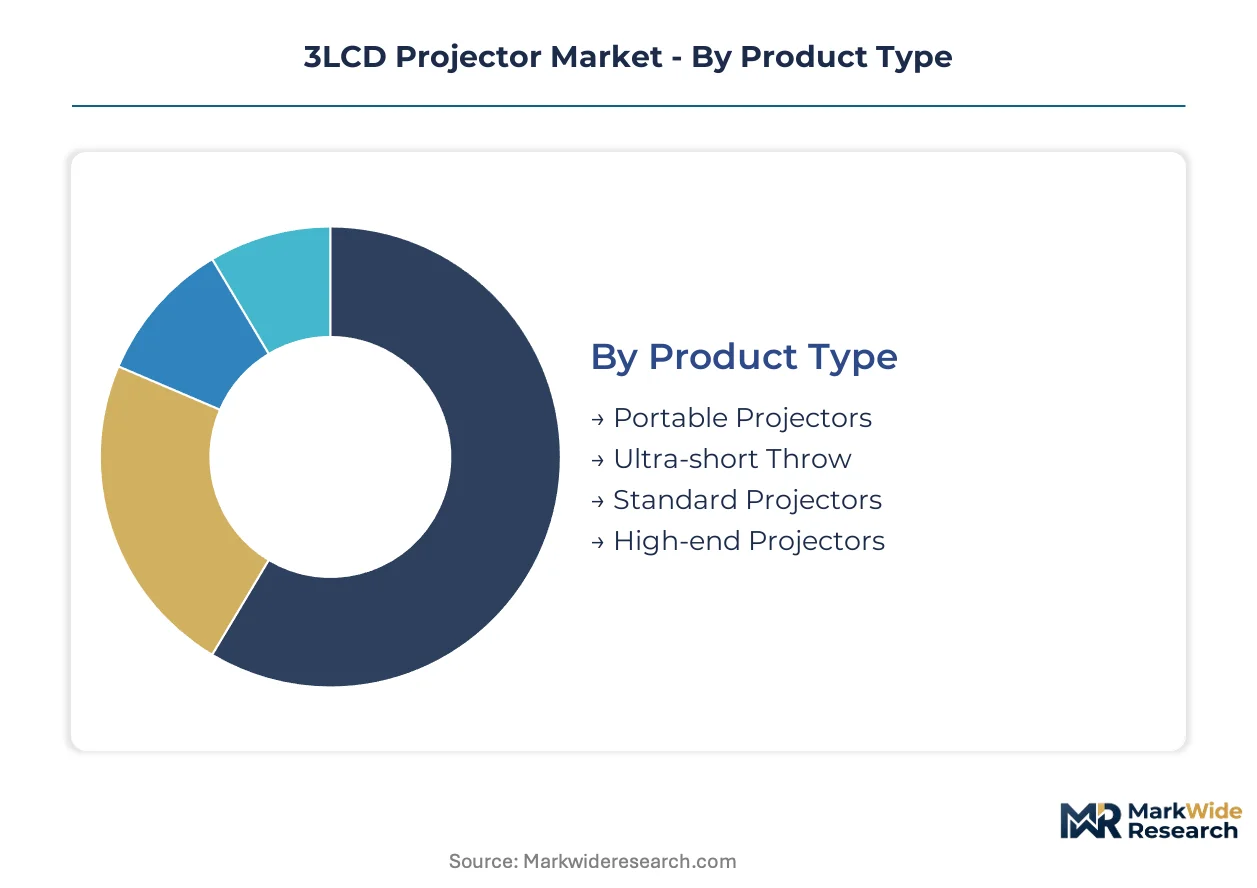
3LCD projector segmentation reveals how illumination architecture and mounting configuration reshape procurement economics across education, corporate, and entertainment verticals. Distinct performance tiers align with divergent total-cost-of-ownership calculations and infrastructure constraints.
Product Type:
Standalone portable units serve mobile presenters without fixed infrastructure, while embedded ultra-short throw and ceiling-mounted systems demand permanent installation and calibration expertise.
- Ultra-short Throw:Projection distances below 0.4:1 throw ratio eliminate presenter shadow interference in constrained Chinese classrooms and Japanese corporate huddle rooms. Educators in tier-2 Indian cities specify these units during digital classroom mandates to avoid costly ceiling reinforcement. Demand concentrates in K-12 refreshes where cabling minimization outweighs per-lumen premiums.
- Portable Projectors:Compact chassis designs under 3kg prioritize transportability over lumen output for mobile sales teams and small-venue event operators. Corporate procurement in Germany and the United States treats these as consumable refresh items rather than capital assets. Battery-powered variants gain specification in outdoor event management where power access is unreliable.
- Standard Projectors:Mid-lumen installations dominate legacy replacement cycles in institutional fleets across mature markets.
- High-end Projectors:Native 4K resolution and expanded color gamut target premium home theater and large-venue immersive entertainment in Middle Eastern cultural districts.
Volume placements concentrate in Standard Projectors; the faster expansion belongs to Ultra-short Throw.
End User:
Customer type determines specification rigor, with institutional buyers prioritizing lifecycle economics and consumer segments emphasizing peak performance metrics.
- Education:K-12 districts and higher-education consortia consolidate procurement through cooperative purchasing agreements in the United States, while India's National Education Policy drives state-level tenders. Laser-hybrid architectures displace lamp systems as twenty-thousand-hour maintenance-free operation reduces facilities staffing burdens. China's GB energy efficiency standards disqualify thermal-heavy alternatives from institutional tenders.
- Corporate:AV refresh cycles in Germany and Japan converge on laser-illuminated ceiling mounts where access costs exceed hardware replacement. Hybrid-work satellite offices fragment procurement authority, complicating volume negotiations for OEMs. Cloud-based fleet management integration emerges as a service differentiator in enterprise accounts.
- Home Theater:Enthusiast buyers prioritize native 4K SXRD integration and expanded color accuracy for dedicated screening rooms.
- Event Management:Rental fleet operators balance lumen density against transportability for temporary installations in Southeast Asian theme parks.
Procurement volume clusters in Education; Corporate exhibits the steepest expansion trajectory as hybrid work normalizes distributed AV infrastructure.
Technology:
Illumination source determines thermal load, maintenance cadence, and regulatory compliance across divergent efficiency mandates.
- Laser:Solid-state diode arrays with phosphor wheel conversion deliver consistent brightness degradation curves and eliminate lamp inventory logistics. EU Ecodesign standby power mandates accelerate displacement of thermal-heavy alternatives in institutional channels. Japanese and German component suppliers control critical diode and phosphor subsystems, creating input concentration risk.
- Hybrid:Laser-phosphor engines with LED augmentation optimize color balance for premium cinema and simulation applications. Corporate AV managers in ceiling-mount installations specify these architectures where access costs dominate total ownership calculations. Extended warranty bundling captures margin pools formerly attached to consumables revenue.
- LED:Compact thermal footprint suits portable and battery-powered configurations with modest lumen requirements.
- LCD:Traditional lamp-based systems retreat to price-sensitive replacement cycles in emerging market education tenders.
Unit shipments favor Hybrid configurations; pure Laser architectures gain share fastest as efficiency mandates tighten.
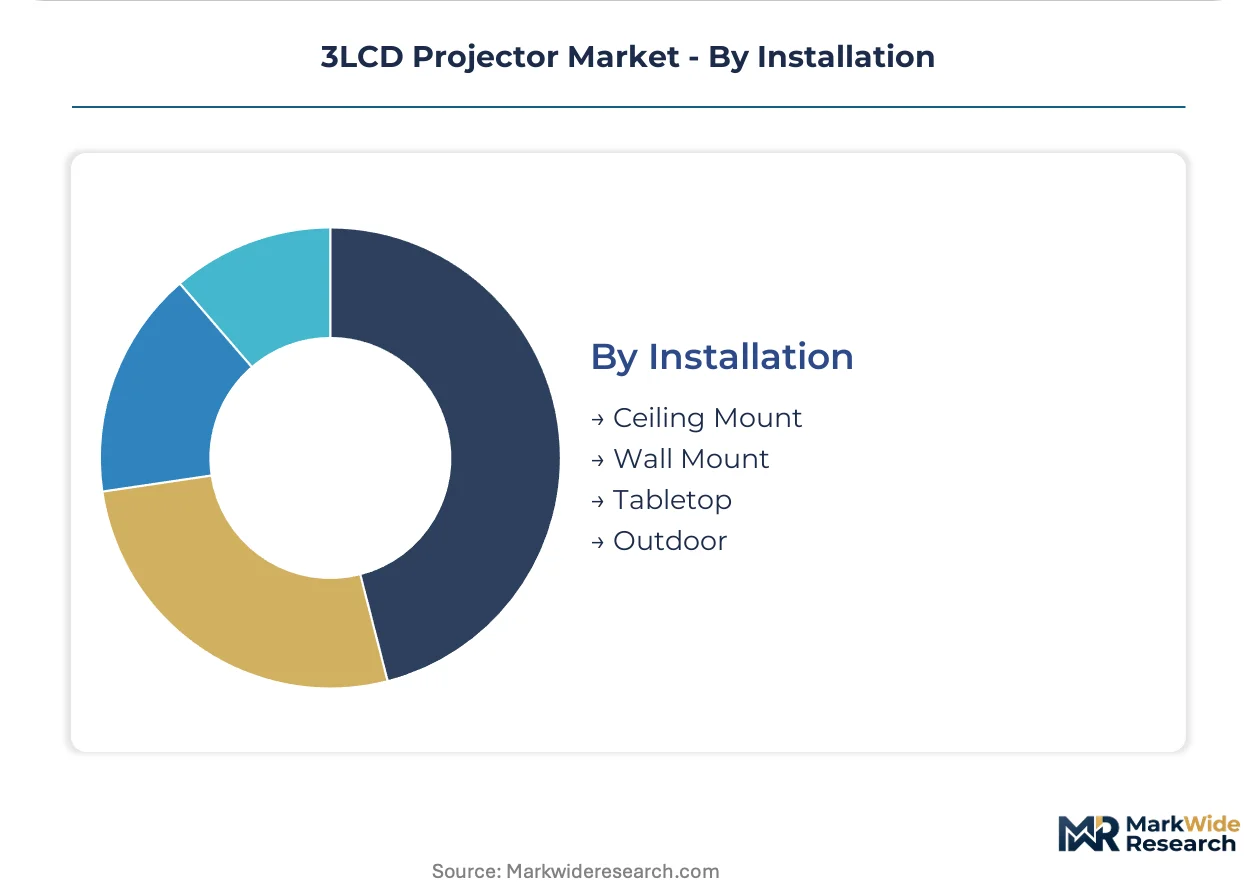
Installation:
Mounting configuration dictates optical calibration complexity and service network requirements, with permanent installations demanding specialized technician deployment.
- Ceiling Mount:Permanent infrastructure in German boardrooms and Japanese corporate facilities requires ruggedized chassis designs and vibration-resistant optical engines. Panasonic Holdings anchors this specification with professional installation support networks. Extended producer responsibility frameworks under EU WEEE directives impose end-of-life collection costs on manufacturers.
- Tabletop:Flexible deployment suits hybrid-work satellite offices and temporary meeting configurations without structural modification. Procurement fragments across departmental budgets, complicating OEM volume negotiations. Transportability prioritization limits lumen density relative to fixed installations.
- Wall Mount:Ultra-short throw compatibility enables shadow-free projection in constrained Chinese classroom dimensions.
- Outdoor:Weatherized chassis and enhanced thermal management target mapped projection applications in Middle Eastern cultural districts and Southeast Asian entertainment venues.
Deployment volume centers on Ceiling Mount; Wall Mount configurations are expanding most quickly as ultra-short throw optics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, Japan, and Germany concentrate procurement volume as digital classroom mandates and corporate AV refresh cycles converge, while India's state-level education tenders and US cooperative purchasing agreements broaden buyer concentration across institutional segments.
China
GB standards for electronic product energy efficiency impose escalating standby power limits that disqualify thermal-heavy lamp architectures from institutional tenders. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate laser-illuminated specifications in government procurement. Yangtze River Delta manufacturing clusters supply optical engines and thermal management subsystems to domestic and multinational projector brands.
Japan
METI efficiency regulations and corporate huddle room densification drive ultra-short throw installations in Tokyo and Osaka commercial districts. JIS standards govern display device performance metrics that influence specification sheets across Asia-Pacific tenders. Chubu/Nagoya industrial corridors host precision optics fabricators and phosphor wheel component suppliers serving laser-hybrid engine production.
Germany
EU Ecodesign standby power mandates and extended producer responsibility frameworks under WEEE directives reshape procurement economics for municipal government and corporate buyers. KBA-adjacent industrial safety protocols influence ceiling-mount installation standards in manufacturing facility deployments. Bavaria and North Rhine-Westphalia anchor professional AV integrator networks serving boardroom and cultural venue installations.
United States
K-12 cooperative purchasing agreements consolidate volume procurement through education consortia, expanding addressable unit sales for standardized classroom configurations. EPA universal waste rules regulate lamp disposal across institutional fleets with large projector deployments. Texas and California school districts lead refresh cycles as ESSER funding absorption extends into AV infrastructure upgrades.
India
State-level education technology procurement programs under the National Education Policy drive volume opportunity in tier-2 and tier-3 cities where digital classroom mandates outpace infrastructure readiness. BIS certification requirements for electronic imports filter supplier participation in government tenders. Maharashtra and Karnataka urban clusters concentrate system integrator capacity for installation and maintenance service delivery.
3LCD Projector Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent solid-state illumination and cloud-connected fleet management services. The vendor base stratifies across three archetypes: vertically integrated LCD panel fabricators controlling upstream component costs, optical engine specialists licensing core technology to downstream brands, and systems integrators bundling hardware with installation and maintenance contracts. Competitive positioning hardens around laser-phosphor engine reliability claims and extended warranty bundling that captures margin pools formerly attached to consumables revenue.
Within the integrated-manufacturing tier, Seiko Epson Corporation and Sony Corporation anchor contrasting positioning vectors—Epson through captive LCD panel production and Sony through native 4K SXRD integration—while Panasonic Holdings Corporation exemplifies the professional-installation archetype with ruggedized chassis targeting ceiling-mount and outdoor configurations. Each represents a distinct approach to margin defense as lamp-based revenue streams erode.
| Leading Market Players |
|---|
| Seiko Epson Corporation |
| Sony Corporation |
| Panasonic Holdings Corporation |
| BenQ Corporation |
| Barco NV |
| Christie Digital Systems |
| Optoma Corporation |
| ViewSonic Corporation |
| LG Electronics Inc. |
| Others |
Pricing and Supply Chain Analysis
EU Ecodesign standby power mandates gate qualified supply and premium-tier pricing access by disqualifying thermal-heavy lamp architectures from institutional tenders, compressing margin pools in economy-tier lines while laser-hybrid configurations capture extended warranty premiums. Manufacturers reconfigure sourcing toward solid-state illumination to maintain market access across European and Chinese procurement channels.
Pricing Analysis
Volume placements concentrate in standard-tier projectors where per-unit margins compress under cooperative purchasing consolidation; premium-mid-economy pricing differentiation separates laser-hybrid installations with bundled service contracts from consumable-dependent lamp systems. Price differentiation hinges on illumination architecture and after-sales service bundling, with corporate AV managers in Germany and Japan least sensitive to upfront cost given access expense dominance. Cost compression in portable segments intensifies because single-chip DLP substitution erodes 3LCD share where color brightness parity matters less. Education consortia in the United States exhibit highest price sensitivity as standardized classroom specifications prioritize interoperability over performance tier.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from education consortia and corporate fleet operators, while regional AV integrators capture service attach revenue in fragmented satellite office deployments. Manufacturing concentrates in China, Japan, and Germany where Yangtze River Delta clusters supply optical engines, Chubu/Nagoya corridors fabricate precision optics and phosphor wheels, and Bavaria anchors professional installation networks. Critical inputs draw from Japanese and German laser diode and phosphor wheel suppliers, creating single-source vulnerability during demand surges. Distribution runs through authorized dealer networks for institutional tenders and direct e-commerce for portable consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
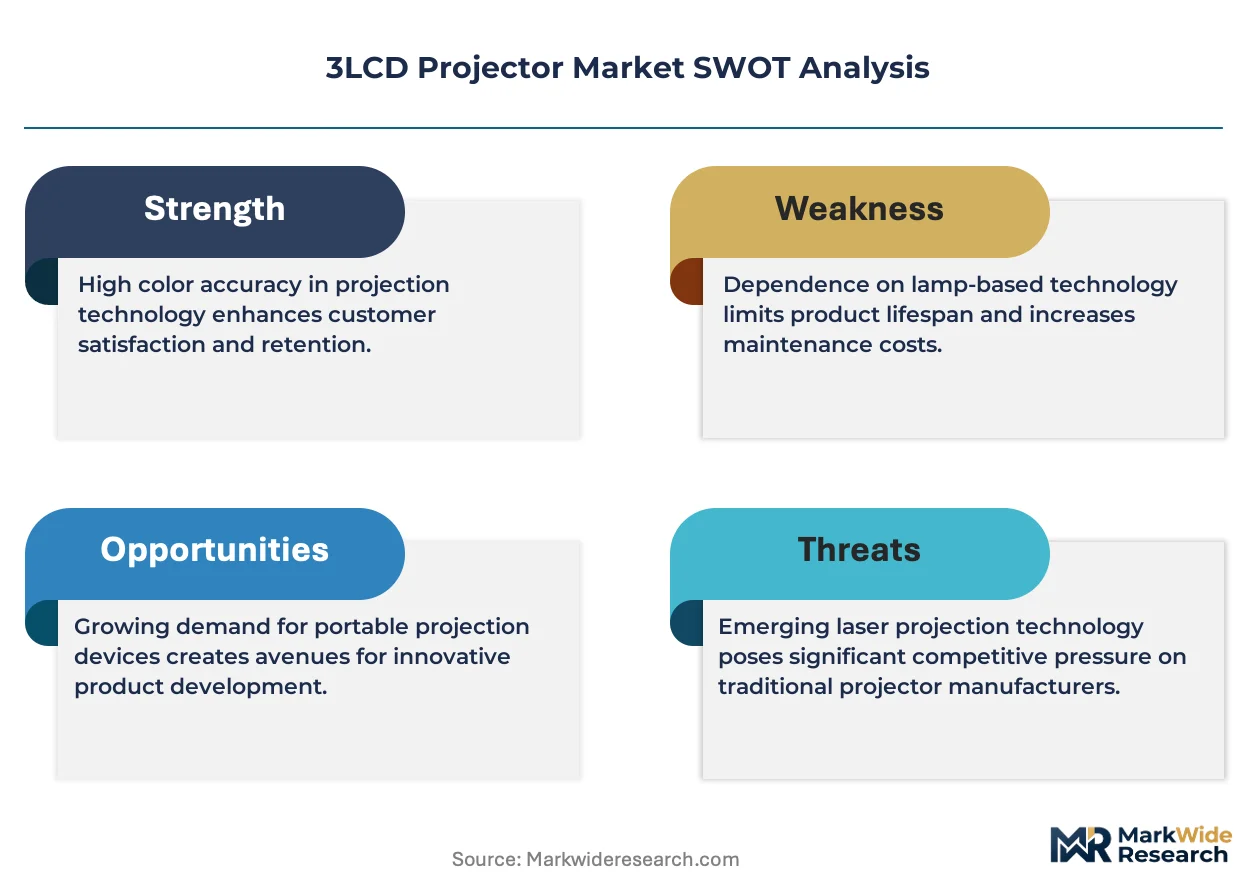
Phosphor wheel and laser diode supply concentration props pricing by constraining qualified component availability, creating a supply-constrained market structure favoring incumbent manufacturers with captive upstream relationships.
For Market Incumbents: Acquire phosphor wheel fabrication capacity or secure long-term offtake agreements with Japanese and German component suppliers to defend against input bottlenecks during education procurement surges. Deepen backward integration into LCD panel production following Seiko Epson's captive fabrication model to compress cost structures across portable and high-end lines. Prioritize IEC 60825-1 laser safety certification investment to accelerate product launches in regulated European and North American institutional channels where documentation delays cede share. For New Entrants and Emerging Players: Capture tier-2 and tier-3 Indian cities where state-level National Education Policy tenders outpace domestic supply capacity and infrastructure readiness gaps favor agile system integrators. Target cloud-based fleet management convergence as a service wedge, bundling projector diagnostics with enterprise IT monitoring platforms to extract recurring revenue from corporate AV deployments fragmented across hybrid-work satellite offices. Pursue direct relationships with regional AV integrators rather than competing on hardware margins. For Investors and Strategic Acquirers: Panasonic Holdings' professional installation network expansion is the leading indicator that ruggedized chassis and service infrastructure command durable margin pools as lamp-based consumables revenue erodes. Long-term viability centers on manufacturers with captive LCD panel supply or established ceiling-mount service networks spanning Germany and Japan. Watch for laser safety certification backlog clearance as the signal that supply-constrained premium-tier capacity is loosening.| Strategic Initiative | Industry Significance |
|---|---|
| Laser-Phosphor Engine Development | Solid-state illumination captures twenty-thousand-hour maintenance-free premiums in corporate ceiling-mount specifications. |
| Cloud Fleet Management Integration | Enterprise IT monitoring convergence enables recurring service revenue from fragmented hybrid-work AV deployments. |
| Ultra-Short Throw Optics Scale-Up | Shadow elimination specifications dominate Chinese classroom and Japanese huddle room refresh cycles. |
| Backward Integration into LCD Panels | Captive fabrication controls cost structures across portable and high-end projector lines as Seiko Epson demonstrates. |
| Regional Service Network Expansion | Installation and calibration expertise scarcity constrains market access in professional ceiling-mount and outdoor configurations. |
Research Methodology
Independent corroboration across projector OEM product managers, AV integrator technical directors, and education procurement officers underwrites the qualitative findings, validated against EU Ecodesign directive filings, EPA universal waste rule documentation, and China GB standards compliance records. Primary interviews with corporate facilities managers and event management rental fleet operators cross-reference secondary data from customs trade flows and institutional tender databases. Bottom-up unit shipment estimates triangulate against top-down value projections across illumination architecture and mounting configuration segments.
Rate-of-change decomposition separates volume trajectory from pricing evolution across the projection horizon, modeling illumination source, throw ratio specification, end-user vertical, and regional regulatory cluster as primary segmentation dimensions. CAGRs derive from fitted growth curves incorporating laser-hybrid adoption elasticity, cooperative purchasing consolidation patterns, and efficiency mandate compliance timelines. Industry-specific forecast inputs include phosphor wheel supply lead times and IEC 60825-1 certification queue depths.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to laser diode supply expansion and extended producer responsibility framework enforcement under EU WEEE directives. Forecasts reflect documented assumptions regarding education funding absorption rates and hybrid-work normalization patterns. Practitioners should monitor phosphor wheel supplier capacity announcements and state-level Indian education technology tender volumes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global 5K Display Resolution Market
Display Technologies
Next Generation 3D Display Market
Display Technologies
Middle East and Africa Industrial Display Market
Display Technologies
Global Portable Monitor Market
Display Technologies
Europe Microdisplay Market
Display Technologies
Global Projector Market
Display Technologies
Global LED Digital Signage Market
Display Technologies
Projector Screen Market
Display Technologies
Flexible Screens Market
Display Technologies
Foldable Screens Market
Display Technologies
3D Display Market
Display Technologies
Volumetric Display Market
Display Technologies
Global Center Stack Display Market
Display Technologies
Collaboration Display Market
Display Technologies
Commercial Touch Display Market
Display Technologies
Microdisplay Market