

Bicycle Front Hub Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Front Hub Market Insights
Taiwan's Taichung precision manufacturing corridor is fragmenting as hub production disperses toward lower-cost Southeast Asian facilities. Shimano leverages in-house forging and bearing assembly to sustain premium positioning across road and mountain bike segments. DT Swiss anchors European demand through Swiss-engineered cartridge bearing systems with extended service intervals. Campagnolo competes narrowly within road racing circles where lightweight aluminum hub shells command loyalty among professional cyclists.
A bicycle front hub is a wheel component housing bearings that enables fork-mounted rotation, typically incorporating steel or ceramic races with axle diameters ranging from 9mm quick-release to 15mm thru-axle configurations for disc brake compatibility. Its primary function distributes rider weight and steering loads while maintaining rotational efficiency across terrain variations. Aluminum hubs occupy the volume core of OEM supply chains due to cost-efficient extrusion and machining, while carbon fiber variants capture margin pools at the premium tier where gram reduction justifies price premiums. Sealed bearing technology leads aftermarket replacement cycles because riders prioritize zero-maintenance reliability, whereas traditional cup-and-cone systems persist in value-oriented markets where serviceability outweighs convenience.
ISO 4210 structural safety standards govern hub fatigue testing protocols, while REACH chemical restrictions in Europe regulate bearing lubricant formulations and surface coating substances. The US Consumer Product Safety Commission monitors quick-release and thru-axle retention failures that trigger recall actions affecting market access. Stakeholders must track evolving e-bike motor integration standards that threaten to subsume front hub relevance as mid-drive systems concentrate torque management at the crank.
Market Dynamics
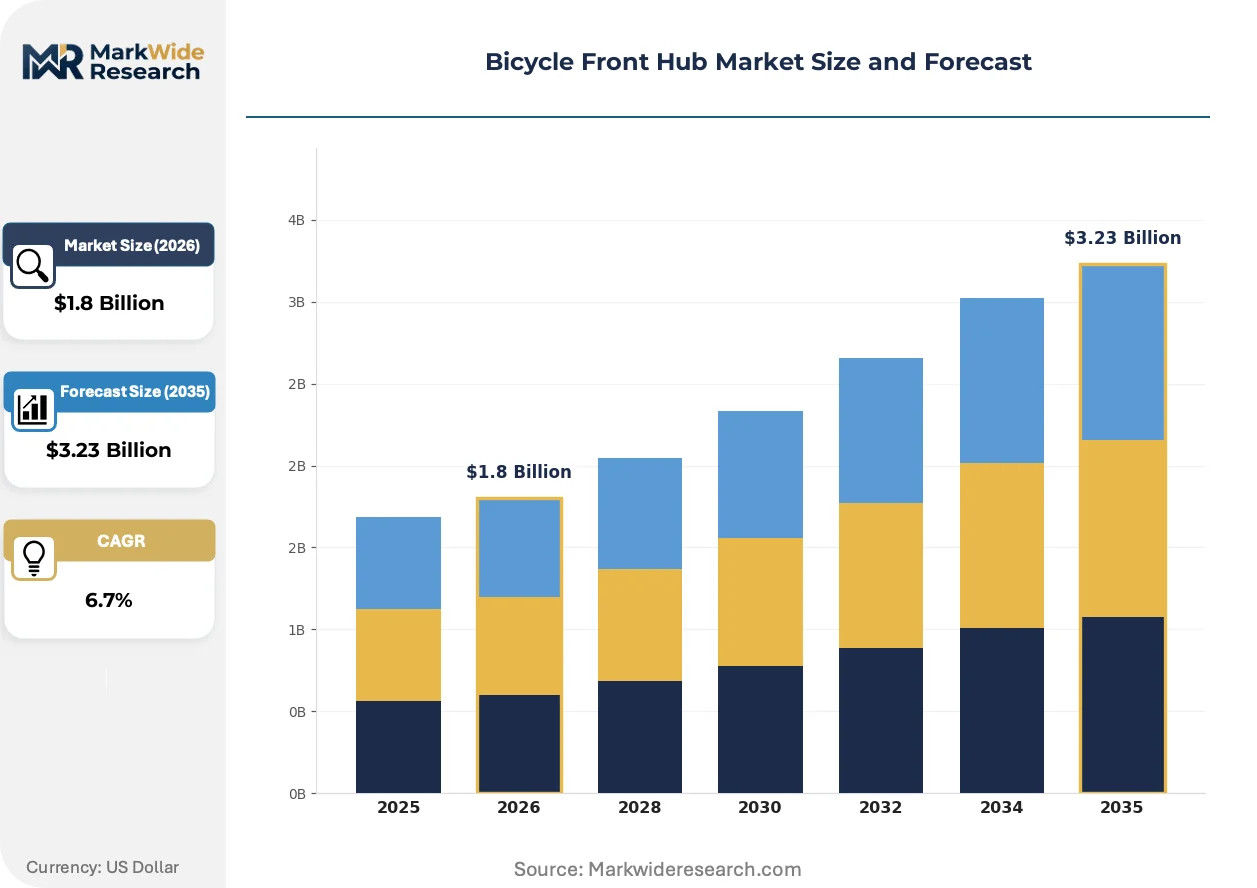
E-bike motor integration standards are compressing front hub relevance as mid-drive architectures concentrate torque management at the crank, forcing suppliers to defend position through bearing precision and service interval extension.
Growth Catalysts
- KBA-type certification frameworks:Germany's tightening e-bike component safety thresholds are elevating quality premiums for certified hub assemblies across European municipal procurement programs.
- Ceramic bearing migration:Sealed ceramic race technology is extending replacement cycles in premium road and mountain bike segments where rotational efficiency commands price tolerance.
- Zhejiang-Guangdong manufacturing clusters:China's concentrated hub forging and CNC finishing capacity is scaling fastest, anchoring OEM cost structures for volume bicycle assembly.
Market Restraints
- Aluminum input volatility:Extrusion-grade aluminum price swings compress margin pools for mid-tier hub suppliers dependent on commodity feedstock.
- Thru-axle technical ceiling:15mm axle configurations face stiffness limitations under heavier e-bike front loads, constraining design latitude for disc brake compatibility.
- REACH lubricant restrictions:ECHA chemical regulations on bearing grease formulations add compliance overhead without commensurate performance differentiation.
Strategic Opportunities
- Carbon fiber hub shells:Gram reduction premiums in professional road racing circles justify margin capture beyond aluminum volume economics.
- Swiss cartridge bearing systems:Extended service interval engineering opens aftermarket replacement cycles in European markets where labor costs favor zero-maintenance reliability.
- Southeast Asian production dispersion:Taichung corridor fragmentation creates capacity relocation options as Taiwan labor costs escalate.
Industry Challenges
- CNC machining skill scarcity:Precision finishing talent concentrates in legacy manufacturing corridors, constraining quality scaling at new Southeast Asian facilities.
- ISO 4210 fatigue certification timelines:Extended structural safety testing protocols delay product launch windows for forged hub redesigns.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Front Hub Market Trends and Innovations
Active material convergence and regulatory chemistry constraints are reshaping hub engineering priorities. Suppliers now balance weight reduction imperatives against extended service life guarantees demanded by fleet operators.
Magnetic levitation bearing technology is hybridizing traditional mechanical race architectures with contactless rotation systems. High-end road racing teams are piloting these hubs for friction reduction. This convergence is hybridizing competitive positioning between established cartridge suppliers and magnetic component specialists.
REACH surface coating restrictions are eliminating hexavalent chromium treatments from hub finishing processes. European suppliers face reformulation costs for anodization chemistries. Aftermarket replacement demand in Germany and Benelux markets is accelerating toward pre-treated aluminum alternatives that bypass post-coating compliance.
Fleet procurement unbundling is separating hub specification from complete bicycle sourcing. Municipal e-bike operators in Northern Europe now contract bearing replacement intervals independently of frame OEM agreements. Denmark and Netherlands transit authorities are pioneering component-level service contracts that override traditional bundled warranties.
Bicycle Front Hub Market Segmentation
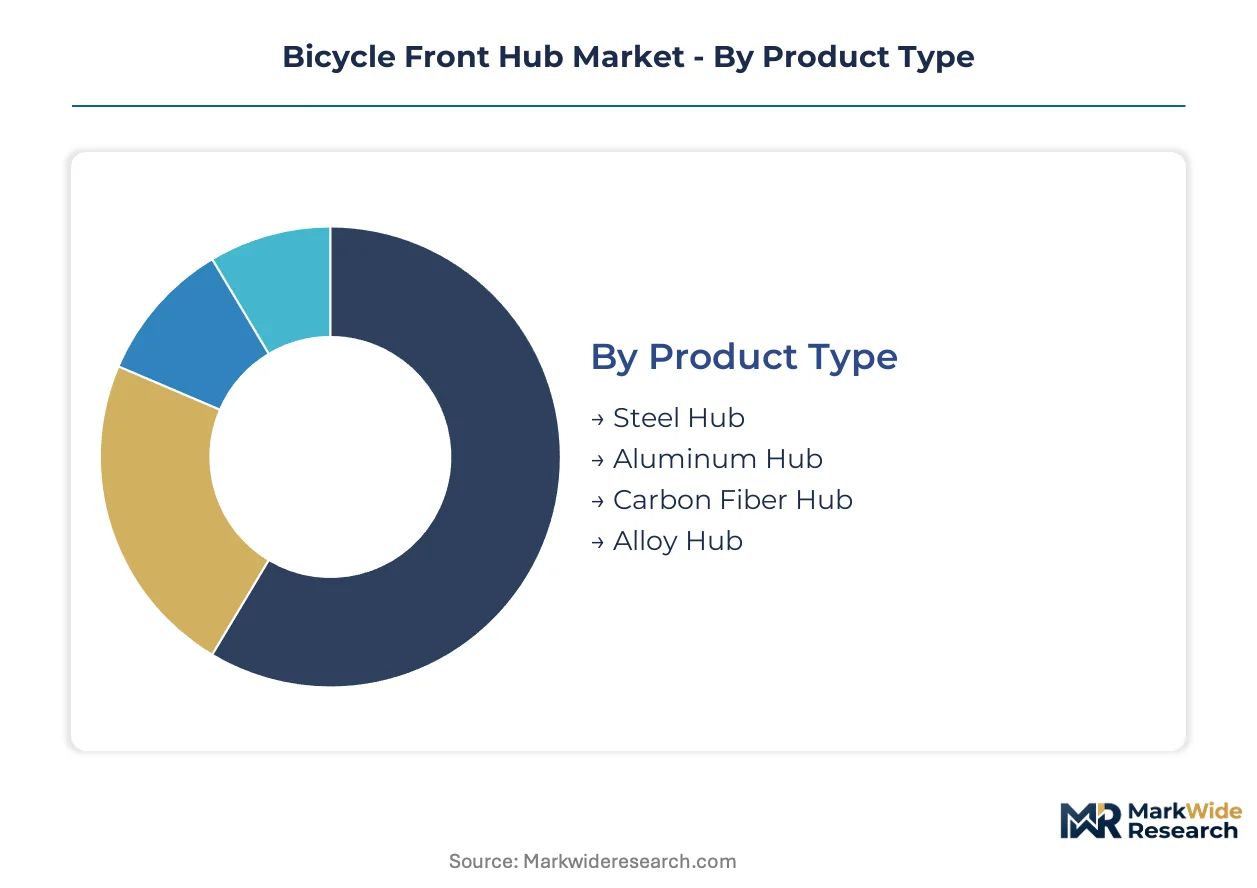
Front hub replacement cycles vary sharply across rider profiles and fleet duty cycles. After-sales service intensity—bearing replacement frequency, field serviceability, and warranty claim rates—differs fundamentally between cup-and-cone systems in rental fleets versus sealed cartridges in consumer channels. Segmentation by product, technology, application, and end user captures these divergent service economics.
Product Type:
After-sales service intensity peaks with carbon fiber variants where shell damage mandates complete replacement rather than bearing service, while aluminum and steel variants support modular repair protocols that extend field life.
- Aluminum Hub:Extruded and CNC-finished shells dominate OEM supply chains for road and mountain bike assembly. Demand concentrates in China's Zhejiang manufacturing corridor where forging capacity scales fastest, though aluminum price volatility compresses margin pools for mid-tier suppliers.
- Steel Hub:Chromoly and stainless variants persist in utility and cargo bike segments where load-bearing durability outweighs weight penalties. European municipal e-bike fleets specify steel shells for extended service intervals under KBA-type certification frameworks.
- Carbon Fiber Hub:Molded composite shells capture gram-reduction premiums in professional road racing.
- Alloy Hub:Magnesium-aluminum blends occupy mid-market positioning between pure aluminum cost efficiency and carbon fiber performance.
By volume, aluminum leads. By growth pace, carbon fiber is expanding most quickly.
Technology:
Cost tier stratification separates premium sealed and magnetic systems from value-oriented cup-and-cone architectures, with aftermarket pricing power correlating directly to service interval extension.
- Sealed Bearing:Pre-lubricated cartridge units with integrated seals eliminate field maintenance requirements. DT Swiss and Swiss-engineered competitors anchor European demand through extended service interval guarantees that command labor-cost premiums in Germany and Benelux markets.
- Cartridge Bearing:Replaceable bearing units bridge serviceability and convenience, supporting independent replacement without hub shell disassembly. Shimano's in-house assembly integration sustains premium positioning across road and mountain segments.
- Traditional Cup and Cone:Adjustable angular contact bearings persist in value markets and rental fleets where serviceability outweighs convenience.
- Magnetic Bearing:Contactless levitation systems hybridize mechanical architectures with friction reduction.
Sealed bearing commands the broadest installed base. Magnetic bearing shows the steepest expansion trajectory among emerging technologies.
Application:
Application-driven volume concentration in electric bikes is reshaping specification requirements, with heavier front loads and disc brake torque demands forcing axle and bearing upgrades across incumbent road and mountain platforms.
- Electric Bikes:Mid-drive motor architectures concentrate torque at the crank but impose heavier front loads requiring reinforced 15mm thru-axle hubs. Denmark and Netherlands municipal procurement programs unbundle hub specification from frame OEM agreements, creating independent component-level service contracts.
- Mountain Bikes:Disc brake compatibility and thru-axle stiffness requirements drive specification toward sealed cartridge systems with 15mm axle configurations.
- Road Bikes:Weight minimization prioritizes lightweight aluminum and carbon fiber shells with ceramic bearing options.
- Hybrid Bikes:Commuter-oriented duty cycles balance durability and cost, favoring aluminum hubs with cup-and-cone serviceability.
Electric bike applications lead by revenue contribution. Mountain bike specifications are gaining share fastest among traditional pedal-powered categories.
End User:
Customer type determines warranty structure and replacement cycle economics, with rental services and competitive racers presenting opposite extremes of utilization intensity and price tolerance.
- Rental Services:Fleet operators prioritize zero-maintenance reliability and standardized replacement intervals over upfront cost. Northern European municipal programs now contract bearing service independently of bicycle OEM warranties.
- Professional Cyclists:Sponsored athletes access equipment through team supply agreements with minimal price sensitivity.
- Recreational Riders:Weekend enthusiasts balance performance aspirations against maintenance convenience.
- Competitive Racers:Amateur and semi-professional competitors self-fund equipment upgrades.
Rental services generate the most predictable replacement demand. Competitive racers show the fastest spending growth per capita.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European municipal procurement programs specify front hubs for electric bike fleets under extended service contracts, while Asian manufacturing clusters supply forged aluminum shells at scale. This consumption-mix differential separates specification authority from production gravity.
Germany
KBA-type certification frameworks tighten quality thresholds for e-bike component safety, elevating certified hub assemblies in municipal procurement. REACH restrictions on bearing lubricant formulations add compliance overhead for suppliers. Industrial concentration centers on Baden-Württemberg engineering corridors where precision finishing capacity serves premium OEM demand.
China
Zhejiang and Guangdong manufacturing clusters scale hub forging and CNC finishing capacity fastest, anchoring global OEM cost structures. GB standards govern structural safety testing for export-bound components. Taizhou and Shenzhen industrial zones concentrate extrusion-grade aluminum processing for mid-tier volume supply.
Switzerland
Swiss-engineered cartridge bearing systems command labor-cost premiums in Germany and Benelux markets through extended service interval guarantees. Swissmedic oversight applies to surface coating substances in precision component finishing. Biel and Grenchen watchmaking-adjacent manufacturing corridors transfer metrology expertise to hub bearing assembly.
United States
CPSC monitoring of quick-release and thru-axle retention failures shapes aftermarket liability structures for hub suppliers. Mountain bike disc brake compatibility drives specification toward 15mm thru-axle configurations in Colorado and Pacific Northwest trail markets. California and Oregon municipal bike-share programs unbundle component-level service contracts from frame OEM agreements.
Netherlands
Denmark and Netherlands transit authorities pioneer component-level service contracts that override traditional bundled warranties, creating independent hub specification channels. ECHA chemical regulations on anodization chemistries eliminate hexavalent chromium treatments from finishing processes. Randstad logistics corridors distribute sealed cartridge systems to Northern European fleet operators prioritizing zero-maintenance reliability.
Bicycle Front Hub Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. Premium positioning depends on in-house forging integration and bearing assembly precision, while volume economics favor concentrated extrusion capacity in coastal Chinese manufacturing zones. Three archetypes dominate: vertically integrated precision specialists, scale-driven OEM suppliers, and niche racing-focused fabricators. Competitive moves center on Southeast Asian production dispersion and ceramic bearing technology licensing.
Within the precision-specialist tier, DT Swiss and Campagnolo exemplify divergent strategic anchors—Swiss cartridge bearing engineering versus Italian road racing heritage. Among Asian volume fabricators, Novatec occupies a position shaped by Zhejiang manufacturing corridor scale advantages. Chris King represents the premium-machining archetype where domestic US fabrication commands price tolerance in aftermarket channels. These three sit within distinct competitive vectors rather than direct confrontation.
| Leading Market Players |
|---|
| Shimano |
| DT Swiss |
| Campagnolo |
| Chris King |
| Hope Technology |
| Industry Nine |
| Mavic |
| Zipp |
| Novatec |
| Others |
Pricing and Supply Chain Analysis
Aluminum input volatility determines both pricing tier spreads and supply chain shape, as extrusion-grade commodity swings compress margin pools for mid-tier hub suppliers while forcing premium manufacturers toward in-house forging integration and ceramic bearing differentiation.
Pricing Analysis
Chinese-manufactured aluminum hubs trade at 40-60% discounts to Swiss-engineered cartridge systems, with price differentiation anchored in certification grade and brand premium. Three-tier pricing structure across premium, standard, and economy levels stratifies around KBA-type certification compliance, ceramic bearing integration, and service interval guarantees. Cost compression in mid-tier extruded aluminum shells is intensifying because of commodity feedstock exposure. Fleet procurement managers at European municipal operators show least price sensitivity due to unbundled component-level service contracts, while Southeast Asian OEM assemblers face acute margin pressure.
Supply Chain Analysis
Supplier-financing through extended payment terms has become standard practice among Zhejiang forging houses serving volume bicycle OEMs, with 90-120 day cycles now typical for extrusion-grade aluminum hub shells. Manufacturing concentrates in China, Taiwan, and Switzerland, with raw material dependencies on bauxite-refined aluminum, bearing-grade steel, and ceramic powder feedstocks. Single-source vulnerability concentrates in precision CNC finishing talent pools that feed from legacy Taichung corridors. Distribution runs through frame OEM bundled procurement, aftermarket replacement channels, and emerging fleet service contract unbundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward fleet operators as Northern European municipal procurement unbundles hub specification from complete bicycle sourcing, fragmenting traditional OEM channel control.
For Market Incumbents: Entrench position through backward integration into bearing assembly and captive forging capacity in Zhejiang manufacturing corridors. Ceramic bearing technology licensing and ISO 4210 fatigue certification investment defend against magnetic levitation substitution threats. Prioritize extended service interval engineering to capture fleet procurement contracts that override traditional bundled warranties. For New Entrants and Emerging Players: Southeast Asian underpenetration in precision CNC finishing capacity offers white-space entry as Taichung labor costs escalate. Carbon fiber hub shell fabrication for professional road racing presents margin capture opportunities beyond aluminum volume economics. Target component-level service contract channels in Denmark and Netherlands transit authorities with zero-maintenance reliability positioning. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision-specialist acquisition targets with in-house forging and cartridge bearing assembly integration. Long-term viability hinges on regulatory certification moats and ceramic technology licensing portfolios. Watch KBA-type framework expansion beyond Germany as the inflection signal for quality-premium repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Bearing Technology Licensing | Extends replacement cycles for premium road and mountain bike segments where DT Swiss and Swiss competitors anchor European demand. |
| ISO 4210 Fatigue Certification Investment | Accelerates product launch timelines for forged hub redesigns under tightening German KBA-type safety frameworks. |
| Southeast Asian Production Dispersion | Relocates capacity from escalating Taichung labor costs toward Vietnam and Indonesia precision manufacturing zones. |
| Fleet Service Contract Unbundling | Captures independent hub specification channels as Denmark and Netherlands transit authorities pioneer component-level procurement. |
| Magnetic Levitation R&D Partnership | Hybridizes mechanical race architectures with contactless rotation systems piloted by high-end road racing teams. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including frame OEM procurement directors, fleet maintenance managers at Northern European municipal operators, precision forging engineers in Zhejiang manufacturing corridors, and aftermarket distribution channel heads. Secondary validation drew from customs and trade data, bicycle industry association production statistics, KBA and ECHA regulatory filings, and SEC disclosures from publicly traded component suppliers. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Calibration against historical replacement cycle data and fleet procurement contract structures anchored the analytical framework. Segmentation dimensions modeled include product type, bearing technology, application category, and end-user archetype. CAGRs were derived from regression analysis of installed base growth, duty cycle intensity, and technology migration patterns. E-bike motor integration standards and REACH chemical restriction timelines served as industry-specific forecast modifiers.
Macroeconomic conditions sit as an overlay; deviation in aluminum commodity pricing, European municipal procurement budgets, or Southeast Asian manufacturing wage inflation would shift the trajectory. Forecasts reflect documented assumptions about certification framework adoption rates and ceramic bearing cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.