
 5G Security Market | 2026-2036
5G Security Market Size, Share, and Industry Trends Forecast 2026-2036
5G Security Market Intelligence
Platform bundling is recalibrating buyer choice across the 5G security landscape. Ericsson leverages its end-to-end portfolio to anchor large operator contracts with embedded encryption layers. Palo Alto Networks specializes in cloud-native firewalls that compete directly with traditional telecom equipment vendors. Nokia sustains R&D intensity in zero-trust architectures for industrial automation networks.
5G security encompasses encryption protocols, network slicing isolation mechanisms, and AI-driven threat detection systems operating at sub-millisecond latency thresholds to protect ultra-reliable low-latency communications. Its primary commercial purpose is to safeguard massive machine-type communications and critical infrastructure from distributed attacks targeting edge nodes. Network security solutions dominate current operator spending as legacy perimeter defenses prove inadequate for decentralized architectures. Cloud-native deployment models represent the fastest-growing configuration, though on-premise installations persist among government agencies with data sovereignty mandates. Security analytics is emerging as a margin-rich segment where real-time behavioral monitoring commands premium pricing.
The FCC in the United States mandates supply chain risk management for federally funded 5G infrastructure, while the EU NIS2 Directive imposes stricter incident reporting on telecom operators across member states. ETSI standards for network function virtualization security shape product certification requirements and market access timelines. Stakeholders must monitor how 3GPP Release 18 security specifications will alter encryption key management obligations for edge computing deployments.
Market Dynamics
Network slicing architectures are fragmenting security perimeters across distributed edge nodes, forcing operators to abandon centralized fortress models in favor of zero-trust enforcement at every network function. This structural decomposition is accelerating procurement cycles for cloud-native security stacks that can scale horizontally across heterogeneous infrastructure layers.
Growth Catalysts
- EU NIS2 Directive:Mandatory incident reporting timelines for telecom operators are compressing security upgrade schedules across European member states, creating immediate replacement demand for legacy monitoring systems.
- Industrial automation networks:Manufacturing facilities in Germany and South Korea are deploying private 5G cores that require dedicated security orchestration platforms with sub-millisecond threat response capabilities.
- Post-quantum cryptography:NIST standardization of quantum-resistant algorithms is electrifying R&D investment in encryption key management systems designed for 5G core networks.
Market Restraints
- Silicon supply concentration:Advanced encryption processor fabrication depends on a limited foundry base concentrated in Taiwan, creating vulnerability to geopolitical disruption.
- ETSI NFV certification complexity:Multi-stage security validation for virtualized network functions extends product launch timelines by 18-24 months, freezing vendor revenue recognition.
- Skilled workforce scarcity:Deep expertise in 3GPP security specifications and cloud-native orchestration concentrates among specialists command compensation premiums that inflate project costs.
Strategic Opportunities
- United States federal infrastructure:FCC supply chain risk management mandates for federally funded 5G deployments are opening dedicated procurement channels for domestic security vendors with trusted foundry certifications.
- AI-driven behavioral analytics:Convergence of machine learning inference at the edge with 5G core signaling data is creating new product categories for real-time anomaly detection in massive machine-type communications.
- Open RAN security gaps:Disaggregation of radio access network hardware from software is exposing interoperability vulnerabilities that specialized security vendors can address through multi-vendor certification services.
Industry Challenges
- Legacy integration friction:Operators maintaining 4G core networks alongside 5G standalone deployments face complex interworking security protocols that delay feature parity and increase operational overhead.
- Certification timeline compression:Accelerated 3GPP release cycles are outpacing security validation frameworks, forcing vendors to ship products with provisional certifications that expose liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Security Market |
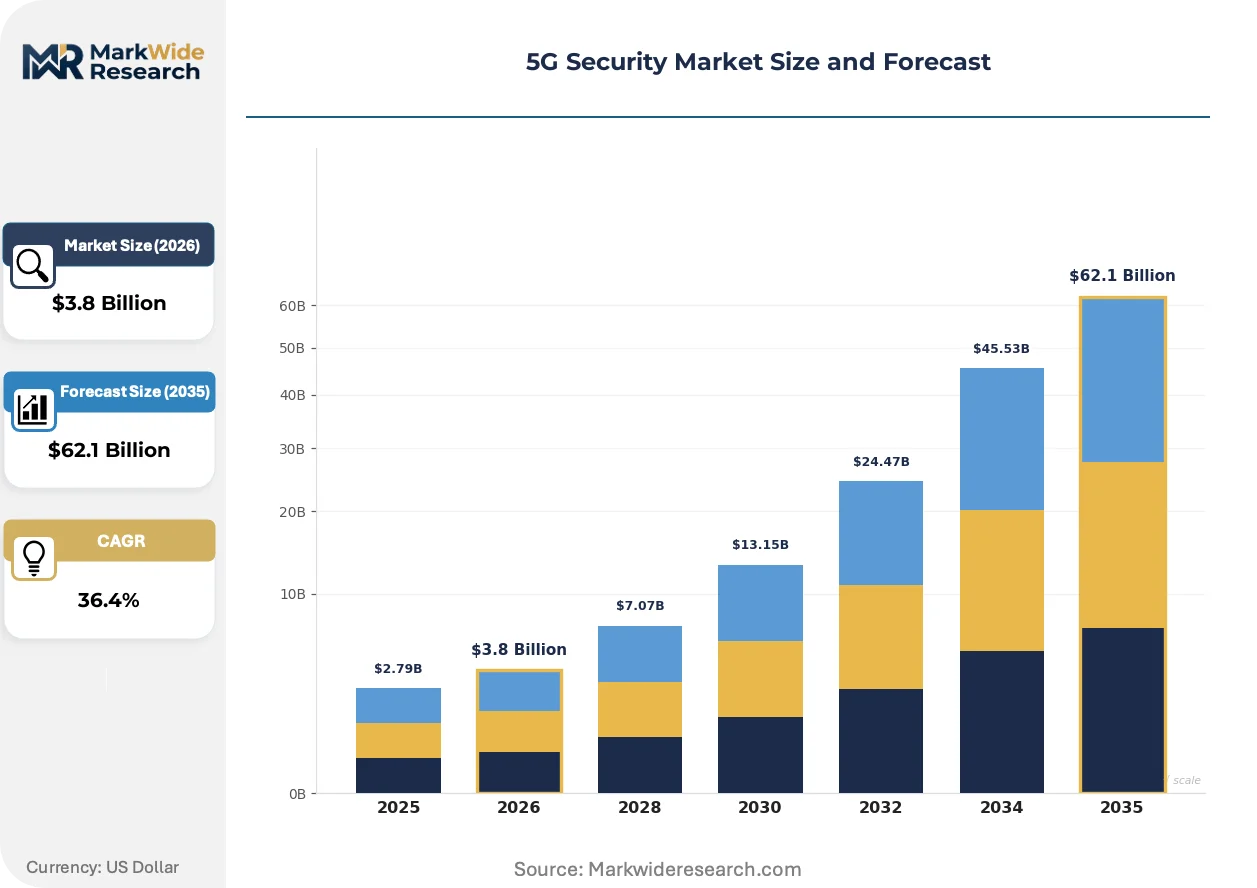
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $62.1 Billion |
| CAGR (2026 – 2036) | 36.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Native, On-Premise, Hybrid, Edge-Computing Solution Type: Network Security, Data Encryption, Identity & Access Management, Threat Intelligence, Security Analytics Application: Smart Cities, Industrial Automation, Autonomous Vehicles, Public Safety, Remote Healthcare End User: Telecom Operators, Managed Security Service Providers, Government Agencies, Technology Vendors |
| Companies Covered | Ericsson, Palo Alto Networks, Nokia, Cisco Systems, Huawei, Fortinet, Check Point Software Technologies, Juniper Networks, F5 Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Security Market Strategic Shifts & Innovations
Security orchestration is migrating from policy-driven configuration toward autonomous response systems that execute containment actions without human intervention. This automation imperative is reshaping vendor competitive positioning around latency benchmarks and AI model accuracy rather than feature breadth alone.
Confidential computing hardware is electrifying trust boundaries at the chip level, enabling encrypted computation on sensitive data without exposing cleartext to host operating systems. Telecom operators in South Korea are piloting these trusted execution environments for subscriber authentication functions that previously required dedicated hardware security modules. The technology is compressing capital requirements for multi-tenant edge deployments by eliminating physical segregation dependencies.
The EU AI Act risk classification framework is imposing algorithmic transparency obligations on security vendors deploying automated threat detection in critical infrastructure. Systems categorized as high-risk must maintain audit trails and human oversight mechanisms that increase development overhead but create compliance barriers against unregulated competitors. German operators are prioritizing vendors with established conformity assessment procedures to preempt regulatory enforcement actions.
Security-as-a-service consumption models are displacing perpetual license purchases among mid-tier operators seeking to align security spending with subscriber growth trajectories. Managed detection and response offerings bundle telemetry ingestion, analyst coverage, and incident response into per-subscriber pricing that reduces upfront capital commitment. This pattern is most pronounced in United States regional carriers navigating standalone 5G core transition costs.
5G Security Market Segmentation
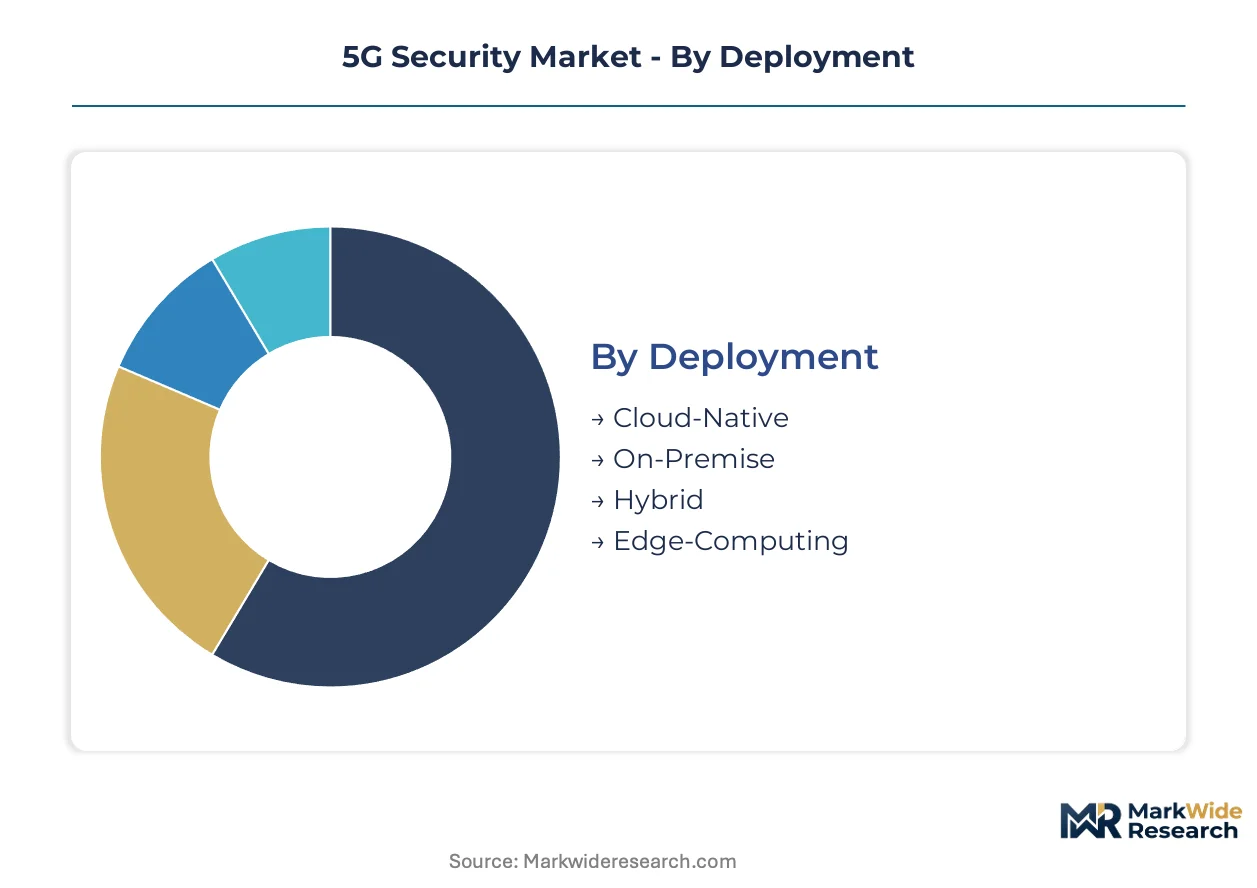
5G security procurement patterns diverge sharply between operators pursuing cloud-native scale and agencies bound by data sovereignty mandates. Understanding deployment configurations, solution architectures, and end-user priorities reveals where vendor margins concentrate and which segments command premium pricing.
Deployment:
Volume deployment concentrates in cloud-native configurations, while premium pricing attaches to edge-computing and hybrid installations where latency requirements override cost optimization.
- Cloud-Native:Containerized security functions orchestrate across distributed infrastructure using Kubernetes-based automation. German and South Korean operators are standardizing on these stacks for network slicing isolation, driven by 3GPP Release 18 compliance timelines that compress upgrade windows.
- On-Premise:Dedicated hardware deployments satisfy government data residency requirements through physical infrastructure control. United States federal agencies mandate these configurations under FCC supply chain risk management rules, constraining vendor selection to domestic trusted foundry certifications.
- Hybrid:Split architectures balance core network sovereignty with edge scalability across multi-vendor environments.
- Edge-Computing:Sub-millisecond threat response capabilities protect ultra-reliable low-latency communications at distributed radio units.
Mature deployment sits with On-Premise installations in defense and intelligence applications. Newer deployment is concentrated in Cloud-Native stacks among tier-one operators accelerating standalone 5G core transitions.
Solution Type:
Application focus separates commodity network perimeter tools from margin-rich analytics platforms where AI inference commands recurring revenue premiums.
- Network Security:Distributed firewall and segmentation policies protect fragmented network slicing architectures across heterogeneous infrastructure layers. Telecom operators in the United States allocate the largest procurement budgets here as legacy centralized defenses prove inadequate for decentralized 5G topologies.
- Security Analytics:Real-time behavioral monitoring correlates 5G core signaling data with machine learning models for autonomous threat containment. German operators under EU AI Act obligations prioritize vendors with established algorithmic transparency and audit trail capabilities.
- Data Encryption:Quantum-resistant key management systems prepare core networks for post-cryptographic standards.
- Identity & Access Management:Subscriber authentication functions migrate toward confidential computing hardware eliminating physical security module dependencies.
- Threat Intelligence:Federated data sharing across operator consortiums enhances detection coverage against distributed attacks.
Procurement maturity clusters around Network Security. Security Analytics is gaining share fastest as automated response replaces policy-driven configuration.
Application:
Critical infrastructure classification determines regulatory scrutiny intensity and corresponding security investment levels across vertical deployments.
- Industrial Automation:Private 5G cores in manufacturing facilities demand dedicated orchestration platforms with deterministic threat response. South Korean automotive and electronics plants are deploying these systems at scale, compelled by operational technology convergence that dissolves legacy IT-OT boundaries.
- Public Safety:Mission-critical communications for emergency services require encryption resilience against sophisticated interception attempts. United States FirstNet deployments anchor this segment with federal funding streams that bypass standard procurement cycles.
- Smart Cities:Massive sensor networks create distributed attack surfaces across municipal infrastructure.
- Autonomous Vehicles:V2X communication security demands sub-millisecond verification of roadside unit authenticity.
- Remote Healthcare:Patient data transmission over 5G networks triggers HIPAA compliance obligations for encryption and access logging.
Established deployment dominates Public Safety with dedicated spectrum allocations. Industrial Automation is climbing the fastest as Germany and South Korea accelerate factory digitization.
End User:
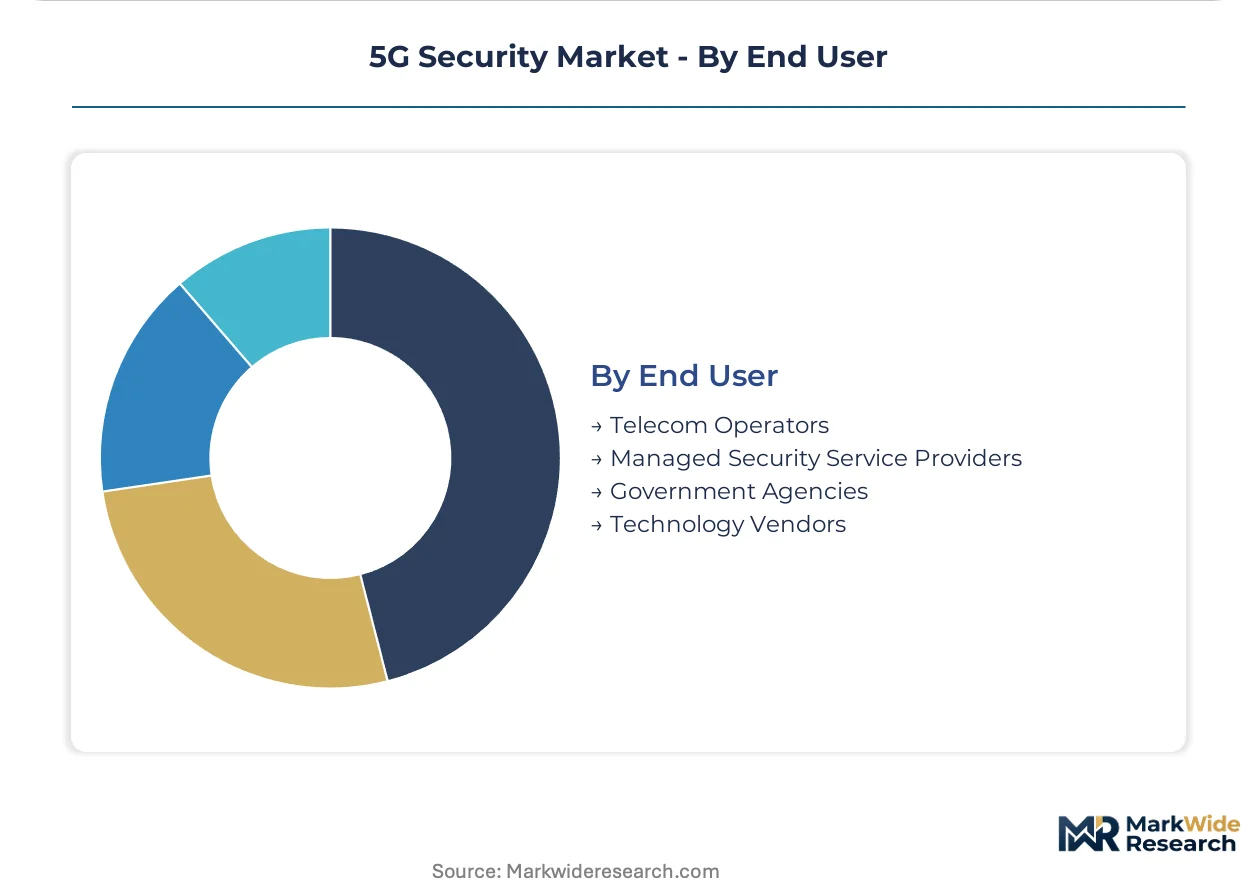
Buying power concentration varies from capital-constrained regional carriers to government procurement channels with sovereign guarantee backing.
- Telecom Operators:Tier-one carriers drive standardization through RFP specifications that embed security requirements into core network contracts. United States operators are consolidating vendor relationships around integrated suites rather than point solutions, compressing supplier margins but securing interoperability commitments.
- Government Agencies:National security and critical infrastructure protection mandates override commercial pricing considerations. EU member states under NIS2 Directive obligations are accelerating replacement demand with mandatory incident reporting timelines that expose legacy monitoring inadequacies.
- Managed Security Service Providers:Per-subscriber pricing models align security spending with growth trajectories for mid-tier operators.
- Technology Vendors:Equipment manufacturers embed security layers to differentiate radio and core network offerings.
Procurement maturity rests with Government Agencies under long-standing critical infrastructure frameworks. Managed Security Service Providers are expanding most quickly as security-as-a-service consumption displaces perpetual licenses among capital-constrained operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Security solution production concentrates among telecom equipment vendors in Sweden and Finland, while consumption gravity shifts toward operator deployment clusters in Germany, South Korea, and the United States where standalone 5G core buildouts accelerate procurement cycles.
United States
Federal infrastructure mandates and regional carrier consolidation drive procurement of integrated security suites. FCC supply chain risk management rules constrain vendor selection to domestic trusted foundry certifications for federally funded deployments. FirstNet installations in the Northeast Corridor anchor mission-critical communications security spending with dedicated federal funding streams.
Germany
Industrial automation networks and private 5G core deployments in manufacturing facilities compress upgrade timelines for zero-trust architectures. EU NIS2 Directive mandatory incident reporting obligations expose legacy monitoring inadequacies across telecom operators. Automotive plants in Bavaria deploy dedicated orchestration platforms with deterministic threat response capabilities for operational technology convergence.
South Korea
Electronics manufacturing and automotive digitization propel private 5G core security investments at sub-millisecond latency thresholds. Confidential computing hardware pilots for subscriber authentication functions eliminate physical security module dependencies in Seoul Capital Area deployments. National regulators accelerate certification frameworks for multi-tenant edge infrastructure.
Japan
Industrial IoT integration and smart factory initiatives generate demand for network slicing isolation mechanisms. METI guidelines on critical infrastructure protection shape operator procurement specifications for cloud-native security stacks. Manufacturing clusters in Aichi Prefecture and Osaka-Kobe industrial zones pilot autonomous response systems for ultra-reliable low-latency communications.
United Kingdom
Telecom security resilience mandates and post-Brexit regulatory autonomy recalibrate supplier diversification strategies. National security frameworks impose encryption standards on core network vendors serving critical infrastructure. London financial services and Manchester digital clusters drive security analytics procurement for real-time behavioral monitoring compliance.
5G Security Market Key Industry Players
The competitive structure tilts toward integrated equipment vendors with end-to-end portfolio breadth. Tier-one operators consolidate vendor relationships around embedded security layers rather than point solutions, compressing supplier margins but securing interoperability commitments. Two strategic archetypes dominate: telecom-native equipment vendors anchoring core network contracts, and cloud-native cybersecurity specialists competing at the network edge. Dominant competitive moves include strategic partnerships between radio vendors and cloud security platforms, plus portfolio diversification into AI-driven threat analytics.
Among telecom-native vendors, Ericsson and Nokia exemplify the integrated equipment archetype with embedded encryption layer strategies, while Palo Alto Networks occupies a position among cloud-native specialists competing directly at the firewall and analytics tier. These three anchors represent divergent approaches to operator procurement—end-to-end bundling versus best-of-breed cloud security—shaping how security spending fragments across network slicing architectures and edge computing deployments.
| Leading Market Players |
|---|
| Ericsson |
| Palo Alto Networks |
| Nokia |
| Cisco Systems |
| Huawei |
| Fortinet |
| Check Point Software Technologies |
| Juniper Networks |
| F5 Networks |
| Others |
Cost & Logistics Intelligence
FCC supply chain risk management mandates for federally funded 5G infrastructure are forcing operators to source exclusively from domestic trusted foundry certifications, compressing vendor pools and elevating pricing power among compliant suppliers. This procurement constraint cascades through encryption processor tiers, creating cost premiums for hardware security modules and confidential computing chips that meet federal assurance standards.
Pricing Analysis
Margin tightening in cloud-native security stacks reflects operator consolidation around integrated suites rather than point solutions. Three-tier pricing structure across premium, standard, and economy levels separates vendors with 3GPP Release 18 provisional certifications from those holding full ETSI NFV validation. Certification grade and volume scale drive price differentiation, with tier-one carriers commanding 40-60% discounts unavailable to mid-tier operators. Cost compression accelerates in network security appliances as Chinese vendors penetrate developing markets with subsidized offerings. Regional carriers in the United States exhibit highest price sensitivity due to standalone 5G core transition costs, while government agencies under sovereign guarantee backing show lowest sensitivity to unit pricing.
Supply Chain Analysis
Single-source vulnerability sits with advanced encryption processor fabrication concentrated in Taiwan, South Korea, and the United States. Raw material dependencies span silicon wafers, rare earth elements for chip packaging, and specialized substrates for millimeter-wave components. Geopolitical disruption risk looms over foundry access, with tariff exposure escalating for components crossing multiple regulatory jurisdictions. Distribution runs through telecom equipment vendors with direct operator relationships, bypassing traditional IT channel partners for core network security procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native security orchestration is displacing policy-driven configuration systems across operator procurement cycles, creating transition-phase arbitrage for vendors with autonomous response capabilities. Legacy perimeter defense vendors face compressed margins as zero-trust architectures fragment security spending across distributed network functions.
For Market Incumbents: Hedge against Open RAN disaggregation by embedding encryption layers deeper into radio access network software stacks rather than hardware-dependent modules. Prioritize R&D investment in post-quantum cryptography key management to preempt NIST standardization disruption. Acquire confidential computing hardware specialists to eliminate physical security module dependencies in multi-tenant edge deployments. Defensive consolidation around AI-driven behavioral analytics capabilities protects against cloud-native cybersecurity specialists encroaching on core network contracts. For New Entrants and Emerging Players: EU NIS2 Directive in European member states opens a window for managed detection and response offerings that compress incident reporting timelines for legacy monitoring replacement. Target mid-tier United States regional carriers navigating standalone 5G core transition costs with per-subscriber pricing models that align security spending with subscriber growth trajectories. Penetrate South Korean automotive and electronics manufacturing facilities with deterministic threat response platforms for private 5G core deployments. Go-to-market leverage rests on multi-vendor certification services that address Open RAN interoperability vulnerabilities. For Investors and Strategic Acquirers: The window for entry favors cloud-native cybersecurity specialists with AI inference capabilities at sub-millisecond latency thresholds. Long-term viability centers on vendors commanding recurring revenue premiums in security analytics rather than commoditized network perimeter tools. Acquisition target archetype: managed security service providers with established per-subscriber pricing models and analyst coverage infrastructure. Signal to watch: 3GPP Release 18 security specification finalization altering encryption key management obligations for edge computing deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Hardware Integration | Trusted execution environments eliminate physical security module dependencies in Seoul Capital Area multi-tenant deployments. |
| Post-Quantum Cryptography R&D Acceleration | NIST quantum-resistant algorithm standardization electrifies investment in encryption key management for 5G core networks. |
| Managed Detection and Response Platform Launch | Per-subscriber pricing aligns security spending with growth trajectories for capital-constrained United States regional carriers. |
| Multi-Vendor Open RAN Certification Services | Interoperability vulnerability exposure creates service revenue from disaggregated radio access network security validation. |
| Zero-Trust Architecture Industrial Deployment | German automotive plants in Bavaria demand deterministic threat response for operational technology convergence scenarios. |
Research Approach
Document review covered 3GPP technical specifications, ETSI NFV security standards, FCC supply chain risk management filings, and EU NIS2 Directive implementation guidance, complemented by interviews with network security architects at tier-one telecom operators, procurement leads at managed security service providers, and regulatory compliance officers at equipment vendors. Secondary validation drew from SEC 10-K disclosures of publicly traded cybersecurity firms, hyperscaler capex reports detailing edge infrastructure investments, and customs data tracking encryption processor trade flows. Bottom-up demand modeling across deployment configurations, solution types, and end-user segments was triangulated against top-down market sizing from equipment vendor revenue disclosures.
Historical spending patterns from operator procurement databases were cross-referenced against panel input from infrastructure planning executives to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include deployment configuration, solution architecture, application vertical, and end-user buying power concentration. CAGRs were derived from slope analysis of disclosed contract values and stated replacement cycle compression under regulatory mandates. Industry-specific forecast inputs encompass 3GPP release timeline acceleration, ETSI certification backlog estimates, and confidential computing hardware pilot expansion rates.
Caveats apply where geopolitical disruption to Taiwan foundry operations, accelerated EU AI Act enforcement timelines, or premature NIST post-quantum standardization could materially shift the outlook. Forecasts reflect assumptions about operator consolidation rates, regulatory compliance cost pass-through, and edge computing deployment velocity that remain sensitive to macroeconomic conditions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Managed SIEM Service Market
Cybersecurity
Morocco Cybersecurity Market
Cybersecurity
Next-Gen Firewall Market
Cybersecurity
Global Content Disarm and Reconstruction Market
Cybersecurity
Data Center Logical Security Market
Cybersecurity
Global Mobile Anti Malware Market
Cybersecurity
Mexico Cybersecurity Market
Cybersecurity
Internet of Things (IoT) Security Market
Cybersecurity
Europe Data Exfiltration Market
Cybersecurity
Vietnam Cybersecurity Market
Cybersecurity
Multi-Cloud Data Protection Market
Cybersecurity
Malaysia Cybersecurity Market
Cybersecurity
M2M Network Security Market
Cybersecurity
Cloud Network Security Market
Cybersecurity
Global Cloud Security Posture Management Market
Cybersecurity
Global Distributed Denial of Service (Ddos) Protection Market