
 Capacity Management Analytics Market | 2026-2036
Capacity Management Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Capacity Management Analytics Market Outlook
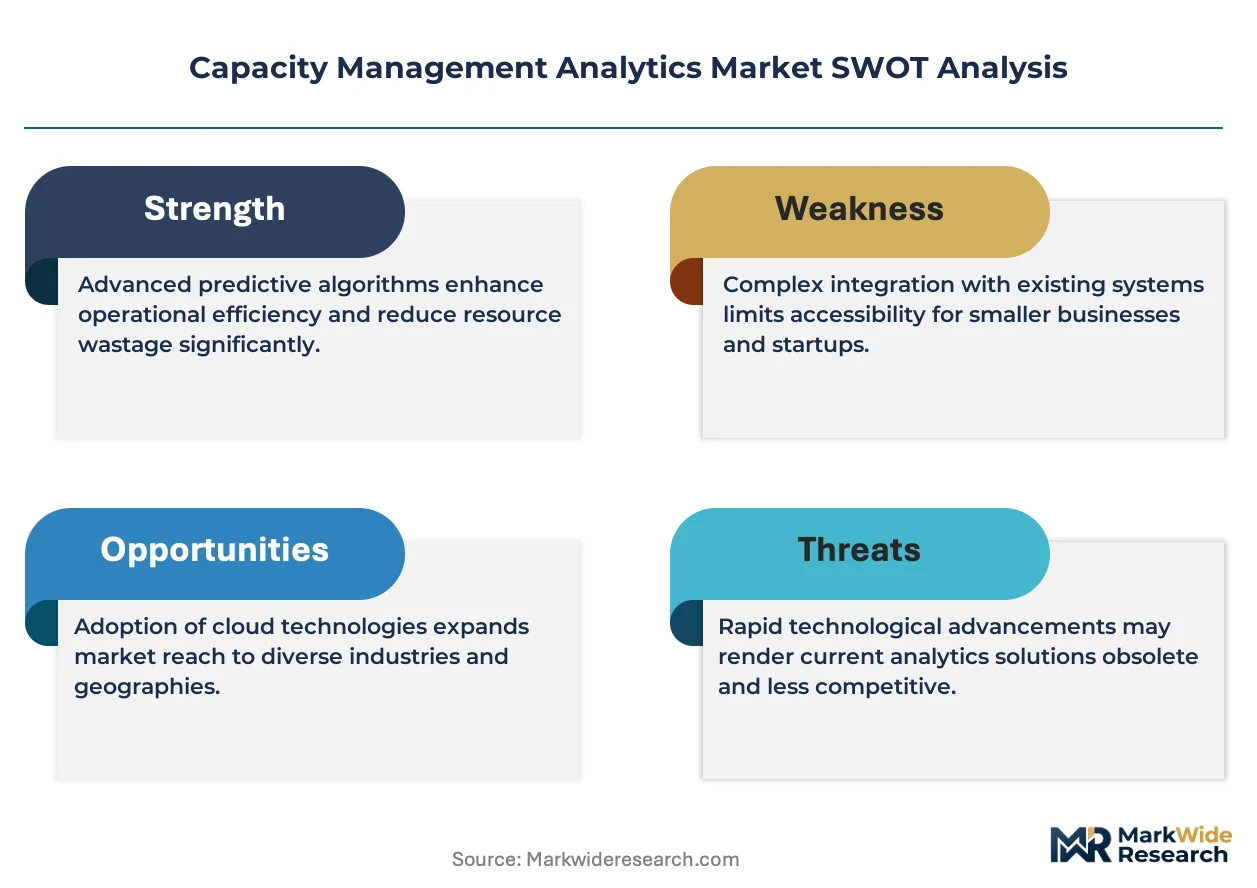
Capability gaps between full-stack platform vendors and point-solution specialists is collapsing as mid-tier buyers demand unified visibility across hybrid estates. IBM Corporation leverages its Watson analytics backbone to anchor premium positioning in predictive capacity planning. Broadcom Inc. competes through backward integration into semiconductor telemetry, feeding proprietary optimization algorithms. BMC Software, Inc. specializes in mainframe-born workload intelligence that still dominates financial services procurement cycles.
Capacity management analytics encompasses software systems that ingest real-time infrastructure telemetry—CPU utilization, memory saturation, storage IOPS, and network throughput—to forecast resource constraints and automate provisioning decisions across distributed computing environments. These platforms typically employ time-series databases with sub-minute granularity and machine learning models trained on historical workload patterns to project bottlenecks before service degradation occurs. Cloud-based deployment now leads solution uptake as enterprises retire on-premises control planes, while predictive analysis commands the fastest expansion within the solution layer due to its direct linkage with automated remediation workflows. Real-time monitoring retains the largest installed base but faces margin compression as commoditized open-source alternatives encroach on basic telemetry collection.
FERC efficiency reporting obligations and EPA data center energy disclosure rules in the United States are compelling operators to adopt optimization software with auditable carbon-intensity tracking. ISO 50001 energy management standards and EU Green Deal digital sustainability targets in Europe are similarly reshaping procurement specifications toward platforms with embedded environmental metrics. Stakeholders must evaluate whether their current tooling can satisfy emerging regulatory attestation requirements without parallel infrastructure overhauls.
Market Dynamics
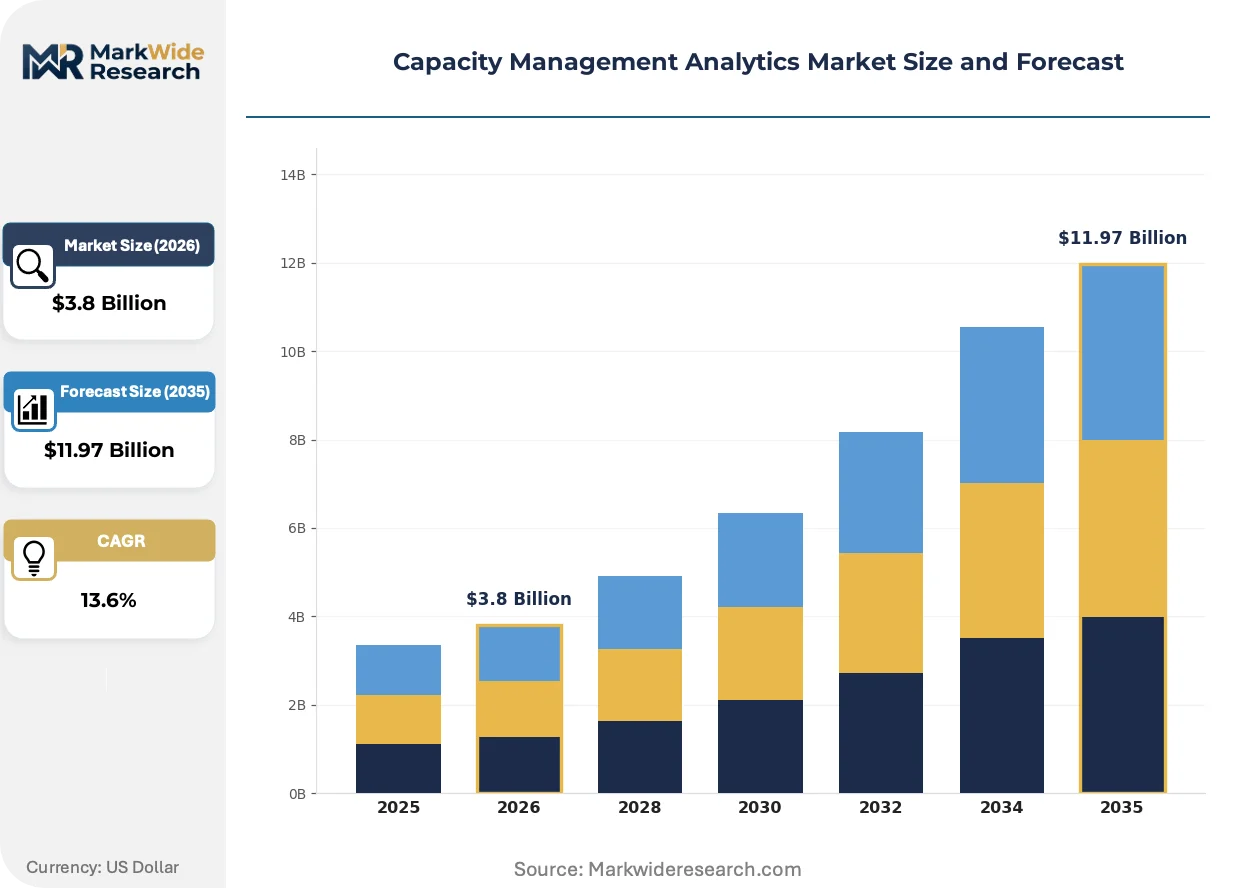
The capacity management analytics market is compressing around unified telemetry platforms as mid-tier enterprises abandon siloed monitoring tools for consolidated hybrid-cloud visibility. This consolidation pressure is eroding the historical advantage of point-solution specialists while forcing full-stack vendors to absorb mainframe-born intelligence capabilities.
Growth Catalysts
- 5G network densification:Telecommunications operators in the United States deploy cloud-native capacity platforms to manage massive small-cell proliferation and edge compute orchestration.
- EU AI Act compliance:Automated decision-making transparency mandates accelerate procurement of predictive workload management with auditable model governance.
- FERC efficiency reporting:Federal Energy Regulatory Commission disclosure obligations compel data center operators to install carbon-intensity tracking within optimization software.
Market Restraints
- Semiconductor telemetry concentration:Proprietary optimization algorithms depend on captive chip-level data feeds controlled by a narrow set of integrated hardware-software vendors.
- GDPR data residency friction:Cross-border telemetry aggregation faces structural barriers from European Union data localization requirements and Schrems II transfer restrictions.
- Open-source commoditization:Prometheus and Grafana stacks displace commercial real-time monitoring at the infrastructure edge, compressing margins for basic telemetry collection.
Strategic Opportunities
- India data center buildout:PLI scheme incentives and BIS energy efficiency standards create procurement pull for predictive cooling optimization in hyperscale facilities.
- ISO 50001 convergence:Energy management certification integration with capacity analytics opens attestation-grade pricing tiers for sustainability-conscious buyers.
- FinOps workflow embedding:Cloud cost governance platforms represent a channel innovation route for capacity intelligence to penetrate finance-led procurement cycles.
Industry Challenges
- Time-series database specialization:Sub-minute granularity engineering talent remains scarce relative to demand from autonomous remediation pipeline builds.
- Mainframe integration complexity:Financial services workload intelligence migration to distributed cloud architectures demands expensive bridge infrastructure and retained expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capacity Management Analytics Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: IT Sector, Manufacturing, Telecommunications, Healthcare Solution: Real-Time Monitoring, Predictive Analysis, Reporting Tools, Optimization Software Application: Network Management, Resource Allocation, Capacity Planning, Workload Management |
| Companies Covered | IBM Corporation, Broadcom Inc., NetApp, Inc., Hewlett Packard Enterprise Company, VMware, Inc., BMC Software, Inc., Riverbed Technology, Inc., Teoco Corporation, ITRS Group Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capacity Management Analytics Market Strategic Shifts
Telemetry ingestion architectures are fragmenting into specialized layers as buyers reject monolithic platforms. This decomposition is accelerating vendor repositioning around specific workload domains rather than universal coverage claims.
Observability pipelines are fragmenting into discrete signal paths for infrastructure metrics, application traces, and business KPIs. Platform engineering teams at Fortune 500 enterprises now assemble best-of-breed telemetry stacks rather than accepting bundled visibility suites. This decomposition is fragmenting vendor account control and compressing renewal pricing power for legacy full-stack providers.
EU Green Deal digital sustainability targets are reshaping procurement specifications toward platforms with embedded environmental metrics. ISO 50001 attestation requirements now appear in RFP technical criteria for data center operators across Germany, France, and the Netherlands. European buyers are prioritizing vendors with pre-certified carbon accounting modules to accelerate compliance timelines.
Finance-led cloud governance is displacing infrastructure-centric procurement for capacity management tools. CFO organizations now mandate FinOps-integrated analytics that translate technical metrics directly into unit economics and chargeback allocations. This behavioral shift is most visible among North American SaaS providers and digital-native retailers with material cloud spend concentration.
Capacity Management Analytics Market Segmentation
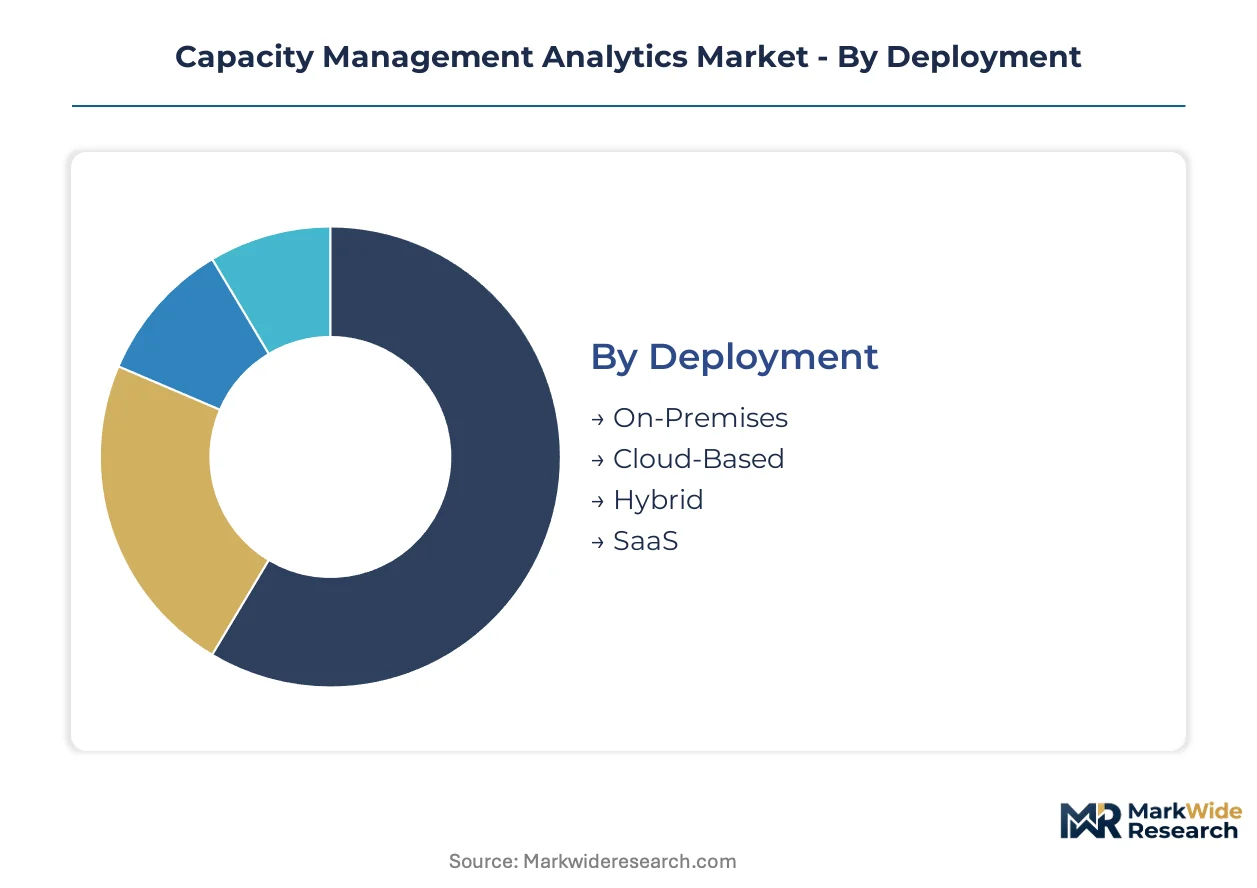
Segmentation in capacity management analytics reveals how procurement priorities diverge across infrastructure maturity levels and regulatory exposure. Buyers select deployment architectures and solution layers based on workload sovereignty requirements, energy disclosure obligations, and the complexity of their hybrid estate footprints.
Deployment:
GDPR data residency mandates and FERC audit trail requirements create sharp differentiation in how buyers evaluate control plane location.
- Cloud-Based:Cloud-native architectures ingest telemetry through managed time-series databases with elastic scaling for 5G edge workloads. Telecommunications operators in the United States deploy these platforms to manage small-cell densification and distributed compute orchestration under EPA data center energy disclosure rules.
- On-Premises:Captive infrastructure retains control over cryptographic boundaries and model governance artifacts required by EU AI Act automated decision-making transparency mandates. Financial services institutions in Germany and France maintain these deployments to satisfy CNIL and BaFin expectations for workload auditability.
- Hybrid:Split-plane architectures route sensitive telemetry to local processing while bursting predictive workloads to cloud substrates. Manufacturing facilities in the Netherlands and Belgium adopt this pattern to balance ISO 50001 attestation requirements with compute elasticity.
- SaaS:Fully managed control planes abstract database administration and model retraining operations. Mid-tier enterprises in India and Singapore select this option to accelerate time-to-value without specialized platform engineering hires.
Cloud-Based handles the majority of throughput; SaaS is gaining share fastest among finance-led procurement organizations.
End User:
Customer type determines whether procurement centers on cost governance, uptime guarantees, or sustainability attestation.
- IT Sector:Hyperscale data center operators and cloud service providers consume the largest solution volumes. These buyers embed capacity analytics directly into automated remediation pipelines for Kubernetes and serverless workloads.
- Telecommunications:5G network operators deploy predictive platforms to orchestrate radio access network resources and edge compute nodes. TRAI energy efficiency guidelines in India and FCC reporting obligations in the United States shape vendor selection criteria.
- Manufacturing:Industrial IoT deployments demand sub-second telemetry granularity for predictive maintenance integration. German automotive suppliers prioritize ISO 50001-certified modules to satisfy customer ESG audit requirements.
- Healthcare:HIPAA-covered entities in the United States impose stringent access logging and data encryption standards on capacity platforms. Hospital systems select vendors with pre-validated compliance documentation to accelerate security reviews.
IT Sector absorbs the largest solution volumes; Healthcare climbs fastest as patient data volumes expand and cyber-insurance requirements tighten.
Solution:
Margin structure varies dramatically across the solution stack, with basic telemetry collection facing open-source displacement while predictive layers command premium pricing.
- Predictive Analysis:Machine learning models trained on historical workload patterns project resource constraints before service degradation occurs. These platforms integrate directly with automated remediation workflows, justifying premium pricing through downtime avoidance.
- Real-Time Monitoring:Sub-minute granularity telemetry collection from CPU, memory, storage, and network layers retains the largest installed base. Prometheus and Grafana open-source stacks compress margins for this functionality at the infrastructure edge.
- Optimization Software:Carbon-intensity tracking and energy efficiency recommendations embed directly into procurement specifications under EU Green Deal and FERC efficiency reporting mandates. Data center operators in France and the Netherlands require pre-certified modules.
- Reporting Tools:Static dashboards and scheduled exports serve compliance documentation needs for ISO 50001 and CSRD sustainability disclosures. These solutions face pricing pressure as predictive platforms absorb visualization capabilities.
Real-Time Monitoring retains the broadest footprint; Predictive Analysis expands most quickly through linkage with autonomous infrastructure operations.
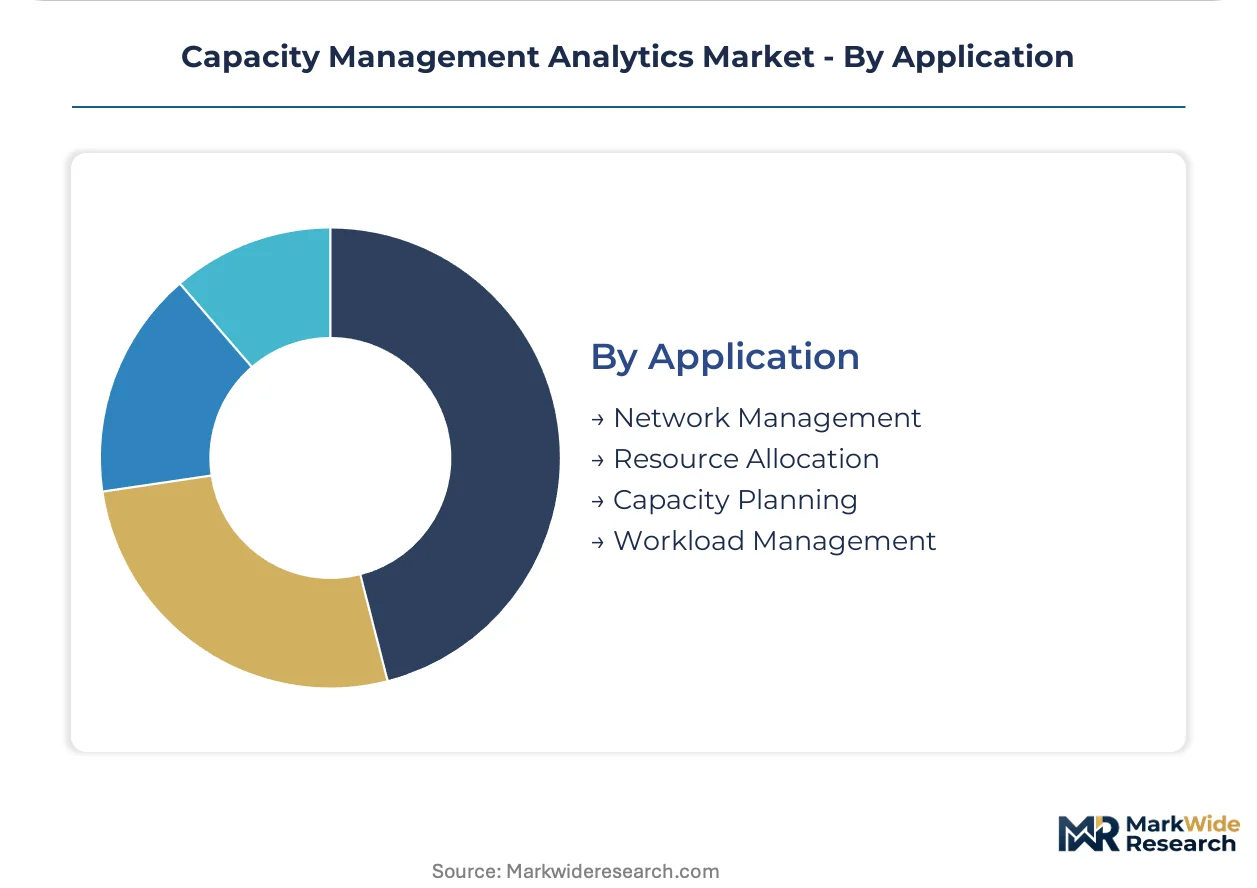
Application:
Functional use case determines integration complexity and the required depth of historical data retention.
- Workload Management:Orchestrates container and virtual machine placement across heterogeneous compute substrates. Financial services institutions demand mainframe-born intelligence integration for hybrid cloud migration scenarios.
- Capacity Planning:Long-horizon resource forecasting aligns infrastructure investment with business growth trajectories. SaaS providers in North America embed FinOps-integrated analytics to translate technical metrics into unit economics for CFO review.
- Network Management:Traffic engineering and bandwidth allocation for software-defined wide area networks. Telecommunications operators in the United States prioritize 5G radio access network optimization.
- Resource Allocation:Dynamic provisioning decisions triggered by real-time demand signals. Manufacturing facilities deploy these capabilities for seasonal production peaks and supply chain volatility absorption.
Capacity Planning anchors the largest contract values; Workload Management shows steepest expansion trajectory as platform engineering teams automate infrastructure operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States absorb capacity management analytics solutions with minimal price elasticity, while procurement teams in India and Southeast Asia negotiate aggressively on per-seat licensing. European purchasers occupy a middle ground, prioritizing compliance-grade attestations over pure cost optimization.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth deploy predictive platforms to manage Kubernetes orchestration at massive scale. FERC efficiency reporting obligations and EPA data center energy disclosure rules compel carbon-intensity tracking integration. The Ashburn-Loudoun County corridor anchors the nation's densest concentration of cloud infrastructure, driving demand for automated remediation pipelines.
Germany
Automotive suppliers and industrial manufacturers in Bavaria and Baden-Württemberg prioritize ISO 50001-certified capacity modules for customer ESG audits. BaFin supervisory expectations and EU AI Act transparency mandates shape procurement specifications toward auditable model governance. Frankfurt's financial services cluster maintains on-premises control planes to satisfy CNIL-aligned workload auditability requirements.
India
Hyperscale facility construction in Maharashtra and Karnataka accelerates procurement of predictive cooling optimization under BIS energy efficiency standards. PLI scheme incentives for data center infrastructure create pull for SaaS-delivered capacity platforms among mid-tier enterprises lacking specialized platform engineering talent. Mumbai and Bengaluru anchor the buildout, with Noida emerging as a secondary cluster.
France
Data center operators in Île-de-France and the Hauts-de-France region require pre-certified carbon accounting modules to satisfy EU Green Deal digital sustainability targets. ANSM-aligned procurement protocols in healthcare and CNIL expectations for automated decision-making transparency reshape vendor selection. Paris hosts the densest concentration of financial services workload intelligence migration projects.
Netherlands
Manufacturing facilities in North Brabant and South Holland adopt hybrid deployment patterns to balance ISO 50001 attestation requirements with compute elasticity. The Amsterdam metropolitan area concentrates colocation provider demand for optimization software with embedded environmental metrics. Dutch buyers prioritize vendors with pre-certified modules to accelerate compliance timelines under CSRD sustainability disclosure rules.
Capacity Management Analytics Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the capacity management analytics market. Full-stack platform vendors with Watson-class analytics backbones occupy premium pricing tiers, while semiconductor-telemetry-integrated specialists compete through proprietary optimization algorithms. The market structure reveals three dominant archetypes: predictive intelligence platforms, mainframe-born workload specialists, and cloud-native telemetry consolidators. Competitive dynamics center on backward integration into chip-level data feeds and absorption of mainframe intelligence capabilities into distributed architectures.
Within the predictive intelligence tier, IBM Corporation anchors premium positioning through its Watson analytics backbone, while Broadcom Inc. exemplifies semiconductor-telemetry integration feeding proprietary algorithms. BMC Software, Inc. occupies a distinct position as a mainframe-born specialist whose workload intelligence still dominates financial services procurement cycles. These three companies represent the structural fault lines between full-stack consolidation and point-solution specialization that mid-tier buyers now force together through unified visibility demands.
| Leading Market Players |
|---|
| IBM Corporation |
| Broadcom Inc. |
| NetApp, Inc. |
| Hewlett Packard Enterprise Company |
| VMware, Inc. |
| BMC Software, Inc. |
| Riverbed Technology, Inc. |
| Teoco Corporation |
| ITRS Group Ltd |
| Others |
Value Chain & Pricing Dynamics
Long-term SaaS subscription contracts lock in both supply access for cloud-native capacity platforms and predictable price visibility for telecommunications operators managing 5G densification workloads. These multi-year agreements bundle predictive analytics modules with guaranteed telemetry ingestion volumes, insulating vendors from open-source commoditization while constraining buyer flexibility under FERC efficiency mandates.
Pricing Analysis
After-sales service revenue from model retraining and compliance attestation drives lifetime value for predictive capacity platforms. Three-tier pricing structure across premium, standard, and economy levels segments buyers by ISO 50001 certification requirements and audit trail granularity. Cost compression in real-time monitoring tiers intensifies because Prometheus and Grafana stacks displace commercial telemetry at the infrastructure edge. Mid-tier enterprises in India exhibit highest price sensitivity, while hyperscale data center operators in the United States absorb premium pricing with minimal elasticity.
Supply Chain Analysis
Just-in-time talent acquisition for time-series database engineers constrains platform engineering throughput, forcing vendors to maintain strategic stockpiles of specialized personnel through acquihires and university partnerships. Software development concentrates in the United States, India, and Germany, with cloud infrastructure provisioning anchored in hyperscale facilities across Northern Virginia, Mumbai, and Frankfurt. Proprietary optimization algorithms draw from captive semiconductor telemetry feeds controlled by integrated hardware-software vendors. Single-source vulnerability in chip-level data access threatens algorithm differentiation. Distribution runs through direct enterprise sales teams and hyperscaler marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as mid-tier enterprises abandon siloed point solutions for unified hybrid-cloud visibility platforms, compressing vendor pricing power and forcing consolidation responses across the competitive landscape.
For Market Incumbents: Consolidate mainframe-born workload intelligence capabilities into distributed cloud architectures before financial services procurement cycles shift entirely to cloud-native alternatives. Absorb specialized time-series database engineering talent through targeted acquihires to defend algorithm differentiation against open-source telemetry stacks. Prioritize backward integration into semiconductor telemetry feeds to secure proprietary optimization data access. For New Entrants and Emerging Players: Differentiate on FinOps-integrated analytics that translate technical capacity metrics directly into CFO-facing unit economics and chargeback allocations. Target healthcare sector procurement in the United States, where HIPAA-covered entities demand pre-validated compliance documentation and cyber-insurance requirements tighten. Penetrate through channel partnerships with cloud cost governance platforms rather than direct infrastructure sales. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors predictive intelligence platforms with embedded sustainability attestation capabilities over commoditized real-time monitoring vendors. Acquisition targets should display ISO 50001 pre-certification and established relationships with European data center operators facing CSRD disclosure deadlines. Watch for inflection when BIS energy efficiency standard enforcement accelerates India's hyperscale buildout beyond PLI scheme incentives.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies telemetry ingestion across hybrid estates for mid-tier enterprise buyers abandoning siloed tools. |
| Acquisition of Specialist Firm | Absorbs scarce time-series database engineering talent for autonomous remediation pipeline development. |
| Strategic Partnership | Embeds capacity intelligence into FinOps workflows penetrating finance-led procurement cycles. |
| Geographic Expansion | Establishes local presence in Maharashtra and Karnataka to capture PLI-driven hyperscale demand. |
| Green Certification Program | Pre-certifies carbon accounting modules accelerating EU Green Deal compliance timelines for Dutch buyers. |
Study Parameters
Desk research of SEC filings from hyperscale data center operators, hyperscaler capex disclosures, and EPA energy reporting databases preceded structured interviews with platform engineering directors, IT procurement officers, and telecommunications network planners. Primary fieldwork combined with secondary validation across FERC efficiency filings, ISO 50001 certification registries, and EU AI Act implementation guidance. Bottom-up deployment model sizing triangulated against top-down market value estimates from infrastructure software spending analysis.
Variance decomposition across deployment architectures, solution layers, and regional regulatory clusters shaped the analytical framework over the projection horizon. Modeled dimensions encompassed cloud-native versus on-premises control plane location, predictive versus real-time solution functionality, and vertical segmentation by telecommunications, financial services, and manufacturing end-use. CAGRs derived from elasticity-adjusted adoption curves and infrastructure investment trajectories. Forecast inputs included 5G small-cell densification schedules and data center PUE improvement mandates.
The analysis sits within stated boundaries; outcomes outside sustained hyperscale capital expenditure growth or abrupt regulatory enforcement acceleration would require recalibration. Forecasts reflect assumptions regarding open-source telemetry displacement rates and mainframe migration timelines. Revision becomes warranted when EU AI Act transparency mandate enforcement crosses thresholds triggering wholesale control plane relocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Israel ICT Market
Analytics
Product Analytics Market
Analytics
Asia-Pacific Contact Center Analytics Market
Analytics
Content Intelligence Market
Analytics
Hadoop Big Data Analytics Solution Market
Analytics
India Big Data Technology and Service Market
Analytics
Spend Analytics Software Market
Analytics
Sentiment Analytics Market
Analytics
Big Data Analytics in Automotive Market
Analytics
Europe Location Data Analytics Market
Analytics
Middle East Geospatial Analytics Market
Analytics
Pandemic Analytics Market
Analytics
HR Analytics Market
Analytics
Supply Chain Big Data Analytics Market
Analytics
Global Big Data Analytics in Telecom Market
Analytics
Geospatial Analytics Market