
 Global Mobile Anti Malware Market | 2026-2036
Global Mobile Anti Malware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Anti Malware Market Foresight
Subscription-based threat intelligence feeds is repositioning how vendors monetize mobile defense, shifting perpetual licenses toward recurring revenue models. McAfee, LLC leverages its carrier partnerships to pre-install protection on Android devices across North American telecom channels. Bitdefender anchors its competitiveness in heuristic detection engines that reduce false positives on iOS platforms. Kaspersky specializes in behavioral analysis for enterprise BYOD environments, particularly in European financial sectors.
Mobile anti malware encompasses software systems that detect, quarantine, and neutralize malicious code targeting smartphones and tablets, typically operating through real-time scanning engines that process application signatures against threat databases exceeding 500 million discrete indicators. The technology serves to protect sensitive data transmissions, prevent unauthorized device access, and maintain operational integrity of mobile-dependent business workflows. Cloud-based deployment modes are capturing the fastest expansion as enterprises abandon on-premise appliance models for elastic, API-driven security orchestration. Android platform protection retains the largest absolute volume given the operating system's open architecture and dominant handset share, though iOS security spend per device runs higher due to stricter sandboxing requirements and premium enterprise user profiles.
The U.S. Federal Trade Commission scrutinizes mobile privacy practices under Section 5 authority, while the EU AI Act imposes conformity assessments on automated threat detection systems deployed across member states. India's Telecom Regulatory Authority mandates incident reporting timelines that compress vendor response cycles. Stakeholders must weigh compliance fragmentation against the operational efficiency of unified global security stacks.
Market Dynamics
Cloud-native security orchestration is compressing deployment cycles for mobile threat defense, forcing vendors to abandon appliance-based architectures in favor of API-driven elastic infrastructure that scales with enterprise device fleets.
Growth Catalysts
- GDPR Article 32 mandates:European enterprises must implement technical measures ensuring mobile data processing security, creating procurement urgency for endpoint protection suites across banking and healthcare verticals.
- Zero-trust architecture adoption:Financial services firms in the United States are mandating continuous device verification, expanding budgets for mobile threat detection that validates every access request regardless of network perimeter.
- Ransomware targeting payment applications:Attack campaigns against mobile banking interfaces in India are compelling regional lenders to harden transaction security layers, accelerating vendor engagement cycles.
Market Restraints
- Sandboxing fragmentation:iOS and Android operate incompatible security architectures, forcing vendors to maintain dual development tracks that inflate engineering overhead and compress margins.
- False positive tolerance thresholds:Enterprise security operations centers reject solutions exceeding 0.1% false positive rates on behavioral detection, limiting heuristic engine innovation.
- Carrier pre-installation gatekeeping:North American telecom operators control device-level security distribution, creating supply concentration that disadvantages independent software vendors without carrier partnerships.
Strategic Opportunities
- BYOD policy expansion in Germany:Financial sector employers are formalizing bring-your-own-device frameworks, opening enterprise-grade mobile security procurement to previously unmanaged personal handset fleets.
- EU AI Act conformity assessments:Automated threat detection systems require third-party validation, creating certification service revenue streams for vendors with established compliance documentation.
- API-first security orchestration:Convergence between mobile anti-malware and SIEM platforms enables unified telemetry pipelines, allowing vendors to embed detection engines within broader security stacks.
Industry Challenges
- Threat intelligence analyst scarcity:Mobile-specific malware reverse engineering expertise concentrates among contractors in Israel and the United States, inflating talent acquisition costs for product development teams.
- Cross-platform certification timelines:Apple's App Store review processes and Google's Play Protect validation create sequential approval bottlenecks that delay feature parity between iOS and Android releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Anti Malware Market |
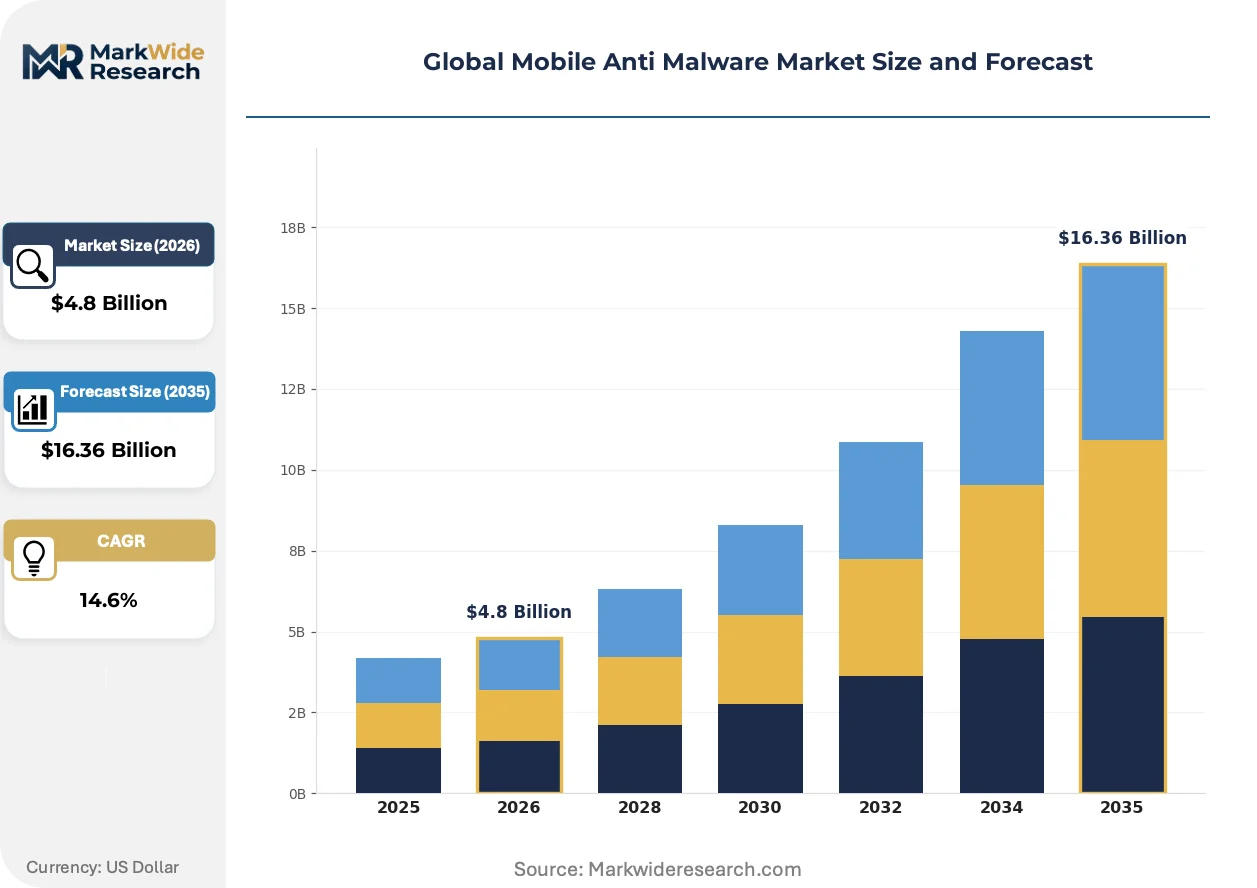
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Signature-Based, Heuristic, Behavior-Based, Cloud-Based, Hybrid Platform: Android, iOS, Windows Mobile, Blackberry OS, Symbian Deployment Mode: On-Premise, Cloud, Hybrid Cloud, Managed Services End User: Telecom Operators, Financial Institutions, Educational Institutes, Government Agencies, Enterprises |
| Companies Covered | McAfee, LLC, Bitdefender, Trend Micro Incorporated, Gen Digital Inc., Kaspersky, ESET, Lookout, Inc., Malwarebytes Inc., Sophos Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Anti Malware Market Shifts & Advancements
Behavioral biometrics and on-device machine learning are converging to create authentication frameworks that operate independently of network connectivity, fundamentally altering how mobile security validates user identity.
On-device federated learning is electrifying privacy-preserving threat detection by training models locally on handset telemetry without centralizing sensitive user data. Healthcare and defense contractors in Switzerland and Singapore are piloting these architectures for regulated environments. This compression of data residency risk is electrifying vendor competitiveness in jurisdictions with strict cross-border transfer prohibitions.
The EU AI Act imposes conformity assessments on automated threat detection systems deployed across member states, requiring vendors to document training data provenance and algorithmic decision boundaries. Industrial consequence includes extended product launch timelines and documentation burdens that favor established vendors with dedicated compliance functions. European financial institutions are responding by consolidating procurement around suppliers with pre-validated AI system registrations.
Enterprise buyers are unbundling mobile security from broader endpoint protection platforms, creating direct procurement relationships with specialized vendors rather than accepting bundled suites from incumbent providers. This channel disintermediation is most visible among mid-market financial services firms in the United States, where CISOs are mandating best-of-breed mobile stacks separate from desktop security contracts.
Global Mobile Anti Malware Market Segmentation
Mobile anti-malware buyers fragment sharply by technical sophistication, platform exposure, and compliance burden. Procurement patterns diverge between carriers seeking pre-installed scale and financial institutions demanding behavioral precision.
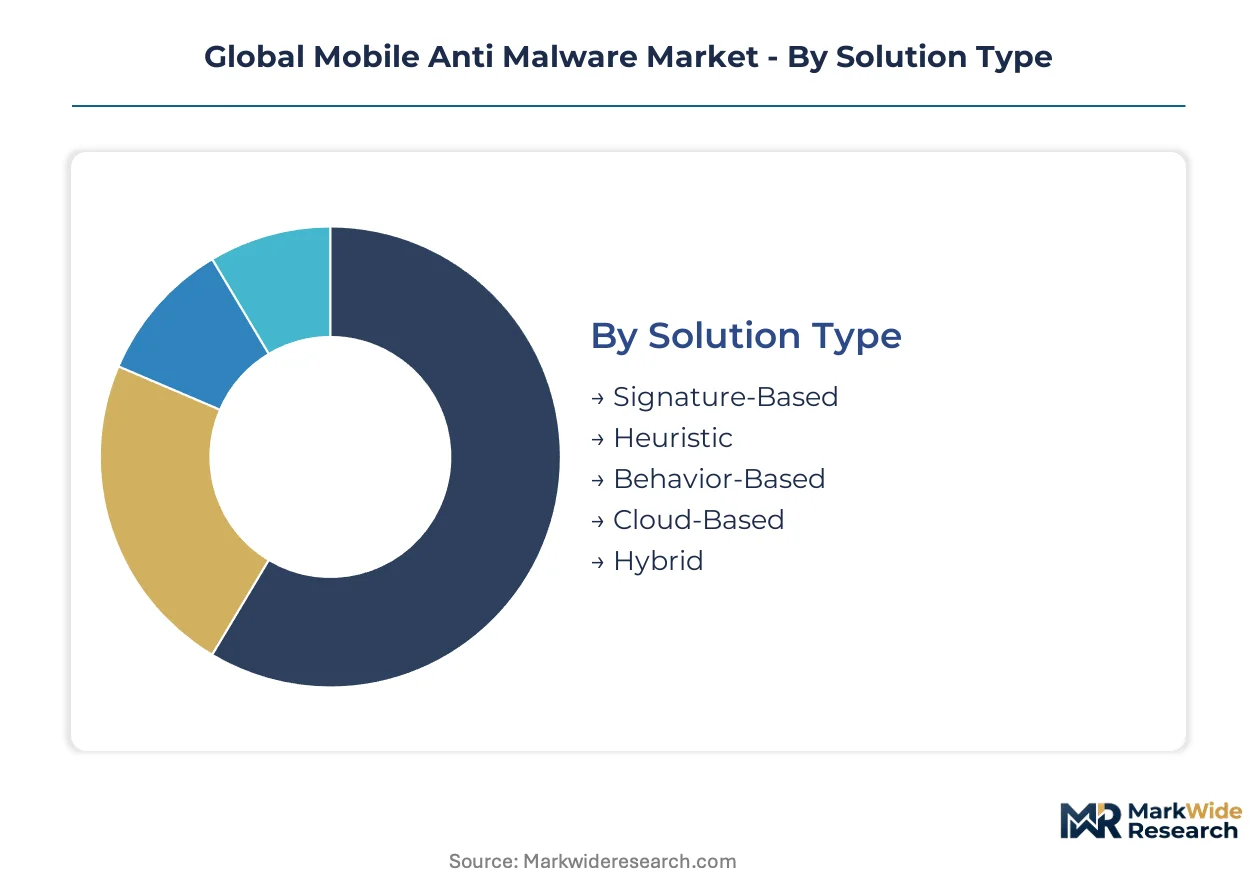
Solution Type:
Security teams select detection methodologies based on false-positive tolerance and threat-actor sophistication they face.
- Signature-Based:Pattern-matching engines compare file hashes against threat databases exceeding 500 million indicators. Financial institutions in India deploy these for payment app hardening where known ransomware variants dominate attack campaigns.
- Behavior-Based:Anomaly detection monitors system calls, network traffic, and API usage in real-time. European banks under GDPR Article 32 mandates favor these engines for BYOD environments where zero-day exposure is acute.
- Heuristic:Rule-based analysis identifies suspicious code structures without exact signature matches. German automotive suppliers use these for supply-chain device protection.
- Cloud-Based:Elastic threat intelligence processing offloads scanning to remote infrastructure. Singapore healthcare contractors pilot these for federated learning compliance.
- Hybrid:On-device engines synchronize with cloud analytics for layered defense. U.S. federal contractors favor these for FedRAMP-aligned mobile deployments.
Signature-based engines lead volumes today; behavior-based detection is gaining share fastest.
Platform:
Operating system architecture dictates sandboxing capabilities and vendor development overhead.
- Android:Open-source kernel and sideloading permissions create broad attack surface. Indian mobile lenders and Southeast Asian fintechs drive procurement volume given the platform's dominant handset share in emerging markets.
- iOS:Stricter app review and hardware-encrypted enclaves reduce baseline vulnerability. U.S. enterprise security spend per device runs highest here due to premium user profiles and MDM integration requirements.
- Windows Mobile:Legacy enterprise deployments in logistics and field services maintain residual demand. Eastern European industrial firms still maintain pockets of usage.
- Blackberry OS:Specialized government and defense installations persist in Canada and the United Kingdom. National security agencies mandate these for classified mobile communications.
- Symbian:Embedded industrial control systems in legacy manufacturing environments represent vanishing niche. Some Middle Eastern utility operators retain these for SCADA-adjacent mobile terminals.
Android protection commands absolute volume; iOS security expenditure per device climbs steepest.
Deployment Mode:
Enterprise infrastructure maturity and data residency requirements shape delivery architecture choices.
- On-Premise:Appliance-hosted scanning within corporate network perimeters. Swiss pharmaceutical manufacturers and Saudi defense contractors insist on these for air-gapped compliance.
- Cloud:API-driven elastic infrastructure scales with device fleet fluctuations. U.S. mid-market financial services firms are abandoning appliance models fastest for this architecture.
- Hybrid Cloud:Sensitive scanning localizes to on-premise nodes while threat intelligence feeds pull from cloud repositories. German automotive OEMs favor these for supplier network orchestration.
- Managed Services:Third-party SOC operators handle mobile threat monitoring and incident response. Australian healthcare networks and Singaporean government agencies outsource mobile security operations here.
On-premise retains entrenched base in regulated verticals; cloud deployment expands most quickly.
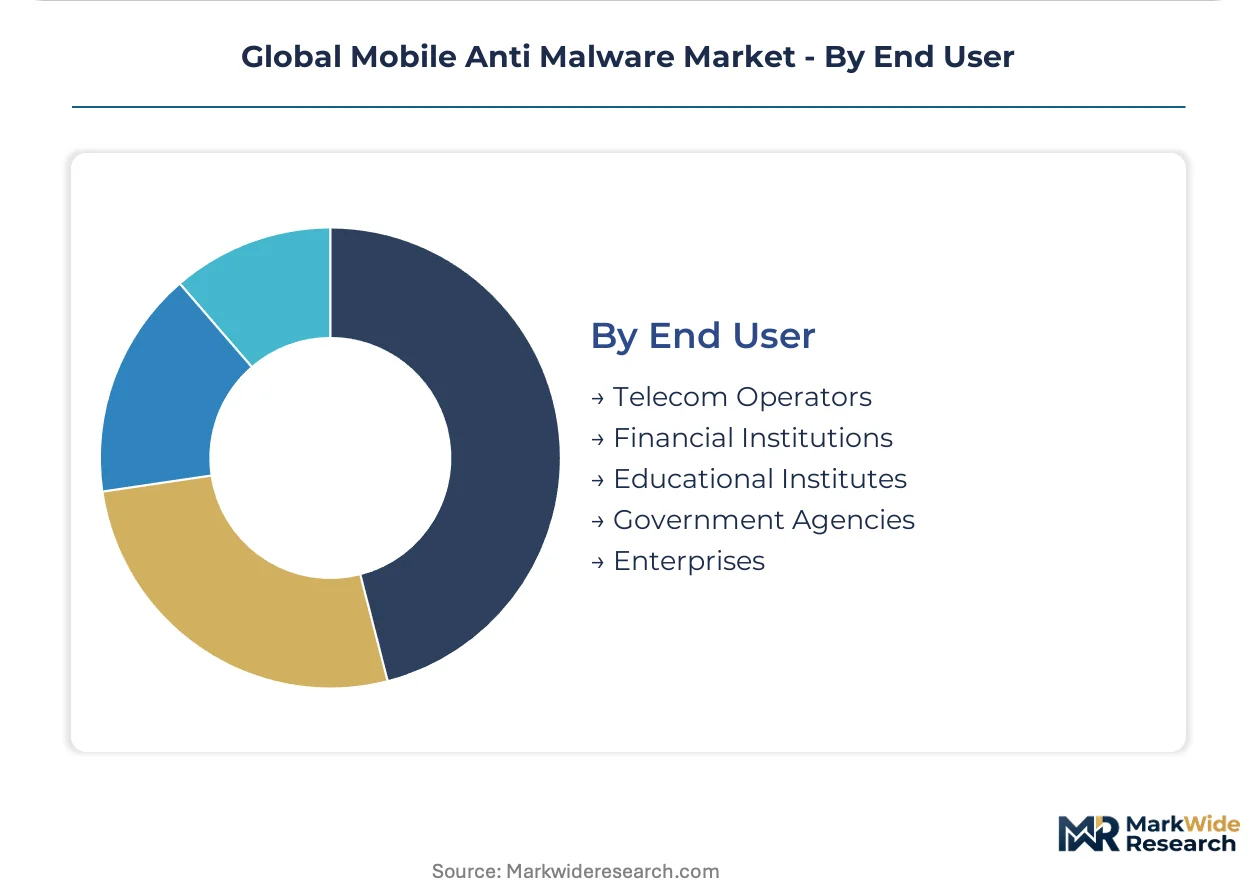
End User:
Procurement authority and compliance exposure create distinct buying center dynamics across sectors.
- Financial Institutions:Mobile banking interfaces face targeted ransomware campaigns. Indian regional lenders and U.S. credit unions are expanding dedicated mobile security budgets separate from desktop endpoint contracts.
- Telecom Operators:Carrier-controlled pre-installation channels dominate consumer distribution. North American operators like Verizon and AT&T gate device-level protection for Android handsets.
- Government Agencies:FedRAMP, IRAP, and comparable certifications mandate validated supply chains. U.S. federal and Australian state governments consolidate procurement around pre-approved vendor lists.
- Enterprises:BYOD formalization drives unmanaged personal device protection. German financial sector employers are opening enterprise-grade procurement to previously unsanctioned handset fleets.
- Educational Institutes:Student and faculty device diversity complicates unified policy enforcement. U.S. public university systems and Indian technical institutes balance open access with phishing protection.
Financial institutions anchor revenue concentration; government agencies drive certification complexity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile security expenditure in the United States outpaces German investment on a per-device basis, while Indian financial institutions deploy protection at scale across the largest Android handset fleet globally.
United States
Zero-trust mandates from federal contractors and mobile banking proliferation drive procurement volume. The FTC scrutinizes privacy practices under Section 5 authority, compelling vendors to document data handling protocols. Silicon Valley clusters anchor cloud-native security development, while New York financial services firms mandate continuous device verification.
Germany
BYOD formalization in banking and automotive sectors expands enterprise-grade protection to personal handsets. GDPR Article 32 mandates technical security measures for mobile data processing, accelerating endpoint protection procurement. Bavarian automotive OEMs favor hybrid cloud deployments for supplier network orchestration.
India
Regional lenders harden transaction security as ransomware campaigns target mobile banking interfaces. TRAI mandates compressed incident reporting timelines, forcing vendors to accelerate response cycles. Mumbai and Bangalore fintech clusters drive signature-based detection deployment for payment app protection.
Singapore
Healthcare contractors pilot federated learning architectures to preserve data residency compliance. The national cybersecurity agency validates mobile threat detection systems for government procurement. Biomedical research clusters demand on-device machine learning that operates without cross-border data transfer.
Switzerland
Pharmaceutical manufacturers insist on air-gapped on-premise scanning for intellectual property protection. Swissmedic-aligned documentation requirements favor vendors with established compliance functions. Basel and Zurich clusters anchor healthcare security procurement for regulated clinical trial environments.
Global Mobile Anti Malware Market Competitive Landscape
Top-tier vendors anchor enterprise and carrier channels, while mid-tier specialists compete on behavioral detection precision and API integration depth. The market structure reflects consolidation around pre-installation partnerships and fragmentation among best-of-breed mobile specialists. Three archetypes dominate: carrier-integrated platforms, heuristic engine specialists, and cloud-native API-first vendors. Competitive moves concentrate on strategic carrier partnerships and M&A to acquire behavioral biometrics capabilities.
Within the carrier-integrated tier, McAfee, LLC and Lookout, Inc. occupy positions shaped by North American telecom distribution gatekeeping. Bitdefender exemplifies the heuristic detection archetype, anchoring competitiveness in false-positive reduction for iOS environments. These three represent distinct strategic vectors—pre-installation scale, engine precision, and platform-specific optimization—that define competitive positioning across enterprise and consumer segments.
| Leading Market Players |
|---|
| McAfee, LLC |
| Bitdefender |
| Trend Micro Incorporated |
| Gen Digital Inc. |
| Kaspersky |
| ESET |
| Lookout, Inc. |
| Malwarebytes Inc. |
| Sophos Ltd. |
| Others |
Supply & Pricing Matrix
Cloud-native security orchestration is simultaneously compressing vendor cost structures and concentrating procurement leverage among carrier-integrated platforms, creating asymmetric pricing power between API-first specialists and appliance-dependent incumbents. Subscription-based threat intelligence feeds now dominate monetization, shifting perpetual license revenue toward recurring models that reward scale economies in threat database maintenance.
Pricing Analysis
Capacity additions in Singapore and India are reshaping price floors for cloud-based deployment tiers, compressing margins for on-premise appliance vendors. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-validated government contracts from mid-market financial services bundles and consumer pre-installation volumes. Price differentiation hinges on certification grade and threat intelligence refresh frequency. Cost compression in the economy tier is intensifying because carrier pre-installation gatekeeping concentrates distribution control among North American telecom operators. Government agencies exhibit lowest price sensitivity due to compliance mandates, while educational institutes face acute budget constraints.
Supply Chain Analysis
Freight costs for hardware security modules and specialized threat intelligence appliances remain marginal given the industry's software-dominant delivery model. Engineering talent concentrates in Israel, the United States, and Estonia, with mobile malware reverse expertise anchoring product development cycles. Raw material dependencies center on cloud infrastructure access, GPU compute for ML training, and proprietary threat data licensing. Single-source vulnerability in behavioral biometrics IP creates acquisition risk for vendors lacking in-house R&D. Distribution runs through carrier partnerships, direct enterprise sales, and managed security service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where GDPR Article 32 mandates and the EU AI Act conformity requirements continuously expand compliant vendor addressable demand.
For Market Incumbents: Deepen carrier partnership exclusivity to defend against API-first challengers, while accelerating FedRAMP and IRAP certification investments to capture government procurement consolidation. Threat intelligence analyst scarcity in Israel and the United States inflates talent acquisition costs, making vertical integration into automated detection R&D a critical margin defense lever. For New Entrants and Emerging Players: The price-point gap between premium FedRAMP-validated suites and economy-tier consumer pre-installation opens white space in mid-market financial services. Target German automotive suppliers and Swiss pharmaceutical manufacturers with hybrid cloud deployments that satisfy data residency without full on-premise appliance overhead. Lead with API-first SIEM integration to bypass carrier gatekeeping. For Investors and Strategic Acquirers: Valuations sit cheapest among heuristic engine specialists with iOS optimization capabilities but limited enterprise channel presence. Five-to-ten-year viability favors vendors with pre-validated AI system registrations under EU AI Act frameworks. Watch for TRAI-mandated incident reporting timeline compression in India as an inflection signal for vendor response cycle competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier Partnership Expansion | Verizon and AT&T pre-installation channels lock in Android distribution scale across North America. |
| Behavioral Biometrics Acquisition | On-device ML authentication capabilities differentiate iOS enterprise offerings against signature-based competitors. |
| FedRAMP Validation Investment | U.S. federal contractor mandates create procurement moats around cloud-native security orchestration platforms. |
| EU AI Act Conformity Pre-Registration | Third-party validation documentation accelerates European financial institution procurement cycles. |
| Federated Learning Architecture Pilot | Singapore healthcare and Swiss pharmaceutical demand for data-resident threat detection opens regulated verticals. |
Research Methodology
Multiple input streams — primary interviews with CISOs at financial institutions and government agencies, threat intelligence vendor executive discussions, and carrier partnership managers — were reconciled against secondary validation from SEC filings, TRAI regulatory disclosures, and EU AI Act implementation guidance. Bottom-up triangulation across deployment mode adoption curves and top-down reconciliation with endpoint protection market sizing anchored volume estimates.
Data-stream reconciliation applied segmentation modeling across solution type, platform architecture, deployment mode, and end-user vertical throughout the forecast period. CAGRs derived from elasticity-adjusted adoption curves incorporating GDPR enforcement timelines and zero-trust architecture mandate propagation. Cloud infrastructure capex disclosures and mobile banking penetration statistics informed platform-specific growth differentials.
Caveats apply where TRAI reporting timeline revisions or EU AI Act conformity assessment delays could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Hungary Cybersecurity Market
Cybersecurity
Post-Quantum Cryptography Market
Cybersecurity
India Cybersecurity Market
Cybersecurity
Cryptojacking Solution Market
Cybersecurity
Cyber Security Consulting Market
Cybersecurity
Russia Cybersecurity Market
Cybersecurity
SD-WAN Security Market
Cybersecurity
Europe IoT Security Market
Cybersecurity
Virtualization Security Tools Market
Cybersecurity
Global Information Security Consulting Market
Cybersecurity
Global API Security Market
Cybersecurity
Botnet Detection Market
Cybersecurity
Austria Cybersecurity Market
Cybersecurity
Brazil Cybersecurity Market
Cybersecurity
Global Cyber Threat Intelligence Market
Cybersecurity
Bangladesh Cybersecurity Market