
 Mobile Sharing Power Bank Rental Service Market | 2026-2036
Mobile Sharing Power Bank Rental Service Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Sharing Power Bank Rental Service Market Insights
A shift from single-source hardware procurement to multi-source manufacturing is decoupling supply risk from brand expansion timelines. Energy Monster leverages its station-based footprint across Chinese commercial districts to sustain density advantages. Xiaodian Technology anchors its model through kiosk partnerships with convenience retail chains. Jiedian competes on unit-based flexibility, deploying compact banks in ride-sharing vehicles and food-delivery networks.
Mobile sharing power bank rental service denotes a distributed energy-access infrastructure where lithium-ion cells rated between 5000 mAh and 20000 mAh are dispensed through automated stations or mobile-activated units for temporary consumer use, primarily addressing on-the-go charging deficits in urban environments. Portable charger units dominate transaction volume due to universal compatibility, while wireless charger deployments represent the fastest-growing segment as Qi-enabled handset penetration rises among business travelers. The service model dimension shows pay-per-use retaining the largest user base, though corporate packages capture superior per-account economics through bulk subscription terms with hospitality and event venues.
China's SAMR enforces GB 31241 certification for portable lithium-ion cells, directly determining which hardware suppliers qualify for network deployment. The EU F-Gas Regulation and REACH chemical restrictions shape battery composition standards for any European expansion, while Japan's METI mandates PSE marking for electrical appliances entering that market. Stakeholders must track evolving battery recycling mandates across these jurisdictions, as extended producer responsibility frameworks will soon dictate end-of-life collection logistics and unit refurbishment economics.
Market Dynamics
China's GB 31241 certification regime for lithium-ion cells is compressing hardware supplier pools and forcing network operators to rebuild procurement relationships around qualified cell manufacturers.
Growth Catalysts
- Transit hub density:Metro systems in Bangkok, Jakarta, and Ho Chi Minh City generate concentrated foot traffic that sustains station-level utilization rates above breakeven thresholds.
- Qi wireless proliferation:Handset manufacturers embedding native wireless charging coils are eliminating cable compatibility friction for business travelers in airport terminals.
- SAMR certification consolidation:China's unified safety framework reduces testing duplication for cross-provincial network expansion, accelerating deployment timelines in tier-two cities.
Market Restraints
- Cobalt price volatility:Lithium-ion cathode chemistry dependence on DRC-sourced cobalt creates margin pressure when commodity exchanges spike.
- Station hardware concentration:Shenzhen-based enclosure manufacturers control 70% of kiosk mechanical subassemblies, creating single-source vulnerability for international operators.
- EU F-Gas compliance:Thermal management system refrigerant restrictions add engineering cost for European climate-controlled deployments.
Strategic Opportunities
- Vietnam underpenetration:Da Nang and Can Tho lack station networks despite smartphone penetration exceeding 85%, presenting first-mover density advantages.
- Event venue integration:Music festivals and convention centers in Singapore seek bulk subscription arrangements for attendee retention.
- India PLI scheme:Domestic cell manufacturing incentives could localize supply chains for operators targeting Mumbai and Delhi NCR.
Industry Challenges
- GB 31241 retesting cycles:Cell chemistry modifications trigger 90-day recertification delays that stall hardware refresh programs.
- Field technician scarcity:Station maintenance and battery swap logistics require skilled labor pools that remain thin in secondary Chinese cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Sharing Power Bank Rental Service Market |
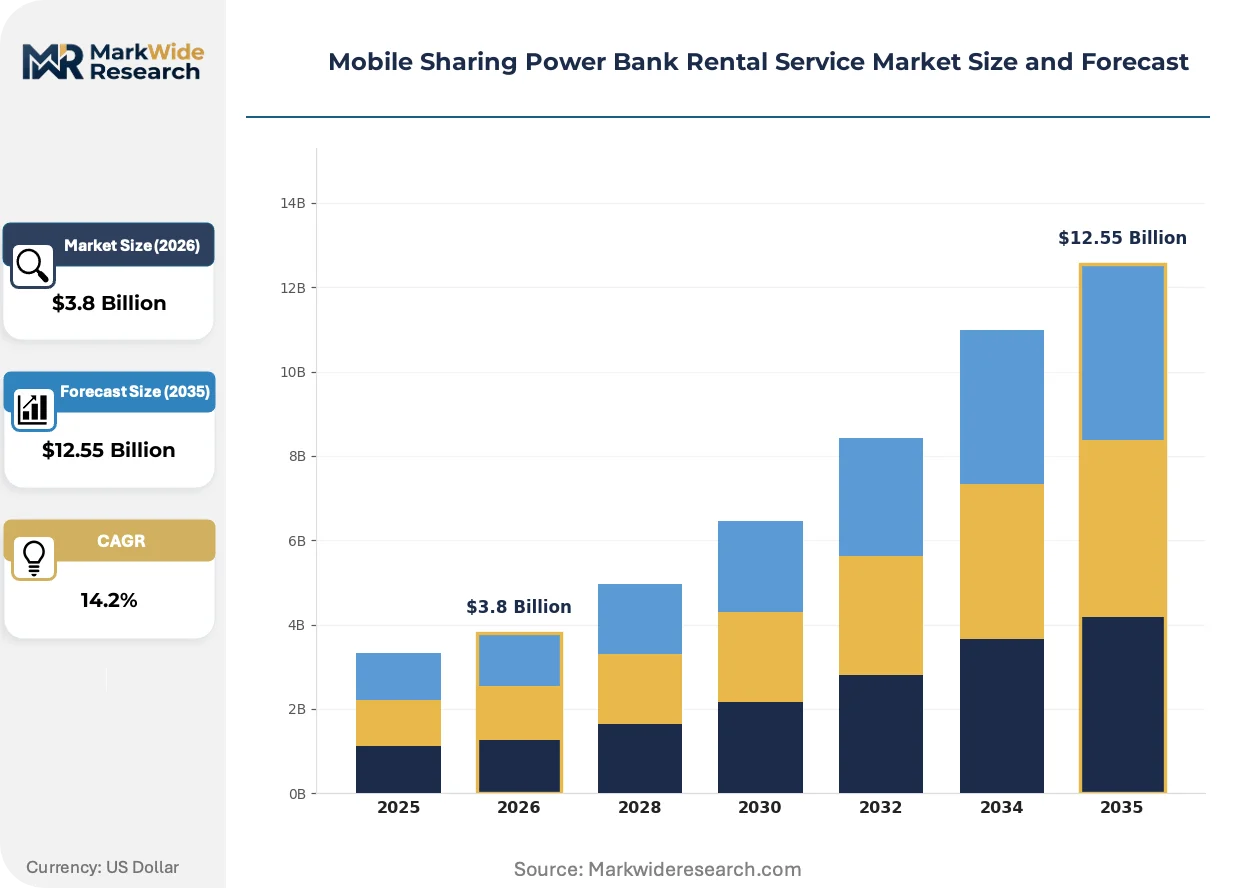
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Charger, Multi-Port Bank, Solar Power Bank, Wireless Charger Deployment: Station-Based, Unit-Based, Kiosk, Mobile Application Customer Type: Tourists, Students, Event Attendees, Business Travelers Service Model: Subscription, Pay-Per-Use, Rental, Corporate Packages |
| Companies Covered | Energy Monster, Xiaodian Technology, Jiedian, Laidian Technology, ChargedUp, Powerqube, ChargeSpot, ChargeItSpot, Anker Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Sharing Power Bank Rental Service Market Trends and Innovations
Wireless charging hardware is penetrating premium deployment locations while regulatory fragmentation around battery chemistry is forcing modular platform architectures. Network operators are simultaneously pursuing density in established corridors and piloting flexible form factors for mobility-integrated use cases.
GaN-based fast-charging circuitry is expanding into high-turnover station designs. Airport lounge operators in Dubai and Singapore are retrofitting kiosks with 65W output banks to serve laptop and tablet users. This capability compression allows single units to capture multi-device rental occasions that previously required separate hardware categories.
Japan's METI PSE marking requirements are reshaping import logistics for any operator targeting Tokyo or Osaka. The electrical appliance safety framework mandates third-party testing at designated Japanese laboratories, adding 45-60 days to deployment schedules. Vendors are responding by pre-certifying reference designs rather than customizing per-market hardware.
Corporate procurement departments at hospitality chains are consolidating vendor relationships from fragmented station-by-station contracts to master service agreements. Marriott and Hilton properties in Southeast Asia now negotiate network-wide pricing with guaranteed uptime SLAs. This buyer concentration is visible most acutely in Bangkok and Kuala Lumpur where international hotel density supports dedicated operational teams.
Mobile Sharing Power Bank Rental Service Market Segmentation
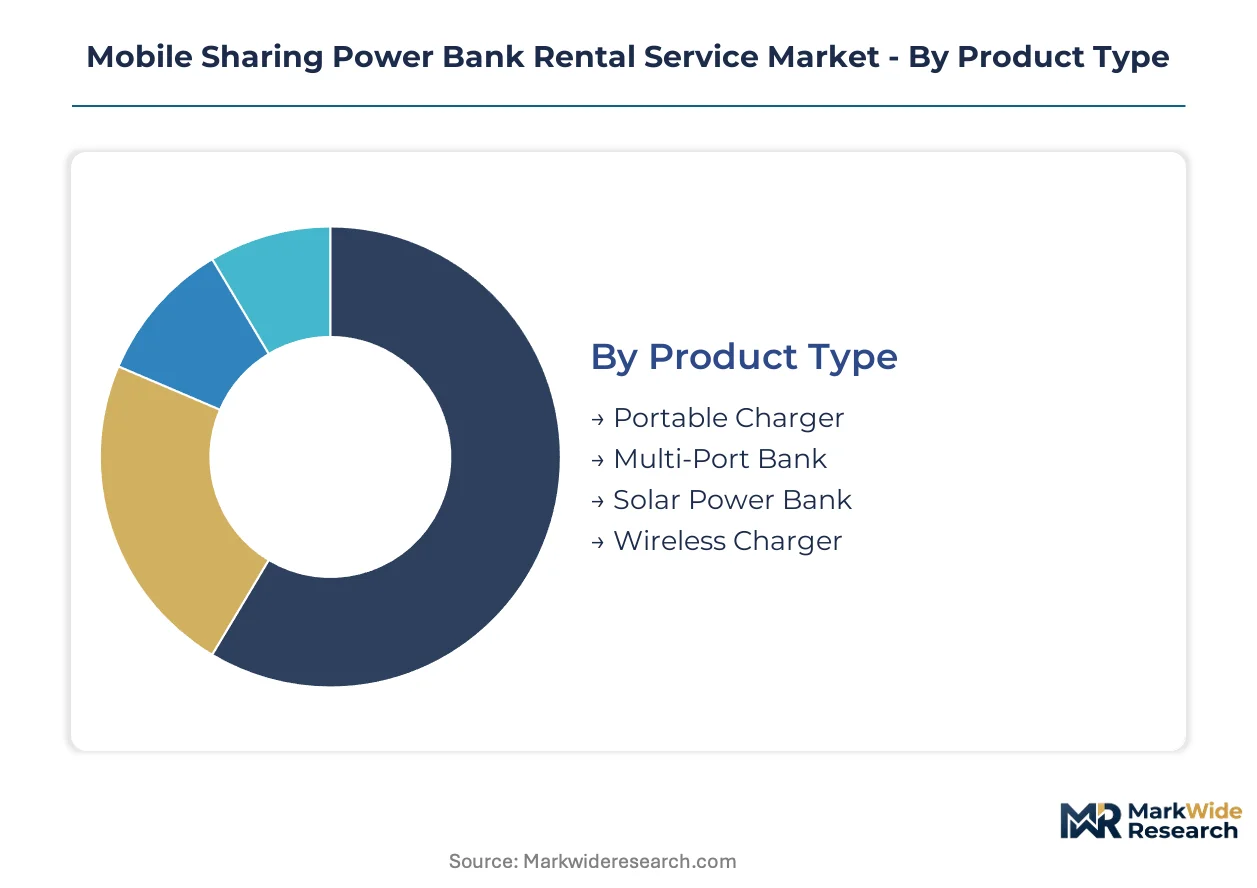
Segmentation in mobile sharing power bank rental services reveals how hardware form factors, deployment density, and pricing architectures align with distinct urban mobility patterns. Operators configure network investments around these divisions to match utilization economics against local charging infrastructure gaps.
Product Type:
Standalone units dominate high-turnover transit corridors while embedded wireless systems penetrate premium hospitality environments.
- Portable Charger:Lithium-ion cells between 5000 mAh and 20000 mAh housed in pocket-sized enclosures with USB-A and USB-C output ports. Metro stations in Bangkok and Jakarta sustain utilization rates above breakeven through universal handset compatibility and rapid swap logistics.
- Wireless Charger:Qi-enabled pads and docks eliminating cable friction for compatible handsets. Business travelers in Singapore Changi and Dubai International drive adoption as native coil penetration rises among flagship devices.
- Multi-Port Bank:Simultaneous charging capability for multiple devices serving group travelers.
- Solar Power Bank:Photovoltaic panel integration for outdoor event deployments and emergency backup scenarios.
Portable chargers lead volumes today; wireless chargers are gaining share fastest.
Deployment:
Fixed infrastructure captures commuter density while distributed units serve mobility-integrated use cases.
- Station-Based:Automated kiosks with 20-50 unit capacity positioned in commercial districts and transit interchanges. Energy Monster leverages this format across Chinese tier-one cities to sustain network density advantages against competitors.
- Unit-Based:Compact single-unit dispensers embedded in ride-sharing vehicles and food-delivery fleets. Jiedian deploys this flexible format to capture charging occasions during transport rather than at destination points.
- Kiosk:Staffed or semi-staffed retail partnerships with convenience chains enabling human-assisted pickup and return.
- Mobile Application:Pure software coordination of peer-to-peer lender networks without dedicated hardware infrastructure.
Station-based deployments anchor revenue today; unit-based formats are climbing the fastest.
Customer Type:
Usage intensity and price sensitivity diverge sharply between leisure and commercial traveler profiles.
- Business Travelers:Premium segment prioritizing reliability and speed over unit cost. Airport lounge deployments in Singapore and Dubai target this cohort with GaN-based fast-charging hardware and guaranteed availability SLAs.
- Tourists:High-frequency users concentrated in historic districts and entertainment corridors where unfamiliarity with local charging infrastructure creates dependency.
- Students:Price-sensitive campus-based demand clustering around university districts in Ho Chi Minh City and Manila.
- Event Attendees:Episodic high-density demand at music festivals and convention centers seeking bulk subscription arrangements.
Business travelers generate the highest per-transaction economics; tourists represent the largest addressable population.
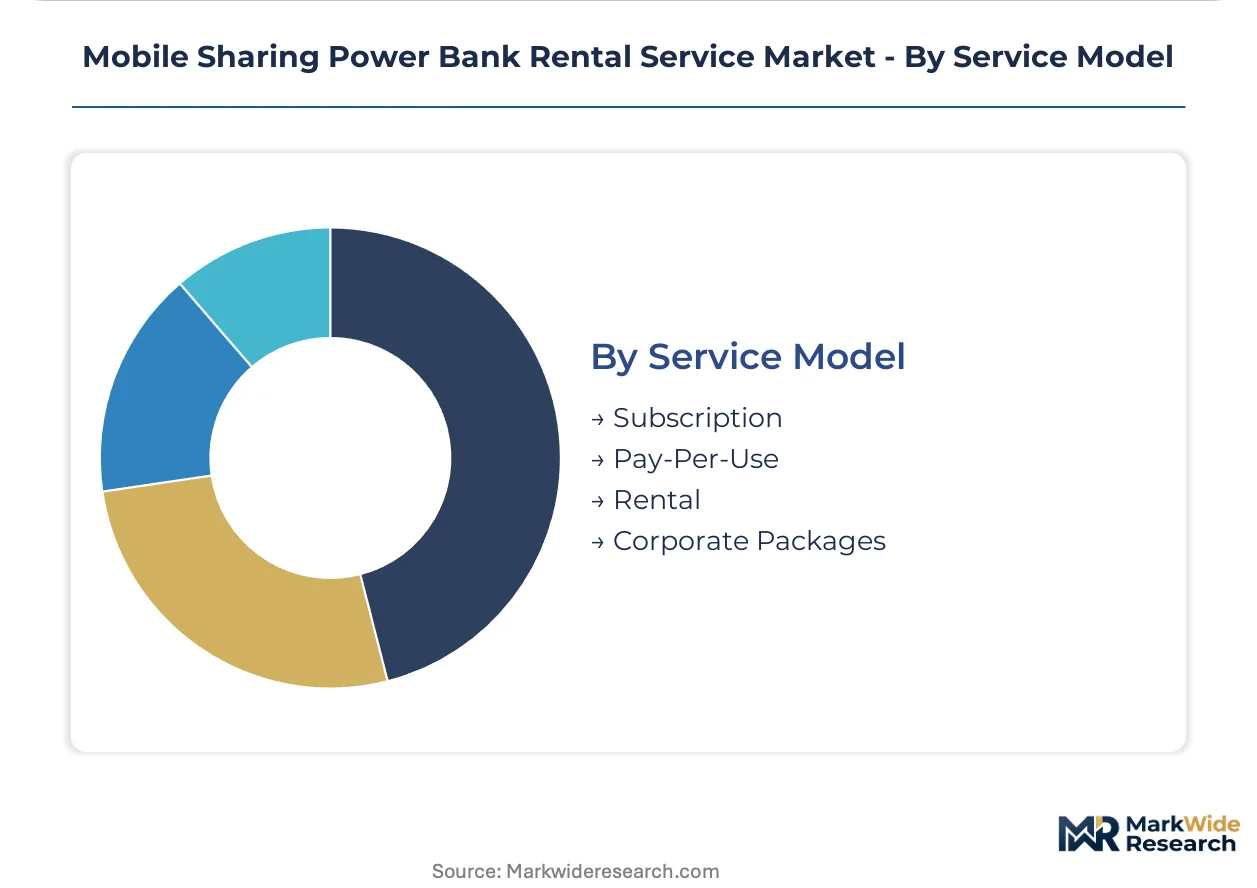
Service Model:
Pricing architecture separates casual consumption from committed commercial relationships.
- Pay-Per-Use:Per-hour or per-day rates without ongoing commitment. Retains the largest user base across Southeast Asian megacities where smartphone penetration outpaces charging infrastructure development.
- Corporate Packages:Bulk subscription terms negotiated with hospitality chains and event venues. Marriott and Hilton properties in Bangkok and Kuala Lumpur now demand network-wide pricing with guaranteed uptime SLAs.
- Subscription:Monthly or annual flat-rate access for frequent individual users.
- Rental:Extended multi-day arrangements for travelers without return logistics constraints.
Pay-per-use dominates transaction counts today; corporate packages capture superior per-account economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the hardware supply ecosystem for mobile sharing power bank networks, with enclosure manufacturers and lithium-ion cell suppliers clustering in Guangdong Province. This concentration shapes deployment economics across Southeast Asian expansion corridors and European pilot programs alike.
China
Metro systems in Beijing, Shanghai, and Guangzhou generate sustained station utilization through commuter density. SAMR's GB 31241 certification regime compresses qualified supplier pools, forcing procurement rebuilds around certified cell manufacturers. Tier-two cities in Sichuan and Shaanxi provinces accelerate network expansion as unified safety standards reduce cross-provincial testing duplication.
Singapore
Changi Airport and Marina Bay hospitality clusters drive premium wireless charging adoption among business travelers. The country's Building and Construction Authority coordinates infrastructure placement in transit terminals. Downtown commercial districts host concentrated station networks serving financial district commuters.
Japan
Tokyo and Osaka metro systems present high-frequency use cases for station-based deployments. METI mandates PSE marking through designated domestic laboratories, adding 45-60 days to hardware import schedules. Kansai International Airport operators pilot GaN-equipped kiosks targeting multi-device business travelers.
Thailand
Bangkok's BTS and MRT networks sustain utilization rates above breakeven through tourist and commuter overlap. The country's Industrial Standards Institute aligns with regional battery safety frameworks. Sukhumvit and Silom commercial corridors concentrate station density for hospitality district access.
Vietnam
Ho Chi Minh City District 1 and Da Nang beach tourism zones present first-mover opportunities with 85% plus smartphone penetration. The Ministry of Science and Technology develops domestic certification pathways for imported lithium-ion hardware. Can Tho and other secondary cities remain substantially underpenetrated despite comparable device ownership rates.
Mobile Sharing Power Bank Rental Service Market Competitive Landscape
Global majors compete with regional champions across deployment format and pricing architecture. The market structure tiers between density-focused station operators and flexibility-oriented unit-based networks. Three archetypes dominate: transit-hub specialists anchoring metro corridors, hospitality-integrated providers securing venue exclusives, and mobility-embedded operators capturing in-transit charging occasions. Capacity expansion and strategic venue partnerships constitute the dominant competitive moves, with operators racing to lock in transit authority and hotel chain relationships before saturation.
Within the density-driven tier, Energy Monster and Xiaodian Technology exemplify contrasting geographic concentration strategies. Jiedian occupies a position on the flexibility vector through mobility-integrated deployment formats. These three anchors illustrate how procurement relationships with Shenzhen hardware suppliers and certification navigation through SAMR, METI, and EU F-Gas frameworks differentiate competitive positioning across expansion corridors.
| Leading Market Players |
|---|
| Energy Monster |
| Xiaodian Technology |
| Jiedian |
| Laidian Technology |
| ChargedUp |
| Powerqube |
| ChargeSpot |
| ChargeItSpot |
| Anker Innovations |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up station operators in Chinese tier-one cities exert pricing discipline through captive procurement relationships with Shenzhen enclosure manufacturers, compressing hardware refresh cycles while sustaining per-transaction margins above pay-per-use breakeven thresholds.
Pricing Analysis
Input-cost pass-through from lithium-ion cell chemistry modifications flows directly to end-user rates, with GB 31241 recertification delays forcing operators to absorb margin compression rather than accelerate price adjustments. Three-tier pricing structure across premium wireless, standard portable, and economy kiosk tiers separates business travelers from tourists from students. Pricing pressure stems from cobalt price volatility in DRC-sourced cathode materials. Students in Ho Chi Minh City and Manila exhibit highest price sensitivity, while corporate hospitality packages in Singapore and Dubai capture least elastic demand through guaranteed availability SLAs.
Supply Chain Analysis
Reverse-logistics flows for battery swap and unit refurbishment concentrate operational complexity in secondary Chinese cities where field technician scarcity extends turnaround cycles. Shenzhen, Dongguan, and Huizhou anchor enclosure and cell manufacturing clusters. Lithium carbonate, cobalt sulfate, and GaN semiconductor components feed from South Korean and Japanese specialty chemical suppliers. Single-source vulnerability runs through Shenzhen-based kiosk mechanical subassemblies controlling seventy percent of global enclosure output. Distribution runs through direct procurement relationships with network operators rather than tiered distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
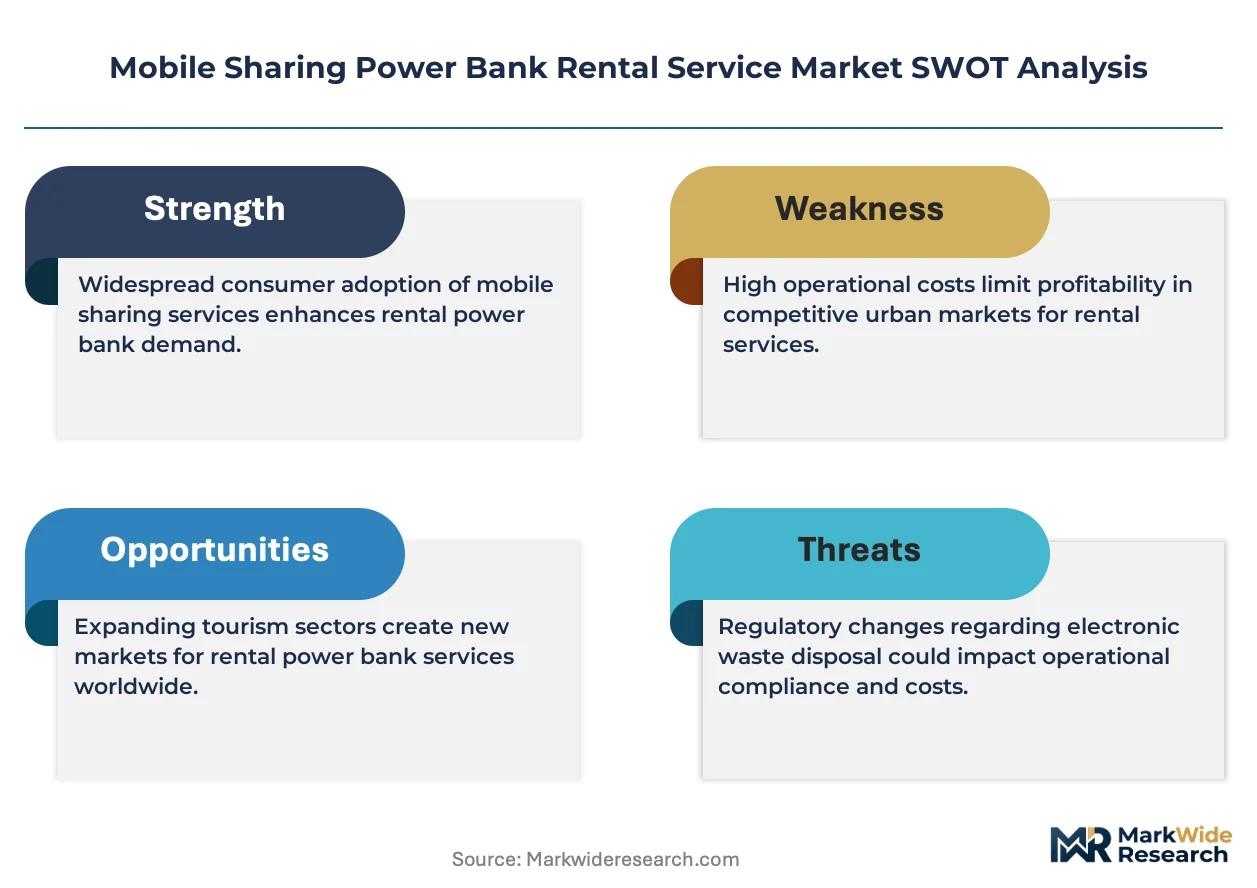
Margin expansion in this market rests on GaN-based fast-charging hardware penetration enabling premium-tier pricing for multi-device rental occasions, offsetting cobalt input volatility through capability compression rather than volume scaling.
For Market Incumbents: Hedge against Shenzhen enclosure manufacturer concentration by qualifying secondary mechanical subassembly suppliers in Vietnam and India before station hardware refresh cycles accelerate. Lock in multi-year cobalt offtake agreements with DRC-focused traders to isolate margin pressure from commodity exchange spikes. GB 31241 recertification timelines represent the critical regulatory threat to hardware refresh economics. For New Entrants and Emerging Players: Super-app integration partnerships with Grab, Gojek, and Meituan offer lowest customer acquisition cost routes into mobility-embedded charging occasions. Target Vietnam's Da Nang and Can Tho corridors where smartphone penetration exceeds eighty-five percent yet station networks remain underdeployed. Pursue kiosk partnerships with convenience retail chains rather than building dedicated station infrastructure from greenfield. For Investors and Strategic Acquirers: Valuations sit cheapest among unit-based mobility-integrated operators with established ride-sharing fleet relationships but limited geographic footprint. Five-to-ten year viability hinges on backward integration into certified cell manufacturing or captive refurbishment capabilities. Watch for SAMR announcements expanding GB 31241 scope to wireless charging hardware as inflection signal for certification-heavy consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Circuitry Upgrade | Enables 65W laptop-capable kiosks capturing multi-device rental occasions in Dubai and Singapore airports. |
| Pre-Certified Reference Design | Reduces METI PSE marking delays by 45-60 days for Tokyo and Osaka network deployments. |
| Master Service Agreement | Consolidates fragmented station contracts into network-wide SLAs with Marriott and Hilton properties. |
| Secondary City Density Build | Exploits unified GB 31241 standards accelerating cross-provincial expansion in Sichuan and Shaanxi. |
| Mobility Fleet Embedding | Captures in-transit charging demand through Jiedian-style ride-sharing and food-delivery unit placement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with network operations directors, hardware procurement leads at Shenzhen manufacturers, hospitality procurement managers in Bangkok and Singapore, and regulatory affairs specialists navigating SAMR certification pathways. Secondary validation drew from SAMR GB standard filings, EU F-Gas Regulation updates, METI PSE marking databases, and customs records for lithium-ion cell imports. Bottom-up station deployment counts triangulated against top-down addressable smartphone user estimates.
Segment-weighting approaches distributed value and volume across product type, deployment format, customer archetype, and service model dimensions throughout the projection horizon. CAGRs derived from logistic diffusion curves fitted to smartphone penetration trajectories and charging infrastructure gap closures. Industry-specific forecast inputs incorporated GB 31241 certification timeline assumptions and Qi wireless coil penetration rates among flagship handset releases.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery chemistry would alter the outlook through extended cycle life and reduced refurbishment logistics. Forecasts reflect documented assumptions around cobalt price stabilization and unified certification regime persistence. Practitioners should monitor SAMR announcements on wireless charging safety scope, DRC cobalt export quota adjustments, and Grab-Gojek super-app partnership exclusivity terms for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
UAE ICT Market
Digital Solutions
Asia-Pacific Digital Pen Market
Digital Solutions
Digital Business Support System Market
Digital Solutions
Contact Tracing Application Market
Digital Solutions
North America 3D Rendering Services Market
Digital Solutions
Europe Warranty Management System Market
Digital Solutions
Deviation Management and CAPA Platforms for Cold Chain Logistics Market
Digital Solutions
Product Data Management Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Enterprise Imaging Solutions Market
Digital Solutions
Global Inventory Optimization Software Market
Digital Solutions
Location As a Service Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
Affiliate Marketing Platform Market
Digital Solutions
Global Digital Experience Management Market
Digital Solutions
Global Transport Management Software Market