
 Global Distributed Denial of Service (Ddos) Protection Market | 2026-2036
Global Distributed Denial of Service (Ddos) Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Distributed Denial of Service (Ddos) Protection Market Foresight
Mid-market enterprises is reorganizing demand patterns as legacy buyers in telecommunications plateau. Akamai Technologies leverages its edge network density to deliver sub-second mitigation response times. Cloudflare sustains pricing pressure through freemium-to-enterprise conversion funnels. NETSCOUT Systems anchors high-value contracts with carriers requiring deep packet inspection at scale.
Distributed Denial of Service protection encompasses hardware appliances, cloud scrubbing services, and hybrid architectures engineered to absorb or deflect volumetric, protocol, and application-layer attacks exceeding one terabit per second. The technology serves to preserve service availability for revenue-generating digital platforms and critical infrastructure operators. Cloud-Based deployment leads in new contract velocity while On-Premise solutions retain margin concentration in regulated sectors with data sovereignty mandates. Application Layer Defense commands premium pricing as API-targeted attacks outpace network flooding in sophistication.
The FCC enforces communications reliability standards that obligate US carriers to maintain DDoS resilience, while the EU AI Act imposes algorithmic transparency requirements on automated threat detection systems. Japan's METI cybersecurity framework mandates incident reporting timelines that shape product design priorities for vendors serving East Asian markets. Stakeholders must weigh captive SOC buildouts against managed service dependencies as attack automation outpaces internal staffing cycles.
Market Dynamics
Attack automation is compressing mitigation response windows below human reaction thresholds, forcing infrastructure operators to choose between captive security operations centers and managed service dependencies.
Growth Catalysts
- EU AI Act compliance mandates:Automated threat detection systems in European markets must demonstrate algorithmic transparency, accelerating vendor investment in explainable behavioral analysis capabilities.
- API economy expansion:Financial services and e-commerce platforms are deploying application-layer defense as REST and GraphQL endpoints become primary attack surfaces.
- Japan METI incident reporting requirements:Compressed disclosure timelines for critical infrastructure operators are driving procurement of real-time telemetry and automated response orchestration.
Market Restraints
- Specialized engineering talent scarcity:Shortages of network security architects with deep packet inspection expertise constrain vendor scaling and inflate compensation costs.
- Silicon supply concentration:Custom ASIC and FPGA fabrication for high-throughput scrubbing hardware depends on concentrated East Asian foundry capacity.
- Data sovereignty mandates:GDPR and sector-specific regulations fragment cloud service architectures, forcing redundant infrastructure deployment across jurisdictions.
Strategic Opportunities
- Underpenetrated mid-market segment:Enterprises with 500-5,000 employees lack dedicated security staff, creating demand for fully managed scrubbing services with SLA-backed availability guarantees.
- 5G network slicing:Telecommunications carriers can monetize dedicated DDoS-protected network slices for industrial IoT and autonomous vehicle communication.
- Convergence of zero-trust and edge mitigation:Integration of identity-aware access control with distributed scrubbing nodes enables per-user, per-session protection policies.
Industry Challenges
- Legacy load balancer integration:Enterprises with F5 and Citrix ADC deployments face complex retrofit requirements for modern behavioral detection.
- Certification timeline compression:FedRAMP and ISO 27001 audit cycles lag behind product release velocities, delaying public sector contract eligibility.
- Attribution ambiguity:State-affiliated actors employ proxy infrastructure and cryptocurrency payment rails, complicating incident response and legal recourse.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Distributed Denial of Service (Ddos) Protection Market |
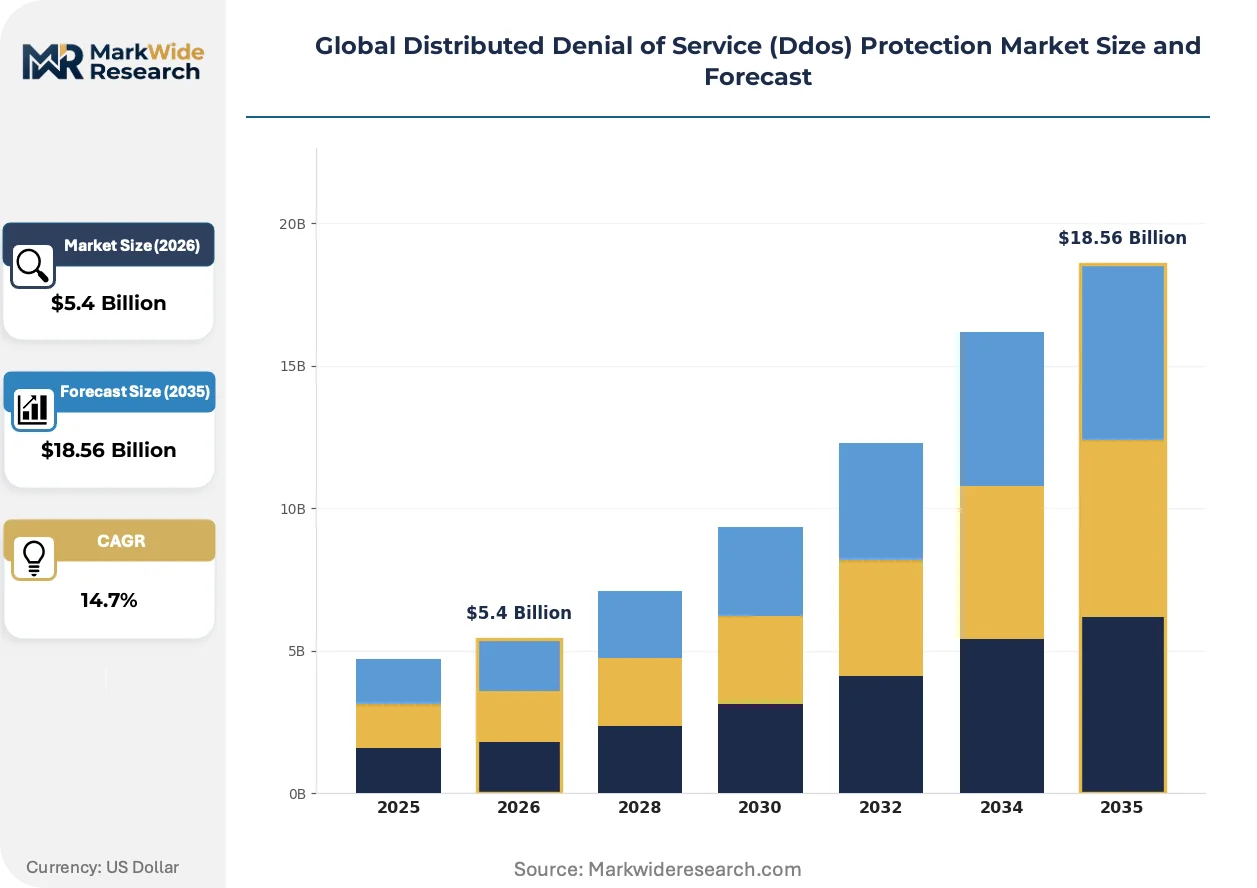
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $18.56 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Managed Services Solution: Network Layer Protection, Application Layer Defense, Hybrid Protection, Behavioral Analysis Application: Telecommunication Providers, Financial Institutions, E-Commerce Platforms, Government Agencies, Educational Institutions Customer Type: Enterprises, Small and Medium Businesses, Internet Service Providers, Data Centers |
| Companies Covered | NETSCOUT Systems, Akamai Technologies, Cloudflare, Radware, F5, Imperva, Fortinet, Corero Network Security, A10 Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Distributed Denial of Service (Ddos) Protection Market Shifts & Advancements
Edge computing density and machine learning inference at the network perimeter are redefining where mitigation decisions execute, collapsing the architectural distinction between detection and response.
Serverless compute at scrubbing nodes is fragmenting traditional hardware-software boundaries in DDoS protection. Hyperscale edge locations now host containerized mitigation functions that spin up in milliseconds based on traffic pattern signatures. Telecommunications carriers in Germany and the United States are piloting these architectures for sub-second response to application-layer attacks. The shift is fragmenting vendor competitive positions, as pure-play hardware appliance suppliers lose differentiation against cloud-native alternatives.
The EU AI Act's algorithmic transparency requirements are reshaping automated threat detection procurement in European financial services. Vendors must document training data provenance and decision logic for machine learning models used in blocking determinations. German critical infrastructure operators are requiring model cards and bias audits as contract prerequisites. This regulatory pressure is fragmenting product roadmaps, with European deployments diverging from global codebases to satisfy documentation mandates.
Consumption-based pricing for scrubbing capacity is displacing flat-rate annual contracts in mid-market procurement. Channel partners in Japan and the United States are unbundling professional services from traffic volume commitments, allowing seasonal businesses to align security spending with revenue cycles. E-commerce platforms with flash sale events represent the most visible adopters, negotiating burst capacity with per-gigabyte billing rather than permanent overprovisioning.
Global Distributed Denial of Service (Ddos) Protection Market Segmentation
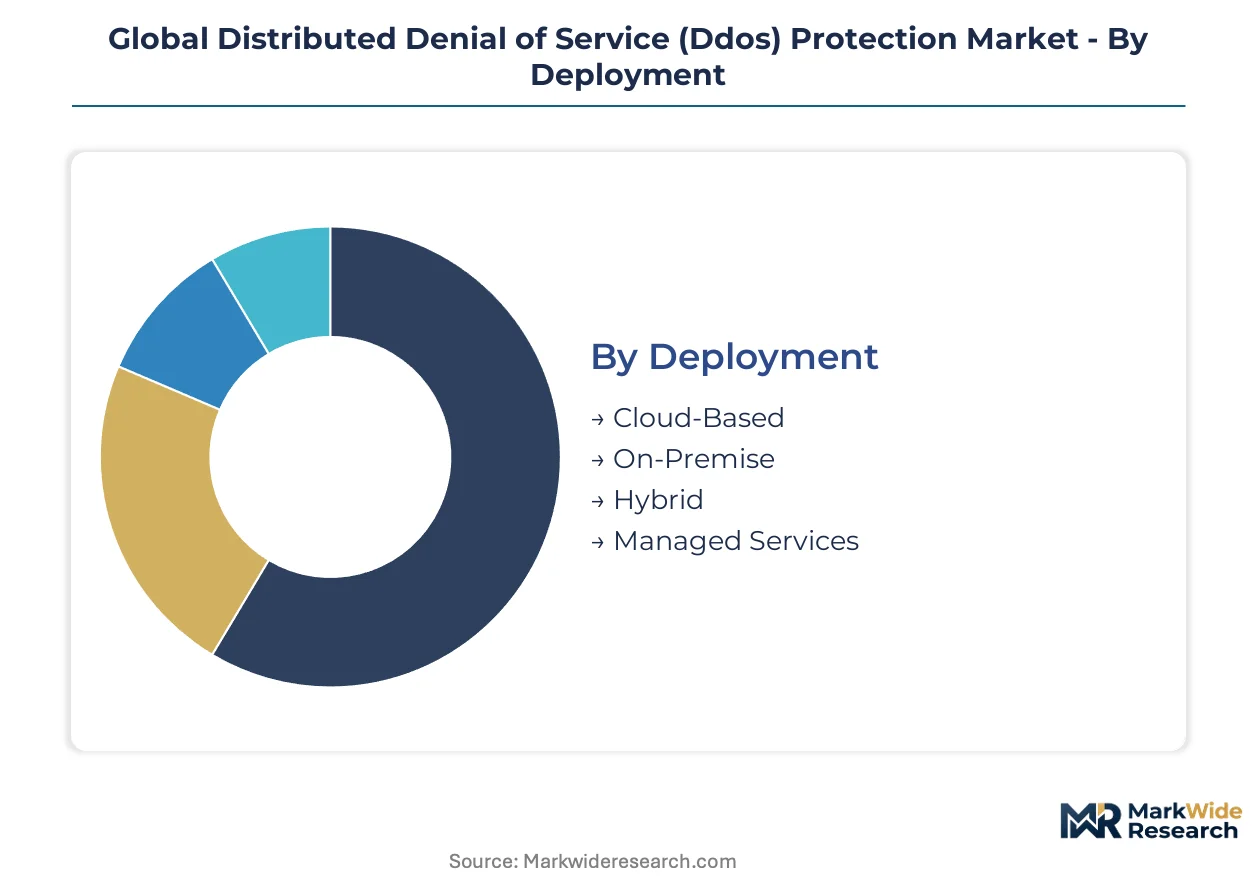
DDoS protection procurement splits sharply between domestic-regulated buyers and export-facing digital platforms. Deployment choices reflect data sovereignty mandates in Germany and Japan versus latency requirements for US-based SaaS providers. Understanding these geographic fault lines clarifies why vendor roadmaps diverge across regions.
Deployment:
German critical infrastructure operators and Japanese manufacturers anchor demand for sovereign-controlled hardware, while US fintech exporters drive cloud-native adoption.
- Cloud-Based:Scrubbing capacity scales elastically across hyperscaler edge locations without customer-managed hardware. Financial institutions in Singapore and e-commerce platforms in the United States prioritize sub-second provisioning over capital ownership.
- On-Premise:Dedicated appliances process traffic within facility-controlled environments using custom ASIC or FPGA silicon. German energy utilities and Japanese automotive manufacturers mandate this architecture for operational technology network segmentation.
- Hybrid:Split-path routing directs volumetric floods to cloud scrubbers while sensitive application-layer inspection remains on-site. This configuration satisfies US healthcare providers with HIPAA-controlled data flows.
- Managed Services:Third-party security operations centers assume monitoring and response obligations under SLA-backed contracts. Mid-market enterprises in France and the United Kingdom lacking captive SOCs represent the core demand pool.
On-Premise commands the established base. The steepest expansion runs through Cloud-Based.
Solution:
Margin concentration tracks technical sophistication, with behavioral detection commanding premium pricing against commodity volumetric scrubbing.
- Application Layer Defense:Deep packet inspection and protocol-aware filtering target HTTP floods, Slowloris variants, and API-specific exploits. Financial services in London and e-commerce platforms in New York deploy these capabilities as REST endpoints multiply.
- Behavioral Analysis:Machine learning models baseline legitimate traffic patterns to flag anomalies without signature dependency. EU AI Act compliance mandates in Germany and France are accelerating procurement with explainability requirements.
- Network Layer Protection:Volumetric absorption against UDP floods and amplification attacks using sinkholing and blackholing techniques. Telecommunications carriers in Japan and Brazil maintain this as foundational infrastructure.
- Hybrid Protection:Coordinated network and application defenses with unified policy orchestration. US federal contractors pursuing FedRAMP authorization favor this consolidated approach.
Network Layer Protection retains volume leadership. Application Layer Defense is climbing the fastest as API-targeted attacks outpace raw bandwidth floods.
Application:
End-use concentration varies by attack surface exposure and regulatory pressure intensity across national jurisdictions.
- Financial Institutions:Multi-layered defenses protecting payment card infrastructure, trading platforms, and mobile banking APIs. Banks in Switzerland and Singapore face the most sophisticated application-layer campaigns.
- E-Commerce Platforms:Flash sale events and seasonal traffic spikes create unpredictable capacity requirements. Retailers in the United States and Germany are adopting consumption-based scrubbing contracts.
- Telecommunication Providers:Carrier-grade scrubbing at internet exchange points and backbone aggregation layers. Operators in Japan and South Korea lead investment in 5G slicing integration.
- Government Agencies:Classified and unclassified network segmentation with nation-state threat modeling. Defense contractors in the United States and intelligence services in Israel drive specialized procurement.
- Educational Institutions:Protection for research networks and student-facing services with limited security staffing. Universities in the United Kingdom and Australia represent growing managed service demand.
Telecommunication Providers anchor infrastructure-scale deployment. Financial Institutions are gaining share fastest as open banking APIs expand attack surfaces.
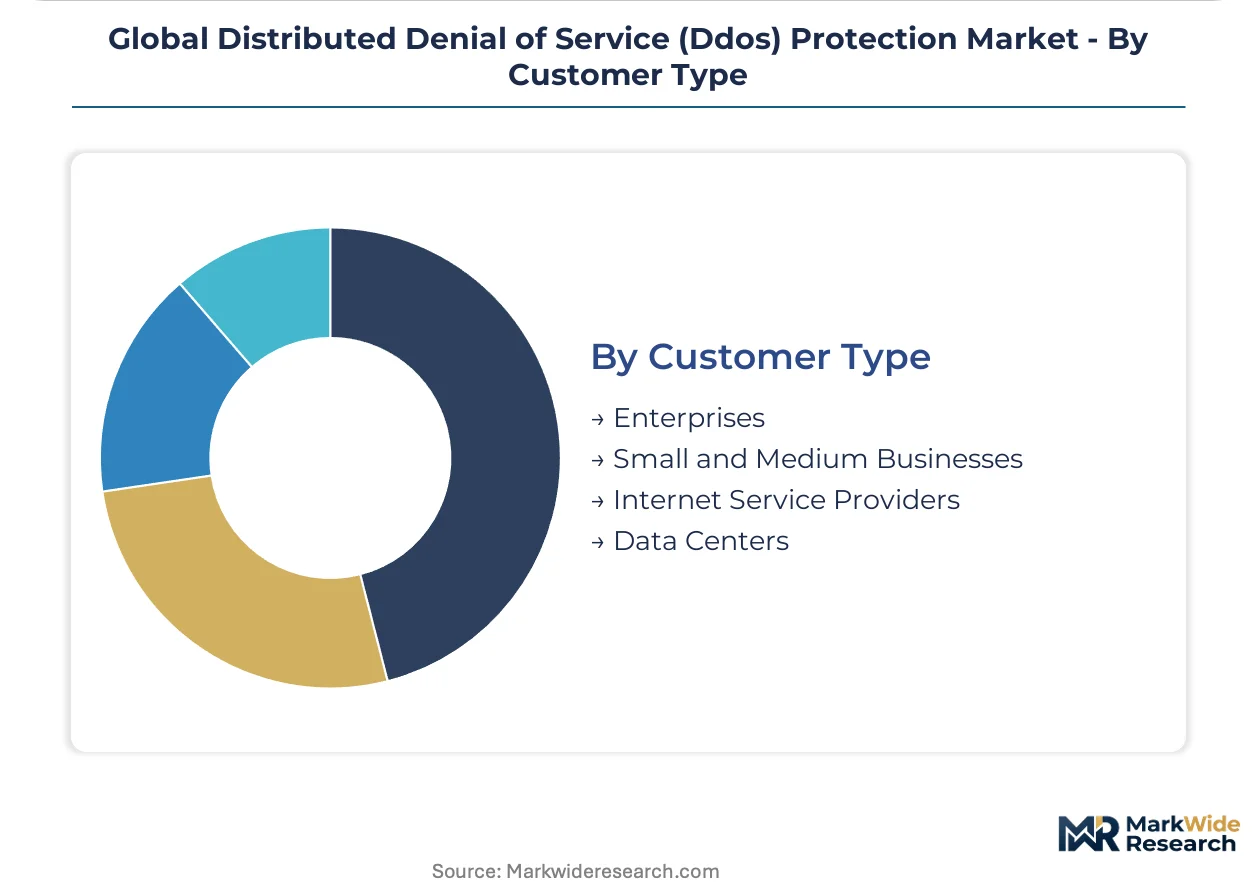
Customer Type:
Organizational scale determines build-versus-buy calculus as attack automation compresses response windows below internal staffing capacity.
- Enterprises:Global 2000 organizations with captive security operations centers and multi-vendor architectures. German automotive conglomerates and US technology platforms maintain the most mature programs.
- Data Centers:Colocation and hyperscale facilities offering scrubbing as a value-added service to tenant customers. Operators in Frankfurt and Ashburn compete on mitigation response time guarantees.
- Internet Service Providers:Residential and business broadband protection with network-wide traffic engineering. National carriers in Japan and regional providers in Brazil represent distinct procurement tiers.
- Small and Medium Businesses:Organizations with 500-5,000 employees lacking dedicated network security architects. Channel partners in the United States and United Kingdom are unbundling managed detection from hardware sales.
Enterprises command the established base. Small and Medium Businesses show the steepest expansion trajectory as attack democratization forces security investment downmarket.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Custom ASIC and FPGA fabrication for high-throughput scrubbing hardware concentrates in East Asian foundry capacity, yet procurement decisions cluster in Germany, Japan, and the United States where critical infrastructure operators confront the most sophisticated threat environments.
United States
Financial institutions and SaaS exporters drive cloud-native adoption with sub-second provisioning priorities. The FCC enforces communications reliability standards obligating carriers to maintain DDoS resilience. Ashburn data center operators compete on mitigation response time guarantees for federal contractors pursuing FedRAMP authorization.
Germany
Critical infrastructure operators and automotive manufacturers anchor demand for sovereign-controlled hardware with operational technology network segmentation. EU AI Act algorithmic transparency requirements accelerate procurement with explainability mandates. Frankfurt colocation facilities offer scrubbing as value-added services under GDPR-controlled data flows.
Japan
Telecommunications carriers lead investment in 5G network slicing integration for industrial IoT protection. METI cybersecurity frameworks mandate compressed incident reporting timelines shaping real-time telemetry procurement. Tokyo-based national carriers maintain carrier-grade scrubbing at internet exchange points with backbone aggregation layers.
United Kingdom
Mid-market enterprises lacking captive security operations centers represent growing managed service demand. Channel partners unbundle professional services from traffic volume commitments for seasonal businesses. London financial services deploy application-layer defenses as REST and GraphQL endpoints multiply attack surfaces.
Singapore
Banks and regional fintech hubs face sophisticated application-layer campaigns targeting payment card infrastructure. Data sovereignty requirements intersect with latency optimization for Southeast Asian digital platforms. Singapore-based financial institutions prioritize elastic scrubbing capacity across hyperscaler edge locations without capital ownership.
Global Distributed Denial of Service (Ddos) Protection Market Competitive Landscape
Concentration sits with edge-network incumbents and cloud-native platforms rather than pure-play hardware specialists. Three distinct archetypes occupy competitive positions: hyperscale edge providers leveraging distributed infrastructure density, carrier-anchored vendors with deep packet inspection at scale, and freemium-to-enterprise conversion platforms sustaining pricing pressure. Strategic moves center on M&A for behavioral analysis capabilities and capacity expansion into sovereign cloud regions.
Among established infrastructure providers, NETSCOUT Systems and Akamai Technologies occupy positions at the carrier-grade and edge-network tiers respectively, while Cloudflare exemplifies the freemium conversion archetype penetrating mid-market procurement. These three entities represent the dominant competitive vectors shaping contract structures across financial services, telecommunications, and e-commerce verticals.
| Leading Market Players |
|---|
| NETSCOUT Systems |
| Akamai Technologies |
| Cloudflare |
| Radware |
| F5 |
| Imperva |
| Fortinet |
| Corero Network Security |
| A10 Networks |
| Others |
Supply & Pricing Matrix
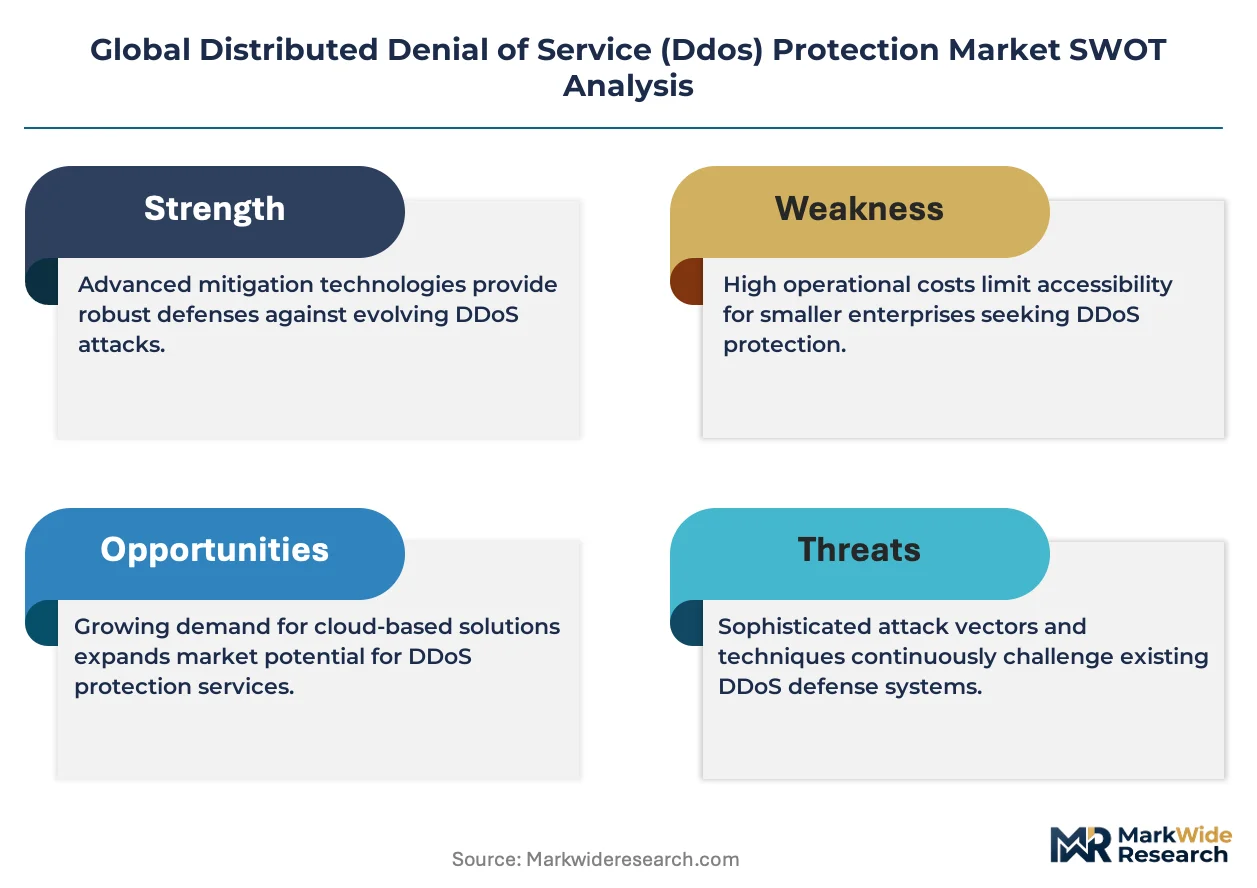
Consumption-based billing for scrubbing capacity is displacing flat-rate annual contracts across mid-market procurement, simultaneously fragmenting vendor revenue predictability and compressing margins for providers lacking elastic infrastructure. This shift redraws competitive geography as cloud-native platforms capture seasonal buyers while hardware-anchored vendors retreat toward sovereign-controlled deployments in Germany and Japan.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for automated threat detection systems in European markets, mandating algorithmic transparency documentation that vendors embed as premium service charges. Pricing stratifies across explainable behavioral analysis, standard signature-based scrubbing, and commodity volumetric absorption tiers. Price differentiation hinges on certification grade for FedRAMP authorization and customization level for operational technology integration. Cost compression in the standard tier is intensifying because hyperscale edge providers leverage freemium conversion funnels. Small and medium businesses with 500-5,000 employees exhibit the highest price sensitivity, while German critical infrastructure operators demonstrate the lowest due to data sovereignty mandates.
Supply Chain Analysis
TSMC and Samsung foundry capacity for custom ASIC and FPGA fabrication anchors global supply of high-throughput scrubbing hardware. Raw material dependencies center on silicon wafers, advanced packaging substrates, and rare earth elements for magnetics in appliance power supplies. Single-source vulnerability concentrates in East Asian semiconductor fabrication, exposing vendors to geopolitical disruption and export control fluctuations. Distribution runs through direct enterprise sales for on-premise deployments and hyperscaler marketplaces for cloud-native services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive advantages through certification barriers and switching costs that cement incumbent positions.
For Market Incumbents: Shield carrier-grade relationships by deepening backward integration into custom silicon design, insulating against hyperscaler encroachment. Fortify FedRAMP and EU AI Act compliance documentation as contract prerequisites to raise rival entry costs. Expand sovereign cloud regions in Germany and Japan to capture data sovereignty-driven procurement. For New Entrants and Emerging Players: Lead with fully managed scrubbing services targeting mid-market enterprises lacking captive security operations centers, where incumbent coverage remains sparse. Penetrate the educational institution segment in the United Kingdom and Australia through channel partnerships unbundling hardware from professional services. Position against consumption-based pricing flexibility to differentiate from legacy annual contract structures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed behavioral analysis specialists possessing EU AI Act-ready model documentation. Long-term viability rests on algorithmic explainability capabilities that regulatory frameworks are entrenching as mandatory. Monitor hyperscaler capex disclosures for edge location expansion as an inflection signal for infrastructure-scale competitive shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Behavioral Analysis Specialist | EU AI Act compliance mandates accelerate consolidation around explainable machine learning capabilities. |
| Sovereign Cloud Region Expansion | German and Japanese data sovereignty requirements favor localized scrubbing infrastructure deployment. |
| Custom ASIC Development Partnership | Deep packet inspection at terabit scale demands captive silicon design beyond merchant chip availability. |
| Managed Service Channel Program | Mid-market enterprises lacking security staff drive demand for SLA-backed outsourced monitoring. |
| 5G Network Slicing Integration | Telecommunications carriers in Japan and South Korea monetize dedicated protection for industrial IoT communication. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vendor financial disclosures, hyperscaler infrastructure reports, and regulatory filing databases. Primary interviews engaged network security architects at financial institutions, procurement leads at telecommunications carriers, compliance officers at German critical infrastructure operators, and channel partners serving mid-market enterprises. Secondary sources encompassed FCC enforcement records, EU AI Act implementation guidance, METI cybersecurity framework documents, and customs data on networking hardware trade flows. Bottom-up contract analysis triangulates against top-down infrastructure spending estimates.
Segmentation dimensions modeled span deployment architecture, solution type, end-use application, customer scale, and regional regulatory cluster across the analysis window. CAGRs derive from elasticity-adjusted demand curves incorporating attack frequency trajectories and compliance mandate timelines. Industry-specific forecast inputs include telecommunications carrier 5G capex cycles and financial services API endpoint proliferation rates.
Forecasts assume regulatory continuity in FCC communications reliability standards, EU AI Act algorithmic transparency requirements, and METI incident reporting frameworks; material policy shifts would require re-modeling. Attack automation trajectories and hyperscaler pricing aggression represent primary uncertainty vectors. Practitioners should keep alternative scenarios live as sovereign cloud deployment patterns and foundry capacity allocation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Europe Data Protection-As-A-Service Market
Cybersecurity
Romania Cybersecurity Market
Cybersecurity
Cloud Encryption Gateways Market
Cybersecurity
Global Virtualization Security Market
Cybersecurity
Europe SOC As a Service Market
Cybersecurity
Information Security Products and Services Market
Cybersecurity
Norway Cybersecurity Market
Cybersecurity
Netherlands Cybersecurity Market
Cybersecurity
Network Security Market
Cybersecurity
Retail Cybersecurity Market
Cybersecurity
LAMEA Deception Technology Market
Cybersecurity
Saas-Based IT Security Market
Cybersecurity
Banking Cyber Security Market
Cybersecurity
Network Traffic Analysis Solutions Market
Cybersecurity
Asia Pacific Data Exfiltration Market
Cybersecurity
Data Center Security Market