
 Mobility As a Service Market | 2026-2036
Mobility As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Mobility As a Service Market Intelligence
Platform licensing revenue is narrowing as operators consolidate API access under proprietary ecosystems. Uber Technologies Inc. leverages its global driver network to sustain density advantages in peak-hour corridors. DiDi Chuxing Technology Co. anchors its position through deep integration with municipal transit APIs in Asian megacities. Grab Holdings Limited differentiates via super-app architecture that controls food delivery, payments, and mobility within unified interfaces.
Mobility As a Service denotes digitally orchestrated transportation where users access multiple modes through unified subscription or pay-per-use platforms, typically requiring real-time data exchange between GPS navigation systems, payment gateways, and cloud-based fleet management layers. The architecture enables dynamic route optimization across ride-hailing, car sharing, and public transit integration. Ride-hailing dominates current revenue pools due to established consumer familiarity and driver supply liquidity. Public transit integration represents the fastest-expanding segment as municipalities embed MaaS layers into legacy fare collection infrastructure. Cloud platforms concentrate margin pools by reducing per-transaction latency for multimodal itinerary stitching.
The European Union's GDPR and the EU AI Act impose strictures on algorithmic pricing transparency and passenger data portability across competing platforms. The US Department of Transportation and the FAA coordinate on emerging aerial mobility integration into urban MaaS stacks. Stakeholders must monitor whether open-data mandates in major transit jurisdictions fragment platform exclusivity or reinforce first-mover data advantages.
Market Dynamics
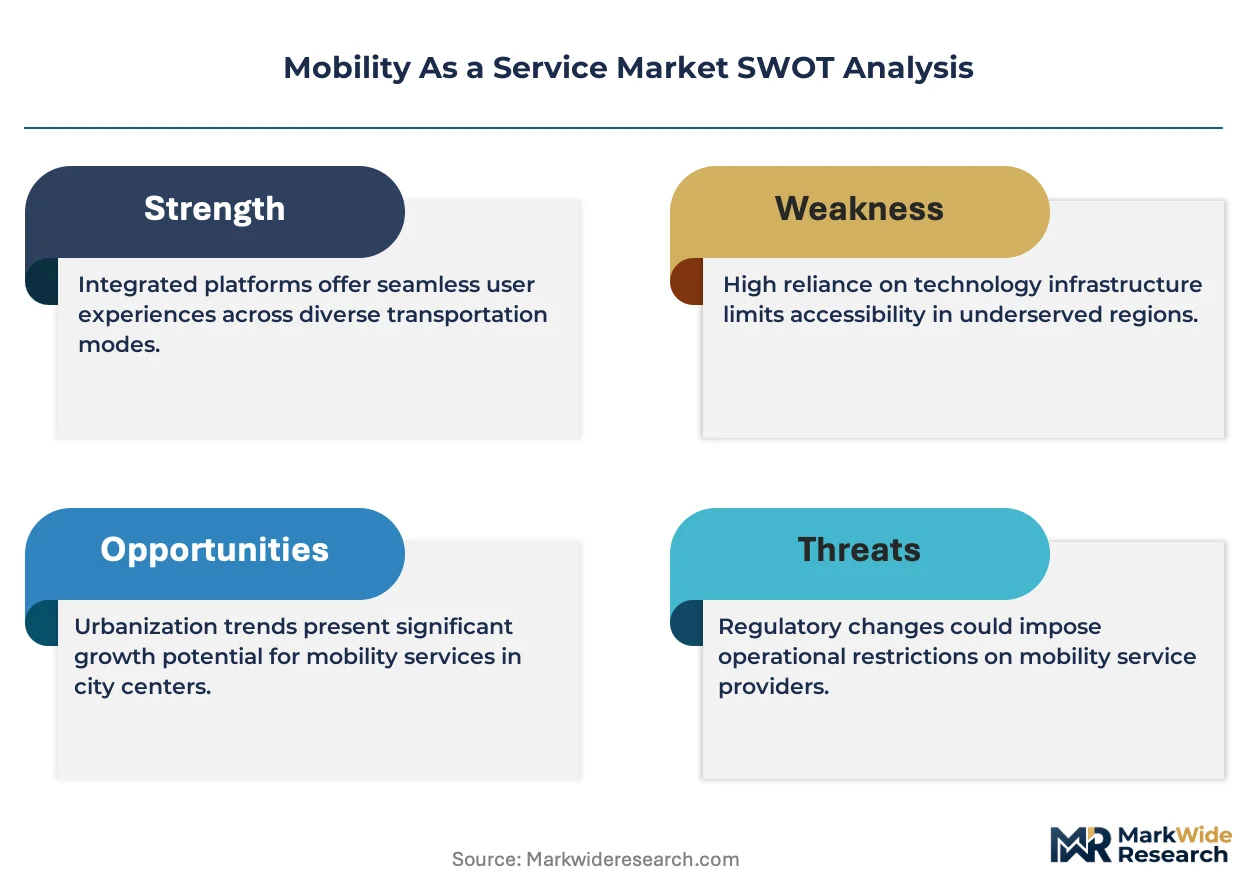
API consolidation among dominant platforms is compressing third-party aggregator margins while municipal open-data mandates fragment proprietary data advantages across transit corridors.
Growth Catalysts
- GDPR-mandated data portability:European regulators force interoperability standards that reduce switching costs for urban commuters between competing platforms.
- Cloud-native fleet orchestration:Real-time containerized dispatch systems slash per-trip latency below 200 milliseconds in high-density corridors.
- Berlin-Hamburg regulatory sandboxes:German federal transport authorities test unified mobility account frameworks that bundle public transit with private ride-hailing under single billing layers.
Market Restraints
- Driver supply liquidity constraints:Peak-hour density requirements demand floating pools of 15-20% excess capacity that sit idle during off-peak windows.
- Payment processor concentration:Three dominant gateways control tokenized transit fare settlement, extracting 2.5-3.5 basis points per multimodal itinerary stitch.
- Legacy fare collection technical debt:Municipal transit agencies operate 15-30 year-old magnetic stripe infrastructure incompatible with NFC wallet integration.
Strategic Opportunities
- India's urban agglomeration corridors:Metro rail expansions in Bangalore, Hyderabad, and Pune lack integrated first-last mile connectors.
- Convergence of autonomous shuttles with fixed-route microtransit:Geofenced AV pods operating at Level 4 autonomy fill gaps between trunk bus corridors and origin points.
- US Department of Transportation aerial mobility coordination:FAA urban air mobility integration frameworks create vertiport-to-transit-hub connection standards.
Industry Challenges
- Multimodal itinerary stitching latency:Sub-second route optimization across disparate fleet APIs demands specialized cloud engineering talent scarce outside Seattle, Singapore, and Tallinn clusters.
- Algorithmic pricing audit compliance:EU AI Act documentation requirements for dynamic fare engines impose 18-24 month certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobility As a Service Market |
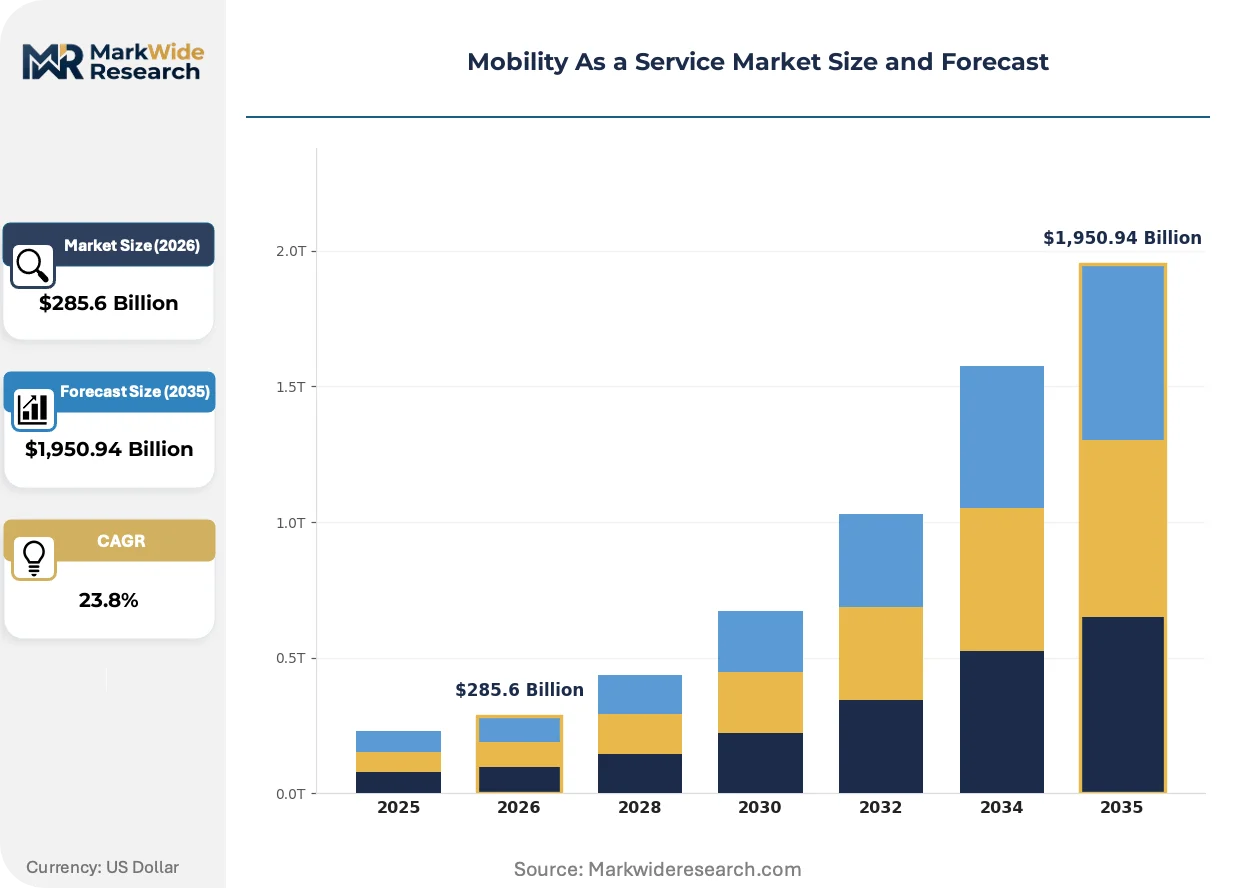
| Market Size in 2026 | $285.6 Billion |
| Market Size in 2035 | $1,950.94 Billion |
| CAGR (2026 – 2036) | 23.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ride-Hailing, Car Sharing, Bike Sharing, Public Transit Integration, Shuttle Services Technology: Mobile Applications, GPS Navigation, Payment Gateways, Cloud Platforms, Telematics End User: Urban Commuters, Tourists, Corporate Employees, Students, Elderly Passengers Distribution Channel: Direct App Downloads, In-Vehicle Infotainment, Partner Websites, Third-Party Aggregators, API Integrations |
| Companies Covered | Uber Technologies Inc., Lyft Inc., DiDi Chuxing Technology Co., Grab Holdings Limited, BlaBlaCar, Moovit Inc., SkedGo Pty Ltd, MaaS Global Oy, Free Now, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobility As a Service Market Strategic Shifts & Innovations
Digitally native transit authorities are abandoning closed-loop smart cards for account-based models that bind identity, payment, and entitlement across operator boundaries.
Distributed ledger settlement protocols is virtualizing the clearing layer between competing mobility providers. Transit agencies in the Netherlands and Estonia pilot tokenized fare reconciliation that eliminates 48-hour settlement delays. The technology is virtualizing inter-operator trust mechanisms previously requiring bilateral contracts.
The EU AI Act imposes algorithmic transparency mandates on dynamic pricing engines used in ride-hailing and demand-responsive transit. Operators must document training data provenance and decision boundaries for surge multipliers. Asian megacities with less prescriptive AI governance attract R&D relocation from European headquarters.
Subscription fatigue among urban professionals is fragmenting annual multimodal passes into modular micro-subscriptions. Commuters in Stockholm and Singapore now bundle 10-ride public transit blocks with pooled e-scooter minutes and car-sharing hours through wallet-native interfaces. Employer-sponsored mobility budgets represent the fastest-growing procurement channel.
Mobility As a Service Market Segmentation
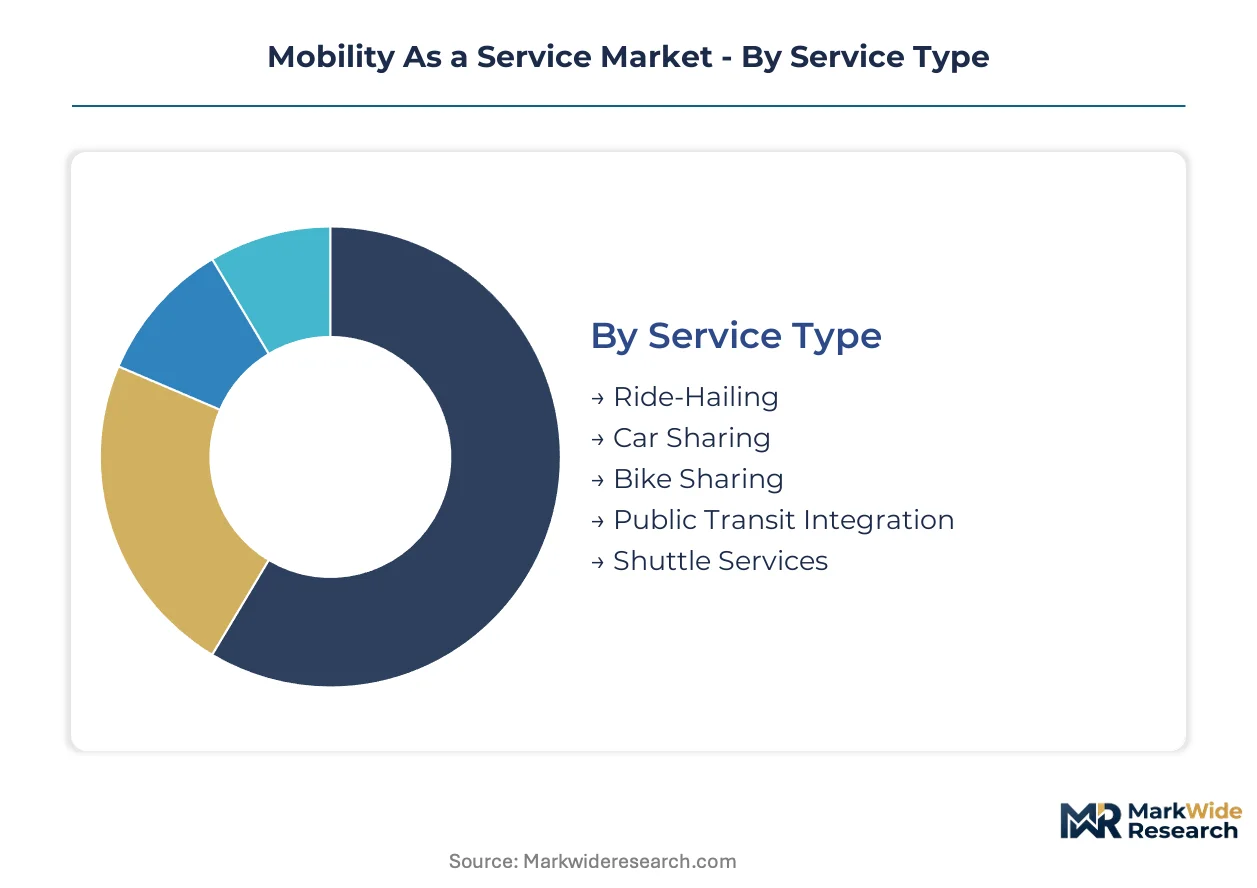
Mobility As a Service platforms stitch disparate transportation modes into unified digital experiences. Segment boundaries blur as operators bundle ride-hailing minutes with transit passes and micro-mobility credits. Understanding where value concentrates across service layers reveals where platform margins accrue.
Service Type:
Mature revenue pools sit alongside emerging modalities still proving unit economics at scale.
- Ride-Hailing:On-demand vehicle dispatch through driver networks dominates current transaction volumes. Peak-hour density requirements in Berlin, Hamburg, and Singapore drive floating capacity pools that compress margins during off-peak windows.
- Public Transit Integration:Account-based fare collection replacing closed-loop smart cards enables multimodal itinerary stitching. German regulatory sandboxes in Berlin and Hamburg test unified mobility accounts that bundle municipal transit with private operators under single billing layers.
- Car Sharing:Station-based and free-floating vehicle access models serve intermittent vehicle needs without ownership burden.
- Bike Sharing:Docked and dockless bicycle fleets address first-last mile gaps in transit corridors.
- Shuttle Services:Fixed-route and on-demand microtransit fills density gaps between trunk bus lines and origin points.
Ride-Hailing retains volume leadership; Public Transit Integration holds the steepest expansion curve.
Technology:
Cost tier stratification separates commodity infrastructure from specialized orchestration layers commanding premium engineering talent.
- Cloud Platforms:Containerized dispatch systems orchestrate multimodal fleet movements with sub-200 millisecond latency. Real-time itinerary stitching across competing operator APIs concentrates in Seattle, Singapore, and Tallinn engineering clusters where scarce talent commands premium compensation.
- Payment Gateways:Tokenized fare settlement layers extract basis points per transaction while enabling wallet-native subscription bundling. Three dominant processors control multimodal itinerary clearing, creating concentration risk for platform operators.
- Mobile Applications:Consumer-facing interfaces aggregate service discovery, booking, and post-trip functions.
- GPS Navigation:Real-time positioning infrastructure enables dynamic route optimization and driver-rider matching.
- Telematics:Vehicle-mounted sensors feed fleet health, utilization, and safety data into predictive maintenance systems.
Cloud Platforms command the highest margin tier; Payment Gateways scale most linearly with transaction growth.
End User:
Customer type segmentation tracks how mobility budgets flow through employer sponsorship, individual subscription, or pay-per-use channels.
- Urban Commuters:Daily work-trip travelers generate predictable demand patterns that anchor platform capacity planning. Subscription fatigue among Stockholm and Singapore professionals fragments annual passes into modular micro-subscriptions bundling transit blocks with e-scooter minutes.
- Corporate Employees:Employer-sponsored mobility budgets represent the fastest-growing procurement channel as enterprises consolidate transportation allowances into platform partnerships.
- Tourists:Episodic visitors with unfamiliarity of local transit networks drive demand for simplified multimodal discovery.
- Students:Price-sensitive riders with flexible timing preferences concentrate demand in off-peak discount windows.
- Elderly Passengers:Accessibility requirements and digital literacy gaps create service design constraints for inclusive platform interfaces.
Urban Commuters anchor daily transaction density; Corporate Employees drive the fastest procurement channel expansion.
Distribution Channel:
Volume concentration versus margin capture splits between owned channels and intermediary dependencies.
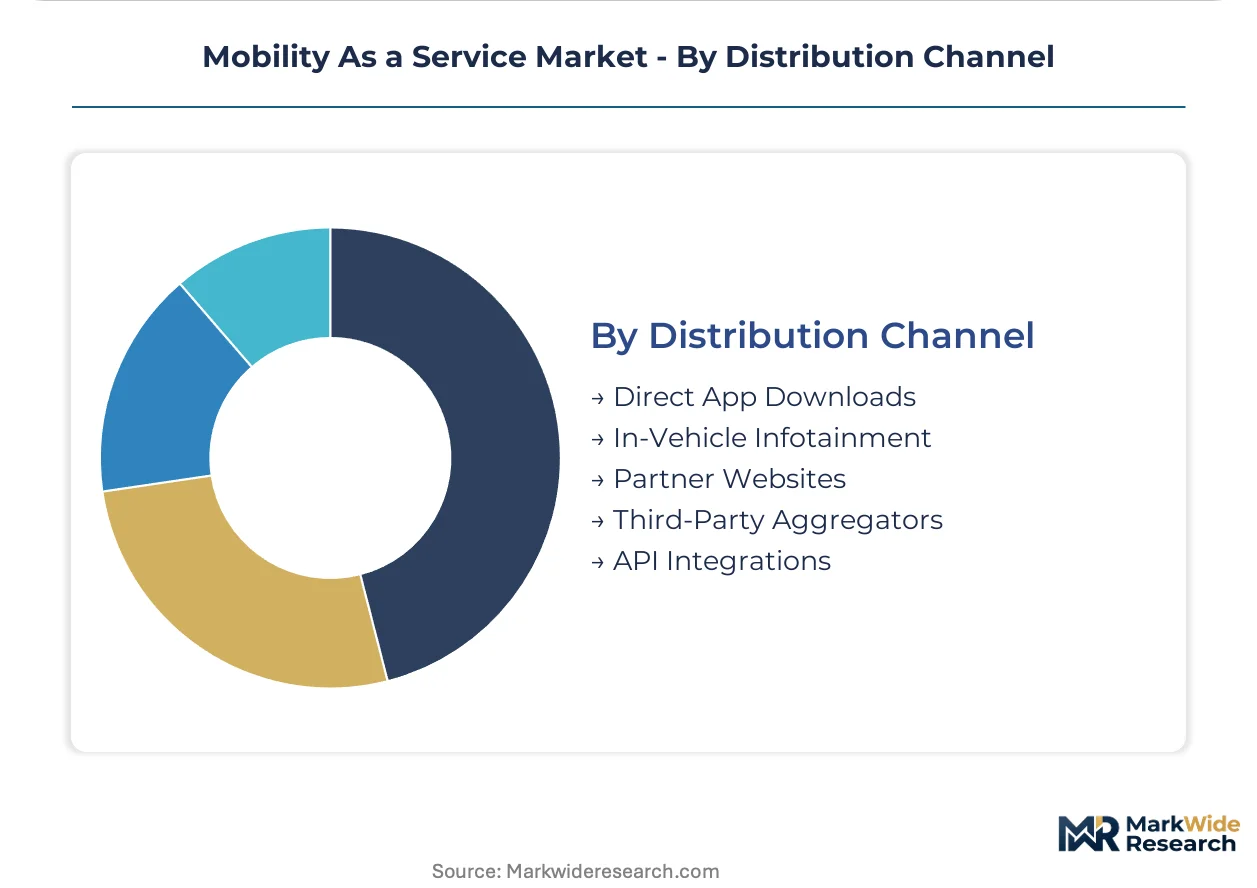
- Direct App Downloads:Platform-controlled acquisition builds proprietary user identity graphs and reduces per-transaction acquisition costs. Super-app architectures in Asian markets consolidate food delivery, payments, and mobility within unified interfaces that deepen engagement frequency.
- API Integrations:Backend connectivity enabling third-party platforms to embed mobility services expands reach without front-end investment. Municipal open-data mandates fragment proprietary data advantages while expanding addressable market.
- In-Vehicle Infotainment:Automotive OEM embedded interfaces capture mobility demand at the point of vehicle interaction.
- Partner Websites:Travel and hospitality platforms extend mobility booking into broader trip planning contexts.
- Third-Party Aggregators:Comparison interfaces reduce platform exclusivity while capturing demand from price-sensitive switchers.
Direct App Downloads capture the highest lifetime value; API Integrations scale reach fastest without proportional marketing spend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commuters in Germany and Singapore purchase bundled multimodal subscriptions, while Indian and Brazilian riders predominantly access single-mode pay-per-use platforms through mobile wallets.
United States
Employer-sponsored mobility budgets drive enterprise procurement of multimodal platforms in Seattle, San Francisco, and New York. The FAA coordinates with the Department of Transportation on urban air mobility integration frameworks. Los Angeles and Dallas-Fort Worth pilot vertiport-to-transit-hub connection standards for aerial mobility corridors.
Germany
Berlin and Hamburg test unified mobility accounts bundling municipal transit with private ride-hailing under single billing layers. The KBA and federal transport authorities operate regulatory sandboxes for account-based fare collection. Munich and Cologne concentrate cloud-native fleet orchestration engineering talent commanding premium compensation.
Singapore
Urban professionals fragment annual passes into modular micro-subscriptions combining transit blocks with e-scooter minutes. The Land Transport Authority mandates open payment standards and real-time data interoperability across competing platforms. The city-state's super-app architecture consolidates food delivery, payments, and mobility within unified interfaces.
India
Metro rail expansions in Bangalore, Hyderabad, and Pune lack integrated first-last mile connectors. The Ministry of Housing and Urban Affairs promotes smart city mobility stacks without unified regulatory frameworks. Mumbai and Delhi-NCR anchor ride-hailing volume through driver network density in peak-hour corridors.
Netherlands
Transit agencies pilot tokenized fare reconciliation using distributed ledger settlement protocols that eliminate 48-hour delays. GDPR-mandated data portability forces interoperability standards reducing commuter switching costs. Amsterdam and Rotterdam concentrate multimodal itinerary stitching development within European engineering clusters.
Mobility As a Service Market Key Industry Players
Capability concentration sits with specialized orchestration platforms; scale advantage sits with global ride-hailing networks possessing driver supply liquidity. The market structures around three tiers: dominant platforms with proprietary API ecosystems, municipal-integrated specialists, and super-app conglomerates bundling adjacent services. Consolidation pressures compress third-party aggregator margins while open-data mandates fragment proprietary data advantages. Competitive moves center on API access consolidation and cloud-native dispatch system deployment.
Within the platform tier, Uber Technologies Inc. and DiDi Chuxing Technology Co. exemplify divergent geographic scale strategies, with the former leveraging global driver network density and the latter anchoring through municipal transit API integration. Grab Holdings Limited occupies a super-app position controlling food delivery, payments, and mobility within unified interfaces. Specialists including Moovit Inc. and SkedGo Pty Ltd represent the orchestration archetype, concentrating engineering talent for multimodal itinerary stitching. MaaS Global Oy sits within the subscription-native tier, testing modular micro-subscription frameworks in Nordic pilot markets.
| Leading Market Players |
|---|
| Uber Technologies Inc. |
| Lyft Inc. |
| DiDi Chuxing Technology Co. |
| Grab Holdings Limited |
| BlaBlaCar |
| Moovit Inc. |
| SkedGo Pty Ltd |
| MaaS Global Oy |
| Free Now |
| Others |
Cost & Logistics Intelligence
North Sea container corridors linking Tallinn, Rotterdam, and Hamburg transmit cloud engineering talent costs into platform pricing tiers, concentrating margin capture among operators with captive dispatch infrastructure while fragmenting aggregator economics.
Pricing Analysis
Long-term municipal transit API contracts anchor enterprise pricing for unified mobility accounts, while spot-market ride-hailing rates fluctuate with driver supply liquidity. Price differentiation rests on cloud-native latency performance and GDPR certification tiers. Cost compression in third-party aggregator tiers intensifies as API access consolidates under proprietary ecosystems. Corporate mobility budgets exhibit lowest price sensitivity; individual pay-per-use commuters in Indian metro corridors show highest elasticity.
Supply Chain Analysis
Upstream feedstock for cloud-native dispatch systems concentrates engineering talent in Seattle, Singapore, and Tallinn clusters. Raw component dependencies span containerized orchestration software, real-time GPS positioning infrastructure, and tokenized payment settlement protocols. Single-source vulnerability in payment gateway concentration creates systemic risk for multimodal itinerary clearing. Distribution runs through direct app downloads and API integrations with municipal transit authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent platforms face substitution pressure from autonomous shuttle operators deploying Level 4 geofenced pods in microtransit gaps, threatening density economics in first-last mile corridors.
For Market Incumbents: Pre-empt autonomous shuttle convergence by securing exclusive API integrations with municipal transit authorities in German regulatory sandboxes. Anchor driver supply liquidity through floating capacity pools in peak-hour corridors. Vertical integration into cloud-native dispatch infrastructure defends against latency-based price erosion. For New Entrants and Emerging Players: Establish a beachhead in India's first-last mile connector gaps across Bangalore, Hyderabad, and Pune metro expansions. Target employer-sponsored mobility budgets as the fastest-growing procurement channel. Deploy wallet-native micro-subscription bundling to bypass annual pass fatigue among urban professionals. For Investors and Strategic Acquirers: Carve-out targets emerge from municipal-integrated specialists possessing scarce multimodal itinerary stitching engineering talent. Long-term viability hinges on regulatory sandbox positioning and open-data mandate navigation. Watch EU AI Act algorithmic audit timelines as inflection indicator for R&D relocation patterns.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Consolidation | Proprietary transit API access in Berlin and Hamburg sandboxes locks in municipal partnerships. |
| Cloud-Native Dispatch Deployment | Sub-200 millisecond latency infrastructure commands premium pricing in high-density corridors. |
| Regulatory Sandbox Positioning | KBA unified mobility account frameworks create first-mover data advantages. |
| Micro-Subscription Modularization | Employer-sponsored mobility budgets in Stockholm and Singapore drive recurring revenue anchoring. |
| Autonomous Shuttle Integration | Level 4 geofenced pod deployment fills density gaps between trunk bus lines and origin points. |
Research Approach
A spread of perspectives from platform engineering leads, municipal transit procurement officers, payment gateway product managers, and cloud infrastructure architects converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC filings, EU regulatory sandbox documentation, and municipal transit authority procurement databases. Bottom-up transaction volume modeling triangulated against top-down mobility budget penetration estimates.
Demand-supply balance across the projection horizon reflects commuter density patterns, driver network liquidity, and cloud infrastructure capacity constraints. Segmentation dimensions modeled include service type, deployment architecture, end-user procurement channel, and regional regulatory framework. CAGRs derive from iterative reconciliation of platform transaction disclosures and municipal ridership statistics.
Sensitivities concentrate around GDPR enforcement intensity, EU AI Act certification timelines, and autonomous vehicle regulatory clearance trajectories. Cross-checking against FAA urban air mobility integration frameworks and Dutch distributed ledger pilot results is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Fleet Health Monitoring and Diagnostic Analytics Systems Market
Smart Transportation Solutions
Automotive V2X Market
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
Long Haul Solutions Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Personal Transporter Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
North America Smart Transportation Market
Smart Transportation Solutions
Middle East and Africa Passenger Information System Market
Smart Transportation Solutions
E-Scooter Sharing Market
Smart Transportation Solutions
B2C Mobility Sharing Market
Smart Transportation Solutions
Road Weather Information Systems (RWIS) Market
Smart Transportation Solutions
Micro Mobility Market
Smart Transportation Solutions
Shared Vehicles Market
Smart Transportation Solutions
Smart Fleet Management Market
Smart Transportation Solutions
Road Asset Management Software Market