
 Transportation for Smart Cities Market | 2026-2036
Transportation for Smart Cities Market Size, Share, and Industry Trends Forecast 2026-2036
Transportation for Smart Cities Market Outlook
ISO 37120 certification for sustainable cities and communities is redrawing vendor eligibility across municipal procurement cycles. Siemens AG leverages its rail signaling heritage to dominate European traffic management installations. Cisco Systems anchors its position through edge computing infrastructure that processes vehicle-to-everything data streams at intersection level. Huawei Technologies Co., Ltd. competes aggressively on 5G roadside unit pricing, though its access faces scrutiny under national security frameworks in multiple jurisdictions.
Transportation for Smart Cities encompasses integrated hardware, software, and communication systems that coordinate urban mobility through real-time data exchange, typically operating on sub-100 millisecond latency thresholds to enable collision avoidance and signal prioritization. The primary purpose is to optimize passenger throughput while reducing energy consumption and emissions across multimodal networks. IoT-enabled sensor networks currently capture the largest deployment share, while blockchain applications for automated tolling and ridesharing settlement represent the fastest-expanding segment as cities pilot transparent fare distribution. Public transit applications retain the deepest municipal budget allocations, though smart parking solutions command premium margins due to immediate revenue generation for cash-strapped local governments.
The U.S. Department of Transportation's Smart City Challenge framework and the EU's F-Gas Regulation on transport refrigeration emissions are both reshaping procurement specifications and technology roadmaps for vendors seeking public contracts. China's MIIT mandates GB-standard vehicle connectivity protocols that foreign suppliers must adapt for market participation. Stakeholders must weigh interoperability commitments against geopolitical technology fragmentation when selecting long-term platform partners.
Market Dynamics
Municipal procurement cycles are compressing as ISO 37120 certification becomes mandatory for vendor eligibility, forcing technology providers to restructure solution architectures around sustainability audit trails rather than standalone performance metrics.
Growth Catalysts
- EU Green Deal mobility targets:Fleet operators face binding emissions reductions that accelerate connected vehicle platform deployment across German, French, and Dutch urban networks.
- Edge computing infrastructure:Real-time intersection-level data processing enables sub-100 millisecond collision avoidance systems that transit authorities now specify in RFPs.
- Blockchain settlement pilots:Transparent automated tolling and ridesharing fare distribution attracts municipal adoption in cash-constrained jurisdictions seeking revenue integrity.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet motors for electric bus fleets depend on Chinese rare earth processing that faces export quota volatility.
- 5G roadside unit security screening:National security frameworks in multiple jurisdictions delay vendor qualification timelines for Chinese-manufactured telecommunications hardware.
- Interoperability protocol fragmentation:China's GB-standard vehicle connectivity mandates create adaptation costs for foreign suppliers seeking MIIT certification.
Strategic Opportunities
- Smart parking revenue models:Immediate cash generation potential commands premium margins from municipal governments facing structural budget deficits.
- Multimodal integration mandates:German federal smart city funding prioritizes networks connecting rail, bus, micromobility, and pedestrian systems under unified data architectures.
- IoT sensor network densification:Low-power wide-area networks enable granular traffic flow monitoring that supports dynamic congestion pricing pilots in Asian megacities.
Industry Challenges
- Cyber-physical systems engineering talent:The intersection of civil infrastructure, automotive electronics, and network security expertise remains scarce in regional labor markets.
- Legacy signal system integration:Decades-old traffic control hardware requires costly middleware development to interface with modern vehicle-to-infrastructure protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transportation for Smart Cities Market |
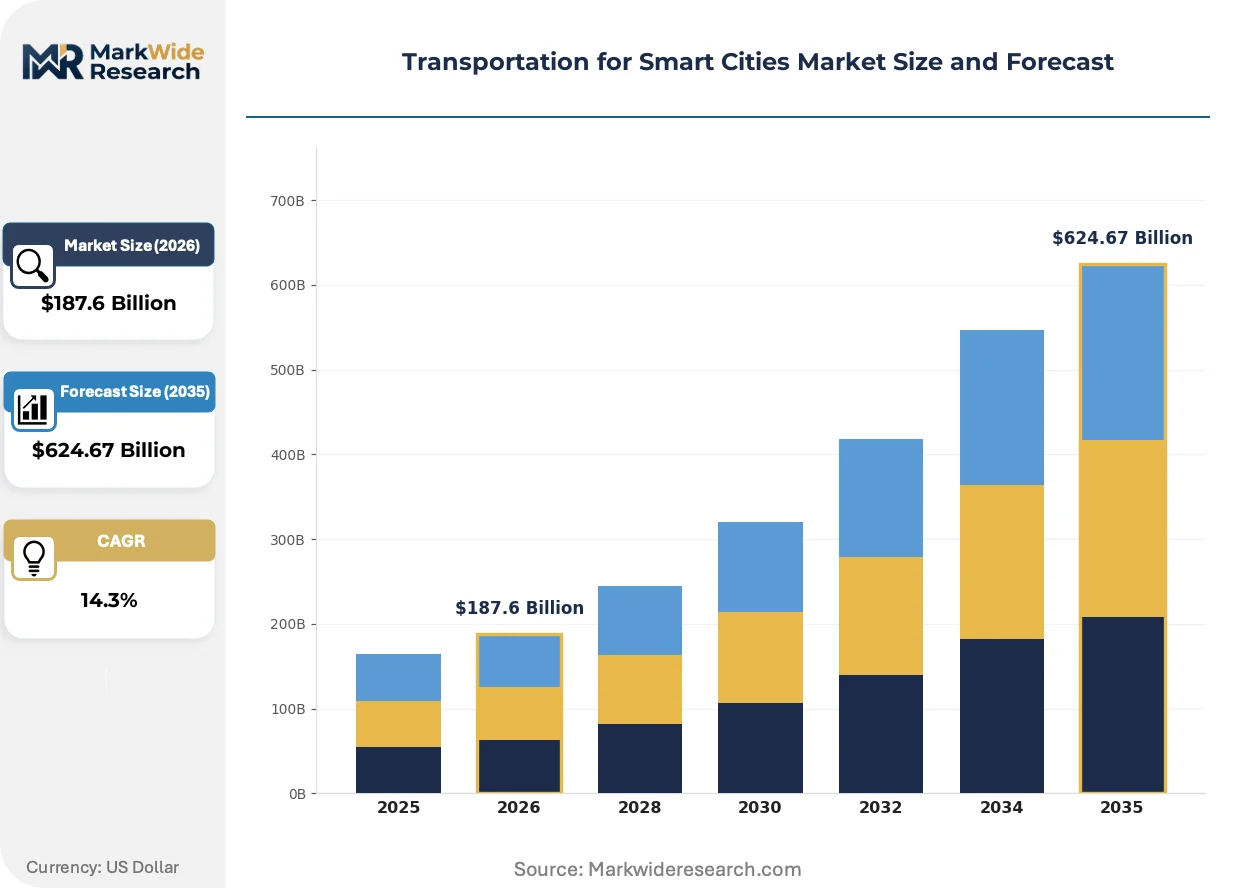
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $624.67 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wi-Fi, 5G, IoT, Blockchain Application: Public Transit, Ridesharing, Freight Management, Smart Parking End User: Government, Private Sector, Citizens, Logistics Providers Service Type: Data Analytics, Infrastructure Maintenance, Fleet Management, Advisory Services |
| Companies Covered | Siemens AG, Cisco Systems, Thales Group, Alstom, Hitachi Ltd., IBM Corporation, Huawei Technologies Co., Ltd., Cubic Corporation, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transportation for Smart Cities Market Strategic Shifts
Real-time data architectures are displacing scheduled optimization models across urban mobility networks, creating demand for hardware-software bundles that guarantee latency performance rather than throughput capacity alone.
Vehicle-to-everything communication modules are supplanting isolated autonomous vehicle perception stacks in municipal procurement specifications. Transit authorities in Singapore, Germany, and the United States now require cooperative intelligent transport systems that share hazard data across mixed fleets. This technology convergence is compressing vendor differentiation toward edge computing latency guarantees and intersection-level hardware durability.
The EU's F-Gas Regulation on transport refrigeration emissions is forcing cold-chain fleet operators to retrofit or replace diesel-powered auxiliary units with electric alternatives. Compliance deadlines in 2027 and 2030 are accelerating R&D spending on battery thermal management systems. Urban delivery segments in Germany and the Netherlands face the steepest retrofit cost exposure under this framework.
Municipal procurement departments are consolidating vendor relationships around platform providers capable of delivering integrated multimodal dashboards. Long-standing equipment suppliers with single-mode expertise face displacement by enterprise software vendors offering subscription-based mobility-as-a-service orchestration. This concentration is most visible in German and French metropolitan authorities where federal funding requires cross-modal data interoperability.
Transportation for Smart Cities Market Segmentation
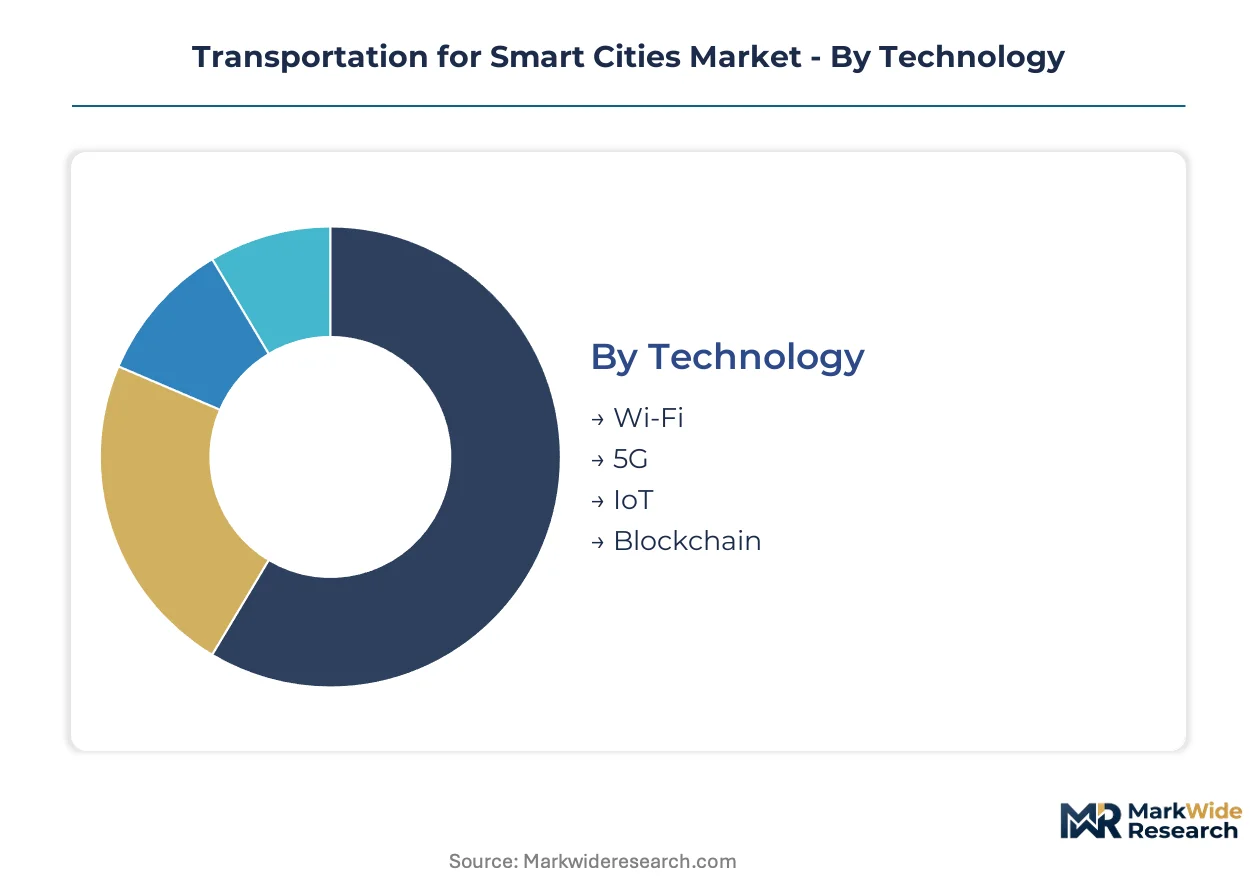
Technology substitution pressures are intensifying across smart city transport architectures as latency requirements harden and security frameworks evolve. Municipal procurement teams now weight interoperability and vendor lock-in risks alongside raw performance specifications when segmenting platform investments.
Technology:
IoT sensor networks face the most acute substitution threat from 5G-enabled edge architectures that promise unified connectivity without fragmented protocol stacks.
- IoT:Low-power wide-area sensor grids capture traffic flow, air quality, and occupancy data through distributed node deployments. German federal smart city funding prioritizes IoT densification for dynamic congestion pricing pilots in Berlin and Hamburg.
- 5G:Millimeter-wave roadside units enable sub-100 millisecond vehicle-to-infrastructure communication with guaranteed quality-of-service tiers. Security screening delays for Chinese-manufactured equipment compress adoption timelines in North American and European jurisdictions.
- Blockchain:Distributed ledger protocols automate toll settlement and ridesharing fare distribution with transparent audit trails.
- Wi-Fi:Legacy 802.11p roadside networks persist in existing deployments but face displacement by cellular-V2X standards.
IoT anchors the volume base while 5G gains share at the steepest rate.
Application:
Revenue concentration clusters around applications with immediate monetization pathways rather than long-term efficiency gains.
- Smart Parking:Sensor-guided space allocation and dynamic pricing platforms generate direct municipal revenue streams. Cash-constrained local governments in France and the Netherlands prioritize parking deployments for their budget closure properties.
- Public Transit:Real-time passenger information and signal prioritization systems coordinate bus and rail networks through centralized control centers. EU Green Deal mobility targets accelerate procurement across German, French, and Dutch urban networks.
- Freight Management:Cold-chain monitoring and last-mile optimization tools address EU F-Gas Regulation compliance deadlines for transport refrigeration.
- Ridesharing:Aggregated mobility platforms integrate micromobility, taxi, and transit access through unified payment interfaces.
Public transit commands the deepest budget allocations while smart parking delivers the strongest margin expansion.
End User:
Budget authority fragmentation creates divergent procurement rhythms across stakeholder categories.
- Government:Municipal transit authorities specify interoperable multimodal platforms with ISO 37120 sustainability certification requirements. German metropolitan procurement cycles compress as federal funding mandates tighten vendor eligibility windows.
- Private Sector:Fleet operators and mobility service providers invest in connected vehicle platforms to meet binding emissions reductions under EU Green Deal frameworks.
- Logistics Providers:Cold-chain specialists face steep retrofit cost exposure from EU F-Gas Regulation compliance deadlines.
- Citizens:End-user demand manifests through adoption of mobility-as-a-service applications rather than direct infrastructure investment.
Government entities dominate capital deployment while private sector adoption expands most quickly.
Service Type:
Margin structures diverge sharply between asset-heavy infrastructure roles and knowledge-based advisory functions.
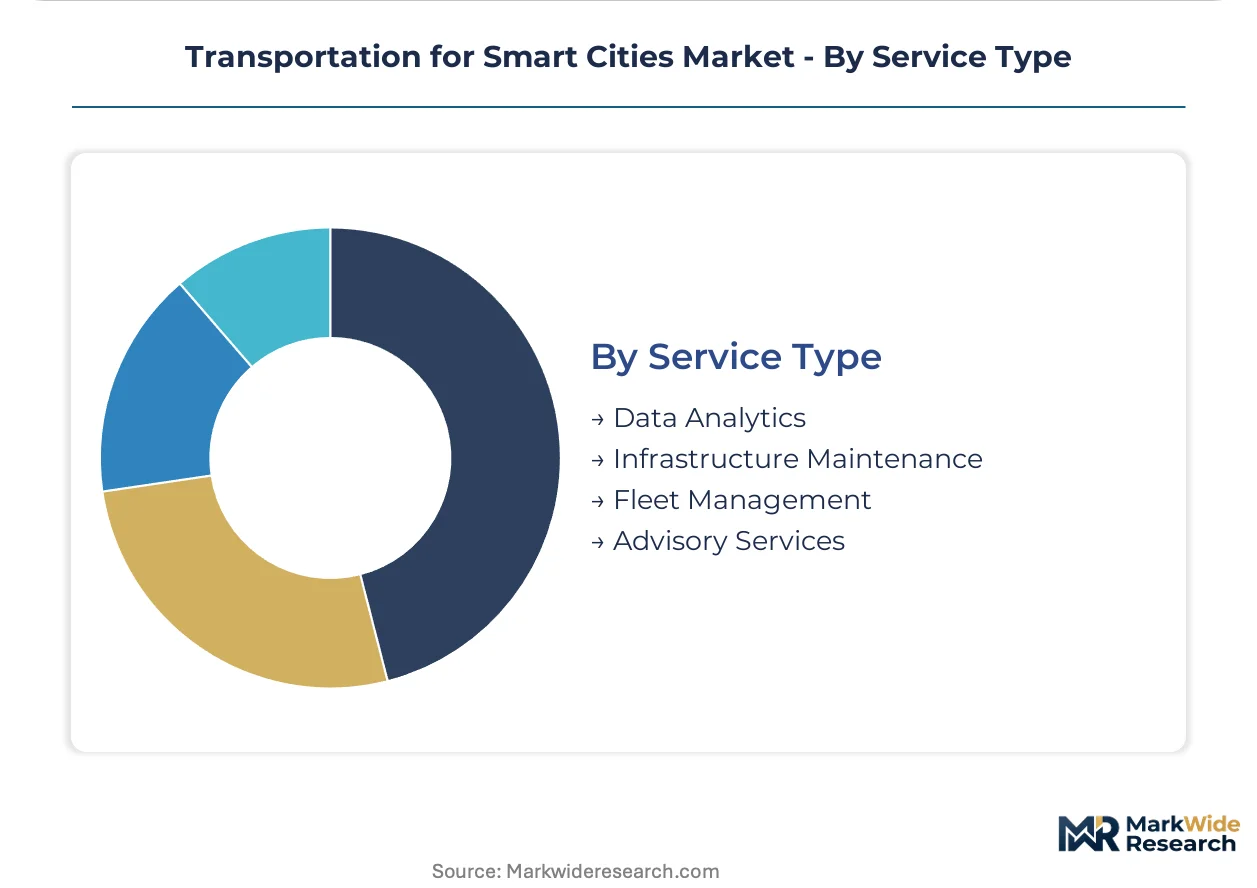
- Fleet Management:Real-time vehicle tracking, predictive maintenance scheduling, and energy optimization software coordinate electric bus and delivery van operations. Chinese MIIT GB-standard connectivity protocols force adaptation costs for foreign platform providers seeking market participation.
- Data Analytics:Traffic pattern recognition and demand forecasting algorithms process intersection-level sensor streams to enable dynamic signal timing.
- Infrastructure Maintenance:Condition monitoring and predictive repair scheduling extend asset life for aging signal systems and roadside units.
- Advisory Services:System integration consulting and procurement support guide municipal authorities through complex multimodal platform selections.
Fleet management captures the largest revenue pool while data analytics climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal transit authorities concentrate procurement authority in Germany, the United States, China, Singapore, and the Netherlands, where federal funding programs and emissions mandates accelerate platform deployment.
Germany
Federal smart city funding prioritizes integrated multimodal networks connecting rail, bus, and micromobility systems. The EU Green Deal's binding mobility emissions targets compress procurement cycles for connected vehicle platforms in Berlin and Hamburg. Siemens AG leverages its rail signaling heritage to dominate traffic management installations across metropolitan networks.
United States
The Department of Transportation's Smart City Challenge framework reshapes procurement specifications for real-time data architectures. FCC spectrum allocations for cellular-V2X enable sub-100 millisecond collision avoidance systems that transit authorities now mandate in RFPs. Cisco Systems anchors its position through edge computing infrastructure processing vehicle-to-everything data streams at intersection level in cities including Los Angeles and Columbus.
China
MIIT mandates GB-standard vehicle connectivity protocols that foreign suppliers must adapt for market participation. Dual carbon goals accelerate electric bus fleet procurement requiring permanent magnet motors dependent on domestic rare earth processing. Huawei Technologies Co., Ltd. competes aggressively on 5G roadside unit pricing, though national security screening delays qualification timelines in Western jurisdictions.
Singapore
Cooperative intelligent transport systems now supplant isolated autonomous vehicle perception stacks in municipal specifications. The Land Transport Authority requires hazard data sharing across mixed fleets through unified vehicle-to-infrastructure protocols. Dense IoT sensor networks enable granular traffic flow monitoring supporting dynamic congestion pricing pilots across the island city-state.
Netherlands
EU F-Gas Regulation compliance deadlines in 2027 and 2030 force cold-chain fleet operators to retrofit diesel-powered auxiliary units with electric alternatives. Cash-constrained local governments prioritize smart parking deployments for immediate revenue generation and budget closure properties. Amsterdam and Rotterdam metropolitan authorities consolidate vendor relationships around platform providers delivering integrated multimodal dashboards.
Transportation for Smart Cities Market Competitive Environment
Player mix skews toward diversified industrial conglomerates with civil infrastructure heritage, creating a tiered structure where rail signaling specialists and telecommunications equipment providers compete for intersection-level hardware contracts. Strategic archetypes include legacy traffic control vendors, enterprise software entrants, and 5G infrastructure specialists. Dominant competitive moves center on strategic partnerships for interoperability certification and portfolio diversification into mobility-as-a-service orchestration.
Within the diversified industrial tier, Siemens AG and Hitachi Ltd. represent archetypes leveraging rail and power infrastructure heritage to anchor traffic management positions. Cisco Systems exemplifies the telecommunications-to-mobility pivot, while Huawei Technologies Co., Ltd. occupies a contested position where aggressive roadside unit pricing confronts security screening barriers in multiple jurisdictions.
| Leading Market Players |
|---|
| Siemens AG |
| Cisco Systems |
| Thales Group |
| Alstom |
| Hitachi Ltd. |
| IBM Corporation |
| Huawei Technologies Co., Ltd. |
| Cubic Corporation |
| Schneider Electric |
| Others |
Value Chain & Pricing Dynamics
Edge computing hardware substitution for legacy traffic control systems simultaneously relocates procurement toward semiconductor fabrication hubs and compresses margin structures through volume-scale economies in sensor manufacturing.
Pricing Analysis
Cost-plus contracts with rare earth magnet indexation dominate electric bus fleet procurement, exposing municipal buyers to neodymium price volatility from Chinese export quotas. Price differentiation rests on ISO 37120 certification tier and intersection-level latency guarantee specifications. Pricing pressure stems from 5G roadside unit commoditization as Huawei Technologies Co., Ltd. compresses hardware margins through aggressive unit pricing. Municipal governments exhibit acute price sensitivity on upfront infrastructure, while fleet operators prioritize total-cost-of-ownership metrics.
Supply Chain Analysis
Inventory lead times for millimeter-wave roadside units stretch eighteen to twenty-four months due to Taiwan and South Korea semiconductor fabrication constraints. Permanent magnet motors draw from Chinese rare earth processing, Japanese precision machining, and German winding equipment. Single-source vulnerability concentrates in Beijing-controlled export licensing for dysprosium and terbium. Distribution runs through systems integrators like Siemens AG and Cisco Systems that bundle hardware with municipal procurement compliance services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against software-defined vehicle platforms that bypass traditional traffic infrastructure entirely. Incumbents must navigate cooperative intelligent transport system disintermediation.
For Market Incumbents: Fortify multimodal data platform positions through backward integration into edge computing silicon supply. Prioritize ISO 37120 certification investment to lock municipal procurement eligibility windows against enterprise software entrants. Anchor recurring revenue through subscription-based mobility-as-a-service orchestration that displaces single-mode equipment vendors.
For New Entrants and Emerging Players: Advisory services for legacy signal system integration represent the most penetrable white-space where incumbents under-serve cash-constrained municipalities. Target Dutch and French metropolitan authorities consolidating vendor relationships around unified dashboards. Pursue channel partnerships with federal funding program administrators to bypass direct municipal sales cycles.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed traffic management software specialists lacking IoT sensor hardware capabilities. Five-to-ten year viability hinges on interoperability protocol consolidation rather than proprietary stack dominance. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for cold-chain fleet retrofit demand acceleration.
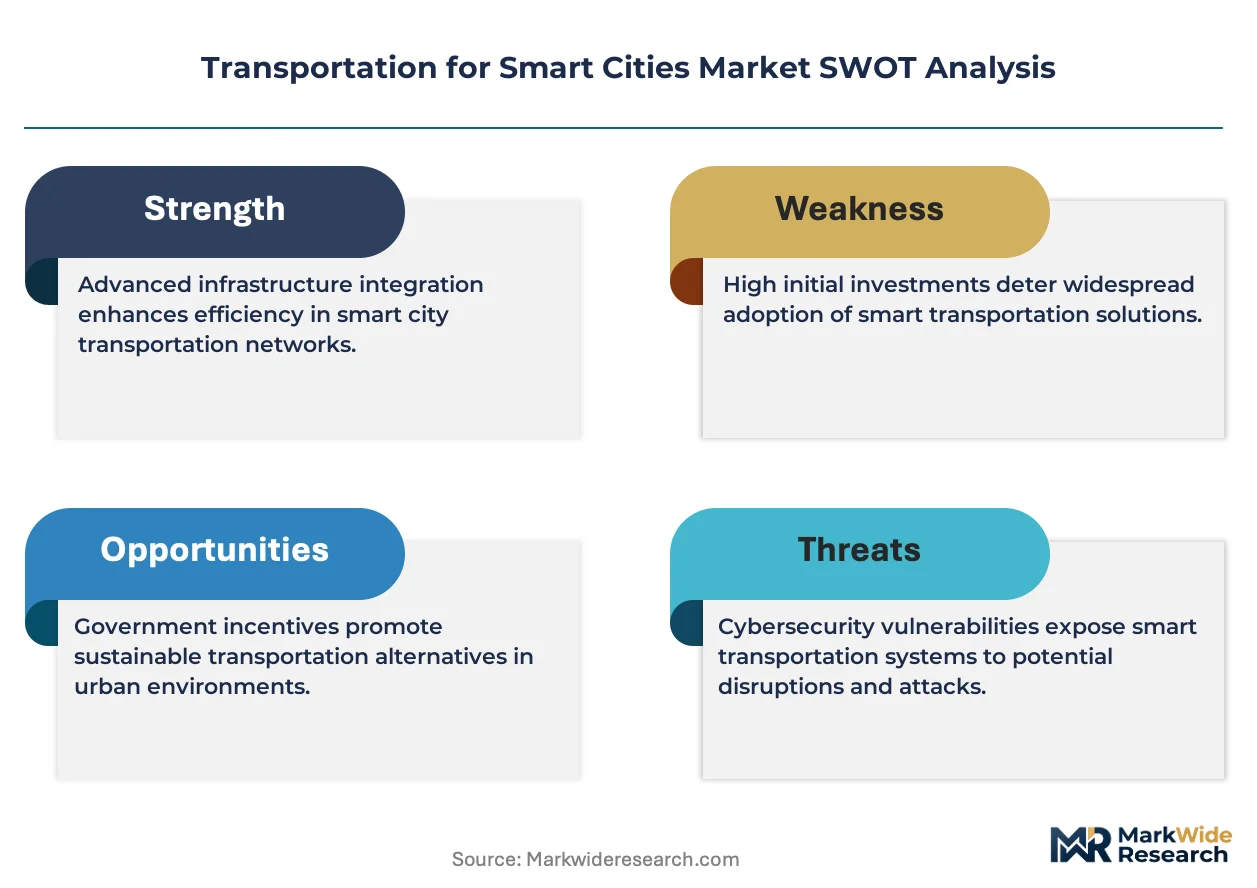
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies rail, bus, and micromobility data architectures under German federal funding compliance. |
| Strategic Partnership | Links edge computing latency guarantees with municipal RFP specifications in Singapore and Columbus. |
| Acquisition of Specialist Firm | Absorbs blockchain settlement pilots for transparent ridesharing fare distribution capabilities. |
| Geographic Expansion | Establishes local presence to navigate MIIT GB-standard adaptation requirements in Chinese markets. |
| Product Launch | Introduces sub-100 millisecond collision avoidance modules meeting FCC cellular-V2X mandates. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, EU procurement databases, and MIIT standardization notices. Municipal transit authority procurement directors, connected vehicle platform engineers, and federal smart city program administrators provided structured input. Trade data from German federal funding disclosures and Singapore Land Transport Authority technical specifications anchored bottom-up segmentation. Top-down validation cross-checked against Cisco Systems and Siemens AG segment reporting.
Segmentation dimensions modeled span technology type, application function, end-user budget authority, and service delivery model across the projection horizon. CAGRs derive from intersection-level deployment velocity curves and municipal capital allocation patterns. Electric bus fleet electrification timelines and 5G roadside unit security screening delays constitute primary forecast sensitivity inputs.
Forecasts assume regulatory continuity in EU Green Deal mobility targets and FCC spectrum allocation regimes; material policy shifts would require re-modeling. Rare earth export quota volatility and national security screening protocol changes present specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Mobility Technologies Market
Smart Transportation Solutions
Transportation Predictive Analytics Market
Smart Transportation Solutions
Ride-Hailing Market
Smart Transportation Solutions
Micro Mobility Market
Smart Transportation Solutions
Transportation Vehicle Automated Passenger Counting (APC) System Market
Smart Transportation Solutions
Micromobility Platform Market
Smart Transportation Solutions
Rail Freight Digital Transformation Market
Smart Transportation Solutions
Sustainable Last-Mile Delivery Network Design Services Market
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Global IoT in Transportation Market
Smart Transportation Solutions
US Smart Highway Market
Smart Transportation Solutions
Automatic Identification Systems (AIS) Market
Smart Transportation Solutions
North America Smart Transportation Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market