
 Smart Car Digital Key System Market | 2026-2036
Smart Car Digital Key System Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Car Digital Key System Market Insights
A capital-intensity divergence between semiconductor specialists and tier-one automotive suppliers is redrawing competitive boundaries in digital key ecosystems. NXP Semiconductors leverages its secure element portfolio to anchor high-assurance authentication architectures for premium OEM programs. Continental AG sustains broad deployment capabilities across Bluetooth Low Energy, NFC, and Ultra-Wideband modules, competing on integration scale with global vehicle platforms.
A smart car digital key system replaces physical metal keys with smartphone- or wearable-based wireless authentication, typically operating through Bluetooth Low Energy, NFC, or Ultra-Wideband radios with dedicated secure elements meeting automotive-grade electromagnetic compatibility standards; its primary purpose is to enable passive entry, remote start authorization, and secure credential sharing while eliminating key fob proliferation. Ultra-Wideband technology leads in precision ranging applications where centimeter-level location accuracy prevents relay attacks, while cloud-based deployment captures the fastest expansion as OEMs migrate key credential management to centralized servers for over-the-air updates and fleet orchestration. Biometric access layers, including fingerprint and facial recognition integration, sit at the margin pool center where hardware authentication meets consumer electronics user experience expectations.
The U.S. NHTSA influences digital key safety integration through vehicle immobilizer and theft-prevention mandates, while European ETSI and CE marking frameworks enforce radio equipment interoperability and electromagnetic compliance across cross-border vehicle sales. China's MIIT and GB standards govern wireless transmission protocols and data localization requirements for connected vehicle credentials. Stakeholders must monitor whether regional divergence in security certification pathways fragments platform development or creates openings for standardized middleware providers.
Market Dynamics
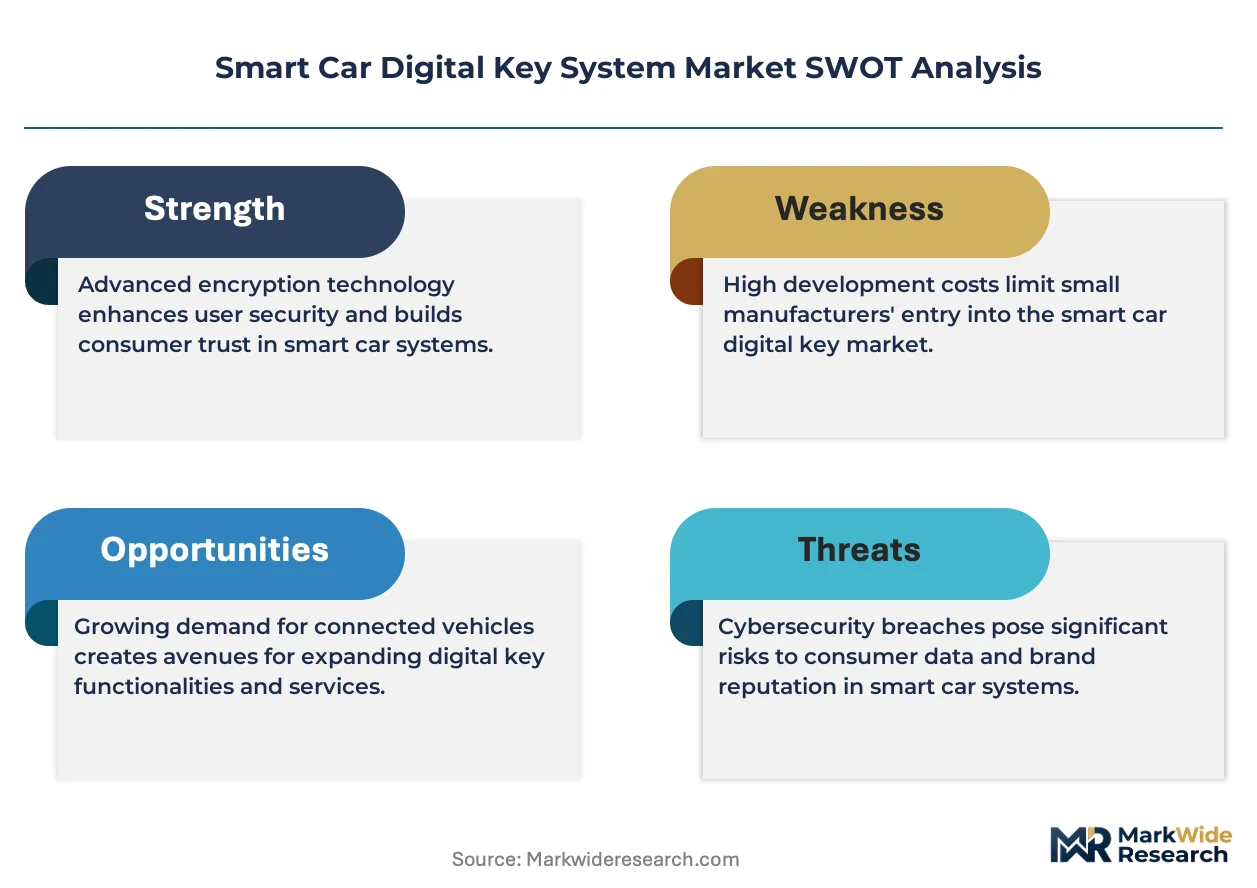
Ultra-Wideband precision ranging is compressing Bluetooth Low Energy's dominance in passive entry architectures, forcing authentication stack redesigns across premium and mass-market vehicle programs simultaneously.
Growth Catalysts
- U.S. NHTSA Theft-Prevention Mandates:Federal immobilizer requirements are accelerating OEM migration from physical key cylinders to encrypted wireless authentication modules.
- Electric Vehicle Platform Standardization:Battery-electric architectures in Germany and China are embedding digital key capability at the electrical backbone design stage rather than as aftermarket add-ons.
- Secure Element Miniaturization:Semiconductor process advances are reducing automotive-grade secure module costs, enabling two-wheeler and commercial fleet deployment.
Market Restraints
- Silicon Supply Concentration:Automotive secure microcontroller fabrication concentrates in Taiwan and South Korea, exposing credential hardware to single-source vulnerability.
- Electromagnetic Compatibility Certification:ETSI and FCC radio equipment approvals add 14-18 month lead times to new frequency band adoption, slowing Ultra-Wideband rollout.
- Relay Attack Countermeasure Costs:Distance-bounding protocols and motion sensors add per-unit expense that mass-market OEMs resist without regulatory compulsion.
Strategic Opportunities
- India Two-Wheeler Digitalization:The country's PLI scheme for automotive electronics is creating first-mover openings in scooter and motorcycle keyless entry systems.
- Fleet Credential Orchestration:Car-sharing platforms in urban China require centralized key lifecycle management, driving cloud-based deployment architecture demand.
- Biometric-Convergence Integration:Fingerprint and facial recognition modules from consumer electronics supply chains are merging with automotive secure elements for multi-factor cabin access.
Industry Challenges
- Automotive Cybersecurity Engineering Talent:Shortage of engineers with both embedded systems and cryptographic protocol expertise is constraining secure element integration timelines.
- Legacy Key Fob Coexistence:OEMs must maintain dual-authentication infrastructure during 5-7 year model transitions, complicating supply chain and service training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Car Digital Key System Market |
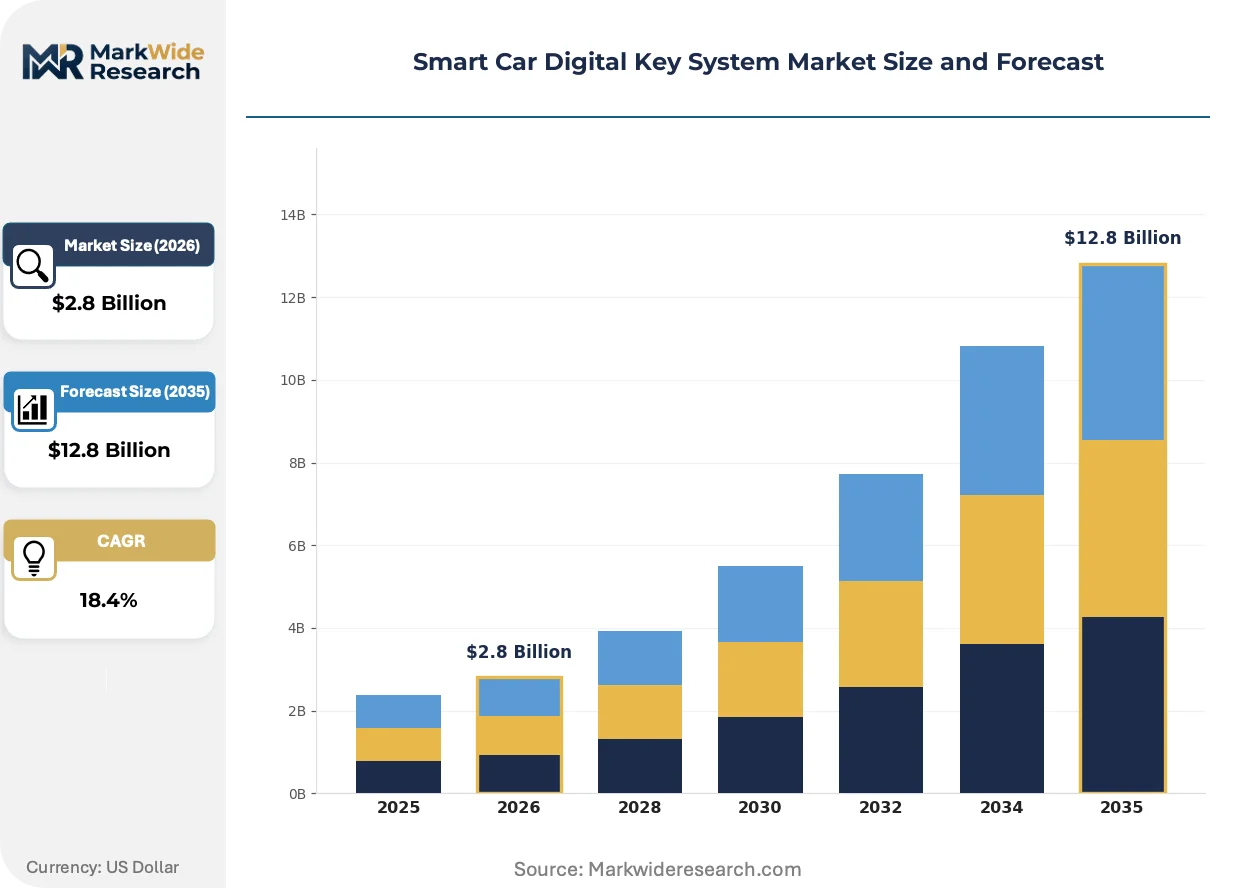
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Bluetooth Low Energy, NFC, Ultra-Wideband, QR Code End User: OEMs, Fleet Operators, Car Sharing Services, Individual Consumers Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Security Feature: Encryption, Biometric Access, Two-Factor Authentication, Remote Locking |
| Companies Covered | Robert Bosch GmbH, Continental AG, NXP Semiconductors, Denso Corporation, BMW AG, Valeo SA, Samsung Electronics, Hyundai Mobis, HELLA GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Car Digital Key System Market Trends and Innovations
Authentication architecture decisions are migrating from tier-one suppliers to OEM electrical engineering teams, compressing traditional component vendor influence windows.
Ultra-Wideband is supplanting Bluetooth Low Energy as the default ranging technology for relay-attack-resistant passive entry. German premium OEMs are mandating UWB for all new electric vehicle launches from 2026. This shift is collapsing the addressable market for BLE-only secure element vendors and forcing module suppliers to add UWB transceiver capability or exit automotive credentialing.
ETSI EN 303 413 standardization for UWB automotive applications is harmonizing European frequency allocation and power limits, enabling cross-border vehicle sales without regional hardware variants. The regulation's industrial consequence is a consolidated European supplier base capable of serving multiple OEM programs from single manufacturing lines. Ultra-Wideband module certification is most affected, with test houses in Germany and France expanding automotive-specific accreditation capacity.
Subscription-based key credential provisioning is displacing perpetual hardware licensing in fleet and mobility service procurement. Rental car operators in the United States are negotiating per-activation pricing rather than capitalizing key infrastructure upfront. This pattern is most visible in corporate fleet management, where CFOs prefer operational expenditure treatment for authentication systems that turnover with vehicle lease cycles.
Smart Car Digital Key System Market Segmentation
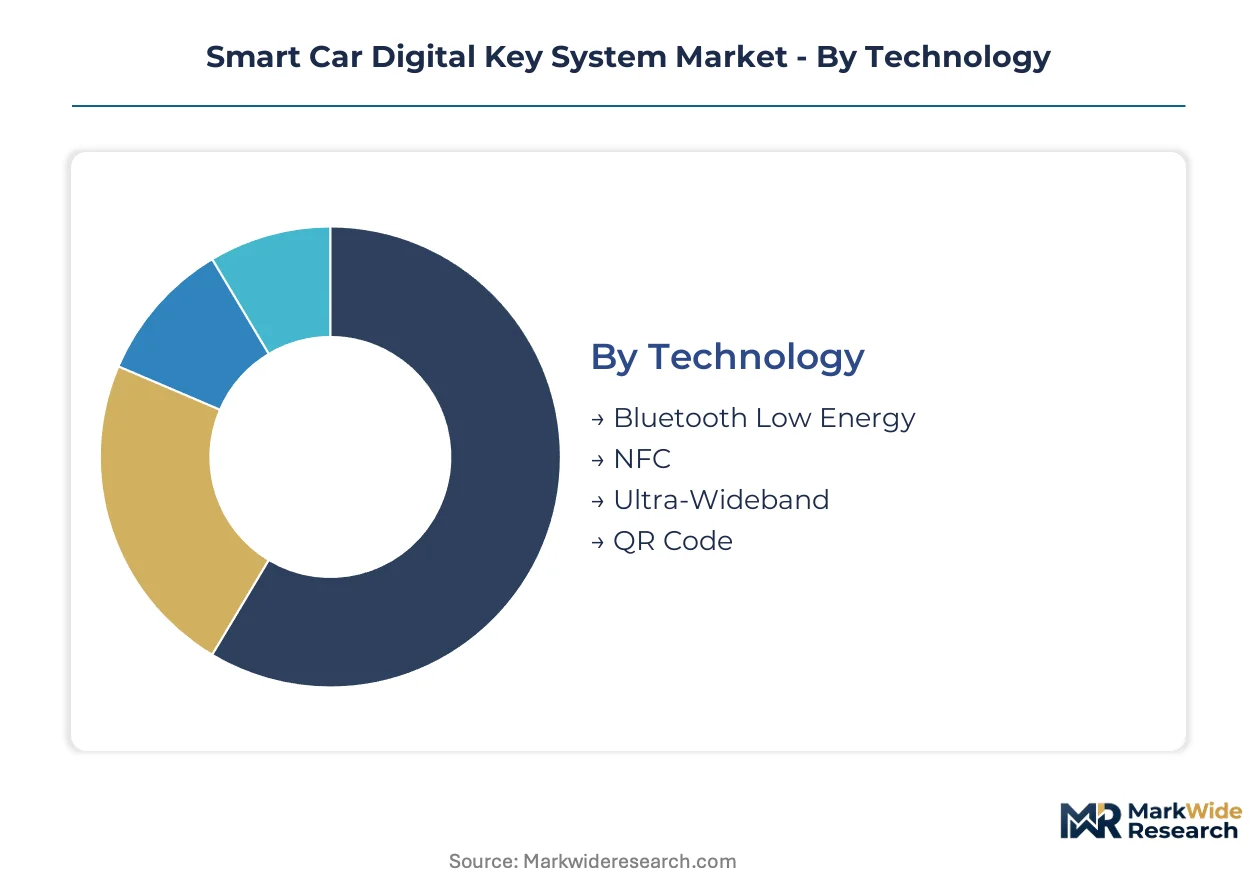
Segmentation in digital key systems reveals how technology substitution pressures and security requirements fragment procurement decisions across automotive value chains. OEMs, fleet operators, and mobility platforms each impose distinct authentication specifications that reshape module supplier priorities.
Technology:
Ultra-Wideband's centimeter-level precision is displacing incumbent radio protocols in passive entry architectures, forcing BLE and NFC vendors to defend position through cost reduction or hybrid integration.
- Bluetooth Low Energy:Mature radio protocol operating in the 2.4 GHz ISM band with sub-meter ranging accuracy and minimal power draw. Demand concentrates in mass-market OEM programs across China and Germany where cost sensitivity outweighs relay-attack resistance requirements.
- Ultra-Wideband:Impulse-radio technology spanning 3.1-10.6 GHz with time-of-flight distance bounding that neutralizes relay attacks through cryptographic challenge-response. German premium OEMs mandate UWB for all battery-electric vehicle launches, compressing BLE's addressable market in luxury segments.
- NFC:Near-field magnetic induction protocol requiring physical proximity under 10 centimeters for credential exchange. Remains essential for smartphone dead-battery operation and valet handoff scenarios.
- QR Code:Optical credential transmission through smartphone camera scanning without dedicated secure elements. Car-sharing services in urban China deploy QR for temporary access provisioning where hardware authentication costs prove prohibitive.
Bluetooth Low Energy anchors the volume base while Ultra-Wideband gains share at the steepest rate.
End User:
Procurement authority is shifting from tier-one suppliers toward OEM electrical engineering teams and fleet CFOs, fragmenting traditional component vendor influence windows.
- OEMs:Vehicle manufacturers integrating digital key capability at electrical backbone design stage rather than aftermarket add-on. German and U.S. automakers specify secure element architectures that cascade through global platform variants.
- Fleet Operators:Corporate and rental fleet managers negotiating subscription-based credential provisioning with per-activation pricing. U.S. rental car operators prefer operational expenditure treatment for authentication systems that turnover with vehicle lease cycles.
- Car Sharing Services:Urban mobility platforms requiring centralized key lifecycle management for transient user access. Chinese operators drive cloud-based deployment architecture demand through high-frequency credential rotation.
- Individual Consumers:Private vehicle owners accessing digital keys through OEM smartphone applications with limited customization. This segment exhibits lowest switching costs and highest sensitivity to biometric convenience features.
Fleet Operators and Car Sharing Services are expanding most quickly while OEMs retain the procurement value concentration.
Deployment:
Cloud migration patterns diverge between consumer convenience priorities and fleet security requirements, creating tiered infrastructure investment strategies.
- Cloud-Based:Centralized credential management on OEM or third-party servers enabling over-the-air updates and fleet orchestration. Chinese car-sharing platforms and U.S. rental operators favor this model for operational flexibility.
- On-Premise:Local secure element storage within vehicle ECUs without external network dependency. German premium OEMs maintain on-premise architectures for cybersecurity compliance with ETSI standards.
- Hybrid:Split credential storage with local authentication and cloud-based authorization logging. Balances offline reliability with fleet visibility for corporate procurement.
- Edge Computing:Distributed processing at vehicle-gateway level reducing latency for real-time access decisions. Emerging in autonomous vehicle programs where millisecond authentication timing affects safety systems.
Cloud-Based deployment climbs the fastest while Hybrid architectures capture the transitional investment wave.
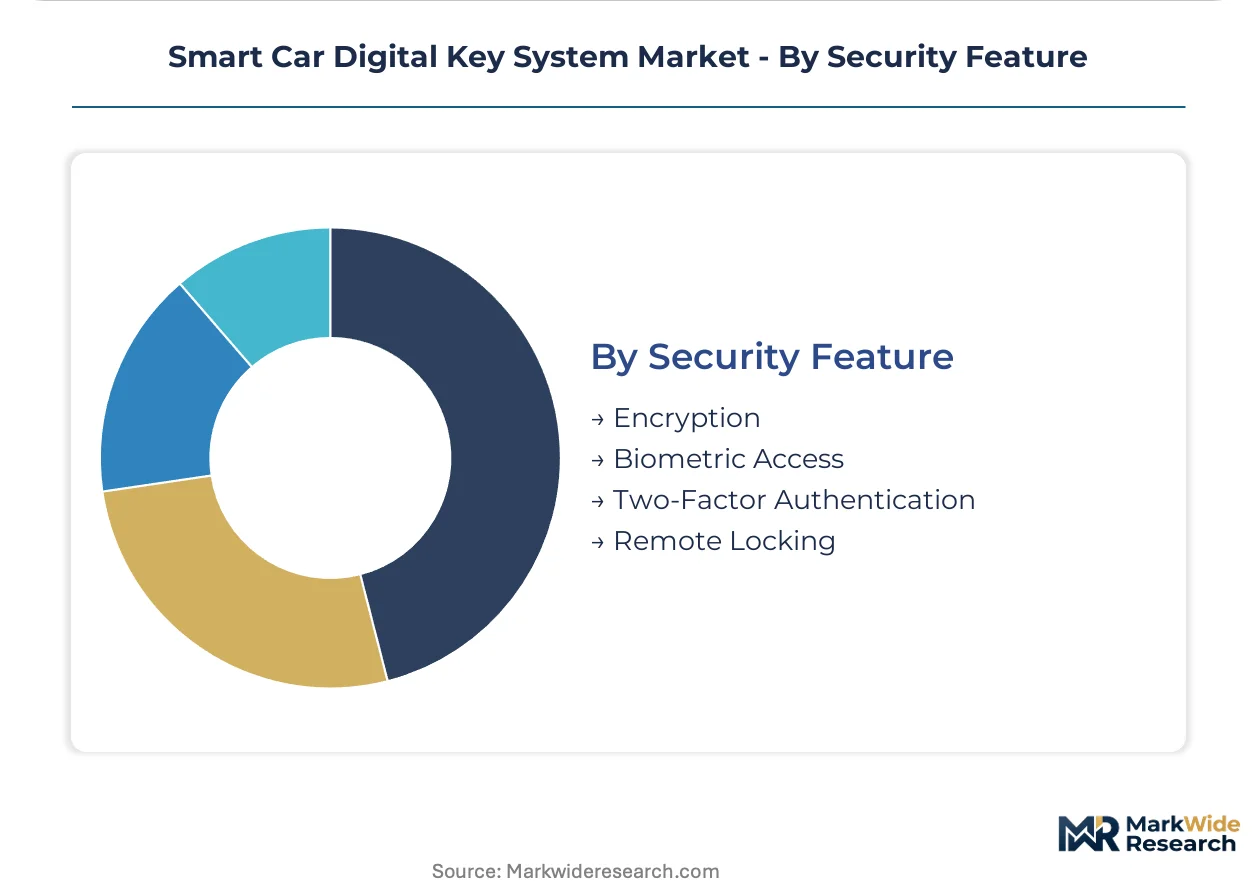
Security Feature:
Regulatory mandates from NHTSA and ETSI are hardening baseline encryption requirements while biometric layers differentiate premium positioning.
- Encryption:AES-128 or AES-256 cryptographic protocols protecting credential transmission against interception. Mandatory baseline under U.S. federal immobilizer requirements and European radio equipment directives.
- Biometric Access:Fingerprint or facial recognition integration from consumer electronics supply chains merging with automotive secure elements. German and U.S. premium OEMs deploy biometric layers for multi-factor cabin access differentiation.
- Two-Factor Authentication:Combined possession and knowledge factors requiring smartphone proximity plus PIN entry. Fleet operators in regulated industries mandate this for commercial vehicle access.
- Remote Locking:Cellular or satellite-enabled vehicle immobilization independent of local radio range. Insurance providers in Germany and the United States incentivize remote locking capability through premium discounts.
Encryption anchors compliance baselines while Biometric Access expands most quickly at the premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German buyers absorb premium pricing for Ultra-Wideband security modules, while Indian two-wheeler manufacturers drive hard bargains on Bluetooth Low Energy units. Chinese fleet operators prioritize cloud-deployment flexibility over hardware ruggedness.
United States
NHTSA theft-prevention mandates accelerate encrypted wireless authentication adoption across Detroit automakers. FCC radio equipment approvals enforce 14-18 month lead times for new frequency certification. Automotive electronics clusters in Michigan and California anchor tier-one supplier engineering centers for digital key module development.
Germany
Premium OEMs mandate Ultra-Wideband for all battery-electric vehicle launches from 2026. ETSI EN 303 413 standardization harmonizes European frequency allocation and power limits for cross-border sales. The Stuttgart-Munich corridor concentrates secure element R&D facilities serving multiple global platform programs.
China
Urban car-sharing platforms drive cloud-based credential orchestration demand through high-frequency key rotation. MIIT and GB standards govern wireless transmission protocols and data localization for connected vehicle credentials. Shenzhen and Shanghai host the dominant automotive semiconductor packaging operations for regional OEM supply.
India
PLI scheme incentives for automotive electronics create first-mover openings in scooter and motorcycle keyless entry systems. BIS certification requirements shape local manufacturing investment decisions. The Chennai-Bengaluru belt attracts module assembly operations targeting two-wheeler OEM export programs.
South Korea
Domestic automakers integrate digital keys at electrical backbone design stage for battery-electric platforms. MFDS-equivalent automotive cybersecurity guidelines influence secure element procurement specifications. Seoul-Incheon clusters concentrate Bluetooth and NFC module fabrication for Asia-Pacific vehicle programs.
Smart Car Digital Key System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in digital key ecosystems. Tier-one automotive suppliers compete on module integration scale across global vehicle platforms, while semiconductor specialists anchor high-assurance authentication architectures. Three archetypes dominate: secure element purveyors, multi-protocol module integrators, and OEM-captive electronics divisions. Consolidation pressure intensifies through strategic partnerships for Ultra-Wideband capability and backward integration into secure microcontroller supply.
Within the multi-protocol integration tier, Continental AG exemplifies the European automotive supplier archetype with broad deployment capabilities spanning radio technologies. NXP Semiconductors anchors the secure element specialist position, leveraging semiconductor process expertise for automotive-grade authentication hardware. Robert Bosch GmbH occupies a position spanning both module integration and tier-one supplier relationships with premium OEM programs. These three entities represent the competitive tension between semiconductor specialists and full-system integrators reshaping procurement authority in digital key markets.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| NXP Semiconductors |
| Denso Corporation |
| BMW AG |
| Valeo SA |
| Samsung Electronics |
| Hyundai Mobis |
| HELLA GmbH & Co. KGaA |
| Others |
Pricing and Supply Chain Analysis
Wafer-scale secure element manufacturing in Taiwan and South Korea generates steep cost curves that compress price floors for automotive-grade authentication modules while simultaneously concentrating supply leverage among foundry operators serving NXP Semiconductors and Continental AG.
Pricing Analysis
After-sales service contracts and extended warranty bundles on digital key infrastructure now drive lifetime value capture for tier-one suppliers. Pricing stratifies across premium UWB modules with relay-attack resistance, standard BLE units for mass-market deployment, and economy NFC-only configurations for two-wheeler applications. Cost compression in BLE secure elements is intensifying because Chinese module assemblers are backward integrating into chip packaging. Fleet operators exhibit highest price sensitivity due to per-activation subscription models, while German premium OEMs absorb premium UWB pricing for theft-prevention compliance.
Supply Chain Analysis
Automotive secure microcontroller inventory cycles now stretch 14-18 months due to ETSI and FCC certification queues for new UWB frequency bands. Fabrication concentrates in Taiwan, South Korea, and Germany for automotive-grade secure elements. Raw material dependencies include silicon wafers, rare-earth magnets for NFC antennas, and lithium niobate substrates for precision timing. Single-source vulnerability in Taiwan foundry capacity exposes credential hardware to geopolitical disruption. Distribution runs through tier-one automotive supplier networks directly into OEM electrical backbone integration programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology substitution between BLE and UWB protocols fragments procurement authority, creating specialist openings for secure element purveyors and cloud-credential orchestrators outside traditional tier-one supply hierarchies.
For Market Incumbents: Consolidate UWB transceiver capability through strategic partnerships or captive R&D investment to defend against semiconductor specialists encroaching on module integration. Secure NHTSA and ETSI certification pipelines early to lock out emerging competitors during 14-18 month approval windows. Prioritize backward integration into secure microcontroller supply to reduce Taiwan foundry dependency. For New Entrants and Emerging Players: Anchor in India's PLI-subsidized two-wheeler electronics corridor where BLE cost sensitivity outpaces UWB adoption timelines. Target cloud-based credential orchestration for Chinese car-sharing platforms requiring high-frequency key rotation. Pursue biometric-convergence partnerships with consumer electronics fingerprint module suppliers as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors secure element specialists with automotive-grade certification moats over module integrators facing BLE commoditization. Long-term viability rests on UWB adoption velocity in premium electric vehicle platforms and cloud-deployment penetration in fleet segments. Watch for ETSI EN 303 413 harmonization completion as the signal indicating European supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| UWB Module Certification Pipeline | ETSI and FCC approvals in Germany and the United States lock in 14-18 month competitive moats. |
| Secure Element Backward Integration | Captive foundry relationships in Taiwan and South Korea reduce single-source vulnerability exposure. |
| Cloud Credential Orchestration Platform | Chinese fleet operators and U.S. rental car platforms drive subscription-based recurring revenue models. |
| Biometric-Convergence Partnership | Fingerprint and facial recognition modules from consumer electronics merge with automotive secure elements. |
| India Two-Wheeler Manufacturing Footprint | PLI scheme incentives in the Chennai-Bengaluru belt capture scooter and motorcycle keyless entry demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across OEM electrical engineering teams, tier-one automotive supplier procurement, fleet CFOs, car-sharing platform operations heads, and secure element R&D directors. Primary interview insights triangulated against vehicle production databases, IHS Markit registration data, SEC filings from semiconductor specialists, ETSI standardization documents, and NHTSA regulatory filings. Bottom-up module shipment estimates and top-down OEM platform penetration rates were cross-validated to anchor volume figures.
Across the analysis window, the forecasting framework modeled technology substitution dynamics, deployment architecture migration, and security feature tiering alongside vehicle class, propulsion architecture, and regional production cluster dimensions. CAGRs were derived from S-curve adoption modeling for UWB penetration in premium electric vehicles and cloud-deployment scaling in fleet segments. Industry-specific inputs included ETSI EN 303 413 harmonization timelines and NHTSA theft-prevention mandate implementation schedules.
Decision-makers should treat outputs as directional under assumptions of sustained UWB cost reduction and stable Taiwan foundry capacity; material deviation in semiconductor supply geography or regulatory certification timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Rail Freight Digital Transformation Market
Smart Transportation Solutions
Temperature-Controlled Last-Mile Delivery Services Market
Smart Transportation Solutions
Smart Chassis Market
Smart Transportation Solutions
Off-Street Parking Management System Market
Smart Transportation Solutions
Automotive V2X Market
Smart Transportation Solutions
Mobility Technologies Market
Smart Transportation Solutions
Nordic Bike Sharing Market
Smart Transportation Solutions
Electric Kick Scooters Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
Global Parking Management Software Market
Smart Transportation Solutions
Smart Car Tracking Systems Market
Smart Transportation Solutions
Global Smart Commute Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
Transportation Predictive Analytics Market
Smart Transportation Solutions
Global Connected Mobility Solutions Market
Smart Transportation Solutions
Big Data Analytics in Transportation Market