
 Benzotrifluoride Market | 2026-2036
Benzotrifluoride Market Size, Share, and Industry Trends Forecast 2026-2036
Benzotrifluoride Market Analysis
Capital-intensity divergence between integrated fluorochemical producers and merchant chemical suppliers is redrawing competitive boundaries in benzotrifluoride supply. Navin Fluorine International Limited leverages captive fluorine feedstock access to sustain cost leadership in pharmaceutical-grade output. Zhejiang Weihua Chemical Co. Ltd. anchors its position through specialized intermediate production for agrochemical clients. BASF SE differentiates via stringent quality protocols that dominate European pharmaceutical sourcing requirements.
Benzotrifluoride is a fluorinated aromatic compound with the formula C7H5F3, typically produced through catalytic fluorination of toluene derivatives and valued for its chemical stability, low surface tension, and solvency power in specialized industrial processes. Its primary purpose centers on serving as a fluorinated building block and process solvent in pharmaceutical synthesis, agrochemical manufacturing, and electronics cleaning applications. The solvent product type captures established volume given its role in extraction and purification workflows, while the intermediate category leads value generation as pharmaceutical and agrochemical makers demand higher-purity grades for downstream synthesis. End-use demand from the pharmaceuticals sector commands premium positioning due to stringent purity certifications, whereas electronics applications are gaining traction as semiconductor fabricators adopt fluorinated cleaning chemistries.
Regulatory oversight from the EPA in the United States, ECHA under REACH in Europe, and MEE in China shapes benzotrifluoride production standards, emissions controls, and market access conditions across major supply corridors. These frameworks compel manufacturers to invest in waste treatment infrastructure and toxicity documentation, elevating compliance costs for non-integrated producers. Stakeholders must monitor evolving fluorochemical restrictions under the EU F-Gas Regulation and corresponding state-level air quality mandates in the United States to anticipate supply chain reconfiguration and qualification requirements.
Market Dynamics
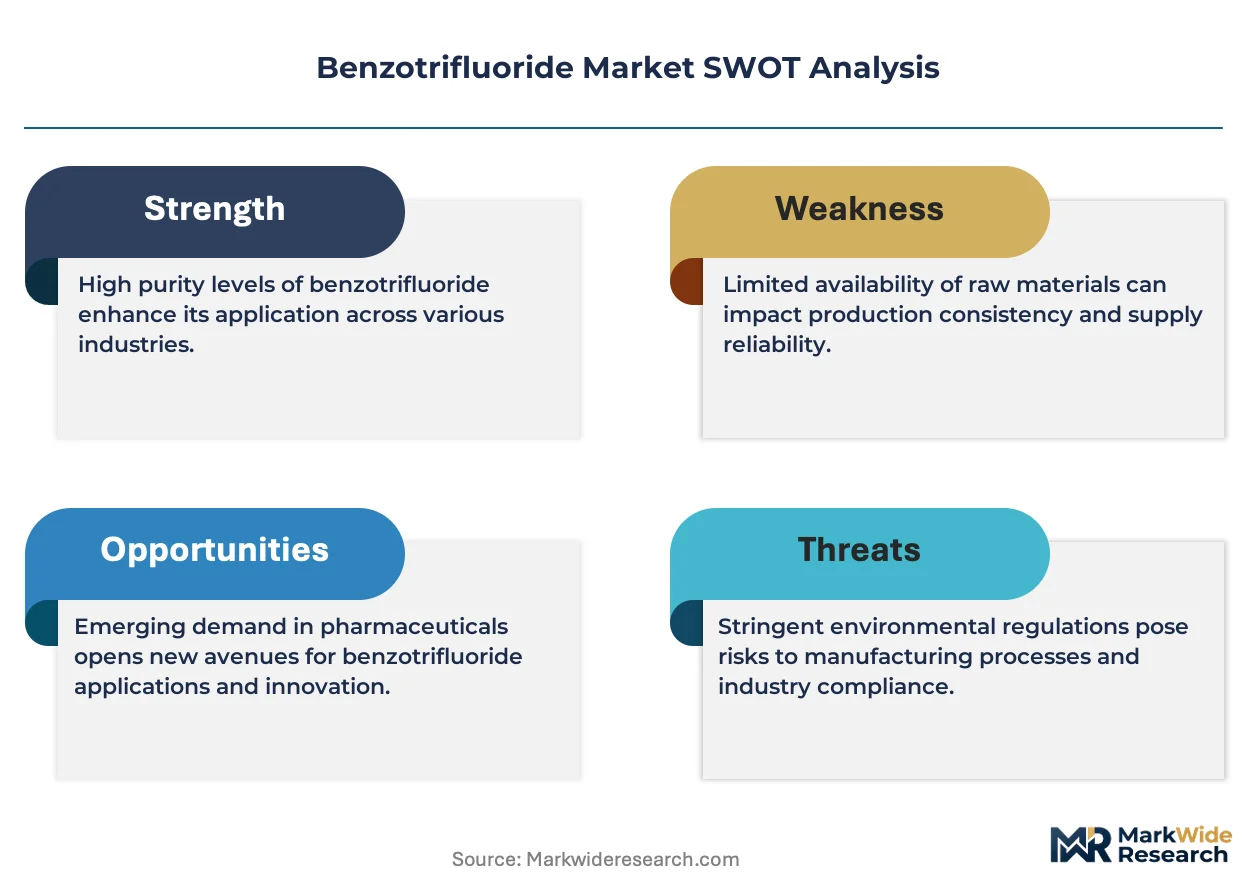
Pharmaceutical manufacturers are consolidating their supplier bases around integrated fluorochemical producers capable of delivering pharmaceutical-grade benzotrifluoride with full REACH and EPA documentation, compressing margins for non-integrated merchant suppliers.
Growth Catalysts
- REACH compliance mandates:European pharmaceutical formulators now require full toxicity dossiers for fluorinated intermediates, advantaging suppliers with pre-qualified documentation.
- Semiconductor cleaning chemistry adoption:Fabricators in South Korea and Taiwan are qualifying benzotrifluoride-based formulations for advanced node wafer cleaning.
- China domestic capacity expansion:Specialty chemical producers in Jiangsu and Zhejiang provinces are scaling pharmaceutical-grade output to substitute imports.
Market Restraints
- Fluorine feedstock volatility:Anhydrous hydrogen fluoride prices fluctuate with phosphate fertilizer production cycles, squeezing non-integrated producers.
- EU F-Gas Regulation tightening:Emissions reporting thresholds for fluorinated compounds are lowering, adding compliance overhead for European manufacturing.
- Aqueous cleaning formulation substitution:Electronics assemblers in cost-sensitive segments are trialing water-based alternatives for non-critical cleaning steps.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO-aligned producers are expanding API synthesis capacity, creating demand for import-substituted fluorinated building blocks.
- Flow chemistry integration:Continuous processing equipment vendors are partnering with benzotrifluoride suppliers to develop dedicated reactor modules.
- US Inflation Reduction Act domestic content:Pharmaceutical manufacturers are reshoring active ingredient production to qualify for federal procurement preferences.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA and EMA qualification batches require 18-24 month validation cycles before commercial supply authorization.
- Fluorochemical waste treatment capex:New production facilities must install calcium fluoride recovery systems meeting MEE discharge standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benzotrifluoride Market |
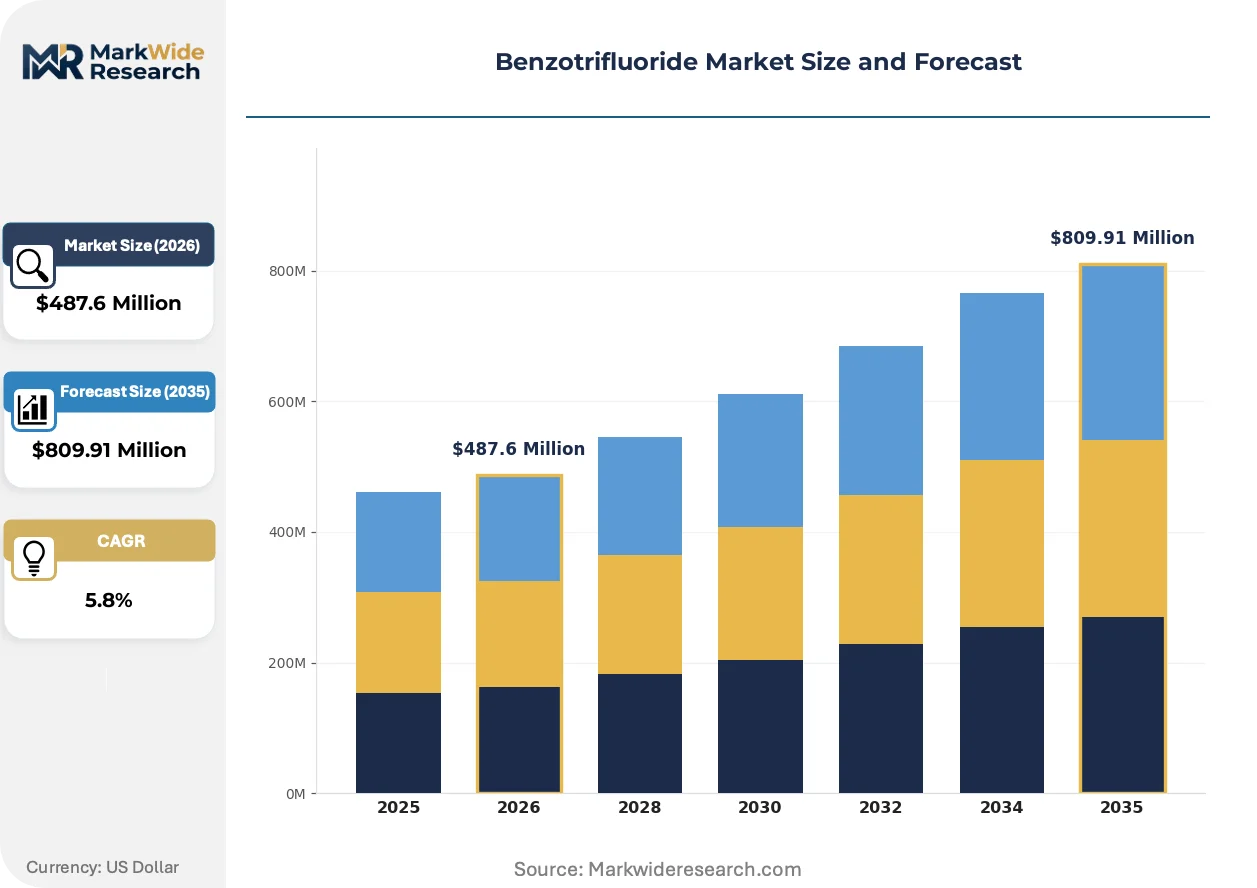
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Intermediate, Chemical Reagent, Additive End Use Industry: Pharmaceuticals, Agriculture, Electronics, Coatings Application: Synthesis, Extraction, Cleaning, Coating Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Navin Fluorine International Limited, SRF Limited, Mitsubishi International PolymerTrade Corporation, Zhejiang Weihua Chemical Co. Ltd., Zhejiang Kangfeng Chemicals Co. Ltd., Wylson-Chem Co. Ltd., BASF SE, Central Glass Co., Ltd., Arkema S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benzotrifluoride Market Emerging Trajectories
Fluorination process intensification and regulatory data digitization are compressing development timelines for pharmaceutical-grade benzotrifluoride while reshaping supplier qualification protocols across major manufacturing clusters.
Membrane-based fluorine recovery systems are decomposing the traditional reliance on thermal decomposition for hydrogen fluoride regeneration. Pharmaceutical-grade producers in Germany and Japan are piloting these units to reduce feedstock costs by fifteen to twenty percent. The technology is decomposing capital allocation patterns, with integrated producers redirecting maintenance budgets toward membrane replacement cycles rather than conventional furnace overhauls.
REACH Annex XVII restrictions on persistent organic pollutants are forcing reformulation of legacy agrochemical intermediates containing legacy fluorinated solvents. European formulators are accelerating qualification of benzotrifluoride-based alternatives with improved biodegradation profiles. Agrochemical end-use applications are absorbing the bulk of compliance-driven switching costs as manufacturers resubmit dossiers ahead of sunset dates.
Direct supplier contracts are displacing distributor-mediated procurement for pharmaceutical-grade volumes above fifty metric tons annually. Large API manufacturers in Switzerland and the United States are negotiating multi-year offtake agreements with integrated fluorochemical producers. This pattern concentrates most visible in oncology and antiviral therapeutic segments where supply security outweighs spot-price flexibility.
Benzotrifluoride Market Segmentation
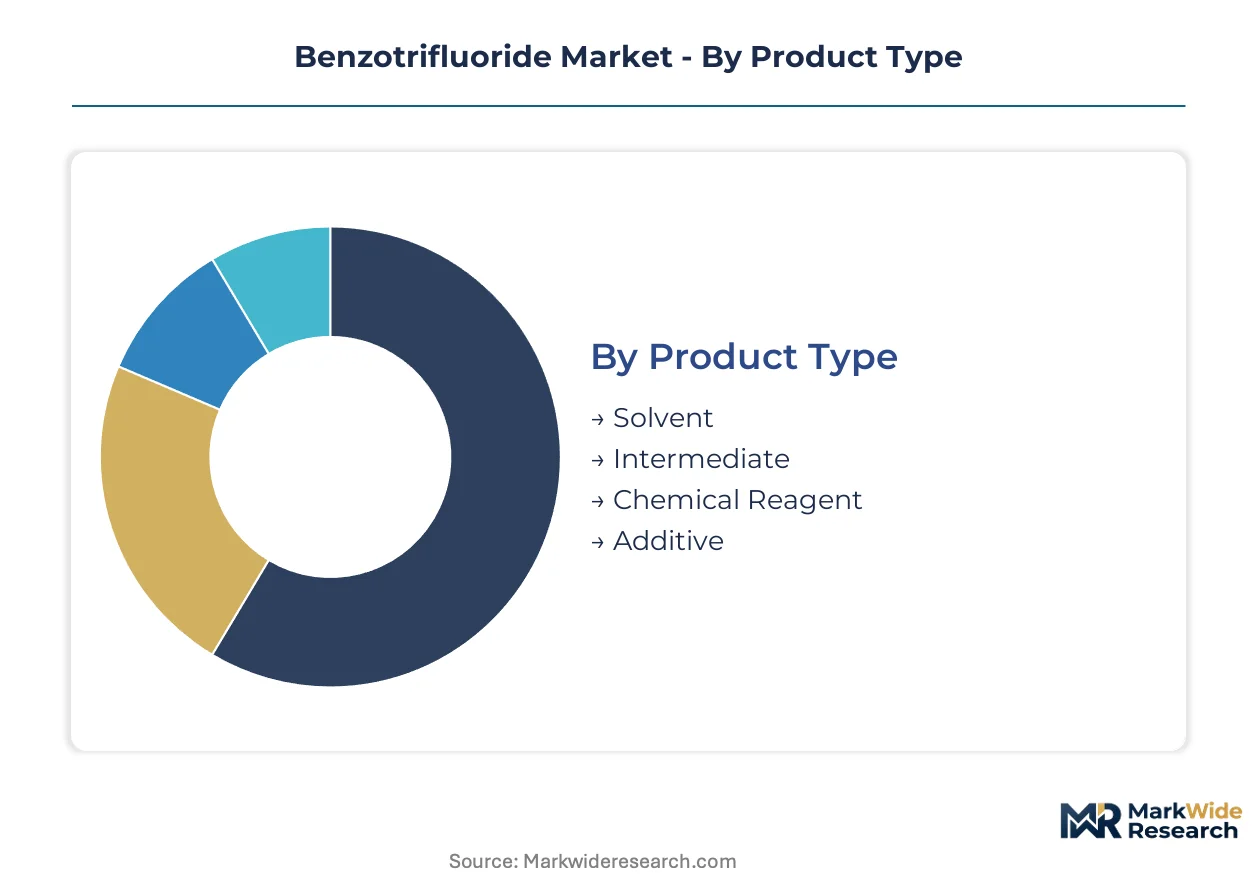
Segmentation in benzotrifluoride markets reveals how purity grades and supply chain configurations create divergent margin structures. Pharmaceutical-grade specifications command substantial premiums over industrial solvent grades due to documentation burdens and qualification timelines.
Product Type:
Margin pools concentrate in pharmaceutical-grade intermediates where certification costs erect barriers against commodity competition.
- Solvent:Technical-grade material serves extraction and purification workflows across agrochemical and electronics manufacturing. Demand concentrates in Taiwan and South Korea where semiconductor fabricators qualify fluorinated cleaning formulations for advanced node production.
- Intermediate:Higher-purity grades function as fluorinated building blocks in active pharmaceutical ingredient synthesis. Pharmaceutical manufacturers in Switzerland and the United States consolidate procurement around integrated producers offering full REACH and EPA documentation.
- Chemical Reagent:Laboratory-scale volumes support analytical and research applications with specialized packaging requirements.
- Additive:Niche incorporation into specialty coatings and polymer formulations depends on surface tension modification properties.
Intermediate holds installed capacity. Solvent is rotating up the share rankings.
End Use Industry:
Application-specific purity requirements segment customers into distinct procurement tiers with divergent price elasticities.
- Pharmaceuticals:FDA and EMA qualification protocols demand 18-24 month validation cycles for pharmaceutical-grade supply. Oncology and antiviral therapeutic segments prioritize supply security over spot-price flexibility.
- Agriculture:REACH Annex XVII restrictions on persistent organic pollutants accelerate reformulation of legacy agrochemical intermediates toward benzotrifluoride-based alternatives with improved biodegradation profiles.
- Electronics:Fabricators in South Korea adopt benzotrifluoride-based chemistries for wafer cleaning as aqueous alternatives face limitations at sub-7 nanometer nodes.
- Coatings:Specialty formulations leverage low surface tension properties for uniform film formation in high-performance industrial applications.
Pharmaceuticals anchors premium positioning. Electronics is gaining share fastest.
Application:
Process integration depth determines whether customers purchase commodity volumes or negotiate dedicated supply arrangements.
- Synthesis:Pharmaceutical and agrochemical manufacturers incorporate benzotrifluoride as a fluorinated building block in multi-step reaction sequences requiring anhydrous conditions.
- Extraction:Solvent applications in purification workflows favor technical grades with established handling protocols across chemical processing facilities.
- Cleaning:Electronics assemblers evaluate fluorinated formulations against water-based alternatives for critical substrate preparation steps.
- Coating:Surface modification applications in specialty materials production require consistent evaporation rates and residue specifications.
Synthesis commands dedicated supply contracts. Cleaning is climbing the fastest.
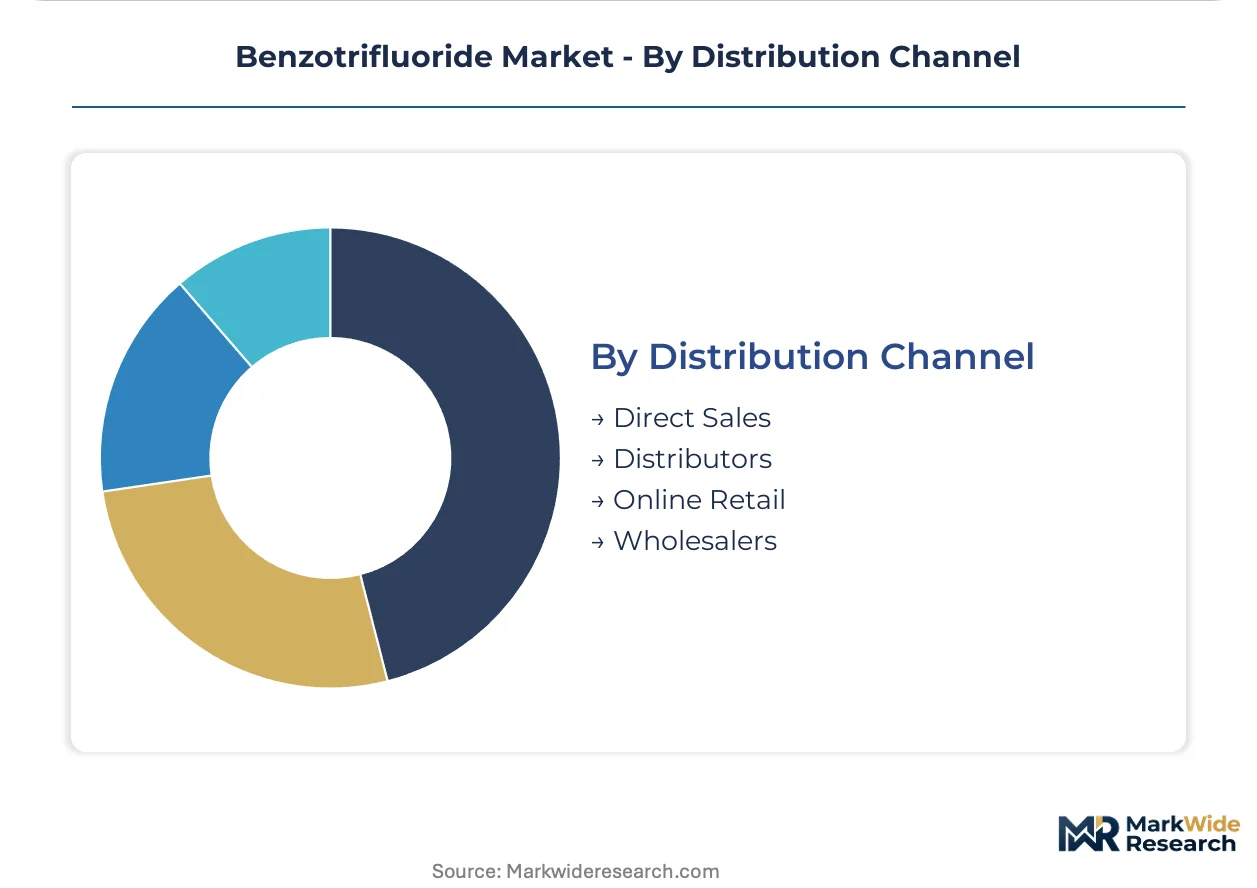
Distribution Channel:
Volume thresholds and documentation requirements reshape how procurement flows reach end-users across geographic clusters.
- Direct Sales:Annual volumes exceeding fifty metric tons now route through multi-year offtake agreements between API manufacturers and integrated fluorochemical producers.
- Distributors:Regional chemical distributors serve mid-scale pharmaceutical and agrochemical formulators requiring smaller batch flexibility.
- Online Retail:Laboratory-scale reagent volumes move through specialized chemical supply platforms serving research institutions.
- Wholesalers:Industrial solvent grades reach coatings and electronics manufacturers through bulk chemical wholesalers in manufacturing clusters.
Direct Sales holds contract value concentration. Distributors is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for benzotrifluoride varies sharply across end-use segments. Electronics fabricators in South Korea and Taiwan accept substantial premiums for ultra-high-purity grades, while agrochemical formulators in India and Southeast Asia prioritize cost efficiency over certification depth.
China
Domestic specialty chemical producers in Jiangsu and Zhejiang provinces are scaling pharmaceutical-grade output to displace historical import dependence. MEE discharge standards for calcium fluoride recovery are elevating capital requirements for new fluorination facilities. The Yangtze River Delta chemical corridor now hosts expanded intermediate production serving both domestic API manufacturers and export markets.
United States
Pharmaceutical manufacturers are reshoring active ingredient synthesis to qualify for IRA domestic content procurement preferences. EPA emissions documentation requirements for fluorinated intermediates are compressing supplier qualification timelines. The Gulf Coast petrochemical corridor maintains integrated fluorochemical capacity serving agrochemical and electronics end-users.
Germany
EU F-Gas Regulation tightening is forcing reformulation of legacy agrochemical intermediates toward benzotrifluoride-based alternatives with improved biodegradation profiles. ECHA REACH compliance mandates are advantaging suppliers with pre-qualified toxicity dossiers. The Rhine-Ruhr industrial cluster concentrates pharmaceutical-grade production serving Swiss and domestic formulators.
India
CDSCO-aligned API manufacturers are expanding fluorinated building block demand as import substitution accelerates. The country's national pharmaceutical regulator is aligning inspection protocols with FDA and EMA standards to accelerate export qualification. Gujarat and Maharashtra chemical corridors are attracting capacity investments from domestic fluorochemical specialists.
Japan
Semiconductor fabricators are qualifying benzotrifluoride-based formulations for sub-7 nanometer wafer cleaning as aqueous alternatives face technical limitations. METI industrial chemical frameworks are shaping emissions control investments for existing fluorination assets. The Chubu region around Nagoya anchors electronics-grade supply serving domestic and Taiwanese chipmakers.
Benzotrifluoride Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes in benzotrifluoride supply. Integrated fluorochemical producers with captive hydrogen fluoride access dominate pharmaceutical-grade segments, while merchant suppliers compete on technical-grade solvent volumes. The market structure separates into three tiers: multinational chemical conglomerates with full regulatory documentation, regional specialists with feedstock integration, and commodity distributors serving spot markets. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers seeking to lock in multi-year offtake agreements with API manufacturers.
Among integrated specialists with feedstock control, Navin Fluorine International Limited and Zhejiang Weihua Chemical Co. Ltd. occupy positions exemplifying divergent geographic strategies—Indian and Chinese capacity expansion respectively. BASF SE represents the multinational archetype where stringent quality protocols anchor European pharmaceutical sourcing relationships. These three players illustrate how regulatory documentation depth and captive fluorine access create defendable positioning against commodity competition.
| Leading Market Players |
|---|
| Navin Fluorine International Limited |
| SRF Limited |
| Mitsubishi International PolymerTrade Corporation |
| Zhejiang Weihua Chemical Co. Ltd. |
| Zhejiang Kangfeng Chemicals Co. Ltd. |
| Wylson-Chem Co. Ltd. |
| BASF SE |
| Central Glass Co., Ltd. |
| Arkema S.A. |
| Others |
Supply Flow & Price Mechanics
Multi-year offtake agreements between API manufacturers and integrated fluorochemical producers lock in both pharmaceutical-grade supply access and price visibility, insulating contract holders from anhydrous hydrogen fluoride volatility while compressing spot-market margins for non-integrated merchant suppliers.
Pricing Analysis
After-sales documentation and certification renewal revenue sustains lifetime value for pharmaceutical-grade producers. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and industrial solvent levels separates customers by purity certification and validation burden. Cost compression in technical-grade solvent tiers is intensifying because Chinese specialty chemical producers are scaling domestic capacity in Jiangsu and Zhejiang provinces. Agrochemical formulators in India and Southeast Asia exhibit highest price sensitivity, while oncology API manufacturers in Switzerland accept substantial premiums for supply security.
Supply Chain Analysis
Anhydrous hydrogen fluoride feedstock access underwrites cost competitiveness across benzotrifluoride supply corridors. Manufacturing concentrates in China, India, and Germany, with the Yangtze River Delta and Rhine-Ruhr clusters anchoring integrated capacity. Production draws from captive fluorine feedstock, catalytic fluorination equipment, and calcium fluoride recovery infrastructure. Single-source vulnerability in pharmaceutical-grade qualification creates supply risk for API manufacturers with sole-supplier dependencies. Distribution runs through direct sales contracts for volumes exceeding fifty metric tons annually, supplemented by regional chemical distributors serving mid-scale formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Benzotrifluoride supply constitutes a defensive-moat market where regulatory entrenchment through REACH and EPA documentation creates switching costs that protect incumbent positioning against commodity competition.
For Market Incumbents: Fortify pharmaceutical-grade certification depth to defend against emerging Chinese specialty chemical producers scaling export capacity. Expand backward integration into anhydrous hydrogen fluoride production to neutralize feedstock volatility squeezing merchant competitors. Prioritize multi-year offtake negotiations with reshoring API manufacturers in the United States seeking IRA domestic content compliance. For New Entrants and Emerging Players: CDSCO-aligned documentation services for Indian API manufacturers represent an underserved layer where incumbents under-serve mid-scale producers navigating FDA and EMA qualification timelines. Electronics-grade cleaning formulations for South Korean semiconductor fabricators offer the most penetrable application segment given technical limitations of aqueous alternatives at sub-7 nanometer nodes. Pursue joint development partnerships with continuous processing equipment vendors to differentiate through flow chemistry integration. For Investors and Strategic Acquirers: Capital is best deployed toward integrated fluorochemical specialists with captive hydrogen fluoride access and pre-qualified REACH dossiers across the medium-term horizon. Acquisition targets should exhibit established relationships with Swiss and United States oncology API manufacturers where supply security commands premium positioning. Monitor EU F-Gas Regulation tightening schedules as the critical inflection signal for compliance-driven reformulation demand in agrochemical end-uses.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogen Fluoride | Captive feedstock access neutralizes phosphate fertilizer cycle volatility pressuring merchant suppliers. |
| Pharmaceutical-Grade Capacity Expansion | CDSCO-aligned output captures import substitution demand from reshoring API manufacturers in India. |
| Membrane-Based Fluorine Recovery Deployment | German and Japanese pilot units reduce feedstock costs by shifting capital from furnace overhauls to membrane cycles. |
| Long-Term Offtake Agreement Negotiation | Swiss and United States oncology manufacturers prioritize supply security over spot-price flexibility in contracting. |
| Flow Chemistry Reactor Module Development | Continuous processing partnerships with equipment vendors compress pharmaceutical-grade development timelines. |
Methodological Framework
Initial hypotheses were tested against primary input from fluorochemical plant managers, pharmaceutical procurement leads at API manufacturers, distribution channel partners, and technical R&D directors, and refined through secondary validation against customs and trade data, Cefic sector reports, SEC 10-K filings from listed chemical producers, and MEE discharge standard documentation. Bottom-up capacity modeling and top-down demand segmentation were triangulated to reconcile volume estimates.
Variance decomposition across pharmaceutical-grade, technical-grade, and electronics-grade purity tiers, coupled with end-use industry splits and regional production hub clustering, structured the analytical framework throughout the forecast period. CAGRs were derived from segment-level volume trajectories calibrated to capacity expansion announcements and qualification timeline assumptions. Anhydrous hydrogen fluoride price cycles and REACH Annex XVII sunset dates served as key industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU REACH, EPA fluorochemical emissions frameworks, and CDSCO alignment protocols; material policy shifts would require re-modeling with revised compliance cost assumptions. Practitioners should keep alternative scenarios live as EU F-Gas Regulation tightening schedules and IRA domestic content enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Methyl Cyclohexane Market
Bulk Chemicals
Lignin Waste Market
Bulk Chemicals
Dimethyl Terephthalate (DMT) Market
Bulk Chemicals
Hydrochloric Acid Market
Bulk Chemicals
Glacial Acrylic Acid (GAA) Market
Bulk Chemicals
Soda Ash Market
Bulk Chemicals
Global Sodium Percarbonate Market
Bulk Chemicals
M, P-Cresol Market
Bulk Chemicals
Clomiphene Citrate Market
Bulk Chemicals
Global Lithium Fluoride Market
Bulk Chemicals
Sodium Silicate Market
Bulk Chemicals
Asia-Pacific Quicklime Market
Bulk Chemicals
Ammonium Sulfate Market
Bulk Chemicals
Needle Coke Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
Carbon Disulfide Market