
 Diisopropylbenzene Market | 2026-2036
Diisopropylbenzene Market Size, Share, and Industry Trends Forecast 2026-2036
Diisopropylbenzene Market Analysis
A capital-intensity divergence between integrated petrochemical giants and specialty chemical operators is rotating competitive dynamics in the diisopropylbenzene landscape. Eastman Chemical Company leverages its integrated aromatics platform to sustain cost advantages across high-purity grades. Arkema competes through specialized solvent formulations for polymerization applications. Syntechem Co. Ltd. anchors its position in technical-grade supply chains serving Asian chemical manufacturing hubs.
Diisopropylbenzene comprises aromatic hydrocarbon isomers with two isopropyl substituents on a benzene ring, typically produced through alkylation of cumene or direct propylene-benzene reactions at elevated temperatures with acid catalysts. The compound serves primarily as a solvent and chemical intermediate in polymerization processes, adhesive formulations, and coating systems. High-purity grades command premium positioning in pharmaceutical synthesis pathways where residual impurity thresholds determine batch qualification. Technical-grade supply dominates volume throughput across chemical intermediate applications, while pharmaceutical-grade segments concentrate margin pools due to certification requirements.
EPA standards under the Toxic Substances Control Act govern manufacturing emissions and workplace exposure limits for diisopropylbenzene producers in the United States. REACH registration requirements in Europe mandate comprehensive safety data documentation for importers and manufacturers above tonnage thresholds. China's MEE enforces GB standards for volatile organic compound emissions from aromatic solvent production facilities. Stakeholders must monitor regulatory divergence between jurisdictions as purity specifications and environmental compliance costs reshape supplier qualification criteria.
Market Dynamics
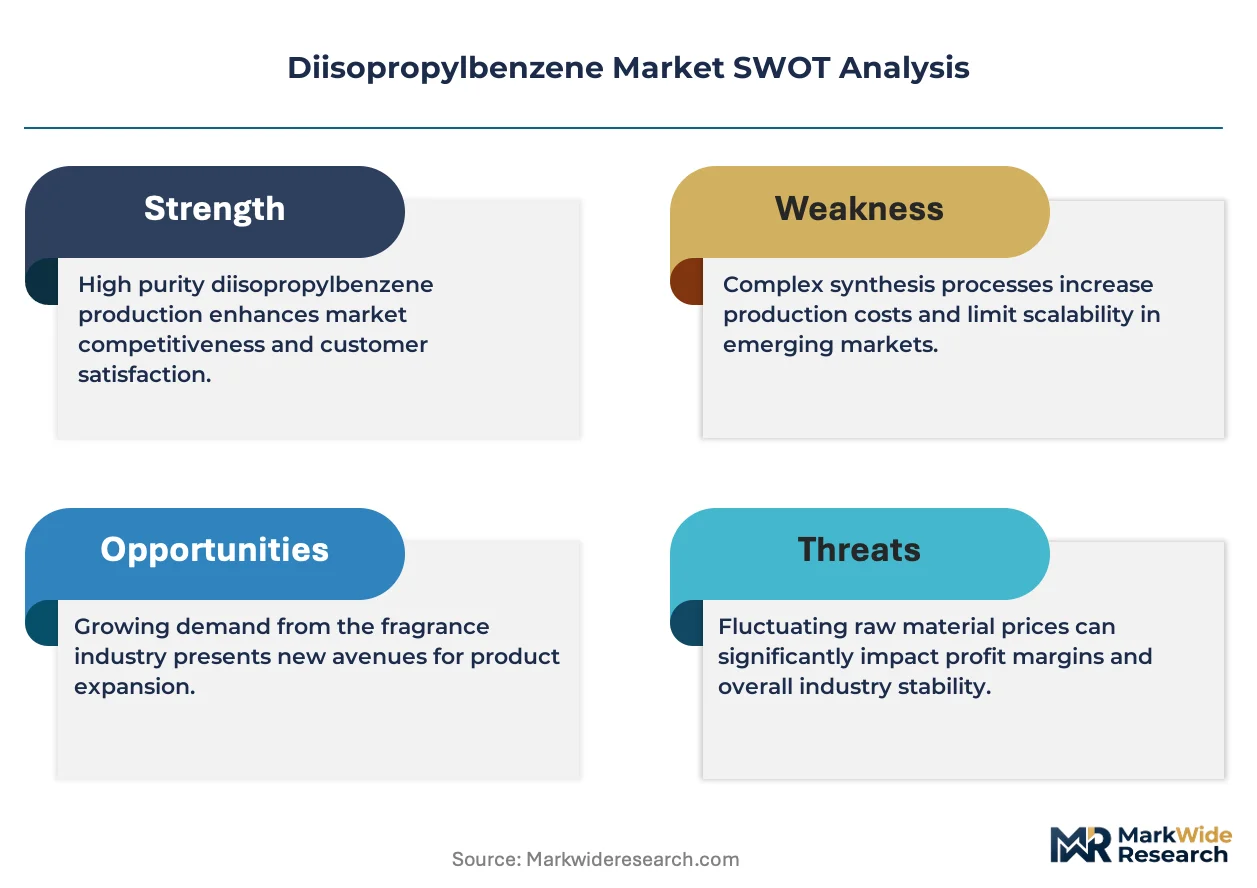
Specialty chemical manufacturers face mounting pressure from REACH compliance deadlines and EPA purity mandates that are compressing technical-grade margins while elevating certification barriers for pharmaceutical-grade supply.
Growth Catalysts
- Polymerization solvent demand:Expanding adhesive and coating production in Chinese manufacturing clusters is pulling technical-grade volumes through Shanghai-area chemical zones.
- REACH registration thresholds:European importers above tonnage mandates are consolidating supplier relationships toward documented safety-data holders, favoring established purity-grade producers.
- Acid-catalyzed alkylation advances:Process intensification at elevated temperatures is improving cumene-to-diisopropylbenzene conversion efficiency in integrated aromatics platforms.
Market Restraints
- Benzene feedstock volatility:Aromatic input costs fluctuate with crude-oil derivatives, squeezing margin predictability for non-integrated operators lacking captive naphtha supply.
- East Asian supply concentration:Production gravity around Gujarat and Jiangsu provinces creates single-source vulnerability for European and North American formulators.
- High-purity synthesis complexity:Residual impurity thresholds below pharmaceutical batch-qualification limits require multi-stage distillation that technical-grade lines cannot retrofit economically.
Strategic Opportunities
- Indian pharmaceutical synthesis:CDSCO-registered intermediate demand from Mumbai-Pune API corridors remains underpenetrated by Western purity-grade suppliers.
- GB standard alignment:China's MEE volatile-organic-compound enforcement is creating first-mover advantage for emission-compliant solvent formulations in coastal chemical parks.
- Digital specification platforms:Blockchain-traceable certificates of analysis are emerging as a procurement differentiator for multinational polymerization customers auditing supplier qualification.
Industry Challenges
- Specialized distillation engineering:Fractionation expertise for pharmaceutical-grade separation is scarce in technical-grade operator workforces, constraining grade-migration timelines.
- Legacy asset retrofit costs:Converting cumene-focused alkylation trains to diisopropylbenzene-optimized configurations demands furnace and catalyst-system capex that mid-capacity sites cannot finance.
- Multi-jurisdiction dossier maintenance:Simultaneous EPA TSCA, REACH, and GB standard updates force parallel compliance investments without harmonized testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diisopropylbenzene Market |
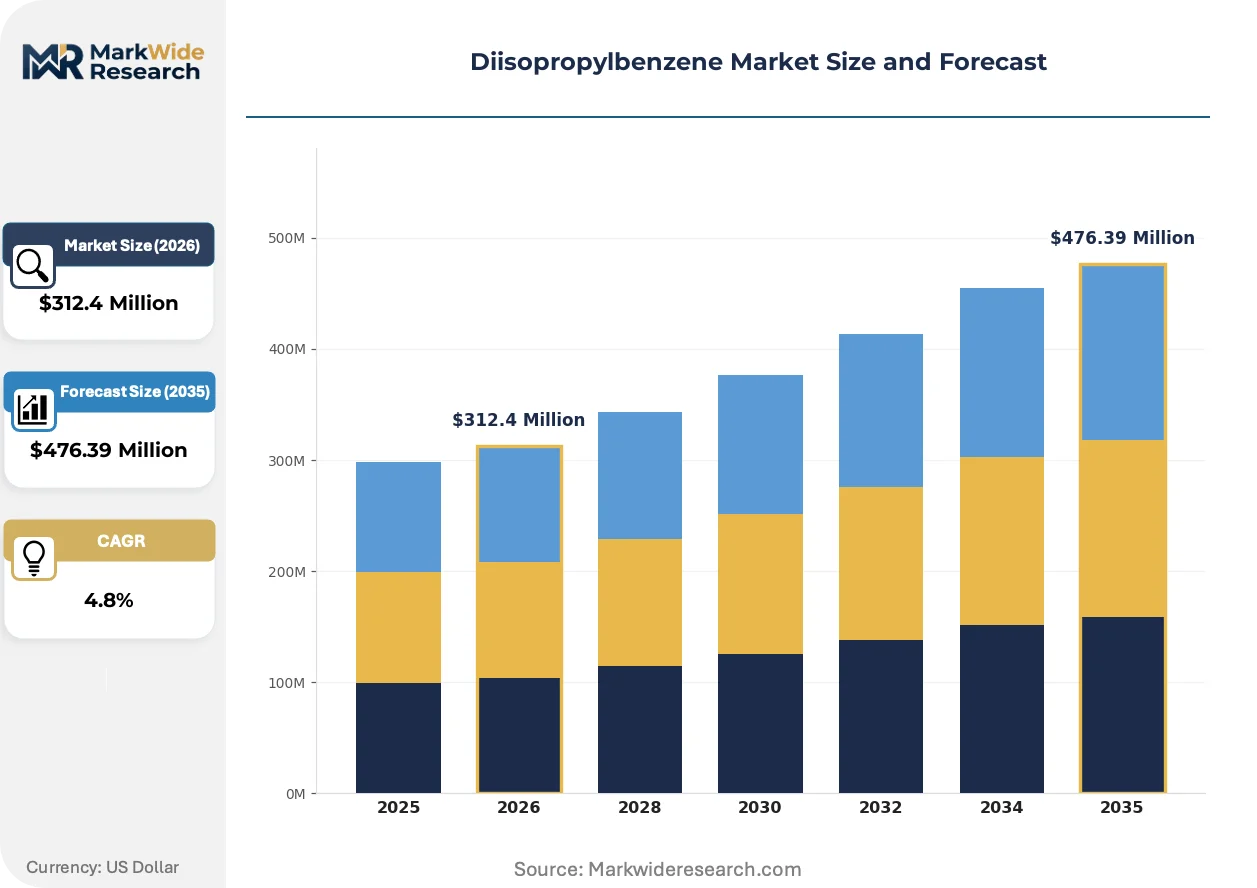
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Technical Grade, Pharmaceutical Grade, Industrial Grade Application: Solvent, Chemical Intermediate, Adhesives, Coatings End User: Chemical Manufacturing, Pharmaceuticals, Paints & Coatings, Textiles Distribution Channel: Direct Sales, Distributors, Online Retail, Resellers |
| Companies Covered | Eastman Chemical Company, SAGECHEM, Goodyear Chemicals, Syntechem Co. Ltd., Tokyo Chemical Industry Co. Ltd., Biosynth Carbosynth, Angene International, Arkema, Santa Cruz Biotechnology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diisopropylbenzene Market Emerging Trajectories
Continuous-flow alkylation reactors and membrane-based purification systems are fragmenting traditional batch-process economics across the diisopropylbenzene value chain. Regulatory divergence between jurisdictions is accelerating certification complexity for cross-border suppliers.
Membrane separation technology for aromatic hydrocarbon purification is fragmenting incumbent distillation-dominant process flows. Pharmaceutical-grade producers in Basel and Boston corridors are piloting polymeric membrane cascades to reduce energy intensity in high-purity finishing. This diffusion is compressing capital barriers for specialty-grade entry while eroding the scale advantages of integrated refinery-aromatics platforms.
REACH substance evaluation under the European Green Deal is tightening hazard-classification requirements for aromatic solvent intermediates. ECHA's persistent, bioaccumulative, and toxic screening criteria are forcing reformulation investments from coating-system suppliers serving EU automotive OEMs. German and French chemical distributors are prioritizing registered-only supply chains, disqualifying technical-grade traders lacking full dossier coverage.
Specification-driven procurement is consolidating buyer power among multinational polymerization houses. Adhesive formulators in Michigan and Bavaria are unbundling solvent sourcing from legacy full-service distribution contracts, instead contracting directly with purity-grade manufacturers for certified batches. This disintermediation is most visible in automotive coating supply chains where OEM audit requirements demand traceable impurity documentation.
Diisopropylbenzene Market Segmentation
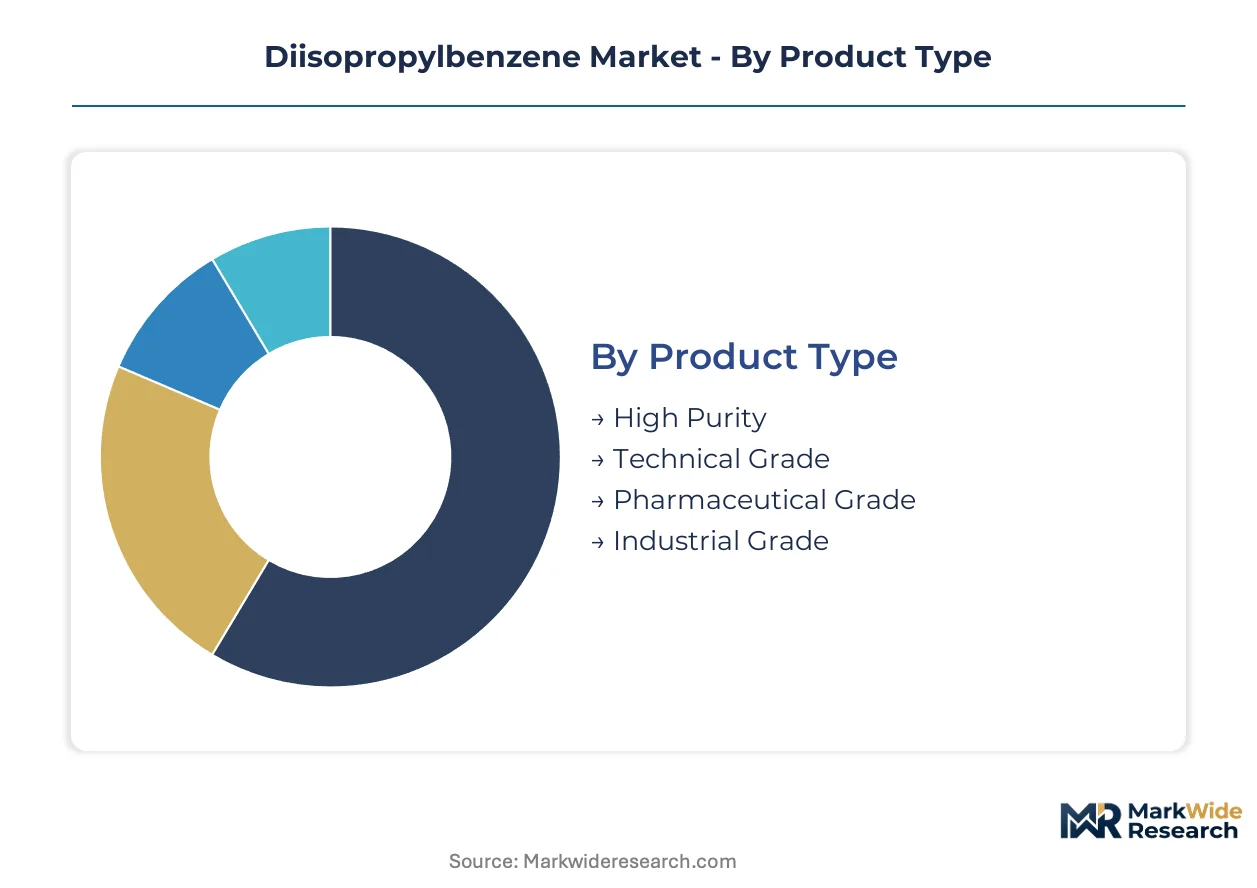
Diisopropylbenzene demand fragments across purity specifications that determine channel economics and regulatory burden. Each grade tier commands distinct qualification protocols and margin structures that reshape supplier-buyer contracting patterns.
Product Type:
Channel mix varies sharply by purity tier—pharmaceutical-grade flows predominantly through direct sales with certificate-of-analysis documentation, while technical-grade volumes move through distributor networks serving chemical manufacturing clusters.
- High Purity:Multi-stage distillation achieves residual impurity thresholds below 500 ppm, satisfying semiconductor and electronic chemical specifications. Demand concentrates in German and Japanese specialty chemical corridors where REACH and METI registration requirements filter out non-compliant traders.
- Technical Grade:Standard alkylation output serves polymerization solvent applications without further purification. Chinese adhesive manufacturers around Shanghai and Guangdong pull the largest technical-grade volumes through regional distributor networks.
- Pharmaceutical Grade:CDSCO-registered batches for API synthesis command documentation-heavy supply chains with full supply-chain traceability.
- Industrial Grade:Bulk aromatic solvent applications in coating systems tolerate broader specification ranges.
Technical Grade dominates installed base. Pharmaceutical Grade is where expansion concentrates.
Application:
Cost tier separation runs deepest in solvent versus intermediate applications—solvent buyers prioritize volume pricing while intermediate users absorb purity premiums for batch qualification.
- Solvent:Dissolution medium for adhesives, coatings, and polymerization reactions. Mumbai-Pune chemical corridors and Michigan automotive coating clusters represent the steepest expansion trajectory for solvent-grade procurement.
- Chemical Intermediate:Feedstock for cumene hydroperoxide and other aromatic derivative synthesis. Integrated aromatics platforms in Texas and Rotterdam favor backward integration into captive intermediate supply.
- Adhesives:Formulation component in pressure-sensitive and structural adhesive systems.
- Coatings:Solvent carrier for automotive and industrial protective coating systems.
Solvent applications anchor volume throughput. Chemical Intermediate is where margin expansion concentrates.
End User:
Customer-type segmentation reveals divergent procurement sophistication—pharmaceutical houses demand audit-ready documentation while textile processors prioritize delivered-cost minimization.
- Chemical Manufacturing:Intermediate and solvent consumption across specialty and commodity chemical production. Gujarat and Jiangsu province chemical parks house the densest concentration of diisopropylbenzene-consuming process plants.
- Pharmaceuticals:API synthesis and pharmaceutical intermediate production. Swissmedic-registered facilities in Basel corridor and CDSCO-registered Mumbai operations drive pharmaceutical-grade specification demand.
- Paints & Coatings:Automotive OEM and industrial protective coating formulators.
- Textiles:Dye carrier and finishing agent applications in fiber processing.
Chemical Manufacturing dominates installed base. Pharmaceuticals is where premium-grade penetration concentrates.
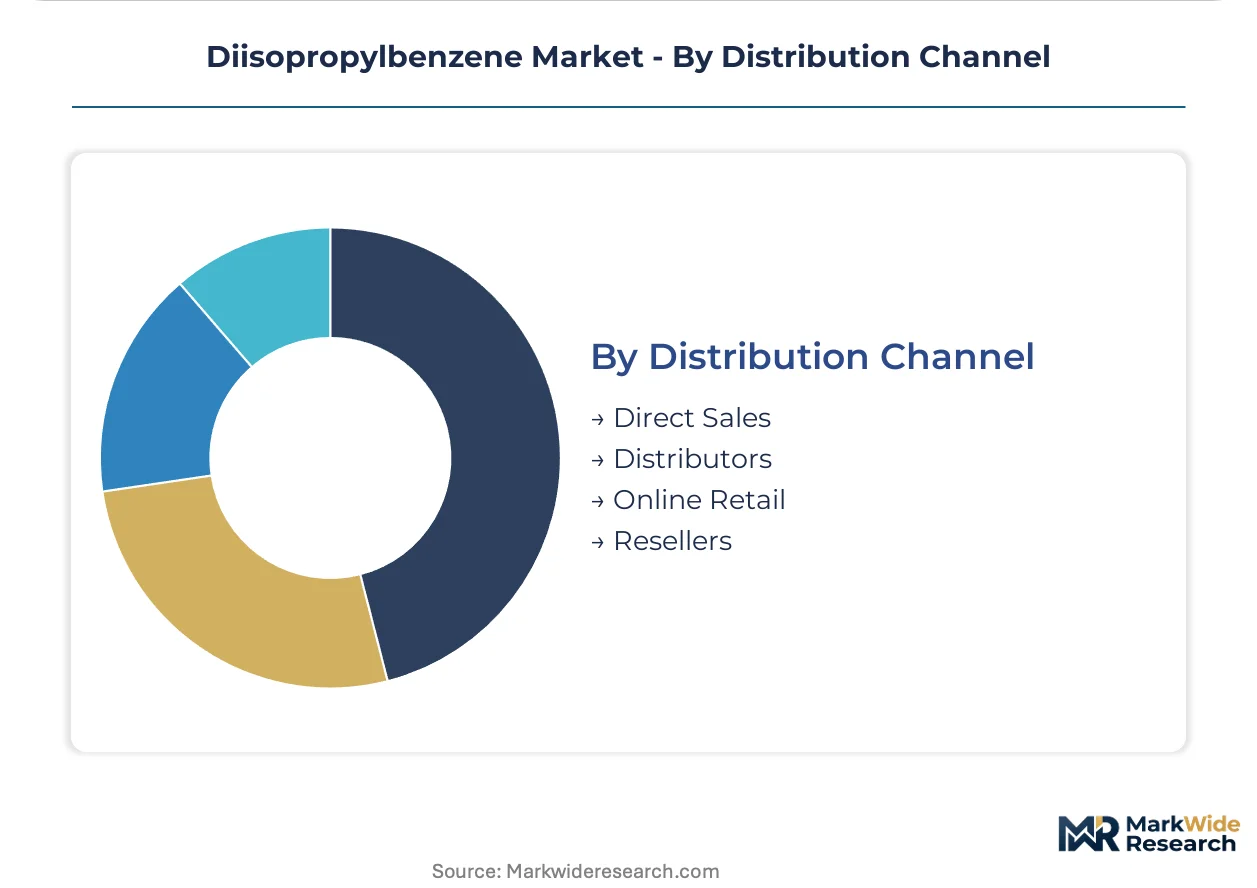
Distribution Channel:
Geographic supply concentration dictates channel efficiency—direct sales prevail where production clusters sit adjacent to consumption centers, while resellers bridge fragmented demand in dispersed markets.
- Direct Sales:Manufacturer-to-formulator contracting for certified pharmaceutical and high-purity grades. BASF and Covestro polymerization operations in Ludwigshafen and Shanghai contract directly with purity-grade producers to satisfy OEM audit requirements.
- Distributors:Regional chemical distributors aggregate technical-grade volumes for mid-sized adhesive and coating formulators. Brenntag and Univar operations in North America and Europe dominate this channel tier.
- Online Retail:E-procurement platforms serving small-volume research and pilot-scale buyers.
- Resellers:Independent traders bridging supply gaps in markets lacking direct manufacturer presence.
Distributors dominate installed base. Direct Sales is where contract value expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Chinese and Indian manufacturing clusters demonstrate the highest price elasticity for technical-grade volumes, while pharmaceutical-grade purchasers in Basel and Boston corridors absorb substantial purity premiums with minimal volume sensitivity.
China
Shanghai-area adhesive manufacturers pull technical-grade volumes through Jiangsu province chemical parks at scale. MEE enforcement of GB volatile organic compound standards is disqualifying non-compliant solvent suppliers from coastal chemical parks. Yangtze River Delta production clusters around Nantong and Zhangjiagang are consolidating captive diisopropylbenzene supply for polymerization processes.
United States
Michigan automotive coating formulators and Texas integrated aromatics platforms anchor divergent demand profiles for solvent and intermediate grades. EPA Toxic Substances Control Act mandates on manufacturing emissions and workplace exposure limits are compressing margins for non-integrated operators lacking captive feedstock. Gulf Coast petrochemical corridors around Houston favor backward integration into captive intermediate supply chains.
Germany
Ludwigshafen polymerization operations and Bavarian adhesive formulators drive specification-heavy procurement for REACH-registered supply. ECHA substance evaluation under the European Green Deal is tightening hazard-classification requirements for aromatic solvent intermediates. BASF and Covestro operations in the Rhine-Neckar metropolitan region contract directly with purity-grade producers to satisfy OEM audit requirements.
India
Mumbai-Pune API corridors generate underpenetrated demand for CDSCO-registered pharmaceutical-grade intermediate supply. DGFT import licensing frameworks and BIS quality standards are elevating documentation barriers for cross-border solvent traders. Gujarat specialty chemical zones around Ankleshwar and Vapi are expanding technical-grade consumption for domestic polymerization processes.
Japan
Osaka-based electronics chemical specialists and Nagoya-area coating formulators concentrate high-purity grade demand for semiconductor applications. METI registration requirements and JIS standards filter out non-compliant traders from precision chemical supply chains. Kanto region pharmaceutical manufacturers around Tokyo maintain stringent residual impurity thresholds for batch qualification.
Diisopropylbenzene Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the diisopropylbenzene landscape. Integrated petrochemical giants command scale economies in high-volume technical-grade supply, while specialty chemical operators capture premium positioning through certification-heavy pharmaceutical-grade channels. Three archetypes dominate: integrated aromatics platforms, specialized solvent formulators, and technical-grade commodity suppliers. Capacity expansion in Asian manufacturing clusters and strategic partnerships for regulatory dossier sharing represent the dominant competitive vectors.
Among the named participants, Eastman Chemical Company anchors the integrated platform archetype with its captive aromatics infrastructure. Arkema occupies a position within the specialized formulation tier, while Syntechem Co. Ltd. exemplifies the technical-grade commodity supplier model serving Asian chemical manufacturing hubs. These three entities represent the structural divergence between scale-driven and specification-driven competitive positioning.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| SAGECHEM |
| Goodyear Chemicals |
| Syntechem Co. Ltd. |
| Tokyo Chemical Industry Co. Ltd. |
| Biosynth Carbosynth |
| Angene International |
| Arkema |
| Santa Cruz Biotechnology, Inc. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at integrated aromatics platforms in Texas and Rotterdam sets price floors for technical-grade volumes, compressing margin headroom for non-integrated operators while elevating premium capture for pharmaceutical-grade specialists serving Basel and Boston corridors. This scale-driven bifurcation concentrates pricing power among backward-integrated producers and fragments negotiation leverage across distributor-dependent buyers.
Pricing Analysis
After-sales certification documentation and multi-year supply agreements anchor lifetime value for pharmaceutical-grade producers serving CDSCO-registered API manufacturers. Three-tier pricing structure across pharmaceutical, high-purity, and technical grades separates batch-traceability premiums from volume-driven solvent economics. Cost compression in technical-grade supply is intensifying because Shanghai-area adhesive manufacturers are consolidating procurement toward direct manufacturer contracts. Chemical manufacturing clusters in Gujarat demonstrate highest price elasticity, while Swissmedic-registered facilities absorb purity premiums with minimal volume sensitivity.
Supply Chain Analysis
Inbound logistics costs through Ningbo-Zhoushan port congestion and container availability constraints on Asia-Europe trade lanes are elevating landed costs for European formulators sourcing Jiangsu province output. Production gravity centers on China, India, and the United States, with feedstock dependencies on benzene derivatives, cumene intermediates, and acid catalyst systems. Single-source vulnerability from East Asian supply concentration creates structural risk for North American and European polymerization houses. Distribution runs through regional chemical distributors aggregating technical-grade volumes for mid-sized adhesive formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diisopropylbenzene market functions as a defensive-moat story where regulatory entrenchment through REACH, EPA TSCA, and CDSCO registration requirements creates switching costs that protect incumbent positioning against commodity challengers.
For Market Incumbents: Secure certification-heavy pharmaceutical-grade channels through CDSCO dossier investments in Mumbai-Pune corridors, while extending backward integration into captive cumene supply to defend against benzene feedstock volatility. Membrane-based purification technology offers a defensible R&D lever for energy-intensity reduction in high-purity finishing operations. For New Entrants and Emerging Players: Anchor in underpenetrated pharmaceutical-grade demand from CDSCO-registered API synthesis operations where Western purity-grade suppliers maintain limited presence. Technical-grade supply to Gujarat specialty chemical zones offers lower certification barriers, with digital specification platforms providing a differentiated go-to-market angle for multinational polymerization customers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty-grade operators with membrane purification capabilities and established regulatory dossiers over commodity technical-grade producers. Long-term viability hinges on regulatory compliance infrastructure rather than scale economies alone. The signal to watch is ECHA substance evaluation outcomes under the European Green Deal, which may recast hazard classifications and force reformulation investments across coating-system supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive cumene supply insulates Eastman and integrated platforms from benzene feedstock volatility. |
| Green Manufacturing Transition | Membrane-based purification reduces energy intensity for Basel and Boston pharmaceutical-grade producers. |
| Long-term Supply Agreement | Direct contracting between Covestro and purity-grade manufacturers satisfies automotive OEM audit requirements. |
| Joint Venture | Regulatory dossier sharing partnerships accelerate REACH and CDSCO compliance for mid-cap entrants. |
| Capacity Expansion | Jiangsu province additions serve Shanghai-area adhesive manufacturers consolidating technical-grade procurement. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant managers at Jiangsu and Gujarat chemical parks, procurement leads at Michigan automotive coating formulators, technical R&D directors at membrane purification specialists, and distribution channel partners at Brenntag and Univar operations. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and ECHA registration databases. Bottom-up volume modeling triangulated against top-down value estimates from production capacity and utilization assumptions.
Across the analysis window, the forecasting framework modeled grade tier segmentation, end-use industry differentiation across adhesives and coatings, regional production hub concentration, and certification level stratification. CAGRs were derived from regression analysis of historical capacity expansion patterns and forward-looking demand elasticity assumptions for polymerization solvent applications. Forecast inputs incorporated benzene derivative pricing trajectories and regulatory compliance cost escalations.
Material uncertainties — feedstock volatility, ECHA hazard reclassification, and MEE enforcement intensity — sit outside the modeled envelope. Forecasts reflect documented assumptions about capacity utilization rates and substitution elasticity for alternative aromatic solvents. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
North America Acrylamide Monomer Market
Bulk Chemicals
North America Potassium Formate Market
Bulk Chemicals
Magnesium Sulfate Market
Bulk Chemicals
Stilbene Market
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market
Bulk Chemicals
Caprolactam Market
Bulk Chemicals
Alkali Metal Hydroxides Market
Bulk Chemicals
Lactic Acid Market
Bulk Chemicals
Ammonium Thiosulfate Market
Bulk Chemicals
Aniline Market
Bulk Chemicals
Asia-Pacific Solid Sulfur Market
Bulk Chemicals
Soda Ash Market
Bulk Chemicals
Methyl Gluceth-10 Market
Bulk Chemicals
Aluminum Sulfate Market
Bulk Chemicals
Cyclohexane Market
Bulk Chemicals
Isobutyraldehyde Market