
 Sander Market | 2026-2036
Sander Market Size, Share, and Industry Trends Forecast 2026-2036
Sander Market Outlook
Aftermarket service revenue is rewriting profit allocation across the Sander Market. Bosch leverages its captive parts network to capture recurring maintenance spend from professional construction fleets. Makita anchors its position in battery-powered platforms through cross-compatible ecosystems that lock in tool replacement cycles. Festool specializes in dust extraction integration, commanding premium positioning among furniture manufacturers who face tightening workplace exposure standards.
A sander is a powered abrasive finishing tool that uses rotating, reciprocating, or orbital motion to smooth surfaces through graduated grit progression from coarse to fine, typically operating at speeds between 4,000 and 24,000 orbits per minute depending on material hardness. Its primary industrial purpose is to prepare substrates for coating adhesion, eliminate machining marks, and achieve specified surface roughness values in production environments. Belt sanders occupy the heavy-material-removal segment where margin pools concentrate in industrial woodworking and metalworking throughput applications. Battery-powered units represent the fastest-expanding power source category as lithium-ion cell energy density improvements extend runtime parity with corded alternatives. DIY end users sustain volume throughput in orbital and detail sander formats through retail channel replenishment cycles.
OSHA enforces permissible exposure limits for respirable crystalline silica that compel integration of onboard dust collection systems in professional-grade equipment sold into construction and restoration workflows. The EU F-Gas Regulation restricts fluorinated greenhouse gas use in manufacturing processes, pressuring pneumatic sander producers to redesign air motor efficiency or shift portfolio weight toward electric alternatives. ISO 28927 establishes hand-transmitted vibration measurement protocols that influence ergonomic design priorities across export-oriented manufacturers. Stakeholders must decide whether to prioritize battery platform consolidation or maintain pneumatic line breadth as regulatory pressure diverges across North American and European enforcement timelines.
Market Dynamics
The Sander Market faces a structural pivot as battery platform consolidation collides with divergent regulatory enforcement timelines across North American and European jurisdictions. Professional-grade equipment procurement now hinges on dust extraction integration mandates and vibration exposure protocols that reshape product development roadmaps.
Growth Catalysts
- OSHA silica exposure limits:Construction and restoration workflows now require onboard dust collection systems. Equipment manufacturers capture premium positioning by bundling extraction technology with base units.
- Furniture manufacturing clusters in Germany:Surface finishing demand concentrates procurement volumes for orbital sanders with precision dust control. German workshops prioritize equipment that meets workplace exposure standards.
- Lithium-ion energy density improvements:Battery-powered variants achieve runtime parity with corded alternatives. Professional users in automotive repair shops migrate platforms without sacrificing throughput.
Market Restraints
- Rare earth magnet supply concentration:Brushless motor production depends on neodymium processing concentrated in China. Pneumatic sander producers face input cost volatility as electric alternatives scale.
- EU F-Gas Regulation friction:Fluorinated greenhouse gas restrictions pressure air motor efficiency redesigns. Manufacturers must either invest in pneumatic innovation or accelerate electric portfolio shifts.
- Technical limitation in battery thermal management:High-orbit sanding applications generate heat that degrades cell performance. Continuous-duty industrial users retain corded equipment for heavy-material-removal tasks.
Strategic Opportunities
- Underpenetrated restoration sector in Japan:Surface finishing demand from heritage building conservation creates niche procurement. Specialized dust extraction integration commands premium positioning among preservation contractors.
- Cross-compatible battery ecosystems:Platform consolidation locks in tool replacement cycles across multiple power tool categories. Manufacturers capture recurring revenue through captive battery and charger sales.
- ISO 28927 certification tailwinds:Hand-transmitted vibration measurement protocols influence ergonomic design priorities. Export-oriented manufacturers differentiate through compliance documentation.
Industry Challenges
- Skill gap in vibration exposure assessment:Workplace safety officers lack training in hand-arm vibration syndrome measurement. Equipment distributors must provide technical support for compliance verification.
- Certification timeline compression:Multiple regulatory frameworks require parallel testing protocols. Product launch schedules stretch as manufacturers sequence OSHA, EU, and ISO validation.
- Legacy pneumatic infrastructure integration:Industrial woodworking facilities maintain compressed air investments. Electric platform migration requires capital reallocation and workflow reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sander Market |
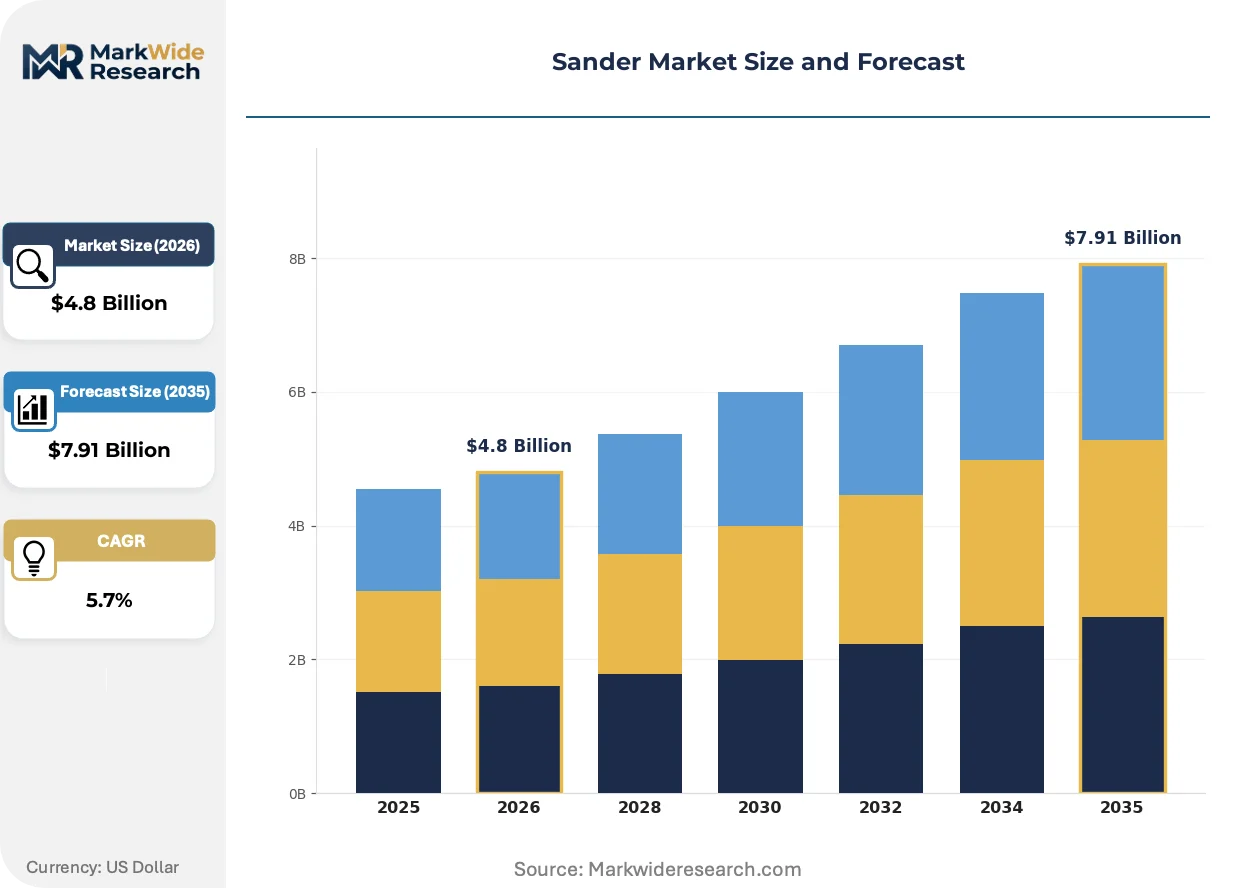
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belt Sanders, Orbital Sanders, Disc Sanders, Detail Sanders Power Source: Electric, Pneumatic, Battery-Powered, Manual End User: Construction, Furniture Manufacturing, Automotive Repair, DIY Application: Woodworking, Metalworking, Surface Finishing, Restoration |
| Companies Covered | Bosch, Stanley Black & Decker, Makita, 3M, Festool, Metabo, Hilti, Ingersoll Rand, Techtronic Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sander Market Strategic Shifts
Active connectivity and sensor integration are digitizing equipment performance tracking. Real-time vibration monitoring and usage analytics reshape how professional users manage tool fleets and maintenance schedules.
Brushless motor control systems with embedded torque sensors are digitizing operational feedback loops. Automotive repair shops in Germany adopt these units to standardize surface preparation quality across technician skill levels. The technology compresses variability in finish consistency while generating warranty documentation trails.
The EU F-Gas Regulation is tightening fluorinated gas use in manufacturing processes. Pneumatic sander producers redesign air motor efficiency or accelerate electric portfolio shifts to maintain European market access. German and French equipment distributors now prioritize electric SKUs in professional catalogues.
Professional buyers increasingly unbundle after-sales service from equipment purchase. Construction fleets in the United States negotiate separate maintenance contracts with third-party providers rather than captive parts networks. This procurement pattern compresses manufacturer service revenue while expanding independent repair shop market share.
Sander Market Segmentation
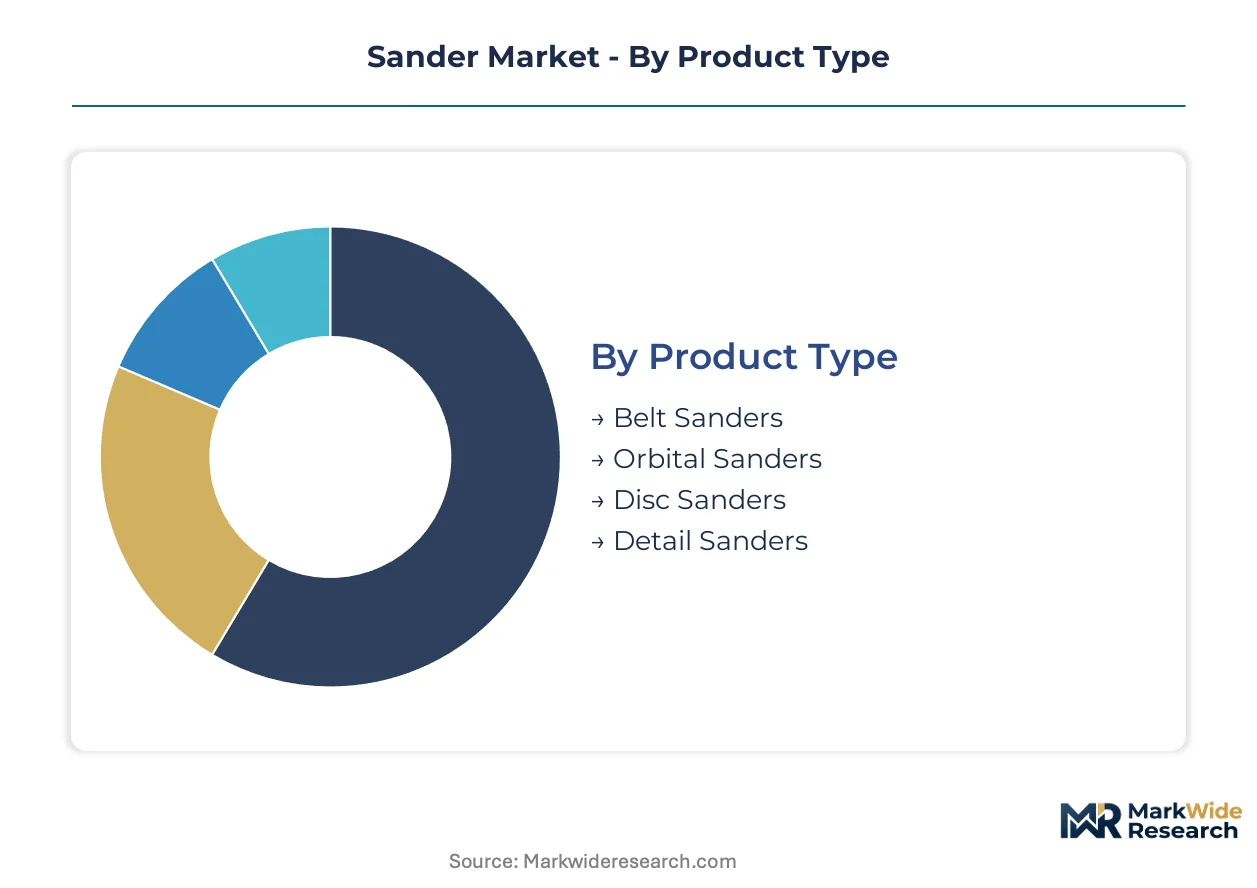
Sander procurement patterns diverge sharply across technical specifications and end-use environments. Aftermarket service intensity varies by segment, with professional-grade categories generating recurring revenue through consumables and maintenance contracts while DIY formats rely on retail replenishment cycles.
Product Type:
After-sales service intensity peaks in belt sander deployments where abrasive belt replacement and drive system maintenance create recurring revenue streams for distributor networks.
- Belt Sanders:These units employ continuous abrasive loops driven by electric or pneumatic motors to remove substantial material volumes from wood and metal substrates. German furniture manufacturers and industrial metalworking facilities in Japan concentrate procurement for heavy-material-removal throughput applications where downtime costs justify premium maintenance contracts.
- Orbital Sanders:Random-orbit action combines spinning and elliptical movement to minimize visible scratch patterns during graduated grit progression. Automotive repair shops across the United States and surface finishing specialists in Japan drive demand for dust-integrated variants that comply with tightening workplace exposure standards.
- Disc Sanders:Rotary abrasive discs mounted on angle or bench configurations target edge profiling and weld seam preparation. Construction contractors favor these for rapid stock removal in restoration workflows.
- Detail Sanders:Compact triangular or finger-shaped pads access confined geometries and intricate profiles. DIY retail channels sustain volume throughput through low-price-point replenishment cycles.
Orbital sanders hold the largest share; momentum sits with battery-powered belt sander variants gaining industrial acceptance.
Power Source:
Cost tier stratification separates professional-grade electric and pneumatic systems from entry-level manual alternatives, with battery platforms commanding premium positioning through ecosystem lock-in.
- Electric:Corded universal and induction motors deliver consistent torque for continuous-duty industrial applications. OSHA silica compliance mandates are accelerating onboard dust collection integration in corded professional units sold into construction markets.
- Pneumatic:Compressed air motors eliminate electrical hazard risks in wet environments and offer favorable power-to-weight ratios. EU F-Gas Regulation pressures are forcing air motor efficiency redesigns or portfolio shifts toward electric alternatives.
- Battery-Powered:Lithium-ion cell packs with brushless motor controllers achieve runtime parity with corded alternatives. Furniture manufacturers and automotive repair shops are migrating platforms to eliminate trip hazards and compressed air infrastructure.
- Manual:Unpowered abrasive blocks and sheets serve touch-up tasks and precision finishing where powered equipment risks substrate damage. Hobbyist woodworkers sustain niche demand through specialty retail.
Electric systems retain the dominant position; battery-powered configurations are climbing the fastest as energy density improvements extend operational runtime.
End User:
Volume concentration in professional segments contrasts with margin structure, where construction and furniture manufacturing procurement generates lower per-unit profitability than specialized automotive and restoration applications.
- Construction:General contractors and specialty trades deploy sanders for surface preparation, drywall finishing, and flooring installation. OSHA enforcement of respirable crystalline silica limits is mandating dust extraction integration across professional-grade equipment categories.
- Furniture Manufacturing:Production line finishing operations in Germany and precision woodworking clusters demand orbital sanders with integrated dust control. ISO 28927 vibration certification influences procurement specifications for worker exposure compliance.
- Automotive Repair:Collision centers and refinishing shops require sanders that achieve specified surface roughness values for coating adhesion. Battery-powered variants are displacing pneumatic equipment in mobile repair operations.
- DIY:Home improvement enthusiasts sustain retail channel throughput for orbital and detail sander formats. Price sensitivity drives private-label and economy-tier procurement patterns.
Construction absorbs the highest unit volumes; automotive repair delivers the steepest expansion trajectory as collision center consolidation accelerates equipment standardization.
Application:
Supply concentration in abrasive media manufacturing shapes equipment bundling strategies, with woodworking and metalworking applications driving bulk consumable purchasing while restoration specialists prioritize precision over volume.
- Woodworking:Solid wood and engineered panel processing requires graduated grit progression from coarse stock removal to fine finishing. German and Japanese industrial clusters concentrate demand for high-orbit precision equipment.
- Metalworking:Ferrous and non-ferrous substrate preparation demands robust construction and thermal management. Belt sanders dominate this segment for weld seam leveling and edge deburring.
- Surface Finishing:Final-stage preparation for coating, staining, or sealing applications specifies tight surface roughness tolerances. Dust extraction integration is becoming non-negotiable in professional environments.
- Restoration:Heritage building conservation and antique refinishing in Japan requires specialized dust control to protect substrate integrity. Premium positioning commands higher equipment margins despite lower unit volumes.
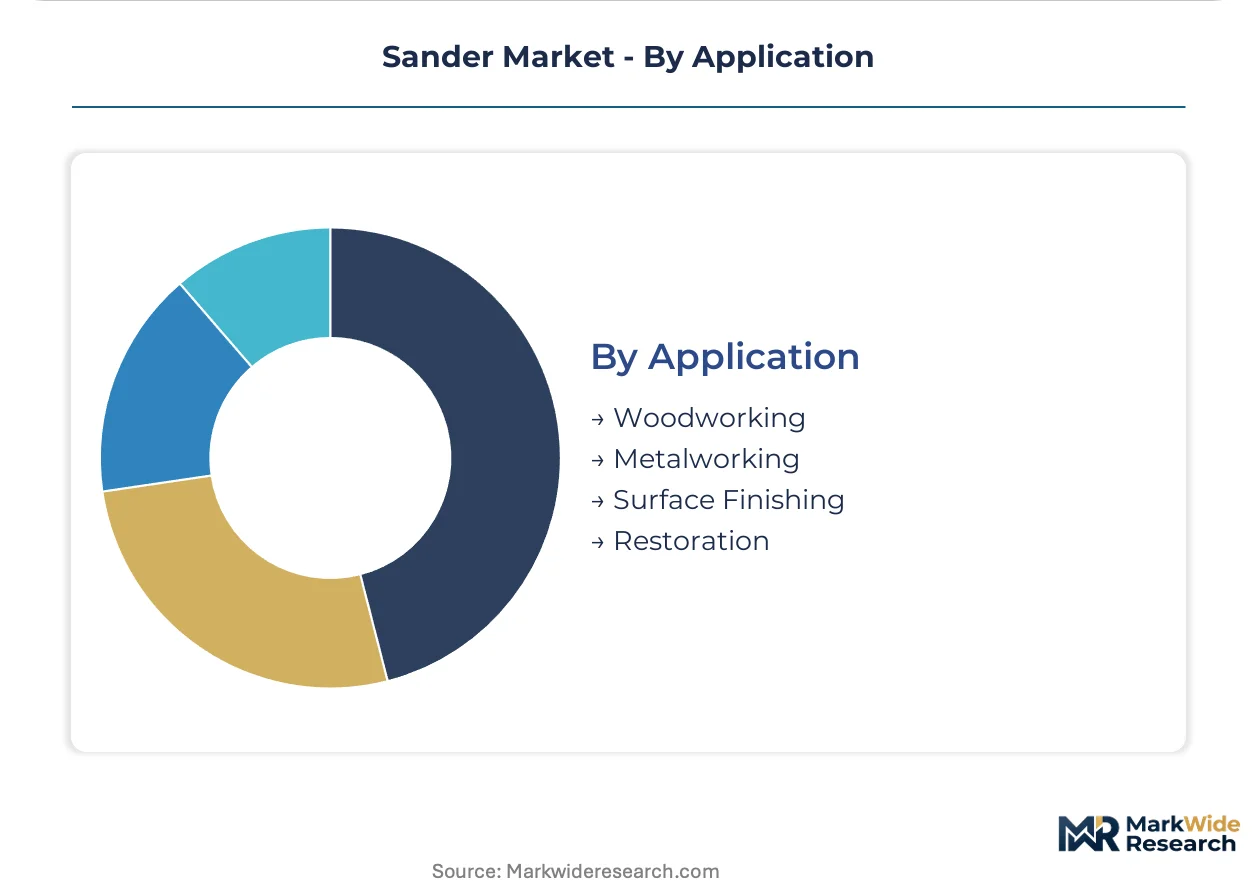
Woodworking captures the largest application share; restoration is gaining share fastest as heritage conservation funding expands across developed economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese industrial clusters concentrate precision surface finishing demand, while OSHA enforcement in the United States and EU F-Gas Regulation compliance reshape procurement specifications across construction and manufacturing workflows.
United States
Construction and automotive repair sectors drive professional-grade equipment procurement. OSHA silica exposure limits mandate onboard dust collection systems in corded units sold into restoration workflows. Dallas-Fort Worth collision centers standardize battery-powered platforms to eliminate compressed air infrastructure.
Germany
Furniture manufacturing clusters in Baden-Württemberg and Bavaria concentrate orbital sander demand with integrated dust control. EU F-Gas Regulation pressures pneumatic equipment producers toward electric portfolio shifts. Stuttgart-area workshops prioritize ISO 28927 vibration certification for worker exposure compliance.
Japan
Heritage building conservation and precision metalworking sustain specialized procurement. METI workplace safety guidelines influence dust extraction integration in professional equipment. Nagoya industrial corridor manufacturers specify high-orbit precision sanders for surface finishing applications.
China
Domestic woodworking machinery production scales brushless motor manufacturing for export markets. GB standards for hand-transmitted vibration measurement align with ISO protocols for equipment certification. Shenzhen electronics assembly plants drive demand for compact detail sanders in precision finishing.
India
Construction sector expansion and furniture manufacturing growth propel equipment imports. BIS certification requirements for power tools shape product specifications for professional-grade entrants. Pune industrial belt workshops adopt orbital sanders for automotive component surface preparation.
Sander Market Competitive Environment
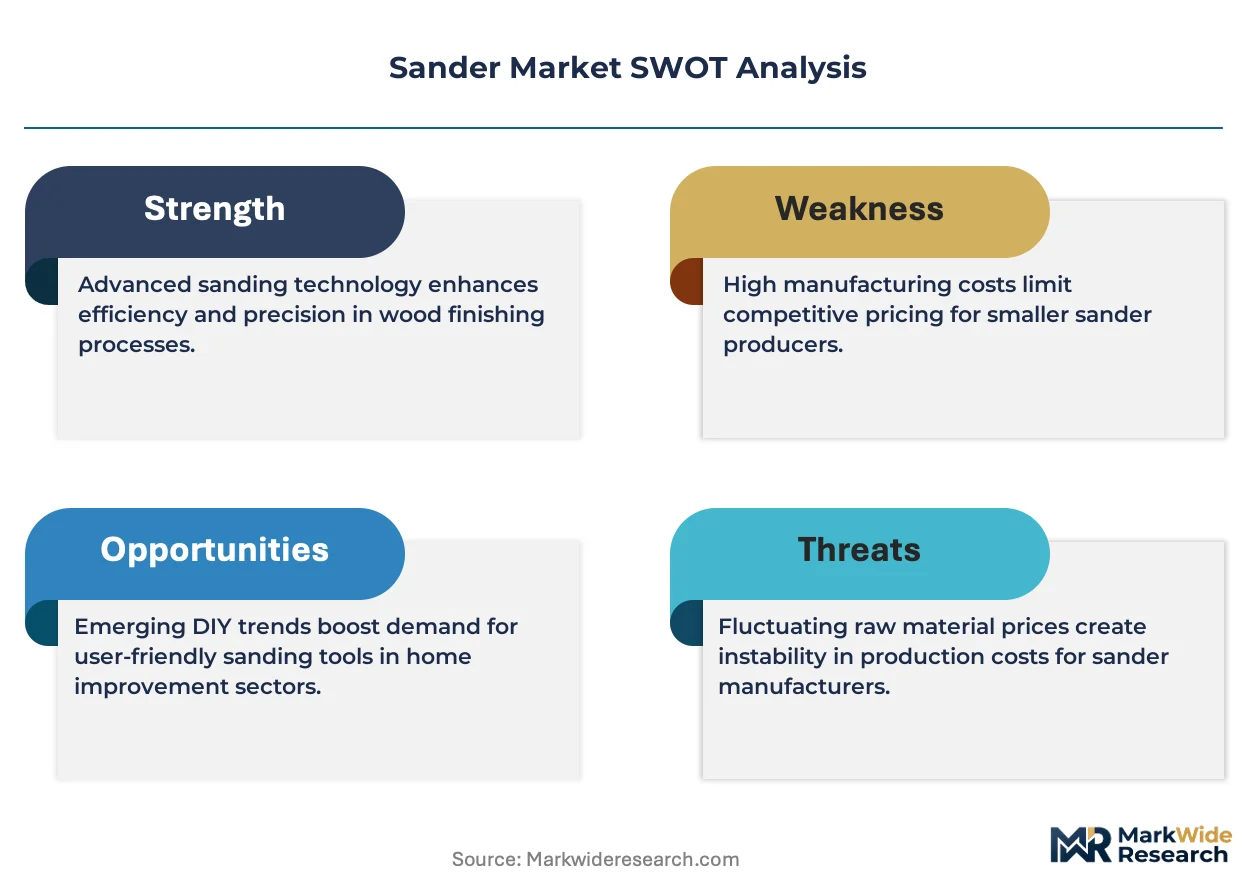
Full-line power tool conglomerates and specialized precision equipment manufacturers split the market between volume-driven platform ecosystems and premium-tier application-specific positioning. The structure favors players with captive battery technology or integrated dust extraction systems. Three archetypes dominate: diversified industrial conglomerates with cross-category battery platforms, pneumatic specialists pivoting toward electric alternatives, and precision-focused brands serving regulated professional environments. Competitive moves center on battery ecosystem lock-in strategies and dust extraction technology bundling.
Among diversified industrial conglomerates, Bosch and Stanley Black & Decker occupy positions defined by platform breadth and retail channel density. Makita exemplifies the battery-centric archetype with cross-compatible ecosystem architecture. Festool represents the precision-specialist tier with dust extraction integration as a differentiation anchor.
| Leading Market Players |
|---|
| Bosch |
| Stanley Black & Decker |
| Makita |
| 3M |
| Festool |
| Metabo |
| Hilti |
| Ingersoll Rand |
| Techtronic Industries |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese brushless motor manufacturing is compressing component costs while simultaneously eroding pricing power for finished sander producers in Europe and North America. This utilization imbalance forces suppliers to absorb margin pressure or accelerate portfolio shifts toward premium-tier positioning.
Pricing Analysis
OSHA silica exposure limits dictate the pricing tier structure across professional-grade equipment categories. Three-tier pricing structure across premium, standard, and economy levels separates dust-integrated orbital sanders with ISO 28927 certification from basic corded units and entry-level DIY formats. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because private-label imports from Chinese OEMs flood retail channels. DIY end users exhibit the highest price sensitivity, while furniture manufacturers in Germany demonstrate minimal elasticity for vibration-compliant equipment.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for electric sander producers. Component sourcing concentrates in China for lithium-ion cells and brushless motors, Germany for precision bearings and dust extraction systems, and Japan for high-grade abrasives. Rare earth magnet supply draws from Chinese neodymium processing with limited alternative sourcing. Single-source vulnerability in battery cell supply creates exposure to export restriction scenarios. Distribution runs through industrial distributors serving professional construction fleets, big-box retailers for DIY segments, and direct-to-workshop channels for precision equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in hand-transmitted vibration measurement and dust extraction integration is concentrated among a narrow set of German and Japanese equipment producers, creating acquisition premiums for buyers seeking regulatory compliance capabilities.
For Market Incumbents: Harden aftermarket service revenue through captive parts networks that lock professional construction fleets into recurring maintenance contracts. Deepen backward integration into brushless motor production to insulate margin structures from rare earth price volatility. Battery platform consolidation represents the critical defensive lever against pneumatic specialists pivoting toward electric alternatives. For New Entrants and Emerging Players: Pursue heritage building restoration contractors in Japan as an underpenetrated segment where specialized dust control requirements command premium positioning. Target automotive repair shops in Dallas-Fort Worth and similar collision center clusters where battery-powered platform migration is displacing compressed air infrastructure. A go-to-market angle anchored in cross-compatible battery ecosystem partnerships with existing power tool platforms accelerates customer acquisition without proprietary R&D investment. For Investors and Strategic Acquirers: Capital is best deployed toward precision-specialist manufacturers with integrated dust extraction technology and established ISO 28927 certification documentation. Long-term viability favors equipment producers positioned at the intersection of tightening workplace exposure standards and battery platform consolidation trends. The signal to watch is EU F-Gas Regulation enforcement intensity accelerating pneumatic-to-electric portfolio shifts among incumbent air motor specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brushless Motor Manufacturing | Captive neodymium magnet supply insulates margin structures from Chinese export restriction scenarios. |
| Battery Platform Ecosystem Expansion | Cross-compatible lithium-ion architectures lock professional users into multi-tool replacement cycles across orbital, belt, and detail sander categories. |
| Dust Extraction Technology Bundling | Integrated onboard collection systems command OSHA-compliant premium positioning in construction and restoration workflows. |
| ISO 28927 Certification Investment | Hand-transmitted vibration documentation opens procurement access to German furniture manufacturing clusters with strict workplace exposure protocols. |
| Regional Manufacturing Footprint Diversification | Assembly capacity in Vietnam or Mexico mitigates tariff exposure between China and the United States for North American market supply. |
Study Parameters
The analysis maps belt sander, orbital sander, disc sander, and detail sander sub-sectors, each validated through equipment procurement managers at German furniture manufacturers, OSHA compliance officers at US construction firms, and aftermarket service directors at industrial distributors. Primary interviews with maintenance directors, plant engineers, and OEM procurement teams combined with secondary validation from customs trade data, SEC filings of listed power tool manufacturers, and ISO certification registries. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Assumptions held fixed include current OSHA enforcement intensity for silica exposure limits, EU F-Gas Regulation compliance timelines, and lithium-ion energy density improvement trajectories observed across the analysis window. The projection framework models product type, power source, end user, and application segmentations alongside regional regulatory cluster variations. CAGRs derived from regression analysis of historical shipment correlations with construction spending and automotive collision repair volume indices. Forecast inputs incorporated brushless motor cost curves and abrasive media price indices.
Sensitivities concentrate around OSHA enforcement acceleration, EU F-Gas Regulation amendment scope, and rare earth export restriction scenarios. Forecasts reflect documented assumptions regarding technology adoption rates and regulatory compliance cost pass-through. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Cordless Impact Wrench Market
Tools
Assembly Fastening Tool Market
Tools
Mechanical Springs Market
Tools
Bandsaw Machines Market
Tools
Pneumatic Marking Machines Market
Tools
Fine Blanking Tools Market
Tools
Woodworking Sanders Market
Tools
Wood Floor Grinding Machine Market
Tools
Masonry Cleaners Market
Tools
Welding Products Market
Tools
Handheld Pipe Cutter Market
Tools
Portable Boring Machines Market
Tools
CNC Leather Cutting Machine Market
Tools
Leather Cutting Machine Market
Tools
Asia Pacific Power Tools & Hand Tools Market
Tools
Digital Levels Market