
 Foldable Ladder Market | 2026-2036
Foldable Ladder Market Size, Share, and Industry Trends Forecast 2026-2036
Foldable Ladder Market Analytics
Professional contractors and maintenance workers are bifurcating from DIY enthusiasts as the faster-growing buyer archetype in foldable ladder procurement. Werner Co. leverages its vertical integration into aluminum extrusion to control cost position across multi-purpose models. Little Giant Ladders differentiates through specialized hinge engineering that extends load capacity ratings. Louisville Ladder anchors its position in the industrial segment with fiberglass compositions rated for electrical work.
A foldable ladder is a portable access device with articulated or telescoping joints that reduce storage length, typically manufactured from aluminum alloys, fiberglass-reinforced polymer, or steel tubing with rung spacing standardized to 12 inches under OSHA rules. The product serves commercial, industrial, and residential height-access applications where transportability and footprint constraints matter. Aluminum dominates volume production due to its strength-to-weight ratio, though fiberglass commands margin pools in electrical utility and industrial end uses where dielectric properties are mandatory. The contractor end-user segment represents the fastest-growing demand pool, while DIY enthusiasts sustain the largest absolute volume through home improvement retail channels.
OSHA, ANSI, and the EU's CE marking framework collectively shape product standards, testing protocols, and market access requirements for foldable ladders sold in North America and Europe. These regulations mandate duty ratings, slip-resistant rung surfaces, and labeling that directly influence manufacturing costs and channel eligibility. Stakeholders must monitor evolving material certification requirements and channel compliance costs as aluminum price volatility and energy-intensive fiberglass production face sustained regulatory scrutiny.
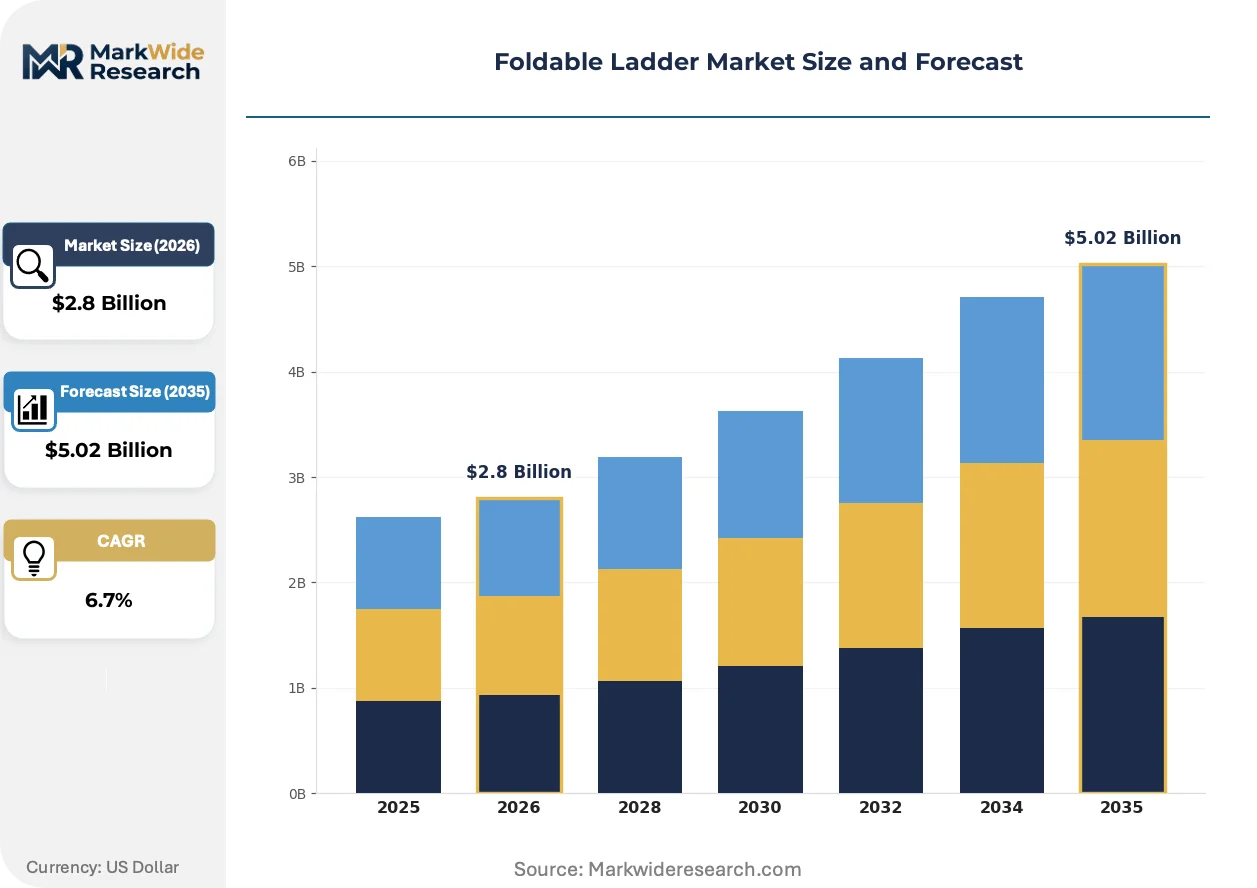
Market Dynamics
OSHA and ANSI duty rating tightening is compressing manufacturer margins while forcing material upgrades across aluminum and fiberglass supply chains. This regulatory pressure concentrates competitive advantage among producers with captive extrusion capabilities and certified testing infrastructure.
Growth Catalysts
- Residential renovation spending:DIY enthusiasts in the United States are expanding absolute volume through home improvement retail channels, creating steady baseline demand for multi-purpose aluminum models.
- OSHA ladder safety standards:Compliance mandates for slip-resistant rung surfaces and standardized 12-inch spacing are locking out uncertified imports and protecting incumbent positions.
- Professional contractor procurement:Maintenance workers and construction crews are accelerating replacement cycles as project backlogs extend and fleet standardization becomes operational priority.
Market Restraints
- Aluminum price volatility:Energy-intensive smelting costs and LME pricing swings compress gross margins for volume producers dependent on spot market sourcing.
- Fiberglass production concentration:Dielectric-grade resin and roving supply clusters in China and the US Gulf Coast create geographic concentration risk for electrical-rated ladder manufacturers.
- Steel tubing substitution:Fixed industrial access equipment and powered lift platforms displace foldable ladders in permanent facility installations above 20-foot reach requirements.
Strategic Opportunities
- EU CE marking expansion:Harmonized EN 131 standards create unified market access across Germany, France, and Italy for certified producers upgrading testing documentation.
- Telescoping hinge convergence:Integration of aircraft-grade aluminum locking mechanisms with polymer composite rails enables lighter duty-rated models for residential delivery services.
- Direct contractor e-procurement:Bypassing traditional two-step distribution through B2B platforms captures margin and captures fleet specification data for predictive replacement scheduling.
Industry Challenges
- Welding certification timelines:AWS D1.2 structural aluminum welding qualifications require 6-12 month technician training cycles, constraining production scaling for specialized industrial orders.
- Legacy ERP integration:ISO 9001 traceability requirements for lot-controlled resin batches clash with older MRP systems, forcing mid-tier manufacturers into expensive WMS upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foldable Ladder Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Steel, Fiberglass, Plastic Application: Residential, Commercial, Industrial, Utility Features: Lightweight, Extendable, Multi-Purpose, Slip-Resistant End User: DIY Enthusiasts, Contractors, Maintenance Workers, Electricians |
| Companies Covered | Werner Co., Little Giant Ladders, Louisville Ladder, Cosco, Gorilla Ladders, Lyte Ladders, Bailey Ladders, Telesteps, Hailo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foldable Ladder Market Evolving Landscape
Material science advances and regulatory harmonization are compressing product development cycles while fragmenting buyer expectations across weight, reach, and electrical insulation specifications.
Carbon fiber reinforced polymer (CFRP) rung inserts are miniaturizing structural components without sacrificing load capacity ratings. Utility contractors in Texas and California are piloting these hybrid designs for hot-stick applications where dielectric properties and reduced carrying weight justify 40% cost premiums over standard fiberglass. The technology is miniaturizing the trade-off between portability and duty rating that has historically segmented aluminum and fiberglass product lines.
REACH substance restrictions on hexavalent chromium passivation coatings are forcing European manufacturers to adopt trivalent chrome or ceramic conversion alternatives for aluminum corrosion protection. The industrial consequence is 8-12% coating cost inflation and extended supplier qualification periods. German and Dutch producers are responding fastest, leveraging existing automotive coating partnerships to accelerate compliant surface treatment transitions.
Facility maintenance departments are unbundling ladder fleet management from general MRO procurement, creating standalone contracts with dedicated inspection and replacement scheduling. This pattern displaces traditional distributor relationships with direct manufacturer service agreements. The shift is most visible in US healthcare and higher education verticals where liability exposure and Joint Commission accreditation requirements prioritize documented compliance over unit cost minimization.
Foldable Ladder Market Segmentation
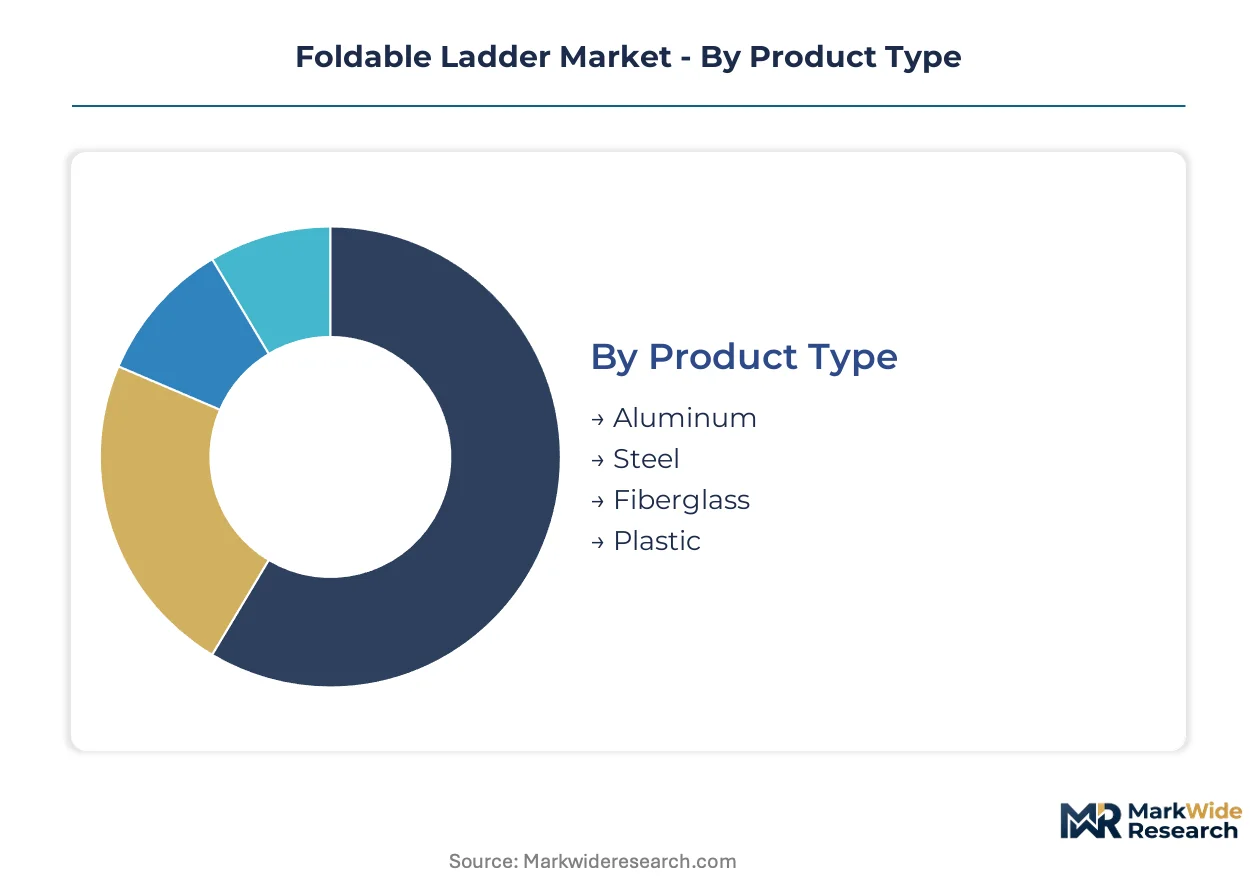
Foldable ladder procurement patterns fragment sharply across material specifications and end-use risk profiles. Regulatory duty ratings and channel access requirements create distinct margin pools that reward precise segment targeting.
Product Type:
Domestic production concentrates aluminum extrusion in the US Midwest and Ohio River Valley, while fiberglass resin supply chains stretch to China and the US Gulf Coast for dielectric-grade roving.
- Aluminum:Aircraft-grade alloys deliver strength-to-weight ratios that satisfy Type IA and IAA duty ratings under ANSI standards. Home improvement retail channels in the United States move the highest absolute volume, though contractor fleet standardization is compressing replacement cycles for multi-purpose models.
- Fiberglass:Pultruded rails with polyester or vinyl ester resin matrices provide mandatory dielectric insulation for electrical utility work. Demand clusters in Texas and California where utility contractors face energized line exposure, with OSHA 1910.269 compliance driving specification rigidity.
- Steel:Carbon and stainless tubing configurations serve permanent facility installations where weight portability matters less than cost minimization.
- Plastic:Polymer composite rails target residential step-stool applications with sub-200-pound duty requirements.
Aluminum holds the largest share; momentum sits with fiberglass as electrical safety mandates tighten.
Application:
Cost tier stratification separates premium certified models from economy retail offerings, with compliance documentation becoming the decisive pricing variable.
- Residential:DIY enthusiasts purchasing through big-box retailers drive volume for lightweight aluminum step and extension designs. OSHA compliance is minimal; ANSI Type III duty ratings suffice for household tasks under 200 pounds.
- Commercial:Facility maintenance departments in US healthcare and higher education verticals unbundle fleet management into standalone service contracts. Joint Commission accreditation requirements prioritize documented inspection over unit cost, creating annuity revenue for certified suppliers.
- Industrial:Manufacturing plants and warehousing operations specify Type I and IA ratings for daily use above 250 pounds.
- Utility:Electrical transmission and distribution contractors require dielectric certification and hot-stick compatibility for energized line work.
Residential commands absolute volume; commercial applications are climbing the fastest as liability exposure reshapes procurement priorities.
Features:
Volume concentration favors multi-purpose articulating designs that collapse for transport and extend for varied reach requirements.
- Lightweight:Hollow-rung aluminum extrusions and polymer rail inserts reduce carrying burden for residential delivery services and mobile contractors.
- Extendable:Telescoping rail systems with aircraft-grade locking mechanisms enable single-user height adjustment without disassembly.
- Multi-Purpose:Hinge engineering permits A-frame, extension, and staircase configurations from a single unit. Werner Co. and Little Giant Ladders compete on proprietary joint designs that extend load capacity without weight penalties.
- Slip-Resistant:OSHA-mandated rung surfaces with serrated aluminum or rubberized coatings protect against fall incidents in wet or oily environments.
Multi-purpose configurations hold the largest share; lightweight designs are gaining share fastest as last-mile delivery operators enter the buyer pool.
End User:
Customer type determines channel structure, with contractors bypassing retail distributors for direct manufacturer relationships.
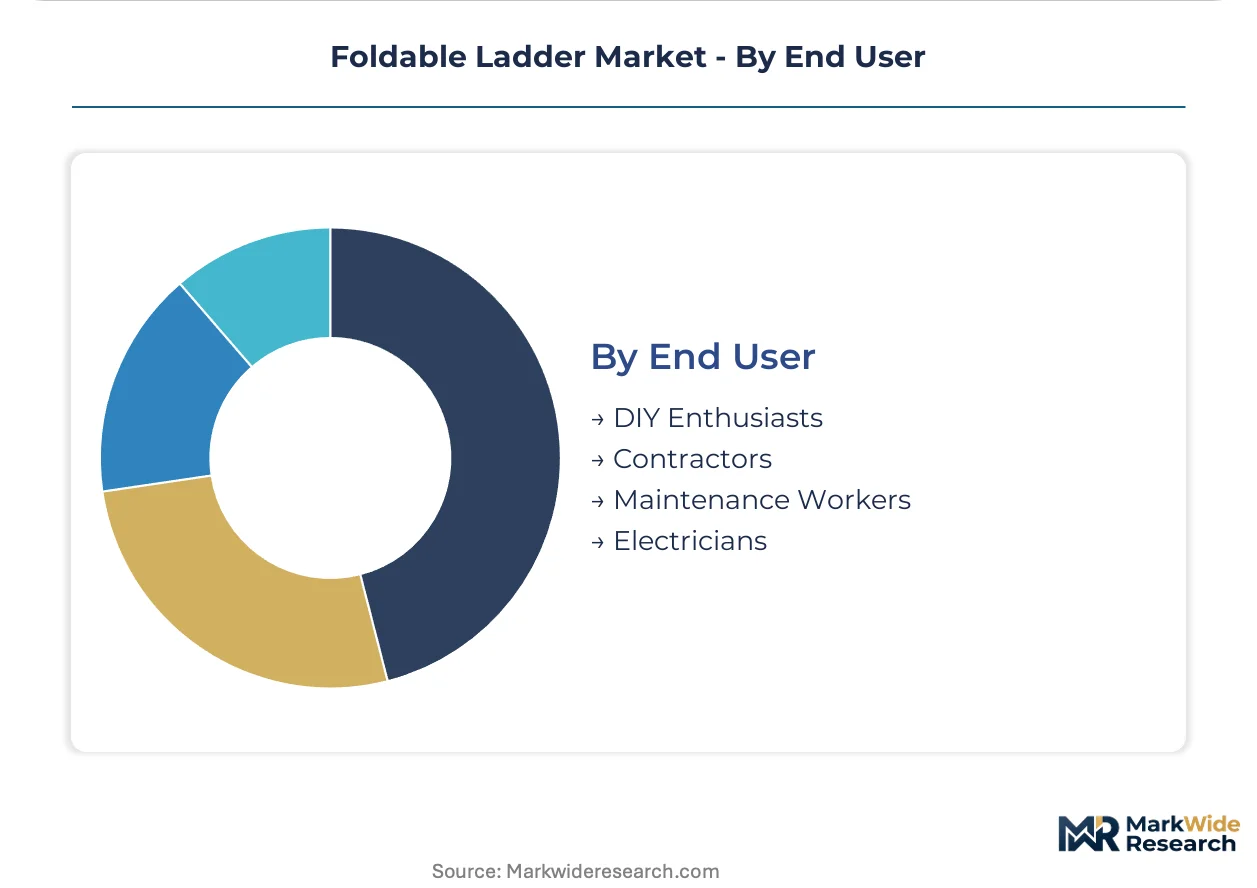
- DIY Enthusiasts:Price-sensitive homeowners purchasing through Home Depot and Lowe's sustain baseline aluminum volume. ANSI Type III and II ratings dominate; brand recognition and shelf placement drive selection.
- Contractors:Construction crews and renovation specialists accelerate replacement cycles as project backlogs extend. Fleet standardization across multi-site operations favors single-source procurement with volume pricing and predictive maintenance scheduling.
- Maintenance Workers:Facility management departments in commercial real estate and institutional buildings prioritize documented compliance and inspection services over upfront unit cost.
- Electricians:Trade-specific certification requirements for dielectric properties and hot-stick compatibility create premium pricing power for fiberglass specialists.
DIY enthusiasts hold the largest share; contractors are expanding most quickly as fleet standardization becomes operational priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's aluminum ingot handling capacity underwrites European supply chain reliability for extrusion-dependent ladder fabricators, while the Ohio River Valley barge network anchors North American raw material flows.
United States
Home Depot and Lowe's distribution centers in Atlanta and Dallas sustain the world's densest retail channel for residential aluminum models. OSHA's 1910.269 energized line work standards mandate dielectric certification for electrical utility procurement. Houston hosts concentrated fiberglass pultrusion capacity serving Texas utility contractors facing hot-stick compliance deadlines.
Germany
Industrial facility maintenance departments in the Ruhr Valley accelerate fleet standardization contracts with documented inspection protocols. REACH substance restrictions on hexavalent chromium passivation force coating transitions to trivalent chrome alternatives. Stuttgart's automotive coating technology clusters enable rapid supplier qualification for compliant surface treatments.
China
Dielectric-grade fiberglass roving production concentrates in Jiangsu and Zhejiang provinces for export to electrical-rated ladder manufacturers. GB standards for portable access equipment align partially with EN 131 frameworks to facilitate CE marking equivalency. Ningbo's port infrastructure handles bulk resin shipments for Gulf Coast fiberglass fabricators.
United Kingdom
Construction project backlogs in Greater London drive contractor fleet replacement cycles for multi-purpose articulating designs. HSE Work at Height Regulations mandate pre-use inspection documentation for commercial applications. Birmingham's metal fabrication heritage supports aluminum extrusion tooling for domestic and export markets.
India
Urban residential renovation in Mumbai and Delhi-NCR expands DIY channel volume for lightweight step configurations. BIS certification requirements for portable ladders tighten import eligibility and protect domestic fabricators. Gujarat's chemical processing corridor develops vinyl ester resin capacity for electrical-grade fiberglass rail production.
Foldable Ladder Market Competitive Landscape
Listed leaders compete with private specialists across certification infrastructure and captive extrusion capabilities. The vendor base organizes into three tiers: integrated aluminum producers with in-house alloy casting, fiberglass specialists with dielectric testing laboratories, and retail-brand distributors without manufacturing assets. Strategic moves concentrate on M&A for testing facility accreditation and backward integration into aluminum billet sourcing.
Among North American fabricators, Werner Co. exemplifies the integrated archetype through captive supply of aircraft-grade aluminum alloys. Louisville Ladder occupies a position within the industrial-grade tier, while Little Giant Ladders represents hinge-engineering specialization for multi-purpose load capacity extension. These three anchors illustrate how competitive positioning fragments across material control, certification depth, and joint mechanism differentiation.
| Leading Market Players |
|---|
| Werner Co. |
| Little Giant Ladders |
| Louisville Ladder |
| Cosco |
| Gorilla Ladders |
| Lyte Ladders |
| Bailey Ladders |
| Telesteps |
| Hailo |
| Others |
Value Network & Pricing Analysis
Carbon fiber reinforced polymer rung inserts displacing standard fiberglass components are redrawing procurement geography toward aerospace-grade composite suppliers while compressing the cost premium between dielectric and non-dielectric ladder tiers. This substitution dynamic simultaneously elevates pricing power for certified hybrid manufacturers and fragments volume discounts across legacy aluminum and emerging composite product lines.
Pricing Analysis
Volume-discount tiering structures separate fleet procurement contracts for multi-site contractors from single-unit retail transactions at home improvement channels. Pricing stratifies across premium, standard, and economy tiers based on ANSI duty rating certification and bundled inspection documentation. Cost compression in the aluminum tier is intensifying because LME price volatility feeds directly into spot-market sourcing for non-integrated producers. DIY enthusiasts purchasing through retail channels exhibit highest price sensitivity, while healthcare facility maintenance departments prioritize documented compliance over unit cost minimization.
Supply Chain Analysis
China and the US Gulf Coast anchor dielectric-grade fiberglass roving production for electrical-rated ladder fabricators serving utility contractors. Raw material flows draw from Jiangsu province resin plants, Ohio River Valley aluminum smelters, and Stuttgart automotive coating clusters adapting REACH-compliant surface treatments. Single-source vulnerability concentrates in Chinese roving supply for North American electrical-grade rail production. Distribution runs through Home Depot and Lowe's regional distribution centers for residential volume, with direct manufacturer agreements displacing traditional two-step distribution for contractor fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct contractor e-procurement platforms are transforming foldable ladder procurement from transactional equipment purchasing into subscription-based fleet management ecosystems with predictive replacement scheduling. This interoperability shift between hardware specifications and digital maintenance infrastructure defines the current platform-economics inflection.
For Market Incumbents: Fortify captive aluminum extrusion capabilities against LME price volatility while accelerating certified testing infrastructure investments to lock out uncertified imports under tightening OSHA duty rating standards. Backward integration into aircraft-grade alloy casting and expansion of in-house AWS D1.2 welding certification programs defend margin position against mid-tier competitors dependent on spot-market sourcing and outsourced fabrication. For New Entrants and Emerging Players: Anchor in lightweight telescoping configurations for last-mile delivery operators entering the buyer pool, where sub-200-pound duty requirements and polymer composite rails create specification white space absent from incumbent catalogs. Target EU CE marking expansion through harmonized EN 131 compliance documentation, leveraging Stuttgart automotive coating partnerships to accelerate trivalent chrome surface treatment transitions faster than legacy competitors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with captive extrusion and certified testing laboratories over retail-brand distributors without manufacturing assets. Acquisition targets should demonstrate ISO 9001 traceability infrastructure and established direct contractor relationships with predictive maintenance scheduling capabilities. The signal to watch is unbundling of ladder fleet management from general MRO procurement into standalone service contracts with documented inspection protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Billet Sourcing | Captive alloy casting insulates Werner Co. and integrated producers from LME price volatility compressing spot-market dependent competitors. |
| CE Marking Documentation Upgrade | Harmonized EN 131 certification unlocks unified market access across Germany, France, and Italy for compliant producers. |
| Direct E-Procurement Platform Launch | Bypassing two-step distribution captures margin and fleet specification data for predictive replacement scheduling with contractors. |
| Fiberglass Pultrusion Capacity Expansion | Dielectric-grade rail production in Texas and California addresses OSHA 1910.269 compliance deadlines for utility contractors. |
| Trivalent Chrome Coating Transition | REACH-compliant surface treatment partnerships with Stuttgart automotive clusters accelerate European market eligibility ahead of legacy competitors. |
Research Methodology
Operator-level perspectives from maintenance directors at healthcare and higher education facilities, procurement leads at electrical utility contractors, plant engineers at aluminum extrusion facilities, and channel sales heads at home improvement retailers anchored the qualitative base. Primary interview insights combined with secondary validation from OSHA regulatory filings, ANSI standards documentation, SEC 10-K disclosures from listed fabricators, and customs trade data for aluminum ingot and fiberglass roving imports. Bottom-up segment sizing and top-down macroeconomic cross-checks established analytical triangulation across material, application, and end-user dimensions.
Sensitivity analysis tested forecast outputs against aluminum price volatility scenarios, regulatory compliance cost inflation, and substitution elasticity between fiberglass and emerging carbon fiber reinforced polymer configurations. Segmentation modeling incorporated material type, duty rating certification tier, distribution channel structure, and regional regulatory cluster across the projection horizon. CAGRs derived from historical shipment data, replacement cycle analysis, and construction spending correlation models with industry-specific inputs for contractor fleet standardization velocity and DIY renovation expenditure patterns.
Decision-makers should treat outputs as directional under sustained residential renovation spending and OSHA duty rating tightening assumptions; material deviation in aluminum LME pricing or REACH substance restriction enforcement would warrant model refresh. Recalibration cycles align with material shifts in regulatory compliance timelines and raw material sourcing geography.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
End Mill Holder Market
Tools
Striking Tools Market
Tools
Gear Honing Machines Market
Tools
Ultra Hard Material Cutting Machines Market
Tools
Broaching Tools Market
Tools
Multi Spindle Machines Market
Tools
Land Survey Equipment Market
Tools
Shape Moulding Machines Market
Tools
Extensometer Market
Tools
Europe Paint Spray Guns Market
Tools
Global Standard Parts for Tool Making Market
Tools
Post Drivers Market
Tools
Europe Stump Cutter/Grinder Market
Tools
Hand and Power Tools Market
Tools
Woodpecker Tools Market
Tools
Screwdriver Market