
 N-Heptane Market | 2026-2036
N-Heptane Market Size, Share, and Industry Trends Forecast 2026-2036
N-Heptane Market Outlook
The N-heptane market is decoupling into two distinct tiers: pharmaceutical-grade material commanding purity premiums versus commodity industrial solvent flowing on volume contracts. ExxonMobil Chemical leverages integrated refinery streams to anchor supply security for high-specification buyers. Haltermann Carless specializes in narrow-cut solvent refining, sustaining margin capture in European analytical applications. SK Geo Centric dominates Northeast Asian petrochemical corridors, competing on scale for bulk fuel additive and chemical intermediate offtake.
N-heptane is a straight-chain alkane hydrocarbon with formula C₇H₁₆, boiling point 98.4°C, and density 0.684 g/cm³, produced primarily via fractional distillation of naphtha or molecular sieve extraction from petroleum reformate streams; its primary purpose centers on serving as a non-polar solvent, calibration reference for octane rating engines, and precursor in polyethylene polymerization catalyst systems. Industrial grade material leads volume flows through fuel additive and general solvent channels, while analytical grade commands concentrated margin pools from pharmaceutical quality control and forensic toxicology laboratories where ASTM D2709 water tolerance standards govern acceptance. Chemical intermediate applications are growing fastest as Ziegler-Natta catalyst formulations expand in Asian polyolefin capacity additions.
EPA fuel volatility standards under the Clean Air Act shape octane testing demand, while REACH registration requirements in Europe constrain importer access for sub-99% purity grades. China's SAMR enforces GB/T 3405 petroleum solvent specifications that filter non-compliant regional blenders from domestic pharmaceutical supply chains. Stakeholders must monitor evolving dual carbon compliance timelines and catalyst technology shifts that could redirect n-heptane offtake from fuel testing toward polymerization feedstock roles.
Market Dynamics
N-heptane demand is bifurcating sharply between pharmaceutical-grade purity requirements and commodity industrial volumes, with polymerization catalyst feedstock applications now commanding the fastest capacity expansion across Asian petrochemical corridors.
Growth Catalysts
- Polyolefin capacity expansion:Ziegler-Natta catalyst systems in new Asian polyethylene plants are absorbing n-heptane volumes as co-catalyst carriers and reaction moderators, redirecting supply from traditional solvent markets.
- REACH purity escalation:ECHA registration thresholds for reagent-grade material are filtering sub-99% imports from European analytical laboratories, consolidating procurement among certified domestic refiners.
- Chromatography solvent standardization:Pharmaceutical QC laboratories in India are upgrading to ASTM D2709-compliant material for HPLC and GC-MS applications, creating specification-driven demand pull.
Market Restraints
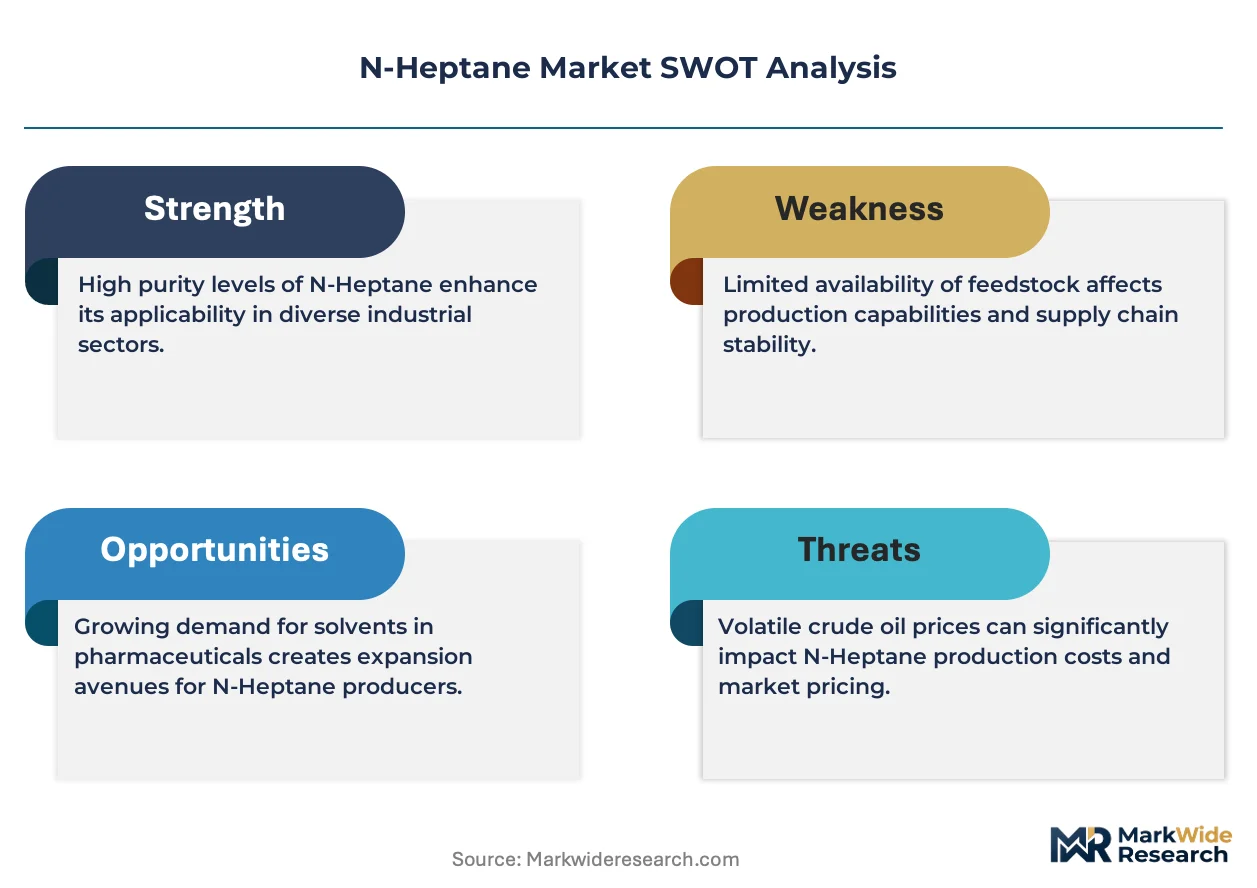
- Naphtha feedstock volatility:Crude-linked naphtha costs transmit directly to n-heptane production economics, compressing margins for non-integrated fractional distillation operators during upstream price spikes.
- Isomeric substitution pressure:Branched C7 isomers and synthetic heptane blends are displacing straight-chain material in select fuel additive applications where octane calibration tolerances permit flexibility.
- Chinese supply concentration:Eastern chemical manufacturing corridors around Shanghai and Ningbo dominate global exportable surplus, creating single-source vulnerability for importers in Southeast Asia and the Middle East.
Strategic Opportunities
- Pharmaceutical corridor penetration:Underdeveloped analytical solvent channels in Brazil and Mexico present white-space expansion potential as ANVISA and COFEPRIS align with ICH Q3C residual solvent guidelines.
- Dual carbon compliance positioning:China's MEE carbon intensity benchmarks for petrochemical processes are incentivizing low-emission n-heptane recovery and recycling infrastructure investments.
- Digital specification platforms:Blockchain-anchored certificates of analysis are emerging as procurement differentiators for forensic toxicology laboratories requiring chain-of-custody documentation.
Industry Challenges
- Refinery technician scarcity:Narrow-cut solvent refining demands specialized fractional distillation expertise that is aging out of European and North American workforce pipelines without adequate replacement training.
- Multi-jurisdiction certification lag:Simultaneous compliance with EPA fuel volatility standards, REACH registration, and SAMR GB/T 3405 specifications extends product qualification timelines for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | N-Heptane Market |
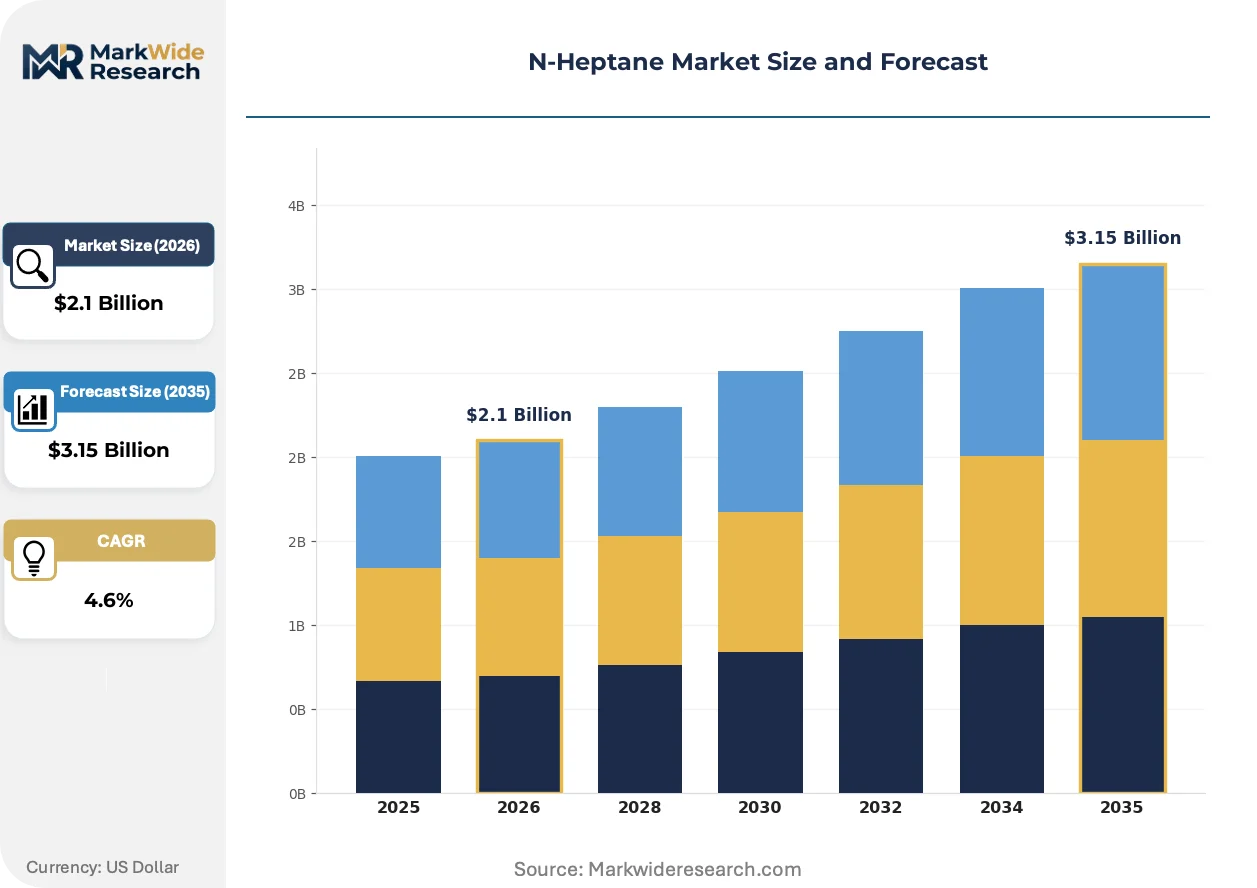
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
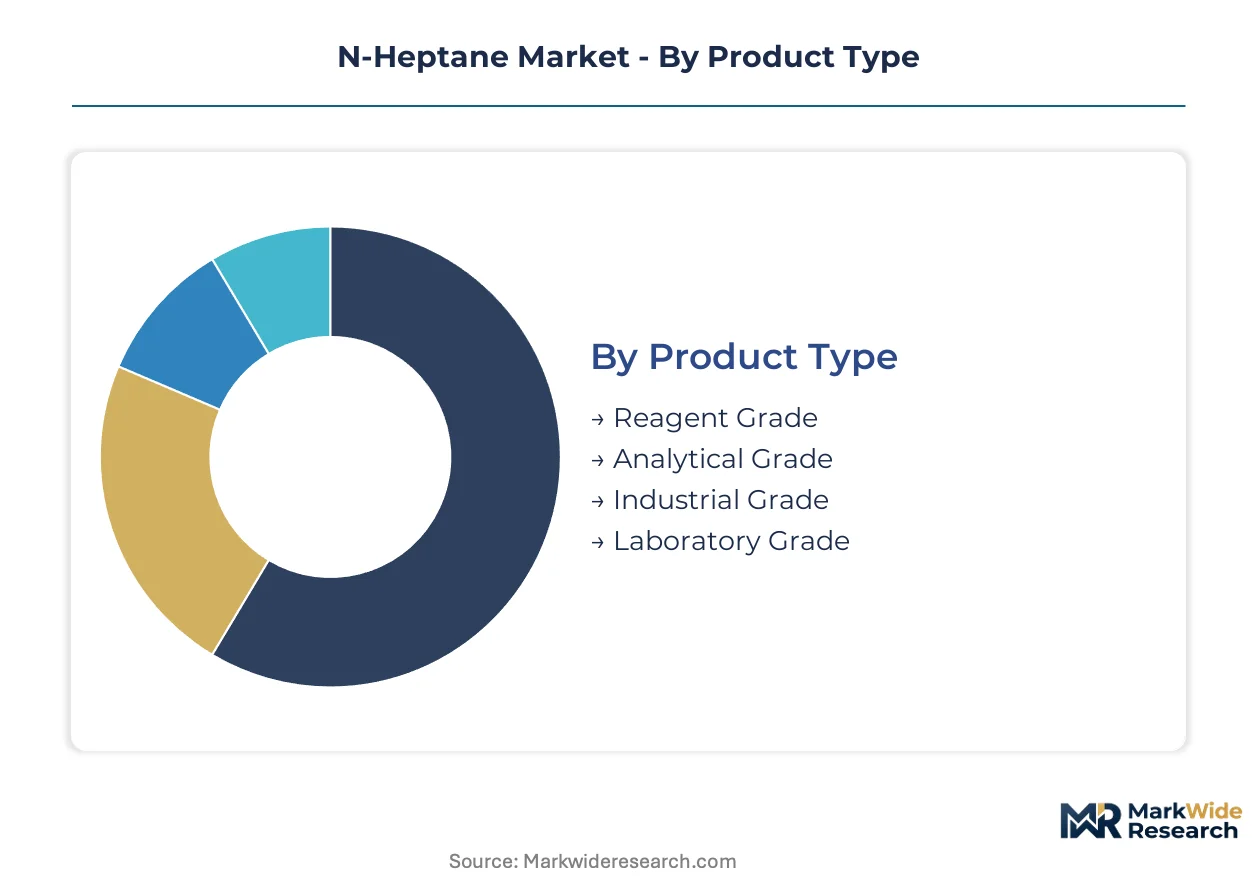
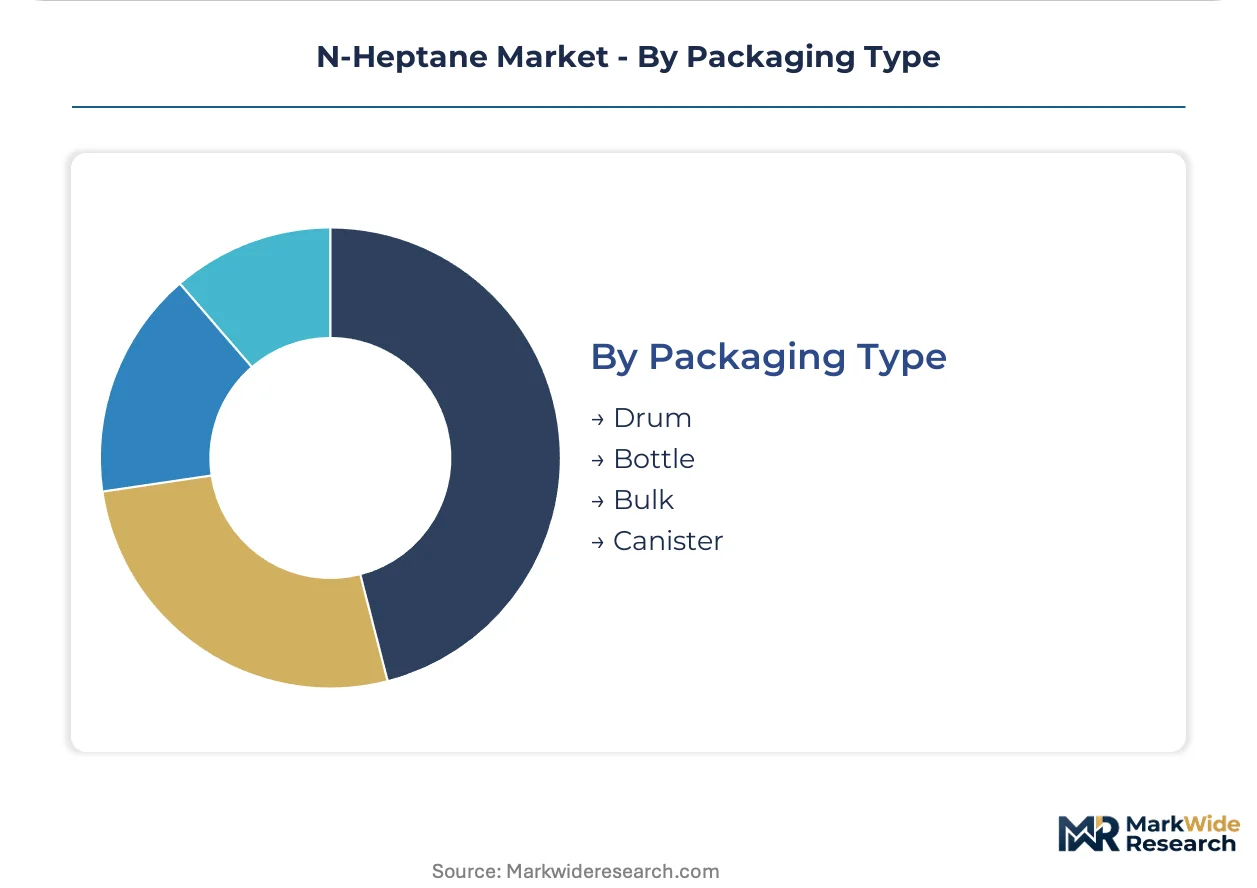
| Segmentation | Product Type: Reagent Grade, Analytical Grade, Industrial Grade, Laboratory Grade Application: Solvent, Fuel Additive, Chemical Intermediate, Calibration Standard End User: Chemical Industry, Oil & Gas, Pharmaceutical, Research Laboratories Packaging Type: Drum, Bottle, Bulk, Canister |
| Companies Covered | ExxonMobil Chemical, Shell Chemicals, Chevron Phillips Chemical, SABIC, Honeywell International, Haltermann Carless, SK Geo Centric, Reliance Industries, Maruzen Petrochemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
N-Heptane Market Strategic Shifts
Molecular sieve extraction technology and catalyst system engineering are converging to reshape how n-heptane purity grades are produced, certified, and consumed across industrial and analytical end-uses.
Advanced molecular sieve adsorption is unifying the separation of straight-chain alkanes from reformate streams, enabling single-unit operations to switch between pharmaceutical-grade and industrial-grade output based on real-time demand signals. Polymer producers in South Korea and Saudi Arabia are adopting these flexible units to secure captive n-heptane supply for metallocene catalyst systems. This unifying capability is compressing the traditional premium between narrow-cut and wide-cut solvent pricing tiers.
REACH registration requirements are tightening substance identity documentation for imported n-heptane, forcing non-EU refiners to establish EU-based only representatives or surrender analytical-grade market access. The industrial consequence is a consolidation of import channels toward integrated petrochemical majors with established ECHA compliance infrastructure. Small-volume pharmaceutical laboratories in Germany and the Netherlands are responding by pooling procurement through distributor consortia to maintain supplier diversification.
Specification-driven purchasing is displacing spot-market sourcing among pharmaceutical QC departments, with multi-year contracts anchored to ASTM D2709 and ACS reagent-grade certifications replacing transactional buying. Distributor networks in India and Southeast Asia are restructuring around certified stockholding rather than bulk-breaking logistics. This behavioral shift is most visible in Mumbai and Hyderabad, where CDSCO-aligned pharmaceutical manufacturers are pre-qualifying solvent suppliers through extended audit protocols.
N-Heptane Market Segmentation
N-heptane purity grades command vastly different capital commitments, from million-dollar molecular sieve units for pharmaceutical-grade output to commodity fractional distillation for industrial volumes. Understanding how production investment maps to end-use requirements reveals where margin pools concentrate and where capacity expansion faces technical barriers.
Product Type:
Reagent-grade and analytical-grade production demands the heaviest upfront capital, requiring dedicated adsorption columns, multi-stage distillation trains, and certified clean-room packaging infrastructure that industrial-grade operators can bypass.
- Reagent Grade:Purity thresholds exceed 99.5% with stringent ACS certification protocols. Pharmaceutical QC laboratories in Hyderabad and Mumbai are consolidating procurement around CDSCO-aligned suppliers who maintain dedicated batch documentation systems. REACH registration in Europe filters non-compliant imports, consolidating supply among integrated refiners with ECHA infrastructure.
- Analytical Grade:ASTM D2709 water tolerance standards govern acceptance for HPLC and GC-MS applications. Forensic toxicology laboratories in Germany and the Netherlands are shifting toward blockchain-anchored certificates of analysis to satisfy chain-of-custody requirements. This grade captures concentrated margin pools but requires continuous in-process monitoring.
- Industrial Grade:Wide-cut solvent material flows through fuel additive and general chemical channels where octane calibration tolerances permit flexibility.
- Laboratory Grade:Intermediate purity tier serves educational institutions and routine testing facilities with less stringent certification demands.
Most installed capacity flows through Industrial Grade. Expansion is steepest in Reagent Grade.
Application:
Volume concentration and value capture diverge sharply across applications, with polymerization catalyst feedstock absorbing growing tonnage while calibration standards sustain premium pricing.
- Solvent:Non-polar extraction and cleaning applications span pharmaceutical manufacturing, electronics degreasing, and coatings formulation. Indian pharmaceutical corridors are upgrading solvent specifications to align with ICH Q3C residual solvent guidelines, displacing lower-grade material.
- Chemical Intermediate:Ziegler-Natta and metallocene catalyst systems in South Korean and Saudi Arabian polyethylene plants consume n-heptane as co-catalyst carriers. Petrochemical majors are installing flexible molecular sieve units to switch between captive supply and merchant sales based on demand signals.
- Fuel Additive:Octane rating reference material for engine testing laboratories faces substitution pressure from branched C7 isomers where specifications permit.
- Calibration Standard:EPA fuel volatility testing under the Clean Air Act maintains steady demand from automotive and regulatory laboratories.
Volume concentrates in Solvent applications. Chemical Intermediate is gaining share fastest.
End User:
Customer sophistication and procurement power vary dramatically, from price-taking bulk chemical processors to specification-locked pharmaceutical manufacturers with extended supplier audit protocols.
- Pharmaceutical:CDSCO-aligned manufacturers in Mumbai and Hyderabad are pre-qualifying solvent suppliers through 18-month audit cycles. Multi-year contracts anchored to ASTM and ACS certifications are displacing spot-market sourcing.
- Chemical Industry:Polyolefin producers across Northeast Asian petrochemical corridors compete on scale for bulk offtake, negotiating volume contracts with integrated refiners.
- Research Laboratories:Academic and government facilities prioritize certified stockholding over bulk-breaking logistics, restructuring distributor networks in India and Southeast Asia.
- Oil & Gas:Downstream refiners and fuel testing operations consume calibration-grade material for octane engine reference standards.
Procurement volume clusters in Chemical Industry. Pharmaceutical is expanding most quickly.
Packaging Type:
Packaging infrastructure investment scales with contamination risk, from stainless steel bulk terminals for industrial processors to nitrogen-purged amber glass for analytical applications.
- Bulk:Tanker and ISO-container delivery dominates polymerization catalyst and fuel additive channels where contamination control requirements are moderate.
- Drum:Standard 200-liter steel drums serve chemical manufacturing and mid-scale solvent applications with established handling protocols.
- Bottle:Amber glass with nitrogen headspace protects analytical-grade material for pharmaceutical QC and forensic laboratories.
- Canister:Specialized pressurized containers serve portable calibration equipment and field testing operations.
Shipment volume runs predominantly through Bulk. Bottle packaging is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the dominant share of global n-heptane production capacity, while India is expanding pharmaceutical-grade solvent demand at the fastest clip among major economies.
China
Ziegler-Natta catalyst systems in new polyethylene plants are absorbing industrial-grade volumes across the Yangtze River Delta. SAMR enforces GB/T 3405 petroleum solvent specifications that filter non-compliant regional blenders from domestic pharmaceutical supply chains. Shanghai and Ningbo chemical manufacturing corridors dominate exportable surplus, creating single-source vulnerability for Southeast Asian importers.
United States
EPA fuel volatility standards under the Clean Air Act sustain steady demand from automotive and regulatory testing laboratories. OSHA workplace exposure limits for hydrocarbon solvents shape packaging and handling protocols across downstream distribution. Gulf Coast petrochemical complexes around Houston and Baytown anchor integrated naphtha-to-solvent production chains for both domestic and export markets.
Germany
REACH registration requirements filter sub-99% purity imports from European analytical laboratories, consolidating procurement among certified domestic refiners. ECHA substance identity documentation mandates force non-EU suppliers to establish EU-based only representatives or surrender market access. Frankfurt and Ludwigshafen pharmaceutical corridors are pooling procurement through distributor consortia to maintain supplier diversification.
India
Pharmaceutical QC laboratories in Mumbai and Hyderabad are upgrading to ASTM D2709-compliant material for HPLC and GC-MS applications. CDSCO-aligned manufacturers are pre-qualifying solvent suppliers through extended audit protocols that displace spot-market sourcing. Gujarat's specialty chemical clusters are building certified stockholding infrastructure to serve CDSCO-compliant export pharmaceutical operations.
Saudi Arabia
Metallocene catalyst systems in new polyethylene capacity are absorbing n-heptane as co-catalyst carriers and reaction moderators. SFDA pharmaceutical manufacturing standards are beginning to align with ICH Q3C residual solvent guidelines, creating specification upgrade pressure. Jubail Industrial City petrochemical complexes are installing flexible molecular sieve units to switch between captive supply and merchant sales.
N-Heptane Market Competitive Environment
Top-tier vendors anchor integrated petrochemical supply chains, while specialized refiners occupy narrow-cut solvent niches. The competitive structure stratifies between scale-driven commodity producers and certification-focused analytical-grade specialists. Three archetypes dominate: integrated oil majors with captive naphtha feedstocks, independent narrow-cut refiners with pharmaceutical-grade capabilities, and regional petrochemical players serving polymerization catalyst demand. Capacity expansion and strategic partnerships represent the dominant competitive vectors.
Within the integrated major tier, ExxonMobil Chemical exemplifies upstream control over refinery stream allocation, while Shell Chemicals occupies a comparable position in European and Asian corridors. Haltermann Carless represents the specialized narrow-cut refiner archetype, anchoring analytical-grade supply for European pharmaceutical and forensic laboratories. SK Geo Centric sits within the Northeast Asian petrochemical player group, competing on scale for bulk chemical intermediate offtake.
| Leading Market Players |
|---|
| ExxonMobil Chemical |
| Shell Chemicals |
| Chevron Phillips Chemical |
| SABIC |
| Honeywell International |
| Haltermann Carless |
| SK Geo Centric |
| Reliance Industries |
| Maruzen Petrochemical |
| Others |
Value Chain & Pricing Dynamics
REACH registration requirements in Europe are forcing pharmaceutical laboratories to consolidate procurement around certified domestic refiners, compelling supply chains to absorb compliance costs and compressing margins for non-integrated importers. This specification-driven purchasing shift is reshaping how n-heptane flows from refinery to end-user, with certification premiums widening the gap between analytical-grade and industrial-grade pricing tiers.
Pricing Analysis
Capacity additions in China and Saudi Arabia are reshaping price floors for industrial-grade material as flexible molecular sieve units enable producers to switch between captive supply and merchant sales. Three-tier pricing structure across pharmaceutical-grade, analytical-grade, and industrial-grade levels captures divergent margin pools, with ASTM D2709 certification commanding substantial premiums over commodity solvent. Cost compression in industrial-grade channels is intensifying because branched C7 isomers are displacing straight-chain material where fuel additive specifications permit flexibility. Polyolefin producers demonstrate lowest price sensitivity due to captive supply arrangements, while educational laboratories face acute budget constraints.
Supply Chain Analysis
Dual-sourcing requirements from CDSCO-aligned pharmaceutical manufacturers in India are compelling distributors to maintain redundant certified stockholding infrastructure rather than relying on single-source bulk-breaking logistics. Supply concentrates in China, South Korea, and Saudi Arabia, with Eastern chemical manufacturing corridors around Shanghai and Ningbo dominating exportable surplus. Production draws from naphtha reformate streams and molecular sieve extraction units, with specialized fractional distillation capacity concentrated among integrated petrochemical majors. Single-source vulnerability for Southeast Asian importers represents the primary structural risk. Distribution runs through tanker and ISO-container delivery for industrial volumes, with nitrogen-purged amber glass channels serving analytical-grade requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The n-heptane market functions as a stable compounder anchored by polymerization catalyst demand from Asian polyethylene capacity expansion, with specification-grade premiums providing defensive margin pools against commodity volatility.
For Market Incumbents: Extend certification infrastructure investments to capture REACH-escalated purity requirements in European analytical laboratories, while anchoring long-term offtake agreements with South Korean and Saudi Arabian polyolefin producers. Molecular sieve flexibility enables switching between pharmaceutical-grade and industrial-grade output based on real-time demand signals, defending margin capture against narrow-cut specialists. Backward integration into naphtha reformate streams secures feedstock cost advantages during upstream price spikes. For New Entrants and Emerging Players: Distributor consortia in Germany and the Netherlands present partnership pathways for certified stockholding operations serving fragmented pharmaceutical QC laboratories. Brazil and Mexico offer the most penetrable white-space targets as ANVISA and COFEPRIS align with ICH Q3C residual solvent guidelines, displacing lower-grade material. Blockchain-anchored certificates of analysis provide a differentiated go-to-market angle for forensic toxicology channels requiring chain-of-custody documentation. For Investors and Strategic Acquirers: Asymmetric upside sits with independent narrow-cut refiners possessing pharmaceutical-grade capabilities and established ECHA compliance infrastructure, as REACH registration requirements filter non-compliant imports and consolidate procurement among certified domestic suppliers. Long-term viability rests on catalyst technology shifts redirecting n-heptane offtake from fuel testing toward polymerization feedstock roles. Watch for dual carbon compliance timelines in China and carbon intensity benchmarks from MEE as inflection indicators for low-emission recovery and recycling infrastructure investment.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | New molecular sieve units in Jubail Industrial City enable flexible pharmaceutical-grade and industrial-grade output switching. |
| Backward Integration | Upstream control over naphtha reformate streams secures feedstock cost advantages for integrated petrochemical majors. |
| Long-term Supply Agreement | Multi-year contracts with CDSCO-aligned manufacturers displace spot-market sourcing in Mumbai and Hyderabad corridors. |
| Joint Venture | Partnerships with distributor consortia in Frankfurt maintain supplier diversification under REACH registration constraints. |
| Green Manufacturing Transition | Low-emission n-heptane recovery infrastructure aligns with China's MEE carbon intensity benchmarks for petrochemical processes. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with refinery operations managers, pharmaceutical procurement leads, solvent distribution channel partners, and technical R&D directors at catalyst manufacturers with secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from petrochemical majors, and ECHA registration databases. Bottom-up capacity modeling and top-down demand segmentation were triangulated to cross-verify volume and value outputs.
Segment-weighting approaches distributed volume and value across purity grade tiers, end-use industries spanning pharmaceutical QC and polyolefin production, packaging formats from bulk tankers to amber glass bottles, and regional production hubs. CAGRs were derived from fitted growth curves against historical capacity utilization and projected demand absorption rates. Key forecast inputs included Ziegler-Natta catalyst system deployment schedules in Asian polyethylene plants and REACH registration compliance timelines filtering import channels.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to crude-linked naphtha cost volatility, catalyst technology substitutions in polymerization systems, and regulatory alignment trajectories for residual solvent guidelines across emerging pharmaceutical manufacturing corridors. Deviation in carbon intensity enforcement timelines or molecular sieve technology adoption rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Benzyl Chloride Market
Bulk Chemicals
Furfuryl Alcohol Market
Bulk Chemicals
North America Potassium Formate Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
North America Copper Sulphate Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
2-Nitrothiophene Market
Bulk Chemicals
Copper Sulfate Market
Bulk Chemicals
Tertiary Butylhydroquinone Market
Bulk Chemicals
Ammonia Storage Tanks Market
Bulk Chemicals
Global Chlorinated Paraffin Wax Market
Bulk Chemicals
Magnesium Lactate Market
Bulk Chemicals
US Carbon Black Market
Bulk Chemicals
Hydrochloric Acid Electrolysis Market
Bulk Chemicals
Isovaleryl Chloride Market