
 Sodium Silicate Market | 2026-2036
Sodium Silicate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Silicate Market Analysis
Direct supply contracts between silicate producers and detergent compounders is tilting procurement power toward large-volume buyers. PQ Corporation leverages captive alkali production to sustain margin control across North American distribution. Tokuyama Corporation anchors its position through specialized high-purity grades for electronics applications. Evonik Industries AG competes on technical service intensity in European industrial coatings channels.
Sodium silicate comprises alkali metal silicates with varying SiO₂-to-Na₂O ratios, typically manufactured by fusing sand with soda ash at temperatures exceeding 1300°C or through hydrothermal dissolution; the compound functions as a binder, deflocculant, and corrosion inhibitor across industrial processes. Liquid sodium silicate dominates volume throughput due to its lower handling cost and direct integration into detergent slurry and cement admixture formulations. Solid sodium silicate carries premium positioning in remote construction markets where freight economics favor reduced water content. Sodium metasilicate leads growth within cleaners applications, driven by alkaline degreasing demand from food processing equipment maintenance.
EPA effluent guidelines constrain mercury and heavy metal residuals in silicate derived from trona-based feedstock, while REACH registration requirements in Europe mandate full substance dossiers for sodium silicate imports above one tonne annually. China's GB standards on industrial chemical purity and India's BIS certification for construction additives create layered compliance thresholds for multinational suppliers. Stakeholders must monitor regulatory divergence between OECD-aligned hazard classifications and emerging economy enforcement capacities to anticipate reformulation costs and market access timing.
Market Dynamics
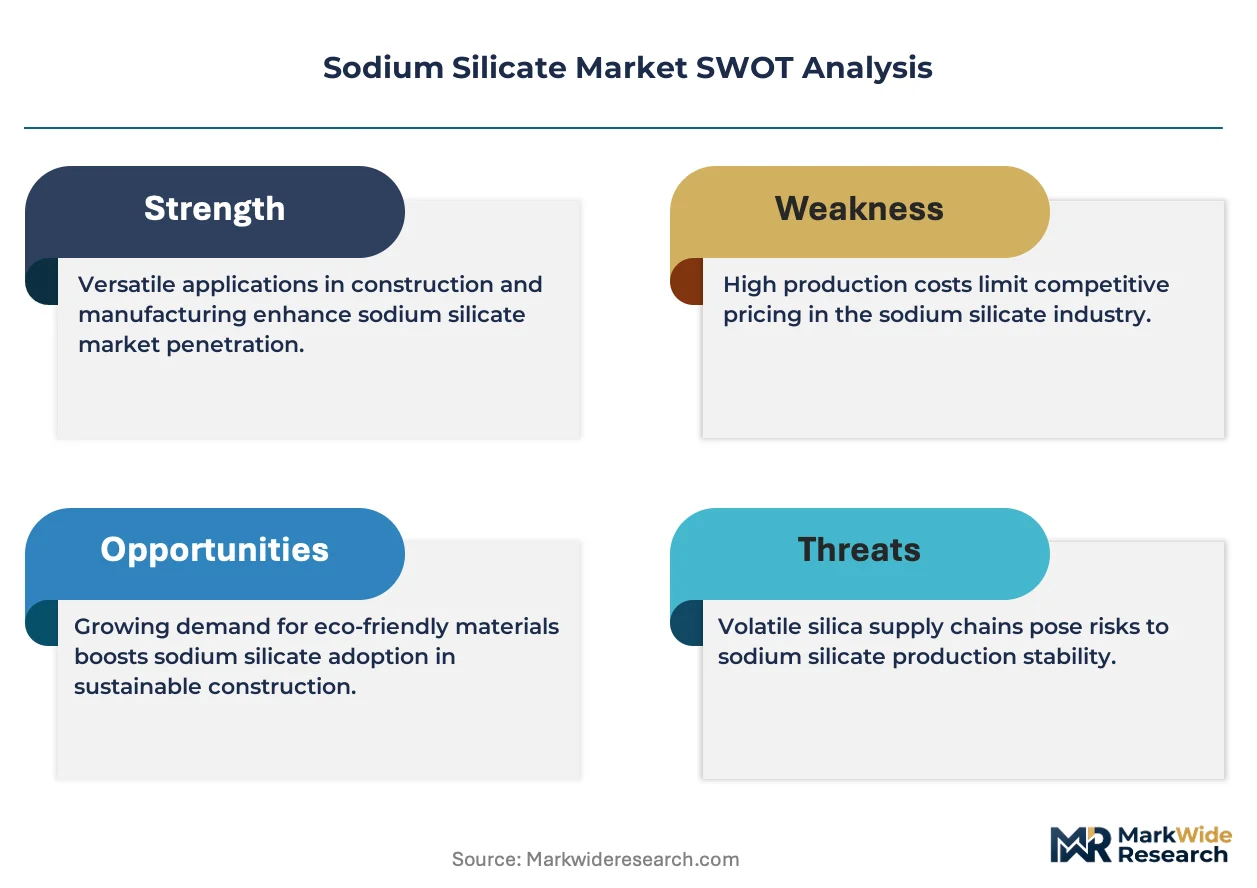
Phosphate-free detergent mandates are restructuring procurement relationships across the sodium silicate value chain, compelling compounders to secure long-term supply agreements with specialized alkali-silicate producers.
Growth Catalysts
- EPA effluent standards:Tightening mercury and heavy metal limits on trona-derived silicate are accelerating plant upgrades that favor integrated producers with captive purification capacity.
- India's PLI scheme for chemicals:Production-linked incentives are attracting greenfield sodium silicate capacity to serve construction and detergent demand from rapid urbanization.
- Alkaline degreasing in food processing:Sodium metasilicate formulations are displacing solvent-based cleaners in equipment maintenance protocols across commercial kitchens and processing facilities.
Market Restraints
- Soda ash price volatility:Energy-intensive Solvay process economics and natural trona mining disruptions transmit directly to silicate feedstock costs.
- REACH dossier requirements:Full substance registration above one tonne annually creates compliance friction for importers serving European industrial coatings channels.
- Solid silicate freight economics:Remote construction markets face delivered cost premiums that liquid alternatives partially offset through regional blending facilities.
Strategic Opportunities
- Electronics-grade high-purity silicate:Semiconductor wafer polishing and display glass manufacturing require ultra-low impurity grades commanding technical premiums.
- China's dual carbon goals:MEE enforcement of industrial emissions standards is shuttering inefficient furnaces, creating import substitution openings for compliant foreign suppliers.
- Cement admixture channel expansion:Direct-to-precast concrete producer relationships bypass traditional construction chemical distributors in high-volume urban projects.
Industry Challenges
- Furnace operator skill scarcity:Hydrothermal dissolution process control and SiO₂-to-Na₂O ratio calibration require experienced technical labor in short supply across emerging production regions.
- Legacy system integration:Automated dosing equipment for liquid silicate in continuous detergent manufacturing demands retrofitting of batch-oriented legacy compounder facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Silicate Market |
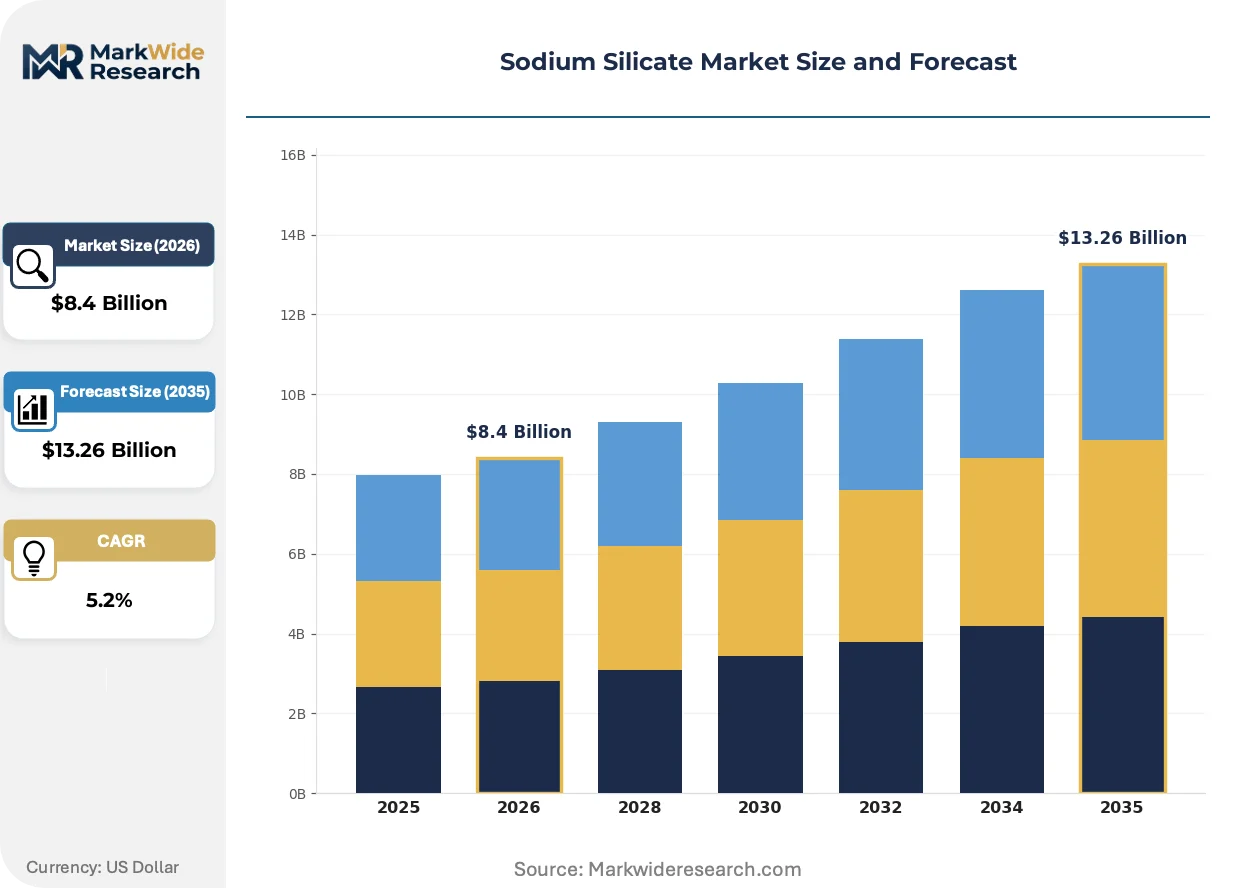
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Sodium Silicate, Solid Sodium Silicate, Sodium Metasilicate, Sodium Disilicate End Use Industry: Construction, Detergents, Textile, Paper Application: Adhesives, Sealants, Coatings, Cleaners Packaging Type: Drums, Bags, IBC Containers, Totes |
| Companies Covered | PQ Corporation, Qemetica, Nippon Chemical Industrial Co., Ltd., Occidental Petroleum Corporation, Tokuyama Corporation, Evonik Industries AG, BASF SE, Fuji Chemical Co., Ltd., IQE Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Silicate Market Emerging Trajectories
Process intensification and regulatory chemistry are compressing product development cycles, while downstream formulation science is unlocking functional performance beyond traditional binder and deflocculant roles.
Membrane filtration for heavy metal removal is migrating from pilot installations to standard plant configuration across trona-based silicate production. Detergent compounders in North America are specifying certified low-mercury grades to preempt EPA enforcement exposure. This technology is enabling integrated producers to defend premium positioning against hydrothermal competitors without captive alkali supply.
REACH registration requirements for sodium silicate imports above one tonne annually are fragmenting supplier bases serving European industrial coatings channels. Full substance dossier costs disproportionately burden small-volume specialty importers relative to integrated multinational producers. Formulators are consolidating procurement toward registrants with complete Annex XV compliance packages.
Direct supply contracting between silicate producers and detergent compounders is compressing traditional chemical distributor margins in high-volume liquid grades. Large-volume buyers are extracting price concessions through multi-year offtake guarantees with indexed soda ash adjustments. India and Southeast Asia exhibit the most pronounced channel disintermediation as phosphate-free formulation mandates concentrate procurement among scaled regional compounders.
Sodium Silicate Market Segmentation
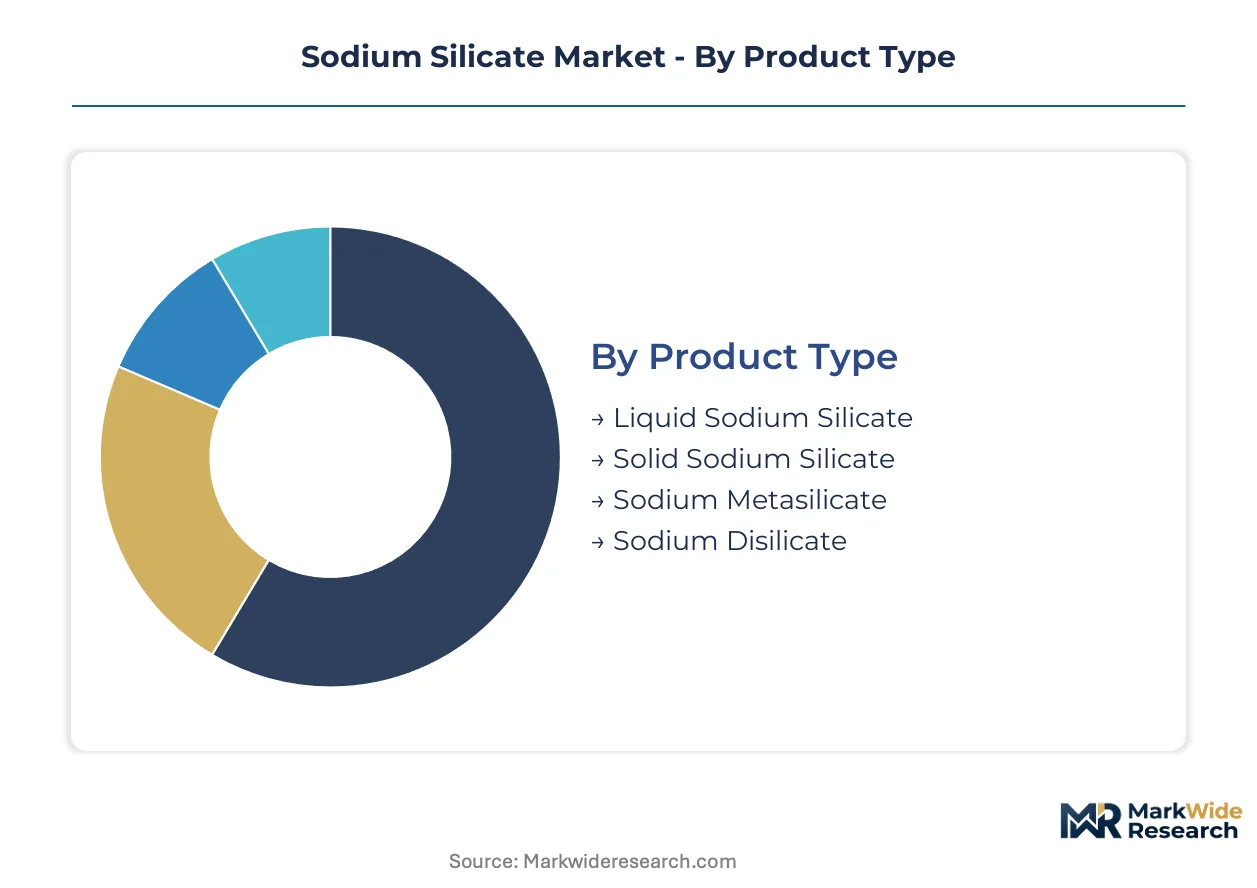
Sodium silicate segmentation reveals divergent margin structures across physical forms and end-use channels. Product type determines furnace economics and freight optimization, while end-use concentration shapes formulation specifications and contract tenure.
Product Type:
Cycle times vary dramatically: liquid grades turn inventory weekly through detergent slurry integration, whereas solid silicate sits for months awaiting remote construction dispatch.
- Liquid Sodium Silicate:Aqueous solutions with SiO₂-to-Na₂O ratios tunable between 1.6 and 3.75 dominate volume throughput. Procurement is concentrating among Indian and Southeast Asian detergent compounders responding to phosphate-free mandates through direct supply contracting.
- Solid Sodium Silicate:Fused glassy lumps or pearls with reduced water content command freight economics favoring remote markets. Demand clusters in African and Central Asian construction corridors where regional blending infrastructure remains underdeveloped.
- Sodium Metasilicate:Crystalline pentahydrate and anhydrous forms deliver precise alkaline dosing for food processing equipment degreasing protocols.
- Sodium Disilicate:Specialized hydrate structures serve compact detergent formulations requiring controlled dissolution kinetics.
Liquid sodium silicate dominates installed base. Sodium metasilicate is where expansion concentrates.
End Use Industry:
Cost tier stratification separates commodity construction applications from specification-driven detergent and textile channels demanding certified low-impurity grades.
- Construction:Cement admixtures, soil stabilization, and refractory binders absorb high-volume standard-grade material. India's urban infrastructure build-out through PLI-supported chemical capacity is accelerating consumption of construction-grade silicate in precast concrete applications.
- Detergents:Phosphate-free formulations depend on silicate for alkalinity buffering, anti-redeposition, and corrosion inhibition. EPA effluent standards on mercury residuals are compelling North American compounders to specify certified low-mercury grades from integrated producers.
- Textile:Bleaching stabilizers and dye fixatives require controlled iron and heavy metal specifications.
- Paper:De-inking operations and coating binders utilize silicate for fiber dispersion and surface sizing control.
Construction commands volume leadership. Detergents is where specification premiums expand.
Application:
Customer type differentiation separates continuous-process manufacturers from intermittent batch operations with divergent dosing infrastructure requirements.
- Adhesives:Laminating and corrugated board bonding applications favor liquid grades with rapid tack development and controlled penetration.
- Sealants:High-modulus formulations for industrial gasketing demand precise viscosity and cure rate specifications.
- Coatings:Intumescent fireproofing and anti-corrosion primers utilize silicate as inorganic binder matrix. REACH registration requirements above one tonne annually are fragmenting supplier bases serving European industrial coatings channels toward dossier-complete registrants.
- Cleaners:Alkaline degreasing formulations for food processing equipment maintenance specify sodium metasilicate for controlled pH and soil emulsification.
Cleaners applications are gaining share fastest. Adhesives maintains the broadest installed base.
Packaging Type:
Supply concentration among drum and IBC formats reflects liquid grade dominance, while bagged solid silicate serves dispersed construction markets.
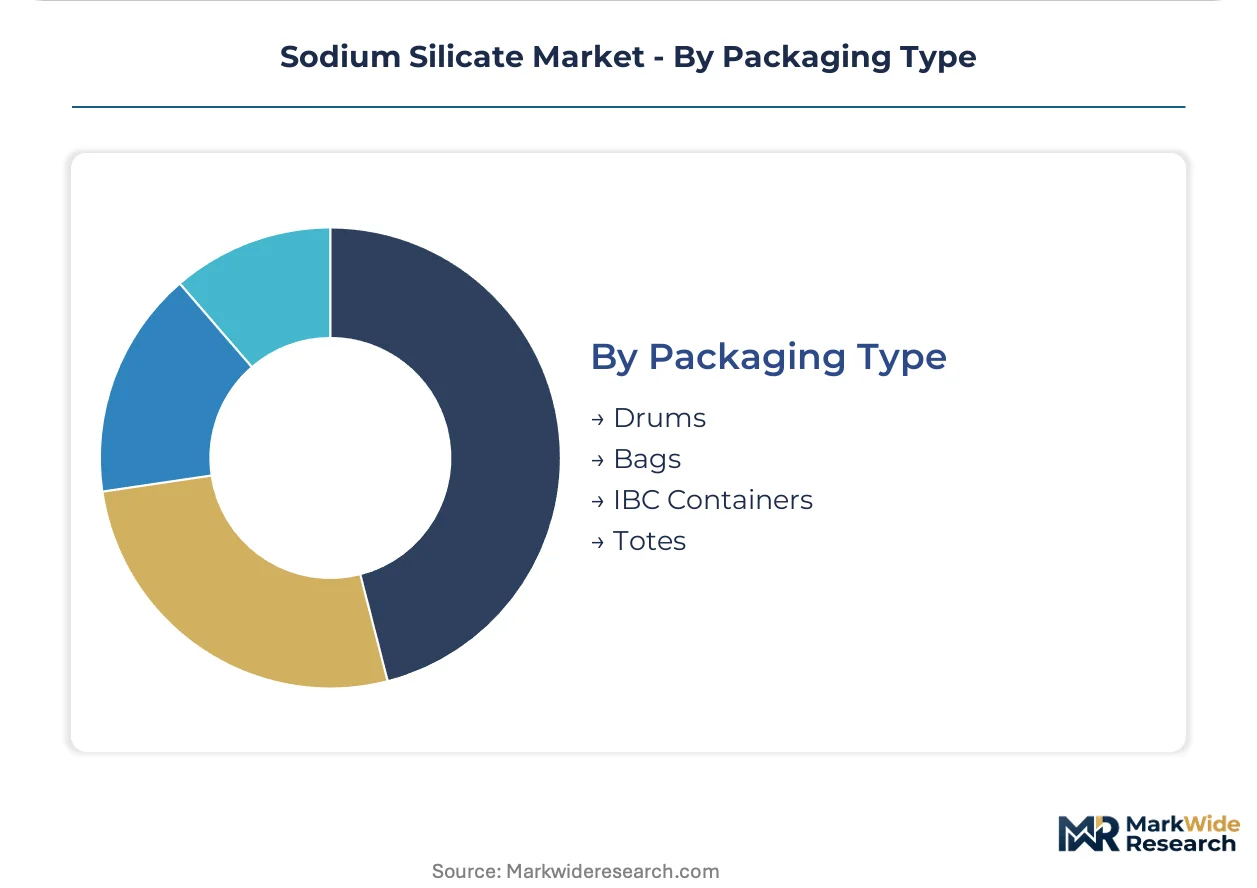
- Drums:Standard 200-liter steel containers serve mid-volume detergent compounders and textile processors with established material handling infrastructure.
- Bags:Multi-wall paper or woven polypropylene packaging for solid silicate pearls and powders enables palletized shipment to remote construction sites.
- IBC Containers:Intermediate bulk containers with integrated dispensing systems support continuous manufacturing lines in high-volume detergent and paper mills.
- Totes:Returnable and disposable bulk bins offer flexible volume positioning for regional blending operations and seasonal demand fluctuations.
IBC containers dominate continuous-process integration. Totes is where flexible procurement patterns concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement power tilts toward detergent compounders in India and Southeast Asia, while European buyers absorb REACH compliance premiums that North American purchasers largely avoid.
United States
EPA effluent standards on mercury residuals are compelling detergent compounders to specify certified low-mercury grades from integrated producers with captive purification capacity. PQ Corporation leverages captive alkali production to sustain margin control across North American distribution channels. The Gulf Coast petrochemical corridor hosts concentrated silicate furnace capacity serving detergent and oilfield applications.
Germany
REACH registration requirements for imports above one tonne annually are fragmenting supplier bases serving European industrial coatings channels toward dossier-complete registrants. Evonik Industries AG competes on technical service intensity in these same coatings channels. The Rhine-Ruhr industrial basin maintains legacy silicate production infrastructure integrated with downstream detergent and textile chemical manufacturing.
China
MEE enforcement of industrial emissions standards under dual carbon goals is shuttering inefficient furnaces, creating import substitution openings for compliant foreign suppliers. GB standards on industrial chemical purity create layered compliance thresholds for multinational suppliers seeking market access. The Yangtze River Delta concentrates glass and ceramics manufacturing that consumes specification-grade silicate for precision applications.
India
The PLI scheme for chemicals is attracting greenfield sodium silicate capacity to serve construction and detergent demand from rapid urbanization. Direct supply contracting between silicate producers and detergent compounders is compressing traditional chemical distributor margins in high-volume liquid grades. Maharashtra and Gujarat host expanding precast concrete production that absorbs construction-grade silicate for cement admixture applications.
Japan
Tokuyama Corporation anchors its position through specialized high-purity grades for electronics applications including semiconductor wafer polishing and display glass manufacturing. METI industrial standards on chemical purity support premium positioning for domestic producers serving precision manufacturing sectors. The Osaka-Kobe industrial corridor maintains concentrated demand for specification-grade silicate in electronics and specialty coatings.
Sodium Silicate Market Vendor Landscape
Integrated alkali-silicate producers and specialized high-purity specialists split the market between volume efficiency and technical premium capture. The vendor base concentrates around furnace operators with captive feedstock supply and compounders with direct procurement relationships. Three archetypes dominate: backward-integrated chemical conglomerates, regional furnace operators with soda ash partnerships, and electronics-grade purification specialists. Capacity expansion in India and Southeast Asia and membrane filtration technology licensing represent the dominant competitive moves reshaping positioning.
Among integrated chemical conglomerates, BASF SE and Evonik Industries AG occupy positions defined by REACH dossier completeness and technical service infrastructure. PQ Corporation exemplifies the North American integrated archetype with captive alkali production. Tokuyama Corporation represents the high-purity specialist tier serving electronics applications with ultra-low impurity grades.
| Leading Market Players |
|---|
| PQ Corporation |
| Qemetica |
| Nippon Chemical Industrial Co., Ltd. |
| Occidental Petroleum Corporation |
| Tokuyama Corporation |
| Evonik Industries AG |
| BASF SE |
| Fuji Chemical Co., Ltd. |
| IQE Group |
| Others |
Supply Flow & Price Mechanics
Soda ash price volatility from Solvay process energy economics and natural trona mining disruptions compresses margin buffers across furnace operators while simultaneously widening spreads between captive-alkali integrated producers and hydrothermal competitors. This feedstock instability dictates both the premium commanded by backward-integrated suppliers and the geographic clustering of cost-competitive capacity.
Pricing Analysis
Configured-to-order pricing for electronics-grade high-purity silicate commands substantial premiums over standard detergent-grade liquid contracts. Contract-based long-term offtake agreements with indexed soda ash adjustments dominate volume procurement, while spot purchases concentrate among smaller compounders lacking scale for direct producer relationships. Price differentiation hinges on mercury certification grade and volume scale, with EPA effluent compliance costs intensifying pricing pressure on trona-based producers. Detergent compounders exhibit highest price sensitivity due to phosphate-free formulation margin compression, whereas semiconductor manufacturers absorb premiums for ultra-low impurity specifications.
Supply Chain Analysis
Tariff exposure between China and downstream Asian markets dominates supply chain risk calculus for furnace operators. Production concentrates in China, India, and the United States, with the Yangtze River Delta and Gulf Coast petrochemical corridor anchoring integrated capacity. Raw material dependencies rest on soda ash from Wyoming trona deposits and high-purity silica sand from regional mining operations. Single-source vulnerability permeates the alkali feedstock layer where trona mining disruptions transmit directly to silicate economics. Distribution runs through direct supply contracting between producers and large-volume detergent compounders, compressing traditional chemical distributor roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phosphate-free detergent mandates across emerging economies signal early-cycle expansion with penetration tailwinds from regulatory-driven formulation switches. Construction-grade demand from India's urban infrastructure build-out compounds this adoption momentum.
For Market Incumbents: Pre-empt membrane filtration technology licensing to hydrothermal competitors lacking captive purification capacity. Secure long-term soda ash offtake agreements with Wyoming trona miners to defend margin position against feedstock volatility. Invest in REACH dossier completeness for European industrial coatings channels before registration deadlines fragment supplier bases toward dossier-complete registrants.
For New Entrants and Emerging Players: African construction corridors exhibit acute underpenetration where solid silicate freight economics favor regional blending facility investments. Target cement admixture direct relationships with precast concrete producers in Maharashtra and Gujarat bypassing established construction chemical distributors. Pursue electronics-grade purification partnerships with Japanese precision manufacturing clusters as the most penetrable premium tier.
For Investors and Strategic Acquirers: The market sits at an early expansion phase that favors integrated alkali-silicate producers with captive feedstock supply. Long-term viability over the next decade hinges on furnace operator skill scarcity and regulatory compliance infrastructure rather than commodity scale alone. Monitor EPA enforcement intensity on mercury residuals as the critical inflection signal for premium grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkali Feedstock | PQ Corporation's captive trona mining insulates margin from Solvay process volatility. |
| Membrane Filtration Technology Licensing | Mercury removal capabilities enable integrated producers to defend premium positioning against hydrothermal competitors. |
| Electronics-Grade Purification Capacity | Tokuyama Corporation's ultra-low impurity grades command technical premiums from semiconductor wafer polishing demand. |
| Direct Supply Contracting Expansion | Indian detergent compounders extract price concessions through multi-year offtake guarantees with indexed soda ash adjustments. |
| Greenfield Capacity in PLI-Supported Zones | India's production-linked incentives attract construction-grade silicate investment to serve rapid urbanization demand. |
Methodological Framework
Operator-level perspectives from furnace plant managers, detergent procurement leads, construction chemical distributors, and electronics-grade technical directors anchored the qualitative base. Primary interviews across these stakeholder categories combined with secondary validation from customs trade data, ACC industry reports, SEC 10-K filings, and BIS certification databases. Bottom-up demand modeling triangulated against top-down production capacity assessments to ensure analytical consistency.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning physical form, end-use industry, application channel, and regional production hub. CAGRs derived from installed base growth rates, replacement demand patterns, and penetration assumptions for phosphate-free detergent formulations. Forecast inputs incorporated soda ash price trajectory assumptions and regulatory enforcement intensity variations across EPA, REACH, and MEE jurisdictions.
Macroeconomic conditions sit as an overlay; deviation in energy prices, construction activity indices, or detergent consumption patterns would shift the trajectory. Forecasts reflect documented assumptions on furnace capacity utilization and regulatory implementation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Furfural Derivatives Market
Bulk Chemicals
North America Lime Market
Bulk Chemicals
Magnesium Sulfate Market
Bulk Chemicals
Ammonium Carbonate Market
Bulk Chemicals
Diisopropylbenzene Market
Bulk Chemicals
Barite Market
Bulk Chemicals
Propionic Acid Market
Bulk Chemicals
Global Acrylic Esters Market
Bulk Chemicals
Hydrated Lime Market
Bulk Chemicals
Saudi Arabia Sodium Thiosulphate Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
DL-Methionine Market
Bulk Chemicals
Phenylalanine Market
Bulk Chemicals
Global Sodium Borohydride Market
Bulk Chemicals
Cresylic Acid Market
Bulk Chemicals
Bromine Market