
 Quad-Flat-No-Lead Packaging (QFN) Market | 2026-2036
Quad-Flat-No-Lead Packaging (QFN) Market Size, Share, and Industry Trends Forecast 2026-2036
Quad-Flat-No-Lead Packaging (QFN) Market Analytics
Die-shrink roadmaps and heterogeneous integration is reshaping how semiconductor packages are architected for space-constrained applications. ASE Technology Holding leverages its massive OSAT footprint to sustain wafer-level packaging dominance across advanced nodes. Amkor Technology anchors North American supply security through diversified factory locations in Portugal and the Philippines. JCET Group competes aggressively on cost-engineered standard QFN volumes for commodity consumer chips.
Quad-Flat-No-Lead Packaging is a surface-mount integrated circuit package format characterized by perimeter I/O pads on the package bottom rather than extending leads, typically manufactured with copper lead frames and epoxy-molded bodies measuring under 1 mm in profile height, designed to maximize board-area efficiency and thermal dissipation in high-pin-count applications. Heat Sink QFN variants command premium positioning where power amplifiers and motor controllers demand superior thermal pathways, while RF QFN specializes in mmWave and sub-6 GHz front-end modules where signal integrity at 40+ GHz dictates package geometry. Standard QFN occupies the high-volume, margin-compressed tier serving consumer electronics and legacy industrial controllers where cost-per-unit dominates procurement decisions.
China's MIIT enforces GB standards for lead-free alloy compositions and dual carbon goals that constrain smelter energy intensity, while Taiwan's EPA implements hazardous substance tracking that elevates compliance costs for cross-strait material flows. The EU REACH regulation and RoHS directives restrict specific flame retardants and heavy metals in molded compounds, forcing material suppliers to qualify halogen-free epoxy alternatives. Stakeholders must monitor how regional carbon-border adjustments and semiconductor subsidy clawback provisions reshape total cost of ownership for QFN manufacturing location decisions.
Market Dynamics
Heterogeneous integration roadmaps and die-shrink imperatives are compressing package form factors while multiplying thermal and electrical performance requirements. This structural tension between miniaturization and power density is forcing substrate and molding compound suppliers to qualify new material systems at unprecedented velocity.
Growth Catalysts
- Electric Vehicle Power Electronics:Battery management systems and motor inverters require compact, thermally efficient packages that QFN formats deliver at scale.
- China's Dual Carbon Mandates:MIIT energy-intensity targets for smelters are accelerating lead-free alloy transitions that favor advanced copper-leadframe QFN architectures.
- mmWave 5G Deployment:Sub-6 GHz and 40+ GHz front-end modules demand RF-optimized QFN geometries with precise signal-integrity engineering.
Market Restraints
- Epoxy Molding Compound Supply Concentration:Halogen-free compound qualification cycles stretch 18-24 months, with resin supply concentrated among Japanese and Korean chemical conglomerates.
- Leadframe Cost Volatility:Copper and silver spot-price swings compress margin predictability for high-volume standard QFN production.
- Wafer-Level Fan-Out Substitution:Advanced packaging formats for premium mobile processors are capturing socket opportunities above 500 I/O counts.
Strategic Opportunities
- Automotive Functional Safety Certification:ASIL-D compliance pathways for QFN-based motor controllers and battery sensors open premium pricing tiers.
- India Electronics Manufacturing:PLI scheme incentives for semiconductor assembly and testing are attracting OSAT capacity investments.
- Silicon Carbide Power Module Convergence:Wide-bandgap die integration with thermally enhanced Heat Sink QFN packages enables traction inverter penetration.
Industry Challenges
- Warpage Control at Thin Profiles:Sub-0.5 mm package heights introduce board-level assembly yield degradation that demands refined mold compound rheology.
- Cross-Strait Material Flow Documentation:Taiwan EPA hazardous substance tracking and China's GB standard alignment create compliance latency for multi-site supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quad-Flat-No-Lead Packaging (QFN) Market |
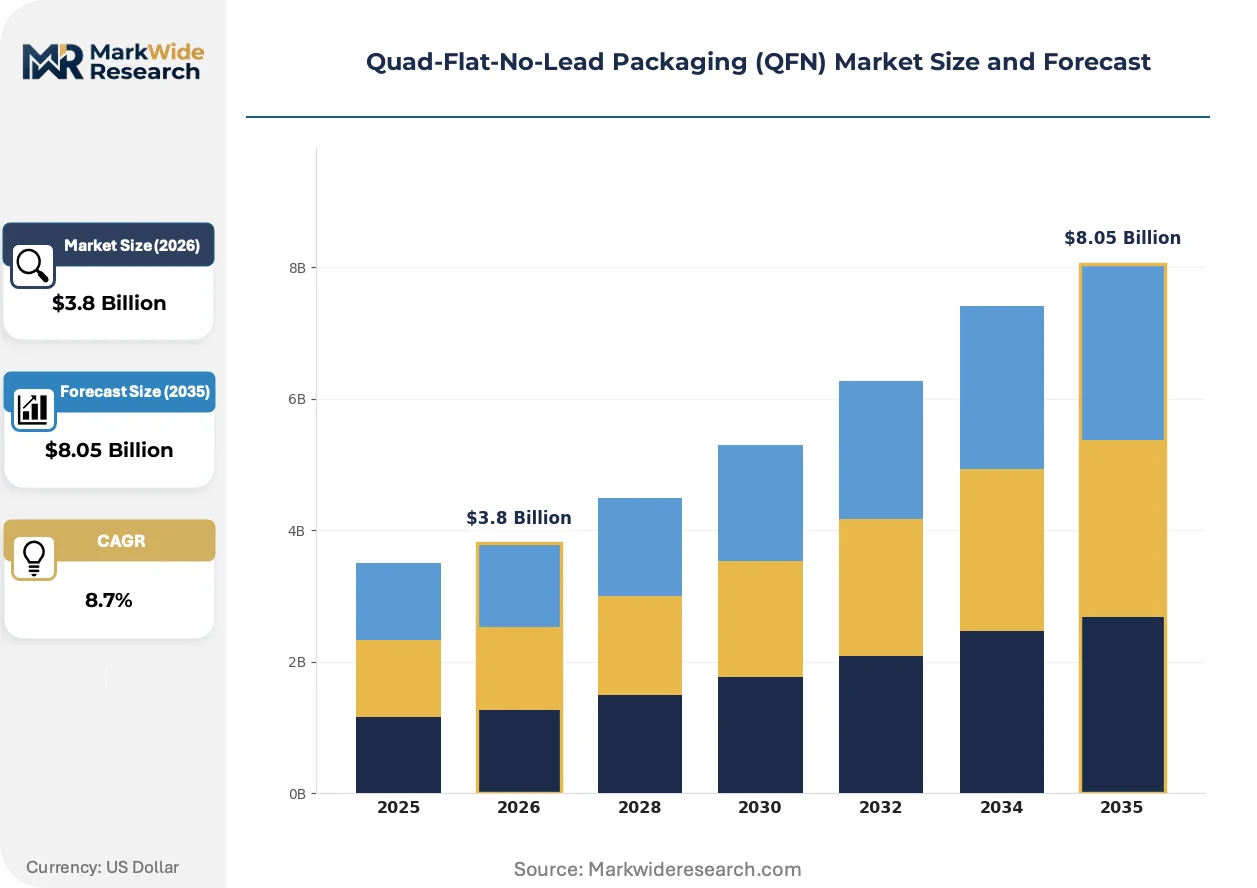
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard QFN, Heat Sink QFN, RF QFN, Thermal Pad QFN Material: Epoxy, Polyimide, Silicone, Lead-free Alloy End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Manufacturing Stage: Die Attach, Wire Bonding, Encapsulation, Testing |
| Companies Covered | JCET Group, Powertech Technology, Amkor Technology, Tianshui Huatian Technology, Siliconware Precision Industries, ASE Technology Holding, NXP Semiconductors, DISCO, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quad-Flat-No-Lead Packaging (QFN) Market Evolving Landscape
Active packaging architectures are displacing passive thermal management as power density requirements outstrip conventional heat-spreader limits. Material science breakthroughs and regulatory chemistry restrictions are simultaneously constraining and enabling next-generation QFN development.
Embedded-die QFN configurations with pre-applied thermal interface materials are rendering obsolete traditional discrete heat-spreader attachment processes. Automotive tier-1 suppliers adopting these architectures for 800V inverter modules compress assembly steps while improving thermal cycling reliability. The shift eliminates secondary operations that previously added 15-20% to total package cost structures.
EU REACH Annex XVII restrictions on halogenated flame retardants in molded compounds are forcing epoxy suppliers to qualify phosphorus-nitrogen hybrid chemistries. The regulatory compression extends qualification timelines but creates differentiation for early movers with certified halogen-free portfolios. Consumer electronics OEMs with EU market exposure are now specifying RoHS-and-REACH-compliant QFN sourcing as a procurement gate.
Consolidated vendor-managed inventory programs are replacing spot-market leadframe procurement for high-volume consumer chip customers. Taiwan-based OSATs and their Chinese counterparts are offering bonded inventory arrangements that transfer price-risk to packaging houses. This pattern concentrates most visibly in smartphone SoC and TWS earbud controller supply chains where annual volume commitments exceed 50 million units.
Quad-Flat-No-Lead Packaging (QFN) Market Segmentation
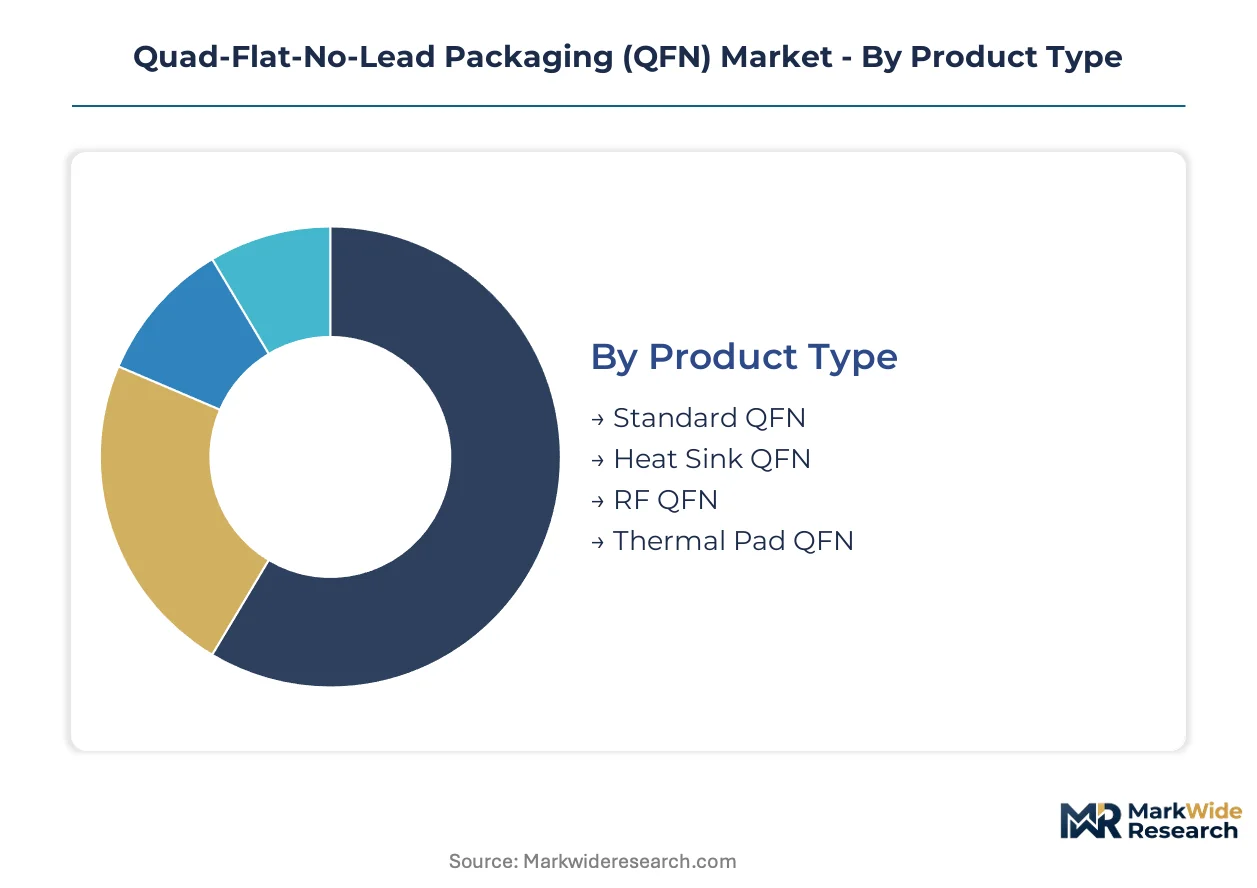
QFN packaging architectures fragment across thermal performance tiers, material compliance regimes, and end-use reliability requirements. Each segmentation axis reveals distinct margin structures and qualification barriers that reshape supplier competitiveness.
Product Type:
Mature formats dominate high-volume consumer sockets while emerging variants capture power and RF applications demanding specialized thermal or signal-integrity engineering.
- Standard QFN:Copper leadframe construction with perimeter I/O pads and molded epoxy bodies under 1 mm height serves cost-sensitive consumer controllers and legacy industrial chips. Procurement concentrates in mainland China and Taiwan OSAT clusters where 50-million-unit annual commitments trigger bonded inventory arrangements.
- Heat Sink QFN:Integrated copper or aluminum thermal slug architectures deliver junction-to-ambient thermal resistance below 15°C/W for motor inverters and battery management systems. Electric vehicle power electronics in Germany and Japan anchor demand as 800V traction inverter designs proliferate.
- RF QFN:Optimized for mmWave and sub-6 GHz front-end modules with controlled impedance routing and minimized parasitic inductance.
- Thermal Pad QFN:Exposed die-attach paddle configurations provide intermediate thermal performance for mid-power industrial motor drives.
Standard QFN retains volume leadership; Heat Sink QFN holds the steepest expansion curve.
Material:
Regulatory chemistry restrictions and thermal performance requirements split procurement between legacy halogenated systems and next-generation compliant formulations.
- Epoxy:Halogen-free phosphorus-nitrogen hybrid molding compounds now dominate EU-bound production as REACH Annex XVII restrictions eliminate brominated flame retardants. Japanese and Korean chemical conglomerates control resin supply with 18-24 month qualification cycles that constrain OSAT material switching.
- Lead-free Alloy:SAC305 and related tin-silver-copper compositions satisfy China's MIIT GB standards and EU RoHS directives. Smelter energy-intensity targets under dual carbon mandates favor advanced copper-leadframe architectures with reduced silver content.
- Polyimide:High-temperature substrate material for automotive under-hood applications exceeding 150°C ambient.
- Silicone:Flexible encapsulant for stress-sensitive large-die configurations in industrial power modules.
Epoxy formulations command the broadest application base; lead-free alloy transitions are expanding most quickly under regulatory pressure.
End User:
Reliability certification tiers and volume scale separate automotive premium sockets from consumer commodity procurement patterns.
- Automotive:ASIL-D functional safety compliance for battery sensors and motor controllers opens premium pricing tiers unavailable to consumer-grade suppliers. Germany's KBA type-approval requirements and Japan's METI safety standards drive qualification investment that excludes mid-tier OSATs.
- Consumer Electronics:Smartphone SoC and TWS earbud controller demand concentrates in Taiwan and mainland China manufacturing clusters where vendor-managed inventory programs transfer copper price risk to packaging houses.
- Telecommunications:5G baseband and mmWave infrastructure modules require RF-optimized QFN geometries with 40+ GHz signal integrity.
- Industrial Equipment:Legacy controller sockets prioritize cost-per-unit over thermal performance in factory automation and building management systems.
Consumer Electronics maintains shipment dominance; Automotive delivers the fastest margin expansion trajectory.
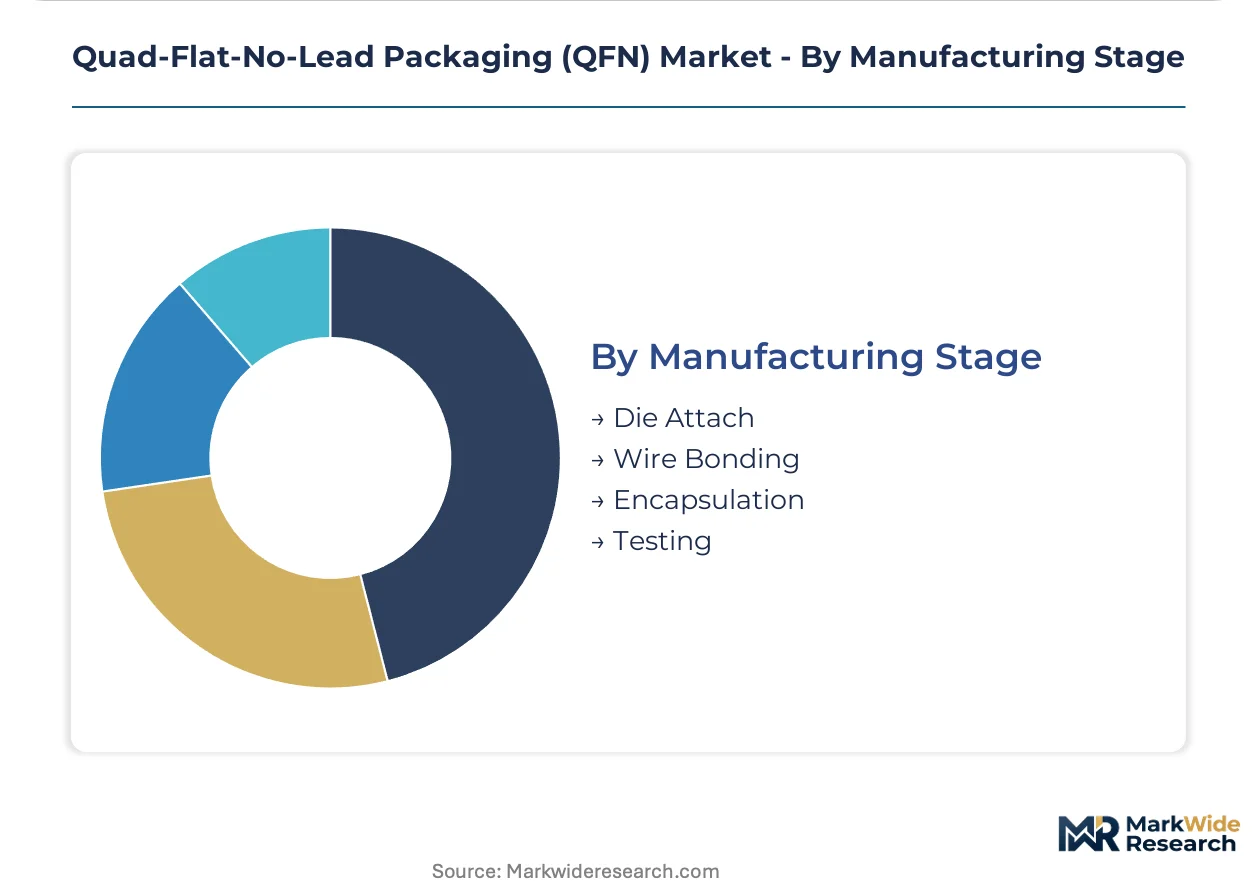
Manufacturing Stage:
Process automation intensity and yield sensitivity differentiate high-volume wire bonding from precision-critical test operations.
- Encapsulation:Transfer molding with epoxy compound rheology control determines warpage performance at sub-0.5 mm package heights. Mold flash and void management directly impacts board-level assembly yield for thin-profile consumer chips.
- Testing:Final electrical test and burn-in protocols for automotive-grade devices require traceable data packages supporting ASIL-D failure analysis. Taiwan EPA hazardous substance tracking adds documentation latency for cross-strait material flows.
- Die Attach:Silver-filled epoxy or sintered paste attachment establishes thermal and electrical connectivity to the leadframe paddle.
- Wire Bonding:Gold or copper ball-wedge interconnect formation creates electrical pathways from die pads to leadframe fingers.
Encapsulation governs final package reliability; Testing captures the steepest automation investment curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan exports packaged semiconductor components to Germany's automotive electronics suppliers and China's consumer device manufacturers, creating a dual-hemisphere trade corridor that concentrates QFN procurement decisions in East Asian manufacturing clusters.
Taiwan
Electric vehicle inverters and smartphone baseband processors drive die-attach and wire-bonding demand. Taiwan's EPA hazardous substance tracking elevates documentation costs for cross-strait material flows. Kaohsiung's southern science park anchors ASE Technology Holding and Siliconware Precision Industries capacity expansion for automotive-grade QFN volumes.
China
Battery management systems for domestic EV brands and TWS earbud controllers absorb standard QFN output at scale. MIIT dual carbon goals and GB standards for lead-free alloys constrain smelter energy intensity. Jiangsu and Zhejiang provinces host JCET Group and Tianshui Huatian Technology facilities where OSAT consolidation accelerates.
Germany
800V traction inverters and motor control modules require Heat Sink QFN thermal performance. KBA type-approval mandates ASIL-D functional safety certification for automotive socket qualification. Saxony's semiconductor corridor and Bavaria's automotive electronics clusters concentrate demand for thermally enhanced packages.
United States
5G mmWave infrastructure and defense-qualified power amplifiers specify RF-optimized QFN geometries. NHTSA vehicle safety standards and EPA chemical reporting shape material selection for automotive and industrial applications. Texas Instruments anchors domestic design activity while Arizona's emerging fab cluster pulls packaging demand westward.
South Korea
Memory module controllers and smartphone AP subsystems sustain high-volume standard QFN procurement. MFDS chemical safety assessments and METI-aligned carbon disclosure requirements affect mold compound qualification. Gyeonggi Province's semiconductor belt around Seoul concentrates OSAT capacity serving Samsung and SK hynix supply chains.
Quad-Flat-No-Lead Packaging (QFN) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven OSATs dominate high-volume consumer sockets and thermally focused specialists capture automotive premium tiers. Taiwan-based incumbents leverage bonded inventory arrangements to transfer copper price risk downstream. Three archetypes define competitive positioning: diversified global OSATs with multi-continent factory footprints, China-focused cost-engineered volume players, and technology-anchored IDMs with captive packaging operations. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers secure long-term commitments from smartphone and EV tier-1 customers.
Among Taiwan-based OSATs, ASE Technology Holding and Siliconware Precision Industries exemplify the diversified global archetype with manufacturing presence spanning multiple continents. JCET Group represents the China-focused volume-engineering tier competing aggressively on standard QFN unit economics. Amkor Technology anchors the North American supply security vector through factory diversification in Portugal and the Philippines. These three entities collectively illustrate how geographic footprint strategy separates premium-tier positioning from commodity procurement relationships.
| Leading Market Players |
|---|
| JCET Group |
| Powertech Technology |
| Amkor Technology |
| Tianshui Huatian Technology |
| Siliconware Precision Industries |
| ASE Technology Holding |
| NXP Semiconductors |
| DISCO |
| Texas Instruments |
| Others |
Value Network & Pricing Analysis
Kaohsiung's southern science park anchors the densest concentration of OSAT capacity for automotive-grade QFN volumes, and this geographic clustering transfers copper price volatility downstream through bonded inventory arrangements that compress margin predictability for packaging houses serving high-volume consumer chip customers.
Pricing Analysis
Heat Sink QFN variants for 800V traction inverters command substantial premiums over standard QFN formats for TWS earbud controllers, with three-tier pricing structure across premium, standard, and economy levels separating ASIL-D certified automotive sockets from consumer-grade procurement. Price differentiation hinges on thermal performance certification and annual volume scale, with smartphone SoC customers above 50 million units extracting the most favorable terms. Pricing pressure stems from wafer-level fan-out substitution above 500 I/O counts. Consumer electronics OEMs exhibit highest price sensitivity, while automotive tier-1 suppliers prioritize thermal reliability over unit cost.
Supply Chain Analysis
Copper leadframe feedstock draws from Japanese and Korean chemical conglomerates controlling halogen-free epoxy resin supply, with Taiwan, mainland China, and South Korea concentrating 80% of global OSAT capacity for QFN assembly. Raw material dependencies center on SAC305 lead-free alloys, phosphorus-nitrogen hybrid molding compounds, and silver-filled die-attach pastes. Single-source vulnerability pervades halogen-free compound qualification cycles stretching 18-24 months. Distribution runs through vendor-managed inventory programs replacing spot-market procurement for annual commitments exceeding 50 million units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified mold compound rheology expertise sits with fewer than six chemical suppliers globally, creating acute bottlenecks for sub-0.5 mm profile QFN development where warpage control determines board-level assembly yield.
For Market Incumbents: Harden automotive certification moats by securing ASIL-D compliance pathways for battery management system QFN sockets before wafer-level fan-out formats penetrate below 500 I/O thresholds. Expand encapsulation capacity in Portugal and the Philippines to diversify beyond Taiwan strait exposure. Vertical integration into halogen-free epoxy formulation hedges Japanese chemical conglomerate supply concentration. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme semiconductor assembly incentives before incumbent OSATs lock in smartphone and EV tier-1 commitments. Target Heat Sink QFN for silicon carbide power modules where thermal performance requirements outstrip standard package capabilities. Lead with embedded-die configurations featuring pre-applied thermal interface materials to eliminate secondary heat-spreader attachment operations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors OSATs with captive halogen-free compound qualification pipelines and automotive functional safety certifications rather than pure-play consumer volume operators. Long-term viability rests on heterogeneous integration roadmaps converging with wide-bandgap die attachment expertise. Watch for MIIT dual carbon enforcement intensity as a signal for lead-free alloy transition acceleration that favors advanced copper-leadframe architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Functional Safety Certification | ASIL-D compliance opens premium pricing tiers for battery sensor QFN sockets in Germany's KBA-regulated supply chains. |
| Halogen-Free Compound Qualification | REACH Annex XVII alignment creates differentiation for early movers with certified phosphorus-nitrogen hybrid epoxy portfolios. |
| India OSAT Capacity Investment | PLI scheme incentives attract assembly and testing facilities serving smartphone and EV controller demand migration. |
| Embedded-Die Thermal Architecture | Pre-applied TIM configurations compress assembly steps for 800V inverter modules while improving cycling reliability. |
| Cross-Strait Material Flow Documentation | Taiwan EPA hazardous substance tracking compliance reduces latency for multi-site supply chains serving EU-bound production. |
Research Methodology
A standing panel of OSAT operations directors, epoxy compound R&D leads, automotive tier-1 procurement managers, and Taiwan EPA compliance officers provided ongoing calibration across primary interview rounds. Secondary validation drew from MIIT GB standard filings, EU REACH Annex XVII restriction updates, SEC 10-K disclosures from listed packaging houses, and customs trade data for leadframe alloy flows. Bottom-up die-attach and wire-bonding capacity estimates triangulated against top-down EV inverter and smartphone shipment projections.
Scenario bracketing anchored the analytical framework across conservative, baseline, and accelerated technology adoption pathways throughout the forecast period. Segmentation dimensions modeled include product type tier, material compliance regime, end-use reliability certification, and manufacturing stage automation intensity. CAGRs derived from installed base growth rates for electric vehicle power electronics and mmWave 5G infrastructure deployment. Industry-specific inputs encompassed smelter energy-intensity targets under China's dual carbon mandates and KBA type-approval timelines for ASIL-D socket qualification.
Sensitivities concentrate around halogen-free compound qualification delays, copper spot-price volatility, and cross-strait logistics disruptions affecting mold compound resin flows. Forecasts reflect assumptions regarding MIIT enforcement consistency and EU carbon-border adjustment implementation. Cross-checking against IHS Markit semiconductor packaging capacity databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
System-On-Package Market
Semiconductor Packaging
Memory Packaging Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
3D Semiconductor Packaging Market
Semiconductor Packaging
Asia-Pacific Quad-Flat-No-Lead Packaging Market
Semiconductor Packaging
Global Semiconductor Packaging and Assembly Equipment Market
Semiconductor Packaging
2.5D IC Packaging Market
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market
Semiconductor Packaging
Semiconductor Solder Flux Market
Semiconductor Packaging
Global Bare Die Shipping and Handling and Processing and Storage Market
Semiconductor Packaging
Semiconductor and IC Packaging Materials Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Test Services (OSAT) Market
Semiconductor Packaging
Microtube Box Market
Semiconductor Packaging
Embedded Die Packaging Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Testing Market
Semiconductor Packaging
Global MEMS Packaging Market