
 3D Semiconductor Packaging Market | 2026-2036
3D Semiconductor Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
3D Semiconductor Packaging Market Analysis
Advanced packaging yield engineering is fragmenting between captive foundry operations and merchant outsourced semiconductor assembly and test providers. Taiwan Semiconductor Manufacturing Company dominates leading-edge 3D integration with in-house CoWoS and SoIC roadmaps. ASE Technology Holding competes aggressively in fan-out and system-in-package assembly for mobile and automotive sockets. Intel Corporation anchors U.S.-based advanced packaging capacity with Foveros and EMIB process development in Arizona and New Mexico.
3D semiconductor packaging stacks and interconnects multiple die layers vertically using through-silicon vias, microbumps, or hybrid bonding to achieve higher bandwidth density and lower power consumption than planar scaling alone. Through-silicon via technology leads in high-performance computing and AI accelerator applications where memory-processor bandwidth limits system performance. Fan-out wafer-level packaging extends fastest in mobile device and IoT device segments because substrate cost reduction and form-factor flexibility outweigh the premium for vertical stacking. Flip chip remains the volume workhorse across computing devices and telecommunications infrastructure where thermal management requirements and established supply chains sustain merchant demand.
The U.S. Department of Commerce CHIPS program office, Taiwan's Industrial Development Bureau, and South Korea's Ministry of Trade, Industry and Energy each condition subsidy disbursements on local advanced packaging investment, reshaping where capacity additions materialize. REACH and RoHS frameworks in Europe restrict certain materials in interconnect metallurgy and underfill compounds, forcing reformulation of bonding pastes and dielectric layers. Stakeholders must track which regulatory jurisdiction captures the next tranche of packaging-specific incentives, because equipment procurement lead times and cleanroom construction cycles lock location decisions years before volume production begins.
Market Dynamics
Advanced packaging yield engineering is fragmenting between captive foundry operations and merchant outsourced semiconductor assembly and test providers. Taiwan Semiconductor Manufacturing Company dominates leading-edge 3D integration with in-house CoWoS and SoIC roadmaps. ASE Technology Holding competes aggressively in fan-out and system-in-package assembly for mobile and automotive sockets. Intel Corporation anchors U.S.-based advanced packaging capacity with Foveros and EMIB process development in Arizona and New Mexico.
Growth Catalysts
- High-performance computing clusters:Data center AI accelerators are absorbing advanced packaging capacity at an accelerating clip, driving demand for through-silicon via interconnect density.
- CHIPS Act disbursements:The U.S. Department of Commerce conditions subsidy releases on domestic back-end semiconductor manufacturing investment, redirecting capital toward Arizona and New Mexico packaging facilities.
- Hybrid bonding maturation:Copper-to-copper direct bonding is displacing microbump architectures in leading-edge memory-processor stacks, enabling finer pitch interconnects.
Market Restraints
- Equipment procurement lead times:Lithography and bonding tool delivery cycles now extend eighteen to twenty-four months, locking capacity expansion timelines regardless of demand signals.
- Substrate supply concentration:ABF substrate manufacturing concentrates in Taiwan and Japan, creating chokepoint vulnerability for fan-out and 2.5D package ramp.
- REACH material restrictions:ECHA regulations on lead-free solder alternatives and underfill compounds force reformulation cycles that delay product qualification.
Strategic Opportunities
- Automotive system-in-package:Advanced driver-assistance systems and domain controllers are creating new sockets for thermally robust 3D packaging in electric vehicle powertrain electronics.
- India semiconductor ecosystem:The country's PLI scheme for electronics manufacturing is attracting OSAT investment for domestic packaging of imported bare die.
- Photonics-electronics convergence:Co-packaged optics in data centers is opening hybrid integration opportunities combining silicon photonics with CMOS logic stacks.
Industry Challenges
- Thermal-mechanical modeling expertise:Multi-physics simulation of stacked die warpage and stress distribution requires rare cross-disciplinary skill sets spanning materials science and finite element analysis.
- Cleanroom construction cycles:Advanced packaging facilities require ISO Class 5-7 environments with vibration isolation, extending facility commissioning timelines to thirty-six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Semiconductor Packaging Market |
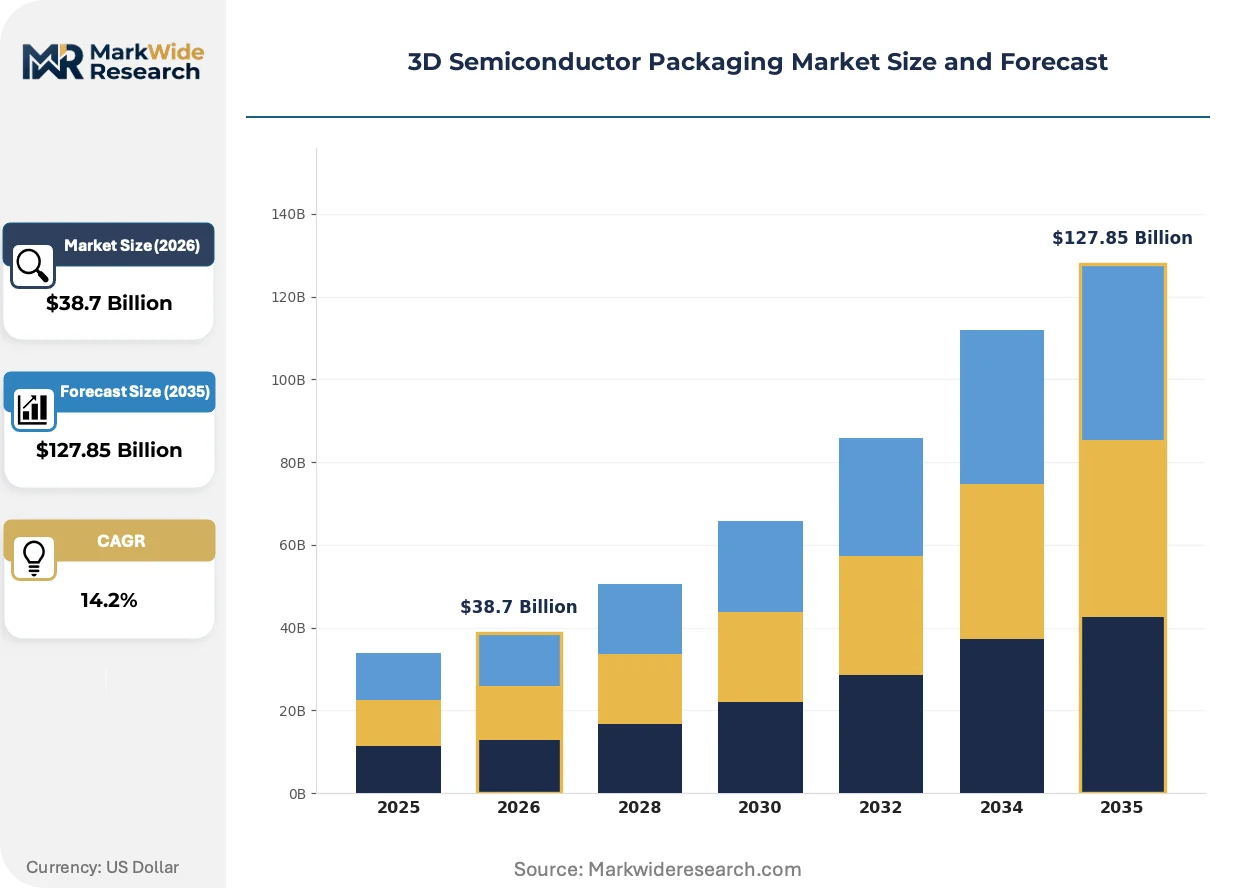
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fan-Out, Through-Silicon Via, Flip Chip, Wafer Level Technology: Integrated Circuit, Optoelectronic, MEMS, RF End User: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Electronics Application: Mobile Devices, Computing Devices, IoT Devices, High-Performance Computing |
| Companies Covered | ASE Technology Holding, Advanced Micro Devices, Taiwan Semiconductor Manufacturing Company, JCET Group, Broadcom, Intel Corporation, Amkor Technology, United Microelectronics Corporation, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Semiconductor Packaging Market Emerging Trajectories
Process roadmaps are compressing the physical gap between memory and logic, reshaping how semiconductor manufacturers architect bandwidth and power efficiency. Three converging developments are redefining competitive positioning.
Hybrid bonding is collapsing the interconnect pitch hierarchy that previously separated wire bond, flip chip, and 3D stacking into distinct cost-performance tiers. AI accelerator designers at NVIDIA and AMD are adopting copper-to-copper bonding for HBM3E stacks, eliminating microbump capacitance penalties. This technology is collapsing the traditional yield-cost tradeoff that constrained high-bandwidth memory adoption to premium compute sockets.
REACH and RoHS frameworks in Europe are forcing reformulation of interconnect metallurgy and dielectric materials across the supply chain. ECHA restrictions on certain brominated flame retardants and lead-free solder alternatives are accelerating qualification of new underfill compounds. Packaging houses serving automotive and industrial segments in Germany and France are responding with dedicated material validation labs to maintain CE marking compliance.
Hyperscale cloud providers are consolidating procurement authority over custom silicon packaging decisions, displacing traditional OEM-driven specifications. Amazon Web Services, Microsoft Azure, and Google Cloud now dictate CoWoS and EMIB requirements directly to foundries and OSATs. This concentration is most visible in Taiwan and the United States, where data center silicon volumes now determine capacity allocation优先级 at leading packaging facilities.
3D Semiconductor Packaging Market Segmentation
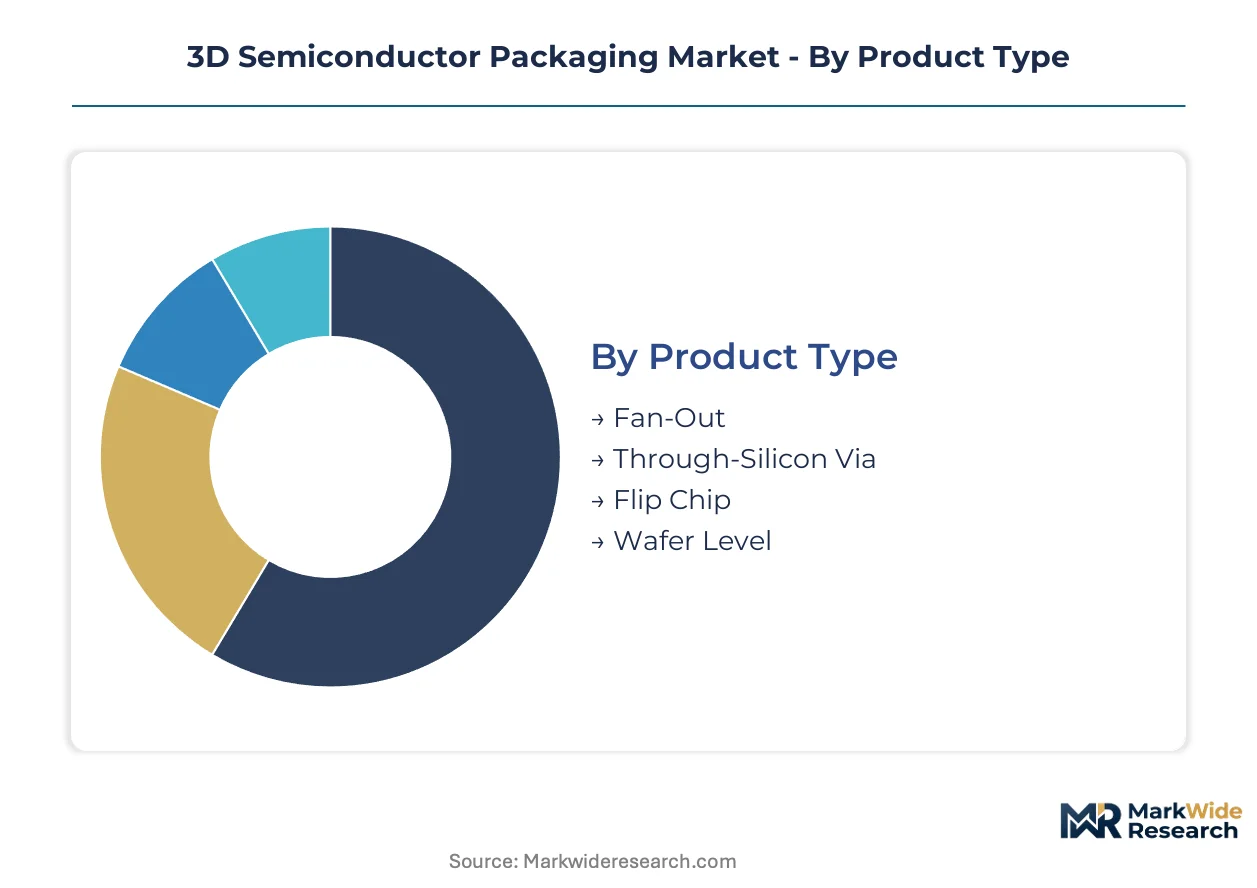
3D semiconductor packaging technology fragments across multiple technical and commercial dimensions, each with distinct equipment requirements, yield profiles, and customer qualification cycles. Understanding these segment boundaries clarifies where capital deployment and competitive positioning concentrate.
Product Type:
Mature processes anchor high-volume production while emerging architectures redefine performance ceilings.
- Through-Silicon Via:Vertical interconnects penetrate silicon substrates to stack die layers, enabling memory-processor bandwidth densities exceeding planar limits. High-performance computing clusters in Taiwan and the United States absorb the bulk of advanced TSV capacity for AI accelerators, constrained by substrate supply concentration and eighteen-month equipment lead times.
- Fan-Out:Redistribution layers extend I/O pads across reconstituted wafer areas, eliminating substrate cost and form-factor constraints of traditional flip chip. Mobile device manufacturers in South Korea and Taiwan drive fastest adoption, prioritizing package thickness reduction and antenna integration flexibility over absolute interconnect density.
- Flip Chip:Solder bump interconnects between die and substrate remain the volume foundation across computing and telecommunications infrastructure where thermal management requirements and established supply chains sustain merchant demand.
- Wafer Level:Die processing completes before singulation, compressing package footprint for space-constrained IoT and wearable applications where cost sensitivity limits vertical stacking adoption.
Flip chip retains volume leadership; fan-out holds the steepest expansion curve.
Technology:
Application requirements dictate which substrate and interconnect technologies dominate each vertical.
- Integrated Circuit:Logic and memory die stacking commands the majority of capital investment, with hybrid bonding displacing microbumps in leading-edge CPU-GPU-memory configurations. NVIDIA and AMD procurement decisions directly shape CoWoS and EMIB capacity allocation at foundries.
- RF:Radio frequency modules for 5G infrastructure and smartphone front-ends integrate filters, switches, and power amplifiers in system-in-package configurations where substrate parasitic control determines performance.
- Optoelectronic:Silicon photonics co-packaging with CMOS logic addresses bandwidth-distance limitations in data center optical interconnects, creating hybrid integration opportunities at the electronics-photonics boundary.
- MEMS:Microelectromechanical systems packaging protects fragile moving structures while maintaining environmental access for pressure sensors, accelerometers, and microphones in automotive and consumer applications.
Integrated circuit technology captures the dominant revenue share; optoelectronic integration is expanding most quickly through data center architecture transitions.
End User:
Customer concentration and qualification rigor create distinct margin and timeline profiles across vertical markets.
- Consumer Electronics:Smartphone and wearable manufacturers prioritize form-factor miniaturization and cost optimization, driving fan-out wafer-level packaging adoption where substrate elimination offsets process complexity premiums.
- Automotive Electronics:Advanced driver-assistance systems and domain controllers demand thermally robust 3D packaging with AEC-Q100 qualification, creating new sockets for system-in-package solutions in electric vehicle powertrain electronics.
- Telecommunications:Base station infrastructure and optical networking equipment sustain flip chip and ceramic substrate demand where reliability requirements and long product lifecycles outweigh packaging cost sensitivity.
- Industrial Electronics:Factory automation and energy management systems require extended temperature range operation, favoring established interconnect technologies with proven field reliability records.
Consumer electronics maintains volume dominance; automotive electronics is gaining share fastest through electrification and autonomy investment cycles.
Application:
Compute intensity and power constraints segment packaging technology selection across device categories.
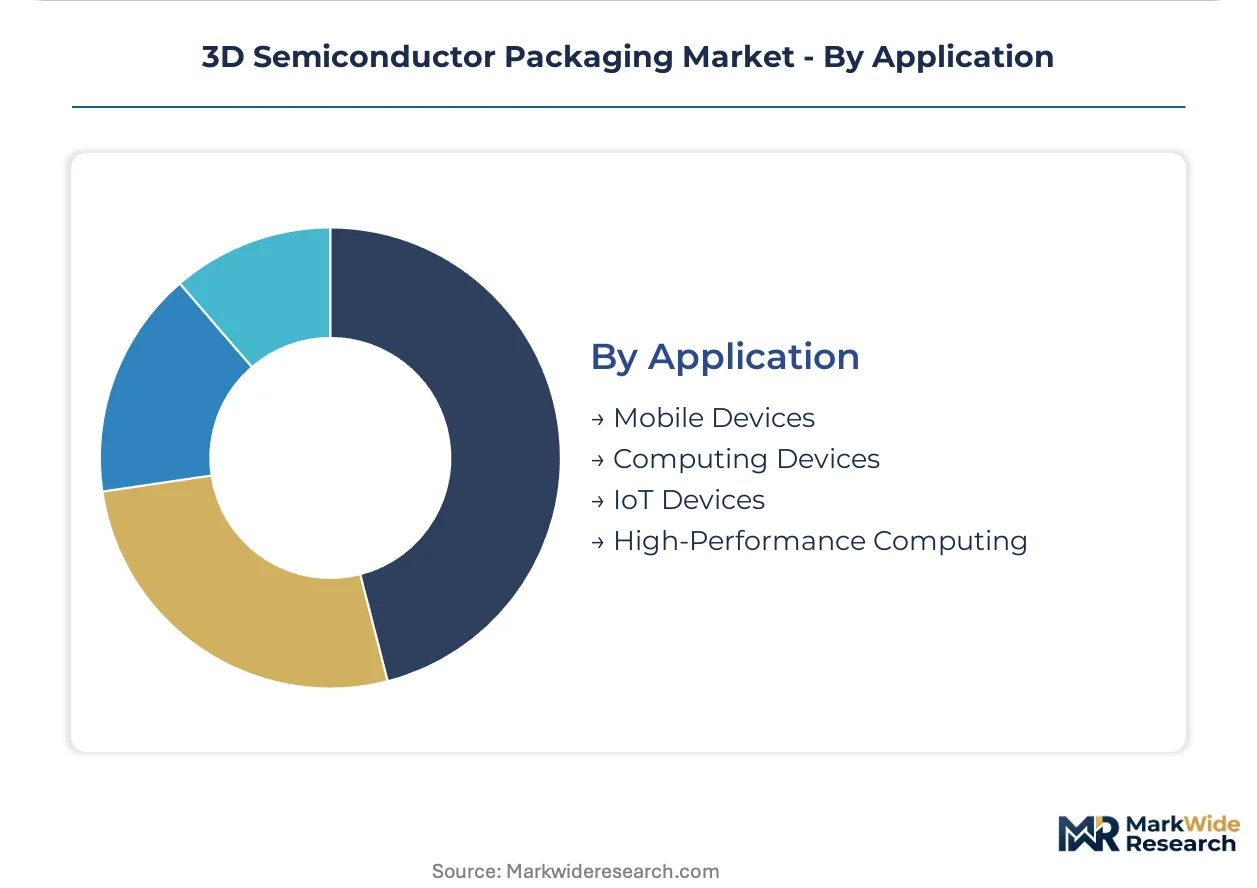
- High-Performance Computing:AI training and inference accelerators absorb leading-edge CoWoS and SoIC capacity, with hyperscale cloud providers consolidating procurement authority over custom silicon packaging decisions.
- Mobile Devices:Smartphone system-in-package integration combines application processors, memory, and RF front-ends within strict thermal and thickness budgets, favoring fan-out and hybrid bonding maturation.
- Computing Devices:Personal computers and enterprise servers balance performance and cost through flip chip and 2.5D interposer solutions where memory bandwidth scaling limits system capability.
- IoT Devices:Sensor nodes and edge endpoints prioritize cost minimization and battery life over interconnect density, sustaining wire bond and wafer-level chip-scale package demand.
High-performance computing commands premium technology adoption; mobile devices sustain the broadest packaging technology diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-performance computing clusters in Taiwan and the United States absorb advanced packaging capacity at divergent rates, while automotive electrification in Germany and consumer electronics manufacturing in South Korea create distinct demand profiles for 3D integration technologies.
United States
Hyperscale cloud providers in Virginia and Oregon dictate CoWoS and EMIB requirements directly to foundries, consolidating procurement authority over custom silicon packaging. The Department of Commerce CHIPS program conditions subsidy disbursements on domestic back-end manufacturing investment, redirecting capital toward Arizona and New Mexico packaging facilities. Intel Corporation anchors advanced packaging capacity with Foveros process development in these states.
Taiwan
AI accelerator designers absorb the bulk of leading-edge 3D integration output from Hsinchu-based facilities, where memory-processor bandwidth limits system performance. The Industrial Development Bureau conditions subsidy releases on local advanced packaging investment, reshaping capacity expansion timelines. Taiwan Semiconductor Manufacturing Company dominates 3D integration with in-house CoWoS and SoIC roadmaps from its Tainan and Taichung complexes.
South Korea
Smartphone manufacturers in Suwon and Pyeongtaek drive fastest fan-out wafer-level packaging adoption, prioritizing package thickness reduction over absolute interconnect density. The Ministry of Trade, Industry and Energy directs subsidy frameworks toward domestic front-end and back-end semiconductor manufacturing. Samsung Electronics operates advanced packaging pilot lines in Hwaseong and Pyeongtaek for mobile and memory applications.
China
Domestic foundries in Shanghai and Beijing expand 2.5D interposer capacity for computing devices and telecommunications infrastructure where established supply chains sustain demand. MIIT standards and dual carbon goals shape equipment procurement and cleanroom energy specifications. JCET Group operates packaging facilities in Jiangsu and Guangdong provinces serving imported bare die assembly.
Germany
Automotive electronics suppliers in Stuttgart and Munich create new sockets for thermally robust system-in-package solutions in electric vehicle powertrain electronics. ECHA REACH restrictions on lead-free solder alternatives and underfill compounds force reformulation cycles that delay product qualification. Packaging houses serving automotive segments operate dedicated material validation labs in Bavaria to maintain CE marking compliance.
3D Semiconductor Packaging Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another, creating a bifurcated structure where leading-edge 3D integration remains captive to integrated device manufacturers while merchant providers dominate high-volume fan-out and flip chip assembly. The vendor base organizes around three strategic archetypes: captive foundry operations with in-house packaging roadmaps, merchant outsourced semiconductor assembly and test providers serving mobile and automotive sockets, and diversified electronics conglomerates with packaging as a vertical component. Dominant competitive moves include capacity expansion in subsidy-conditioned jurisdictions and strategic partnerships between substrate suppliers and packaging houses to secure ABF laminate allocation.
Within the captive foundry tier, Taiwan Semiconductor Manufacturing Company and Intel Corporation exemplify integrated players controlling leading-edge 3D integration roadmaps from wafer fabrication through final assembly. Among merchant providers, ASE Technology Holding occupies a position representing high-volume outsourced assembly and test capacity for mobile and automotive applications. Samsung Electronics sits within the diversified conglomerate archetype, spanning memory fabrication, logic foundry services, and internal packaging capabilities across multiple product verticals.
| Leading Market Players |
|---|
| ASE Technology Holding |
| Advanced Micro Devices |
| Taiwan Semiconductor Manufacturing Company |
| JCET Group |
| Broadcom |
| Intel Corporation |
| Amkor Technology |
| United Microelectronics Corporation |
| Samsung Electronics |
| Others |
Supply Flow & Price Mechanics
ABF substrate supply concentration in Taiwan and Japan determines both pricing tier spreads and supply chain shape, compressing margins for fan-out and 2.5D package ramps while amplifying procurement leverage for integrated device manufacturers with captive laminate allocation.
Pricing Analysis
Long-term offtake agreements dominate high-volume packaging procurement, with hyperscale cloud providers locking CoWoS and EMIB capacity through multi-year contracts while spot-market exposure concentrates among merchant OSATs serving price-sensitive mobile and IoT segments. Price differentiation rests on interconnect density tier and AEC-Q100 automotive certification grade, with thermal-qualified packages commanding substantial premiums over consumer-grade equivalents. Cost compression in standard flip chip assembly is intensifying because Chinese OSATs expand capacity for computing device sockets. Smartphone manufacturers exhibit highest price sensitivity, prioritizing substrate elimination over vertical stacking density.
Supply Chain Analysis
Extended payment terms from foundry customers now stretch to one hundred twenty days for merchant packaging houses, forcing supply-chain finance facilities to bridge working capital gaps for equipment procurement. ABF laminate manufacturing concentrates in Taiwan and Japan, while bonding tool fabrication centers on the United States and Germany. Raw material dependencies include ultra-low-alpha solder spheres, high-purity copper plating chemistries, and brominated epoxy molding compounds. Single-source vulnerability for lithography and hybrid bonding equipment creates chokepoint exposure. Distribution runs through direct foundry relationships for captive capacity and tiered OSAT networks for merchant assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from capital expenditure cyclicality driven by AI accelerator demand absorption, with equipment lead time extension now constraining supply response velocity.
For Market Incumbents: Harden thermal-mechanical modeling capabilities through finite element analysis talent acquisition in Taiwan and Arizona, defending against emerging OSAT entrants from India. Prioritize backward integration into ABF substrate supply through strategic partnerships with Taiwan laminate houses, securing allocation priority before competitor capacity commitments lock.
For New Entrants and Emerging Players: Build out automotive system-in-package qualification infrastructure in Germany and the United States, targeting AEC-Q100-certified sockets for electric vehicle domain controllers where incumbent capacity is stretched. Pursue direct engagement with Tier 1 automotive electronics suppliers rather than foundry-dependent routes to market.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors equipment-light hybrid bonding specialists with process IP. Five-to-ten-year viability hinges on copper-to-copper bonding yield mastery rather than legacy microbump scale. Watch hyperscaler capital expenditure guidance as the inflection indicator for CoWoS demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Process Qualification | Enables copper-to-copper interconnect adoption for HBM3E stacks at NVIDIA and AMD. |
| Automotive Certification Investment | Secures AEC-Q100 qualification for electric vehicle powertrain electronics in Germany. |
| ABF Substrate Partnership | Locks laminate allocation priority from Taiwan suppliers before competitor commitments. |
| India OSAT Facility Establishment | Captures PLI scheme incentives for domestic packaging of imported bare die. |
| Co-Packaged Optics Integration | Addresses data center bandwidth-distance limitations through silicon photonics hybridization. |
Methodological Framework
Initial hypotheses were tested against primary input from packaging process engineers, foundry business development executives, OSAT procurement managers, and automotive electronics qualification leads and refined through secondary validation against SEC 10-K filings, equipment supplier order backlogs, hyperscaler capital expenditure disclosures, and Taiwan Industrial Development Bureau subsidy announcements. Bottom-up segment sizing triangulated against top-down semiconductor assembly value chain estimates.
Demand-supply balance modeling across the projection horizon incorporated packaging technology type, end-use vertical, interconnect density tier, and regional manufacturing cluster segmentation dimensions. CAGRs were derived from equipment installation timelines, cleanroom construction cycles, and substrate supply expansion trajectories rather than extrapolated historical trends. Forecast inputs included bonding tool delivery schedules and CHIPS Act disbursement conditioning requirements.
The forecast holds incumbent behavior within observed patterns; aggressive capacity addition by Chinese state-supported foundries would shift outcomes beyond modeled boundaries. Macroeconomic contraction in data center construction, ECHA REACH restriction expansion, or hybrid bonding yield breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Ceramic IC Packages Market
Semiconductor Packaging
Global Semiconductor Packaging and Assembly Equipment Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Testing Market
Semiconductor Packaging
NOR-Based Multi-Chip Packages Market
Semiconductor Packaging
2.5D and 3D Semiconductor Packaging Market
Semiconductor Packaging
Semiconductor Packaging Market
Semiconductor Packaging
IC Packaging and Testing Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Test Services (OSAT) Market
Semiconductor Packaging
3D IC Packaging Market
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
Memory Packaging Market
Semiconductor Packaging
Semiconductor Chip Handler Market
Semiconductor Packaging
Semiconductor Packaging Material Market
Semiconductor Packaging
Global Bare Die Shipping and Handling and Processing and Storage Market
Semiconductor Packaging
Asia Pacific LED Packaging Market