
 United Kingdom Lithium-Ion Battery for Electric Vehicle Market | 2026-2036
United Kingdom Lithium-Ion Battery for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Lithium-Ion Battery for Electric Vehicle Market Insights
Battery health monitoring as a software-defined service layer is repositioning how value gets captured across the vehicle lifecycle. LG Energy Solution leverages its European manufacturing footprint to anchor cell supply for UK-based OEM assembly lines. Samsung SDI competes through specialized high-nickel cathode formulations designed for premium electric vehicle platforms. Panasonic sustains its position via deep technical collaboration with British automotive engineering centers on next-generation cylindrical cell architectures.
A lithium-ion battery for electric vehicle is an electrochemical energy storage device comprising an anode, cathode, separator, and electrolyte, typically operating at nominal voltages between 3.2V and 3.7V per cell depending on cathode chemistry, engineered to deliver repeated charge-discharge cycles exceeding 1,000 cycles at 80% depth of discharge for automotive traction applications. Nickel Cobalt Manganese cathode formulations currently dominate installed capacity due to their balanced energy density and thermal stability profile, while Lithium Iron Phosphate chemistry is gaining structural share in commercial fleet applications where cycle life and safety margins outweigh gravimetric energy priorities. The End User dimension reveals OEMs as the primary margin pool, though Fleet Operators represent the fastest-expanding procurement channel as electrification mandates tighten across UK logistics and public transport contracts.
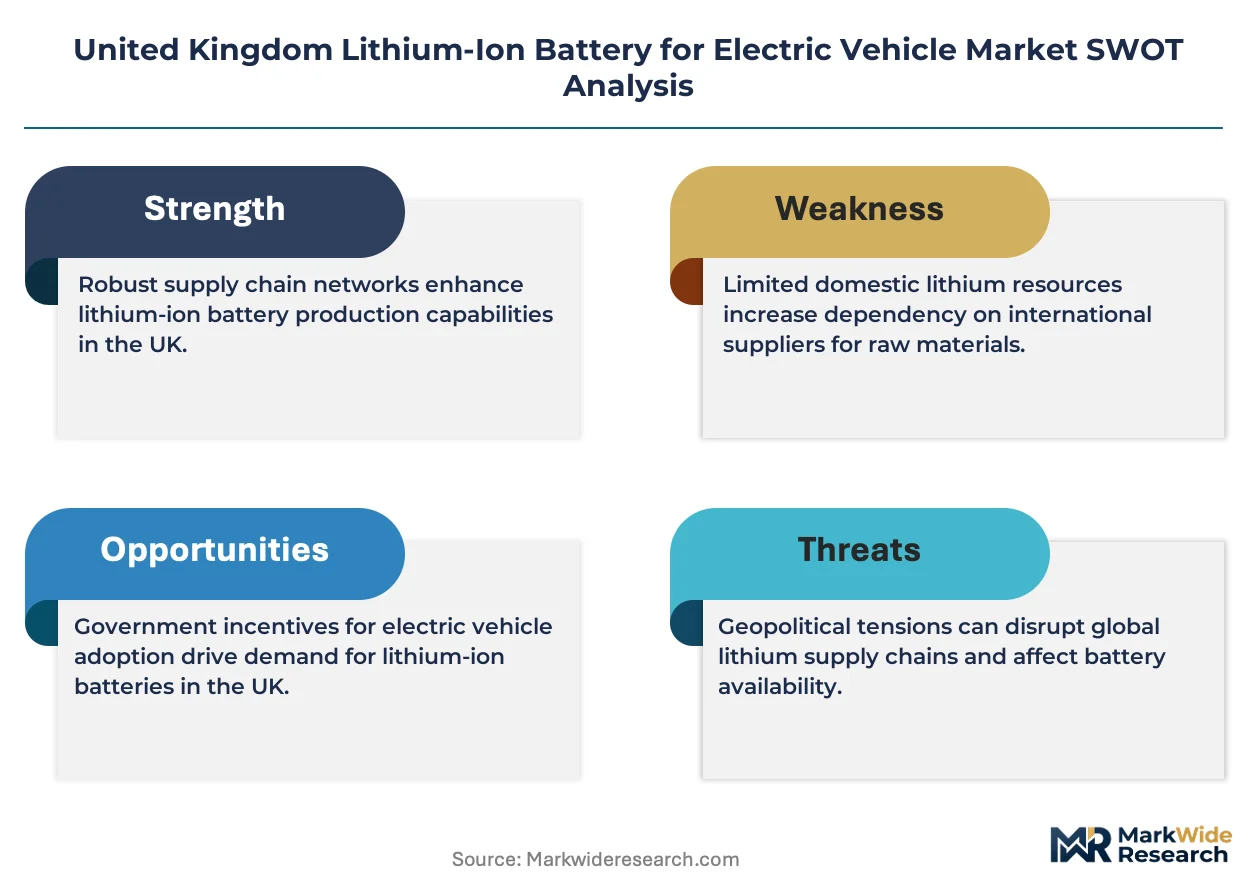
The UK Office for Product Safety and Standards enforces battery safety regulations under the Electrical Equipment Regulations framework, while the Environment Agency governs end-of-life cell collection and recycling obligations through the Waste Batteries Regulations. The British Standards Institution publishes PAS 7062 guidance on battery system safety for electric vehicles, shaping design requirements that manufacturers must satisfy for market access. Stakeholders must track how evolving UK Battery Strategy domestic content thresholds interact with EU Battery Regulation cross-border compliance obligations to determine optimal cell sourcing and pack assembly location decisions.
Market Dynamics
The UK government's Zero Emission Vehicle mandate is compressing OEM procurement timelines and forcing rapid localization of cell pack assembly capacity around the West Midlands battery cluster.
Growth Catalysts
- Zero Emission Vehicle Mandate:The UK regulatory framework imposes escalating EV sales quotas on manufacturers, compelling domestic battery sourcing to secure compliance credits and avoid penalties.
- Battery-as-a-Service Models:Fleet operators in commercial transport are adopting subscription-based battery procurement to decouple asset ownership from operational deployment, accelerating capital-light electrification.
- Nickel Cobalt Manganese Chemistry:This cathode formulation delivers the energy density threshold required for premium passenger EV platforms, sustaining demand pull from UK-based luxury automotive engineering centers.
Market Restraints
- Lithium Price Volatility:Spodumene concentrate and lithium hydroxide spot markets exhibit structural price swings that compress cell manufacturer margins and destabilize long-term supply agreements.
- East Asian Cathode Concentration:Over 70 percent of global NCM precursor processing capacity resides in China, creating geopolitical exposure for UK pack assemblers seeking supply chain resilience.
- Thermal Runaway Limitations:High-nickel cathode chemistries carry inherent thermal instability risks that necessitate costly battery management system redundancy and constrain energy density scaling.
Strategic Opportunities
- Scottish Highlands Grid Storage Convergence:Second-life EV battery repurposing for stationary storage applications is opening revenue streams for UK recyclers beyond material recovery.
- UK Battery Strategy Domestic Content Thresholds:Government procurement preferences for locally manufactured cells are incentivizing greenfield gigafactory investment in North East England and South Wales.
- Solid-State Electrolyte Integration:Sulfide-based ceramic electrolyte research programs at British university consortia are positioning UK entities to license next-generation intellectual property to continental OEMs.
Industry Challenges
- Electrochemical Engineer Scarcity:UK technical universities produce insufficient graduates with specialized expertise in cell chemistry optimization and manufacturing process engineering to staff expanding production facilities.
- PAS 7062 Certification Timelines:British Standards Institution safety validation protocols for novel battery architectures extend development cycles by 12-18 months, delaying market entry for innovative pack designs.
- Legacy Fleet Integration Complexity:Retrofitting battery-electric powertrains into existing commercial vehicle chassis requires bespoke thermal management solutions that fragment engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Lithium-Ion Battery for Electric Vehicle Market |
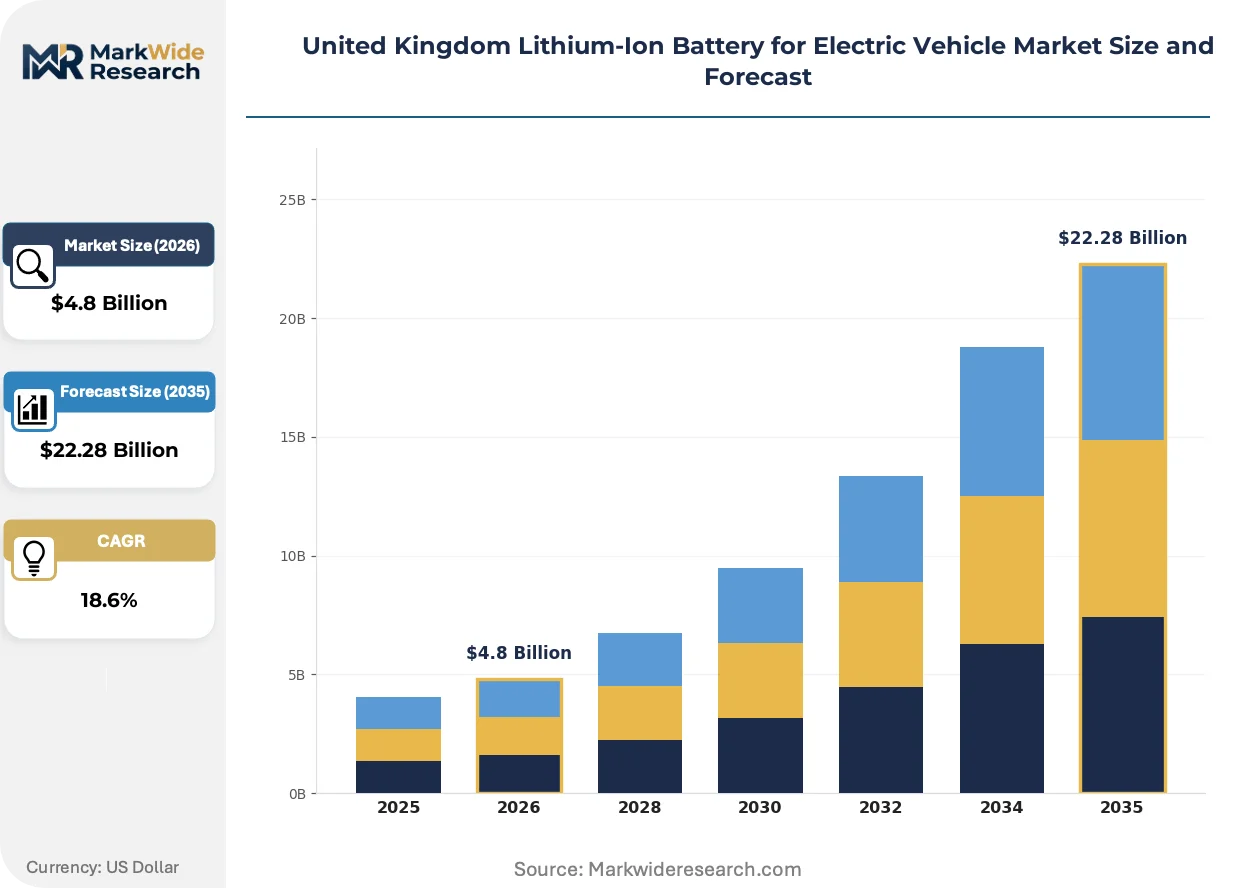
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nickel Cobalt Manganese, Lithium Iron Phosphate, Lithium Nickel Manganese Cobalt, Lithium Polymer End User: OEMs, Fleet Operators, Aftermarket Providers, Charging Infrastructure Technology: Fast Charging, Battery Management Systems, Thermal Management, Energy Recovery Installation: Onboard, Offboard, Modular, Integrated |
| Companies Covered | LG Energy Solution, Samsung SDI, Panasonic, BYD Company, Contemporary Amperex Technology, GS Yuasa Corporation, Toshiba Corporation, SK Innovation, Envision AESC Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Lithium-Ion Battery for Electric Vehicle Market Trends and Innovations
Cell chemistry evolution and software-defined battery architectures are redistributing value capture from hardware manufacturing toward data analytics and lifecycle services across the UK electric vehicle ecosystem.
Solid-state battery prototyping is integrating ceramic electrolyte layers to replace flammable liquid electrolytes, enabling higher energy density configurations. UK automotive engineering centers are piloting these architectures for premium platforms. The technology is integrating thermal stability improvements that compress safety system overhead and unlock pack-level weight reduction.
The UK Office for Product Safety and Standards is enforcing stricter Electrical Equipment Regulations compliance timelines for battery system certification. This regulatory pressure is accelerating third-party testing laboratory capacity expansion. Commercial fleet operators face the steepest compliance burden as they scale electrified logistics contracts under tightened safety audit protocols.
Fleet procurement patterns are consolidating around total-cost-of-ownership contracting rather than upfront capital expenditure models. Battery-as-a-service providers are displacing traditional asset finance structures in municipal bus and delivery van segments. This behavioral shift concentrates most visibly in West Midlands logistics corridors where decarbonization mandates intersect with dense fleet operator presence.
United Kingdom Lithium-Ion Battery for Electric Vehicle Market Segmentation
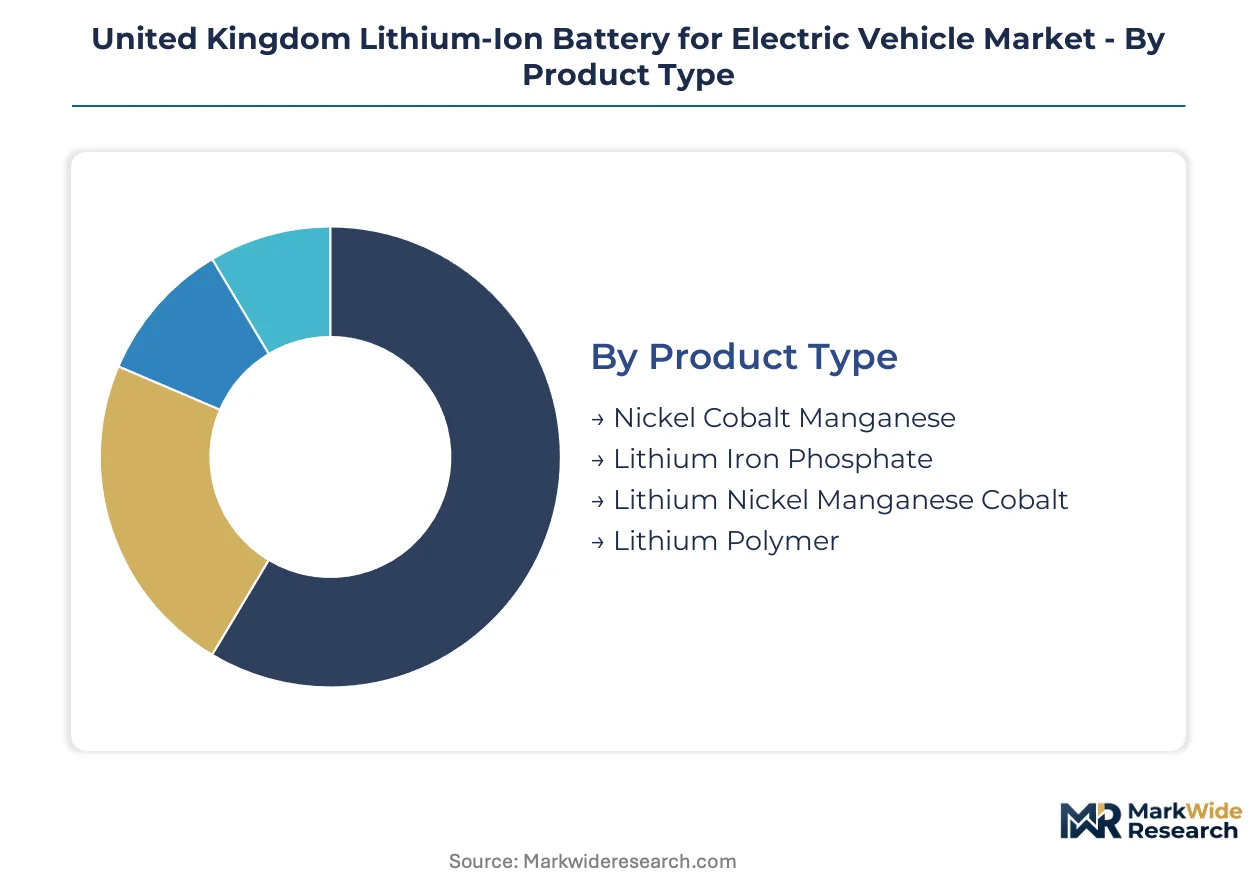
Segmentation reveals how cell chemistry selection, procurement channel structure, and system integration architecture determine margin capture across the UK electric vehicle value chain. Each dimension exposes distinct technical requirements and regulatory compliance burdens that reshape supplier positioning.
Product Type:
Standardization dominates high-volume cathode formulations while specialty chemistries command premium positioning for niche thermal or cycle-life requirements.
- Nickel Cobalt Manganese:Delivers balanced energy density above 250 Wh/kg with moderate thermal stability, making it the default selection for UK passenger OEMs targeting WLTP range benchmarks above 400 kilometers. West Midlands assembly plants source this chemistry most heavily for premium platform integration.
- Lithium Iron Phosphate:Sacrifices gravimetric energy density for cycle life exceeding 3,000 cycles and inherent thermal safety, attracting Birmingham-based commercial fleet operators with depot-charging infrastructure and predictable duty cycles. The chemistry avoids cobalt supply chain exposure entirely.
- Lithium Nickel Manganese Cobalt:Higher nickel ratios push energy density toward 300 Wh/kg for luxury vehicle architectures requiring minimal pack footprint.
- Lithium Polymer:Flexible form factors suit low-volume specialty vehicle conversions where cylindrical or prismatic constraints limit chassis packaging.
Leading the category by volume: Nickel Cobalt Manganese. Growing fastest: Lithium Iron Phosphate.
End User:
Procurement scale and technical specification authority separate direct OEM relationships from intermediated fleet channels with diverging service expectations.
- OEMs:Original equipment manufacturers specify cell chemistry, pack architecture, and battery management system integration at the vehicle design stage, locking suppliers into multi-year platform contracts with stringent PAS 7062 validation requirements.
- Fleet Operators:Municipal bus companies and last-mile delivery services in the West Midlands corridor are adopting battery-as-a-service subscriptions to decouple electrification capital from operational deployment, accelerating procurement velocity.
- Aftermarket Providers:Independent service facilities handle replacement pack installation for out-of-warranty vehicles, requiring backward-compatible diagnostics and cell-matching protocols.
- Charging Infrastructure:Stationary storage-integrated fast charging hubs source second-life battery modules from retired automotive packs, creating circular revenue streams for UK recyclers.
Dominating procurement value: OEMs. Expanding most quickly: Fleet Operators.
Technology:
Hardware-software integration intensity varies from passive thermal solutions to algorithm-dependent charge optimization systems.
- Fast Charging:800V architectures and silicon carbide power electronics enable 10-80% charge times below 20 minutes, demanding enhanced cell cooling and lithium plating mitigation algorithms for UK motorway service station deployment.
- Battery Management Systems:Software-defined monitoring platforms track state-of-health degradation, predict thermal runaway probability, and enable over-the-air parameter updates that extend asset residual value across secondary ownership cycles.
- Thermal Management:Liquid cooling circuits with glycol-based heat transfer fluids maintain cell temperature uniformity within 3°C across the pack, preventing localized degradation acceleration.
- Energy Recovery:Regenerative braking integration with torque-vectoring control harvests kinetic energy during urban deceleration events, feeding captured power back through the inverter to the traction battery.
Commanding highest R&D investment: Battery Management Systems. Gaining functional priority: Fast Charging.
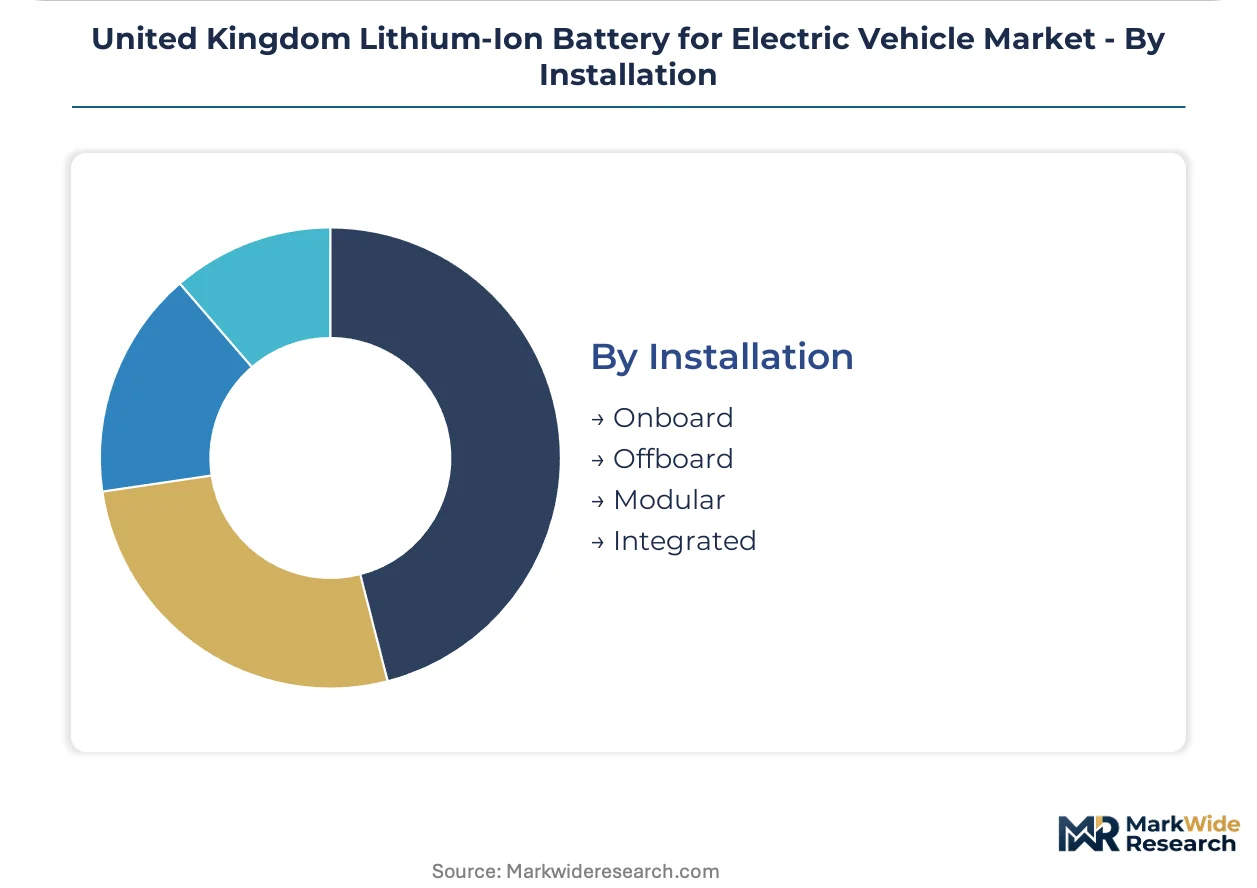
Installation:
Physical integration depth with vehicle chassis architecture determines service accessibility and crash safety certification complexity.
- Onboard:Permanently mounted packs within the vehicle floorpan or transmission tunnel require structural reinforcement for side-impact compliance, dominating UK passenger car and van production lines.
- Offboard:Swappable battery stations at depot facilities enable commercial operators to exchange depleted modules for charged units within minutes, eliminating dwell time constraints for high-utilization logistics fleets.
- Modular:Standardized cell modules with common mechanical interfaces allow capacity scaling across vehicle platforms without pack redesign, reducing engineering amortization for low-volume UK automotive specialists.
- Integrated:Cell-to-pack architectures eliminate module housings, improving volumetric energy density but complicating individual cell replacement and warranty claim isolation.
Prevailing in production volume: Onboard. Steepest expansion trajectory: Modular.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The West Midlands battery cluster near Coventry and Birmingham anchors UK lithium-ion cell pack assembly capacity, drawing cathode supply from continental European precursor processors and concentrating OEM engineering talent around legacy automotive engineering centers.
West Midlands
Coventry's gigafactory pipeline and Birmingham's battery engineering centers concentrate cell-to-pack assembly lines serving Jaguar Land Rover and commercial van platforms. The UK Office for Product Safety and Standards enforces PAS 7062 safety validation protocols from its London headquarters, extending certification timelines for novel architectures. Solihull and Warwick host thermal management testing facilities where liquid-cooled pack designs undergo side-impact compliance verification.
North East England
Nissan's Sunderland manufacturing complex and Britishvolt's collapsed Blyth site demonstrate both opportunity and execution risk for greenfield cell production investments. The UK Battery Strategy's domestic content thresholds incentivize local cathode active material processing. Newcastle University consortia pilot solid-state electrolyte research programs targeting sulfide-based ceramic intellectual property licensing.
South Wales
Warren's emerging battery supply zone near Port Talbot leverages steel industry legacy infrastructure for gigafactory site preparation. Welsh Government procurement preferences for locally manufactured cells attract pack assemblers serving Bristol Channel logistics corridors. Cardiff-based recyclers develop second-life repurposing streams for retired automotive modules.
Scotland
Aberdeen's offshore engineering expertise migrates toward stationary storage integration for Highland wind farm grid balancing applications. Scottish Enterprise funding supports battery-as-a-service pilots for Highland Council municipal bus electrification. Dundee's decommissioned Michelin tire plant site hosts modular pack assembly for commercial fleet retrofit programs.
Greater London
Last-mile delivery fleet operators in the capital adopt subscription-based battery procurement faster than national averages, decoupling electrification capital from operational deployment. Transport for London's zero-emission bus mandates compress procurement timelines for depot-charging infrastructure. Croydon and Enfield host aftermarket service facilities handling out-of-warranty pack replacement for early-adopter taxi fleets.
United Kingdom Lithium-Ion Battery for Electric Vehicle Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the UK electric vehicle battery value chain. Integrated cell manufacturers with captive cathode precursor supply dominate high-volume OEM platform contracts. Specialist pack assemblers without cell fabrication capacity capture margin in commercial fleet retrofit and aftermarket replacement segments. Strategic moves concentrate on securing lithium hydroxide offtake agreements and licensing solid-state electrolyte intellectual property from British university consortia.
Within the integrated manufacturing tier, LG Energy Solution and Samsung SDI occupy positions anchored to European cell supply footprints. Panasonic exemplifies the collaborative engineering archetype through technical partnerships with British automotive development centers. Contemporary Amperex Technology and BYD Company represent scale-driven Asian producers seeking UK pack assembly localization to satisfy domestic content thresholds. These entities collectively illustrate how cathode chemistry specialization and geographic manufacturing presence determine competitive positioning under tightening regulatory compliance timelines.
| Leading Market Players |
|---|
| LG Energy Solution |
| Samsung SDI |
| Panasonic |
| BYD Company |
| Contemporary Amperex Technology |
| GS Yuasa Corporation |
| Toshiba Corporation |
| SK Innovation |
| Envision AESC Group |
| Others |
Pricing and Supply Chain Analysis
The UK government's Zero Emission Vehicle mandate and domestic content thresholds are forcing OEMs to source locally assembled cell packs, compressing procurement timelines and reshaping how suppliers price long-term offtake agreements against spot lithium hydroxide exposure.
Pricing Analysis
Cost-down pressure on high-nickel cathode formulations accelerates as fleet operators consolidate procurement around battery-as-a-service subscriptions, shifting margin capture from hardware markups to lifecycle data monetization. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade under PAS 7062 and volume scale, with commercial fleet buyers exhibiting highest price sensitivity due to total-cost-of-ownership contracting, while luxury OEMs absorb premiums for specialized cell architectures.
Supply Chain Analysis
The UK Battery Strategy's domestic content thresholds are redirecting cathode precursor sourcing away from concentrated East Asian processing hubs toward emerging European supply corridors. Cell pack assembly draws from lithium hydroxide processed in Chile and Australia, separator films manufactured in South Korea and Japan, and copper foil rolled in Germany. Single-source vulnerability in Chinese NCM precursor capacity creates tariff exposure and geopolitical contingency risk. Distribution runs through West Midlands logistics clusters serving Coventry and Birmingham assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race where cathode precursor control and pack assembly localization determine compliance eligibility under tightening domestic content rules.
For Market Incumbents: Hedge against lithium price volatility through long-term spodumene offtake agreements with Australian miners, while accelerating in-house production of battery management system software to defend margin position against emerging solid-state entrants. Lock multi-year platform contracts with West Midlands OEMs before PAS 7062 certification timelines extend for novel architectures. For New Entrants and Emerging Players: Fleet operator procurement consortia represent the most penetrable channel, particularly municipal bus electrification programs in Scotland and last-mile delivery networks in Greater London where battery-as-a-service adoption outpaces national averages. Target second-life stationary storage integration for Highland wind farm grid balancing as a white-space revenue stream with lower certification barriers. For Investors and Strategic Acquirers: The window for entry favors solid-state electrolyte intellectual property holders and modular pack assemblers without captive cell fabrication, as these entities capture licensing fees and retrofit margins without capital-intensive gigafactory exposure. Watch for inflection when British university consortia announce sulfide-based ceramic electrolyte licensing deals with continental OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Localization | Secures UK Battery Strategy compliance credits for OEM platform contracts. |
| Battery-as-a-Service Platform Launch | Decouples fleet electrification capital from operational deployment in West Midlands corridors. |
| Solid-State Electrolyte Licensing | Positions UK entities to capture intellectual property royalties from continental premium OEMs. |
| Second-Life Repurposing Infrastructure | Creates circular revenue streams for Scottish Highland grid storage applications. |
| PAS 7062 Certification Fast-Track | Compresses safety validation timelines for novel pack architectures seeking market entry. |
Research Methodology
Trade databases, UK Office for Product Safety and Standards regulatory filings, and vehicle production registries formed the secondary backbone, cross-referenced with primary interviews involving OEM platform engineers, Tier 1 supplier procurement leads, commercial fleet operators, and battery recycling specialists. Bottom-up and top-down triangulation reconciled cell shipment volumes against vehicle registration data.
Bottom-up modeling aggregated segment-level projections across cathode chemistry, end-user procurement channel, and installation architecture, while top-down validation tested aggregate market evolution against macro EV penetration assumptions. CAGRs derived from fitted growth curves incorporating lithium hydroxide price trajectories, Zero Emission Vehicle mandate compliance schedules, and domestic content threshold phase-ins. Forecast inputs included West Midlands gigafactory capacity announcements and fleet operator subscription adoption rates.
Several conditions sit outside the modeled scope, including potential revisions to EU Battery Regulation cross-border compliance obligations, breakthrough solid-state commercialization timelines, and lithium extraction project delays in Chile and Australia. Forecasts reflect documented assumptions about cathode chemistry mix evolution and OEM localization decisions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Automotive Cylindrical Lithium Batteries Market
Lithium-ion Battery
France Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
India Electric Vehicle Battery Materials Market
Lithium-ion Battery
United States Battery Cell Market
Lithium-ion Battery
Lithium Battery Wet Separator Market
Lithium-ion Battery
Salt Lake Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market
Lithium-ion Battery
Laminated Lithium Ion Secondary Battery Market
Lithium-ion Battery
Lithium-Ion Battery Materials Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
Industrial Lithium-Ion Batteries Market
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Market