
 Lithium Sulfur Dioxide Battery Market | 2026-2036
Lithium Sulfur Dioxide Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Sulfur Dioxide Battery Market Insights
Sulfur cathode chemistry is hardening as the dominant alternative to cobalt-dependent lithium-ion architectures, reducing raw material cost volatility for defense and aerospace suppliers. Sion Power Corporation leverages its thin-film deposition expertise to sustain long-term contracts with satellite manufacturers requiring ultra-lightweight energy densities. Lyten, Inc. anchors its competitive position through graphene-enhanced sulfur composites that improve conductivity without metallic current collectors. GS Yuasa Corporation dominates cylindrical cell production for Japanese industrial automation, where vibration tolerance and wide-temperature performance command premium positioning.
A lithium sulfur dioxide battery is an electrochemical cell pairing a lithium metal anode with a sulfur dioxide catholyte, typically yielding open-circuit voltages near 2.9 volts and specific energies exceeding 250 watt-hours per kilogram in primary configurations. These cells serve applications demanding extreme reliability under thermal stress, including missile guidance systems, sonobuoys, and downhole drilling instruments where conventional lithium-ion chemistries fail. Primary Batteries occupy the largest revenue share due to established military qualification pathways and decades of field-proven performance in ordnance fuzing. Solid-State Technology represents the fastest-expanding segment as nanotechnology-enabled ceramic electrolytes address polysulfide shuttle degradation that has historically limited cycle life in secondary designs.
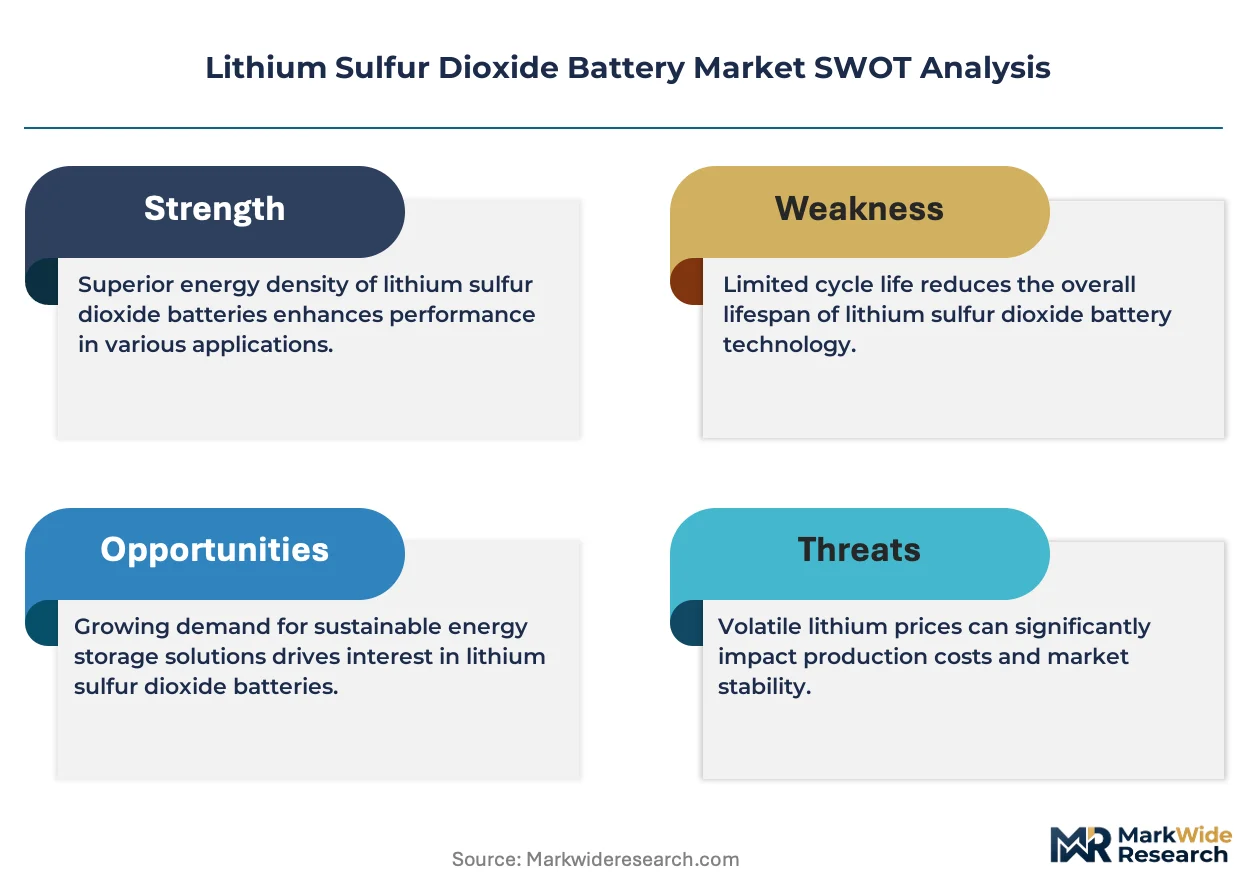
US military specifications governed by the Department of Defense and FAA technical standard orders constrain cell design, testing protocols, and transportation classifications for lithium sulfur dioxide batteries deployed in aviation and weapons platforms. REACH substance restrictions in Europe and China's GB standards for lithium cell safety create divergent compliance burdens that fragment manufacturing footprints and qualification investments. Stakeholders must monitor how solid-state patent filings and sulfur cathode processing improvements alter the trade-off between primary cell reliability and rechargeable cycle life that currently defines segment boundaries.
Market Dynamics
Solid-state electrolyte architectures are displacing liquid catholyte designs across defense procurement channels, compressing qualification timelines while extending operational temperature ranges beyond conventional lithium-ion limits.
Growth Catalysts
- US Defense Sourcing Mandates:Domestic content requirements under Department of Defense acquisition regulations are channeling procurement toward qualified domestic cell manufacturers.
- Extreme-Temperature Performance:Ordnance fuzing and missile guidance systems demand operational reliability from minus fifty-five to plus seventy-one degrees Celsius where competing chemistries fail.
- Sulfur Cathode Processing:Advances in molten sulfur infiltration techniques are reducing cell-to-cell performance variance in high-volume cylindrical formats.
Market Restraints
- Raw Material Concentration:Battery-grade lithium metal supply concentrates among Chinese and Argentinian producers, exposing defense contractors to export control volatility.
- Transportation Classification:FAA and IATA dangerous goods restrictions impose specialized packaging and routing costs that inflate delivered pricing for air-freighted cells.
- Polysulfide Dissolution:Secondary cell designs face fundamental cycle life limitations from soluble polysulfide species that migrate across liquid electrolytes.
Strategic Opportunities
- Satellite Constellation Expansion:Low Earth orbit communication networks are generating demand for ultra-lightweight primary cells with decade-long shelf stability.
- Downhole Instrumentation:Geothermal and oilfield service companies in Texas and North Dakota require pressure-resistant power sources for measurement-while-drilling tools.
- EU Critical Raw Materials Act:Strategic stockpiling incentives and domestic processing subsidies are creating alternative qualification pathways for European defense integrators.
Industry Challenges
- Electrolyte Formulation Expertise:Cell manufacturers face acute shortages of electrochemists experienced with lithium-sulfur dioxide interface stability and corrosion inhibition.
- Military Qualification Timelines:MIL-PRF-49471 testing protocols demand eighteen-to-thirty-six month validation cycles that delay revenue recognition for new cell designs.
- Legacy System Integration:Retrofitting sulfur dioxide cells into existing weapons platforms requires mechanical redesign of battery compartments sized for lithium-thionyl chloride predecessors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Sulfur Dioxide Battery Market |
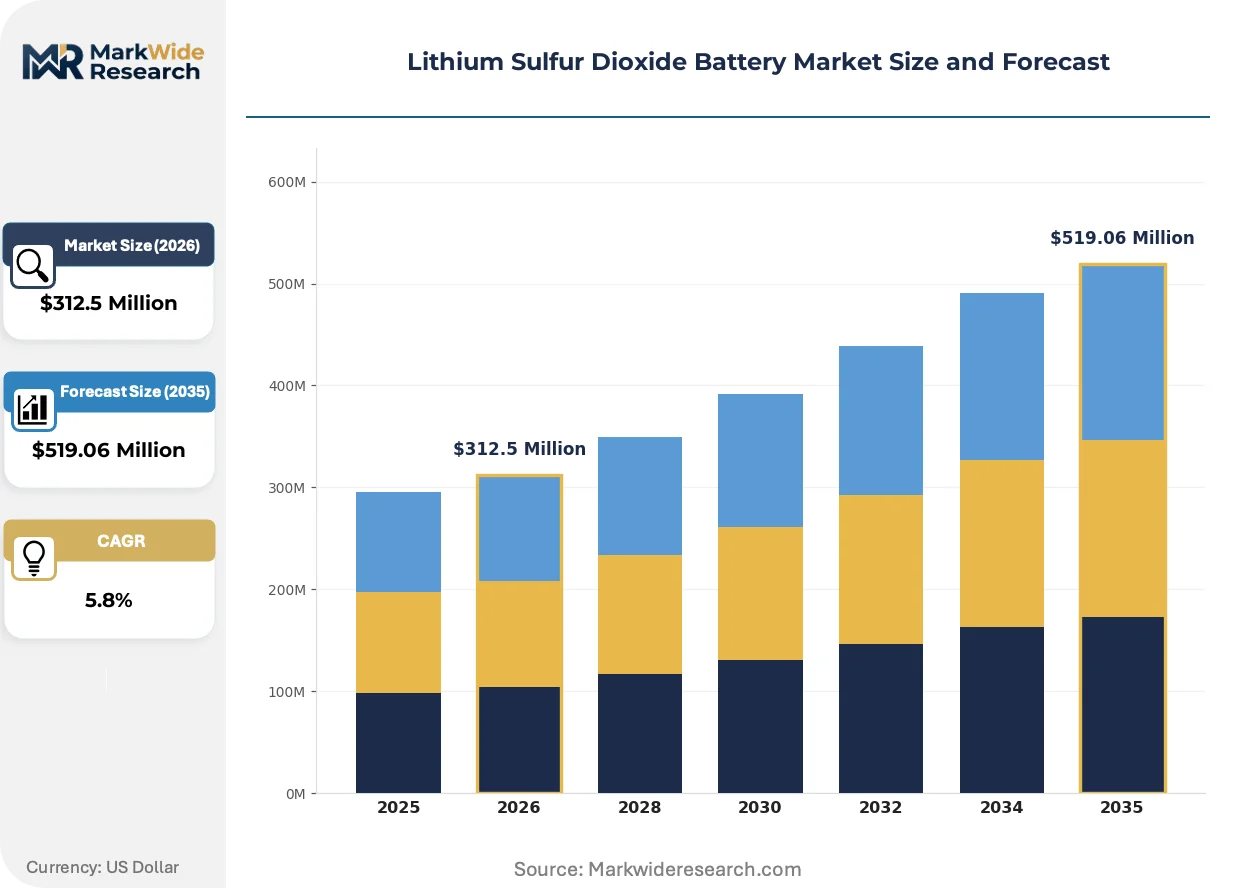
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Batteries, Secondary Batteries, Rechargeable Batteries, High-Energy Batteries End User: Consumer Electronics, Medical Devices, Military Applications, Industrial Equipment Application: Energy Storage, Electric Vehicles, Wireless Sensors, Portable Devices Technology: Nanotechnology, Solid-State Technology, Thin-Film Batteries, Hybrid Systems |
| Companies Covered | PolyPlus Battery Company, NexTech Batteries Inc., Li-S Energy Limited, Lyten, Inc., Zeta Energy LLC, Sion Power Corporation, Giner Inc., GS Yuasa Corporation, Gelion PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Sulfur Dioxide Battery Market Trends and Innovations
Cell architecture standardization and ceramic electrolyte maturation are converging to blur the historical boundary between primary and secondary lithium sulfur dioxide systems.
Solid-state ceramic electrolytes are modularizing around lithium phosphorus oxynitride and sulfide-glass compositions that block polysulfide migration while maintaining lithium-ion conductivity. Satellite manufacturers are qualifying these architectures for ten-year missions. The technology is modularizing what were previously discrete primary and rechargeable product lines into unified platform designs with field-configurable cycle life.
REACH substance restrictions on sulfur dioxide handling and transport are compelling European cell assemblers to invest in closed-loop electrolyte filling systems. Industrial battery packagers in Germany and France must now demonstrate containment engineering that exceeds baseline UN testing protocols. The regulation is accelerating automation capital deployment among mid-volume cylindrical cell producers serving aerospace integrators.
Defense procurement officers are consolidating vendor pools around dual-use qualified suppliers capable of serving both military ordnance and commercial aviation applications. Long-term supply agreements with penalty clauses for qualification failure are displacing spot purchasing for mission-critical programs. This concentration is most visible in United States Navy sonobuoy programs where sole-source contracting has reduced active qualified cell suppliers to three domestic entities.
Lithium Sulfur Dioxide Battery Market Segmentation
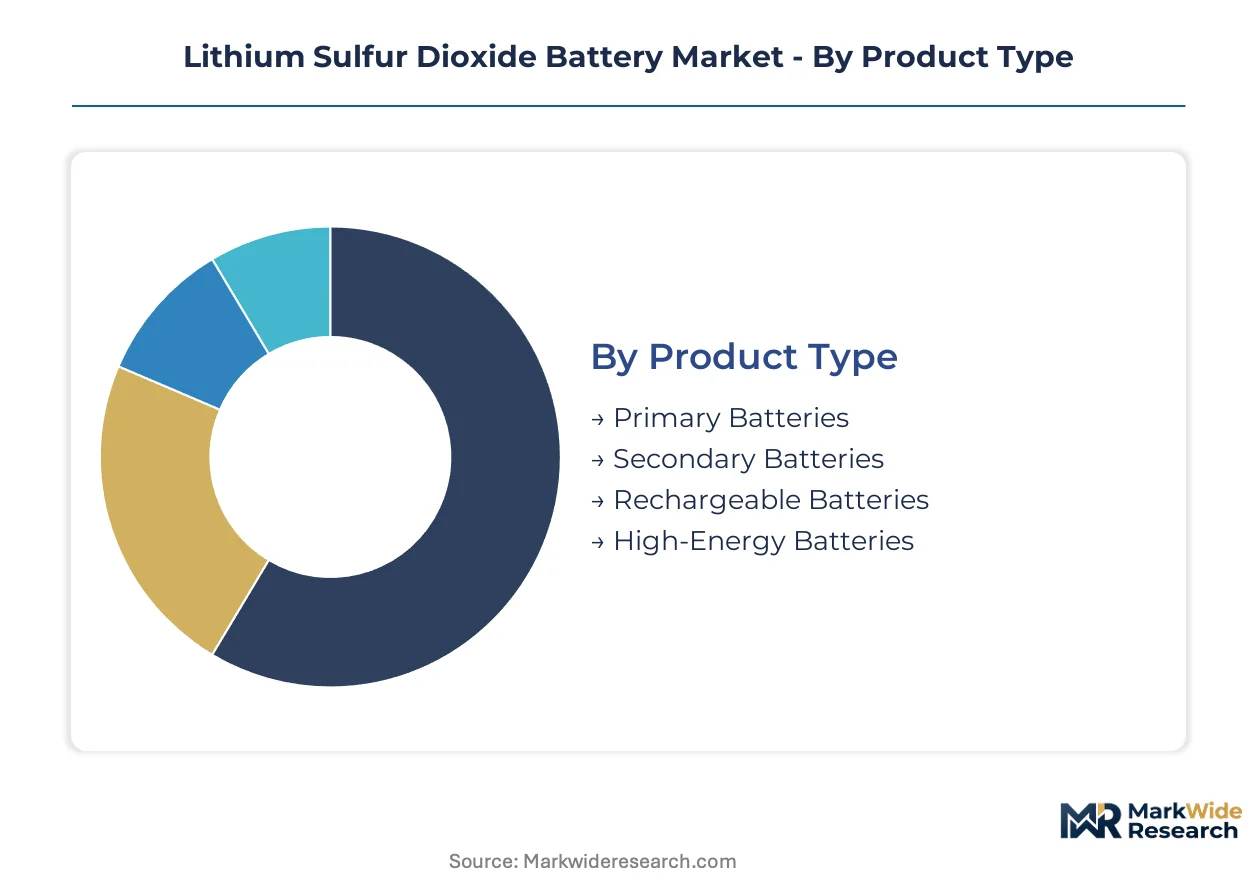
Segmentation in lithium sulfur dioxide batteries reveals how chemistry variants align with operational reliability requirements across defense, aerospace, and industrial verticals. Product architecture choices determine whether cells serve as standalone power sources or integrate into complex weapons and instrumentation systems.
Product Type:
Integration depth varies sharply: primary configurations dominate standalone ordnance applications, while secondary and rechargeable formats embed into retrievable industrial equipment requiring multiple discharge cycles.
- Primary Batteries:Non-rechargeable cells utilizing lithium metal anodes with sulfur dioxide catholytes deliver open-circuit voltages near 2.9 volts and specific energies exceeding 250 watt-hours per kilogram. Demand concentrates in US Navy sonobuoy programs and missile guidance systems where MIL-PRF-49471 qualification mandates decades of field-proven reliability.
- Secondary Batteries:Rechargeable architectures incorporate solid-state electrolytes to mitigate polysulfide shuttle degradation that historically limited cycle life. Demand is accelerating in satellite constellations requiring decade-long operational lifespans with periodic recharging from solar arrays.
- Rechargeable Batteries:Field-configurable cycle life variants are modularizing around ceramic electrolyte platforms that blur traditional primary-secondary boundaries.
- High-Energy Batteries:Ultra-lightweight formats serve downhole drilling instruments in Texas and North Dakota where pressure resistance and energy density command premium positioning.
Volume placements concentrate in Primary Batteries; the faster expansion belongs to Secondary Batteries.
End User:
Customer archetypes span from price-sensitive consumer segments to procurement officers governed by domestic sourcing mandates and technical standard orders.
- Military Applications:Department of Defense acquisition regulations channel procurement toward qualified domestic manufacturers with eighteen-to-thirty-six month MIL-PRF-49471 validation cycles. Ordnance fuzing and aviation power systems demand operational reliability from minus fifty-five to plus seventy-one degrees Celsius.
- Industrial Equipment:Geothermal and oilfield service companies require pressure-resistant cylindrical cells for measurement-while-drilling tools where vibration tolerance justifies premium pricing.
- Consumer Electronics:Limited penetration due to transportation classification restrictions and FAA dangerous goods packaging requirements that inflate delivered costs.
- Medical Devices:Niche applications in implantable and portable diagnostic equipment where long shelf stability offsets higher unit costs.
Revenue concentration sits with Military Applications; Industrial Equipment is climbing the fastest as energy extraction automation expands.
Application:
Use-case segmentation tracks how cell formats align with stationary versus mobile power requirements and mission-critical versus convenience-driven deployment contexts.
- Wireless Sensors:Distributed environmental and structural monitoring networks in defense and infrastructure applications leverage primary cells with decade-long shelf stability for remote, maintenance-free operation.
- Portable Devices:Military field equipment and specialized industrial instrumentation utilize cylindrical formats optimized for wide-temperature performance.
- Energy Storage:Grid-scale and backup power applications remain limited by transportation restrictions and raw material supply concentration risks.
- Electric Vehicles:Minimal adoption due to cycle life constraints and competing lithium-ion chemistries dominating automotive qualification pathways.
Deployment scale favors Wireless Sensors; Portable Devices are gaining share fastest as defense electronics modernization accelerates.
Technology:
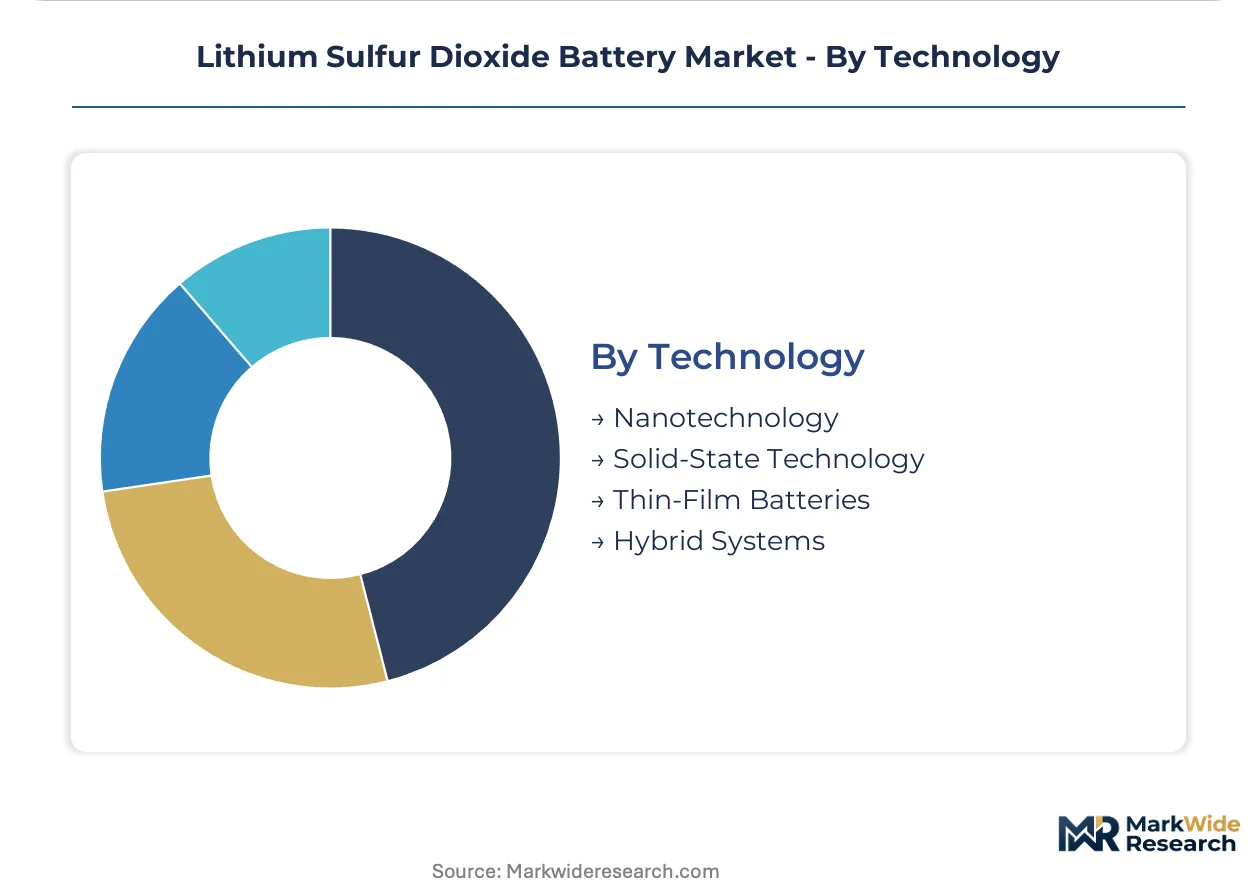
Technology segmentation captures the architectural shift from liquid catholyte designs toward solid-state platforms that redefine performance boundaries.
- Solid-State Technology:Nanotechnology-enabled ceramic electrolytes utilizing lithium phosphorus oxynitride and sulfide-glass compositions block polysulfide migration while maintaining lithium-ion conductivity. Satellite manufacturers are qualifying these architectures for ten-year missions.
- Thin-Film Batteries:Deposition expertise enables ultra-lightweight formats serving satellite manufacturers requiring minimized mass for launch economics.
- Nanotechnology:Molten sulfur infiltration techniques and graphene-enhanced sulfur composites reduce cell-to-cell performance variance in high-volume cylindrical production.
- Hybrid Systems:Combined architectures integrating multiple electrochemical couples for specialized defense and aerospace applications.
Investment intensity centers on Solid-State Technology; Nanotechnology is expanding most quickly as processing improvements mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement concentration in the United States absorbs the dominant share of lithium sulfur dioxide cell output, with satellite constellation deployment and industrial automation in Germany and Japan anchoring secondary demand poles.
United States
Department of Defense acquisition regulations channel procurement toward qualified domestic manufacturers with MIL-PRF-49471 validation cycles. FAA technical standard orders constrain cell design for aviation applications. Sonobuoy programs in Rhode Island and missile guidance system integrators in Arizona concentrate demand for cylindrical primary formats.
Japan
Industrial automation in automotive and robotics sectors drives cylindrical cell demand where vibration tolerance commands premium positioning. METI safety standards and JIS certification requirements structure qualification pathways. GS Yuasa production facilities in Kyoto Prefecture anchor domestic supply for precision instrumentation markets.
Germany
REACH substance restrictions on sulfur dioxide handling compel closed-loop electrolyte filling investments among cell assemblers. ECHA compliance documentation requirements fragment manufacturing footprints. Aerospace integrators in Bavaria and industrial battery packagers in Baden-Württemberg deploy automated containment engineering exceeding UN testing protocols.
China
GB standards for lithium cell safety create divergent compliance burdens that affect export-oriented defense contractors. MIIT industrial policy directs sulfur cathode processing research toward domestic supply chain security. Battery-grade lithium metal refining concentrates in Qinghai and Sichuan provinces, exposing downstream consumers to export control volatility.
United Kingdom
Defense electronics modernization programs generate demand for wide-temperature power systems in avionics and ordnance applications. Ministry of Defence sourcing guidelines emphasize supply chain resilience for mission-critical components. Satellite manufacturers in Surrey and defense integrators in Bristol qualify solid-state architectures for extended operational lifespans.
Lithium Sulfur Dioxide Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense-qualified suppliers consolidating around sole-source contracting while industrial and commercial channels sustain more fragmented procurement patterns. The vendor base organizes around three strategic archetypes: thin-film deposition specialists serving satellite mass constraints, cylindrical cell producers dominating industrial automation, and solid-state electrolyte developers bridging primary-secondary boundaries. Capacity expansion and qualification-driven M&A represent the dominant competitive moves as eighteen-to-thirty-six month validation cycles create barriers to rapid market entry.
Within the defense-aerospace tier, Sion Power Corporation and PolyPlus Battery Company exemplify specialists positioned around deposition expertise and electrochemical interface stability respectively. GS Yuasa Corporation anchors the industrial automation segment with cylindrical production capabilities. Lyten, Inc. occupies a position within the materials innovation archetype, representing graphene-enhanced sulfur composite approaches that reduce reliance on metallic current collectors. These three entities collectively illustrate how geographic origin and technical specialization stratify competitive positioning across procurement channels governed by divergent qualification timelines.
| Leading Market Players |
|---|
| PolyPlus Battery Company |
| NexTech Batteries Inc. |
| Li-S Energy Limited |
| Lyten, Inc. |
| Zeta Energy LLC |
| Sion Power Corporation |
| Giner Inc. |
| GS Yuasa Corporation |
| Gelion PLC |
| Others |
Pricing and Supply Chain Analysis
Battery-grade lithium metal refining costs in Qinghai and Sichuan provinces cascade through cylindrical cell pricing tiers, with defense contractors absorbing premiums for MIL-PRF-49471 qualified formats while industrial automation buyers negotiate volume contracts off standardized specifications.
Pricing Analysis
High-volume cylindrical formats for Japanese industrial automation command thinner margins than low-volume thin-film deposition products for satellite manufacturers. Price differentiation separates aviation-qualified cells with FAA technical standard order compliance from standard industrial grades lacking ordnance fuzing certifications. Cost compression in the industrial tier intensifies because GS Yuasa and competitors scale cylindrical production for robotics applications. Defense procurement officers show least price sensitivity due to sole-source contracting mandates, while geothermal service companies in Texas and North Dakota negotiate hardest on per-unit costs for measurement-while-drilling tools.
Supply Chain Analysis
Dual-sourcing requirements embedded in Department of Defense acquisition regulations compel prime contractors to qualify at least two domestic cell manufacturers for sonobuoy and missile guidance programs. Raw material supply draws from lithium metal refiners in China and Argentina, sulfur processing facilities in Germany and the United States, and ceramic electrolyte precursor specialists in Japan. Single-source vulnerability concentrates in battery-grade lithium metal where export control volatility from Chinese producers threatens downstream availability. Distribution runs through qualified defense logistics channels for military applications and industrial distributors for automation sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIL-PRF-49471 validation cycles function as a cost-of-compliance moat that protects incumbent qualified suppliers from rapid competitive entry, with eighteen-to-thirty-six month testing protocols creating structural barriers that emerging players cannot shortcut.
For Market Incumbents: Deploy qualification-bundling strategies that extend MIL-PRF-49471 certifications across multiple weapons platforms simultaneously, reducing marginal validation costs per program. Deepen upstream control over lithium metal supply through long-term offtake agreements with Argentinian refiners, insulating against Chinese export restriction threats. Solid-state electrolyte patent filings from PolyPlus Battery Company and Sion Power Corporation signal intensifying R&D competition that demands accelerated ceramic platform investments. For New Entrants and Emerging Players: Enter via the satellite constellation secondary battery segment where solid-state qualification pathways remain less entrenched than primary cell military certifications. Target European defense integrators responding to EU Critical Raw Materials Act stockpiling incentives, where alternative qualification timelines offer faster revenue recognition than US Navy sole-source channels. Position around graphene-enhanced sulfur composite processing as a materials innovation wedge distinct from established thin-film and cylindrical production expertise. For Investors and Strategic Acquirers: Solid-state patent filing acceleration is the leading indicator that secondary battery architectures will capture share from primary formats across the analysis window. Acquisition candidates should display dual-use qualification capabilities spanning military ordnance and commercial aviation, with established relationships with FAA and Department of Defense procurement officers. Watch for Department of Defense domestic content requirement tightening as the signal for accelerated consolidation among the three remaining qualified US sonobuoy cell suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| MIL-PRF-49471 Qualification Expansion | Extends incumbent protection across multiple weapons platforms under Department of Defense sourcing mandates. |
| Solid-State Electrolyte Patent Filing | Establishes intellectual property moats around lithium phosphorus oxynitride and sulfide-glass compositions. |
| Argentinian Lithium Metal Offtake Agreement | Reduces concentration risk from Chinese battery-grade lithium refiners exposed to export controls. |
| Closed-Loop Electrolyte Filling Investment | Satisfies REACH substance restrictions for European aerospace integrators in Germany and France. |
| Satellite Constellation Secondary Cell Qualification | Captures demand from low Earth orbit communication networks requiring decade-long operational lifespans. |
Research Methodology
Multi-period observation of MIL-PRF-49471 validation cycle durations, solid-state patent filing velocities, and defense procurement award patterns anchored the trend analysis, supplemented by interviews with cell manufacturing executives, Department of Defense acquisition officers, satellite program power system engineers, and industrial automation procurement leads. Secondary validation drew from FAA technical standard order databases, ECHA REACH compliance filings, USPTO and JPO patent records, and customs trade data tracking lithium metal import flows. Bottom-up cell production estimates triangulated against top-down defense budget allocation analysis.
Segment-weighting approaches distributed value and volume projections across primary-secondary-rechargeable product architectures, military-industrial-consumer end-use categories, and solid-state-thin-film-nanotechnology technology platforms. CAGRs were derived from slope analysis of qualification timeline compression rates, raw material cost trajectories, and satellite constellation deployment schedules. Forecast inputs incorporated polysulfide shuttle degradation mitigation rates in ceramic electrolyte designs and sulfur cathode processing yield improvements from molten infiltration techniques.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control escalation scenarios affecting Chinese lithium metal supply. Deviation in Department of Defense domestic content requirement enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Nanotechnology Enabled Battery Market
Lithium-ion Battery
Europe NMC Battery Pack Market
Lithium-ion Battery
Lithium-Ion Polymer Batteries Market
Lithium-ion Battery
Southeast Asia Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Iron Phosphate (LiFePO4) Battery Market
Lithium-ion Battery
Lithium Battery for Passenger Car Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
Advanced Lithium-Ion Batteries Market
Lithium-ion Battery
United States Battery Cell Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Japan Lithium-Ion Battery Market
Lithium-ion Battery
Next Generation Advanced Battery Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
Liquid Lithium Ion Battery Market
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market